
 Hybrid Cloud in BFSI Market | 2026-2036
Hybrid Cloud in BFSI Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Cloud in BFSI Market Analysis
Modular service bundling is recalibrating procurement patterns across BFSI institutions. Microsoft leverages its Azure Arc platform to anchor multi-environment management for banks navigating fragmented infrastructure. IBM sustains dominance in regulated private cloud deployments through its zSystems and Cloud Paks integration. Google Cloud competes aggressively on AI-ready infrastructure, positioning Vertex AI as a differentiator for algorithmic trading workloads.
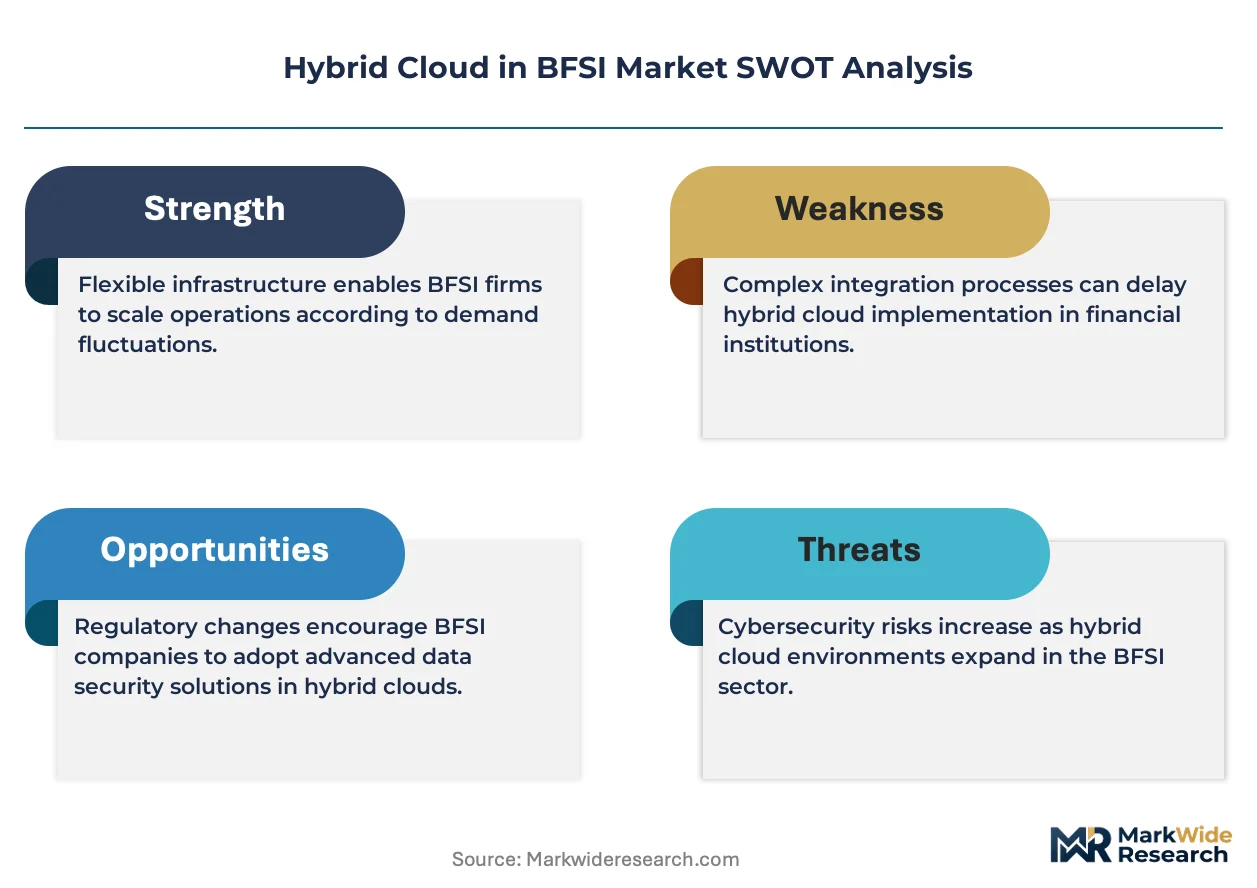
Hybrid Cloud in BFSI denotes an IT architecture combining on-premises private cloud resources with public cloud services, orchestrated through unified management planes enabling workload portability, data sovereignty, and elastic capacity. The configuration serves financial institutions requiring sub-millisecond latency for transactional systems while tapping hyperscale resources for analytics and customer-facing applications. Infrastructure as a Service leads current spending as banks retain control over core ledger environments, while Platform as a Service represents the fastest-expanding segment as institutions containerize legacy applications without full refactoring. Threat Detection within the Security Approach dimension commands premium pricing, reflecting regulatory pressure for real-time anomaly identification across distributed environments.
The SEC's cybersecurity disclosure rules and the EU's Digital Operational Resilience Act reshape vendor selection criteria, mandating demonstrable resilience testing and incident reporting capabilities. India's RBI requires domestic data localization for payment systems, steering cloud architecture toward in-country private infrastructure with selective public burst capacity. Financial institutions must weigh sovereign compliance against AI innovation velocity as regulatory fragmentation intensifies.
Market Dynamics
Regulatory fragmentation across sovereign jurisdictions is forcing BFSI institutions to architect cloud environments that satisfy data localization mandates while preserving elastic compute access for AI workloads.
Growth Catalysts
- EU AI Act compliance deadlines:European banks are accelerating sovereign cloud deployments to meet algorithmic accountability requirements. The regulation mandates explainable AI infrastructure that hybrid architectures uniquely provide.
- RBI data localization framework:Indian payment processors must maintain transaction data within national boundaries. This steers architecture toward domestic private infrastructure with selective public burst capacity.
- Containerization of core banking:Kubernetes orchestration is automating legacy application modernization without full refactoring. Banks retain ledger control while gaining cloud-native deployment velocity.
Market Restraints
- Specialized talent scarcity:Cloud FinOps and sovereign architecture skills command premium compensation. The shortage constrains deployment velocity for mid-tier institutions.
- Cross-border data transfer friction:GDPR adequacy decisions and Schrems II rulings complicate transatlantic workload portability. Banks face legal uncertainty when bursting analytics workloads to US hyperscalers.
- Latency requirements for trading systems:Sub-millisecond transaction processing demands proximity hosting. This limits public cloud utilization for high-frequency trading infrastructure.
Strategic Opportunities
- Edge computing convergence:5G network slicing combined with micro data centers enables branch-level processing. Retail banks in India pilot this for rural credit scoring without central data movement.
- Green cloud incentives:EU CSRD disclosure requirements favor providers with renewable energy matching. Institutions can optimize Scope 3 emissions through selective cloud placement.
- Embedded finance expansion:Non-bank platforms require banking-as-a-service infrastructure. Hybrid cloud delivers the compliance isolation and API scalability this segment demands.
Industry Challenges
- Mainframe integration complexity:COBOL core systems resist containerization without expensive middleware layers. Banks struggle to maintain transactional integrity across distributed environments.
- Resilience testing certification:DORA mandates operational continuity demonstrations that exhaust internal audit capacity. Smaller institutions lack resources for scenario-based failure testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Cloud in BFSI Market |
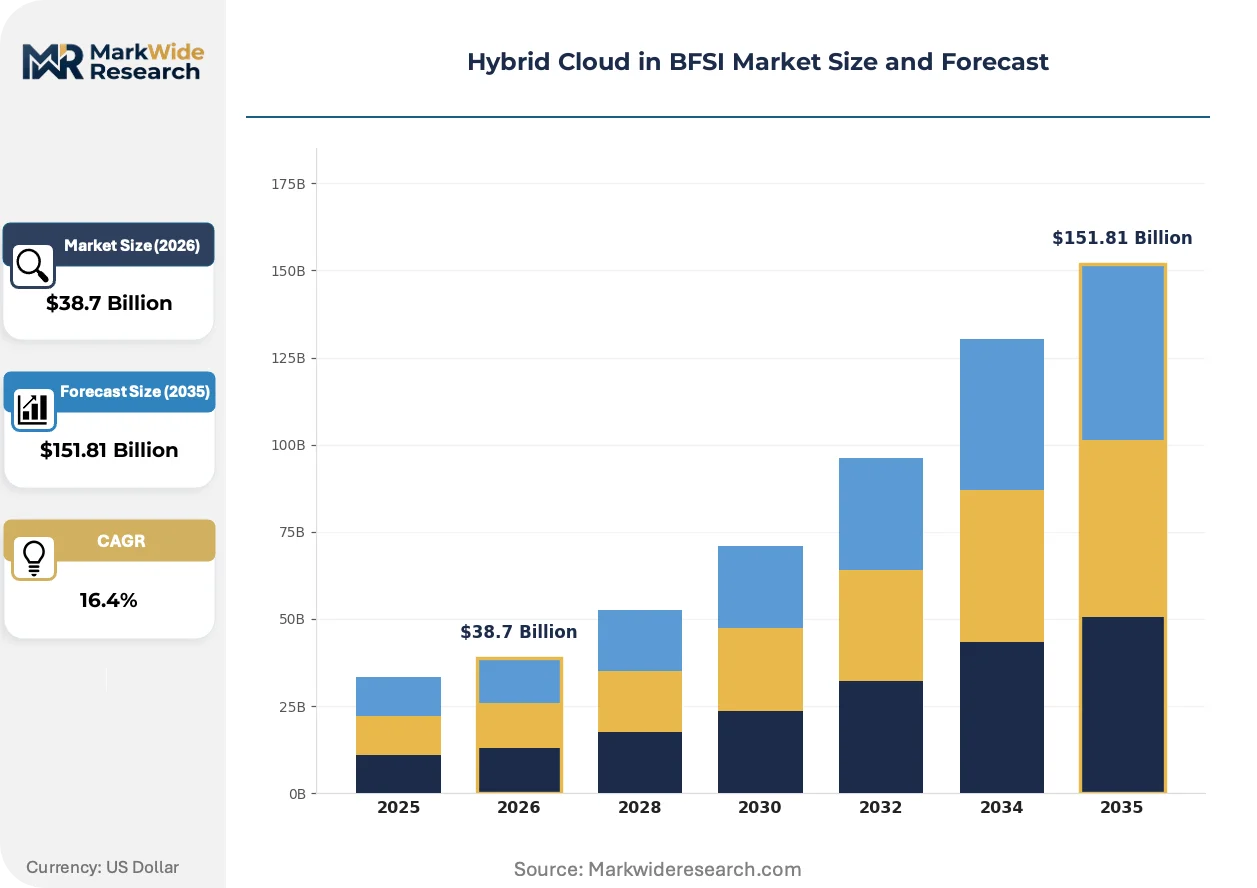
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Community Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Backup as a Service Client Type: Retail Banks, Investment Firms, Insurance Providers, Credit Unions Security Approach: Data Encryption, Identity Management, Compliance Solutions, Threat Detection |
| Companies Covered | Amazon Web Services, Microsoft, IBM, Google Cloud, Oracle, Hewlett Packard Enterprise, VMware, Cisco Systems, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Cloud in BFSI Market Emerging Trajectories
Workload portability standards and sovereign data architectures are converging to reshape how financial institutions architect distributed infrastructure across regulatory boundaries.
Confidential computing using hardware-based trusted execution environments is automating encryption-in-use for sensitive analytics. Large European banks deploy Intel TDX and AMD SEV-SNP enclaves to process customer data on shared infrastructure without exposing plaintext to cloud operators. This technology is automating compliance with data protection requirements that previously mandated physical isolation.
The EU Digital Operational Resilience Act mandates granular incident reporting and third-party risk management for critical ICT providers. Financial institutions must now contractually enforce subprocessor disclosure and audit rights across their cloud supply chains. German and French regulators lead enforcement, with DORA technical standards taking effect in early 2025.
Consumption-based infrastructure contracts are displacing traditional capacity reservations across buy-side institutions. Asset managers and hedge funds now prefer metered compute for risk modeling workloads rather than fixed private cloud allocations. This shift is most pronounced in London and Singapore trading hubs where workload volatility exceeds predictable baselines.
Hybrid Cloud in BFSI Market Segmentation
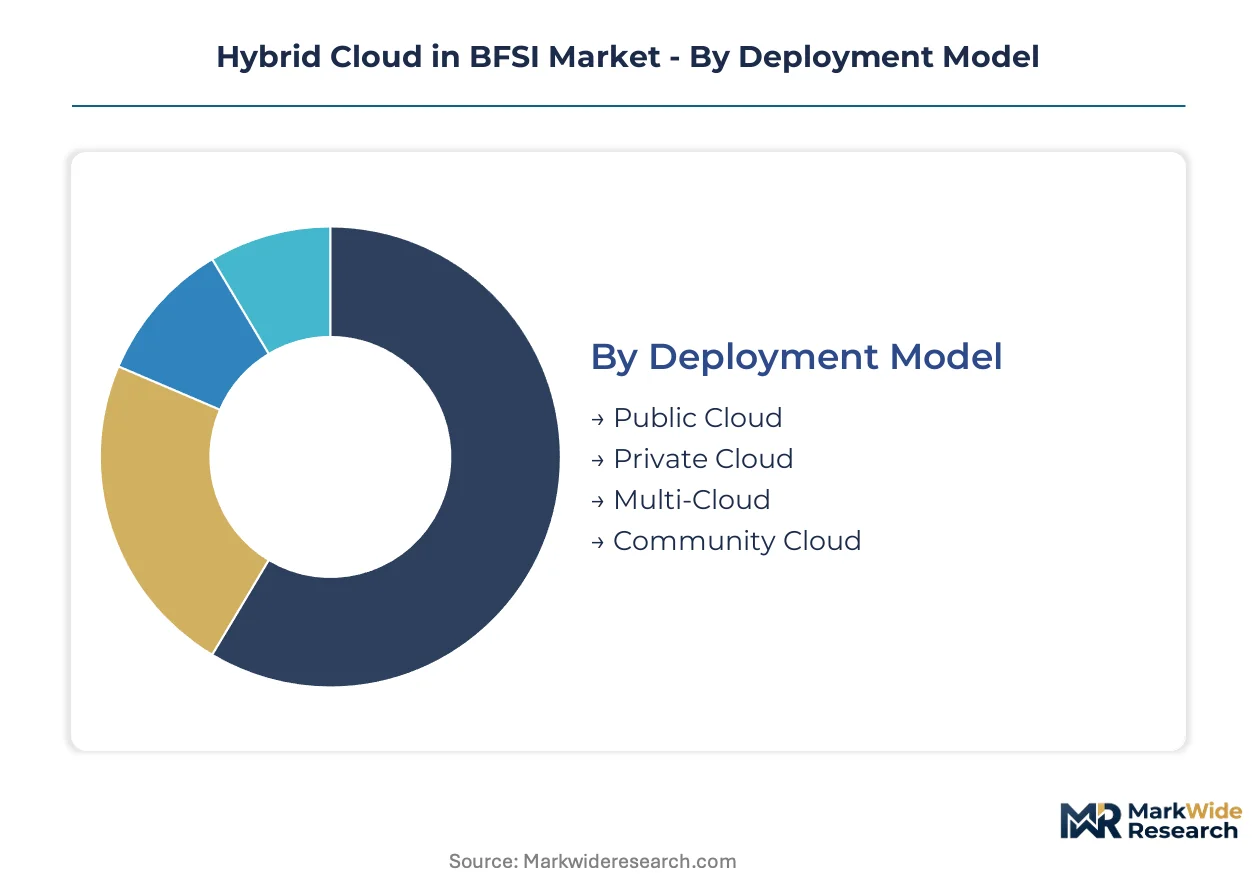
Hybrid cloud architectures in BFSI demand precise segmentation to match workload characteristics with regulatory constraints. Deployment models, service tiers, client categories, and security approaches each carry distinct compliance obligations and latency requirements that shape procurement decisions.
Deployment Model:
Volume deployment concentrates in public-facing configurations, while premium sovereignty commands private infrastructure investment.
- Public Cloud:Hyperscale elasticity supports customer-facing applications and batch analytics. Retail banks in India burst payment processing workloads to public infrastructure during festival season demand spikes.
- Private Cloud:Dedicated infrastructure maintains ledger control and data localization compliance. European institutions deploy sovereign private clouds to satisfy EU AI Act algorithmic accountability mandates.
- Multi-Cloud:Orchestration across heterogeneous environments prevents vendor lock-in. Asset managers distribute risk modeling workloads across providers to optimize compute pricing.
- Community Cloud:Shared infrastructure among affiliated institutions reduces compliance duplication. Credit union consortia in the United States deploy federated private clouds for collective security auditing.
Mature deployment sits with Private Cloud. Newer deployment is concentrated in Multi-Cloud.
Service Type:
Control requirements favor infrastructure ownership, while velocity demands push adoption toward abstracted platforms.
- Infrastructure as a Service:Bare-metal provisioning retains maximum workload customization. Core banking systems at major US retail banks run on IaaS to preserve COBOL environment stability.
- Platform as a Service:Container orchestration accelerates legacy modernization without full refactoring. Indian payment processors adopt PaaS to containerize RBI-compliant transaction pipelines.
- Software as a Service:Managed applications reduce operational overhead for non-differentiated functions. Insurance providers deploy SaaS policy administration to redirect engineering talent toward actuarial innovation.
- Backup as a Service:Automated resilience meets DORA continuity demonstration requirements. German banks contract BaaS for granular recovery point objectives across distributed environments.
Established spend concentrates in Infrastructure as a Service. Platform as a Service is gaining share fastest as containerization accelerates.
Client Type:
Regulatory scrutiny intensity varies sharply across institution categories, driving divergent architecture investments.
- Retail Banks:Massive transaction volumes demand sub-millisecond latency for core systems. Branch network digitization across the United States drives hybrid edge deployments for customer authentication.
- Investment Firms:Algorithmic trading infrastructure requires proximity hosting with burst capacity. London and Singapore hedge funds meter compute for volatility-sensitive risk models.
- Insurance Providers:Long-duration liability management favors stable private infrastructure. European insurers balance legacy policy systems with cloud-native claims automation.
- Credit Unions:Limited IT budgets prioritize managed service consumption over capital expenditure. Federated community clouds enable collective security posture without individual SOC buildout.
Complex deployment sits with Retail Banks. Emerging deployment is concentrated in Investment Firms modernizing trading infrastructure.
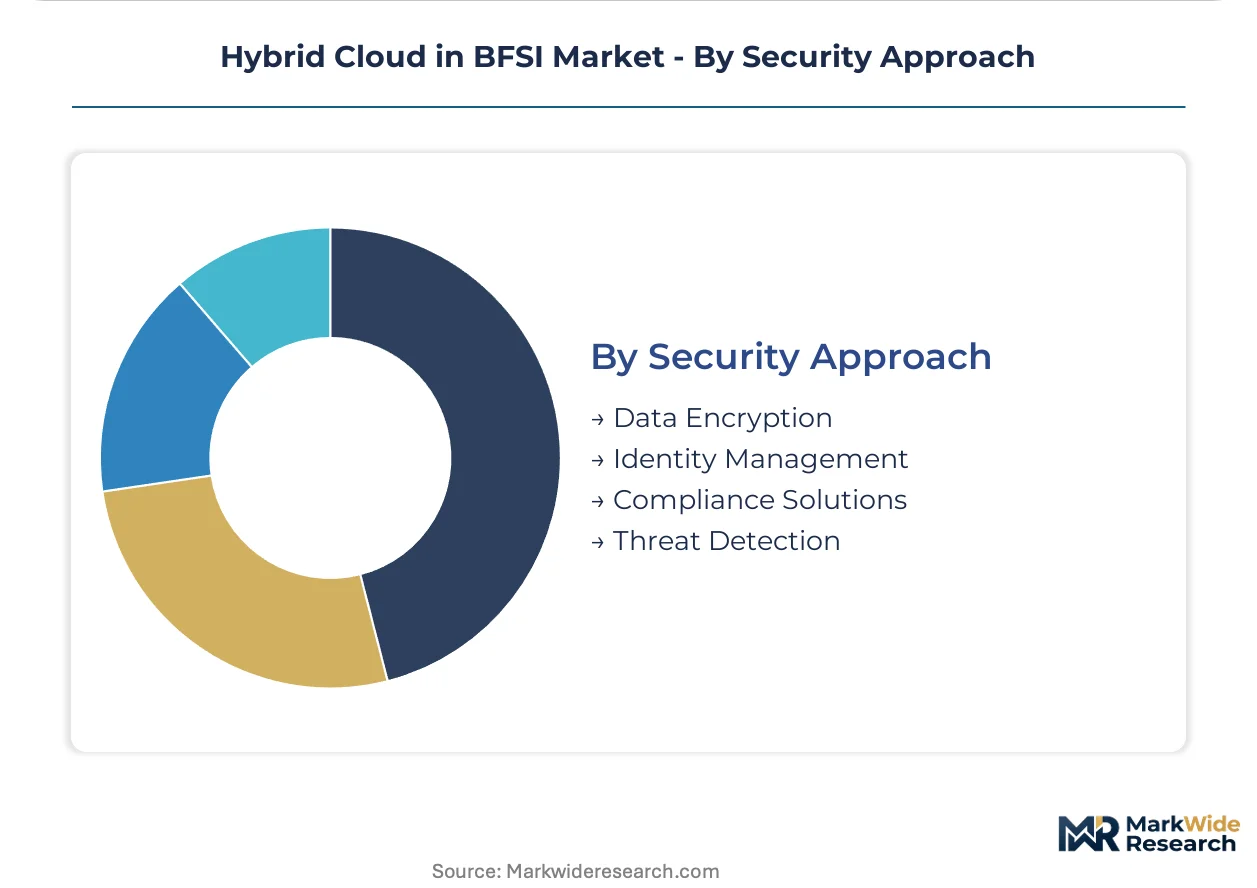
Security Approach:
Threat sophistication and regulatory enforcement intensity determine security spending allocation across control domains.
- Data Encryption:Hardware-based confidential computing automates encryption-in-use for shared infrastructure. Intel TDX and AMD SEV-SNP enclaves process European customer data without plaintext exposure to cloud operators.
- Identity Management:Zero-trust architectures segment access across distributed environments. RBI-mandated multi-factor authentication drives Indian banks toward cloud-native identity fabrics.
- Compliance Solutions:Automated policy enforcement maps technical controls to regulatory frameworks. DORA technical standards require continuous compliance monitoring across third-party processor chains.
- Threat Detection:Real-time anomaly identification commands premium pricing across distributed estates. SEC cybersecurity disclosure rules mandate demonstrable detection capabilities for material incidents.
Foundational deployment sits with Data Encryption. Accelerating deployment is concentrated in Threat Detection as real-time requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hybrid cloud infrastructure production concentrates among hyperscale providers headquartered in the United States, while consumption patterns diverge sharply across regulatory jurisdictions. European institutions prioritize sovereign data architectures, Indian payment processors drive domestic buildouts, and East Asian banks balance latency requirements against AI innovation demands.
United States
Retail banks dominate infrastructure investment as core modernization accelerates. SEC cybersecurity disclosure rules mandate demonstrable resilience testing, reshaping vendor procurement criteria. New York and Chicago financial centers host proximity-critical trading infrastructure with selective public cloud burst capacity for risk analytics.
Germany
Algorithmic accountability requirements under EU AI Act compliance deadlines drive sovereign private cloud deployment. DORA technical standards enforce granular incident reporting across third-party processor chains. Frankfurt's financial district anchors continental European infrastructure investment with confidential computing pilot programs.
India
Payment processors expand domestic data center capacity to satisfy RBI localization mandates for transaction systems. PLI scheme incentives for IT hardware manufacturing accelerate component ecosystem development. Mumbai and Bengaluru clusters concentrate hybrid architecture deployment for festival-season demand elasticity.
United Kingdom
Asset managers prefer metered compute contracts for volatility-sensitive risk modeling workloads. Prudential Regulation Authority expectations on operational resilience influence cloud architecture decisions. London trading hubs distribute workloads across providers to optimize pricing for unpredictable analytics demands.
Singapore
Wealth management platforms require banking-as-a-service infrastructure with compliance isolation capabilities. Monetary Authority of Singapore guidelines on technology risk management shape vendor selection. The city-state's data center cluster serves as regional hub for Southeast Asian financial institutions seeking low-latency connectivity.
Hybrid Cloud in BFSI Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the hybrid cloud infrastructure landscape. Market structure tilts toward consolidated hyperscale dominance at the infrastructure layer, with fragmentation persisting in specialized orchestration and security tooling. Three archetypes define competitive positioning: full-stack platform providers, legacy infrastructure modernizers, and cloud-native security specialists. Capacity expansion through sovereign data center buildouts and strategic partnerships for regulatory compliance certification represent dominant competitive vectors.
Within the full-stack platform tier, Microsoft and Amazon Web Services exemplify hyperscale diversification into financial services verticals. IBM occupies a position representing legacy infrastructure modernizers, anchoring regulated private cloud deployments through mainframe-integrated architectures. These three entities collectively illustrate how competitive positioning stratifies between cloud-native scale advantages and incumbent institutional relationships.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Google Cloud |
| Oracle |
| Hewlett Packard Enterprise |
| VMware |
| Cisco Systems |
| SAP |
| Others |
Supply Flow & Price Mechanics
DRAM spot price indices and silicon wafer contract rates cascade through server hardware procurement tiers, compressing infrastructure-as-a-service margins while sovereign compliance premiums inflate private cloud pricing bands across European and Indian deployments.
Pricing Analysis
Margin tightening in hyperscale infrastructure reflects hyperscaler capex expansion and GPU scarcity. Three-tier pricing structure across premium sovereign, standard compliant, and economy burst tiers separates RBI-mandated domestic data centers from festival-season public overflow. Certification grade under EU DORA and SEC cybersecurity disclosure rules commands 15-25% premia. Mid-tier credit unions exhibit highest price sensitivity; investment firms demonstrate lowest sensitivity due to algorithmic trading latency requirements.
Supply Chain Analysis
Certification gating through FedRAMP, BSI IT-Grundschutz, and MeitY empanelment restricts qualified server OEM participation to Intel, AMD, and domestic Indian hardware vendors under PLI scheme incentives. Supply concentrates in Taiwan for advanced semiconductors, Malaysia for memory assembly, and India for sovereign-compliant rack integration. Single-source vulnerability sits with Intel TDX and AMD SEV-SNP enclave components. Distribution runs through systems integrators with regulatory compliance practices, bypassing direct hyperscaler procurement for regulated institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as DORA technical standards and SEC disclosure rules exhaust smaller institutions' audit capacity, forcing exits and acquisition by scaled platforms with pre-certified compliance architectures.
For Market Incumbents: Acquire sovereign data center footprints in Frankfurt, Mumbai, and Singapore to anchor compliance-localized capacity. Defend against pure-play AI infrastructure entrants by embedding confidential computing enclaves into standard service tiers. Prioritize FedRAMP High and BSI C5 certification maintenance as competitive moats. For New Entrants and Emerging Players: Enter via embedded finance infrastructure partnerships, targeting credit union consortia in the United States with federated community cloud offerings. White-space concentrates in rural Indian branch-level edge computing for RBI-compliant credit scoring. Go-to-market through regional systems integrators with existing banking relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier managed service providers with DORA pre-certification in Germany and France. Long-term viability hinges on sovereign cloud architecture ownership rather than hyperscaler resale margins. Watch for RBI localization enforcement acceleration as inflection signal for Indian domestic capacity valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Data Center Acquisition | Establishes EU AI Act-compliant infrastructure in Frankfurt and Paris financial districts. |
| Confidential Computing Integration | Automates encryption-in-use for shared infrastructure without plaintext exposure to operators. |
| Community Cloud Federation | Enables credit union collectives to share compliance audit burdens across distributed estates. |
| Edge Computing Deployment | Supports RBI-mandated rural credit scoring without central data movement across Indian networks. |
| FinOps Talent Acquisition | Secures scarce cloud cost optimization expertise as deployment velocity constraints bite mid-tier institutions. |
Methodological Framework
Document review covered hyperscaler capex disclosures, RBI circulars on cloud frameworks, and EU DORA technical standards, complemented by interviews with cloud architects at tier-1 retail banks, compliance officers at German insurers, and procurement leads at Indian payment processors. Secondary sources included SEC cybersecurity filings, MeitY empanelment registers, and BSI certification databases. Bottom-up service tier sizing and top-down infrastructure spend estimates were triangulated against disclosed contract values.
Segment-level projections across deployment models, service types, and security approaches were generated through elasticity modeling of regulatory mandate timelines and containerization adoption curves. CAGRs were derived from scenario-weighted infrastructure investment trajectories. Key inputs included RBI localization enforcement probability, EU AI Act compliance cost pass-through rates, and confidential computing hardware availability constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated Schrems II enforcement or sudden GPU supply disruption. Model assumptions reflect documented regulatory deadlines and disclosed hyperscaler expansion plans. A model refresh is warranted upon material change in DORA technical standard implementation timelines or RBI payment data localization scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Computing Stack Layers Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Cloud Directory Services Software Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
United States Cloud Computing Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
Healthcare Cloud Infrastructure Market
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
AI Platform Cloud Service Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
Cloud CDN Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Government Cloud Computing Market
Cloud Computing
Cognitive Cloud Market