
 United States Data Center Cooling Market | 2026-2036
United States Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
United States Data Center Cooling Market Insights
Hyperscale cloud providers are rotating capital toward liquid-cooled infrastructure as AI training clusters exceed traditional air-cooled thermal limits. Vertiv Group Corp. leverages its critical power and thermal integration to anchor large-scale deployments. Schneider Electric sustains broad portfolio depth across chilled water and evaporative systems. CoolIT Systems specializes in direct-to-chip liquid cooling for high-density racks.
United States data center cooling encompasses thermal management systems engineered to maintain IT equipment within ASHRAE-specified temperature and humidity bands, typically delivering supply air between 18°C and 27°C while managing rack densities now exceeding 50 kW per cabinet. The primary commercial purpose centers on preventing thermal throttling, extending hardware lifespan, and enabling continuous operation of compute-intensive workloads. Liquid cooling represents the fastest-expanding cooling type as chip thermal design power escalates beyond air-handling practical limits. Edge computing deployments constitute an emerging deployment model where compact, modular cooling units address distributed latency requirements. Chilled water systems retain dominant share among legacy enterprise on-premises facilities with established mechanical infrastructure.
The EPA administers ENERGY STAR certification thresholds that shape procurement specifications for federal and enterprise buyers. ASHRAE publishes thermal guidelines that define allowable and recommended environmental envelopes, directly influencing cooling system sizing and redundancy architecture. The Department of Energy funds research into advanced cooling technologies including two-phase immersion and heat reuse systems. Stakeholders must monitor evolving state-level water usage restrictions in drought-prone regions where evaporative cooling faces regulatory pressure.
Market Dynamics
AI training clusters are forcing a generational shift from air-cooled to liquid-cooled infrastructure, with rack densities exceeding 50 kW per cabinet rendering traditional CRAC units thermally obsolete.
Growth Catalysts
- EPA ENERGY STAR certification:Federal procurement mandates require cooling equipment meeting strict efficiency thresholds, pulling enterprise buyers toward certified liquid-cooled systems.
- Northern Virginia's Data Center Alley:Hyperscale concentration in Loudoun and Prince William counties generates concentrated demand for high-capacity thermal management.
- Direct-to-chip liquid cooling:Thermal design power escalation beyond 700W per GPU is making immersion and cold-plate systems operationally necessary.
Market Restraints
- Copper supply concentration:Cold-plate manufacturing depends on Chilean and Peruvian copper concentrate, exposing cost volatility to mining disruptions.
- Water scarcity restrictions:Arizona and California state regulations are constraining evaporative cooling deployment in drought-prone Southwest markets.
- Legacy infrastructure lock-in:Enterprise on-premises facilities with 15-20 year depreciation cycles cannot economically retrofit chilled water plants for liquid cooling.
Strategic Opportunities
- Dallas-Fort Worth metroplex:Texas's deregulated power market and lower land costs are attracting secondary hyperscale clusters needing scalable thermal solutions.
- Heat reuse integration:District heating partnerships with municipal utilities in Minneapolis and Seattle monetize waste heat from AI training facilities.
- Edge computing modular units:5G rollout and autonomous vehicle data processing are creating distributed demand for compact, self-contained cooling modules.
Industry Challenges
- Fluid chemistry expertise:Dielectric coolant selection and corrosion management require specialized chemical engineering talent scarce in traditional HVAC labor pools.
- ASHRAE compliance timelines:Evolving thermal guidelines for liquid-cooled environments create certification uncertainty for equipment manufacturers.
- Hybrid infrastructure orchestration:Facilities must simultaneously manage air-cooled legacy racks and liquid-cooled AI clusters under unified building management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Data Center Cooling Market |
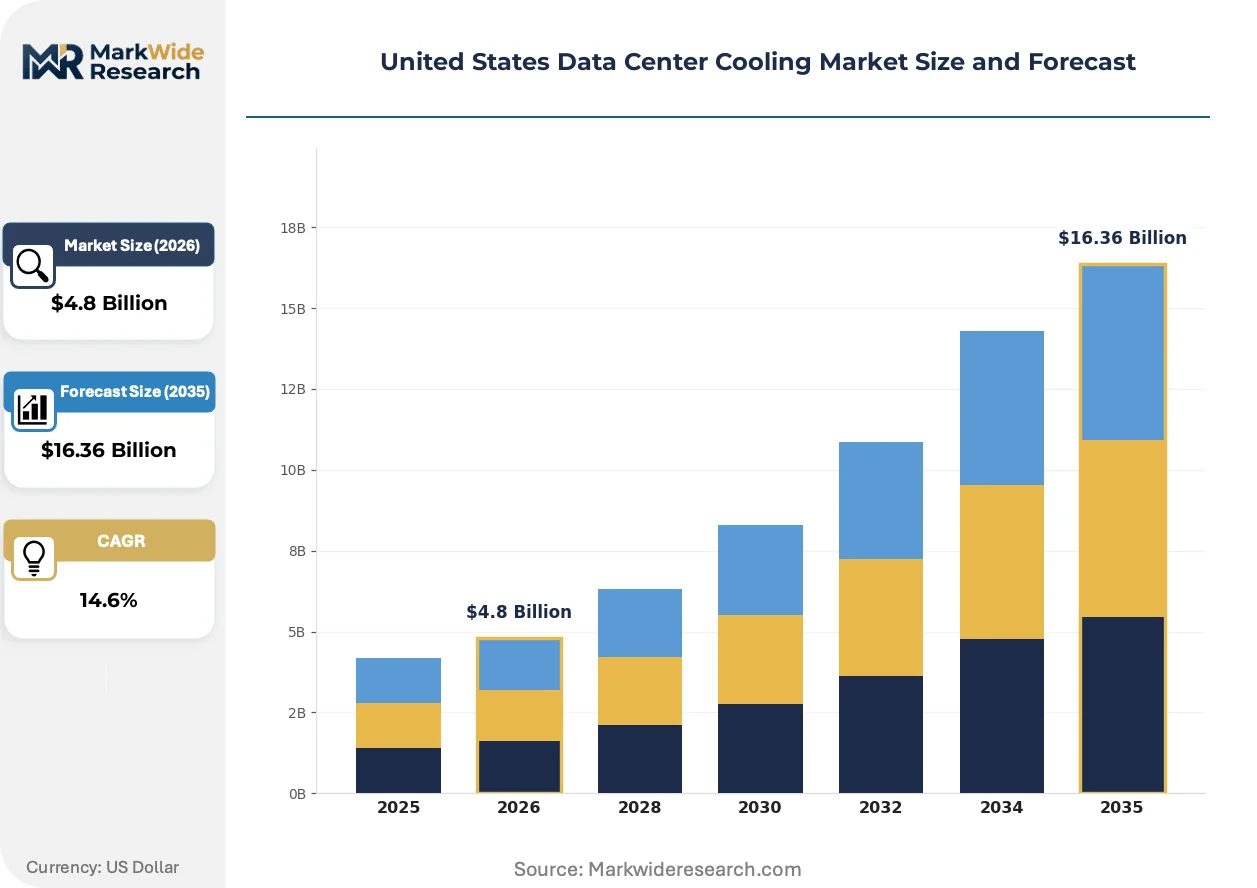
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Chilled Water, Air-Cooled, Liquid Cooling, Evaporative Cooling End User: IT Services, Telecommunications, Cloud Providers, Colocation Providers Component: Cooling Equipment, Power Distribution, Monitoring Solutions, Racks Deployment Model: On-Premises, Hybrid, Multi-Tenant, Edge Computing |
| Companies Covered | Modine Manufacturing Company, Rittal GmbH & Co. KG, Vertiv Group Corp., CoolIT Systems, Stulz GmbH, Schneider Electric, Green Revolution Cooling Inc., Carrier, Johnson Controls International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Data Center Cooling Market Trends and Innovations
Liquid cooling architectures are fragmenting across multiple technical approaches as no single solution dominates all density tiers and climate zones.
Direct-to-chip cold plates are bifurcating the high-performance computing segment from hyperscale cloud deployments. AI training operators are adopting proprietary cold-plate designs at 80-120 kW per rack, while inference-focused facilities remain on hybrid air-liquid systems. This technical split is compressing vendor R&D budgets across divergent product roadmaps.
The EPA's tightening ENERGY STAR certification thresholds are mandating variable-speed compressor and fan controls for federal procurement eligibility. Equipment manufacturers must submit third-party test data demonstrating part-load efficiency performance. Chilled water system vendors serving federal integrators are accelerating controller software development to maintain specification compliance.
Colocation buyers are unbundling thermal infrastructure from power contracts, negotiating separate service-level agreements for temperature stability and energy efficiency. Wholesale data center operators in Northern Virginia are responding with transparent metering of mechanical plant energy consumption. This contractual separation is most visible among financial services tenants with ESG reporting obligations.
United States Data Center Cooling Market Segmentation
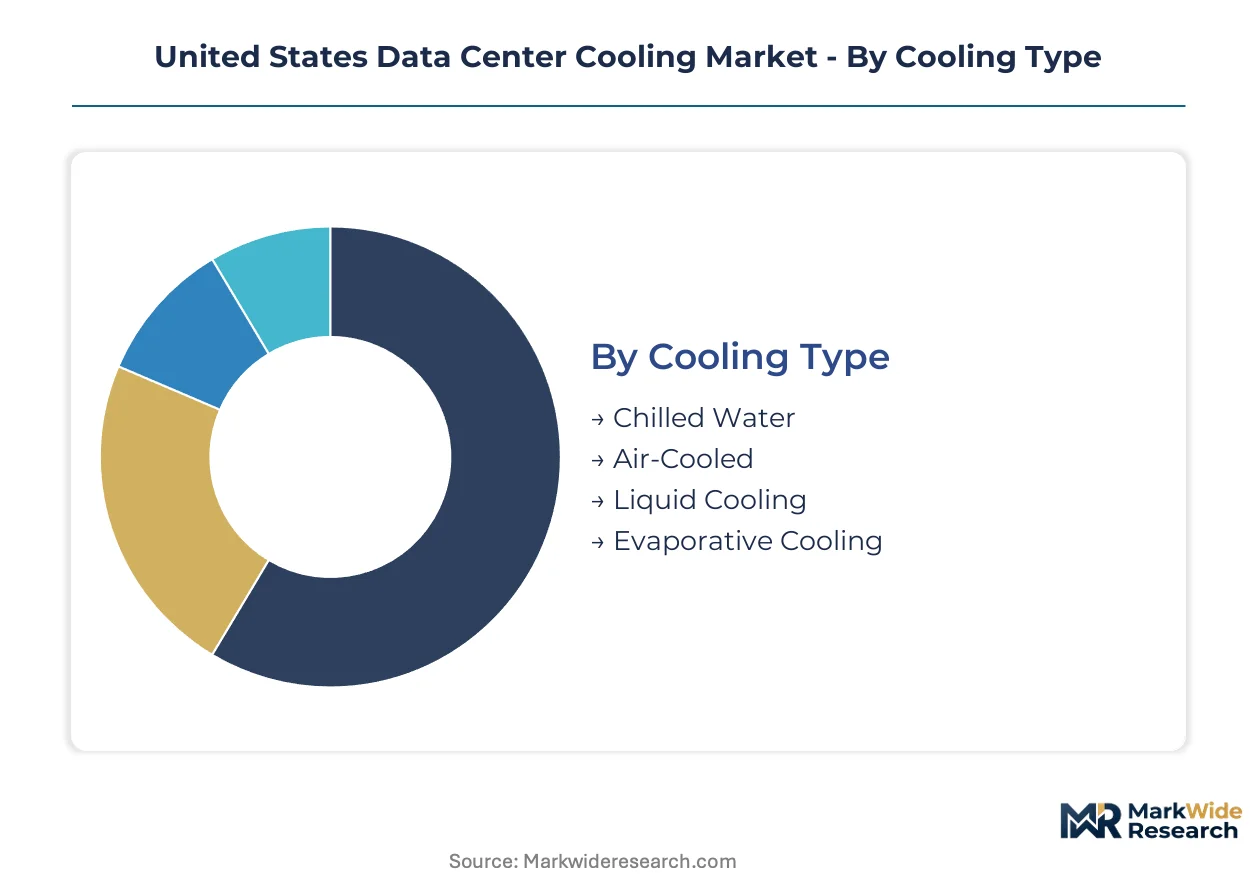
Segmentation in United States data center cooling reveals how thermal infrastructure investment splits across legacy mechanical systems and emerging liquid architectures. Procurement patterns diverge sharply between hyperscale cloud operators retrofitting for AI density and enterprise facilities extending depreciated air-cooled plants.
Cooling Type:
Liquid cooling exerts the strongest substitution pressure on incumbent technologies as GPU thermal design power crosses practical air-handling thresholds.
- Liquid Cooling:Direct-to-chip cold plates and immersion systems handle rack densities exceeding 50 kW per cabinet. Northern Virginia's hyperscale clusters are standardizing on proprietary cold-plate designs for AI training workloads.
- Chilled Water:Centralized mechanical plants with CRAH units dominate legacy enterprise facilities in established markets. Dallas-Fort Worth colocation providers favor these systems for their proven reliability and maintenance accessibility.
- Air-Cooled:CRAC and in-row cooling units serve low-density legacy racks and edge deployments. Phoenix and Tucson operators face mounting regulatory pressure on water-free alternatives under Arizona drought restrictions.
- Evaporative Cooling:Adiabatic and swamp cooling systems exploit dry climates for energy efficiency. California's Title 22 water use regulations are constraining new installations in drought-prone Southern California markets.
Chilled water anchors the volume base while liquid cooling gains share at the steepest rate.
End User:
Cloud providers command the highest capital intensity per square foot, reshaping supplier relationships and certification requirements across the value chain.
- Cloud Providers:Hyperscale operators including AWS, Microsoft Azure, and Google Cloud deploy custom liquid-cooled racks at 80-120 kW density. Their procurement specifications are becoming de facto industry standards for thermal efficiency metrics.
- Colocation Providers:Wholesale and retail colocation operators unbundle thermal SLAs from power contracts to attract ESG-conscious financial services tenants. Northern Virginia operators lead this contractual innovation with transparent mechanical plant metering.
- IT Services:Systems integrators and managed service providers favor hybrid cooling configurations supporting mixed legacy and modern workloads. Their procurement prioritizes interoperability over peak thermal performance.
- Telecommunications:5G edge and central office facilities require compact, modular cooling for distributed latency-sensitive processing. Texas and Florida markets show concentrated deployment of self-contained thermal units.
Colocation providers represent the largest addressable customer base while cloud providers drive the most aggressive technology refresh cycles.
Component:
Power distribution and cooling equipment are converging into integrated thermal-electrical skids as rack densities complicate separate procurement.
- Cooling Equipment:Chillers, CRAH units, cooling towers, and liquid cooling manifolds constitute the core thermal infrastructure. EPA ENERGY STAR certification thresholds are forcing variable-speed control upgrades across federal procurement channels.
- Power Distribution:PDUs, busbars, and rack-level power supplies increasingly embed thermal monitoring for integrated management. ASHRAE guidelines are tightening power usage effectiveness correlation with cooling system design.
- Monitoring Solutions:DCIM platforms and sensor networks track temperature, humidity, and airflow for predictive maintenance. Federal data center consolidation initiatives are accelerating standardized monitoring procurement.
- Racks:Enclosures, containment systems, and cable management support airflow optimization and liquid cooling integration. High-density AI clusters are driving demand for liquid-cooled rack architectures with integrated manifolds.
Cooling equipment generates the largest revenue pool while monitoring solutions expand most quickly as operators pursue predictive thermal management.
Deployment Model:
Edge computing is fragmenting the traditional data center cooling market into distributed, small-footprint thermal requirements.
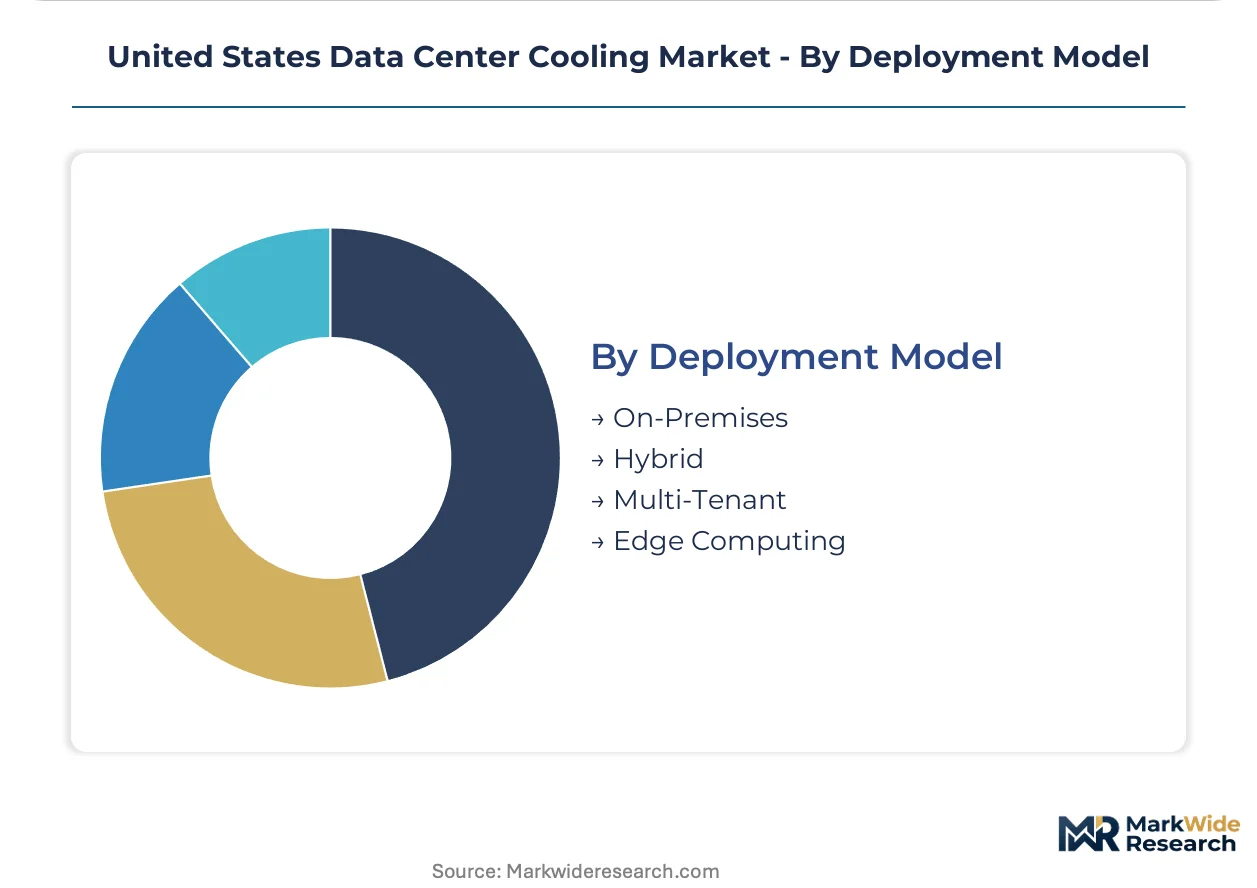
- On-Premises:Enterprise-owned facilities with dedicated mechanical infrastructure and 15-20 year depreciation cycles. Legacy chilled water plants in Midwest manufacturing corridors face the steepest retrofit economics against liquid cooling alternatives.
- Multi-Tenant:Shared colocation facilities with standardized cooling infrastructure serving diverse tenant densities. Northern Virginia's wholesale market concentrates the most sophisticated multi-tenant thermal engineering.
- Hybrid:Split workloads across owned and colocated infrastructure with coordinated cooling strategies. Financial services firms in New York and Chicago metro areas favor this model for regulatory data sovereignty.
- Edge Computing:Distributed micro data centers and modular units for autonomous vehicle, IoT, and 5G processing. Texas, Arizona, and Nevada are seeing concentrated deployment of self-contained cooling modules for desert edge locations.
Multi-tenant deployments anchor current capacity additions while edge computing infrastructure scales fastest in unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud providers concentrate new capacity in three primary U.S. corridors, each shaped by distinct power market structures, water availability constraints, and state-level incentive programs. EPA ENERGY STAR certification requirements and ASHRAE thermal guidelines apply uniformly, though enforcement intensity varies by local air quality districts.
Northern Virginia
Loudoun and Prince William counties host the densest concentration of hyperscale facilities globally, with Dominion Energy's electrical infrastructure supporting multi-gigawatt expansions. The Virginia Department of Environmental Quality enforces stormwater and air permits that constrain evaporative cooling deployment. Data Center Alley operators are standardizing proprietary direct-to-chip liquid cooling for AI training clusters exceeding 80 kW per rack.
Dallas-Fort Worth Metroplex
Texas's ERCOT deregulated power market attracts secondary hyperscale clusters seeking price volatility arbitrage and lower land costs. The Texas Commission on Environmental Quality regulates industrial water withdrawals, though restrictions remain lighter than Southwestern neighbors. Dallas-Fort Worth colocation providers favor chilled water mechanical plants for their proven reliability across mixed-density tenant bases.
Phoenix-Tucson Corridor
Arizona's desert climate and renewable energy portfolio draw operators targeting carbon-neutral commitments, though water scarcity poses operational constraints. The Arizona Department of Water Resources enforces groundwater management requirements that limit evaporative cooling expansion. Phoenix operators are retrofitting legacy air-cooled facilities with adiabatic hybrid systems to maintain compliance.
Pacific Northwest
Washington and Oregon leverage hydroelectric power abundance and mild ambient temperatures to minimize mechanical cooling energy intensity. The Washington State Department of Ecology regulates thermal discharge into the Columbia River basin, affecting water-side economizer designs. Quincy and Boardman industrial parks concentrate Microsoft's and Amazon's most efficient hyperscale deployments.
Chicago Metro
Illinois's central geographic position serves financial services latency requirements with fiber connectivity to East Coast and West Coast markets. The Illinois Environmental Protection Agency enforces Clean Air Act permits that shape diesel backup generator and cooling tower specifications. Elk Grove Village and Aurora host enterprise-owned facilities extending depreciated chilled water infrastructure.
United States Data Center Cooling Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized thermal engineering firms competing across liquid cooling transition cycles. The vendor base splits between legacy HVAC incumbents with chilled water expertise and emerging specialists in direct-to-chip architectures. Two strategic archetypes dominate: integrated power-thermal platform providers and pure-play liquid cooling component suppliers. Competitive dynamics center on federal procurement certification capture and hyperscale custom specification partnerships.
Among diversified industrial players, Vertiv Group Corp. and Schneider Electric occupy positions spanning critical power and thermal integration, while CoolIT Systems exemplifies the specialized liquid cooling archetype focused on high-density rack architectures. Modine Manufacturing Company and Carrier represent established thermal equipment fabricants adapting variable-speed control portfolios to EPA ENERGY STAR thresholds. Rittal GmbH & Co. KG, Stulz GmbH, and Green Revolution Cooling Inc. sit within the precision cooling specialist tier, with Johnson Controls International anchoring building automation integration capabilities across hybrid air-liquid facilities.
| Leading Market Players |
|---|
| Modine Manufacturing Company |
| Rittal GmbH & Co. KG |
| Vertiv Group Corp. |
| CoolIT Systems |
| Stulz GmbH |
| Schneider Electric |
| Green Revolution Cooling Inc. |
| Carrier |
| Johnson Controls International |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with hyperscale cloud operators lock in supply access for liquid cooling component manufacturers while providing price visibility across multi-year deployment cycles. These arrangements concentrate purchasing power among AWS, Microsoft Azure, and Google Cloud procurement teams, compressing margins for chilled water system vendors serving fragmented enterprise buyers.
Pricing Analysis
EPA ENERGY STAR certification dictates the pricing tier structure across federal and enterprise procurement channels. Three-tier pricing structure across premium certified, standard efficiency, and economy non-certified levels separates hyperscale direct-to-chip systems from legacy chilled water retrofits. Cost compression in air-cooled segments is intensifying because Arizona and California water restrictions are forcing rapid obsolescence. Cloud providers exhibit lowest price sensitivity due to TCO-focused procurement, while enterprise IT services buyers prioritize capital expenditure minimization.
Supply Chain Analysis
Strategic stockpiling of Chilean and Peruvian copper concentrate dominates cold-plate manufacturing inventory strategies amid mining disruption risks. Component sourcing draws from China for precision-manufactured manifolds, Germany for high-efficiency compressor units, and domestic U.S. fabricators for containment systems. Single-source vulnerability concentrates in South American copper concentrate supply. Distribution runs through direct OEM relationships with hyperscale operators and regional HVAC distributor networks serving enterprise retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States data center cooling sits in early-cycle expansion as AI training cluster deployment accelerates liquid cooling penetration beyond traditional air-handled density limits. Federal procurement mandates and state-level water restrictions are compressing replacement timelines for legacy infrastructure.
For Market Incumbents: Fortify certification capture by accelerating EPA ENERGY STAR variable-speed control submissions ahead of federal procurement deadlines. Deepen captive supply of Chilean copper concentrate through offtake partnerships to insulate cold-plate manufacturing from mining disruption volatility. For New Entrants and Emerging Players: EPA ENERGY STAR fast-track certification offers the most penetrable entry vector for federal integrator relationships. Target Dallas-Fort Worth colocation providers with modular liquid cooling skids designed for ERCOT power market volatility. Lead with transparent mechanical plant metering to attract ESG-conscious financial services tenants unbundling thermal SLAs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among colocation providers with unbundled thermal service agreements and transparent metering infrastructure. Five-to-ten year viability favors integrated power-thermal platform providers over pure-play component suppliers. Monitor hyperscale custom specification partnership announcements as inflection indicators for vendor market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Chip Cold Plate Standardization | Proprietary designs at 80-120 kW per rack are becoming hyperscale procurement specifications. |
| Federal Certification Fast-Track | EPA ENERGY STAR compliance opens federal and enterprise procurement channels. |
| Copper Concentrate Offtake Partnerships | Chilean and Peruvian mining relationships insulate cold-plate manufacturing cost volatility. |
| Heat Reuse District Heating Integration | Municipal utility partnerships in Minneapolis and Seattle monetize AI training waste heat. |
| Edge Computing Modular Unit Deployment | Self-contained cooling modules address 5G and autonomous vehicle distributed processing demand. |
Research Methodology
Operator-level perspectives from data center facility managers, hyperscale cloud procurement executives, colocation provider engineering directors, and federal integrator specification writers anchored the qualitative base. Primary interviews combined with secondary validation against EPA ENERGY STAR certification databases, ASHRAE technical guideline publications, SEC 10-K capital expenditure disclosures from hyperscale operators, and state-level environmental permit filings. Bottom-up deployment tracking across Northern Virginia, Dallas-Fort Worth, and Phoenix-Tucson corridors triangulated against top-down equipment vendor shipment analysis.
Sensitivity analysis tested forecast outputs against varying AI training cluster penetration rates and liquid cooling substitution elasticities across the projection horizon. Segmentation dimensions modeled include cooling type, end user archetype, component category, and deployment model complexity tier. CAGRs were derived from equipment vendor revenue trajectory analysis and hyperscale capital expenditure commitment patterns. Industry-specific inputs incorporated GPU thermal design power escalation curves and state-level water restriction enforcement timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained AI infrastructure investment and stable copper concentrate supply; material deviation would warrant model refresh. Revision becomes warranted when hyperscale capital expenditure commitments or EPA certification threshold adjustments cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
Singapore Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
China Data Center Cooling Market