
 Global Cloud Business Email Market | 2026-2036
Global Cloud Business Email Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Business Email Market Analysis
GDPR enforcement is realigning the cost-of-entry calculus for cloud email providers serving European enterprises. Microsoft anchors its position through deep integration with productivity suites and enterprise compliance tooling. Google differentiates via AI-native search and classification capabilities embedded within Gmail for business. Amazon Web Services leverages its infrastructure footprint to offer email hosting as a bundled component of broader cloud contracts.
Cloud business email encompasses hosted messaging platforms delivering SMTP, IMAP, and webmail access with guaranteed uptime SLAs, typically exceeding 99.9% availability, alongside encryption protocols for enterprise communication governance. Its primary commercial purpose centers on replacing on-premises mail servers with scalable, maintenance-free infrastructure that IT administrators manage through centralized dashboards. Email Hosting and Security Solutions command the largest revenue pools as enterprises prioritize threat protection alongside core messaging functionality. Hybrid Cloud deployment is gaining traction fastest among large enterprises seeking to retain sensitive archives on-premises while routing active traffic through public infrastructure.
The EU AI Act, GDPR, and ISO 27001 standards collectively shape product architecture by mandating automated data classification, breach notification timelines, and certified security management systems for cross-border email flows. Japan's METI guidelines and China's GB standards add further compliance layers for providers operating across Asia-Pacific data centers. Stakeholders must evaluate whether their current provider's certification portfolio covers emerging jurisdictions before committing to multi-year enterprise agreements.
Market Dynamics
Data sovereignty mandates from the EU AI Act and GDPR are forcing cloud email providers to rearchitect storage and processing footprints, privileging vendors with certified regional data centers over those operating centralized global infrastructure.
Growth Catalysts
- Financial Services Compliance:Banks and insurers in Germany, Japan, and the United States are migrating from on-premises Exchange servers to cloud platforms with native audit trails and e-discovery tooling.
- ISO 27001 Certification:Enterprise procurement teams now mandate certified security management systems for cross-border email flows, accelerating provider investment in compliance infrastructure.
- Hybrid Cloud Architectures:Large enterprises retain sensitive archives on-premises while routing active traffic through public infrastructure, expanding addressable market for integration specialists.
Market Restraints
- Data Residency Compliance Costs:The EU AI Act and GDPR mandate automated classification and localized processing, raising operational expenditure for providers without existing European data center footprints.
- Concentrated Infrastructure Dependency:Three hyperscale providers control the majority of underlying compute and storage capacity, creating single-point-of-failure risk for downstream email hosting services.
- Legacy Migration Friction:Decades of on-premises mail server customization create technical debt that slows cloud transitions in regulated industries with complex routing rules.
Strategic Opportunities
- Sovereign Cloud Demand in Germany:Enterprises subject to Bundesdatenschutzgesetz requirements seek providers offering data processing strictly within national borders.
- AI-Native Classification Convergence:Integration of automated content scanning with email workflows creates new revenue pools for vendors combining messaging with compliance automation.
- Japan METI Guidelines:The Ministry of Economy, Trade and Industry's cybersecurity framework for cloud services creates certified provider status that accelerates enterprise sales cycles.
Industry Challenges
- Cross-Border Certification Timelines:Providers seeking multi-jurisdictional coverage must sequence ISO 27001, GDPR adequacy decisions, and national security certifications, stretching go-to-market timelines.
- Specialized Engineering Talent Scarcity:Shortage of professionals combining email infrastructure expertise with AI governance and data residency law slows product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Business Email Market |
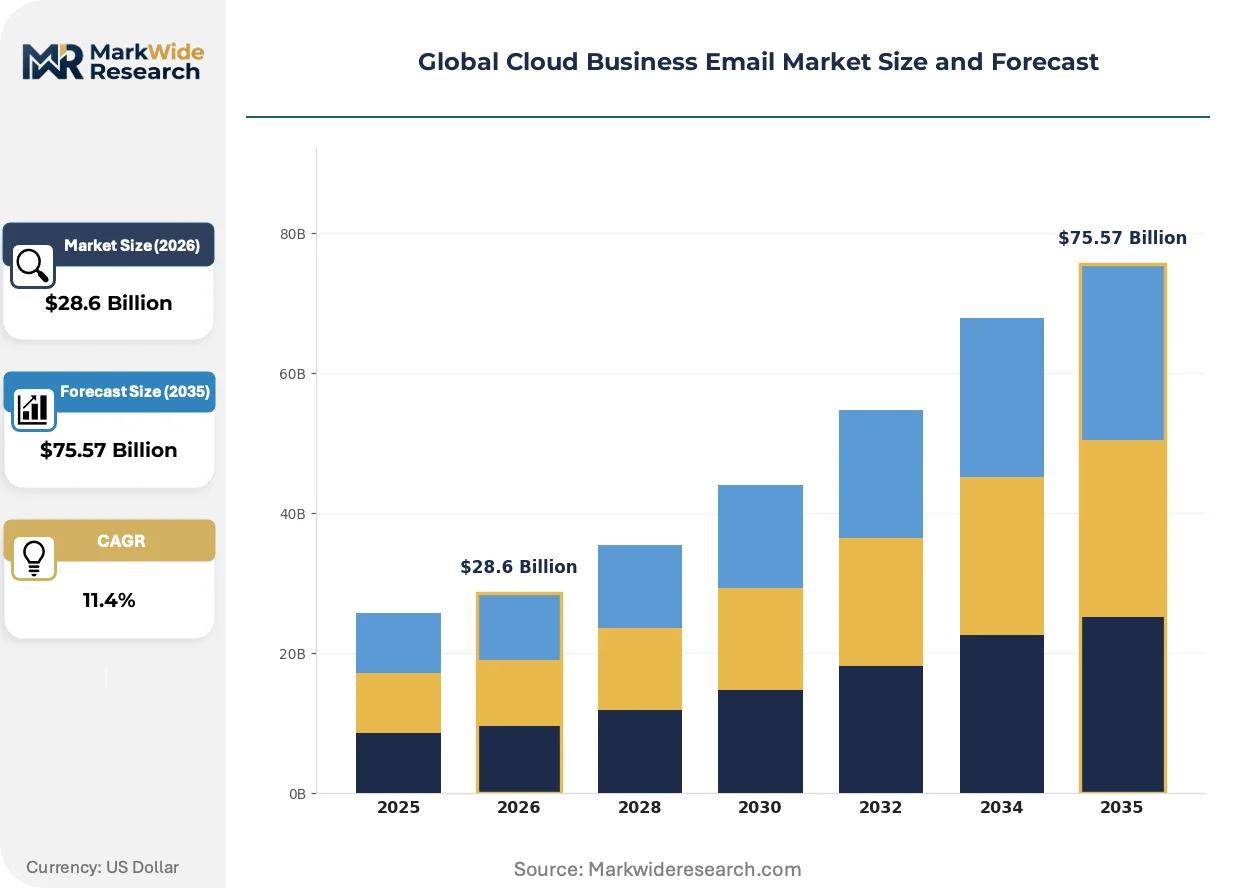
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Email Hosting, Email Archiving, Migration Services, Security Solutions Customer Type: SMEs, Large Enterprises, Government Agencies, Nonprofits Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Tenant Integration Level: APIs, Webhooks, Plugins, Standalone Solutions |
| Companies Covered | Zoho Corporation, Alibaba Cloud, Microsoft, Rackspace Technology, Tencent, Google, IBM, Proton AG, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Business Email Market Emerging Trajectories
Artificial intelligence is embedding into core email workflows, transforming search, classification, and threat detection from bolt-on features into native platform capabilities that reshape buyer evaluation criteria.
Native AI search and classification is overtaking rule-based filtering in enterprise Gmail deployments. Financial services and legal sectors in the United States are adopting these capabilities fastest, replacing legacy e-discovery appliances. This compression of the threat detection and compliance workflow into a single platform is reducing standalone security software procurement.
The EU AI Act's risk-based classification system for automated decision-making is reshaping product architecture for providers serving European enterprises. High-risk applications involving sensitive personal data in email flows now require conformity assessments and human oversight mechanisms. German and French enterprises are prioritizing vendors with pre-certified AI governance modules.
Enterprise buying committees are consolidating email, productivity, and security procurement under single-vendor contracts, displacing best-of-breed point solutions. This bundling preference favors providers with integrated suites and certified compliance tooling. The pattern is most pronounced in Japan and the United States, where IT procurement teams face pressure to reduce vendor management overhead.
Global Cloud Business Email Market Segmentation
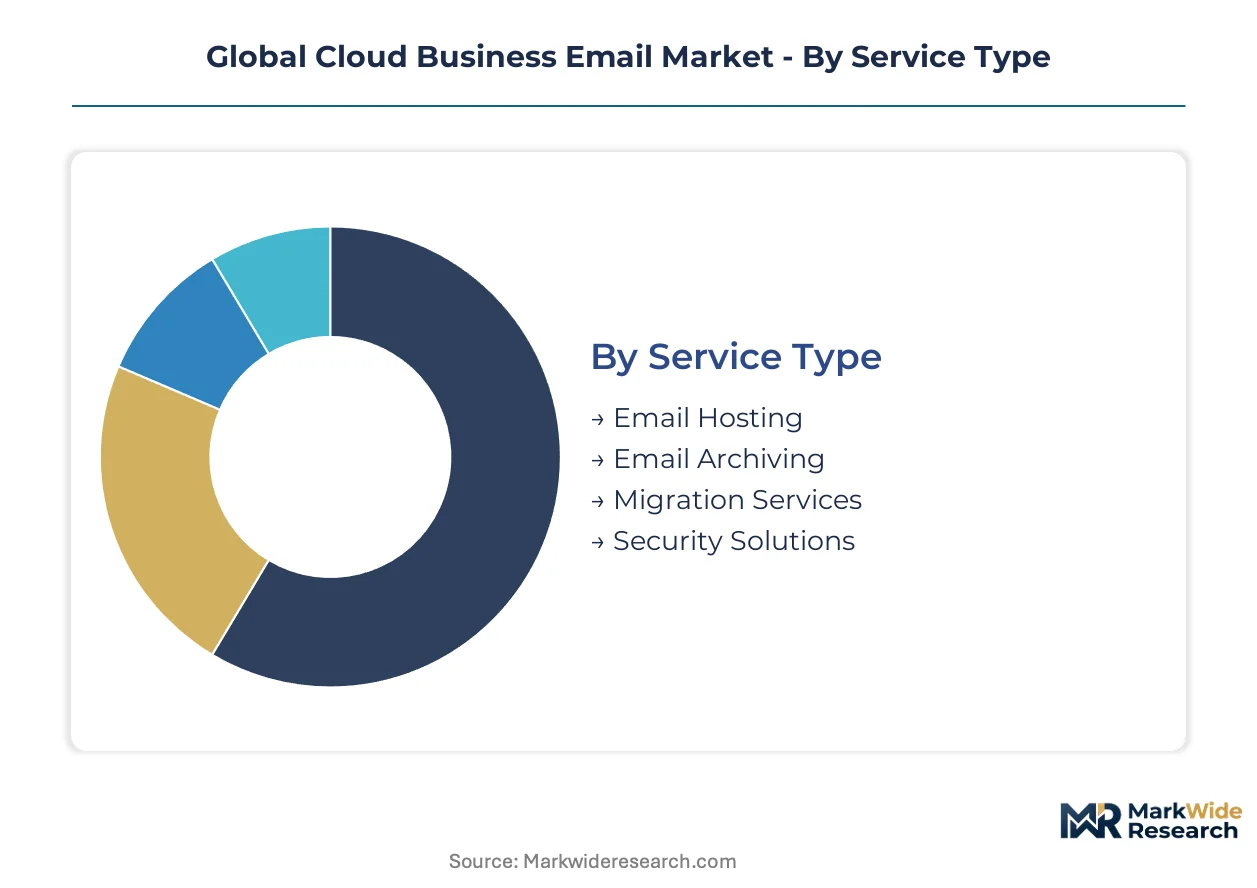
Cloud business email segmentation reveals how procurement priorities diverge across organizational scale, compliance exposure, and technical architecture preferences. Buyers evaluate service tiers through the lens of data residency obligations, integration complexity, and archive retention mandates that vary sharply by industry and geography.
Service Type:
Supply concentration in security-forward offerings is reshaping vendor investment priorities as enterprises bundle threat protection with core messaging infrastructure.
- Email Hosting:Core SMTP, IMAP, and webmail delivery with guaranteed uptime SLAs exceeding 99.9 percent availability. Financial services firms in Germany and the United States concentrate procurement here, driven by Bundesdatenschutzgesetz and SEC audit trail requirements that mandate native logging capabilities.
- Security Solutions:Integrated threat detection, encryption protocols, and compliance automation layered atop messaging flows. Japanese banks subject to METI cybersecurity guidelines are adopting these bundles fastest, displacing standalone security appliances with unified platforms.
- Email Archiving:Long-term retention with e-discovery indexing and legal hold management for regulated industries.
- Migration Services:Technical transition support from on-premises Exchange and Notes environments to cloud infrastructure.
Today's leader: Security Solutions. Tomorrow's challenger: Migration Services.
Customer Type:
Cost tier differentiation separates volume-driven SME provisioning from the compliance-heavy customization demanded by government and financial buyers.
- Large Enterprises:Complex multi-domain deployments with hybrid architectures retaining sensitive archives on-premises while routing active traffic through public infrastructure. These buyers in Japan and the United States command the steepest expansion trajectory as they consolidate productivity and security procurement under single-vendor contracts.
- Government Agencies:Sovereign cloud mandates with strict data residency and classified communication requirements. German federal and state bodies are concentrating demand here, privileging providers with certified national data centers over centralized global infrastructure.
- SMEs:Standardized multi-tenant deployments with limited customization and self-service administration.
- Nonprofits:Cost-optimized tiers with grant-funded migration support and reduced compliance tooling.
Large Enterprises anchor current revenue pools. Government Agencies are gaining share fastest.
Deployment:
Application-specific architecture preferences are fragmenting the vendor landscape between pure public offerings and compliance-driven private infrastructure.
- Hybrid Cloud:Split deployments retaining sensitive archives on-premises while routing active email traffic through public infrastructure. Large enterprises in regulated U.S. sectors are adopting this model fastest, balancing scalability with legacy system integration.
- Private Cloud:Dedicated single-tenant infrastructure with full control over data residency and encryption key management. French and German enterprises subject to GDPR and EU AI Act high-risk classification requirements are concentrating procurement here.
- Public Cloud:Shared multi-tenant infrastructure with standardized security and compliance certifications.
- Multi-Tenant:Logical isolation within shared physical infrastructure, optimizing cost for mid-market buyers.
Hybrid Cloud dominates enterprise RFPs. Private Cloud is climbing the fastest.
Integration Level:
Margin structures favor deep integration plays that embed email workflows within broader productivity and compliance automation stacks.
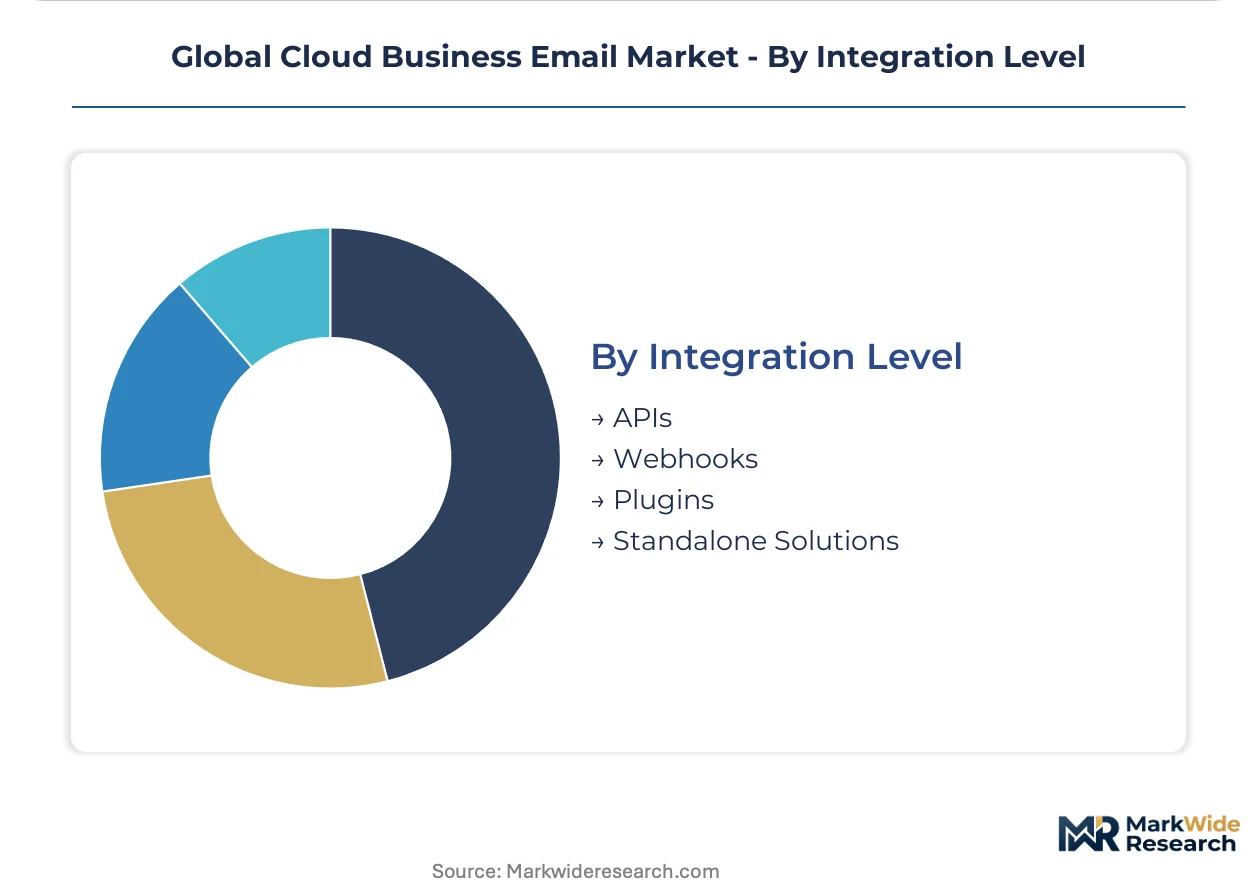
- APIs:Programmatic interfaces enabling custom workflow automation, CRM synchronization, and third-party security tool integration. U.S. financial services and legal technology vendors are concentrating development here, replacing manual e-discovery processes with automated classification pipelines.
- Plugins:Pre-built extensions for productivity suites, CRM systems, and compliance dashboards. Japanese enterprises are adopting these fastest under pressure to reduce vendor management overhead and consolidate procurement.
- Webhooks:Event-driven callbacks triggering real-time notifications and automated responses.
- Standalone Solutions:Disconnected email platforms requiring manual data export and limited ecosystem connectivity.
APIs command premium pricing today. Plugins are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure engineers and data residency specialists cluster in Germany, Japan, and the United States, anchoring regional demand concentration for sovereign email platforms. These talent pools concentrate where financial services compliance and AI governance frameworks intersect with enterprise procurement authority.
United States
SEC audit trail mandates and HIPAA encryption requirements drive financial services and healthcare migration from on-premises Exchange. The Federal Risk and Authorization Management Program (FedRAMP) certifies providers for government contracts. New York and Chicago banking clusters prioritize native e-discovery tooling over standalone security appliances.
Germany
Bundesdatenschutzgesetz strictures and EU AI Act high-risk classification rules compel enterprises toward certified national data centers. The Federal Office for Information Security (BSI) issues cloud service certification criteria that filter procurement shortlists. Frankfurt's financial district concentrates demand for hybrid architectures retaining sensitive archives on-premises.
Japan
METI cybersecurity guidelines and FISC standards accelerate bank migration to certified cloud email platforms. The Ministry of Economy, Trade and Industry maintains a registered provider list that shortens enterprise sales cycles. Tokyo's insurance sector concentrates procurement of bundled security-messaging solutions displacing legacy appliances.
United Kingdom
FCA operational resilience rules and UK GDPR continuity obligations reshape post-Brexit data routing decisions. The National Cyber Security Centre (NCSC) publishes cloud security principles that inform financial services procurement. London's legal technology cluster drives API-first integration demand for automated classification pipelines.
France
CNIL guidance on automated decision-making and EU AI Act conformity assessments elevate certified AI governance modules in enterprise RFPs. ANSSI cloud security certification filters public sector procurement. Parisian banking headquarters concentrate demand for private cloud deployments with full encryption key control.
Global Cloud Business Email Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service categories. Hyperscale technology groups leverage productivity suite integration and infrastructure footprint to anchor enterprise contracts. Security-centric specialists differentiate through encryption-native architectures and jurisdiction-specific compliance certification. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through certified regional data center deployment.
Within the hyperscale tier, Microsoft, Google, and Amazon Web Services occupy positions defined by ecosystem breadth and infrastructure reach. Microsoft exemplifies the productivity-integrated archetype through deep enterprise compliance tooling embedding. Google represents the AI-native differentiation vector with automated classification capabilities. Amazon Web Services anchors the infrastructure-leverage archetype, bundling email hosting within broader cloud compute contracts. Proton AG and Zoho Corporation sit within the specialist tier, representing privacy-first and emerging-market accessibility positions respectively.
| Leading Market Players |
|---|
| Zoho Corporation |
| Alibaba Cloud |
| Microsoft |
| Rackspace Technology |
| Tencent |
| IBM |
| Proton AG |
| Amazon Web Services |
| Others |
Supply Flow & Price Mechanics
Vertical integration into hyperscale data center infrastructure anchors pricing power for cloud email providers operating certified regional facilities. Microsoft, Google, and Amazon Web Services leverage captive compute and storage capacity to bundle email hosting within broader cloud contracts, compressing standalone pricing for pure-play competitors. This integration choice privileges vendors with existing European and Asia-Pacific footprints over those sourcing infrastructure through third-party colocation.
Pricing Analysis
Bundled security-messaging suites command premium positioning against unbundled email-only tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 27001 and FedRAMP credentials lifting contract values. Cost compression in the economy tier intensifies as hyperscalers absorb email functionality into productivity suite subscriptions. SMEs exhibit highest price sensitivity, while German and Japanese financial institutions prioritize compliance certification over per-seat cost.
Supply Chain Analysis
Reverse-logistics flows for decommissioned on-premises Exchange servers create secondary refurbishment markets extending hardware lifecycles. Supply concentrates in the United States, Germany, and Japan, where hyperscaler data center buildouts draw from specialized cooling, power distribution, and fiber interconnect components. Single-source vulnerability in AI training chip supply chains threatens providers scaling automated classification features. Distribution runs through direct enterprise sales teams and systems integrator partnerships, with regional value-added resellers penetrating mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud business email operates as a geographic-arbitrage play where EU AI Act compliance costs in Europe run substantially higher than equivalent certification burdens in the United States, creating margin expansion opportunities for providers with pre-certified infrastructure.
For Market Incumbents: Cement dominance through exclusive certification pipelines with BSI, ANSSI, and METI regulators, accelerating sales cycles in sovereign cloud segments. Acquire AI governance specialists to embed automated classification natively before high-risk application rules harden procurement criteria. Defensive consolidation of regional data center footprints neutralizes emerging entrants lacking multi-jurisdictional coverage.
For New Entrants and Emerging Players: The EU AI Act in Germany and France opens a window for privacy-native architectures targeting Bundesdatenschutzgesetz-compliant deployments. White-space concentrates in hybrid cloud integration services for U.S. financial services firms retaining sensitive archives on-premises. Go-to-market through legal technology channel partners displacing legacy e-discovery appliances with API-first classification pipelines.
For Investors and Strategic Acquirers: Roll-up economics work for compliance-automation specialists because ISO 27001 certification scarcity creates pricing power in cross-border email flows. Five-to-ten year viability hinges on AI governance module differentiation as high-risk classification rules mature. Monitor FedRAMP authorization timelines and BSI cloud certification backlogs as inflection indicators for provider market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Data Center Certification | BSI and ANSSI credentials unlock German and French sovereign cloud procurement shortlists. |
| AI Governance Module Development | EU AI Act high-risk classification rules mandate human oversight mechanisms in automated email flows. |
| Hybrid Cloud Integration Partnership | U.S. financial services firms balance scalability with legacy archive retention requirements. |
| Security-Messaging Bundle Expansion | Japanese METI guidelines accelerate displacement of standalone security appliances. |
| API-First Platform Architecture | Legal technology vendors in London and New York automate e-discovery through programmatic interfaces. |
Methodological Framework
Coverage spans Germany, Japan, the United States, the United Kingdom, and France, with primary inputs from each market cluster. Interviews with cloud infrastructure architects, enterprise IT procurement officers, compliance automation specialists, and systems integrator partners combined with secondary validation from SEC filings, hyperscaler capex disclosures, BSI certification registers, and METI provider lists. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Rate-of-change decomposition separated organic growth from migration-driven replacement demand across the projection horizon. Segmentation dimensions modeled include deployment architecture, customer scale tier, integration complexity level, and regional regulatory cluster. CAGRs derived from fitted adoption curves incorporating compliance mandate enforcement timelines and enterprise contract renewal cycles. Forecast inputs incorporated FedRAMP authorization velocity, EU AI Act implementation phasing, and hybrid cloud penetration rates in regulated U.S. sectors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated GDPR enforcement or AI Act high-risk reclassification events. Projections reflect assumptions regarding certification timeline stability, hyperscaler pricing discipline, and sovereign cloud demand elasticity. Practitioners should monitor BSI cloud certification backlogs, METI registered provider list expansions, and SEC audit trail mandate clarifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Based Information Governance Market
Cloud Computing
Cloud VPN Market
Cloud Computing
Multi-Cloud Optimization Tools Market
Cloud Computing
Cloud Enablement Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Cloud Services Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Platform As a Service (Paas) Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
Cloud API and Management Platforms and Middleware Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market