
 Cloud Data Warehouse Market | 2026-2036
Cloud Data Warehouse Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Data Warehouse Market Analytics
Multi-source cloud procurement is decoupling enterprise data infrastructure from single-vendor lock-in. Amazon Web Services leverages its managed analytics stack to anchor workloads across regulated sectors. Snowflake Inc. competes through separation of compute and storage architecture. Google Cloud Platform differentiates via BigQuery's serverless query engine and AI-integrated pipelines.
A cloud data warehouse is a fully managed, elastic data repository that separates storage from compute resources, enabling petabyte-scale analytics through massively parallel processing and columnar storage formats. Its primary commercial purpose is to consolidate structured and semi-structured data from disparate sources for real-time business intelligence and machine learning operations. Public cloud deployments dominate volume due to operational simplicity, while hybrid configurations capture margin pools from enterprises with data sovereignty constraints. Data analytics services represent the fastest-expanding service type as organizations embed predictive models into operational workflows.
EU GDPR, the EU AI Act, and ISO 27001 standards shape product architecture by mandating encryption, audit trails, and geographic data boundaries. EMA guidelines for pharmacovigilance data integrity and REACH-aligned chemical reporting obligations further tighten compliance requirements for European deployments. Stakeholders must evaluate residency certifications and cross-border transfer mechanisms before committing to platform contracts.
Market Dynamics
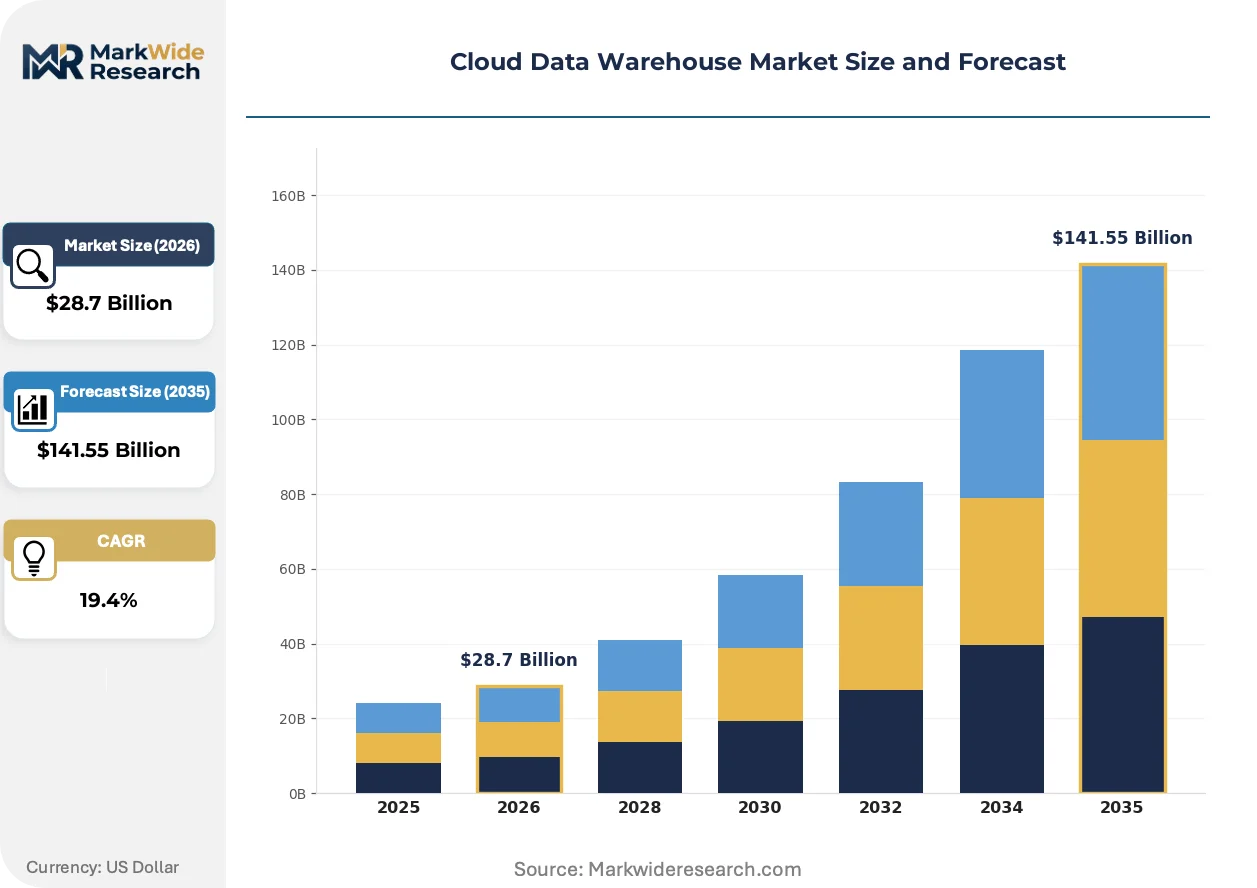
Enterprise migration from on-premise data centers to cloud-native architectures is compressing traditional infrastructure procurement cycles and forcing incumbents to reprice storage-compute bundles. This structural shift is accelerating vendor consolidation around platforms offering sovereign data controls.
Growth Catalysts
- EU AI Act compliance mandates:Financial services firms in Germany and France must deploy auditable data pipelines, driving demand for platforms with built-in lineage tracking and residency controls.
- Pharmaceutical analytics expansion:EMA pharmacovigilance requirements for real-time adverse event monitoring are pushing drug manufacturers toward elastic query engines that scale with regulatory reporting volumes.
- Separation of storage and compute:Columnar formats and massively parallel processing architectures are reducing total cost of ownership for petabyte-scale workloads across European enterprises.
Market Restraints
- Cross-border data transfer friction:GDPR adequacy decisions and Schrems II rulings create legal uncertainty for US-headquartered cloud providers serving EU enterprises.
- Specialized talent scarcity:Shortages of platform engineers fluent in both SQL analytics and Kubernetes orchestration inflate implementation timelines for complex migrations.
- Legacy system entrenchment:Decades of on-premise data warehouse investment in British and German manufacturing sectors slow full-stack replacement decisions.
Strategic Opportunities
- Sovereign cloud deployments:France and Germany are mandating data localization for public sector and defense contractors, creating protected margin pools outside hyperscaler dominance.
- AI-integrated pipelines:Convergence of vector databases with traditional warehouses enables unified platforms for structured analytics and large language model training.
- Chemical industry reporting:REACH-aligned obligations for supply chain transparency are opening specialized vertical solutions for industrial data consolidation.
Industry Challenges
- Multi-cloud skill fragmentation:Enterprises struggle to hire architects proficient across AWS, Azure, and GCP native services simultaneously.
- ISO 27001 certification timelines:Protracted audit cycles for cloud providers delay market entry for new entrants targeting regulated European buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Data Warehouse Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $141.55 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Enterprise, SMB, Government, Educational Institutions Service Type: Data Integration, Data Analytics, Data Migration, Data Security Technology: SQL, NoSQL, NewSQL, Data Lakes |
| Companies Covered | Amazon Web Services, Snowflake Inc., Google Cloud Platform, Microsoft Corporation, Databricks, Oracle Corporation, ClickHouse, Teradata, Yellowbrick Data, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Data Warehouse Market Evolving Landscape
Real-time analytics and machine learning operations are merging into unified data platforms, eliminating the latency between business intelligence and predictive modeling. This convergence is reshaping how enterprises architect their information infrastructure.
Serverless query engines are electrifying how organizations process variable analytical workloads. These engines automatically scale compute resources without manual cluster provisioning. Retail and logistics buyers in the United Kingdom are adopting them fastest for seasonal demand spikes. The technology is electrifying traditional pricing models by replacing reserved capacity contracts with consumption-based billing that aligns costs directly to query execution.
The EU AI Act's risk-based classification system is forcing platform vendors to embed algorithmic audit capabilities directly into data pipelines. High-risk AI applications in credit scoring and medical diagnostics now require explainability trails from training data to model output. German automotive and French insurance sectors are responding by demanding integrated governance tools that map data lineage across distributed storage layers.
Buyers are consolidating vendor relationships around full-stack analytics platforms rather than assembling best-of-breed components. This pattern compresses procurement cycles from multi-year evaluations to pilot-to-production timelines measured in quarters. The shift is most visible among mid-market enterprises in the Netherlands and Belgium, where lean IT teams prioritize operational simplicity over architectural flexibility.
Cloud Data Warehouse Market Segmentation
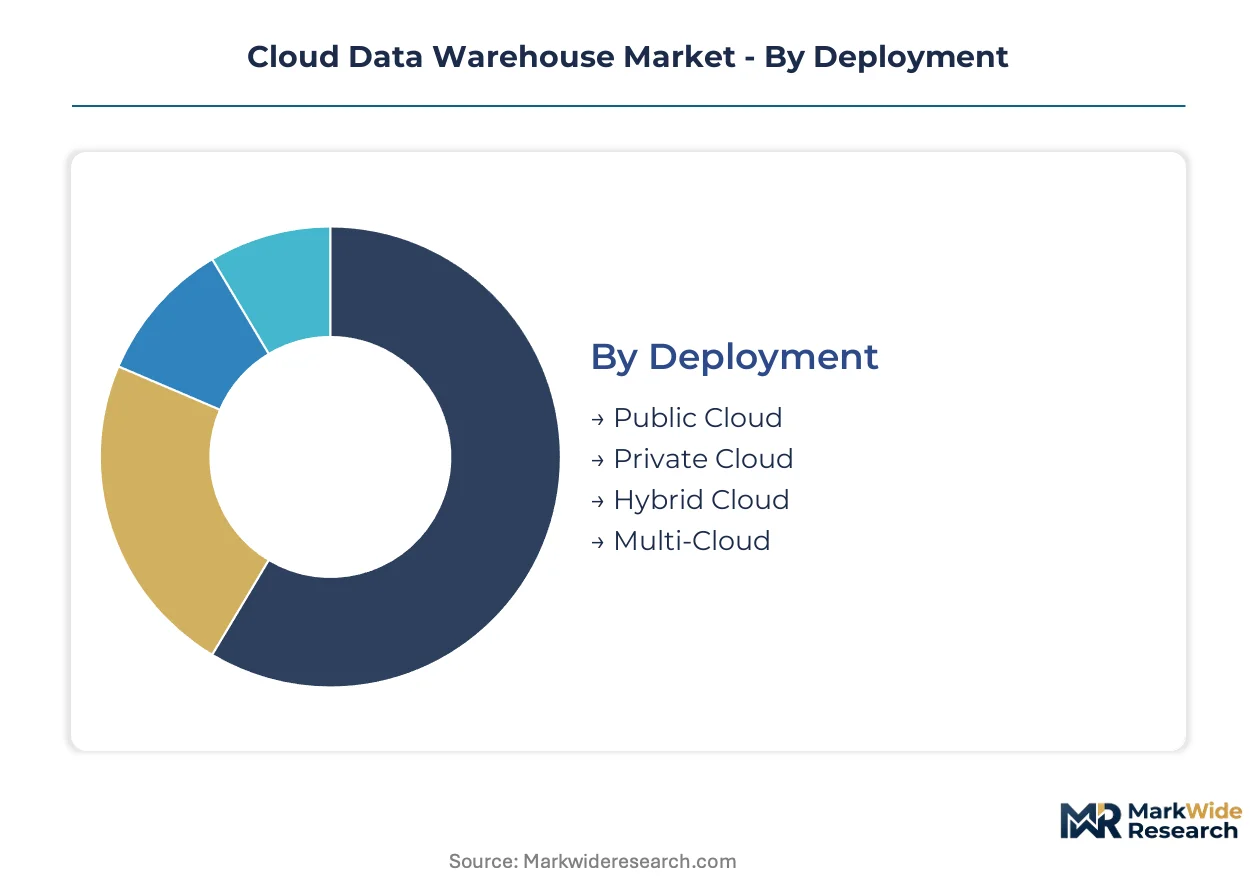
Cloud data warehouse segmentation reveals how architectural choices, customer scale, and workload complexity drive divergent procurement patterns. Vendors configure pricing, compliance tooling, and performance guarantees around these axes to capture specific margin pools.
Deployment:
Architecture selection determines sovereignty posture, operational overhead, and elasticity boundaries for analytical workloads.
- Public Cloud:Fully managed infrastructure delivers on-demand scaling without capital expenditure. Financial services firms in Germany and France favor this model for EBA stress-testing pipelines requiring burst compute capacity.
- Private Cloud:Dedicated single-tenant environments enforce strict data residency. Defense contractors and public sector buyers in France mandate this architecture under ANSSI cloud security guidelines.
- Hybrid Cloud:Split orchestration between on-premise and cloud resources. Manufacturing enterprises in Germany deploy this for shop-floor analytics with sensitive IP remaining on-site.
- Multi-Cloud:Workload portability across AWS, Azure, and GCP prevents vendor lock-in. Dutch and Belgian mid-market enterprises adopt this to arbitrage regional pricing differentials.
Public Cloud leads on scale; Multi-Cloud leads on momentum.
End User:
Customer scale segments procurement complexity, compliance depth, and implementation timeline.
- Enterprise:Global 2000 organizations with petabyte-scale estates and dedicated platform engineering teams. German automotive OEMs represent concentrated demand for real-time supply chain analytics.
- SMB:Mid-sized organizations purchasing through managed service providers rather than direct vendor relationships. United Kingdom retail chains favor pre-configured industry templates.
- Government:Public sector bodies with mandatory certification requirements. French ministries specify SecNumCloud-qualified platforms for administrative data processing.
- Educational Institutions:Universities and research consortia with grant-funded analytics needs. CERN and Max Planck Institute deployments emphasize open-source interoperability.
Enterprise dominates current revenue; Government contracts are climbing the fastest.
Service Type:
Functional layer selection reflects where organizations sit on the data maturity curve.
- Data Integration:ETL/ELT pipeline construction and schema management. Pharmaceutical manufacturers in Switzerland deploy these services for EMA pharmacovigilance data harmonization.
- Data Analytics:Query engines, visualization layers, and predictive modeling tools. This layer is expanding most quickly as insurers embed risk scoring into operational workflows.
- Data Migration:Legacy warehouse extraction and cloud loading services. British banks consume this heavily for mainframe offloading programs.
- Data Security:Encryption, access control, and audit logging implementations. GDPR Article 32 compliance mandates drive consistent demand across all geographies.
Data Analytics captures the steepest expansion trajectory; Data Integration maintains the deepest incumbent relationships.
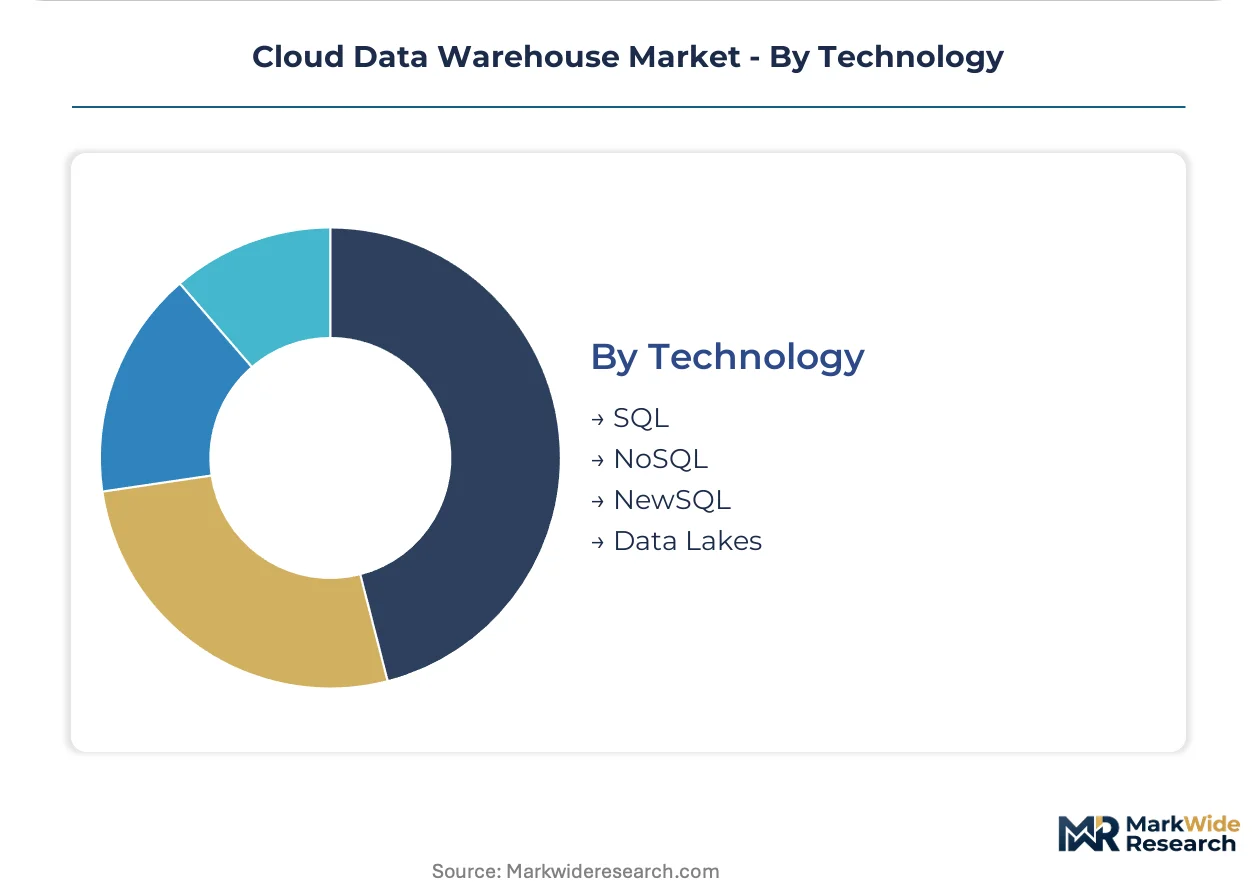
Technology:
Query paradigm and storage architecture determine performance characteristics for specific workload types.
- SQL:Relational engines optimized for structured business intelligence. Columnar implementations dominate financial reporting use cases in Frankfurt and London trading floors.
- NoSQL:Document and key-value stores for semi-structured ingestion. IoT telemetry pipelines in industrial IoT deployments favor this flexibility.
- NewSQL:Distributed relational systems combining ACID guarantees with horizontal scaling. Fintech startups in Berlin and Paris select this for transaction-analytics convergence.
- Data Lakes:Object storage with schema-on-read for raw data exploration. Media and entertainment firms in the United Kingdom deploy this for content metadata management.
SQL retains the largest installed base; NewSQL is gaining share fastest among cloud-native entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German financial services clusters in Frankfurt and Munich are compressing procurement cycles for cloud-native analytics platforms as EBA stress-testing mandates intensify workload volatility.
Germany
Automotive OEMs in Stuttgart and Wolfsburg demand real-time supply chain analytics with strict data residency controls. The EU AI Act's risk-based classification system forces credit-scoring institutions to deploy auditable pipelines with embedded lineage tracking. Bavarian manufacturing consortia hybridize deployments, keeping sensitive IP on-premise while bursting analytics workloads to sovereign cloud instances.
United Kingdom
London-based investment banks consume elastic query engines for regulatory reporting surges during quarterly disclosure windows. The Financial Conduct Authority's operational resilience requirements accelerate migration from legacy mainframe warehouses. Retail and logistics buyers in Manchester and Birmingham adopt serverless architectures fastest for seasonal demand spikes.
France
Parisian insurers embed predictive risk models into operational workflows, driving convergence of structured analytics and machine learning operations. ANSSI cloud security guidelines mandate SecNumCloud-qualified platforms for defense contractors and public sector bodies. The Île-de-France region concentrates demand for private cloud deployments among administrative data processors.
United States
Silicon Valley technology firms and New York financial services drive petabyte-scale adoption of separation-of-storage-compute architectures. HIPAA and SEC record-keeping requirements shape encryption and audit trail specifications for healthcare and capital markets deployments. The Boston-Cambridge biotech corridor demands elastic query engines for FDA-aligned pharmacovigilance data harmonization.
India
Bangalore and Hyderabad fintech startups select distributed relational systems combining ACID guarantees with horizontal scaling for transaction-analytics convergence. RBI data localization directives force foreign cloud providers to establish domestic infrastructure zones. Mumbai-based conglomerates pilot multi-cloud configurations to arbitrage regional pricing differentials across hyperscaler platforms.
Cloud Data Warehouse Market Competitive Landscape
Global majors compete with regional champions across sovereign data controls and compliance depth, creating a tiered structure where hyperscalers anchor volume while specialists capture protected margin pools. The vendor landscape segments into three strategic archetypes: full-stack platform providers with managed analytics stacks, architecture specialists emphasizing compute-storage separation, and vertical solutions targeting regulated industry workflows. Competitive dynamics center on M&A activity consolidating point-solution vendors and strategic partnerships embedding governance tools directly into data pipelines.
Within the hyperscaler tier, Amazon Web Services, Google Cloud Platform, and Microsoft Corporation exemplify platform providers leveraging infrastructure scale to anchor regulated sector workloads. Snowflake Inc. and Databricks occupy positions emphasizing architectural differentiation through elastic resource separation and unified analytics-machine learning convergence. Oracle Corporation and Teradata represent incumbent database vendors repositioning on-premise relationships toward cloud-native subscription models.
| Leading Market Players |
|---|
| Amazon Web Services |
| Snowflake Inc. |
| Google Cloud Platform |
| Microsoft Corporation |
| Databricks |
| Oracle Corporation |
| ClickHouse |
| Teradata |
| Yellowbrick Data |
| Others |
Value Network & Pricing Analysis
Compute instance costs cascade through cloud data warehouse pricing tiers, with hyperscaler infrastructure rates in Frankfurt and Dublin data centers feeding into consumption-based billing models that German financial services firms negotiate against reserved capacity discounts. Storage-compute separation architectures compress margin structures for traditional bundled offerings while creating premium pricing pools for sovereign cloud deployments with ANSSI or BSI certification.
Pricing Analysis
Input-cost pass-through from hyperscaler infrastructure rates shapes consumption-based billing as the dominant pricing model, with query execution metering replacing fixed-capacity contracts. Price differentiation hinges on data residency certification tier and burst compute elasticity, with SecNumCloud-qualified platforms commanding substantial premiums over standard public cloud tiers. Pricing pressure intensifies in the mid-market segment as Snowflake and Databricks compress margins through automated resource scaling. Enterprise buyers in Frankfurt and Paris exhibit lowest price sensitivity due to regulatory compliance mandates, while Dutch and Belgian mid-market adopters arbitrage regional pricing differentials most aggressively.
Supply Chain Analysis
Platform engineering talent scarcity in Bangalore, Berlin, and Warsaw constrains delivery capacity for complex migration implementations, forcing vendors to redistribute professional services resources toward certification-heavy European deployments. Supply concentration centers on United States hyperscaler infrastructure, Irish and German sovereign cloud facilities, and Indian system integration capabilities. Raw material dependencies include silicon for compute instances, rare earth elements for storage hardware, and proprietary columnar database software licenses. Single-source vulnerability runs through AWS, Azure, and GCP control plane architectures. Distribution flows through direct enterprise sales teams, managed service provider channels, and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
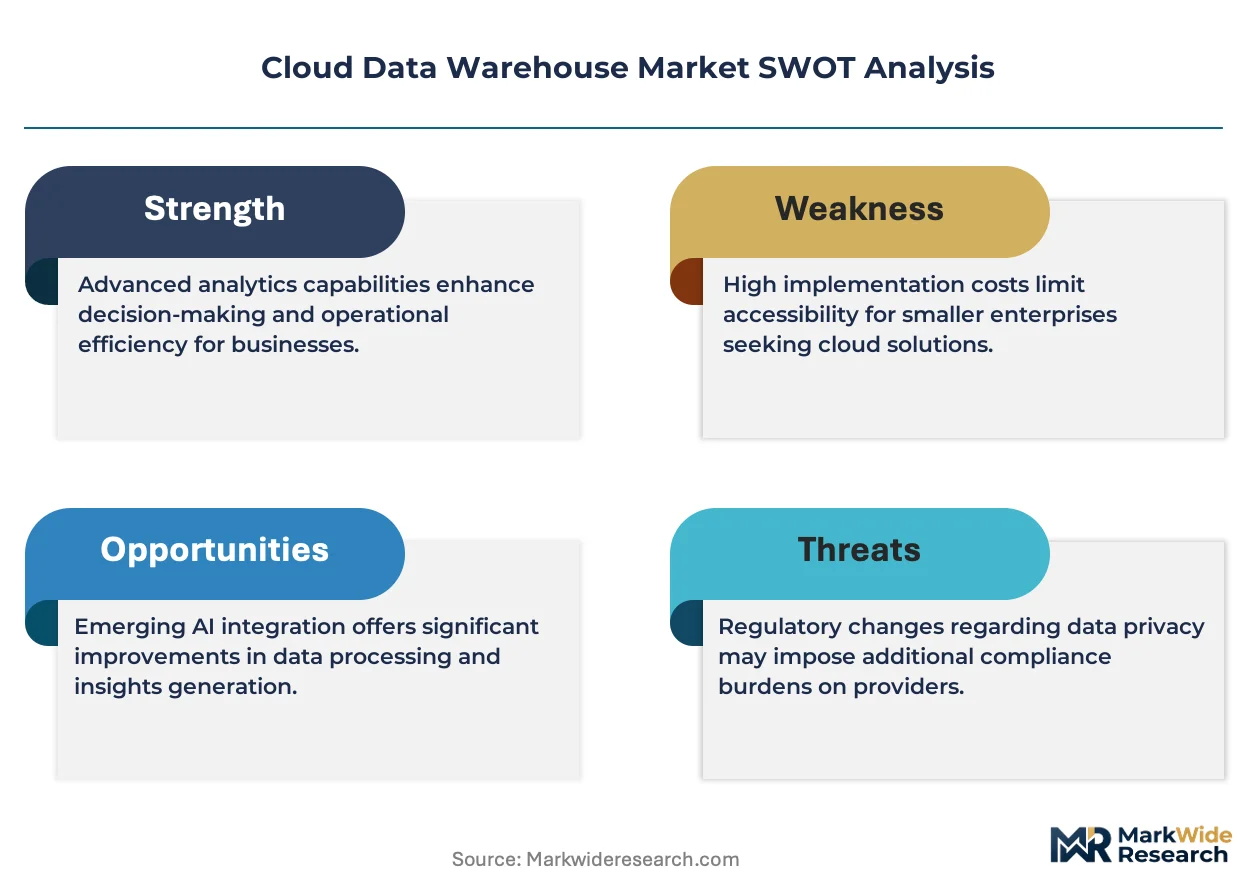
Margin expansion opportunities concentrate in sovereign cloud tiers where EU AI Act compliance mandates create pricing power, while storage-compute separation architectures reduce infrastructure cost bases for cloud-native entrants.
For Market Incumbents: Acquire Kubernetes orchestration specialist teams to close talent gaps slowing European implementation timelines. AWS and Azure must embed automated lineage tracking tools directly into managed analytics stacks before GDPR Article 32 enforcement intensifies. Oracle and Teradata should reposition legacy on-premise relationships through sovereign cloud subscription models to defend against Snowflake's architectural displacement. For New Entrants and Emerging Players: EU AI Act in Germany and France opens a window for niche compliance automation vendors to capture pharmacovigilance and credit-scoring pipeline segments. Target French defense contractors and public sector bodies with SecNumCloud-qualified private cloud offerings where hyperscaler presence remains restricted. Pursue managed service provider channel partnerships rather than direct enterprise sales to accelerate pilot-to-production timelines among Belgian and Dutch mid-market buyers. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 27001 certification timelines exceed twelve months and specialized talent scarcity inflates implementation costs. Long-term viability favors platforms with embedded AI governance tooling and cross-cloud workload portability. Monitor EBA stress-testing mandate expansion as inflection signal for burst compute demand spikes in Frankfurt financial services clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified analytics-ML convergence captures insurers embedding risk scoring into operational workflows. |
| Acquisition of Specialist Firm | Kubernetes orchestration talent acquisition compresses migration timelines for German automotive OEMs. |
| Geographic Expansion | Sovereign cloud infrastructure in France satisfies ANSSI guidelines for defense contractor data processing. |
| Strategic Partnership | Systems integrator alliances accelerate mid-market penetration across Netherlands and Belgium. |
| Product Launch | Serverless query engines with consumption billing align retail and logistics seasonal demand patterns. |
Research Methodology
Bottom-up enterprise workload modeling reconciled against top-down hyperscaler infrastructure tracking forms the analytical core of this study. Primary interviews with CTOs, platform engineers, IT procurement officers, and channel partners across Frankfurt, London, Paris, and Amsterdam informed demand-side assumptions. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EBA stress-testing documentation, and ANSSI cloud security certification registers. Cross-referencing bottom-up segment builds with top-down vendor revenue triangulation ensures consistency across deployment model, organization size, vertical, and regional adoption pattern dimensions.
Input-output matrices map query volume growth rates against infrastructure capacity expansion across public, private, hybrid, and multi-cloud architectures throughout the projection horizon. Segmentation modeling incorporates deployment sovereignty tier, end-user scale band, service type maturity curve position, and query paradigm technology selection. CAGRs derive from elasticity coefficient analysis and regulatory mandate acceleration effects. Forecast inputs include EU AI Act implementation timelines, EMA pharmacovigilance data volume projections, and manufacturing IoT telemetry pipeline growth assumptions.
Revisions become necessary when GDPR adequacy decisions shift, Schrems II rulings alter cross-border transfer legality, or sovereign cloud certification requirements expand beyond current ANSSI and BSI frameworks. Forecasts reflect documented assumptions regarding hyperscaler pricing stability and platform engineering labor market conditions. Material deviation in regulatory enforcement intensity or talent availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
France Cloud Computing Market
Cloud Computing
Healthcare Cloud Infrastructure Market
Cloud Computing
Global Cloud Collaboration Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Public Cloud in BFSI Market
Cloud Computing
Cloud Management Market
Cloud Computing
Cloud Computing in Industrial IoT Market
Cloud Computing
Brazil Cloud Computing Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
India Cloud Computing Market
Cloud Computing
Cloud Computing Market
Cloud Computing
Telecom Cloud Market
Cloud Computing
Public Cloud Application Services Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Cloud-Based Repository Services Market