
 Automotive Internet of Things (IoT) Market | 2026-2036
Automotive Internet of Things (IoT) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Internet of Things (IoT) Market Outlook
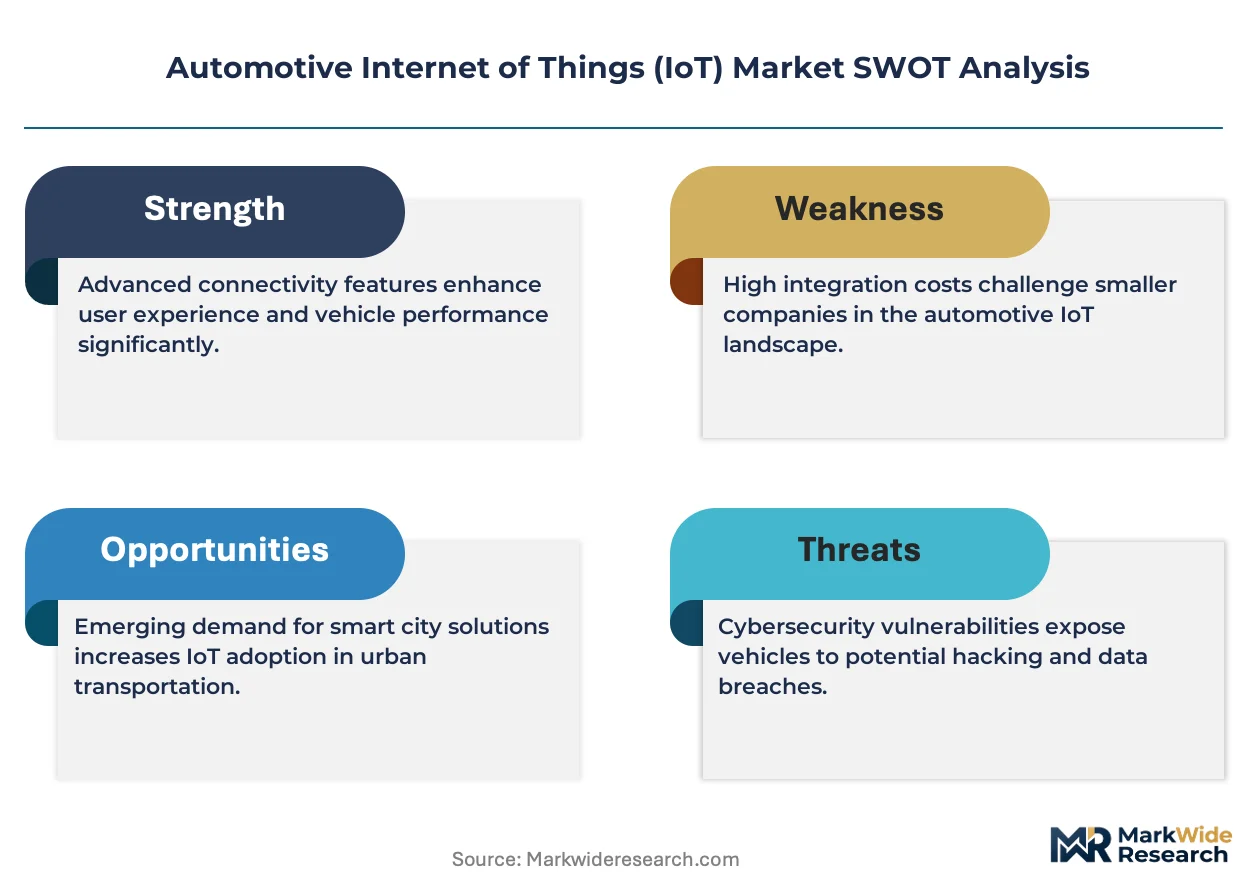
The gap between edge computing architectures and cloud-dependent platforms is narrowing as automakers pursue split workloads for latency-sensitive functions. Robert Bosch GmbH anchors European manufacturing scale in sensor fusion and control modules for connected powertrains. NXP Semiconductors N.V. leads secure element design for vehicle-to-everything authentication protocols. QUALCOMM Incorporated dominates cellular V2X chipset supply for North American and Asian OEM programs.
Automotive Internet of Things denotes embedded sensor networks, communication modules, and software stacks that exchange data between vehicles, infrastructure, and cloud services via cellular, short-range, or satellite links, operating across frequency bands from sub-GHz to mmWave with latency requirements as low as 10 milliseconds for safety-critical functions. Its primary purpose is enabling real-time situational awareness, predictive intervention, and remote operational control across mobility ecosystems. Telematics and V2X Communication represent the most mature revenue pools, though edge-based deployment architectures are capturing disproportionate investment as OEMs seek to reduce backhaul costs and meet functional safety thresholds. Fleet Management applications currently absorb the largest share of enterprise spending, while Insurance Telematics is emerging as a margin-rich segment where granular driving behavior data transforms risk pricing models.
The U.S. Department of Transportation's V2X deployment guidance, the EU's Cyber Resilience Act, and China's MIIT-connected vehicle standards collectively shape certification requirements, cross-border data governance, and supplier market access conditions. NHTSA rulemaking on automated driving system data recording intersects with FCC spectrum allocation decisions to determine which communication protocols achieve commercial scale. Stakeholders must monitor regulatory fragmentation between cellular V2X and DSRC technology mandates, as divergent national standards threaten interoperability and force parallel product development tracks.
Market Dynamics
The convergence of edge computing architectures with functional safety requirements is compressing development cycles for latency-critical automotive IoT systems. OEMs now split workloads between vehicle-side processing and cloud analytics to satisfy sub-10 millisecond response thresholds for collision avoidance and cooperative maneuvering.
Growth Catalysts
- Fleet Management Digitization:Commercial vehicle operators in the United States are deploying connected telematics at scale to optimize route efficiency and predictive maintenance scheduling. The U.S. Department of Transportation's V2X deployment guidance accelerates infrastructure investment along freight corridors.
- Cyber Resilience Mandates:The European Union's Cyber Resilience Act establishes baseline security standards for IoT-enabled automotive components. Tier-one suppliers must now certify control modules and communication gateways against mandatory vulnerability disclosure timelines.
- Cellular V2X Proliferation:5G-based vehicle-to-everything protocols are replacing dedicated short-range communications in new vehicle programs. Chipset availability from Qualcomm and MediaTek enables multi-band operation across sub-6 GHz and mmWave spectrum.
Market Restraints
- Semiconductor Supply Concentration:Secure element fabrication for automotive authentication relies on a concentrated foundry base in Taiwan and South Korea. Geopolitical friction threatens capacity allocation for vehicle-to-everything chipset production.
- Spectrum Allocation Uncertainty:The Federal Communications Commission's 2020 reallocation of the 5.9 GHz band removed 60% of dedicated safety spectrum for DSRC operations. Automakers face stranded investment in roadside unit deployments.
- Integration Cost Escalation:Multi-protocol communication stacks require redundant hardware for cellular, Wi-Fi, Bluetooth, and ultra-wideband coexistence. Bill-of-materials inflation pressures entry-segment vehicle profitability.
Strategic Opportunities
- Insurance Telematics Expansion:Usage-based risk pricing models are penetrating commercial auto lines in Germany and the United Kingdom. Granular driving behavior data enables dynamic premium adjustment for fleet operators.
- Edge AI Convergence:Sensor fusion algorithms and neural network inference are migrating from cloud data centers to vehicle-mounted compute modules. NXP Semiconductors and Renesas Electronics are qualifying automotive-grade system-on-chip architectures.
- India's PLI Scheme:The Production Linked Incentive scheme for automotive components subsidizes domestic manufacturing of telematics control units. Local assembly reduces import duty exposure for connected vehicle platforms.
Industry Challenges
- Functional Safety Talent Scarcity:ISO 26262 certification expertise remains concentrated among semiconductor vendors and tier-one electronics suppliers. OEMs compete for systems engineers capable of ASIL-D validation.
- Cross-Border Data Governance:China's MIIT-connected vehicle standards impose localization requirements for telematics data storage. Foreign automakers must architect parallel cloud infrastructure for domestic versus export market vehicles.
- Legacy Fleet Retrofit Complexity:Aftermarket telematics installation in heavy-duty trucks with proprietary J1939 bus architectures requires protocol translation gateways. Integration timelines extend 18-24 months for mixed-age fleet deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Internet of Things (IoT) Market |
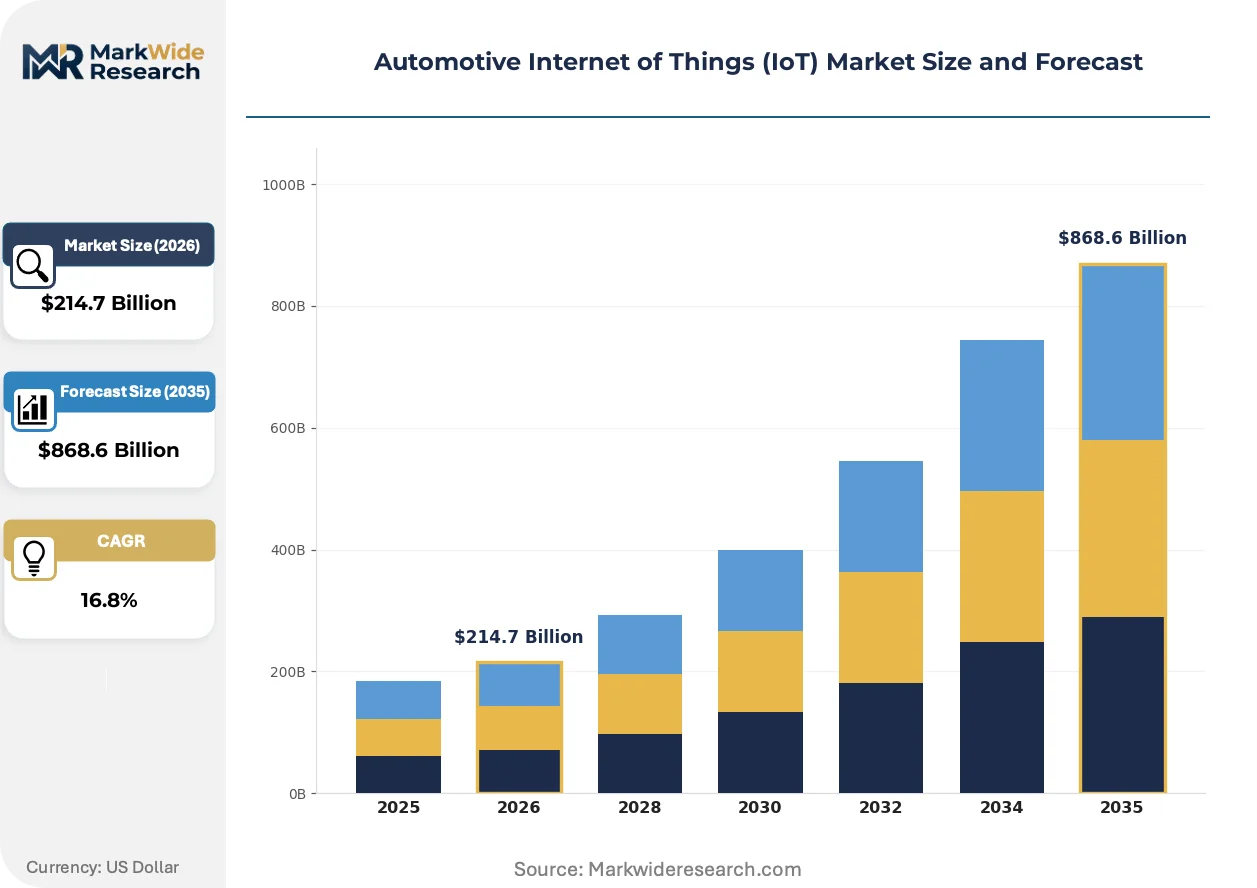
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $868.6 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Telematics, V2X Communication, On-board Diagnostics, Remote Monitoring Application: Fleet Management, Predictive Maintenance, Driver Assistance, Insurance Telematics End User: OEMs, Aftermarket Providers, Fleet Operators, Insurance Companies Deployment: Cloud-based, Edge Computing, Hybrid Solutions, On-Premise |
| Companies Covered | NXP Semiconductors N.V., Robert Bosch GmbH, Intel Corporation, Harman International Industries, Inc., Texas Instruments, Inc., Infineon Technologies AG, TomTom N.V., Thales S.A., QUALCOMM Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Internet of Things (IoT) Market Strategic Shifts
Software-defined vehicle architectures are decoupling hardware refresh cycles from feature deployment. Over-the-air update capabilities now enable continuous enhancement of connected services without physical service bay visits.
Centralized zonal electronic architectures are rendering obsolete distributed domain controller layouts that isolated powertrain, chassis, and infotainment functions. Mercedes-Benz and BMW are migrating to vehicle fusion computers that aggregate sensor inputs across 40+ electronic control units. This consolidation reduces wiring harness mass by 30% while enabling subscription-based feature activation.
The EU's Cyber Resilience Act imposes mandatory security update obligations across the product lifecycle. Automotive suppliers must maintain vulnerability response capabilities for 15 years post-manufacture. German OEMs are restructuring supplier contracts to allocate cybersecurity liability toward component vendors rather than vehicle manufacturers.
Fleet procurement departments are consolidating telematics vendor relationships to capture volume pricing and unified data analytics. Enterprise buyers now demand API interoperability between telematics platforms and transportation management systems. This specification pressure is most visible in North American trucking, where Schneider National and J.B. Hunt negotiate multi-year connected service agreements with embedded hardware refresh guarantees.
Automotive Internet of Things (IoT) Market Segmentation
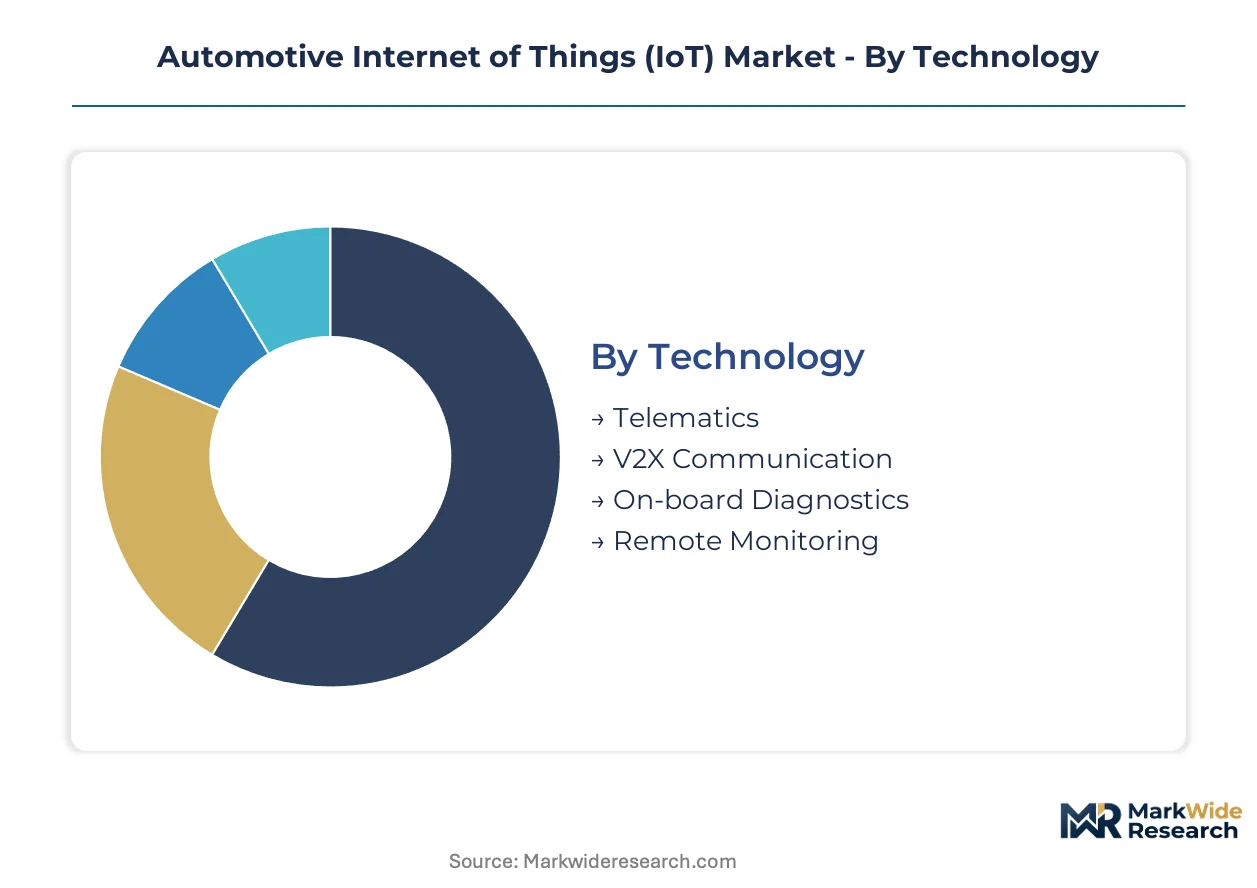
Automotive IoT segmentation reveals divergent refresh cycles across technology layers. Hardware-dependent categories face 5-7 year replacement timelines, while software-centric segments iterate continuously through over-the-air updates.
Technology:
Cycle times compress from multi-year hardware deployments to continuous software enhancement, creating portfolio management complexity for suppliers.
- Telematics:Embedded cellular modules combine GNSS receivers with CAN bus interfaces to transmit vehicle health and location data. Fleet operators in the United States absorb the largest share of enterprise deployments, driven by DOT V2X corridor investments and hours-of-service compliance mandates.
- V2X Communication:Dedicated short-range and cellular protocols enable direct vehicle-to-vehicle and vehicle-to-infrastructure messaging. German OEMs anchor European development, though FCC spectrum reallocation has stranded roadside unit investments in North American markets.
- On-board Diagnostics:Standardized J1962 port access and proprietary fleet protocols extract real-time powertrain fault codes. Aftermarket telematics providers leverage OBD-II dongles for rapid fleet retrofit without manufacturer integration.
- Remote Monitoring:Cloud-connected sensor networks track cargo condition, driver biometric indicators, and trailer refrigeration states. Cold chain logistics operators generate concentrated demand for temperature-critical shipment visibility.
Telematics dominates installed base. V2X Communication is where expansion concentrates.
Application:
Margin profiles separate operational efficiency tools from risk-transfer instruments, with insurance-linked segments commanding premium pricing.
- Fleet Management:Route optimization algorithms integrate traffic, fuel pricing, and driver availability data for commercial vehicle dispatch. North American trucking consolidators negotiate multi-year platform agreements with embedded hardware refresh cycles.
- Predictive Maintenance:Machine learning models applied to vibration, thermal, and oil degradation sensor streams forecast component failure before roadside breakdown. Heavy-duty truck operators achieve measurable downtime reduction through axle and brake monitoring.
- Driver Assistance:Connected services extend beyond single-vehicle sensors to incorporate crowd-sourced hazard warnings and cooperative perception. ADAS functionality increasingly depends on real-time map updates and traffic condition feeds.
- Insurance Telematics:Granular driving behavior scoring—hard braking frequency, cornering aggression, mileage patterns—enables usage-based premium adjustment. Commercial auto underwriters in Germany and the United Kingdom deploy dynamic pricing models for fleet accounts.
Fleet Management commands current spending share. Insurance Telematics offers the steepest expansion trajectory.
End User:
Procurement authority concentrates differently across new vehicle specification, aftermarket retrofit, and enterprise service contracting.
- OEMs:Vehicle manufacturers embed connectivity hardware during assembly and monetize through subscription service tiers. Zonal electronic architectures are consolidating previously distributed telematics control units into centralized compute clusters.
- Aftermarket Providers:Third-party installers serve legacy fleet vehicles and owner-operators outside factory warranty coverage. OBD-II plug-in devices and hardwired installations compete on installation speed and data plan flexibility.
- Fleet Operators:Enterprise buyers demand API interoperability between telematics platforms and transportation management systems. Schneider National and J.B. Hunt exemplify consolidated vendor relationships with unified analytics requirements.
- Insurance Companies:Underwriters procure driving behavior data to refine risk segmentation and claims investigation. Data ownership terms and privacy compliance now structure procurement negotiations more than per-vehicle hardware costs.
OEMs control new vehicle connectivity specification. Fleet Operators drive aftermarket volume.
Deployment:
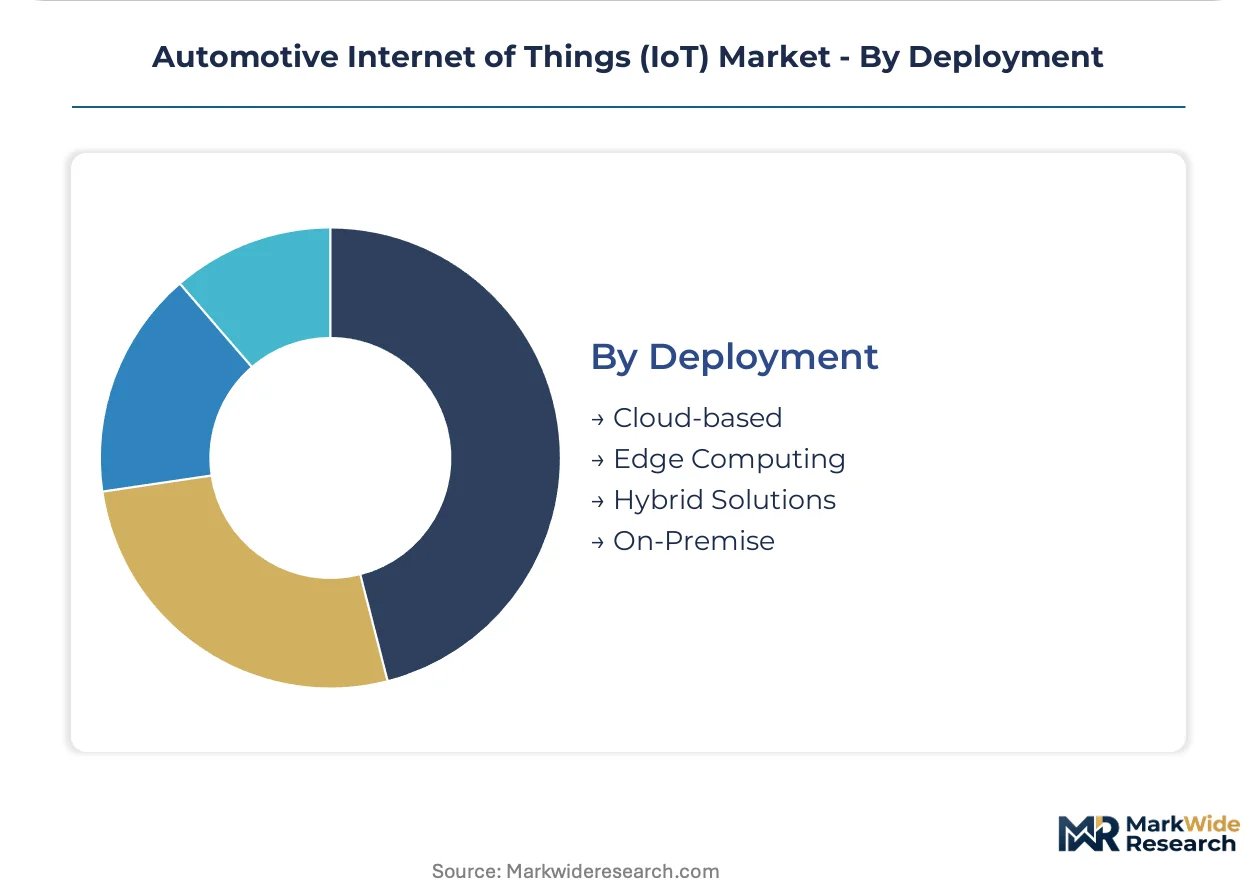
Latency requirements and data sovereignty rules are redistributing computational load between vehicle, edge, and cloud tiers.
- Cloud-based:Centralized data lakes aggregate historical fleet performance for long-term pattern analysis and regulatory reporting. Backhaul costs and connectivity dead zones limit suitability for real-time safety functions.
- Edge Computing:Vehicle-mounted processors execute sensor fusion and neural inference without network dependency. NXP Semiconductors and Renesas Electronics qualify automotive-grade system-on-chip architectures for sub-10 millisecond response thresholds.
- Hybrid Solutions:Split architectures process time-critical functions locally while transmitting aggregated telemetry to cloud analytics. This configuration balances functional safety compliance with fleet-wide operational intelligence.
- On-Premise:Dedicated server infrastructure within fleet depots maintains data residency for defense and government vehicle operators. Air-gapped deployments satisfy classified mission requirements but sacrifice real-time traffic integration.
Cloud-based deployment holds legacy share. Edge Computing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a substantial trade surplus in automotive IoT components, while the United States and China compete for import dominance in telematics modules and V2X chipsets. Export flows from South Korea and Taiwan concentrate in secure element fabrication and cellular baseband processors.
United States
Fleet operators including Schneider National and J.B. Hunt drive concentrated demand for connected telematics platforms across freight corridors. NHTSA rulemaking on automated driving system data recording intersects with FCC spectrum allocation decisions that removed 60% of dedicated safety spectrum for DSRC operations. Detroit anchors OEM specification authority, while Silicon Valley hosts cellular V2X chipset design centers.
Germany
OEMs and tier-one suppliers anchor European V2X communication and telematics development with integrated production of sensor fusion modules. The EU's Cyber Resilience Act mandates baseline security standards for IoT-enabled automotive components with 15-year vulnerability response obligations. Stuttgart and Munich host concentrated engineering centers where Robert Bosch GmbH scales manufacturing for connected powertrain control systems.
China
MIIT-connected vehicle standards impose localization requirements for telematics data storage, forcing parallel cloud infrastructure architectures. Domestic OEMs expand connected vehicle deployments to optimize logistics and reduce downtime across commercial fleets. Shanghai and Shenzhen anchor manufacturing clusters for telematics control units benefiting from subsidized domestic assembly.
South Korea
Secure element fabrication concentrates in foundry complexes supplying authentication protocols for vehicle-to-everything communications. The country's national semiconductor regulator coordinates capacity allocation priorities for automotive-grade chipset production. Seoul anchors design centers where suppliers qualify system-on-chip architectures for sub-10 millisecond response thresholds.
Japan
Automotive electronics suppliers integrate telematics modules with zonal electronic architectures migrating from distributed domain controllers. METI industrial policy supports edge computing qualification for functional safety compliance. Nagoya and Tokyo host engineering centers where Renesas Electronics develops vehicle fusion computers aggregating sensor inputs across 40+ electronic control units.
Automotive Internet of Things (IoT) Market Competitive Environment
On the supply side, the industry is consolidating around semiconductor vendors with automotive-grade certification capabilities and tier-one electronics suppliers with systems integration expertise. Three strategic archetypes dominate: chipset designers with cellular V2X protocol expertise, sensor fusion specialists with control module manufacturing scale, and secure element providers with authentication infrastructure. Competitive moves concentrate on strategic partnerships for multi-protocol communication stacks and geographic expansion to capture PLI scheme subsidies in India.
Within the semiconductor archetype, NXP Semiconductors N.V. and QUALCOMM Incorporated exemplify divergent specialization vectors—NXP anchors secure element design for authentication protocols while Qualcomm dominates cellular V2X chipset supply for North American and Asian OEM programs. Robert Bosch GmbH occupies a position representing European manufacturing scale in sensor fusion and control modules, anchoring tier-one supplier consolidation around connected powertrain systems.
| Leading Market Players |
|---|
| NXP Semiconductors N.V. |
| Robert Bosch GmbH |
| Intel Corporation |
| Harman International Industries, Inc. |
| Texas Instruments, Inc. |
| Infineon Technologies AG |
| TomTom N.V. |
| Thales S.A. |
| QUALCOMM Incorporated |
| Others |
Value Chain & Pricing Dynamics
Taiwanese foundry concentration for automotive-grade secure elements determines both tiered module pricing spreads and multi-source qualification timelines for tier-one electronics suppliers. Automotive OEMs face 18-24 month supplier validation cycles that compress negotiation leverage when single-source dependencies emerge for V2X authentication chipsets.
Pricing Analysis
Industrial OEM buyers anchor a subscription-tiered pricing structure where telematics platforms command recurring SaaS fees against per-unit hardware margins for control modules. Price differentiation separates ASIL-D certified components from standard-grade alternatives, with ISO 26262 validation adding substantial certification premiums. Cost compression in entry-segment telematics hardware is intensifying because MediaTek and Qualcomm chipset competition erodes module margins. Fleet operators exhibit highest price sensitivity due to thousand-unit procurement scales, while German luxury OEMs absorb premium pricing for zonal architecture integration.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment limit foundry capacity expansion for automotive secure element production across Taiwan, South Korea, and the Netherlands. Raw material dependencies center on silicon wafers, rare-earth magnets for GNSS modules, and copper-laminate substrates for high-frequency communication boards. Single-source vulnerability concentrates in TSMC's automotive-grade fabrication nodes where alternative qualification runs 24-36 months. Distribution runs through tier-one electronics suppliers who consolidate sensor fusion modules before OEM assembly line delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive IoT sector rewards organizations that secure functional safety engineering talent and automotive-grade semiconductor certification capabilities ahead of competitor qualification timelines. ASIL-D validation expertise remains scarce across OEM engineering centers and tier-one supplier R&D facilities.
For Market Incumbents: Harden cybersecurity liability allocation through supplier contract restructuring that pushes 15-year vulnerability response obligations toward component vendors. Lock in multi-year foundry capacity reservations at Taiwan Semiconductor Manufacturing and Samsung Foundry before export control tightening restricts equipment availability. Prioritize backward integration into edge AI system-on-chip design to reduce Qualcomm and NXP dependency for neural inference acceleration. For New Entrants and Emerging Players: India's PLI scheme subsidization gaps in domestic telematics control unit assembly offer white-space entry before local OEMs consolidate vendor relationships. Target aftermarket retrofit demand for J1939-compatible heavy-duty truck installations where incumbent integration timelines leave 18-24 month service windows. Pursue API-first platform architectures that bypass hardware margin competition through transportation management system interoperability fees. For Investors and Strategic Acquirers: The EU Cyber Resilience Act's 15-year security update mandate reshapes the acquisition landscape toward component vendors with established vulnerability response infrastructure. Long-term viability favors secure element designers with existing automotive certification over software-only entrants facing hardware qualification barriers. Monitor FCC spectrum reallocation litigation outcomes as the signal indicating whether cellular V2X or DSRC protocol investments capture infrastructure deployment capital.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Mercedes-Benz and BMW zonal architectures reduce 30% wiring harness mass through ECU consolidation. |
| Cellular V2X Chipset Supply Agreement | Qualcomm's sub-6 GHz and mmWave multi-band qualification secures North American OEM program slots. |
| Edge AI System-on-Chip Qualification | NXP Semiconductors and Renesas Electronics compete for sub-10 millisecond inference response thresholds. |
| Geographic Manufacturing Footprint Expansion | India's PLI scheme subsidies reduce import duty exposure for telematics control unit assembly. |
| Charging Infrastructure Data Partnership | Fleet operators demand unified analytics integration between telematics platforms and energy management systems. |
Study Parameters
The analysis maps telematics hardware, V2X communication modules, edge computing architectures, and insurance telematics platforms, each validated through primary interviews with OEM platform engineers, tier-one supplier procurement directors, fleet operations managers, and semiconductor foundry planning officers. Secondary sources include NHTSA rulemaking dockets, FCC spectrum allocation records, EU Cyber Resilience Act implementation guidance, and vehicle production databases from IHS Markit. Bottom-up unit economics for connected vehicle content per unit triangulate against top-down market sizing from regional registration data.
Assumption sets held regulatory timelines and spectrum allocation decisions fixed while varying semiconductor capacity utilization rates and fleet digitization adoption curves across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, deployment tier, and regional production cluster. CAGRs derive from logistic curve fitting to connected vehicle penetration rates, with semiconductor supply elasticity and cybersecurity certification backlog serving as automotive-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in commercial vehicle freight volumes, semiconductor capital expenditure cycles, or cross-border data localization enforcement would shift the trajectory. Material shifts in FCC 5.9 GHz band litigation outcomes or Taiwan Strait supply continuity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
IoT in Retail Market
Internet of Things (IoT)
Iot-Enabled Devices Market
Internet of Things (IoT)
Enterprise IoT Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
Global Internet of Things (IoT) Defence Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
Cellular M2M Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market