
 Consumer Communication Services Market | 2026-2036
Consumer Communication Services Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Communication Services Market Outlook
Multi-source infrastructure partnerships is repositioning how carriers build network capacity. AT&T Inc. leverages its fiber backbone to anchor premium residential and enterprise segments. China Mobile Communications Corporation dominates domestic 5G deployment at manufacturing scale. Deutsche Telekom AG competes across European markets with integrated fixed-mobile convergence.
Consumer communication services encompass voice, messaging, video, and data transmission delivered over packet-switched and circuit-switched networks with latency requirements typically below 150 milliseconds for real-time applications. These services enable personal correspondence, commercial transactions, and organizational coordination across distributed geographies. Data services now captures the largest margin pool as metered and unlimited plans displace legacy voice revenue. 5G technology represents the fastest-expanding infrastructure layer, while VoIP has matured into a cost-optimized baseline for residential users. Messaging services sustains growth through rich communication services protocols that integrate payment and verification functions.
FCC spectrum auctions in the United States, EU AI Act transparency requirements for automated customer interfaces, and India's TRAI tariff regulations collectively shape competitive dynamics and service design constraints. GDPR data localization rules in Europe and India's draft data protection framework impose operational compliance costs that favor carriers with established legal infrastructure. Stakeholders must monitor spectrum allocation timelines, AI governance implementation, and cross-border data flow restrictions to anticipate structural shifts in service economics and market access conditions.
Market Dynamics
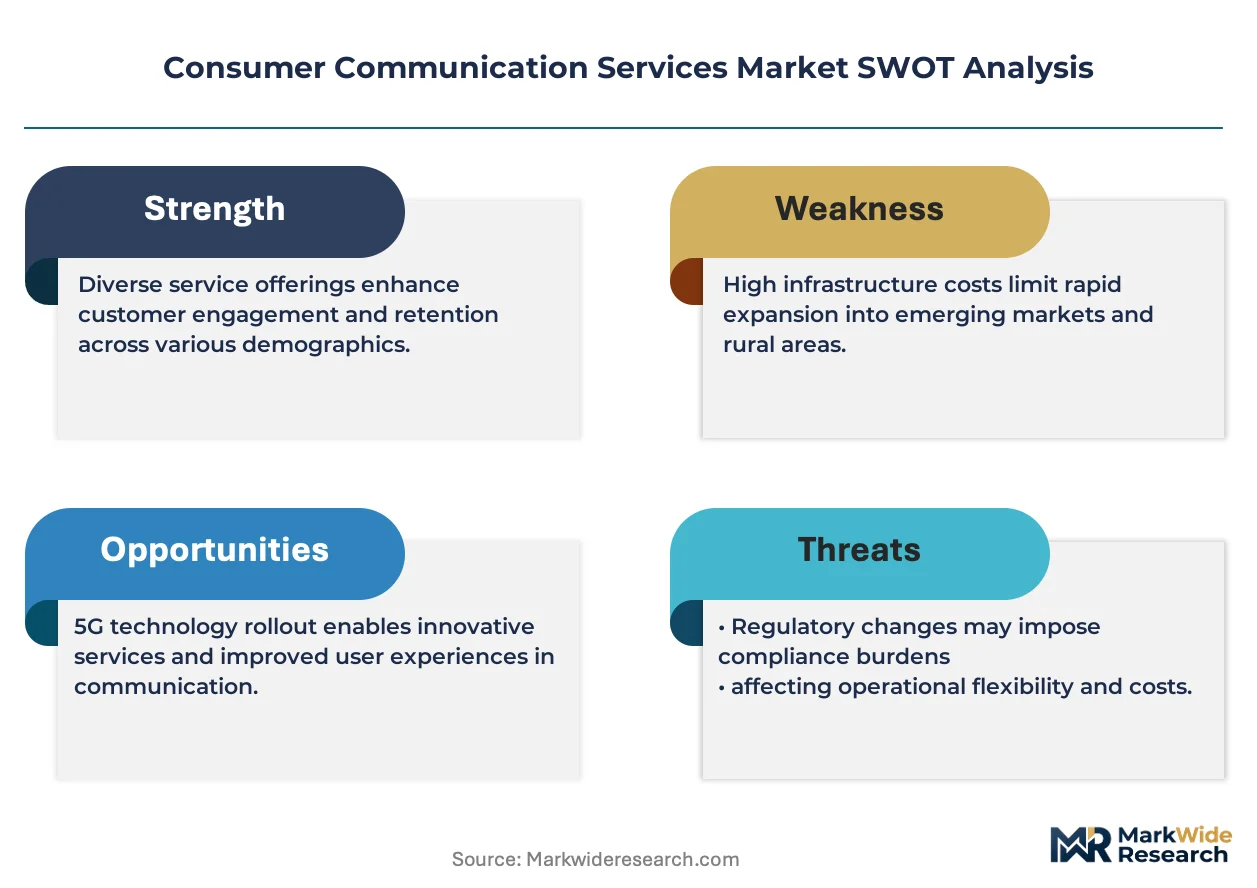
Enterprise migration to cloud-native communication stacks is compressing infrastructure refresh cycles. Carriers face simultaneous pressure from spectrum scarcity and AI-driven service personalization mandates.
Growth Catalysts
- EU AI Act transparency mandates:Automated customer interfaces must disclose algorithmic decision-making, creating demand for compliant middleware platforms.
- India PLI scheme:Domestic telecom equipment manufacturing incentives accelerate 5G base station deployment in underserved districts.
- Rich Communication Services:Protocols embedding payment verification and identity authentication expand messaging utility beyond basic text.
Market Restraints
- Radio frequency spectrum scarcity:Dense urban markets face allocation exhaustion, forcing costly secondary market acquisitions.
- Semiconductor supply concentration:Baseband processor fabrication depends on Taiwan-based foundries, exposing capacity vulnerability.
- Legacy circuit-switched maintenance:Rural copper network obligations drain capital from packet-switched modernization.
Strategic Opportunities
- Fixed-mobile convergence in Germany:Integrated billing and unified customer premises equipment reduce churn in saturated broadband markets.
- Edge computing co-location:Low-latency 5G infrastructure enables carrier partnerships with autonomous vehicle and industrial automation sectors.
- GDPR-compliant data residency:European enterprises prioritize carriers with sovereign cloud infrastructure for sensitive communications.
Industry Challenges
- AI/ML engineering talent scarcity:Network optimization and predictive maintenance functions compete with technology sector compensation.
- Multi-vendor interoperability certification:Open RAN deployments require extended testing cycles against proprietary stack benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Communication Services Market |
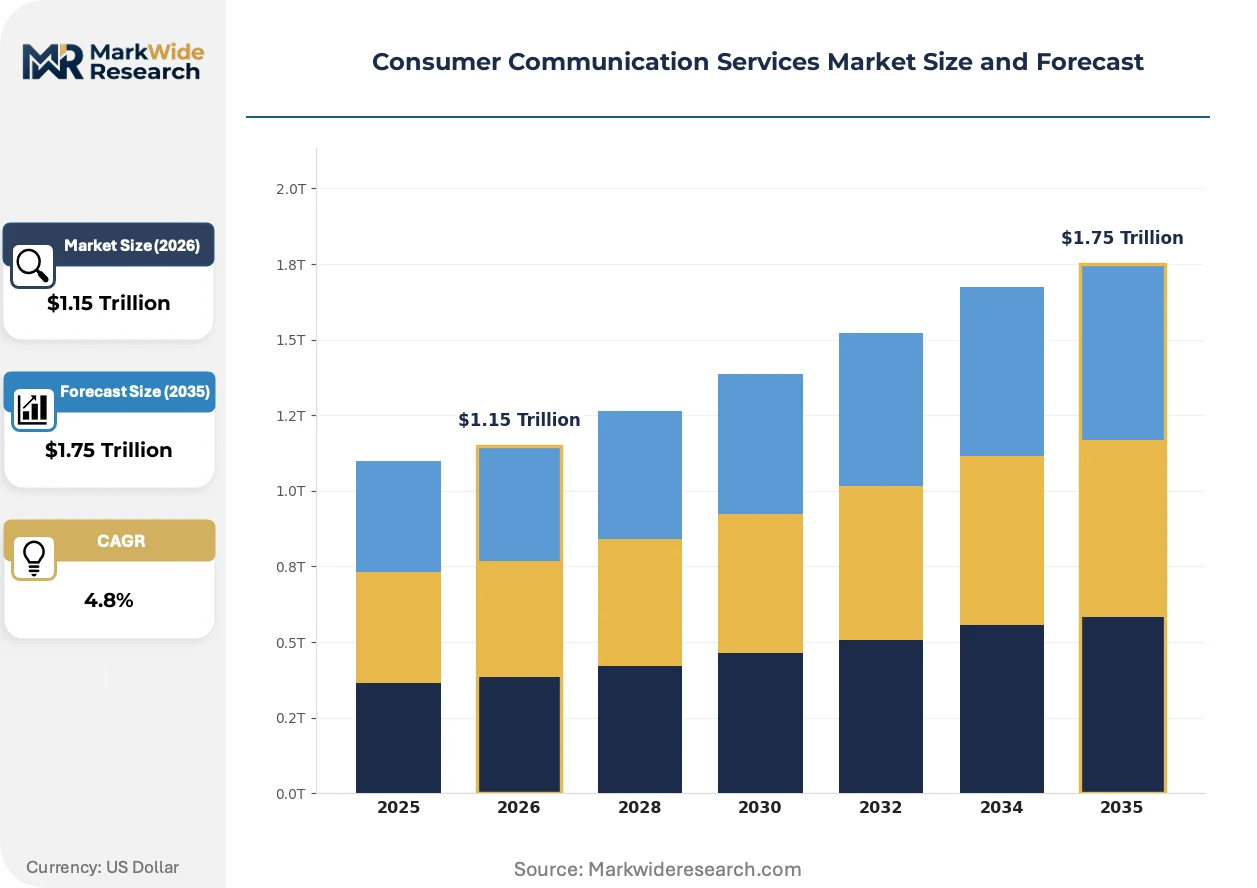
| Market Size in 2026 | $1.15 Trillion |
| Market Size in 2035 | $1.75 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice Services, Messaging Services, Video Conferencing, Data Services Customer Type: Residential Users, Small Businesses, Enterprises, Government Agencies Technology: VoIP, 4G LTE, 5G, Wi-Fi Application: Customer Support, Marketing Communication, Social Networking, Internal Communication |
| Companies Covered | AT&T Inc., Verizon Communications Inc., China Mobile Communications Corporation, Vodafone Group plc, Deutsche Telekom AG, Telefonica S.A., T-Mobile US Inc., Orange S.A., NTT Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Communication Services Market Strategic Shifts
Communication service architectures are fragmenting across edge, core, and cloud layers simultaneously. This decomposition creates new interface standards and vendor specialization points.
Network function virtualization is integrating software-defined routing with containerized session border controllers. Tier-1 carriers deploy these stacks to reduce proprietary hardware dependency. The shift is integrating third-party application marketplaces directly into carrier service portals.
GDPR data localization enforcement is tightening cross-border traffic routing requirements. European carriers must maintain subscriber metadata within jurisdictional boundaries. German and French enterprises now specify sovereign infrastructure clauses in procurement contracts.
Subscription fatigue among residential users is driving unbundling of communication service components. Consumers in India and Brazil select standalone data, voice, and messaging plans from different providers. Mobile virtual network operators capture this fragmentation with flexible, short-cycle pricing.
Consumer Communication Services Market Segmentation
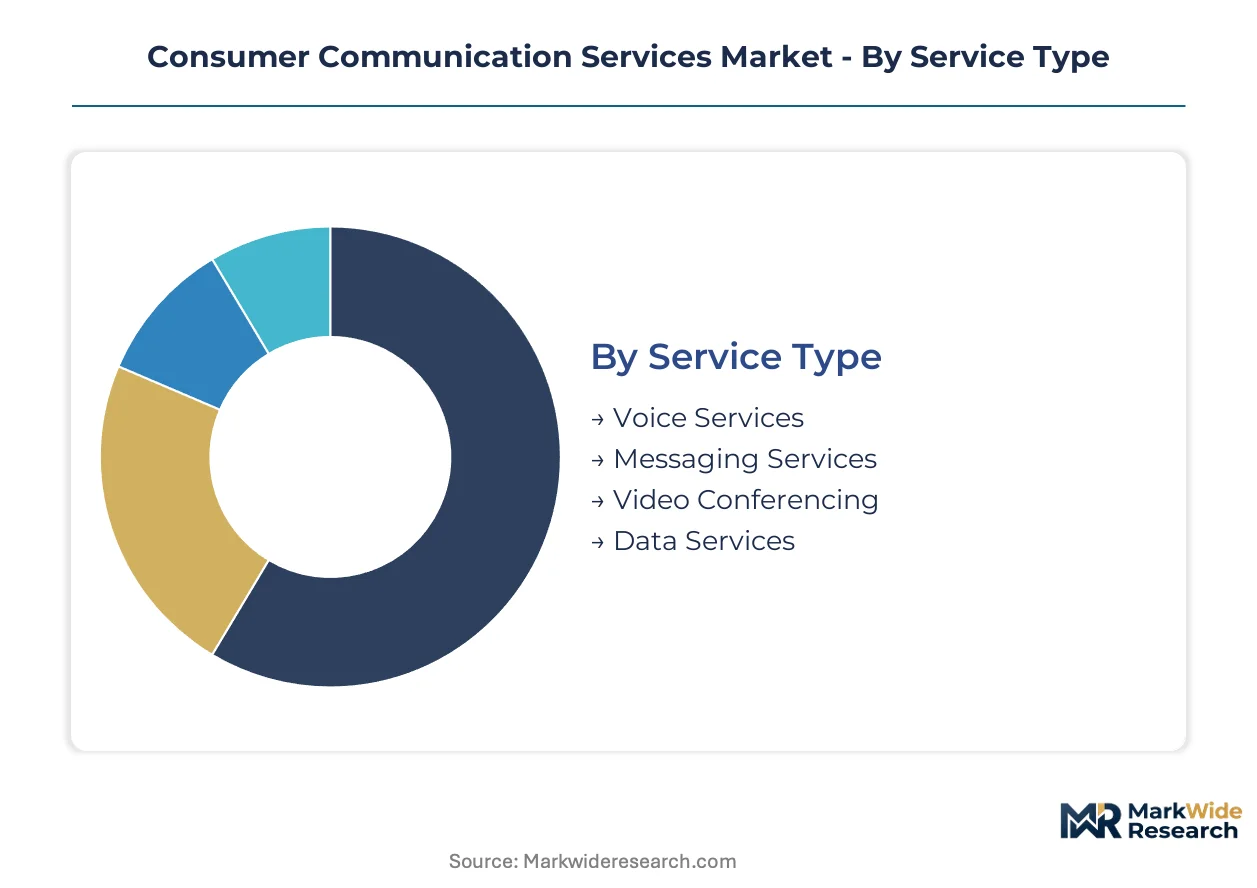
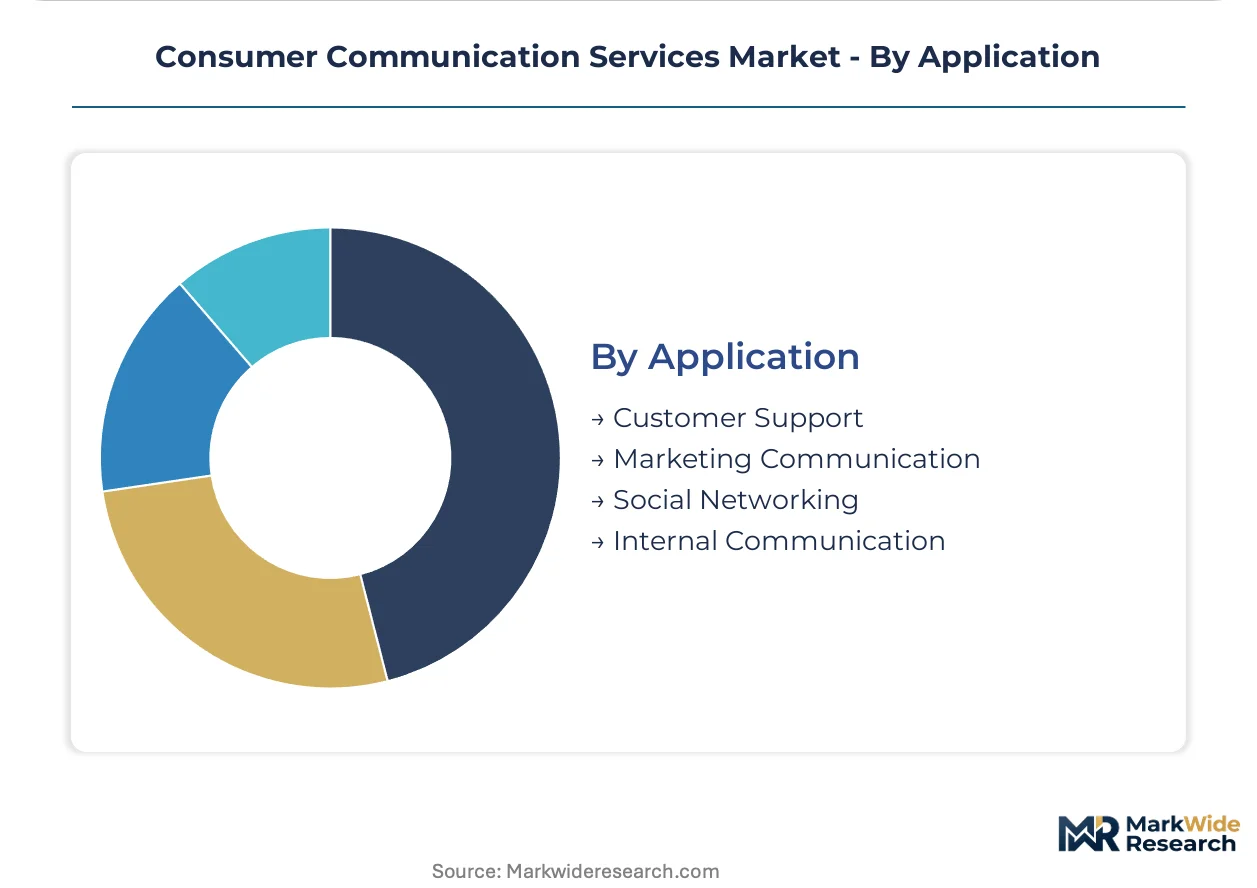
Segmentation in consumer communication services reveals distinct procurement patterns across customer tiers and use cases. Service providers configure network resources, pricing architectures, and support models differently for each segment to optimize margin capture and retention.
Service Type:
Residential subscribers prioritize cost predictability while enterprises demand service-level guarantees that residential tiers cannot support.
- Voice Services:Circuit-switched and packet-switched voice transmission with PSTN interconnection requirements. Demand concentrates in rural India and Southeast Asia where copper infrastructure obligations delay VoIP migration; TRAI tariff floors protect incumbent revenue pools.
- Data Services:Metered and unlimited internet access plans with bandwidth tiering. Enterprise adoption in Germany and France drives premium fiber deployments; GDPR data residency clauses now specify sovereign cloud infrastructure in procurement contracts.
- Messaging Services:SMS, MMS, and rich communication services protocols.
- Video Conferencing:Real-time video collaboration with sub-150ms latency requirements.
Volume sits with Data Services; growth tilts toward Messaging Services.
Customer Type:
Procurement authority and contract complexity separate these tiers more than usage volume alone.
- Enterprises:Multi-site organizations with unified communication requirements and custom integration needs. Cloud-native stack migration in the United States compresses infrastructure refresh cycles; FCC spectrum auctions shape carrier selection criteria for low-latency applications.
- Government Agencies:Public sector entities with sovereign infrastructure mandates and security certification requirements. EU AI Act transparency mandates for automated interfaces reshape procurement specifications; German federal contracts now require algorithmic decision disclosure.
- Residential Users:Individual consumers and households selecting bundled or unbundled plans.
- Small Businesses:Commercial subscribers with simplified procurement and standardized service tiers.
Revenue concentrates with Enterprises; expansion tilts toward Government Agencies.
Technology:
Infrastructure maturity and capital intensity create divergent deployment economics across protocol generations.
- 5G:New radio interfaces with network slicing and edge computing capabilities. Manufacturing-scale deployment by China Mobile anchors domestic infrastructure buildout; India PLI scheme incentives accelerate base station installation in underserved districts.
- VoIP:Session initiation protocol and real-time transport protocol voice delivery over IP networks. Residential cost optimization in Brazil and India drives standalone plan selection; mobile virtual network operators capture fragmentation with flexible pricing cycles.
- 4G LTE:Mature radio access technology with established device ecosystems.
- Wi-Fi:Unlicensed spectrum access for indoor and hotspot coverage extension.
Deployment volume sits with 4G LTE; infrastructure investment tilts toward 5G.
Application:
Use case specificity determines feature requirements and integration depth with enterprise systems.
- Customer Support:Interactive voice response and chatbot-enabled service interfaces. Automated system deployment in the United States faces FCC disclosure requirements for AI-driven decision-making; EU AI Act mandates algorithmic transparency for consumer-facing automation.
- Internal Communication:Organizational coordination tools with directory integration and access controls. German and French enterprises specify sovereign cloud infrastructure in procurement; GDPR metadata localization rules constrain cross-border routing architectures.
- Marketing Communication:Campaign orchestration and promotional messaging delivery.
- Social Networking:Peer-to-peer content sharing and community platform integration.
Adoption volume sits with Internal Communication; feature development tilts toward Customer Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spectrum allocation decisions in Washington, Brussels, and Beijing anchor geographic differentiation in network deployment timelines and service economics.
United States
Enterprise cloud migration and fixed wireless access adoption drive infrastructure investment. FCC spectrum auctions shape carrier capital allocation priorities for mid-band 5G coverage. The Dallas-Fort Worth metroplex hosts major network operations centers where fiber-to-the-home buildouts accelerate.
Germany
Industrial automation demand and automotive sector connectivity requirements propel 5G standalone deployment. The EU AI Act mandates algorithmic transparency for automated customer interfaces used by federal agencies. Bavaria's manufacturing corridor anchors private network installations at automotive assembly plants.
China
Manufacturing-scale 5G deployment and smart city integration sustain infrastructure investment velocity. MIIT spectrum policies prioritize domestic equipment vendor ecosystems in base station procurement. The Yangtze River Delta concentration around Shanghai drives enterprise private network adoption at port and logistics facilities.
India
Rural connectivity gaps and digital payment integration expand addressable subscriber bases. TRAI tariff regulations protect incumbent revenue floors while PLI scheme incentives accelerate domestic telecom equipment manufacturing. Karnataka's Bengaluru tech corridor anchors enterprise communication stack development centers.
Brazil
Mobile virtual network operator proliferation and unbundled plan selection reshape residential pricing dynamics. Anatel spectrum management frameworks influence carrier consolidation patterns in secondary markets. São Paulo's metropolitan density supports millimeter-wave 5G trials for fixed wireless substitution.
Consumer Communication Services Market Competitive Environment
Fixed-mobile convergence dominates the current landscape as carriers seek to reduce churn in saturated broadband markets. The vendor base organizes around three tiers: integrated national operators with fiber-wireless assets, mobile-first challengers with spectrum depth, and infrastructure-light virtual operators with flexible pricing. Strategic archetypes include convergence specialists bundling residential and enterprise services, wholesale capacity brokers selling network slices, and platform aggregators integrating third-party applications. M&A activity and spectrum acquisition represent the dominant competitive moves.
Within the integrated operator tier, AT&T Inc. and Verizon Communications Inc. exemplify fiber-anchored convergence strategies, while Deutsche Telekom AG occupies a position as the European fixed-mobile integration reference. China Mobile Communications Corporation represents manufacturing-scale deployment archetypes with domestic infrastructure concentration. These entities sit within distinct regulatory environments—FCC auction frameworks in North America, EU AI Act compliance mandates in Europe, and MIIT industrial policy coordination in China—that shape permissible competitive moves and capital allocation priorities.
| Leading Market Players |
|---|
| AT&T Inc. |
| Verizon Communications Inc. |
| China Mobile Communications Corporation |
| Vodafone Group plc |
| Deutsche Telekom AG |
| Telefonica S.A. |
| T-Mobile US Inc. |
| Orange S.A. |
| NTT Group |
| Others |
Value Chain & Pricing Dynamics
Carrier-owned infrastructure with sovereign-backed spectrum licenses shapes both supply commitments and pricing discipline across fixed-mobile convergence bundles. Deutsche Telekom and China Mobile anchor procurement volumes that determine equipment vendor pricing tiers, while mobile virtual network operators in Brazil and India arbitrage wholesale capacity to compress retail margins.
Pricing Analysis
Warranty and service-bundling separates premium enterprise tiers from unbundled residential offerings in this market. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation resting on service-level guarantees and GDPR-compliant data residency certification. Cost compression in residential data plans is intensifying because mobile virtual network operators capture subscriber fragmentation with flexible short-cycle pricing. Small businesses exhibit highest price sensitivity due to standardized procurement, while government agencies with sovereign infrastructure mandates show lowest sensitivity.
Supply Chain Analysis
Freight and logistics costs for baseband processors and radio frequency equipment concentrate supply risk around Taiwan-based foundries and Chinese assembly facilities. Semiconductor fabrication draws from TSMC and Samsung Foundry capacity, with passive components and antenna systems sourced from Chinese and Vietnamese manufacturing clusters. Single-source vulnerability in advanced node chip production exposes carrier infrastructure timelines to geopolitical disruption. Distribution runs through equipment vendor direct sales for tier-1 carriers and distributor networks for regional operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase where 5G standalone architectures displace 4G LTE as the baseline infrastructure layer. VoIP and rich communication services protocols are simultaneously eroding legacy circuit-switched voice revenue pools.
For Market Incumbents: Deepen fixed-mobile convergence bundling to reduce churn in saturated broadband markets across Germany and the United States. Acquire spectrum depth in secondary markets before auction exhaustion forces costly secondary market acquisitions. Invest in sovereign cloud infrastructure certification to capture GDPR-compliant enterprise procurement in France and Germany.
For New Entrants and Emerging Players: Mobile virtual network operator partnerships with wholesale capacity brokers offer lowest barrier to subscriber acquisition in Brazil and India. Target underserved rural districts in India where PLI scheme incentives accelerate domestic equipment deployment and reduce capital intensity. Lead with unbundled standalone data and messaging plans that exploit subscription fatigue among residential users.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional fiber operators with last-mile density in secondary US and European metros where enterprise cloud migration sustains demand. Long-term viability hinges on 5G network slicing capabilities and edge computing co-location partnerships with industrial automation sectors. Monitor FCC and EU spectrum auction timelines as inflection indicators for carrier capital allocation priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Acquisition | FCC mid-band auctions and EU 5G allocations determine carrier competitive positioning for low-latency services. |
| Fixed-Mobile Convergence | Integrated billing and customer premises equipment reduce churn in German and US broadband markets. |
| Edge Computing Co-location | Carrier partnerships with automotive and industrial automation sectors monetize 5G network slicing capabilities. |
| GDPR-Compliant Infrastructure | Sovereign cloud certification captures enterprise procurement from German and French federal agencies. |
| Open RAN Deployment | Multi-vendor interoperability reduces proprietary hardware dependency but extends testing cycles. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with network operations executives, carrier procurement managers, telecom equipment vendor sales directors, and regulatory affairs specialists at TRAI and FCC combined with FCC spectrum auction records, EU AI Act implementation guidance, carrier SEC 10-K infrastructure disclosures, and ITU spectrum allocation databases. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from carrier reported metrics.
Granularity-level modeling deployed service type, customer tier, technology generation, and application use case as core segmentation dimensions across the projection horizon. CAGRs derived from equipment deployment trajectories, subscriber migration patterns, and ARPU compression curves. 5G base station installation rates and enterprise unified communication stack adoption curves served as industry-specific forecast inputs.
Caveats apply where semiconductor supply disruption, spectrum auction delays, or AI Act compliance cost escalation could materially shift the outlook. Forecasts reflect assumptions about infrastructure investment continuity and regulatory implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Walkie Talkie Market
Communication Services
Mobile Messaging Market
Communication Services
Pcaas Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Latin America Postal Service Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
India Communication Platform As a Service (Cpaas) Market
Communication Services
Video Conferencing Market
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Outbound Telemarketing Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Web Conferencing Market
Communication Services
Broadcasting Solutions Market