
 Global Autonomous Data Platform Market | 2026-2036
Global Autonomous Data Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autonomous Data Platform Market Foresight
The gap between premium autonomous data platforms and commodity cloud warehousing is recalibrating competitive dynamics across the sector. Oracle Corporation leverages its integrated database heritage to anchor high-margin enterprise contracts with deep on-premise footprints. Snowflake Inc. competes through elastic cloud-native architecture that sustains pricing power among data-intensive SaaS buyers.
An autonomous data platform orchestrates ingestion, quality assurance, governance, and analytics workflows through embedded machine learning algorithms that minimize human intervention in pipeline management. These systems process structured and semi-structured data across distributed environments, enabling real-time operational intelligence for enterprises managing petabyte-scale estates. Cloud-based deployment configurations are capturing the fastest expansion as organizations migrate from rigid on-premise estates to elastic consumption models. Within solution categories, data governance modules are deepening margin pools as regulatory complexity intensifies compliance spending.
The EU AI Act, HIPAA in the United States, and ISO standards for data quality management are reshaping product requirements and procurement criteria across jurisdictions. The report notes that vendors must align autonomous decision-making capabilities with emerging algorithmic transparency mandates to maintain market access in regulated industries. Stakeholders should monitor how enforcement patterns around automated data processing evolve across national regulators.
Market Dynamics
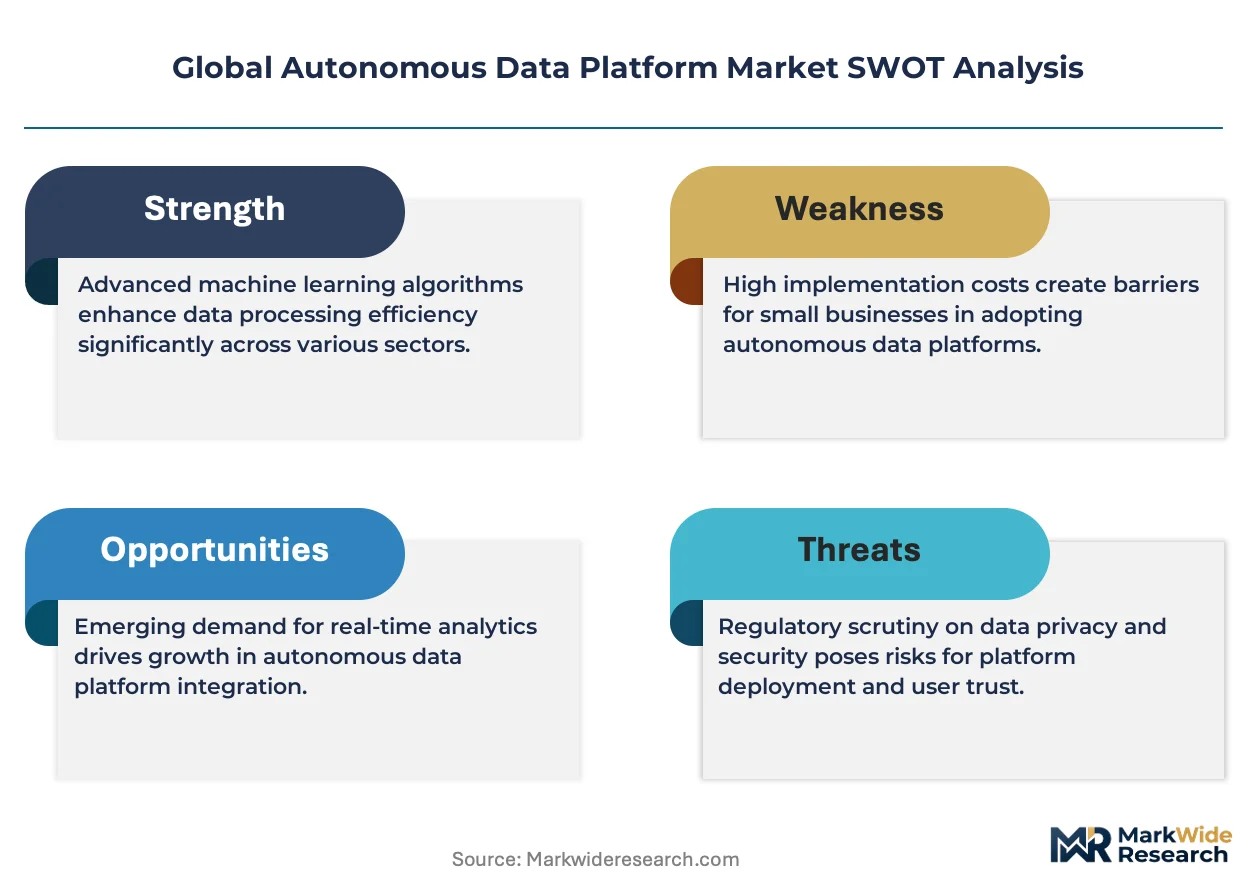
Machine learning pipeline automation is compressing the labor cost structure for enterprise data operations, forcing vendors to rearchitect around embedded AI rather than human-managed workflows.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making transparency requirements are compelling financial services firms in Germany and France to upgrade legacy data infrastructure with governance-native platforms.
- Petabyte-scale SaaS estates:Cloud-native software vendors operating multi-tenant architectures require autonomous quality assurance to maintain service-level agreements across distributed customer workloads.
- Silicon Valley venture deployment:Concentrated capital allocation to AI-native startups is accelerating demand for self-optimizing data pipelines that minimize engineering headcount.
Market Restraints
- Specialized MLOps talent scarcity:Shortage of engineers capable of tuning autonomous pipeline algorithms limits deployment velocity at mid-market enterprises.
- Hyperscaler dependency:Compute and storage concentration within AWS, Azure, and GCP creates vendor lock-in risk and margin pressure for independent platform vendors.
- Algorithmic interpretability gaps:Black-box automation conflicts with ISO standards for data quality management and sector-specific audit requirements in healthcare.
Strategic Opportunities
- India's digital public infrastructure:Unified Payments Interface and Account Aggregator frameworks generate real-time data volumes requiring autonomous governance for compliance with RBI data localization norms.
- Edge-to-cloud orchestration:Convergence of 5G network slicing with containerized data pipelines enables latency-sensitive manufacturing analytics in industrial corridors.
- CSRD sustainability reporting:Mandatory EU corporate sustainability disclosures are creating demand for autonomous ESG data collection and validation workflows.
Industry Challenges
- Legacy mainframe integration:Financial institutions with core banking systems on IBM zSeries face multi-year migration timelines to connect autonomous pipelines with batch-oriented historical data.
- Cross-border data sovereignty:Conflicting national requirements from China's PIPL, EU GDPR, and US CLOUD Act complicate architecture design for multinational deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autonomous Data Platform Market |
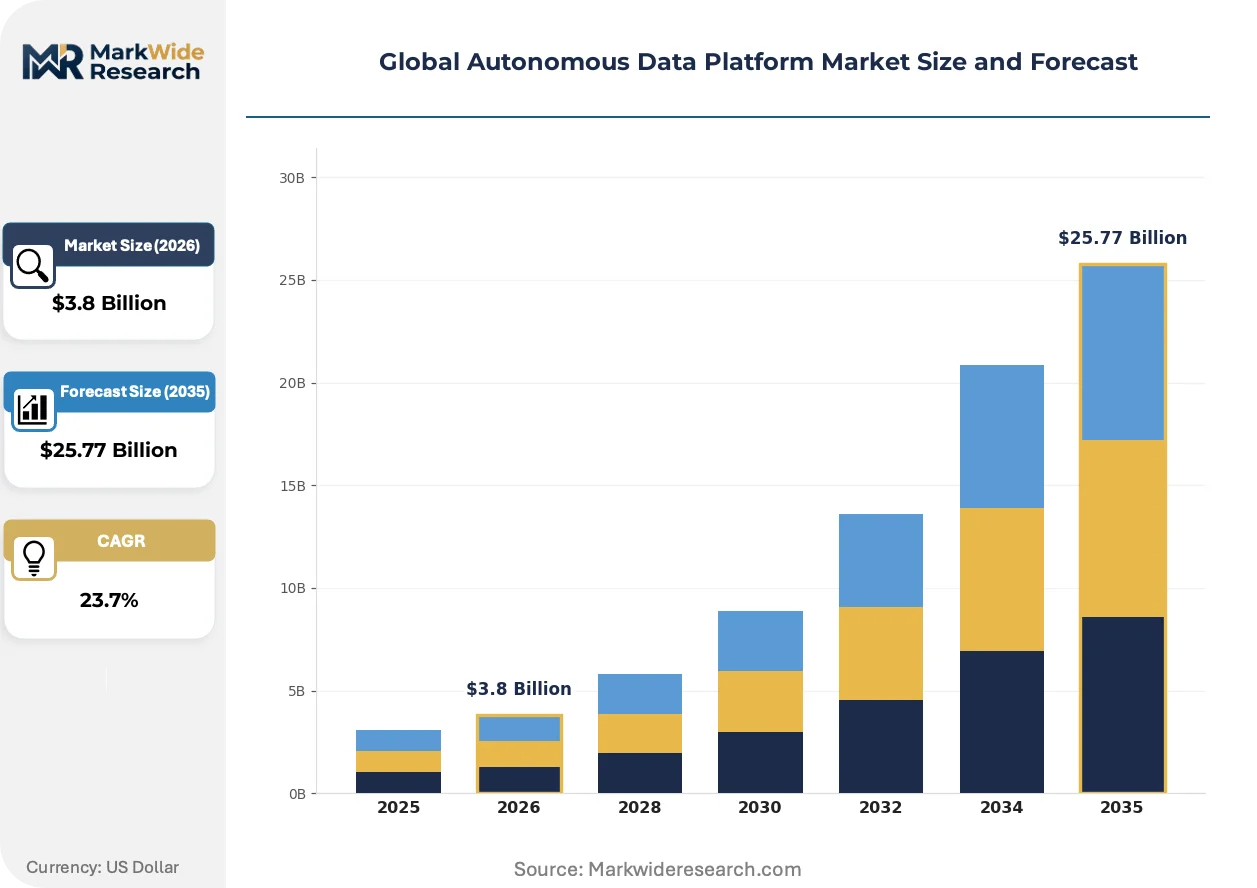
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $25.77 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Cloud Solution: Data Integration, Data Quality, Data Governance, Analytics End User: Enterprises, SMEs, Government Agencies, Education Technology: Machine Learning, Natural Language Processing, Data Warehousing, Data Lakes |
| Companies Covered | Oracle Corporation, Amazon Web Services, International Business Machines Corporation, Microsoft Corporation, Teradata Corporation, Snowflake Inc., Google LLC, Cloudera, Inc., Databricks, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autonomous Data Platform Market Shifts & Advancements
Autonomous data platforms are pivoting from passive storage layers to active decision infrastructure, embedding governance and optimization directly within ingestion workflows rather than treating them as downstream concerns.
Neural query optimization is expanding into enterprise data warehouses, automatically rewriting SQL execution plans based on workload patterns. Large retailers and logistics operators in the United States are deploying these engines to cut query latency by half without manual index tuning. This compression of performance engineering labor is expanding into adjacent markets as vendors bundle optimization with governance modules.
The EU AI Act's risk classification framework is forcing platform vendors to implement algorithmic audit trails and human-in-the-loop checkpoints for high-risk automated decisions. Financial services procurement teams in Frankfurt and Paris now require documentation of training data provenance and model drift monitoring. Vendors lacking these capabilities are losing RFP eligibility in regulated European verticals.
Consumption-based pricing for data pipeline workloads is displacing fixed-capacity licensing among cloud-native buyers. SaaS vendors with variable data volumes prefer per-query or per-GB models that align costs with actual processing rather than provisioned infrastructure. This preference is most visible in New York and London financial corridors where CFOs scrutinize unit economics of data operations.
Global Autonomous Data Platform Market Segmentation
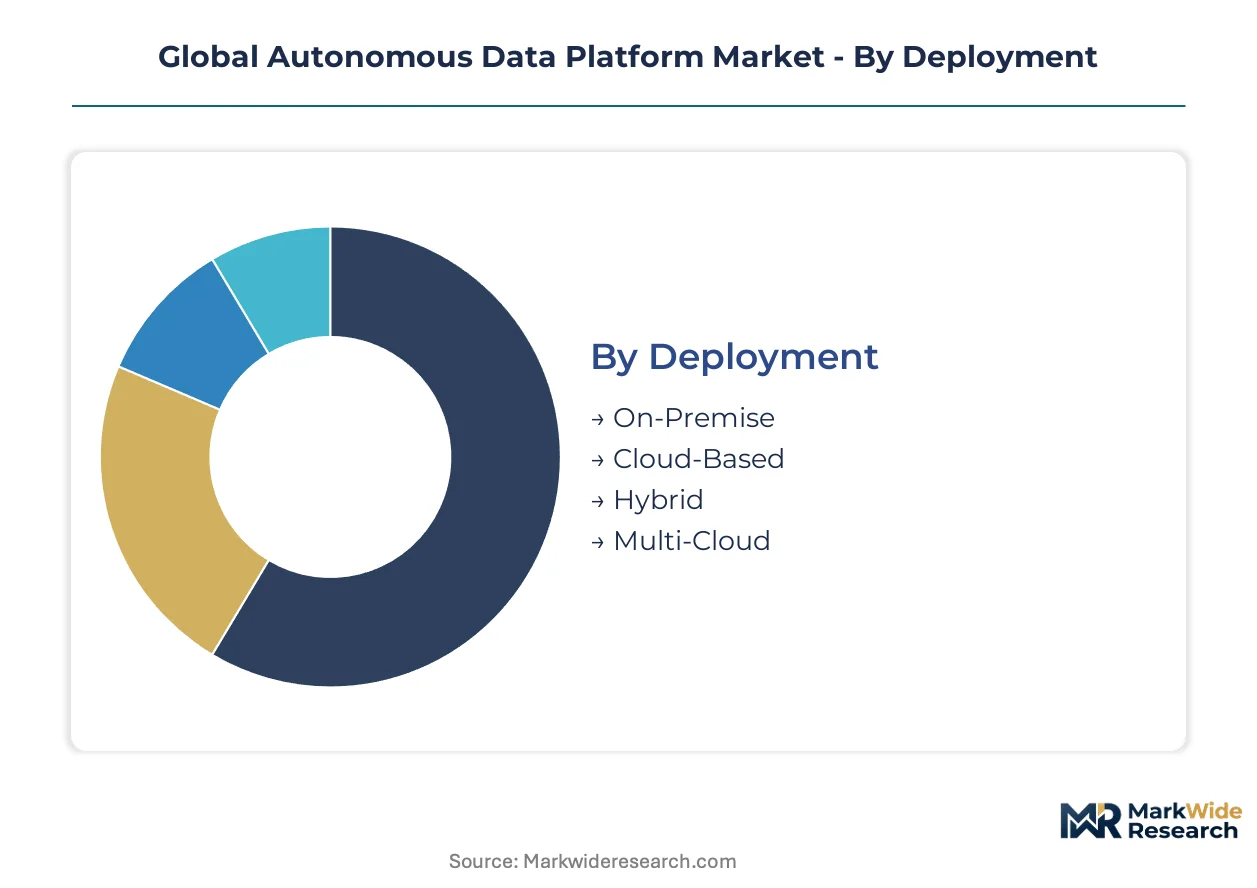
Segmentation in autonomous data platforms reveals how infrastructure choices cascade through compliance obligations, operational complexity, and talent requirements. Buyers select deployment modes and technology stacks based on regulatory jurisdiction, data sovereignty mandates, and existing IT estate composition.
Deployment:
Architecture decisions hinge on data residency requirements and latency sensitivity for real-time workloads.
- Cloud-Based:Elastic compute pools enable consumption-aligned spending for variable analytics workloads. Financial services firms in New York and London prefer this model to avoid capital-intensive infrastructure commitments while meeting SEC and FCA audit requirements through provider certifications.
- On-Premise:Dedicated hardware estates retain sensitive data within corporate perimeters for sectors with strict localization mandates. German automotive manufacturers and French defense contractors deploy these configurations to satisfy EU data sovereignty expectations and ANSSI security guidelines.
- Hybrid:Split architectures process regulated data on-premise while bursting analytics to cloud regions. Japanese manufacturers use this approach to keep METI-designated critical data domestic while leveraging AWS Tokyo for compute-intensive simulations.
- Multi-Cloud:Orchestration across AWS, Azure, and GCP reduces vendor lock-in risk for mission-critical pipelines. Australian banks and Singaporean fintechs adopt this pattern to negotiate pricing and satisfy APRA or MAS operational resilience mandates.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Multi-Cloud.
Solution:
Functional modules address distinct pain points across the data lifecycle, from ingestion through consumption.
- Data Governance:Policy enforcement engines automate lineage tracking, access control, and retention scheduling. EU AI Act compliance spending in Frankfurt and Paris is accelerating procurement of these modules for algorithmic audit trail generation.
- Data Quality:Automated profiling and cleansing pipelines detect anomalies without manual schema inspection. US healthcare systems under HIPAA deploy these tools to maintain patient record integrity across fragmented EHR environments.
- Data Integration:Connectors and transformation engines unify siloed sources into queryable pipelines. Indian enterprises integrating UPI transaction streams with legacy core banking systems represent expanding demand.
- Analytics:Embedded BI and ML model serving layers deliver insights without separate visualization platforms. Brazilian retailers and Mexican logistics operators leverage these capabilities for demand forecasting without dedicated data science teams.
Margin concentration sits with Data Governance. Volume expansion is climbing the fastest in Data Quality.
End User:
Organizational scale determines complexity tolerance, customization requirements, and procurement sophistication.
- Enterprises:Global corporations with petabyte-scale estates require federated governance across business units. Swiss pharmaceutical multinationals and South Korean conglomerates drive demand for multi-tenant configurations with granular cost allocation.
- SMEs:Mid-market buyers prioritize managed services and pre-configured templates over customization. Canadian professional services firms and Spanish regional banks select these offerings to compress implementation timelines.
- Government Agencies:Public sector procurement emphasizes security certifications and domestic support infrastructure. UAE federal entities and Saudi government ministries require Arabic-language interfaces and local data center presence.
- Education:Universities and research institutions seek discounted licensing for non-commercial analytics workloads. Australian Group of Eight universities and Dutch technical institutes deploy these platforms for genomic and climate research datasets.
Procurement sophistication peaks with Enterprises. Fastest-growing demand is materializing in Government Agencies.
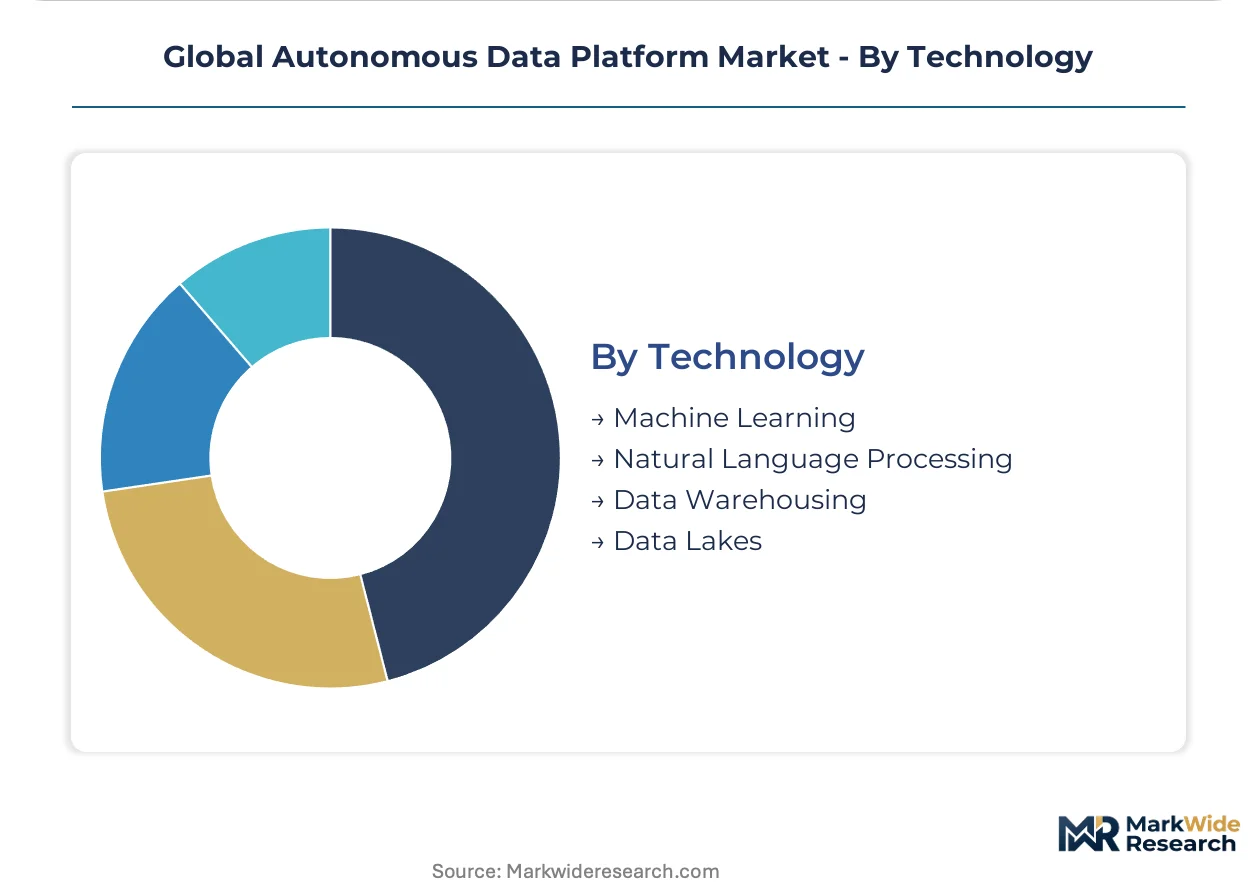
Technology:
Underlying capabilities determine automation depth, interpretability, and integration complexity with existing toolchains.
- Machine Learning:Automated feature engineering and model management pipelines reduce MLOps headcount. Silicon Valley SaaS vendors and Tel Aviv cybersecurity firms embed these engines for predictive workload scaling.
- Natural Language Processing:Semantic parsing and entity extraction enable conversational interfaces for non-technical users. Italian insurance underwriters and Polish customer service operations deploy these capabilities for policy document analysis.
- Data Warehousing:Structured storage with columnar optimization supports high-concurrency BI workloads. Nordic retail chains and Austrian industrial manufacturers rely on these foundations for ERP-integrated reporting.
- Data Lakes:Schema-on-read repositories accommodate raw ingestion before transformation decisions. Indonesian e-commerce platforms and Vietnamese digital banks use these architectures for exploratory analytics on unmodeled event streams.
Technology maturity clusters around Data Warehousing. Investment intensity is concentrating in Machine Learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley and New York financial corridors concentrate autonomous data platform procurement, with venture capital deployment and cloud-native enterprise density driving North American dominance in the sector.
United States
SEC audit requirements and HIPAA compliance obligations propel financial services and healthcare adoption. Cloud-native SaaS vendors in San Francisco and Manhattan prioritize elastic consumption models to minimize engineering headcount. The Boston biotech corridor deploys autonomous pipelines for genomic data governance under FDA regulatory frameworks.
Germany
Automotive manufacturers and industrial conglomerates demand on-premise configurations for EU data sovereignty. ANSSI security guidelines and the EU AI Act's risk classification framework reshape procurement criteria in Frankfurt and Munich. German financial services firms upgrade legacy infrastructure to meet algorithmic transparency mandates.
India
RBI data localization norms and UPI transaction volumes generate real-time governance requirements. Account Aggregator frameworks compel autonomous quality assurance for compliance across Mumbai and Bangalore fintech clusters. The country's national IT regulator pushes domestic cloud infrastructure development.
United Kingdom
FCA operational resilience mandates and post-Brexit data adequacy negotiations complicate architecture decisions. London financial services firms adopt multi-cloud configurations to negotiate pricing across AWS, Azure, and GCP. Edinburgh and Manchester emerging tech clusters drive mid-market demand for managed service offerings.
Japan
METI-designated critical data localization requirements shape hybrid deployment patterns. Tokyo-based manufacturers burst analytics to cloud regions while retaining sensitive operational data domestically. Osaka financial institutions pursue autonomous governance modules for algorithmic audit trail generation under evolving regulatory frameworks.
Global Autonomous Data Platform Market Competitive Landscape
Premium-margin players sit above commodity-margin players across deployment flexibility and governance depth, with integrated database heritage commanding enterprise contract pricing power. The vendor base stratifies between hyperscale cloud providers with captive infrastructure and independent platforms competing through architectural differentiation. Three archetypes dominate: legacy database incumbents with deep on-premise footprints, cloud-native specialists with elastic consumption models, and vertical integration plays embedding MLOps automation. M&A activity concentrates on governance module acquisitions and regional cloud partnerships.
Within the integrated database tier, Oracle Corporation and International Business Machines Corporation occupy positions anchored by enterprise legacy infrastructure relationships. Snowflake Inc. and Databricks, Inc. exemplify the cloud-native archetype competing through workload elasticity and consumption-based pricing alignment. Amazon Web Services, Microsoft Corporation, and Google LLC represent hyperscale infrastructure plays with autonomous data services layered atop compute and storage dominance.
| Leading Market Players |
|---|
| Oracle Corporation |
| Amazon Web Services |
| International Business Machines Corporation |
| Microsoft Corporation |
| Teradata Corporation |
| Snowflake Inc. |
| Google LLC |
| Cloudera, Inc. |
| Databricks, Inc. |
| Others |
Supply & Pricing Matrix
Cloud-native software vendors backed by venture capital concentration in Silicon Valley and Manhattan are compressing procurement timelines while demanding consumption-aligned pricing models that tether vendor revenue to actual workload throughput rather than provisioned capacity commitments.
Pricing Analysis
Consumption-based pricing tied to query volume and data processed dominates procurement negotiations among cloud-native buyers in New York and London financial corridors. Three-tier pricing structure across premium, standard, and economy levels separates governance-heavy enterprise configurations from lightweight SaaS integrations and developer-tier sandbox environments. Cost compression in the economy tier is intensifying because hyperscaler infrastructure bundles commoditize baseline storage and compute. Mid-market enterprises in Canadian professional services and Spanish regional banking exhibit highest price sensitivity, while Swiss pharmaceutical multinationals and South Korean conglomerates absorb premium tiers for federated governance capabilities.
Supply Chain Analysis
Compute infrastructure rests on hyperscaler concentration within AWS, Azure, and GCP facilities across the United States, Ireland, and Singapore. Specialized silicon for ML acceleration draws from Taiwan Semiconductor Manufacturing and Samsung Foundry operations in South Korea. Proprietary training datasets for autonomous pipeline algorithms feed from enterprise data estates in Frankfurt, Mumbai, and Tokyo. Single-source vulnerability in GPU supply creates procurement bottlenecks for vendors building embedded AI optimization engines. Distribution runs through direct enterprise sales teams for large contracts and cloud marketplace listings for developer adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over governance module IP determines margin capture as regulatory complexity deepens compliance spending across financial services and healthcare verticals.
For Market Incumbents: Deploy governance-native acquisition strategies to consolidate algorithmic audit trail capabilities before EU AI Act enforcement hardens in Frankfurt and Paris. Oracle Corporation and International Business Machines Corporation should anchor enterprise renewals through deep on-premise integration while building cloud-native migration pathways to defend against Snowflake Inc. and Databricks, Inc. elastic consumption models. Certification investment in ISO 27001 and SOC 2 Type II frameworks preserves RFP eligibility among US healthcare systems under HIPAA. For New Entrants and Emerging Players: Enter via India's Account Aggregator ecosystem where RBI data localization norms and UPI transaction volumes outpace incumbent platform deployment velocity. Target mid-market SaaS vendors in São Paulo and Mexico City with pre-configured templates for neural query optimization that eliminate dedicated database administrator headcount. Go-to-market leverage concentrates in managed service partnerships with regional systems integrators lacking autonomous pipeline expertise. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertical integration plays in Germany and Japan where ANSSI security guidelines and METI critical data localization requirements extend sales cycles for pure-cloud vendors. Long-term viability hinges on governance module IP ownership rather than infrastructure resale margins. Acquisition target archetype: MLOps automation specialists with proven deployments in European automotive manufacturing. The signal to watch is enforcement pattern divergence between EU AI Act implementation in France and Germany versus emerging US algorithmic accountability frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Governance Module Acquisition | Algorithmic audit trail capabilities secure RFP eligibility under EU AI Act risk classification frameworks in Frankfurt. |
| Cloud-Native Migration Pathway | Elastic consumption models capture pricing power among data-intensive SaaS buyers in San Francisco and Manhattan corridors. |
| Regional Cloud Partnership | Domestic data center presence satisfies RBI localization norms for Mumbai and Bangalore fintech clusters. |
| Neural Query Optimization Launch | Automated SQL execution rewriting cuts latency for US logistics operators without manual index engineering. |
| Vertical Integration into MLOps | Embedded feature engineering reduces customer engineering headcount and deepens platform switching costs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while structured conversations with platform engineering directors, enterprise data architects, cloud procurement officers, and compliance leads at financial services firms validated demand assumptions. SEC 10-K disclosures from Oracle Corporation, Snowflake Inc., and Databricks, Inc., alongside EU AI Act implementation guidance from European Commission working groups and RBI circulars on data localization, provided segmentation benchmarks. Bottom-up deployment volume estimates triangulated against top-down addressable market calculations from hyperscaler infrastructure spend disclosures.
Reconciliation of vendor-reported bookings, customer implementation timelines, and regulatory compliance spending trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution module functional depth, organizational scale tier, and underlying automation technology. CAGRs derived from logistic diffusion curves fitted to historical cloud migration patterns and adjusted for EU AI Act compliance acceleration effects. Industry-specific inputs encompassed petabyte-scale estate growth rates among SaaS vendors and MLOps talent availability indices by metropolitan cluster.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU AI Act enforcement escalation or hyperscaler pricing warfare. Assumptions reflect current regulatory trajectories and infrastructure cost curves. Geopolitical fragmentation of cross-border data flows and sudden scarcity in GPU supply for ML acceleration warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Equipment Tracking Software Market
Digital Solutions
China Digital Twin Market
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
Digital Marketing Software Market
Digital Solutions
North America Everything As a Service (Xaas) Market
Digital Solutions
Data Broker Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
Real Time Bidding Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Smart Signage Market
Digital Solutions
France Digital Twin Market
Digital Solutions
Global Sharing Economy Market