
 Global Cloud/Mobile Backend AS a Service (Baas) Market | 2026-2036
Global Cloud/Mobile Backend AS a Service (Baas) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud/Mobile Backend AS a Service (Baas) Market Foresight
The boundary between client-side and server-side development is narrowing as serverless architectures and managed backend services absorb traditional infrastructure complexity. Google Firebase leverages real-time synchronization and embedded analytics to anchor mobile-first development workflows. Microsoft Azure competes through deep integration with enterprise identity stacks and hybrid cloud pathways. Amazon Web Services (AWS) Mobile dominates at scale, extending its cloud primitives into purpose-built mobile SDKs that reduce time-to-market for application teams.
Cloud/Mobile Backend as a Service delivers managed infrastructure for authentication, data persistence, push notifications, and serverless compute through API-driven platforms that eliminate self-hosted backend operations. The architecture typically provisions auto-scaling databases, CDN-backed file storage, and event-triggered functions with sub-100ms latency targets for synchronous user requests. Public cloud deployment leads volume due to zero-capital entry and pay-per-use metering, while hybrid cloud configurations capture margin from enterprises with data residency requirements. API management and serverless computing within solution offerings attract the fastest growth as microservices decomposition accelerates.
FDA oversight applies where BaaS supports connected medical devices, while FCC regulations govern wireless data transmission protocols embedded in mobile SDKs. HIPAA constraints shape healthcare adoption, forcing providers toward BaaS vendors with signed business associate agreements and encrypted-at-rest storage. Stakeholders must monitor how NHTSA and FAA rules expand into automotive and drone telemetry backends, as these sectors represent emerging demand pools with stringent operational safety requirements.
Market Dynamics
Serverless function architectures are compressing the traditional backend engineering cycle from weeks to hours, eliminating provisioning overhead and redirecting developer talent toward application logic rather than infrastructure maintenance.
Growth Catalysts
- EU AI Act compliance mandates:Automated data governance pipelines embedded in certified BaaS platforms reduce audit preparation time for AI-enabled mobile applications. Developers in Germany and France increasingly select providers with pre-built GDPR and AI Act alignment.
- Mobile gaming infrastructure offloading:Studios building real-time multiplayer systems consume managed WebSocket and matchmaking services to avoid self-hosted server farms. Latency-sensitive battle royale titles drive consumption spikes in South Korea and the United States.
- Edge function deployment:Sub-50ms compute placement at CDN nodes enables augmented reality overlays and live commerce interactions. Retailers in Japan deploy these capabilities for in-store navigation apps.
Market Restraints
- Hyperscaler concentration risk:Three cloud providers control the underlying infrastructure for over 80 percent of public BaaS deployments, creating single-point-of-failure exposure for multi-tenant platforms.
- Cross-border data transfer friction:China's data localization requirements under MIIT and GB standards fragment global application architectures, forcing redundant backend deployments.
- Serverless cold-start latency:Infrequently invoked functions exhibit 200-500ms initialization delays, disqualifying BaaS for certain financial trading and industrial control use cases.
Strategic Opportunities
- Healthcare IoT telemetry backends:FDA-regulated connected devices require HIPAA-compliant data pipelines with signed business associate agreements. BaaS providers with healthcare certifications capture device manufacturer migrations from self-managed infrastructure.
- India's PLI scheme for cloud services:Domestic data center incentives under the Production Linked Incentive program attract regional BaaS nodes, reducing latency for Southeast Asian application developers.
- WebAssembly edge runtime convergence:Portable bytecode execution across browser and server environments enables unified codebases for progressive web applications. This technology pairing lowers skill barriers for full-stack mobile teams.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Engineering teams lack proficiency in abstracting across AWS, Azure, and Google Cloud primitives, forcing vendor lock-in or brittle abstraction layers.
- ISO 27001 and SOC 2 Type II certification timelines:Six-to-twelve-month audit cycles delay market entry for regional BaaS challengers competing against pre-certified incumbents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud/Mobile Backend AS a Service (Baas) Market |
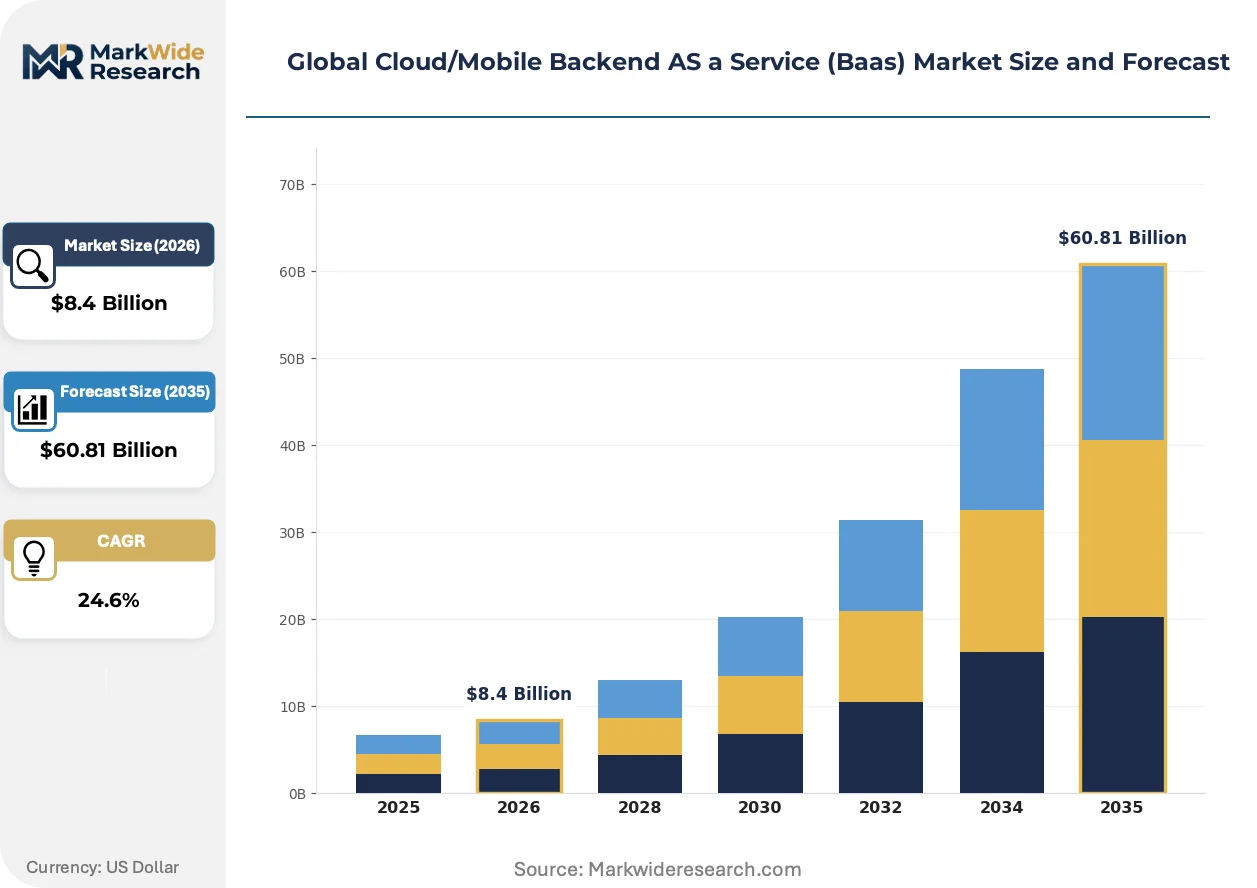
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $60.81 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Offering: API Management, User Authentication, Data Storage, Push Notifications, Serverless Computing Use Case: Gaming Applications, Social Networking, E-Commerce Platforms, IoT Management, Enterprise Mobility End User Industry: Financial Services, Telecommunications, Media & Entertainment, Education Technology, Travel & Hospitality |
| Companies Covered | Amazon Web Services (AWS) Mobile, Microsoft Azure, Google Firebase, IBM Cloud, Oracle Mobile Cloud, Kinvey, Backendless, Rackspace Technology, SAP Mobile Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud/Mobile Backend AS a Service (Baas) Market Shifts & Advancements
Real-time data synchronization protocols are displacing request-response architectures in mobile application development, while regulatory pressure on AI systems reshapes how backend services handle model inference and training data.
GraphQL query layers with persisted queries and automatic persisted query caching are rendering obsolete RESTful endpoint proliferation that previously required manual versioning and documentation maintenance. Fintech startups in Singapore and mobile commerce platforms in Brazil adopt these patterns to accelerate frontend iteration cycles without backend redeployment. The structural compression of API surface areas reduces security audit scope and accelerates third-party integration timelines.
The EU AI Act's risk-based classification system for automated decision-making imposes documentation and human oversight obligations on backend services processing biometric or credit-scoring data. BaaS providers serving European financial institutions must implement model cards, training data provenance tracking, and audit logging by mid-2025. Healthcare applications leveraging diagnostic AI in Germany face additional MDR conformity assessments for software-as-a-medical-device classifications.
Consumption-based pricing with granular per-request metering replaces committed-use contracts for early-stage application teams. Developer tooling vendors in Israel and productivity software startups in Canada now evaluate backend providers on marginal cost scaling rather than upfront platform credits. This behavioral shift pressures incumbent vendors to expose finer-grained billing dimensions and transparent cost estimation tools.
Global Cloud/Mobile Backend AS a Service (Baas) Market Segmentation
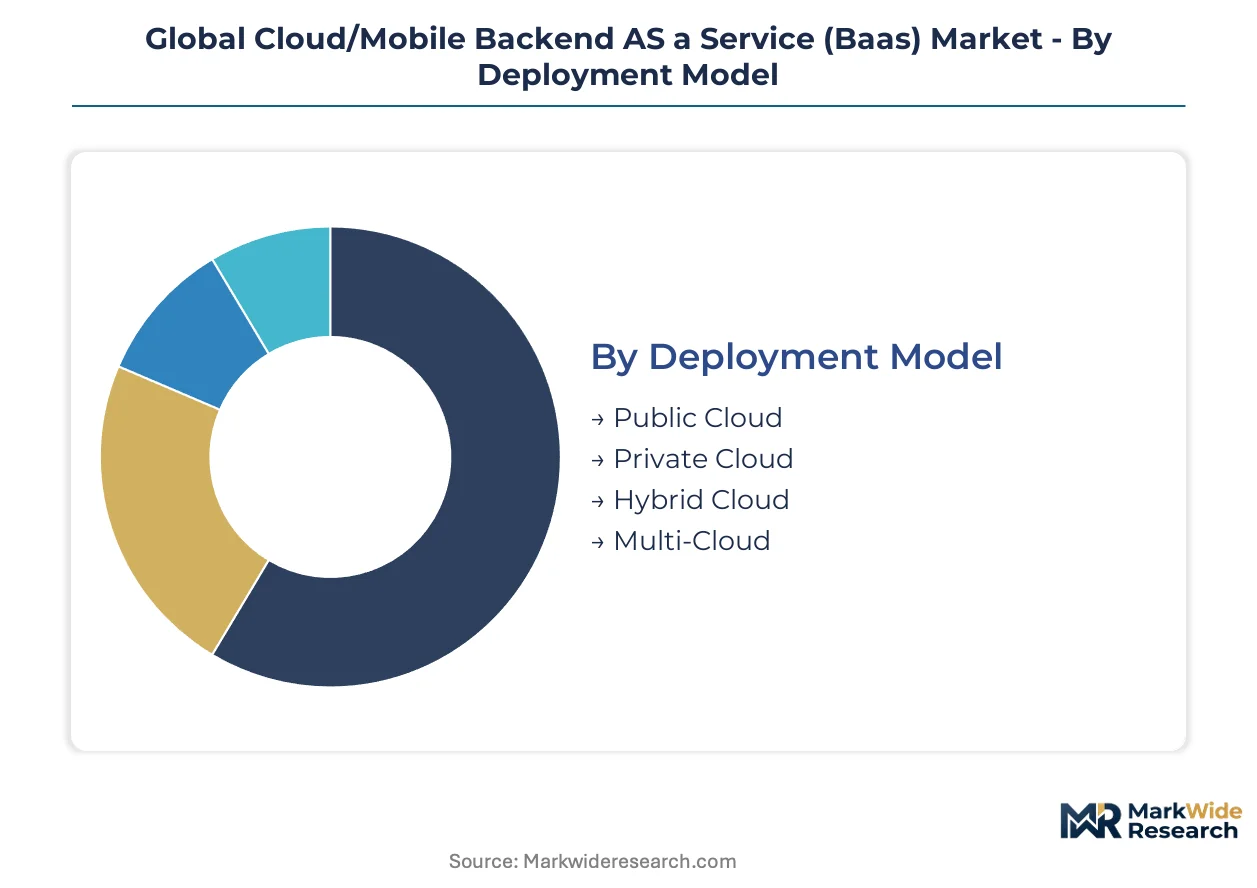
Backend infrastructure purchasing patterns diverge sharply across deployment topologies and industry verticals. Understanding these fault lines reveals where platform engineering investments concentrate and which compliance frameworks shape vendor selection criteria.
Deployment Model:
Cost tier differentiation separates self-service entry points from governed enterprise environments with dedicated resource pools.
- Public Cloud:Shared infrastructure pools deliver metered consumption with zero capital commitment. Startups in Austin and Bangalore default to this tier for pre-revenue application validation.
- Private Cloud:Isolated compute and storage clusters satisfy data residency mandates in regulated sectors. German automotive suppliers operating under GDPR and BSI IT-Grundschutz specifications favor this architecture.
- Hybrid Cloud:Burst capacity bridges on-premises legacy systems with elastic cloud scaling. Japanese manufacturers with METI-guided digital transformation roadmaps deploy this pattern for incremental migration.
- Multi-Cloud:Abstraction layers distribute workloads across provider boundaries to reduce concentration risk. Fintech operators in Singapore architect across AWS and Azure to satisfy MAS operational resilience guidelines.
Public Cloud commands the established base. The steepest expansion runs through Hybrid Cloud as enterprises reconcile legacy estate with cloud-native development.
Solution Offering:
Application workflow requirements determine which managed services anchor platform selection decisions versus commoditized add-ons.
- API Management:Gateway policies, rate limiting, and developer portal provisioning standardize service exposure. Brazilian neobanks leverage these capabilities to expose open banking interfaces under Central Bank of Brazil regulations.
- User Authentication:Identity federation, multi-factor enforcement, and session management integrate with enterprise directories. Healthcare providers in Canada selecting Health Canada-aligned vendors prioritize HIPAA-equivalent identity controls.
- Data Storage:Document, key-value, and time-series persistence with automatic replication and point-in-time recovery.
- Push Notifications:Cross-platform messaging with delivery tracking and audience segmentation for re-engagement campaigns.
- Serverless Computing:Event-triggered execution with automatic scaling and per-invocation billing eliminates capacity planning.
Data Storage commands the established base. API Management gains share fastest as microservices decomposition accelerates interface proliferation.
Use Case:
Volume concentration tracks where real-time synchronization and elastic scaling deliver decisive competitive advantage over self-managed alternatives.
- Gaming Applications:Managed WebSocket infrastructure and matchmaking services support synchronous multiplayer sessions. South Korean battle royale studios consume these services to avoid自建 server farms for transient player peaks.
- Social Networking:Feed aggregation, graph queries, and notification fan-out demand sub-100ms latency at unpredictable scale.
- E-Commerce Platforms:Inventory synchronization, cart persistence, and checkout orchestration across mobile and web channels.
- IoT Management:Device provisioning, telemetry ingestion, and command dispatch for connected hardware fleets.
- Enterprise Mobility:Secure containerization, offline synchronization, and policy enforcement for workforce applications.
Gaming Applications command the established base. IoT Management shows the steepest climb as industrial OEMs outsource telemetry pipeline engineering.
End User Industry:
Customer type maturity determines whether procurement prioritizes consumption economics or pre-certified compliance bundles.
- Financial Services:PCI-DSS scope reduction, fraud detection integration, and audit logging for transaction backends. Indian NBFCs migrating to cloud under RBI data localization guidelines favor certified BaaS stacks.
- Telecommunications:Subscriber identity management, billing mediation, and network function exposure through standardized APIs.
- Media & Entertainment:Content personalization, digital rights management, and streaming analytics for audience engagement.
- Education Technology:Learning record stores, assessment delivery, and roster synchronization across institutional boundaries.
- Travel & Hospitality:Reservation systems, loyalty program management, and real-time inventory distribution.
Financial Services commands the established base. Education Technology expands most quickly as institutional procurement shifts from perpetual licenses to consumption models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based hyperscalers export managed backend infrastructure to application developers across Germany, India, and South Korea, creating transnational dependency chains for authentication and data persistence services.
United States
Mobile gaming studios in Austin and San Francisco drive consumption of managed WebSocket infrastructure for real-time multiplayer sessions. FCC regulations govern wireless data transmission protocols embedded in mobile SDKs distributed to North American carriers. Seattle and Northern Virginia host the densest concentrations of hyperscaler cloud regions, where AWS and Microsoft operate multiple availability zones serving latency-sensitive enterprise workloads.
Germany
Automotive suppliers building connected vehicle telemetry systems require GDPR-compliant data pipelines with BSI IT-Grundschutz certification. The EU AI Act mandates automated documentation for backend services processing biometric data in AI-enabled applications. Munich and Stuttgart industrial clusters deploy hybrid cloud configurations to satisfy data residency requirements while connecting to legacy manufacturing execution systems.
India
Non-banking financial companies migrating under RBI data localization guidelines consume certified BaaS stacks for transaction backends. The Production Linked Incentive scheme for cloud services attracts regional BaaS nodes to domestic data centers in Mumbai and Hyderabad. Bangalore's startup density generates concentrated demand for serverless compute with per-invocation billing models.
South Korea
Battle royale game studios consume managed matchmaking services to handle transient player peaks without自建 server farms. MFDS oversight applies where BaaS supports connected medical devices with diagnostic AI components. Seoul's Pangyo Techno Valley anchors the highest density of mobile gaming infrastructure offloading in the Asia-Pacific region.
Japan
Retailers deploying augmented reality overlays for in-store navigation require sub-50ms edge function placement at CDN nodes. METI-guided digital transformation roadmaps push manufacturers toward hybrid cloud burst capacity bridging on-premises legacy systems. Tokyo and Osaka metropolitan areas concentrate demand for real-time inventory synchronization across mobile commerce channels.
Global Cloud/Mobile Backend AS a Service (Baas) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Hyperscale cloud providers anchor the premium tier with integrated identity stacks and serverless primitives. Mid-tier challengers differentiate through vertical-specific compliance certifications and regional data residency options. The base tier comprises open-source and self-hosted alternatives competing on cost transparency. Consolidation pressure intensifies as incumbents acquire niche authentication and analytics vendors to broaden platform surface areas.
Within the hyperscale tier, Amazon Web Services (AWS) Mobile, Microsoft Azure, and Google Firebase occupy positions defined by cloud-native ecosystem lock-in. AWS exemplifies the infrastructure-first archetype, extending compute and storage primitives into mobile-specific SDKs. Microsoft represents the enterprise integration specialist, embedding BaaS capabilities within broader productivity and identity suites. Google anchors the consumer-data-native position, leveraging search and advertising infrastructure for real-time synchronization and embedded analytics. These three entities collectively provision the underlying infrastructure for the majority of public BaaS deployments globally.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) Mobile |
| Microsoft Azure |
| Google Firebase |
| IBM Cloud |
| Oracle Mobile Cloud |
| Kinvey |
| Backendless |
| Rackspace Technology |
| SAP Mobile Platform |
| Others |
Supply & Pricing Matrix
Seattle's hyperscaler cloud region concentration anchors global BaaS infrastructure capacity, with AWS and Microsoft operating multiple availability zones that translate compute scarcity into tiered pricing power across downstream markets. Capacity tightness in Northern Virginia and Singapore nodes feeds through to committed-use contract premiums, while spot pricing for serverless invocations fluctuates with regional demand spikes from gaming studios and fintech operators.
Pricing Analysis
Cost-plus contracts with compute indexation to hyperscaler capex cycles dominate enterprise procurement, with pricing stratifying across premium dedicated resource pools, standard multi-tenant tiers, and economy serverless pay-per-invocation levels. Price differentiation rests on ISO 27001 certification tier and data residency zone selection, with German automotive suppliers paying premiums for BSI IT-Grundschutz alignment. Cost compression in the standard tier is intensifying because Indian NBFCs migrating under RBI guidelines are consolidating purchasing volume. Early-stage startups in Bangalore exhibit highest price sensitivity, while FDA-regulated medical device manufacturers accept premium tiers for signed business associate agreements.
Supply Chain Analysis
Upstream silicon feedstock from Taiwan, South Korea, and the United States feeds into hyperscaler server farms that constitute the foundational BaaS infrastructure layer. Compute hardware, network transit, and renewable energy certificates represent critical input dependencies. Single-source vulnerability concentrates around three cloud providers controlling underlying infrastructure for over 80 percent of public deployments. Distribution runs through direct hyperscaler marketplaces and regional systems integrators with vertical specialization in healthcare or gaming.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hyperscaler concentration as mobile gaming studios and fintech operators consolidate procurement through multi-year committed-use agreements, fragmenting negotiating leverage for regional BaaS challengers.
For Market Incumbents: Harden compliance moats by accelerating EU AI Act certification timelines and embedding automated data governance pipelines that reduce audit preparation for German and French developers. Defend against open-source Firebase alternatives by deepening healthcare certifications with HIPAA business associate agreements. Prioritize capacity expansion in Mumbai and Hyderabad under India's PLI scheme to capture RBI-mandated data localization demand. For New Entrants and Emerging Players: Establish a beachhead in education technology by targeting institutional procurement shifts from perpetual licenses to consumption models, with Health Canada-aligned identity controls for Canadian healthcare providers as a secondary wedge. Penetrate Brazil's mobile commerce sector through Central Bank of Brazil open banking compliance bundles. Lead with WebAssembly edge runtime convergence to lower skill barriers for full-stack mobile teams. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical-specific compliance specialists over horizontal infrastructure plays. Long-term viability hinges on regulatory certification depth rather than feature velocity. Target acquisition archetypes include healthcare IoT telemetry backend providers with FDA submission track records and ISO 27001 pre-certification. Watch for inflection signals in NHTSA automotive telemetry backend rulemaking and FAA drone data pipeline requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Healthcare Certification Investment | FDA business associate agreements capture medical device manufacturer migrations from self-hosted infrastructure. |
| Edge Function Expansion | Sub-50ms CDN node deployment enables Japanese retailer augmented reality commerce applications. |
| Multi-Cloud Abstraction Layer | Cross-AWS-Azure orchestration satisfies Singapore MAS operational resilience guidelines for fintech operators. |
| Regional Data Center Buildout | Mumbai and Hyderabad nodes under PLI scheme reduce latency for Southeast Asian application developers. |
| WebAssembly Runtime Integration | Portable bytecode execution unifies progressive web application codebases across browser and server environments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs at mobile gaming studios, platform engineers at hyperscaler cloud providers, IT procurement officers at German automotive suppliers, and integration specialists at Indian NBFCs. Secondary validation drew from SEC hyperscaler capex disclosures, App Annie mobile SDK adoption data, FDA 510(k) submission databases, and RBI circulars on data localization. Bottom-up triangulation across deployment model, solution offering, and end-user industry segments was cross-checked against top-down market sizing.
Calibration against historical hyperscaler revenue reporting and mobile application download velocity informed the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment topology, compliance certification tier, organization size by developer headcount, and regional regulatory cluster. CAGRs were derived from slope analysis of adoption curve inflection points, with inputs from EU AI Act implementation timelines and MFDS connected device oversight expansion.
Sensitivities concentrate around EU AI Act enforcement severity, NHTSA automotive telemetry rulemaking, and hyperscaler concentration risk crystallization. Cross-checking against hyperscaler quarterly infrastructure spend disclosures and mobile gaming studio server cost benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Private Cloud Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
Cloud Identity Management Market
Cloud Computing
Europe AI Cloud Computing in Automotive Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
Virtual Private Cloud (VPC) Market
Cloud Computing
United States Cloud Computing Market
Cloud Computing
Cloud Computing Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
Cloud Computing Services Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Israel Cloud Computing Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Community Cloud Market