
 Hyperscale Cloud Market | 2026-2036
Hyperscale Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperscale Cloud Market Analytics
Capital-intensity divergence between hyperscale incumbents and challenger platforms is reorganizing competitive dynamics across infrastructure provisioning. Amazon Web Services leverages its server fleet scale and custom silicon pipeline to sustain pricing power in core compute. Microsoft Azure anchors enterprise hybrid workloads through deep integration with productivity software stacks. Google Cloud Platform competes on AI-optimized tensor processing and open-source Kubernetes stewardship.
Hyperscale cloud denotes distributed computing infrastructure operated by providers with massive data center footprints, typically exceeding five hundred thousand servers, delivering elastic compute, storage, and networking over the internet. These facilities deploy custom accelerators, liquid cooling systems, and software-defined networking to achieve power usage effectiveness ratios below 1.2. Public cloud deployment captures the dominant revenue share as enterprises exit owned facilities, while hybrid cloud configurations are expanding fastest among regulated industries requiring data sovereignty. Infrastructure-as-a-Service retains the largest margin pool due to long-term reserved instance commitments and egress fee structures.
FCC spectrum allocations shape edge computing deployment density across the United States, while the EU AI Act imposes conformity assessment burdens on machine learning services offered to European public sector buyers. China's MIIT enforces data localization through GB standards for cross-border transfer, fragmenting architecture decisions for multinational tenants. Stakeholders must monitor divergent sovereignty regimes when selecting primary and failover regions for critical workloads.
Market Dynamics
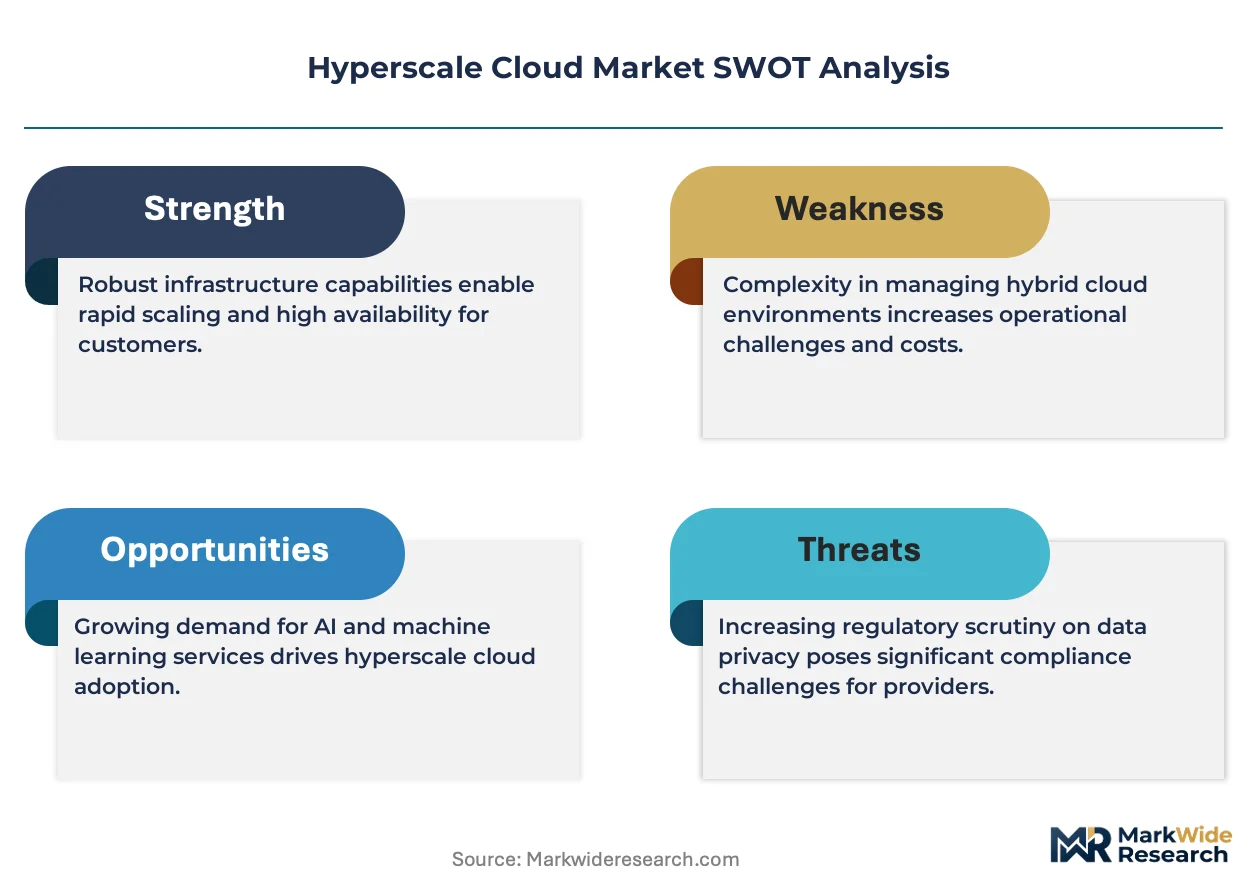
Regulatory fragmentation around data sovereignty and algorithmic transparency is forcing hyperscale providers to architect region-specific infrastructure stacks rather than operate unified global fabrics.
Growth Catalysts
- EU AI Act conformity assessments:European public sector procurement now mandates algorithmic transparency documentation, creating specialized demand for compliant cloud instances.
- Healthcare cloud-native migration:Providers are accelerating decommissioning of on-premise data centers in favor of elastic compute for electronic health record systems.
- Liquid cooling deployment:Advanced thermal management technologies enable higher rack densities and sustain performance for AI training clusters.
Market Restraints
- Custom silicon supply concentration:Accelerator fabrication depends on a limited foundry base in East Asia, creating procurement bottlenecks for tensor processing units.
- Egress fee structures:Data transfer pricing models lock enterprises into single-provider architectures and suppress multi-cloud adoption.
- Power availability constraints:Grid interconnection queues in Northern Virginia and Frankfurt delay data center commissioning by 24-36 months.
Strategic Opportunities
- Sovereign cloud demand in France:Gaia-X compliance requirements and ANSSI certification create protected market segments for EU-controlled infrastructure.
- Edge-5G convergence:FCC mid-band spectrum allocations enable ultra-low latency workloads for autonomous systems and industrial robotics.
- Reserved instance secondary markets:Enterprises are developing internal exchanges to monetize underutilized long-term compute commitments.
Industry Challenges
- Site selection and permitting velocity:Local zoning disputes and environmental review processes extend facility construction timelines unpredictably.
- Legacy workload refactoring:Mainframe-dependent financial institutions struggle to decompose monolithic applications into containerized microservices architectures.
- Cross-border data governance:Conflicting localization mandates between China's MIIT, EU GDPR, and US CLOUD Act create architectural compliance conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperscale Cloud Market |
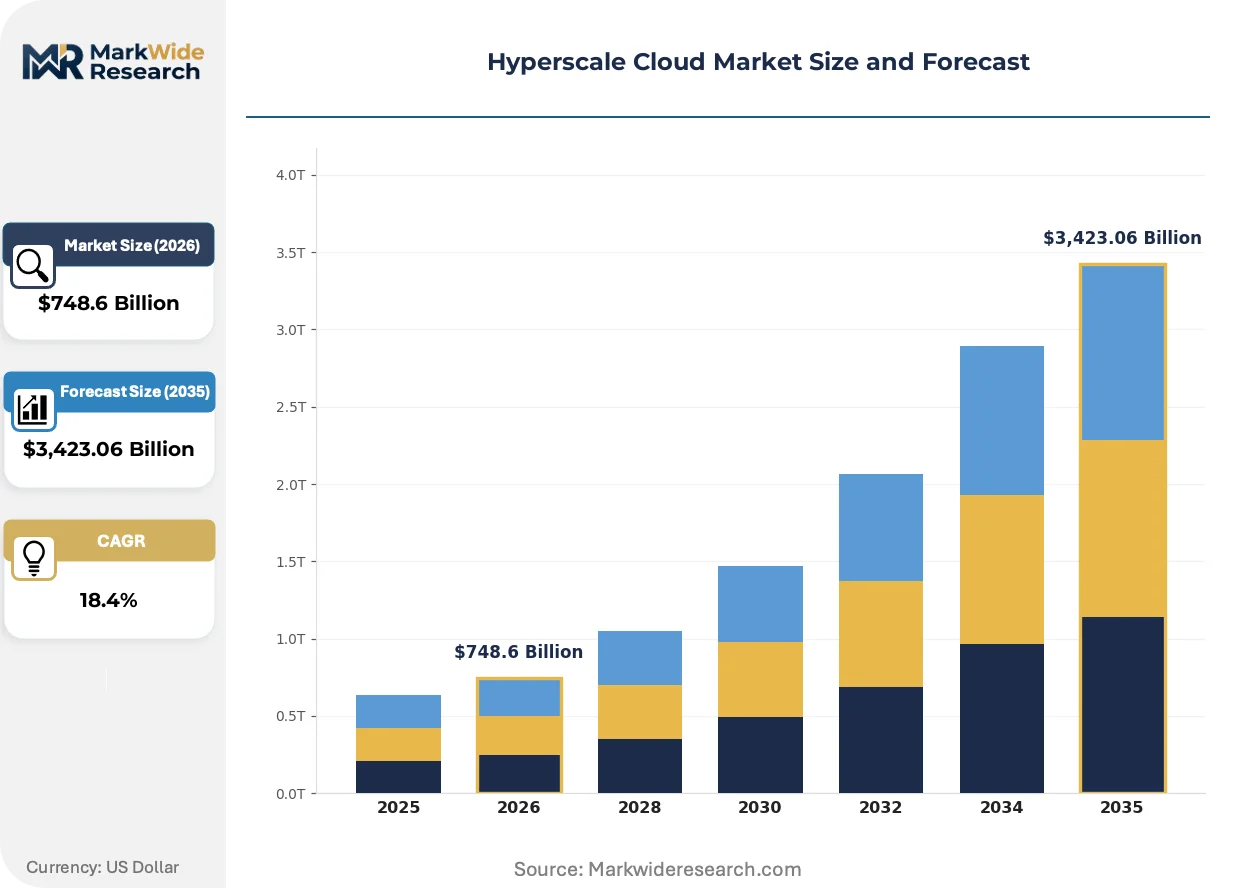
| Market Size in 2026 | $748.6 Billion |
| Market Size in 2035 | $3,423.06 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, DaaS End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Technology: Virtualization, Containers, Microservices, Networking |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud Platform, Alibaba Cloud, Oracle Cloud Infrastructure, IBM Cloud, Tencent Cloud, Apple, Salesforce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperscale Cloud Market Evolving Landscape
Workload placement logic is fragmenting across sovereignty, latency, and carbon-intensity dimensions simultaneously. Providers must now optimize across three independent optimization curves rather than cost-performance alone.
Custom accelerator architectures are bifurcating the compute tier. AWS Trainium and Google TPU v5e serve distinct training versus inference optimization paths. Financial services firms adopt inference-optimized instances for real-time fraud detection while media companies reserve training clusters for generative model fine-tuning. The silicon layer is bifurcating into two non-interoperable supply chains with separate software ecosystems.
EU AI Act risk-classification requirements reshape service catalog design. High-risk AI system providers must maintain conformity assessment documentation and human oversight protocols. Healthcare and public sector buyers in Germany, France, and Netherlands now require audit trails for automated decision systems. Providers are responding with isolated compliance environments and certification pre-validation workflows.
Enterprise buyers are unbundling professional services from infrastructure contracts. Procurement teams negotiate compute and storage separately from migration and managed operations. This disintermediation pressures traditional systems integrators and creates direct contracting relationships between cloud vendors and internal platform engineering teams. The pattern is most pronounced among Fortune 500 manufacturers in the US Midwest consolidating vendor relationships.
Hyperscale Cloud Market Segmentation
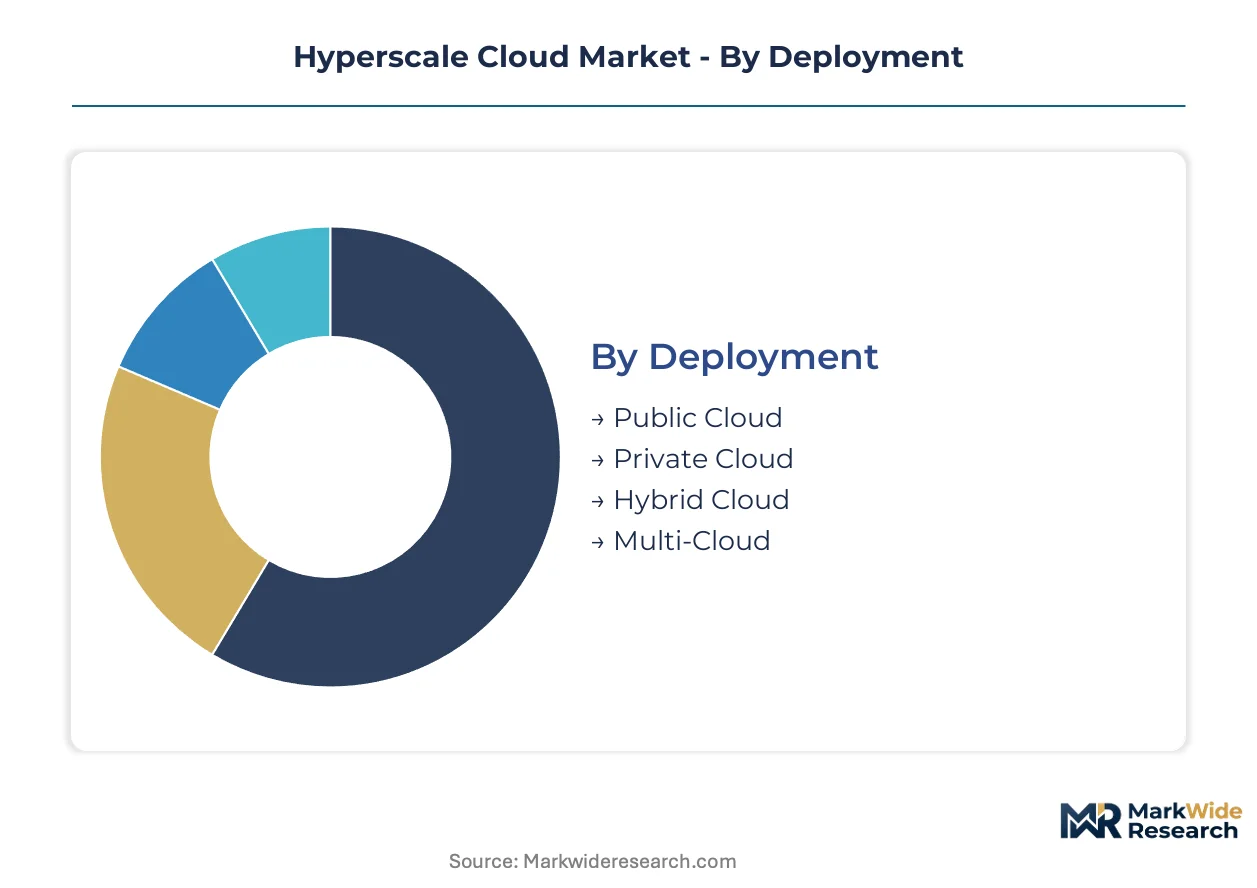
Hyperscale cloud procurement patterns diverge sharply across deployment models and service tiers, with margin concentration shifting toward infrastructure primitives and sovereign configurations. Understanding these fault lines reveals where pricing power accrues and where commodification pressures mount.
Deployment:
Margin pools concentrate in configurations that reconcile elastic scalability with data residency mandates, particularly where egress fees and reserved instance structures lock in long-term commitments.
- Public Cloud:Shared infrastructure pools deliver compute, storage, and networking over the internet through multi-tenant architectures. Financial services firms in New York and London drive demand for burst capacity during quarterly reporting cycles, constrained by SEC and FCA audit trail requirements.
- Hybrid Cloud:Orchestrated workloads span on-premise infrastructure and public cloud fabrics through unified management planes. German automotive manufacturers anchor demand for factory-floor latency compliance combined with cloud-based supply chain analytics, navigating GDPR data localization rules.
- Private Cloud:Single-tenant dedicated infrastructure serves organizations with stringent isolation requirements.
- Multi-Cloud:Distributed architectures across competing provider platforms reduce vendor lock-in exposure.
The dominant share belongs to Public Cloud, while Hybrid Cloud is closing the gap fastest.
Service Type:
Customer contracting behavior splits between raw infrastructure procurement and higher-level abstraction layers, with procurement teams increasingly unbundling professional services from core compute agreements.
- IaaS:Fundamental compute, storage, and networking resources provisioned as metered utilities with API-driven orchestration. Healthcare providers in the United States accelerate migration of electronic health record systems, constrained by HIPAA Business Associate Agreement complexity and state-level Medicaid data residency rules.
- PaaS:Application development and deployment environments abstract underlying infrastructure management through container orchestration and serverless functions. French public sector buyers require EU AI Act conformity documentation for algorithmic services, creating compliance-prevalidated demand clusters.
- SaaS:Fully managed application software delivered through browser interfaces or mobile endpoints.
- DaaS:Desktop virtualization streams complete workstation environments to thin clients and mobile devices.
IaaS commands the largest revenue base, though PaaS is expanding most quickly as enterprises refactor legacy monoliths.
End User:
Procurement sophistication and contract scale vary dramatically across organizational size and sector, with public sector buyers imposing distinct compliance burdens on service catalog design.
- Large Enterprises:Fortune 500 manufacturers consolidate vendor relationships through direct platform engineering contracts, bypassing traditional systems integrators. Midwest industrial firms negotiate compute and storage separately from migration services, compressing margin capture for bundled professional services.
- Government Agencies:European public sector procurement mandates algorithmic transparency documentation under EU AI Act risk-classification frameworks. German, French, and Dutch healthcare authorities require isolated compliance environments with audit trails for automated decision systems.
- SMEs:Mid-market organizations consume standardized service tiers with limited customization.
- Educational Institutions:Universities and research centers leverage academic pricing programs for compute-intensive workloads.
Large Enterprises retain the dominant spend share, while Government Agencies are gaining procurement velocity fastest through sovereign cloud mandates.
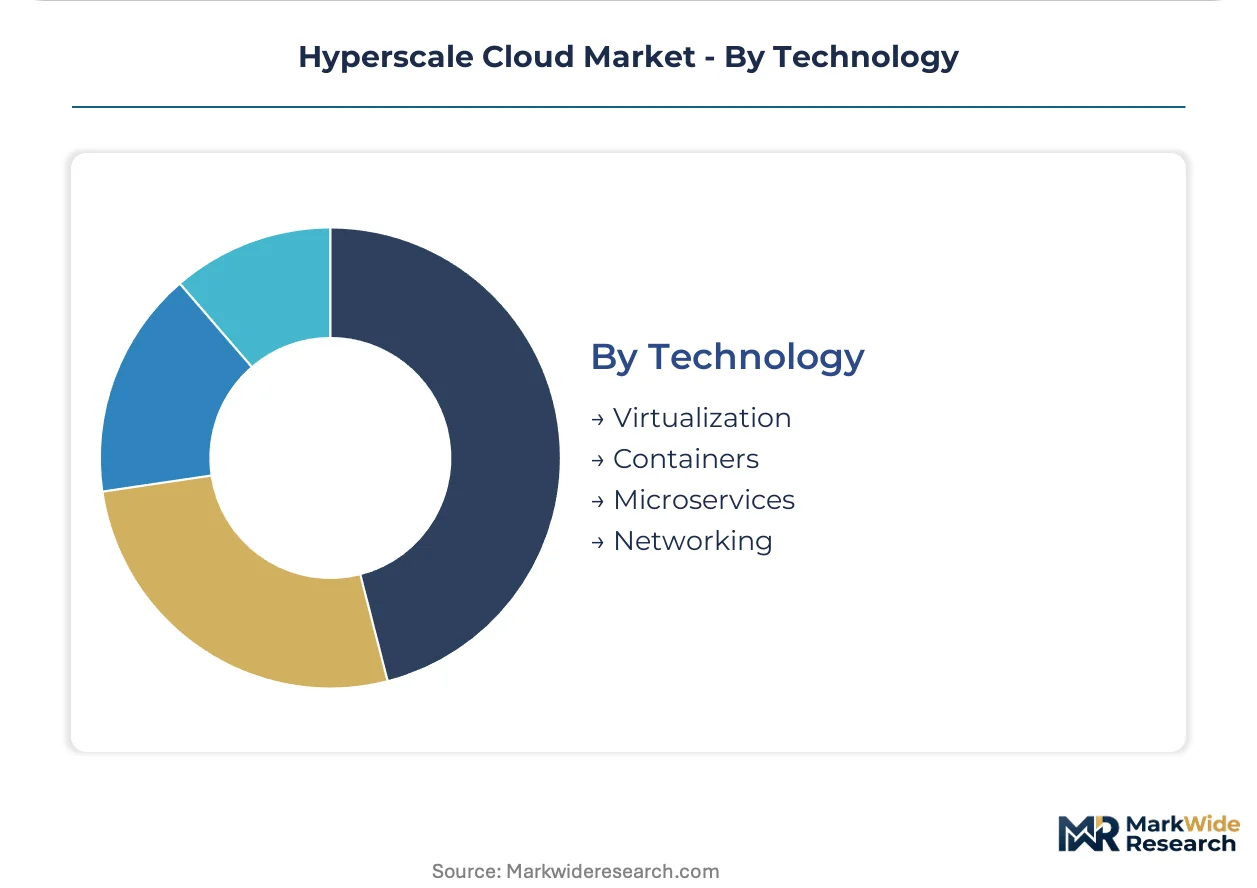
Technology:
Underlying infrastructure primitives determine performance characteristics and operational complexity, with container orchestration displacing traditional virtualization for cloud-native workloads.
- Containers:Lightweight operating system virtualization packages applications with dependencies for consistent deployment across environments. Media companies reserve training clusters for generative model fine-tuning on Kubernetes-orchestrated infrastructure, leveraging Google Cloud Platform's open-source stewardship.
- Microservices:Decomposed application architectures enable independent scaling and deployment of functional components. Financial institutions struggle to refactor mainframe-dependent core banking systems into containerized services, creating demand for hybrid integration platforms.
- Virtualization:Hypervisor-based abstraction of physical server resources into logical compute instances.
- Networking:Software-defined connectivity fabrics manage traffic across distributed infrastructure footprints.
Virtualization still underpins the majority of deployed workloads, though Containers are climbing the fastest as enterprises exit legacy data centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Germany exhibit the lowest price elasticity, absorbing sovereign cloud premiums for Gaia-X compliance, while mid-market adopters in India negotiate aggressively on egress fees and reserved instance discounts.
United States
Northern Virginia and Dallas-Fort Worth anchor the world's densest hyperscale cluster concentration, with over 4.5 gigawatts of commissioned capacity. FCC mid-band spectrum allocations accelerate edge-5G convergence for autonomous logistics. AWS, Microsoft, and Google operate contiguous campus developments across Loudoun County, where interconnection queues now stretch 36 months.
Germany
Automotive manufacturers in Baden-Württemberg drive hybrid cloud demand for factory-floor latency compliance. The EU AI Act imposes conformity assessment burdens on machine learning services sold to federal agencies. Frankfurt's data center market faces power availability constraints, with grid interconnection delays pushing new supply into 2027-2028.
China
MIIT enforces data localization through GB standards, fragmenting architecture decisions for multinational tenants. Alibaba Cloud and Tencent Cloud dominate domestic procurement for state-owned enterprises. The Yangtze River Delta concentration—Shanghai, Hangzhou, Suzhou—generates 40% of national cloud revenue despite export control friction on advanced accelerators.
France
ANSSI certification and Gaia-X compliance requirements create protected market segments for EU-controlled infrastructure. Healthcare authorities in Île-de-France mandate isolated compliance environments with audit trails for automated decision systems. Thales and Orange Business Services capture sovereign cloud premiums from defense and public sector buyers.
India
Digital Public Infrastructure expansion and UPI transaction volumes drive elastic compute demand from fintech clusters in Mumbai and Bangalore. MeitY's data localization guidelines pressure multinational providers to establish in-country regions. Chennai and Hyderabad emerge as secondary hubs, with Telangana offering power subsidies for hyperlocal edge deployments.
Hyperscale Cloud Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the hyperscale cloud market. Amazon Web Services, Microsoft Azure, and Google Cloud Platform command the infrastructure layer through custom silicon pipelines and proprietary fiber networks. Three archetypes define competitive positioning: full-stack incumbents with productivity software integration, AI-optimized challengers with tensor processing specialization, and sovereign-cloud specialists with government security clearances. Capacity expansion and strategic partnerships dominate competitive moves, with providers securing renewable power purchase agreements and landing submarine cable consortium positions.
Within the full-stack incumbent tier, Amazon Web Services exemplifies server fleet scale and pricing power in core compute, while Microsoft Azure anchors enterprise hybrid workloads through deep Office 365 integration. Google Cloud Platform occupies a position on AI-optimized infrastructure, competing through open-source Kubernetes stewardship and tensor processing differentiation. These three entities represent the consolidated apex of global infrastructure provisioning.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud Platform |
| Alibaba Cloud |
| Oracle Cloud Infrastructure |
| IBM Cloud |
| Tencent Cloud |
| Apple |
| Salesforce |
| Others |
Value Network & Pricing Analysis
Server fleet scale above five hundred thousand units enables hyperscale providers to sustain price floors through reserved instance structures and egress fee lock-in. Liquid cooling deployment costs and custom silicon fabrication cycles concentrate supply leverage among incumbents with captive infrastructure pipelines.
Pricing Analysis
Reserved instance secondary markets and multi-year enterprise commitments generate lifetime value exceeding raw compute margins. Pricing stratifies across dedicated sovereign environments, standard multi-tenant pools, and spot-interruptible tiers, with EU AI Act compliance premiums widening spreads between certified and uncertified workloads. Cost compression in standard compute pools is intensifying because challenger platforms compete on egress fee discounts. Mid-market adopters in India negotiate most aggressively on data transfer pricing, while German automotive manufacturers absorb sovereign cloud premiums for Gaia-X alignment.
Supply Chain Analysis
TSMC fabrication capacity in Taiwan and Samsung foundry output in South Korea anchor accelerator production for tensor processing units. Supply chains draw from cobalt refining in the Democratic Republic of Congo, rare earth processing in China, and advanced substrate manufacturing in Japan. Single-source vulnerability concentrates in East Asian foundry capacity, with export control friction fragmenting access to leading-edge nodes. Distribution runs through submarine cable consortium positions and terrestrial fiber backhaul into regional data center campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services and professional services layers are expanding faster than raw infrastructure provisioning, creating service-attach opportunities for providers who unbundle migration and operations from core compute contracts.
For Market Incumbents: Consolidate pricing power through deeper reserved instance lock-in and egress fee structures that suppress multi-cloud adoption. Expand liquid cooling deployment in Northern Virginia and Frankfurt to sustain rack density leadership against power availability constraints. Defend against sovereign cloud specialists by accelerating Gaia-X and ANSSI certification timelines.
For New Entrants and Emerging Players: Anchor in edge-5G convergence opportunities where FCC mid-band spectrum allocations enable ultra-low latency workloads outside incumbent campus footprints. Target industrial robotics and autonomous logistics segments in Dallas-Fort Worth and Chennai where latency requirements outstrip centralized cloud economics. Pursue direct contracting relationships with Fortune 500 platform engineering teams bypassing traditional systems integrators.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sovereign cloud specialists with government security clearances and EU AI Act pre-validation capabilities. Long-term viability hinges on renewable power purchase agreement portfolios and submarine cable landing rights rather than pure compute scale. Monitor grid interconnection queue clearance in Frankfurt and Northern Virginia as inflection indicators for capacity expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | ANSSI and Gaia-X compliance unlocks protected French public sector procurement segments. |
| Custom Silicon Pipeline | AWS Trainium and Google TPU v5e bifurcate training versus inference optimization paths. |
| Edge-5G Convergence | FCC mid-band spectrum enables autonomous logistics workloads outside centralized data centers. |
| Liquid Cooling Deployment | Advanced thermal management sustains AI training cluster performance at sub-1.2 PUE ratios. |
| Reserved Instance Marketplace | Secondary markets for underutilized compute commitments unlock enterprise cost optimization. |
Research Methodology
The analysis maps IaaS, PaaS, and sovereign cloud configurations, each validated through conversations with cloud procurement officers, platform engineering directors, and data center development leads. Primary fieldwork with hyperscaler solution architects and enterprise IT executives combined with secondary validation against SEC capex disclosures, hyperscaler earnings reports, and FCC spectrum allocation records. Bottom-up service tier sizing and top-down infrastructure capacity estimates were triangulated for consistency.
Output consistency was checked against external benchmarks including hyperscaler reported revenue segments and third-party data center power consumption estimates. The projection horizon spans deployment models, service types, end-user scale tiers, and regional regulatory clusters. CAGRs were derived from elasticity-adjusted demand curves and capacity commissioning timelines. Forecast inputs include grid interconnection queue data and EU AI Act implementation schedules.
Material uncertainties — foundry capacity allocation shifts, sovereign data localization mandate revisions, and power availability delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about enterprise migration velocity and reserved instance renewal rates. Practitioners should keep alternative scenarios live as EU AI Act enforcement patterns and FCC spectrum auction outcomes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Distributed Cloud Market
Cloud Computing
GPU Virtualization Market
Cloud Computing
North America Cloud Computing Market
Cloud Computing
Government Cloud Market
Cloud Computing
Cloud Database Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
Public Cloud Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
North America Healthcare Cloud Computing Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Global Marketing Cloud Platform Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
South Korea Cloud Computing Market