
 High-Performance Computing (HPC) As a Service Market | 2026-2036
High-Performance Computing (HPC) As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
High-Performance Computing (HPC) As a Service Market Foresight
Cloud reseller and systems integrator channels are reconfiguring how enterprise buyers access HPC capacity, bypassing traditional direct-sales relationships with hardware vendors. Amazon Web Services leverages its custom Graviton and Trainium silicon to sustain price-performance advantages in large-scale simulation workloads. Microsoft Azure anchors government and defense contracts through its dedicated Azure Government regions with FedRAMP authorization. NVIDIA dominates the GPU-accelerated tier, controlling the essential CUDA software layer that most HPCaaS providers build upon.
High-Performance Computing as a Service delivers on-demand access to clustered compute, storage, and interconnect resources capable of sustained petaflop-scale operations, typically orchestrated through containerized or bare-metal provisioning with low-latency InfiniBand or RDMA over Converged Ethernet networking. Its primary commercial purpose is to eliminate capital expenditure on supercomputing infrastructure while enabling time-elastic execution of simulation, inference, and analytics workloads. The public cloud deployment model leads in revenue scale due to pay-as-you-go elasticity, though hybrid cloud architectures capture the fastest expansion as regulated enterprises seek data sovereignty with burst capacity. Among service types, infrastructure as a service occupies the dominant margin pool because compute and networking raw capacity commands premium pricing over abstracted platform layers.
The US Federal Risk and Authorization Management Program and the EU AI Act create divergent compliance frameworks that shape where providers build sovereign infrastructure and how customers qualify workloads for sensitive applications. ISO 27001 and SOC 2 Type II certifications function as baseline market-access requirements, with providers lacking these attestations excluded from enterprise procurement shortlists. Stakeholders must monitor how export control expansions on advanced GPUs redirect capacity investments toward alternative architectures and geographic deployment patterns.
Market Dynamics
US export controls on advanced semiconductors are fragmenting GPU supply chains and forcing HPCaaS providers toward alternative accelerators and sovereign infrastructure deployments. This regulatory pressure is hybridizing procurement patterns across automotive, pharmaceutical, and defense end-uses.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for high-stakes AI workloads are steering regulated enterprises toward certified HPCaaS environments with built-in audit trails and data sovereignty guarantees.
- Containerized workload portability:Kubernetes-native orchestration is collapsing migration friction between on-premise clusters and burst cloud capacity, accelerating hybrid adoption among Fortune 500 manufacturers.
- Germany:Fraunhofer institutes and automotive OEMs in Baden-Württemberg and Bavaria are anchoring multi-year HPCaaS procurement contracts that validate sovereign cloud business models.
Market Restraints
- Advanced GPU supply concentration:Foundry capacity constraints in Taiwan and US export licensing delays are extending delivery timelines for training clusters beyond eighteen months.
- Energy cost volatility:Power purchase agreement repricing in Nordic and Singapore data center hubs is compressing provider margins on fixed-rate contracts.
- Substitution by specialized AI clouds:Purpose-built training-as-a-service offerings from hyperscalers are capturing inference workloads that previously ran on general-purpose HPC clusters.
Strategic Opportunities
- India:PLI scheme incentives for semiconductor design and the absence of legacy supercomputing infrastructure create greenfield demand for sovereign HPCaaS among domestic pharmaceutical and fintech developers.
- Convergence of quantum-classical workloads:Hybrid algorithm development is creating demand for orchestration layers that seamlessly schedule across GPU clusters and early quantum processing units.
- Channel innovation through systems integrators:Wipro, TCS, and Accenture are building vertical-specific HPCaaS practices that bundle compliance consulting with capacity provisioning, bypassing direct hyperscaler relationships.
Industry Challenges
- InfiniBand and RDMA engineering talent scarcity:Low-latency network architecture expertise is concentrated among a shrinking pool of specialists from Cray and Mellanox heritage, inflating implementation costs.
- FedRAMP authorization timelines:US federal agency adoption of commercial HPCaaS stalls for twelve to eighteen months during security assessment, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Performance Computing (HPC) As a Service Market |
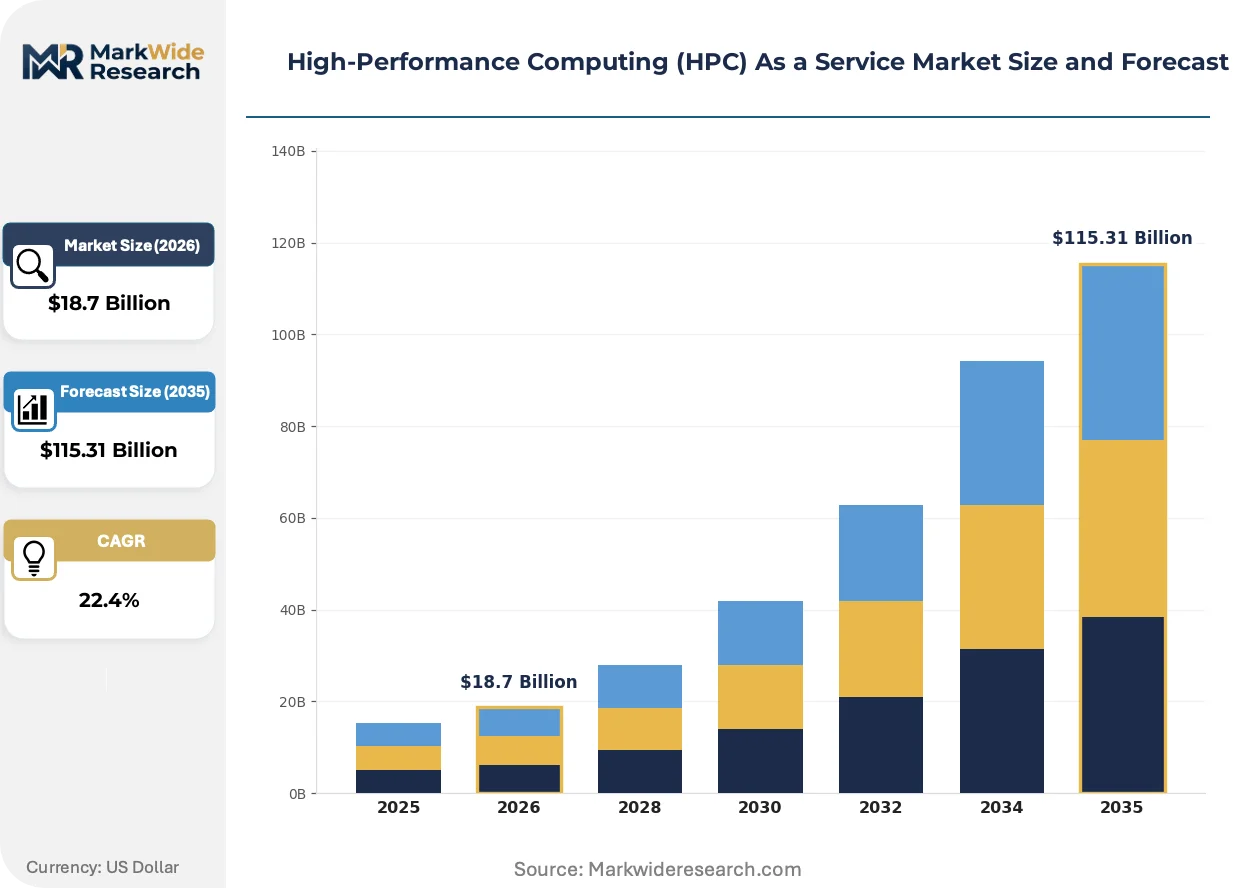
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Infrastructure as a Service (IaaS), Platform as a Service (PaaS), Software as a Service (SaaS), Managed Services End User: Academia, Research Institutions, Enterprises, Government Agencies Application: Data Analytics, Machine Learning, Simulation, Financial Modeling |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM, Hewlett Packard Enterprise, Dell Technologies, NVIDIA, Oracle, Atos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Performance Computing (HPC) As a Service Market Shifts & Advancements
Workload portability requirements and sovereign data mandates are dissolving the boundary between on-premise supercomputing and elastic cloud capacity. Providers are racing to deliver unified control planes that mask infrastructure heterogeneity.
Arm-based server processors are hybridizing the HPCaaS silicon stack. AWS Graviton3E and forthcoming Azure Cobalt instances are capturing cost-sensitive simulation workloads in computational chemistry and finite element analysis. Automotive crash simulation teams at BMW and Continental are validating these platforms against x86 baselines, compressing the price-performance gap that previously locked workloads onto Intel and AMD architectures.
The EU AI Act's risk-tier classification system is forcing providers to rearchitect data residency and model governance capabilities. High-risk AI training workloads now require documentation trails that trace compute provenance through every training step. German automotive suppliers and French pharmaceutical developers are qualifying only those HPCaaS environments with EU-based infrastructure and ISO 27001-certified operational controls, marginalizing providers without continental presence.
Enterprise buying committees are unbundling professional services from raw capacity contracts. Procurement teams at Siemens Healthineers and Roche are negotiating separate statements of work for workload optimization and compliance consulting, then sourcing compute through spot-market mechanisms. This pattern is most pronounced in Switzerland and the Netherlands, where centralized IT procurement functions have matured vendor management capabilities.
High-Performance Computing (HPC) As a Service Market Segmentation
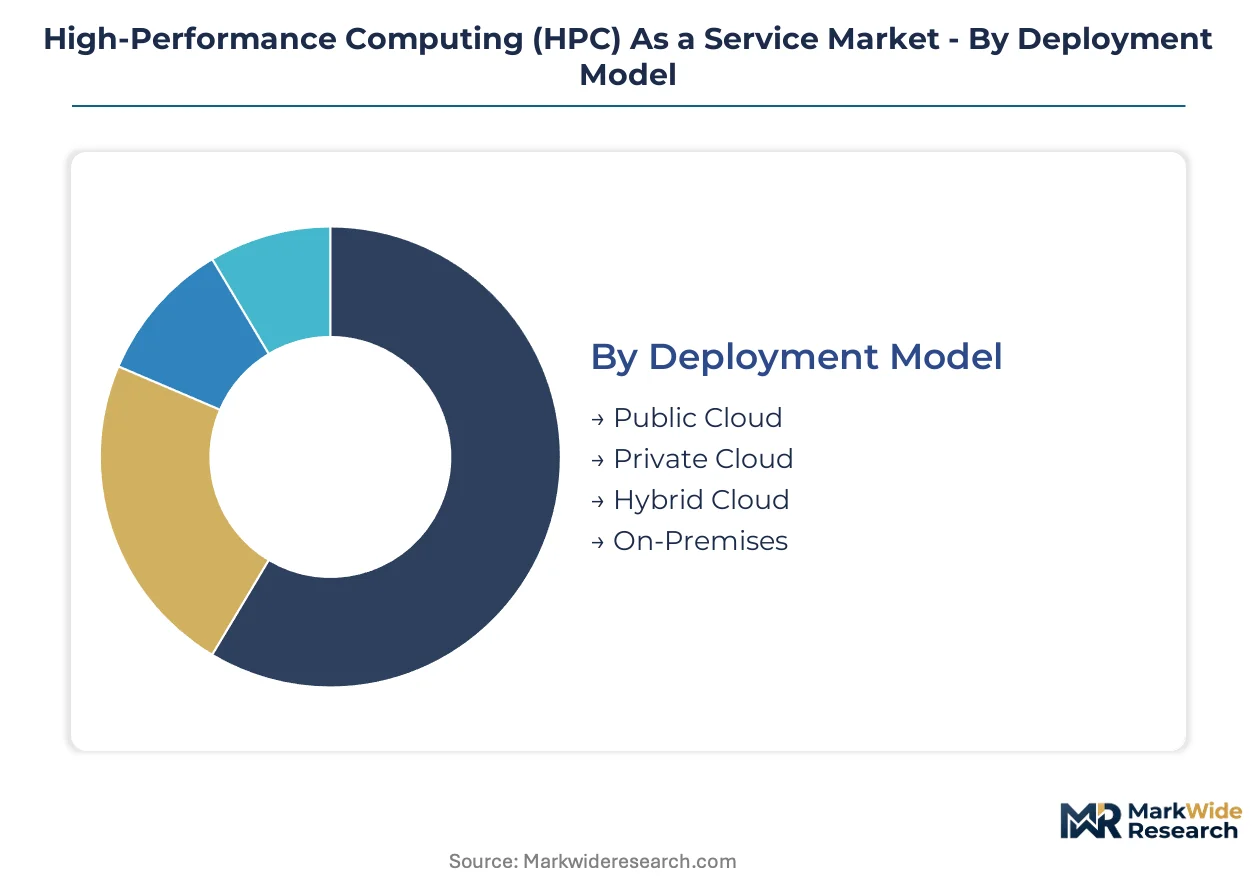
Segmentation in HPCaaS reveals how workload characteristics, compliance requirements, and procurement sophistication dictate infrastructure choices. Buyers sort across deployment models based on data sovereignty needs, service types by internal technical capacity, and applications by computational intensity thresholds.
Deployment Model:
Use-case spectrum spans burst elasticity for transient workloads to captive infrastructure for persistent classified processing.
- Public Cloud:Multi-tenant environments deliver pay-as-you-go petaflop access without capital commitment. Pharmaceutical developers at Roche and Novartis burst molecular dynamics simulations during trial design windows, avoiding $50 million supercomputer procurements.
- Hybrid Cloud:Orchestrated control planes synchronize on-premise clusters with elastic cloud bursts. German automotive OEMs in Baden-Württemberg maintain sovereign data lakes locally while tapping Azure or AWS for crash simulation peaks, satisfying EU AI Act residency mandates.
- Private Cloud:Dedicated single-tenant infrastructure serves defense contractors and intelligence agencies with air-gapped security postures. FedRAMP authorization timelines of twelve to eighteen months constrain provider selection to pre-certified environments.
- On-Premises:Customer-owned supercomputing facilities persist in national laboratories and semiconductor design centers requiring sub-microsecond latency. Taiwan Semiconductor Manufacturing Company operates captive HPC for process node simulation.
Established volume favors Public Cloud; emerging adoption favors Hybrid Cloud.
Service Type:
Margin concentration tracks abstraction depth, with raw infrastructure commanding premium pricing over managed layers.
- Infrastructure as a Service (IaaS):Bare-metal GPU clusters with InfiniBand interconnects provision petaflop-scale compute, storage, and networking as metered resources. NVIDIA DGX Cloud and AWS ParallelCluster anchor this tier, capturing the dominant margin pool through scarcity of low-latency networking expertise.
- Platform as a Service (PaaS):Containerized orchestration layers abstract Kubernetes scheduling, MPI configuration, and job queuing. Research teams at Fraunhofer institutes leverage PaaS environments to collapse setup time from weeks to hours for computational fluid dynamics workflows.
- Software as a Service (SaaS):Pre-configured simulation applications delivered through browser interfaces eliminate infrastructure management entirely. Ansys Cloud and Siemens Simcenter on Azure exemplify this model, targeting mechanical engineers without HPC administration skills.
- Managed Services:Provider-operated workload optimization, compliance consulting, and 24/7 operations support. Wipro and Accenture bundle these services with capacity contracts, bypassing direct hyperscaler relationships for enterprise buyers.
Revenue concentration favors IaaS; capability expansion favors Managed Services.
End User:
Procurement sophistication separates grant-funded academic users from enterprise buying committees with vendor management functions.
- Enterprises:Fortune 500 manufacturers and pharmaceutical developers negotiate multi-year enterprise agreements with reserved capacity guarantees. BMW validates Arm-based Graviton instances against x86 baselines for crash simulation cost reduction.
- Academia:University research groups access HPCaaS through national allocation programs and institutional subscriptions. ETH Zurich and Technical University of Munich anchor European academic demand with specialized quantum chemistry workloads.
- Government Agencies:Defense, intelligence, and civilian agencies mandate FedRAMP or equivalent sovereign certifications. US Department of Energy laboratories burst to commercial clouds during facility maintenance windows.
- Research Institutions:National laboratories and independent research centers operate at scale between academic and government procurement regimes. CERN's Openlab program evaluates cloud HPC for particle physics data processing.
Contract value favors Enterprises; growth velocity favors Research Institutions.
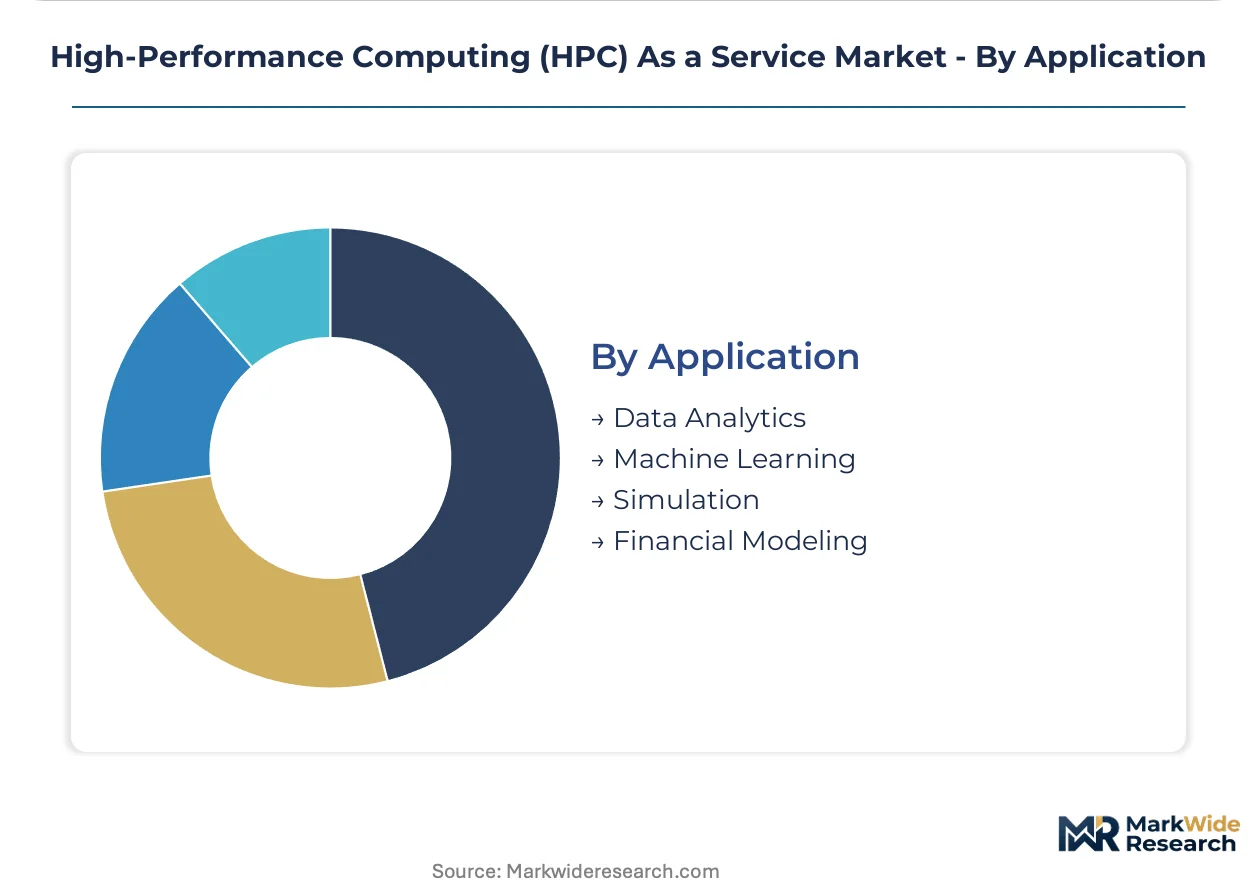
Application:
Computational intensity and data parallelism requirements segment workload economics across GPU, CPU, and specialized accelerator configurations.
- Simulation:Finite element analysis, computational fluid dynamics, and molecular dynamics demand sustained petaflop throughput with low-latency interconnects. Automotive crash simulation at Continental consumes the largest reserved capacity blocks in European HPCaaS.
- Machine Learning:Distributed training of transformer models and neural architecture search requires GPU clusters with high-bandwidth memory. Export control restrictions on NVIDIA H100 accelerators are redirecting demand toward AMD MI300X and custom silicon alternatives.
- Data Analytics:Large-scale genomics, geospatial processing, and log analytics operate on memory-optimized CPU configurations. Illumina and 23andMe process population-scale genomic datasets through cloud HPC for variant calling pipelines.
- Financial Modeling:Monte Carlo risk simulation and derivative pricing exploit massive parallelism with modest memory footprints. Swiss Re and Munich Re validate catastrophe models across thousands of stochastic scenarios.
Capacity reservation favors Simulation; spot-market elasticity favors Financial Modeling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's automotive corridors while India operates on thinner margins under PLI scheme incentives. The EU AI Act and US export controls on advanced semiconductors are redrawing infrastructure deployment maps across both markets.
United States
Defense contractors and national laboratories anchor sovereign HPCaaS demand through FedRAMP-authorized environments. The Department of Energy's National Nuclear Security Administration mandates burst capacity contracts for facility maintenance windows. Lawrence Livermore National Laboratory validates commercial cloud clusters for classified simulation workloads.
Germany
Fraunhofer institutes and automotive OEMs in Baden-Württemberg and Bavaria drive multi-year procurement contracts with data residency guarantees. The EU AI Act's high-risk classification system requires audit trails tracing compute provenance through training steps. BMW validates Arm-based Graviton instances against x86 baselines for crash simulation cost reduction in Munich.
India
Domestic pharmaceutical developers and fintech startups create greenfield demand absent legacy supercomputing infrastructure. The PLI scheme for semiconductor design incentivizes sovereign HPCaaS capacity among domestic cloud providers. Bangalore's technology corridor anchors demand for molecular dynamics and risk modeling workloads.
Singapore
Commodity trading houses and regional headquarters of multinational banks exploit low-latency connectivity to ASEAN markets. Power purchase agreement repricing in data center hubs compresses provider margins on fixed-rate contracts. The island's financial district concentrates Monte Carlo simulation workloads for catastrophe risk modeling.
United Kingdom
Research-intensive universities and defense primes split procurement between academic allocation programs and classified contracts. The UK National Quantum Computing Centre demands orchestration layers spanning GPU clusters and early quantum processing units. Cambridge's technology cluster evaluates hybrid classical-quantum algorithms for pharmaceutical applications.
High-Performance Computing (HPC) As a Service Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin from scarcity. Hyperscale cloud providers consolidate around custom silicon and sovereign infrastructure certifications while systems integrators fragment the mid-market with vertical-specific bundles. Two archetypes dominate: full-stack platform operators with captive silicon roadmaps, and channel intermediaries bundling compliance consulting with capacity provisioning. Competitive moves concentrate on M&A for networking talent and strategic partnerships for sovereign data center buildouts.
Among hyperscale platform operators, Amazon Web Services, Microsoft Azure, and Google Cloud exemplify the full-stack archetype with custom accelerator programs and government-authorized regions. AWS leverages Graviton and Trainium silicon for price-performance positioning in simulation workloads. Microsoft anchors defense contracts through FedRAMP-authorized Azure Government regions. Google occupies a position emphasizing Kubernetes-native orchestration for hybrid workload portability. These three represent divergent bets on silicon autonomy versus ecosystem openness.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM |
| Hewlett Packard Enterprise |
| Dell Technologies |
| NVIDIA |
| Oracle |
| Atos |
| Others |
Supply & Pricing Matrix
US export licensing delays on advanced NVIDIA H100 and AMD MI300X accelerators determine both the premium spread for configured-to-order GPU clusters and the geographic redistribution of foundry-dependent supply chains toward alternative architectures.
Pricing Analysis
The customization-premium spread separates bare-metal InfiniBand-connected GPU clusters from standard Ethernet-based CPU instances by a factor of three to five. Pricing stratifies across premium certified tiers with FedRAMP authorization, standard commercial deployments, and economy spot-market capacity for transient workloads. Cost compression in the premium tier is intensifying because foundry capacity constraints in Taiwan extend delivery timelines beyond eighteen months. Financial modeling teams at reinsurance carriers exhibit the highest price sensitivity, while defense contractors accepting air-gapped private cloud deployments show minimal elasticity.
Supply Chain Analysis
Contract manufacturing concentration rests on Taiwan Semiconductor Manufacturing Company for advanced GPU fabrication, Samsung Foundry for HBM memory stacking, and Foxconn for server assembly. The HPCaaS supply chain draws from Taiwan for logic chips, South Korea for high-bandwidth memory, and Malaysia for passive components. Single-source vulnerability in CoWoS packaging capacity creates chokepoint exposure for training cluster deployments. Distribution runs through hyperscaler direct-provision channels, systems integrator bundles, and sovereign cloud reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards providers who control scarce low-latency networking engineering talent and pre-certified sovereign infrastructure, while penalizing those dependent on concentrated GPU supply chains subject to export control disruption.
For Market Incumbents: Insulate margin pools by deepening backward integration into custom silicon roadmaps such as AWS Trainium and Azure Cobalt, and by securing multi-year power purchase agreements in Nordic and Singapore data center hubs before repricing cycles complete. The threat of purpose-built AI training clouds from hyperscalers capturing general-purpose HPC workloads demands pre-emptive certification investments in EU AI Act compliance architectures. For New Entrants and Emerging Players: India's absence of legacy supercomputing infrastructure offers the most penetrable white-space for sovereign HPCaaS targeting domestic pharmaceutical developers and fintech startups under PLI scheme incentives. A second target lies in quantum-classical workload orchestration layers for UK National Quantum Computing Centre requirements. Go-to-market execution should anchor on vertical-specific compliance consulting bundled with burst capacity contracts. For Investors and Strategic Acquirers: The EU AI Act's risk-tier classification system reshapes the acquisition landscape by privileging providers with continental data residency and ISO 27001-certified operational controls. Long-term viability favors full-stack platform operators with captive silicon autonomy over channel intermediaries dependent on hyperscaler relationships. The signal to watch is FedRAMP authorization velocity for commercial cloud providers seeking defense contractor procurement eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Roadmap Investment | AWS Trainium and Graviton development sustains price-performance positioning against x86 and NVIDIA baselines. |
| Sovereign Cloud Certification | EU AI Act compliance investments unlock German automotive OEM and Fraunhofer institute procurement pipelines. |
| Systems Integrator Partnership | Wipro and Accenture vertical practices bypass direct hyperscaler relationships for enterprise compliance bundling. |
| Power Purchase Agreement Securement | Fixed-rate energy contracts in Nordic hubs defend margins against volatility in Singapore data center markets. |
| Quantum-Classical Orchestration Layer | Hybrid algorithm scheduling capabilities capture UK National Quantum Computing Centre evaluation contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cloud infrastructure executives, HPC procurement officers at automotive OEMs, pharmaceutical R&D directors, and sovereign cloud regulatory leads; and secondary validation through hyperscaler capex disclosures, EU AI Act implementation guidance, US Bureau of Industry and Security export control filings, and national supercomputing center allocation reports. Bottom-up capacity deployment tracking and top-down enterprise spending surveys were triangulated against foundry utilization data.
Forecast inputs considered deployment model adoption curves, service type margin trajectories, and end-user procurement sophistication across the projection horizon. Segmentation dimensions modeled include infrastructure abstraction depth, workload computational intensity thresholds, data sovereignty requirements, and regional regulatory cluster classifications. CAGRs were derived from elasticity-adjusted capacity expansion rates and price-performance improvement curves in GPU and alternative accelerator architectures.
Practitioners should monitor US export control expansion scope, EU AI Act enforcement precedence, and foundry CoWoS capacity allocation for early signals of forecast revision. Assumptions underlying projections reflect current regulatory frameworks and supply chain configurations. Quarterly review of hyperscaler custom silicon deployment velocity and sovereign cloud certification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
GPU Virtualization Market
Cloud Computing
Cloud Management Platform Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Telecom Cloud Market
Cloud Computing
France Cloud Computing Market
Cloud Computing
Automotive Cloud Based System Market
Cloud Computing
Automotive Cloud Based Solutions Market
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Nigeria Cloud Computing Market
Cloud Computing
Global Multi Cloud Management Market
Cloud Computing
Cloud ECS Market