
 Asia Pacific Multi-Cloud Management Market | 2026-2036
Asia Pacific Multi-Cloud Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Multi-Cloud Management Market Analytics
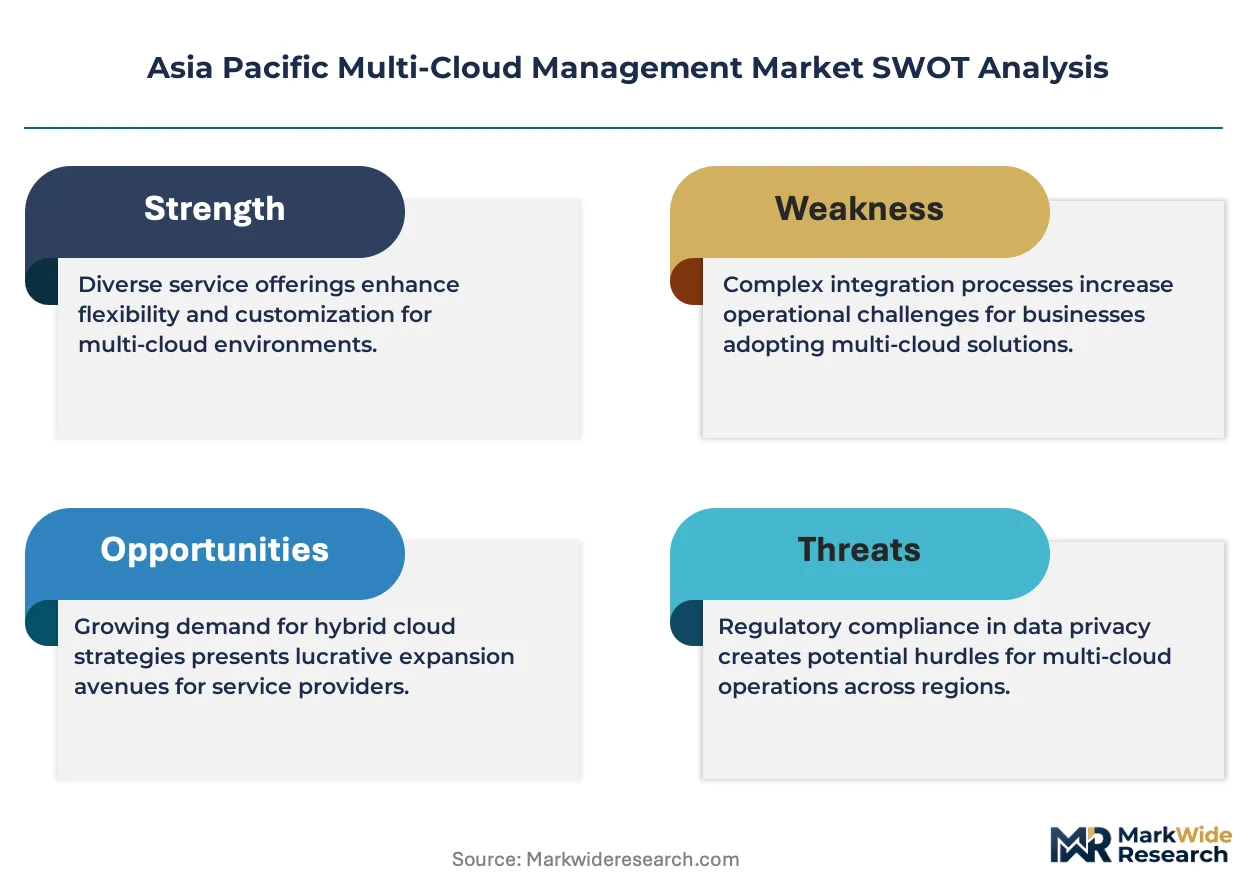
Enterprise-grade SLA tiering is collapsing the gap between basic cloud orchestration and mission-critical multi-cloud governance. VMware leverages its Tanzu portfolio to anchor hybrid cloud management across Australian financial institutions. Alibaba dominates mainland China's multi-cloud interoperability layer, while IBM sustains mainframe-to-cloud integration strength in Japanese manufacturing verticals.
Asia Pacific multi-cloud management encompasses the unified orchestration, monitoring, and governance of workloads distributed across two or more public, private, or edge cloud environments through centralized control planes with API abstraction layers. The discipline automates resource provisioning, cost allocation, and security policy enforcement across heterogeneous infrastructure stacks to prevent vendor lock-in and optimize capital efficiency. Hybrid cloud deployment architectures command the largest addressable base as regulated industries maintain on-premises sovereignty for sensitive data while bursting compute to public infrastructure. Security services within the service type dimension capture disproportionate margin pools as sovereign data requirements multiply compliance complexity across national boundaries. SMEs represent the fastest-growing end user category as managed service providers package pre-configured automation platforms at consumption-based price points.
India's BIS cloud standards mandate data localization for government workloads, compelling vendors to architect in-country control plane instances. Japan's METI digital infrastructure guidelines and Australia's Privacy Act cross-border data restrictions shape product certification requirements and market access conditions. Stakeholders must calibrate platform roadmaps against divergent national sovereignty regimes rather than pursuing uniform regional deployment templates.
Market Dynamics
National data sovereignty mandates are fragmenting cloud architectures across Asia Pacific, compelling vendors to deploy in-country control planes and certified infrastructure stacks that complicate unified management.
Growth Catalysts
- India's BIS cloud standards:Data localization requirements for government workloads are mandating domestic control plane instances, creating certified vendor ecosystems.
- Financial services verticals:Southeast Asian banks are accelerating multi-cloud adoption to satisfy cross-border data restrictions under national cloud-first policies.
- Edge-to-core orchestration:Distributed manufacturing and IoT deployments are driving demand for unified management across heterogeneous infrastructure stacks.
Market Restraints
- API interoperability gaps:Proprietary cloud-native toolchains from hyperscalers create technical lock-in that resists abstraction layer standardization.
- Certification cost burden:Divergent national compliance regimes in Australia, Japan, and India multiply audit and accreditation expenses for platform vendors.
- Skill scarcity:Shortage of engineers proficient in Kubernetes, Terraform, and sovereign cloud architectures constrains enterprise deployment velocity.
Strategic Opportunities
- Indonesia's digital infrastructure gap:Limited domestic cloud capacity creates first-mover advantage for vendors building certified in-country management platforms.
- AI workload orchestration:Convergence of GPU cluster management with multi-cloud governance opens specialized service tiers for model training pipelines.
- Japan's METI digital guidelines:Manufacturing sector modernization incentives are channeling public funding toward hybrid cloud integration projects.
Industry Challenges
- Legacy mainframe integration:Japanese and Australian financial institutions require complex middleware bridges to synchronize on-premises core banking systems with cloud-native control planes.
- Cross-border policy misalignment:Australia's Privacy Act restrictions, India's BIS mandates, and Japan's METI guidelines create conflicting compliance matrices that fragment product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Multi-Cloud Management Market |
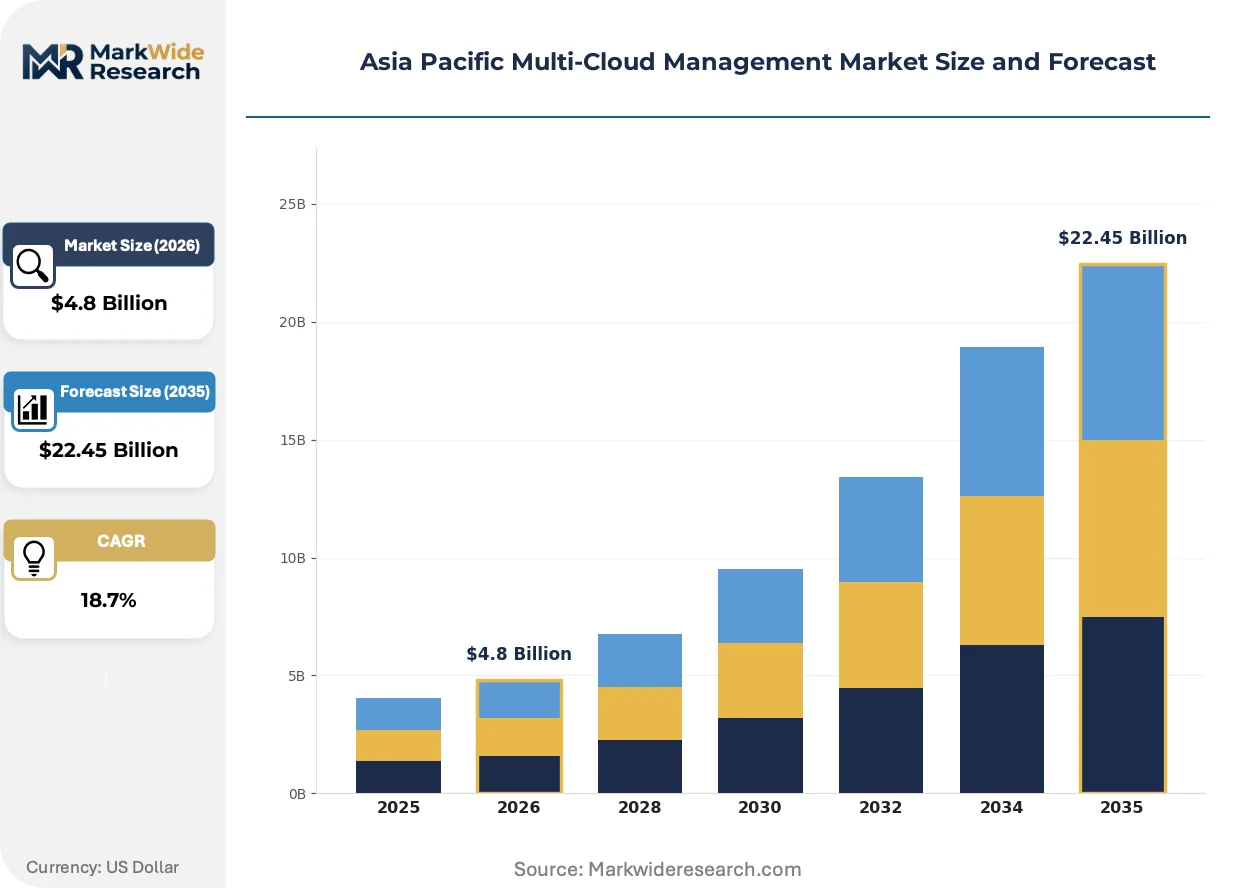
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure Management, Application Deployment, Security Services, Cost Management End User: Enterprises, SMEs, Government, Educational Institutions Solution: Monitoring Tools, Automation Platforms, Data Integration, Backup Solutions |
| Companies Covered | VMware, Inc. (Broadcom Inc.), IBM Corporation, Cisco Systems Inc., BMC Software, Inc. (KKR & Co., Inc.), Accenture PLC, Citrix Systems, Inc. (Cloud Software Group), Alibaba Group Holding Limited, Microsoft Corporation, Amazon.com Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Multi-Cloud Management Market Evolving Landscape
Platform engineering practices are reshaping how Asia Pacific enterprises consume multi-cloud management, shifting from ticket-based provisioning to self-service internal developer portals with embedded governance guardrails.
FinOps tooling is displacing manual cost allocation spreadsheets across Australian and Indian enterprises, embedding real-time spend visibility and automated budget enforcement directly into CI/CD pipelines. Mid-market SaaS providers are adopting these capabilities fastest, compressing procurement cycles from quarterly reviews to continuous optimization loops.
Australia's Privacy Act cross-border data restrictions are forcing vendors to architect region-locked control planes with data residency attestations, reshaping product certification requirements. Financial services and healthcare verticals face the steepest compliance burdens, driving demand for pre-certified sovereign cloud management templates.
Consumption-based pricing models are unbundling traditional perpetual licenses, with managed service providers packaging pre-configured automation platforms at metered price points. SME adoption is accelerating fastest in India and Southeast Asia, where capital-constrained buyers prefer operational expenditure structures over upfront platform investments.
Asia Pacific Multi-Cloud Management Market Segmentation
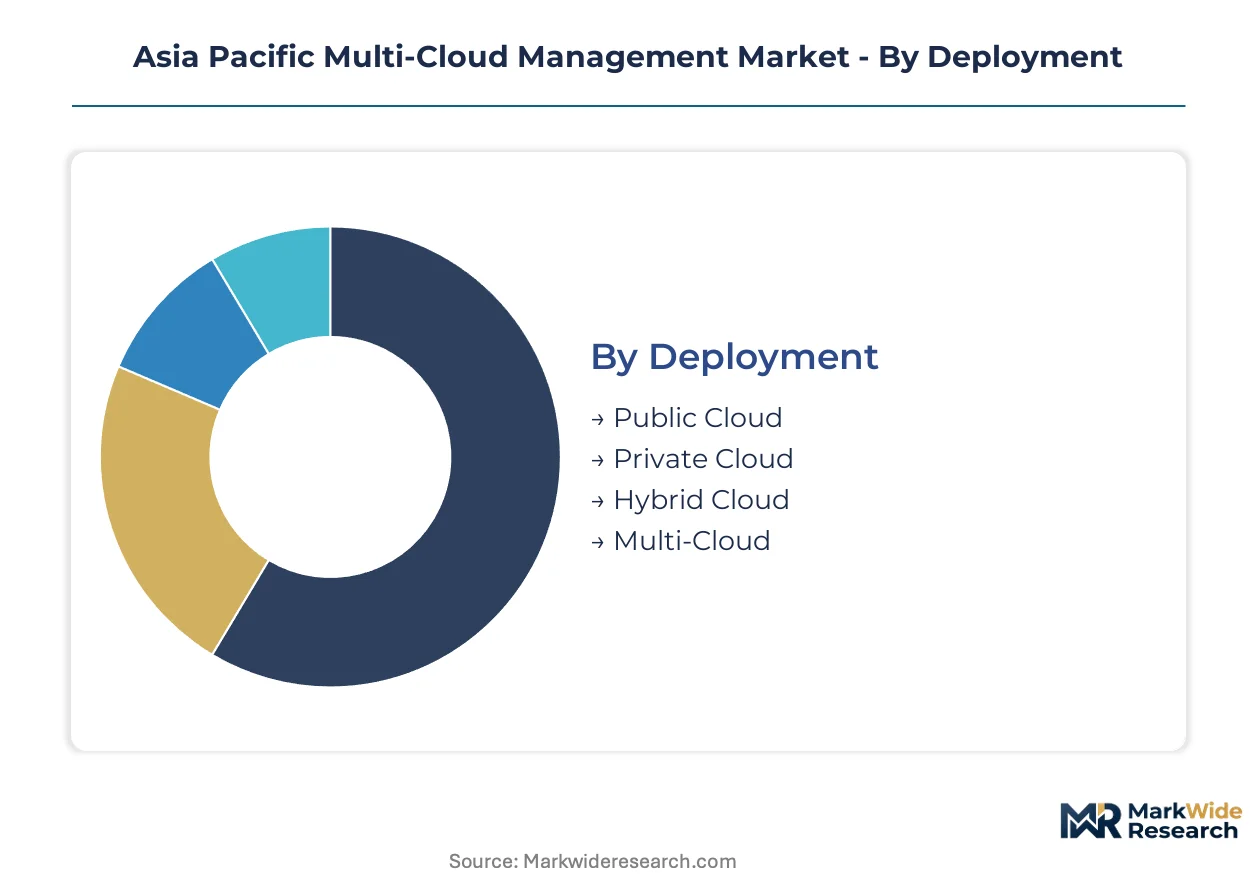
Multi-cloud management platforms must align deployment architectures with sovereignty mandates and service tiers with compliance complexity. Channel strategy varies sharply across these dimensions, with direct enterprise sales dominating regulated verticals while MSPs penetrate mid-market segments through consumption-based packaging.
Deployment:
Channel mix bifurcates between direct platform sales for sovereign architectures and partner-led distribution for standardized public cloud tooling.
- Public Cloud:Delivers centralized orchestration across hyperscaler-native environments through API abstraction layers. Australian financial institutions and Indian SaaS providers concentrate procurement here, constrained by cross-border data restrictions that force region-locked control plane instances.
- Hybrid Cloud:Synchronizes on-premises sovereignty zones with public infrastructure bursting through unified governance frameworks. Japanese manufacturing verticals and Southeast Asian banks drive demand, compelled by METI digital guidelines and national cloud-first policies requiring domestic data residency.
- Private Cloud:Provides dedicated control planes for classified workloads through single-tenant infrastructure stacks.
- Multi-Cloud:Orchestrates three or more heterogeneous environments through federated management consoles.
Hybrid Cloud dominates installed base. Multi-Cloud is where expansion concentrates.
Service Type:
Margin pools concentrate in services where compliance complexity multiplies audit and accreditation burdens for platform vendors.
- Security Services:Enforces sovereign data policies, encryption key management, and zero-trust architectures across distributed infrastructure. Financial services institutions across Singapore, Hong Kong, and Thailand channel procurement here, driven by BIS-grade certification requirements and cross-border transaction monitoring mandates.
- Cost Management:Embeds FinOps tooling for real-time spend visibility and automated budget enforcement within CI/CD pipelines. Indian mid-market SaaS providers and Australian enterprises are expanding most quickly, compressing procurement cycles from quarterly reviews to continuous optimization loops.
- Infrastructure Management:Automates resource provisioning and lifecycle orchestration across heterogeneous stacks.
- Application Deployment:Streamlines containerized workload placement through Kubernetes-native control planes.
Security Services commands premium pricing tiers. Cost Management is climbing the fastest.
End User:
Procurement authority shifts from centralized IT governance in enterprises to line-of-business buyers in SME segments.
- SMEs:Consume pre-configured automation platforms through managed service providers at metered price points. Capital-constrained buyers across India and Southeast Asia prefer operational expenditure structures, with Jakarta and Bangalore emerging as MSP consolidation hubs.
- Enterprises:Deploy customized control planes with embedded governance guardrails for mission-critical workloads. Australian healthcare networks and Japanese automotive suppliers anchor demand, requiring mainframe-to-cloud middleware bridges.
- Government:Mandates domestic control plane instances under BIS and METI certification regimes.
- Educational Institutions:Adopts consumption-based research computing platforms with federated identity management.
Enterprises anchor current revenue. SMEs represent the steepest expansion trajectory.
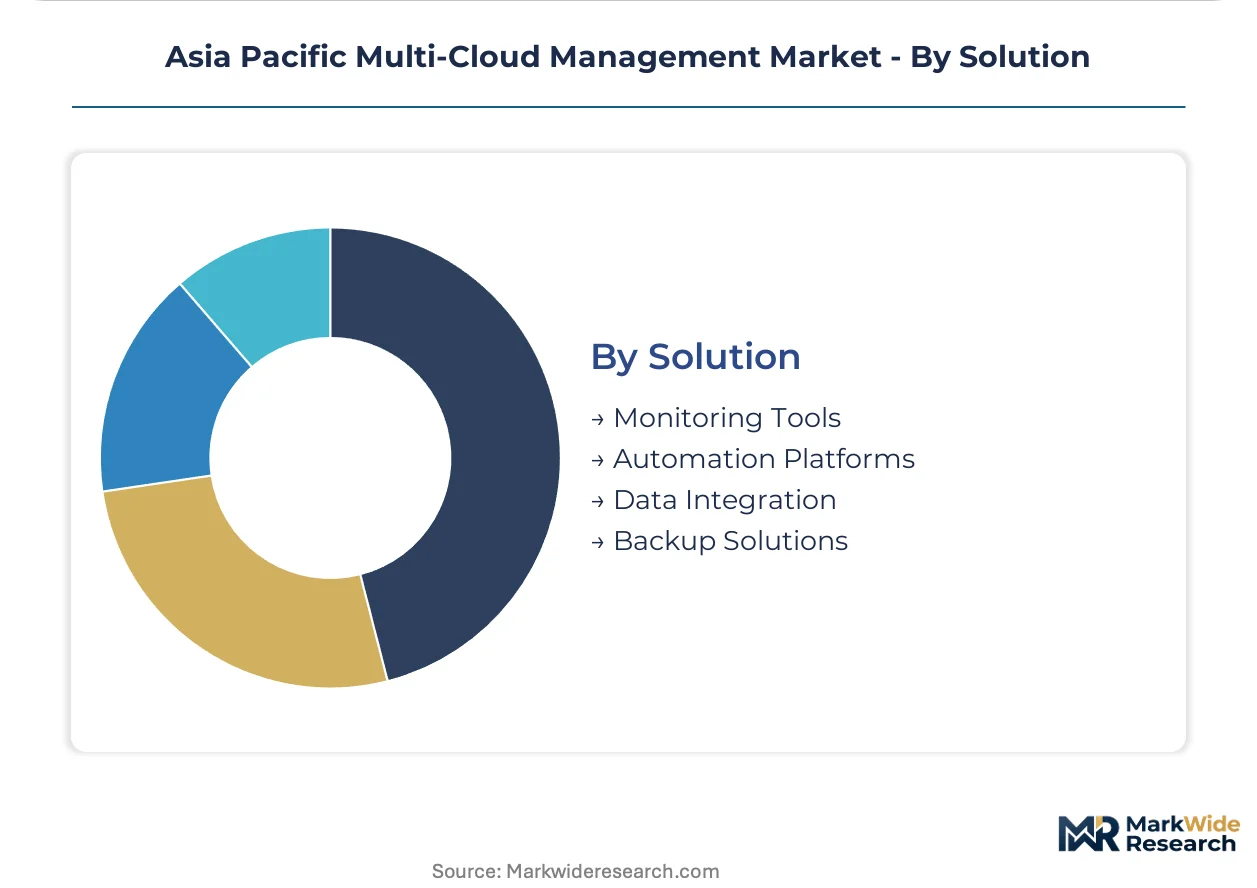
Solution:
Technology maturity separates monitoring and automation platforms with established deployment patterns from emerging data integration and backup categories.
- Automation Platforms:Delivers self-service internal developer portals with policy-as-code guardrails replacing ticket-based provisioning. Platform engineering teams at Singaporean fintechs and South Korean conglomerates are standardizing procurement here, displacing manual orchestration workflows.
- Data Integration:Synchronizes distributed data lakes across edge, core, and cloud environments through federated query engines. Indonesian logistics operators and Vietnamese manufacturers are gaining share fastest, bridging legacy ERP systems with cloud-native analytics pipelines.
- Monitoring Tools:Provides unified observability across heterogeneous infrastructure through centralized telemetry aggregation.
- Backup Solutions:Orchestrates cross-cloud disaster recovery with sovereignty-compliant replication policies.
Automation Platforms dominate current deployment. Data Integration is where vendor R&D concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor control plane deployments concentrate in jurisdictions with the strictest data localization mandates. Australia's Privacy Act, India's BIS standards, and Japan's METI guidelines force distinct infrastructure architectures that complicate unified regional management.
India
Bureau of Indian Standards certification requirements and RBI data localization directives compel domestic control plane instances for government and financial workloads. Mumbai and Bangalore host the densest vendor infrastructure clusters as cloud providers establish certified facilities to serve public sector procurement. The BIS framework fragments procurement by mandating separate compliance pathways for sensitive versus non-sensitive data categories.
Japan
METI digital infrastructure guidelines channel public funding toward hybrid cloud integration in automotive and precision manufacturing supply chains. The Nagoya industrial corridor anchors demand for mainframe-to-cloud middleware bridges that synchronize legacy core systems with modern orchestration layers. JIS certification requirements add accreditation overhead that favors established platform vendors with existing compliance infrastructure.
Australia
Privacy Act cross-border data restrictions force region-locked control planes with explicit data residency attestations for financial services and healthcare verticals. Sydney and Melbourne concentrate procurement authority for enterprise-grade sovereign cloud management templates. APRA prudential standards layer additional compliance complexity onto banking sector deployments.
Singapore
MAS cross-border transaction monitoring mandates drive financial institutions toward certified multi-cloud security services with embedded governance guardrails. The city-state's position as regional headquarters for Southeast Asian banking groups amplifies procurement scale for compliance-heavy orchestration platforms. Fintech clusters in the Central Business District accelerate adoption of self-service developer portals with policy-as-code enforcement.
Indonesia
Limited domestic cloud capacity creates infrastructure gaps that favor vendors building certified in-country management platforms ahead of competitors. Jakarta emerges as the primary consolidation hub for managed service providers packaging consumption-based automation for capital-constrained mid-market buyers. Government cloud-first policies are accelerating faster than local infrastructure deployment, generating temporary demand for hybrid architectures bridging international and emerging domestic capacity.
Asia Pacific Multi-Cloud Management Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific multi-cloud management market. Hyperscale cloud providers anchor the infrastructure layer with native orchestration toolchains, while specialized software vendors concentrate on governance abstraction and compliance automation. Three archetypes dominate: hyperscalers with integrated control planes, enterprise software incumbents with hybrid cloud middleware, and regional champions with sovereign-certified deployments. Competitive dynamics revolve around strategic partnerships with systems integrators and geographic expansion through certified local infrastructure.
Within the enterprise software tier, VMware exemplifies hybrid cloud governance specialization following its acquisition by Broadcom, while IBM Corporation occupies a position bridging mainframe integration with modern container orchestration. Alibaba Group Holding Limited anchors the regional champion archetype with sovereign-certified deployments across mainland China and Southeast Asian expansion markets. These three companies represent distinct strategic postures: infrastructure abstraction, legacy modernization, and jurisdiction-specific compliance automation.
| Leading Market Players |
|---|
| VMware, Inc. (Broadcom Inc.) |
| IBM Corporation |
| Cisco Systems Inc. |
| BMC Software, Inc. (KKR & Co., Inc.) |
| Accenture PLC |
| Citrix Systems, Inc. (Cloud Software Group) |
| Alibaba Group Holding Limited |
| Microsoft Corporation |
| Amazon.com Inc. |
| Others |
Value Network & Pricing Analysis
Consumption-based SaaS licensing is displacing perpetual software licenses across Asia Pacific multi-cloud management, compressing upfront capital requirements for Indian and Southeast Asian buyers while forcing vendors to absorb infrastructure costs through metered pricing structures.
Pricing Analysis
BIS certification requirements dictate the pricing tier structure across Indian government procurement, separating certified sovereign cloud management platforms from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects compliance grade, with BIS-certified instances commanding 40-60% premiums over baseline orchestration tooling. Pricing pressure stems from MSPs packaging pre-configured automation at aggressive per-seat rates, squeezing standalone platform margins. SMEs across Jakarta and Bangalore exhibit highest price sensitivity, while Japanese automotive suppliers and Australian healthcare networks prioritize certification over cost.
Supply Chain Analysis
India and Japan anchor control plane infrastructure deployment, with Mumbai, Bangalore, and Tokyo hosting the densest certified facility clusters for sovereign cloud management. Software supply chains draw from US-based hyperscaler APIs, open-source Kubernetes distributions, and domestic middleware specialists. Single-source vulnerability concentrates around proprietary orchestration toolchains from major cloud providers. Distribution runs through systems integrators in regulated verticals and MSPs in mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data sovereignty fragmentation creates specialized vendor niches across Asia Pacific, as divergent national certification regimes prevent standardized regional platform deployment.
For Market Incumbents: Consolidate certification infrastructure across BIS, METI, and Australian Privacy Act compliance pathways to defend against emerging regional champions. Acquire domestic middleware specialists in Nagoya and Sydney to bridge legacy mainframe integration gaps. Lock in systems integrator partnerships to control distribution in Japanese manufacturing and Australian financial services verticals. For New Entrants and Emerging Players: Differentiate on sovereign-certified edge-to-core orchestration for Indonesian manufacturing and logistics operators facing domestic cloud capacity constraints. Target Jakarta-based MSP consolidation as the most penetrable channel, leveraging consumption-based pricing to bypass capital expenditure barriers. Lead with AI workload governance for GPU cluster management as the primary go-to-market wedge. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed enterprise software vendors holding JIS and BIS certification infrastructure but lacking cloud-native orchestration depth. Five-to-ten year viability hinges on successful platform engineering transitions away from ticket-based provisioning. Watch hyperscaler API standardization initiatives as the critical inflection signal for abstraction layer commoditization risk.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Certification Investment | BIS and METI compliance unlocks Indian government and Japanese manufacturing procurement channels. |
| Platform Engineering Transition | Self-service developer portals with policy-as-code guardrails displace manual ticket-based provisioning workflows. |
| MSP Channel Partnership | Metered consumption packaging through Jakarta and Bangalore hubs penetrates capital-constrained SME segments. |
| Legacy Middleware Acquisition | Mainframe-to-cloud bridges address Japanese automotive and Australian banking integration requirements. |
| Edge Orchestration Development | Distributed IoT and manufacturing deployments demand unified management across heterogeneous infrastructure stacks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud architects at Australian financial institutions, platform engineering leads at Singaporean fintechs, procurement officers at Japanese automotive suppliers, and MSP principals in Jakarta and Bangalore. Secondary validation drew from BIS certification registries, METI digital infrastructure guidelines, APRA prudential standards disclosures, and hyperscaler capex filings. Bottom-up deployment estimates triangulated against top-down market sizing across hybrid, public, and multi-cloud deployment architectures.
Across the analysis window, forecasts modeled deployment type, service tier, organization size, vertical compliance complexity, and national regulatory cluster. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs incorporated sovereign certification pipeline timelines, MSP packaging velocity, and edge infrastructure buildout trajectories.
Material uncertainties — abrupt regulatory harmonization or hyperscaler API standardization — sit outside the modeled envelope. Forecasts reflect assumptions about continued fragmentation in national data sovereignty regimes. Recalibration cycles align with material shifts in BIS, METI, or Australian Privacy Act enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Enablement Market
Cloud Computing
Cloudifier Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Cloud Backup Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Global Cloud-Native Software Market
Cloud Computing
Cloud Microservices Market
Cloud Computing
Cloud Load Balancers Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Spain Cloud Computing Market
Cloud Computing
Cognitive Cloud Market
Cloud Computing
Cloud Services Brokerage (CSB) Market
Cloud Computing
Cloud ECS Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
Bare Metal Cloud Market