
 Cloud Continuum Market | 2026-2036
Cloud Continuum Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Continuum Market Intelligence
The capital-intensity divergence between hyperscale infrastructure operators and boutique edge providers is redrawing competitive boundaries in cloud services. Amazon Web Services leverages its global fiber backbone and custom silicon investments to sustain pricing power at the infrastructure layer. Microsoft anchors enterprise trust through deep Azure integration with productivity suites, while Google Cloud differentiates via AI-optimized tensor processing clusters and open-source Kubernetes stewardship.
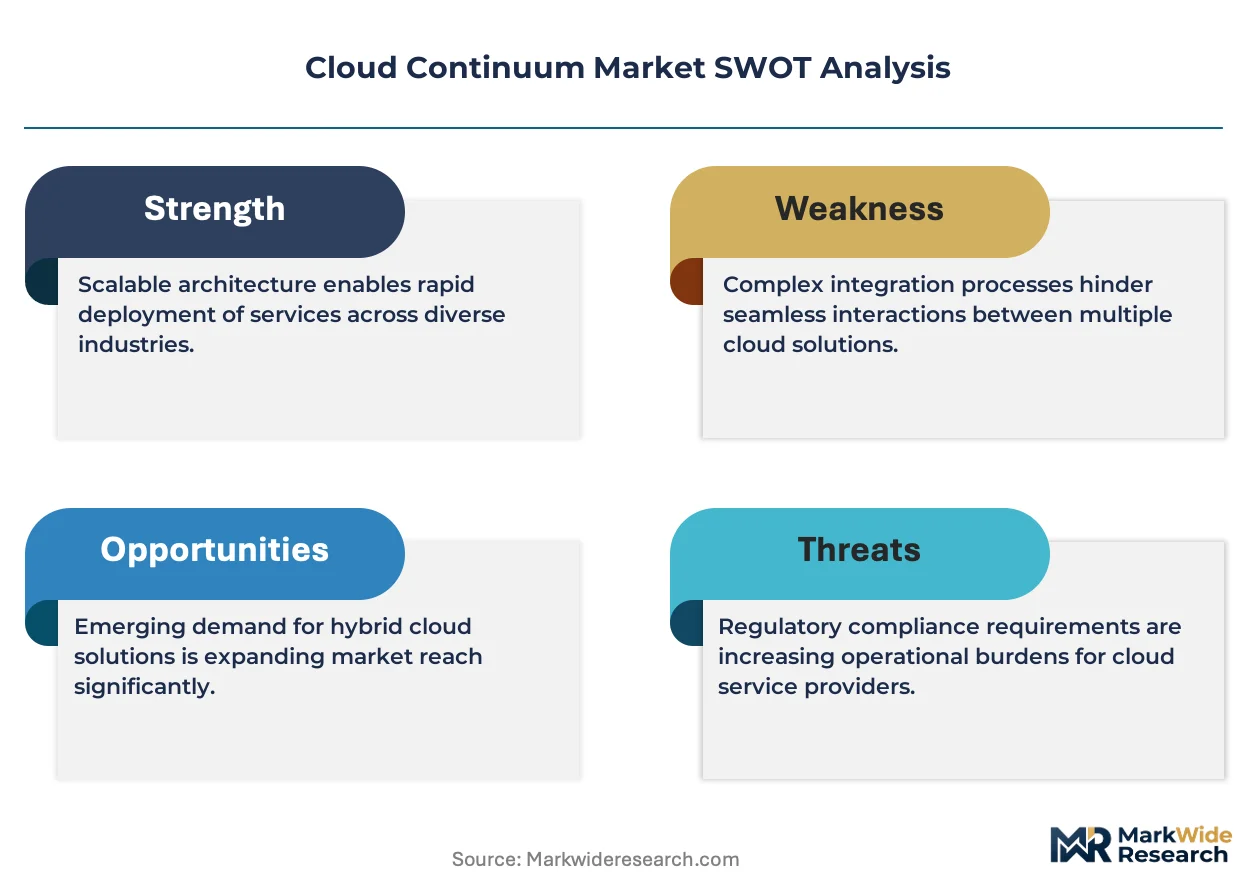
Cloud Continuum denotes the seamless orchestration of computing workloads across centralized data centers, regional edge nodes, and on-premises environments through unified control planes and policy-driven workload placement. The architecture relies on software-defined networking, container orchestration, and latency-sensitive scheduling algorithms to maintain sub-50 millisecond response thresholds for time-critical applications. Hybrid Cloud deployments now capture the largest share of enterprise infrastructure budgets as organizations straddle legacy systems and elastic cloud capacity. Platform as a Service offerings represent the fastest-expanding margin pool, abstracting infrastructure management while locking developers into proprietary runtime environments. Large Enterprises dominate current consumption volumes, though Government Agencies are emerging as a structurally distinct procurement segment with sovereign-cloud requirements.
GDPR, the EU AI Act, and ISO 27001 certification frameworks collectively shape data residency obligations and algorithmic transparency mandates across European deployments. In the United States, NIST cybersecurity standards and SEC disclosure rules for cloud-dependent financial infrastructure impose additional compliance layers on providers serving regulated industries. Stakeholders must monitor evolving cross-border data transfer mechanisms and sovereign-cloud certification programs as determinants of market access and customer retention.
Market Dynamics
Data sovereignty mandates and latency-sensitive application architectures are fragmenting cloud infrastructure deployment patterns, forcing providers to engineer distributed control planes that span hyperscale regions, sovereign facilities, and on-premises edge nodes.
Growth Catalysts
- EU AI Act Algorithmic Transparency:Financial services firms in Germany and France must deploy explainable AI workloads within jurisdictional boundaries, accelerating sovereign cloud procurement.
- Industrial IoT Latency Thresholds:Manufacturing automation in Stuttgart and Wolfsburg demands sub-10 millisecond response times, pulling compute capacity toward plant-adjacent edge nodes.
- Container Orchestration Maturation:Kubernetes-native workload portability eliminates vendor lock-in friction, enabling multi-cloud strategies across regulated European enterprises.
Market Restraints
- Specialized Silicon Cost Structure:Custom AI accelerators from TSMC's advanced nodes carry 40-60% premium over commodity x86, compressing margins for regional cloud operators.
- Submarine Cable Concentration:Transatlantic bandwidth depends on landing stations concentrated in Cork, Bude, and Marseille, creating single-point-of-failure exposure for cross-border data flows.
- Legacy Mainframe Interoperability:Core banking systems running COBOL on IBM Z architectures resist API-native integration, extending hybrid migration timelines.
Strategic Opportunities
- Poland's Underserved Manufacturing Belt:Katowice and Wrocław industrial zones lack sovereign cloud presence, creating first-mover advantage for GDPR-certified regional deployments.
- Federated Learning Architectures:Convergence of differential privacy techniques with edge aggregation enables cross-institutional AI training without raw data centralization.
- Green Cloud Procurement Mandates:CSRD disclosure rules pressure enterprises to source from providers with verified renewable energy matching, favoring Nordic hydro-powered facilities.
Industry Challenges
- Site Reliability Engineering Talent Scarcity:European labor markets lack sufficient practitioners skilled in distributed systems observability and chaos engineering methodologies.
- ISO 27001 Certification Timelines:Sovereign cloud providers face 12-18 month audit cycles, delaying market entry against established hyperscale competitors.
- Multi-Cloud Policy Orchestration Complexity:Enterprises struggle to maintain consistent security posture across AWS, Azure, and Google Cloud control planes without proprietary abstraction layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Continuum Market |
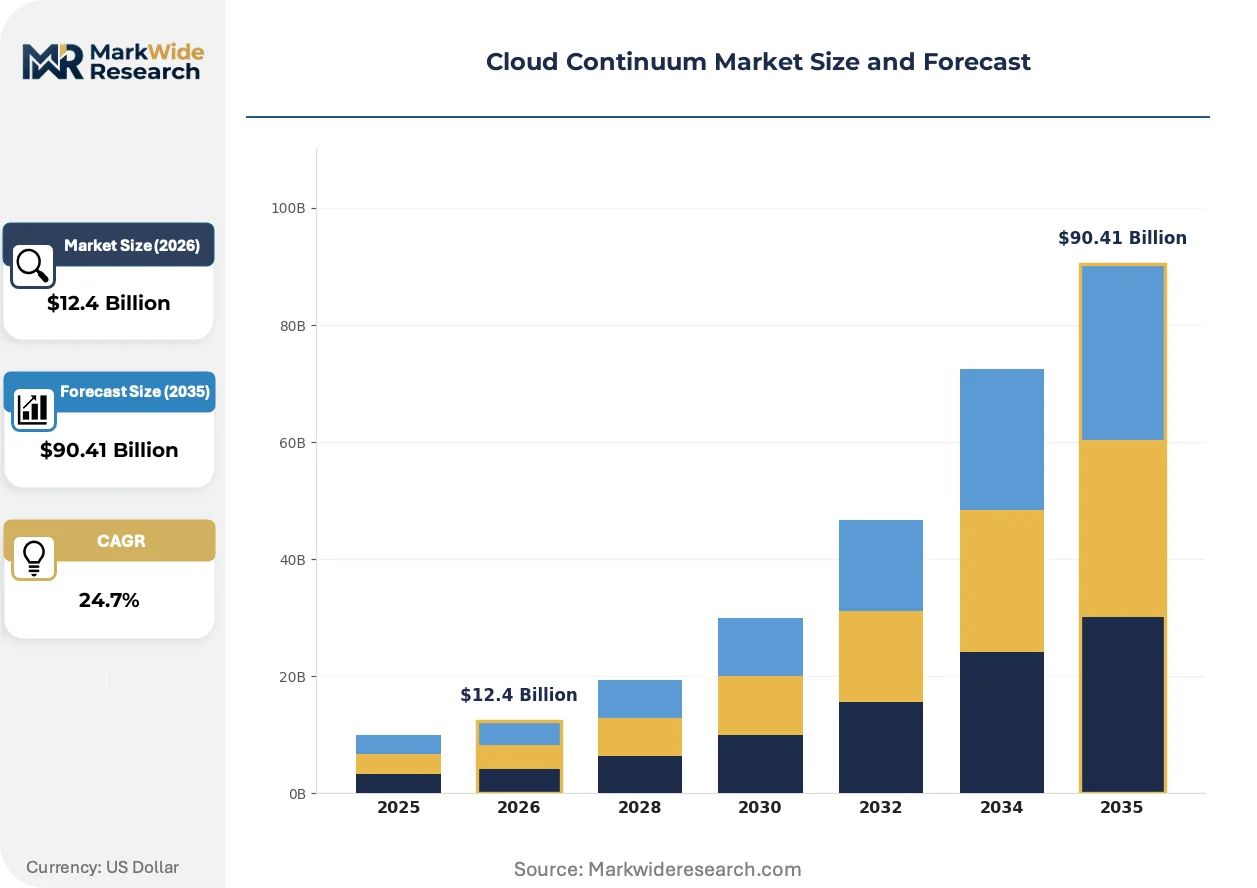
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $90.41 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service End User: SMEs, Large Enterprises, Startups, Government Agencies Service Model: Managed Services, Professional Services, Consulting Services, Training Services |
| Companies Covered | Oracle, Alibaba Cloud, Amazon Web Services, VMware, Salesforce, Microsoft, IBM, Equinix, Google Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Continuum Market Strategic Shifts & Innovations
Software-defined infrastructure is dissolving the boundary between cloud and edge, enabling workload placement decisions driven by real-time latency, cost, and compliance signals rather than static architectural boundaries.
Microservices architectures are decomposing monolithic enterprise applications into function-as-a-service components. Automotive manufacturers in Munich and Stuttgart are deploying event-driven serverless workloads to factory-floor gateways. This decomposition compresses the addressable market for traditional virtual-machine-centric hosting while expanding margin pools for specialized edge orchestration platforms.
GDPR's Article 44-49 transfer mechanism restrictions are forcing architectural redesign of transatlantic data flows. European enterprises are abandoning standard contractual clauses for EU-approved certification schemes. Healthcare and financial services verticals in Frankfurt and Amsterdam are migrating analytics workloads to regional sovereign cloud zones to preempt Schrems III litigation exposure.
Consumption-based metering is displacing reserved-capacity contracts as the dominant procurement paradigm. Mid-market enterprises in Barcelona and Milan are adopting pay-per-query data warehouse pricing over three-year commit structures. This shift compresses provider revenue predictability while accelerating customer experimentation with specialized database engines and AI inference services.
Cloud Continuum Market Segmentation
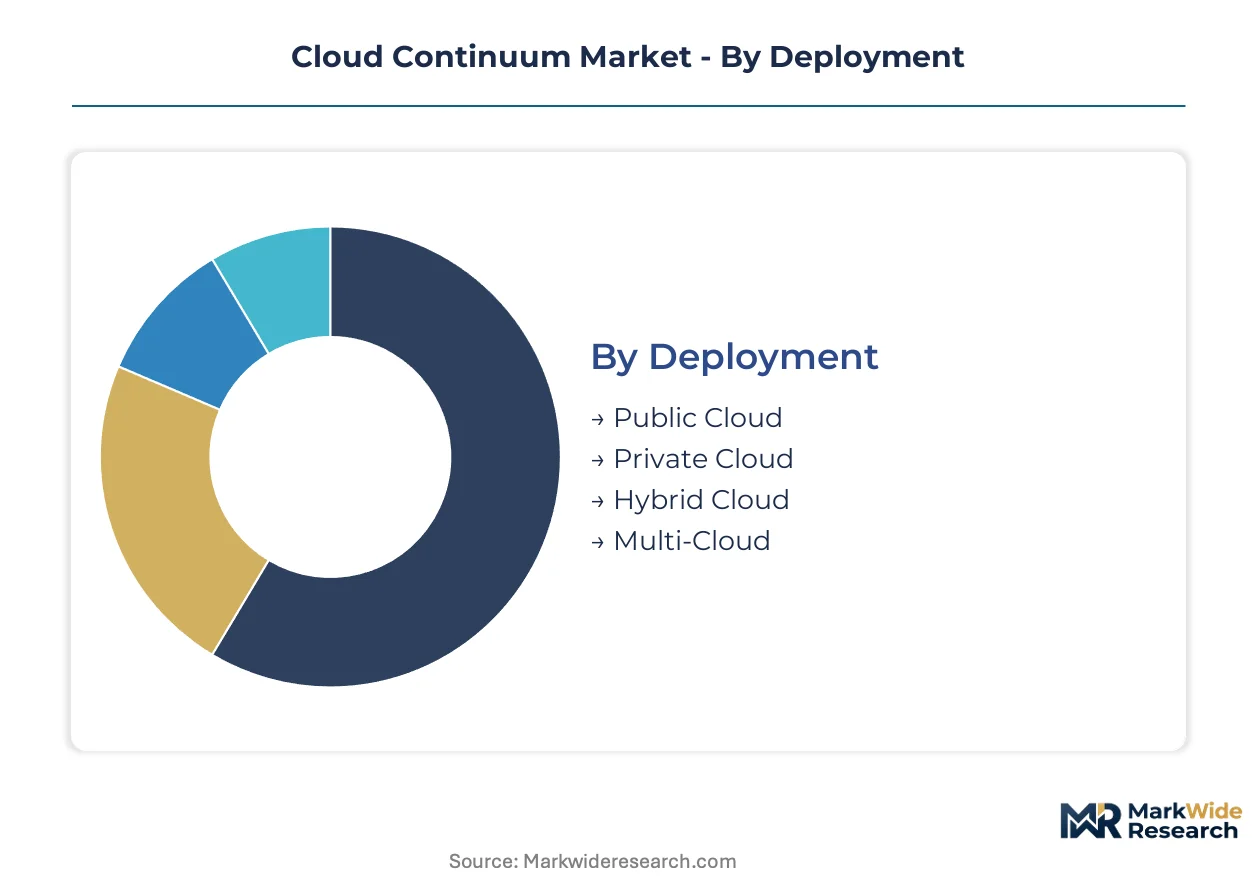
Cloud Continuum architectures fragment procurement decisions across deployment topology, solution abstraction layers, and service delivery models. Understanding how these segments intersect with compliance mandates and latency requirements reveals where margin pools concentrate and which configurations face commoditization pressure.
Deployment:
Geographic spread varies sharply: Public Cloud serves export-oriented workloads with minimal data residency constraints, while Private Cloud and Hybrid deployments concentrate domestically within regulated European jurisdictions.
- Public Cloud:Hyperscale shared infrastructure delivers elastic compute through globally distributed regions. Frankfurt and Amsterdam data centers capture financial services demand driven by GDPR Article 44-49 transfer mechanism uncertainties.
- Private Cloud:Dedicated single-tenant environments isolate workloads for algorithmic transparency compliance under the EU AI Act. German automotive manufacturers in Stuttgart deploy plant-adjacent private clusters to achieve sub-10 millisecond automation response thresholds.
- Hybrid Cloud:Unified orchestration across on-premises and cloud capacity. Legacy mainframe interoperability requirements in French banking extend migration timelines for this configuration.
- Multi-Cloud:Workload portability across AWS, Azure, and Google Cloud control planes. Kubernetes-native container orchestration eliminates vendor lock-in friction for mid-market enterprises in Barcelona and Milan.
Hybrid Cloud holds the largest share; momentum sits with Multi-Cloud as policy-driven workload placement matures.
Solution Type:
Cost tier stratification separates infrastructure-heavy offerings from high-margin abstraction layers, with Platform as a Service commanding premium pricing through developer ecosystem lock-in.
- Infrastructure as a Service:Raw compute, storage, and networking resources provisioned through APIs. Price compression intensifies as custom silicon premiums from TSMC advanced nodes squeeze regional operator margins.
- Platform as a Service:Abstracted runtime environments with managed middleware and database services. French and German enterprises adopt PaaS for AI workload deployment to satisfy EU AI Act explainability mandates without building internal MLops capabilities.
- Software as a Service:End-user applications delivered through browsers and mobile clients. Healthcare verticals in Amsterdam migrate analytics to regional sovereign SaaS zones to preempt Schrems III litigation exposure.
- Function as a Service:Event-driven serverless execution for microservices decomposition. Munich automotive manufacturers deploy factory-floor FaaS gateways for real-time quality control processing.
Platform as a Service captures the highest margins; Function as a Service climbs fastest as edge-native architectures proliferate.
End User:
Customer type determines procurement sophistication, with Large Enterprises driving volume through reserved-capacity contracts while Government Agencies introduce structurally distinct sovereign-cloud requirements.
- Large Enterprises:Complex multi-workload environments with dedicated cloud centers of excellence. Industrial digitization programs in Germany's Ruhr region anchor demand for GDPR-certified hybrid configurations.
- Government Agencies:Sovereign-cloud mandates with data localization and algorithmic transparency requirements. French public sector procurement now requires EU AI Act compliance certification for all AI-dependent cloud services.
- SMEs:Consumption-based metering preference with minimal internal platform engineering. Pay-per-query data warehouse pricing in Milan accelerates experimentation with specialized database engines.
- Startups:Cloud-native architectures with serverless-first development patterns. Berlin and Paris venture-backed firms leverage credits programs to offset early-stage infrastructure costs.
Large Enterprises dominate current volume; Government Agencies represent the steepest expansion trajectory as sovereign-cloud certification programs proliferate.
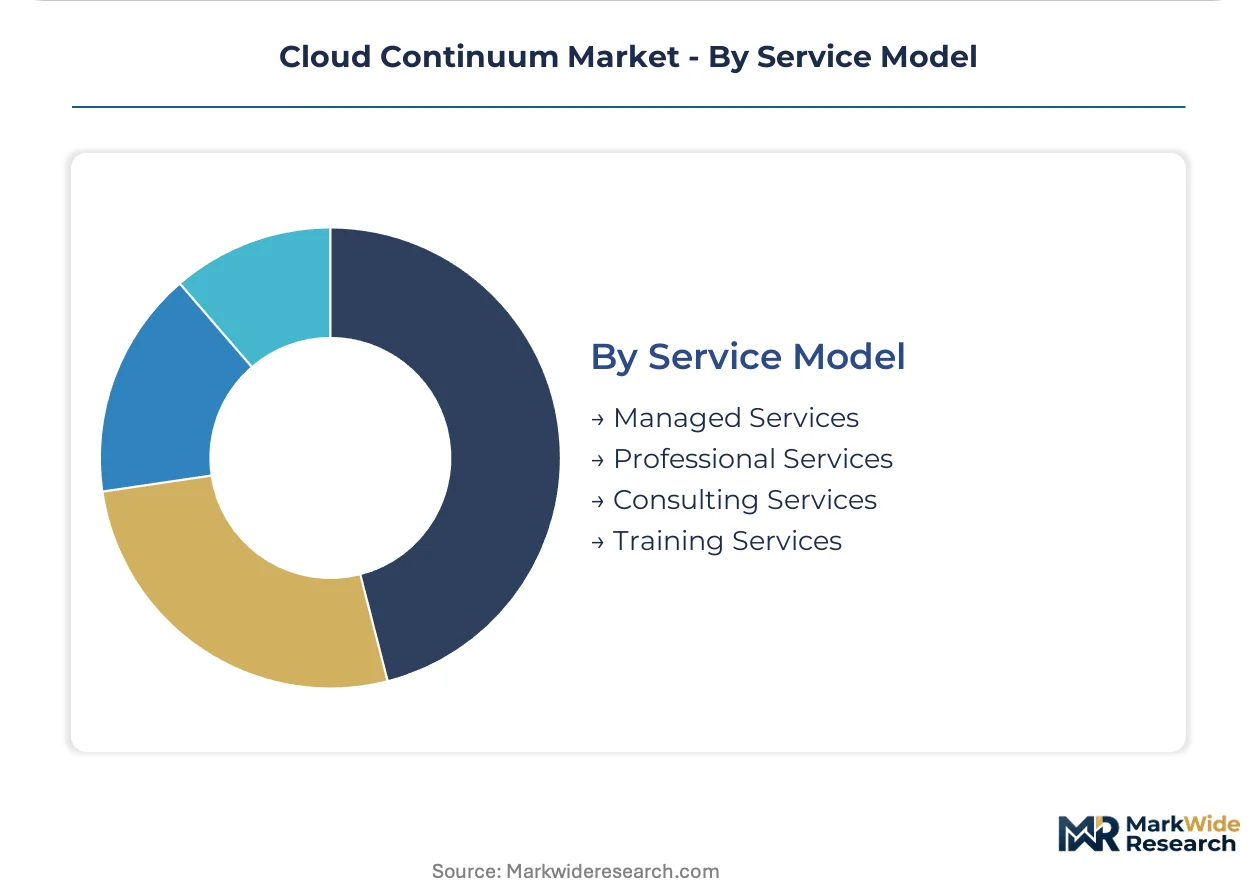
Service Model:
Maturity gradients separate established managed services from emerging consulting specializations, with site reliability engineering talent scarcity constraining delivery capacity across all tiers.
- Managed Services:Ongoing infrastructure operations and platform administration outsourced to provider or third party. ISO 27001 certification timelines of 12-18 months delay market entry for regional competitors against hyperscale incumbents.
- Professional Services:Implementation and migration project delivery. Kubernetes expertise shortages across European labor markets limit deployment velocity for multi-cloud strategies.
- Consulting Services:Architecture design and compliance roadmap development. EU AI Act readiness assessments drive demand from Frankfurt financial services firms.
- Training Services:Cloud certification and platform-specific skill development. Distributed systems observability and chaos engineering curricula address acute talent gaps in Stuttgart and Munich industrial corridors.
Managed Services anchors revenue stability; Consulting Services gains share fastest as regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France demonstrate low price elasticity as GDPR and EU AI Act compliance costs dominate procurement decisions, while mid-market enterprises in Spain and Italy exhibit higher sensitivity to per-workload pricing, driving consumption-based metering adoption.
Germany
Industrial digitization and strict data localization rules anchor demand for hybrid cloud configurations. The EU AI Act mandates algorithmic transparency for financial AI workloads, pushing Frankfurt banks toward sovereign cloud deployments. Stuttgart automotive manufacturers deploy plant-adjacent edge nodes to achieve sub-10 millisecond automation response thresholds.
France
French public sector procurement now requires EU AI Act compliance certification for all AI-dependent cloud services. CNIL enforcement of GDPR Article 44-49 transfer restrictions accelerates migration from standard contractual clauses to EU-approved certification schemes. Paris-based healthcare enterprises are migrating analytics workloads to regional sovereign zones to preempt Schrems III litigation exposure.
United Kingdom
Post-Brexit data adequacy negotiations create architectural uncertainty for transatlantic data flows. UK financial regulators impose NIST-aligned cybersecurity standards on cloud-dependent infrastructure. London's fintech cluster drives multi-cloud strategies to maintain EU market access while optimizing latency to domestic users.
Netherlands
Amsterdam data centers capture spillover demand from Frankfurt capacity constraints. The Dutch Authority for Personal Data enforces strict interpretation of GDPR territorial scope for non-EU cloud providers. Healthcare verticals in the Randstad region prioritize regional sovereign deployments to satisfy patient data residency requirements.
Poland
Katowice and Wrocław industrial zones lack sovereign cloud presence, creating first-mover opportunity for GDPR-certified regional deployments. Polish manufacturing firms exhibit high price elasticity, favoring pay-per-query consumption models over reserved-capacity contracts. The country's central IT regulator accelerates certification timelines for EU AI Act readiness.
Cloud Continuum Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Cloud Continuum Market. Hyperscale operators command infrastructure-layer pricing power through custom silicon and global fiber investments, while regional specialists compete on sovereign compliance and latency-optimized edge presence. Three archetypes dominate: vertically integrated hyperscalers with full-stack control, compliance-focused regional operators with certified sovereign facilities, and platform-agnostic orchestration vendors enabling multi-cloud abstraction. Competitive moves concentrate on strategic partnerships with industrial automation vendors and geographic expansion into underserved manufacturing corridors.
Among hyperscale infrastructure operators, Amazon Web Services, Microsoft, and Google Cloud occupy positions defined by differentiated control plane architectures. AWS exemplifies the custom silicon path with proprietary chip investments sustaining infrastructure margins. Microsoft anchors enterprise trust through productivity suite integration. Google Cloud represents the AI-optimized vector with tensor processing specialization. Regional compliance specialists include Equinix with interconnection-focused sovereign facilities, while Oracle and IBM occupy hybrid cloud archetypes bridging legacy enterprise workloads with cloud-native orchestration.
| Leading Market Players |
|---|
| Oracle |
| Alibaba Cloud |
| Amazon Web Services |
| VMware |
| Salesforce |
| Microsoft |
| IBM |
| Equinix |
| Google Cloud |
| Others |
Cost & Logistics Intelligence
Reserved-capacity contracts with three-year commit structures lock in supply access for Frankfurt financial services firms while capping price visibility against spot-market volatility in compute resources. Consumption-based metering is displacing these legacy arrangements across Barcelona and Milan mid-market enterprises, compressing provider revenue predictability while exposing buyers to algorithmic pricing swings.
Pricing Analysis
Managed service attach rates drive lifetime value for sovereign cloud deployments, with ISO 27001 certification premiums and sub-10 millisecond latency guarantees commanding substantial uplifts over commodity public cloud tiers. Price differentiation rests on compliance grade and edge proximity, with GDPR-certified facilities in Stuttgart extracting premiums over standard Frankfurt hyperscale capacity. Cost compression in raw Infrastructure as a Service is intensifying because custom AI accelerators from TSMC advanced nodes carry substantial premiums over commodity x86 architectures. Large Enterprises exhibit lowest price sensitivity due to regulatory compliance mandates, while Polish manufacturing SMEs demonstrate highest elasticity favoring pay-per-query consumption models.
Supply Chain Analysis
Extended lead times for EU AI Act certification audits stretch 12-18 months, constraining sovereign cloud provider market entry velocity against hyperscale incumbents with pre-certified facilities. Supply concentrates in Germany, France, and the Netherlands for GDPR-compliant data center capacity, while submarine cable landing stations in Cork, Bude, and Marseille create transatlantic bandwidth dependencies. Raw material and component inputs draw from specialized silicon foundries, fiber optic cable manufacturing, and precision cooling systems. Single-point-of-failure exposure at cable landing stations presents structural supply chain risk for cross-border data flows. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud Continuum adoption sits in early-cycle expansion as EU AI Act enforcement deadlines force architectural redesigns across European financial services and automotive verticals.
For Market Incumbents: Consolidate sovereign cloud certification portfolios through accelerated ISO 27001 audit pipelines and captive edge node deployments in underserved Polish manufacturing corridors. Regional specialist entrants with GDPR-native facilities threaten hyperscale market share in algorithmic transparency workloads. Vertical integration into custom silicon design preserves infrastructure-layer margins against TSMC pricing power. For New Entrants and Emerging Players: Anchor in Katowice and Wrocław industrial zones where sovereign cloud presence remains undeveloped and manufacturing automation demand concentrates. Poland's central IT regulator accelerates EU AI Act readiness timelines, creating first-mover structural advantage. Federated learning architectures with differential privacy techniques offer differentiated go-to-market positioning against centralized hyperscale AI training offerings. For Investors and Strategic Acquirers: Compliance-focused regional operators with certified sovereign facilities and established edge presence in Stuttgart or Munich industrial corridors represent priority acquisition targets. Long-term viability hinges on regulatory enforcement durability across GDPR Article 44-49 transfer restrictions and EU AI Act algorithmic transparency mandates. Watch for Schrems III litigation developments as inflection signal for sovereign cloud demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Acceleration | ISO 27001 and EU AI Act readiness compresses 12-18 month audit timelines for Frankfurt financial services procurement. |
| Edge Node Geographic Expansion | Plant-adjacent deployments in Stuttgart and Wolfsburg achieve sub-10 millisecond automation response thresholds. |
| Multi-Cloud Orchestration Platform Development | Kubernetes-native abstraction layers resolve policy consistency challenges across AWS, Azure, and Google Cloud control planes. |
| Green Cloud Procurement Alignment | CSRD disclosure rules favor Nordic hydro-powered facilities with verified renewable energy matching for Amsterdam healthcare verticals. |
| Federated Learning Architecture Investment | Differential privacy with edge aggregation enables cross-institutional AI training without raw data centralization under GDPR constraints. |
Research Approach
Operator-level perspectives from cloud infrastructure architects, sovereign compliance officers, and site reliability engineering directors anchored the qualitative base for this analysis. Primary interviews with procurement leads at German automotive manufacturers and French financial services firms combined with secondary validation from SEC hyperscaler capex disclosures, EU regulatory filings, and data center development databases. Bottom-up workload deployment modeling and top-down infrastructure spend analysis provided triangulation across the projection horizon.
Sensitivity analysis across deployment topology, solution abstraction layers, and end-user procurement sophistication shaped the analytical framework. Segmentation dimensions modeled include public-private-hybrid-multi-cloud configurations, IaaS-PaaS-SaaS-FaaS service tiers, and large enterprise-government-SME-startup customer archetypes. CAGRs derived from regression analysis against historic cloud infrastructure spend patterns and regulatory enforcement intensity indices. AI workload growth trajectories and sovereign certification program expansion rates served as industry-specific forecast inputs.
Material uncertainties — evolving cross-border data transfer mechanism rulings, submarine cable disruption events, and custom silicon cost volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement durability and enterprise migration velocity from legacy mainframe architectures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Cloud Managed Networking Market
Cloud Computing
Global Cloud Migration Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Nigeria Cloud Computing Market
Cloud Computing
Cloud Computing Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Public Cloud in BFSI Market
Cloud Computing
Global Cloud Business Email Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Serverless Computing Market
Cloud Computing
Europe AI Cloud Computing in Automotive Market