
 Europe Process Automation Market | 2026-2036
Europe Process Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Process Automation Market Foresight
The gap between premium integrated systems and commodity hardware is consolidating around software-defined architectures and edge analytics capabilities. Siemens AG leverages its digital twin portfolio to anchor high-margin automation suites across German process industries. ABB Ltd. competes through its Ability platform, sustaining R&D intensity in collaborative robotics and process optimization. Emerson Electric Co. differentiates via deep vertical specialization in valve automation and measurement instrumentation for European refineries.
Europe process automation encompasses the hardware, software, and control technologies that govern continuous and batch manufacturing operations through real-time data acquisition, closed-loop feedback, and distributed decision-making. Systems typically integrate field-mounted sensors with programmable controllers executing scan cycles measured in milliseconds to maintain pressure, temperature, and flow parameters within specified tolerances. Distributed Control Systems command the largest installed base among technology segments, reflecting decades of deployment in petrochemical complexes where fault tolerance and redundancy remain paramount. Cloud-based and edge deployments represent the fastest-expanding deployment categories as pharmaceutical manufacturers in Ireland and Switzerland pursue validated remote monitoring architectures that reduce on-site infrastructure.
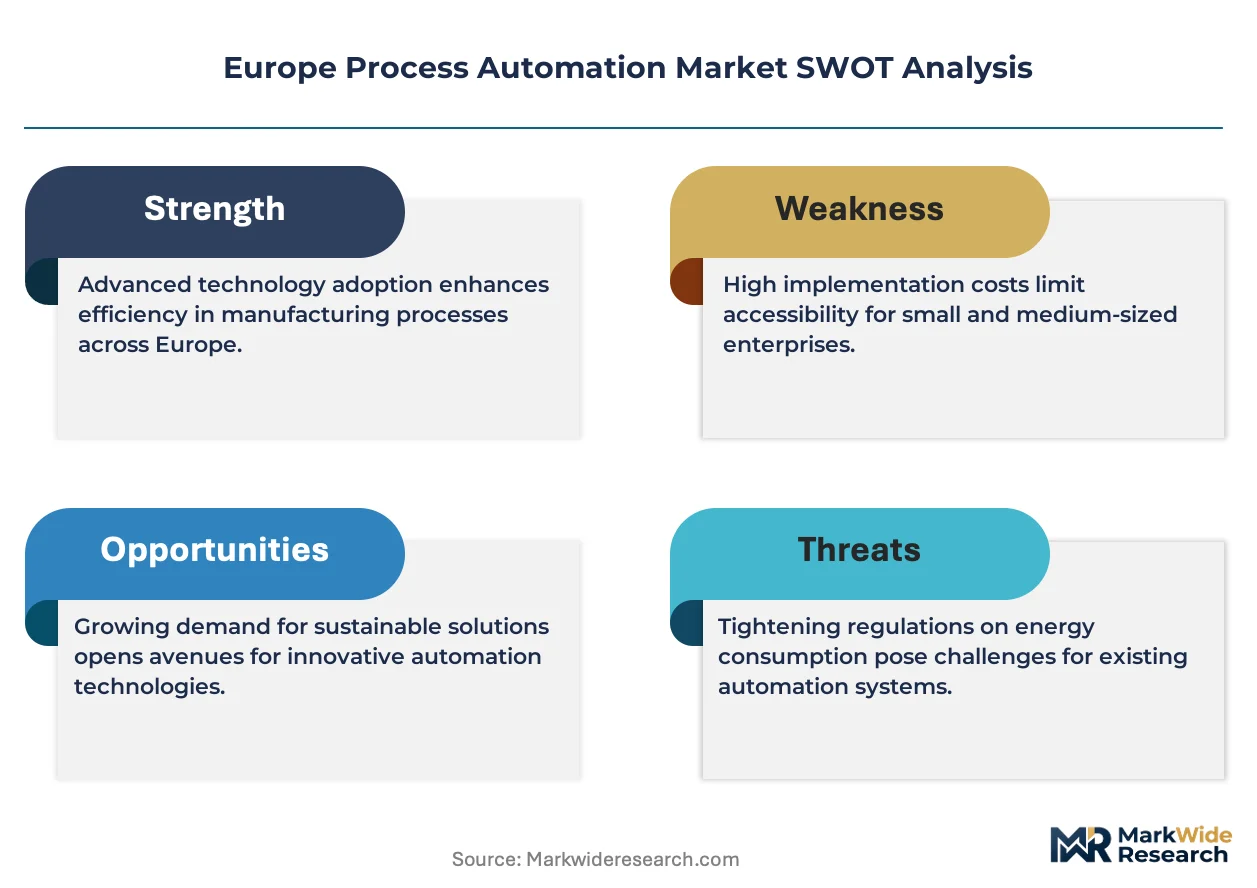
The EU Green Deal and F-Gas Regulation are reshaping equipment specifications, compelling vendors to certify energy efficiency and refrigerant containment across control valve and compressor product lines. EMA guidelines on computer system validation and the EU AI Act's risk-classification framework for automated decision-making are elevating compliance costs for pharmaceutical and medical device applications. Stakeholders must weigh the pace of edge-to-cloud migration against evolving cybersecurity standards under EN IEC 62443 before committing to multi-year automation roadmaps.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing equipment replacement cycles across European process industries, forcing vendors to redesign control architectures around energy efficiency and refrigerant containment mandates.
Growth Catalysts
- EU Green Deal mandates:Energy-efficiency certifications for control valves and compressors are compelling petrochemical operators in Germany and the Netherlands to accelerate retrofit investments.
- Pharmaceutical validation requirements:EMA guidelines on computer system validation are driving demand for cloud-based architectures with validated remote monitoring capabilities in Ireland and Switzerland.
- Edge analytics convergence:Real-time process optimization at the network edge is displacing centralized SCADA architectures in batch manufacturing facilities.
Market Restraints
- Semiconductor input volatility:Programmable logic controller production depends on specialized industrial chip supply concentrated in East Asian foundries.
- Technical debt in legacy DCS:Decades-old distributed control system installations in French refineries resist modular upgrade paths without full replacement.
- Cybersecurity compliance friction:EN IEC 62443 certification timelines extend procurement cycles for critical infrastructure operators.
Strategic Opportunities
- Polish chemical corridor expansion:Underpenetrated process automation density in Central European petrochemical clusters offers first-mover positioning for integrated platform vendors.
- EU AI Act risk classification:Automated decision-making systems in pharmaceutical manufacturing face new compliance tiers, creating consultative service revenue streams.
- Digital twin convergence:Physics-based simulation married with live operational data is opening predictive maintenance contracts in German automotive paint shops.
Industry Challenges
- OT-IT integration skill scarcity:Control engineers with simultaneous expertise in operational technology protocols and cloud-native architectures command premium compensation.
- Multi-vendor interoperability testing:Proprietary fieldbus standards from competing automation houses complicate brownfield system expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Process Automation Market |
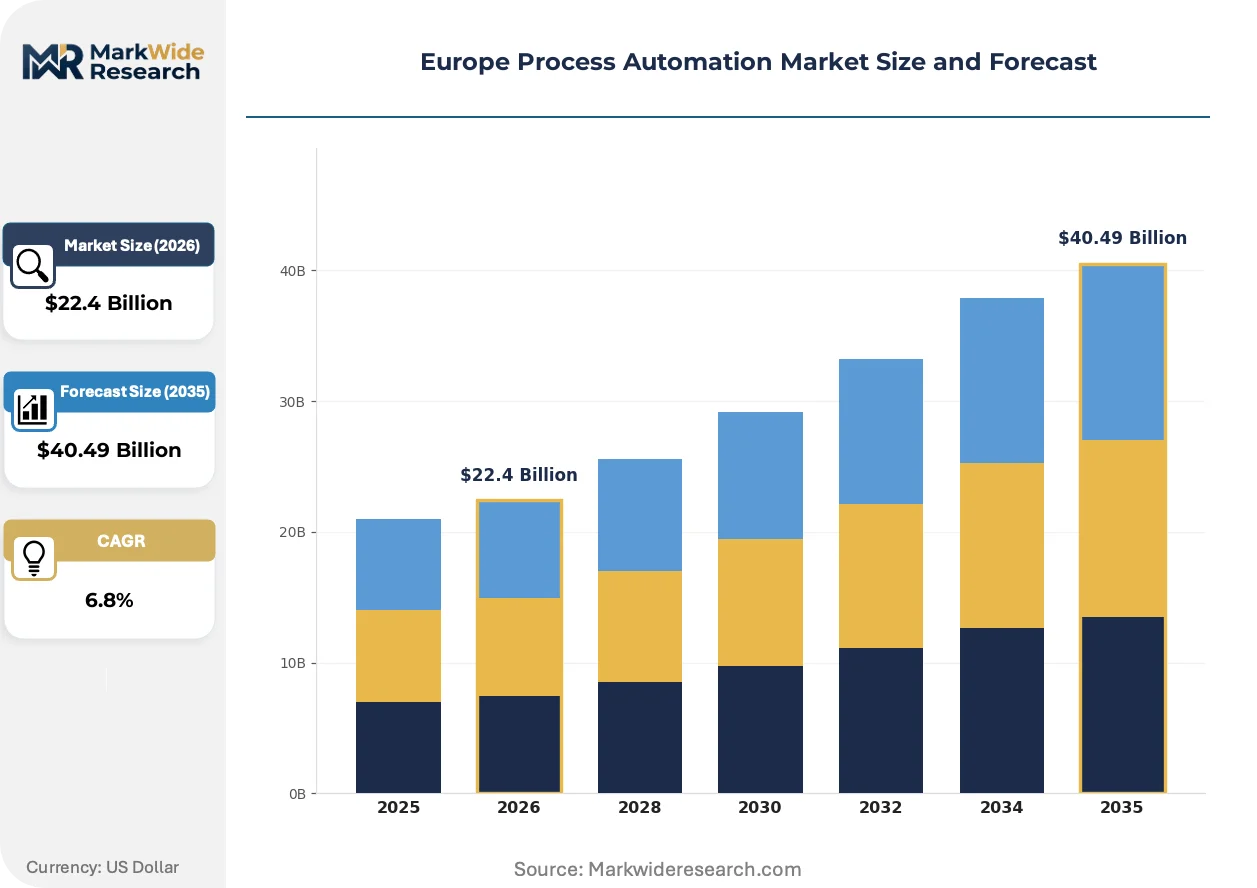
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $40.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controllers, Sensors, Software, Actuators Technology: Distributed Control Systems, SCADA, PLC, HMI End User: Manufacturing, Oil & Gas, Chemicals, Pharmaceuticals Deployment: On-premises, Cloud-based, Hybrid, Edge |
| Companies Covered | Emerson Electric Co., Rockwell Automation Inc., ABB Ltd., Mitsubishi Electric Corp., General Electric Co., Siemens AG, Honeywell International Inc., Yokogawa Electric Corp., Schneider Electric SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Process Automation Market Shifts & Advancements
Software-defined architectures are compressing the traditional hardware-software boundary in European process automation, with implications for vendor margin structures and buyer procurement patterns.
Edge-native control platforms are consolidating distributed intelligence at the production line level. Pharmaceutical manufacturers in Switzerland are deploying these systems to reduce latency in sterile filling operations. The shift is consolidating maintenance contracts around software subscriptions rather than hardware replacement cycles.
F-Gas Regulation phase-down schedules are mandating refrigerant containment monitoring across compressor control systems. Equipment vendors must now certify leak detection algorithms to maintain CE marking eligibility. Chemical processors in Belgium and France are prioritizing vendors with pre-validated compliance documentation.
Service unbundling is fragmenting traditional automation procurement. End-users in Dutch food processing are separating hardware acquisition from software licensing and ongoing optimization services. This pattern concentrates in sectors with mature internal engineering capabilities and compressed capital approval timelines.
Europe Process Automation Market Segmentation
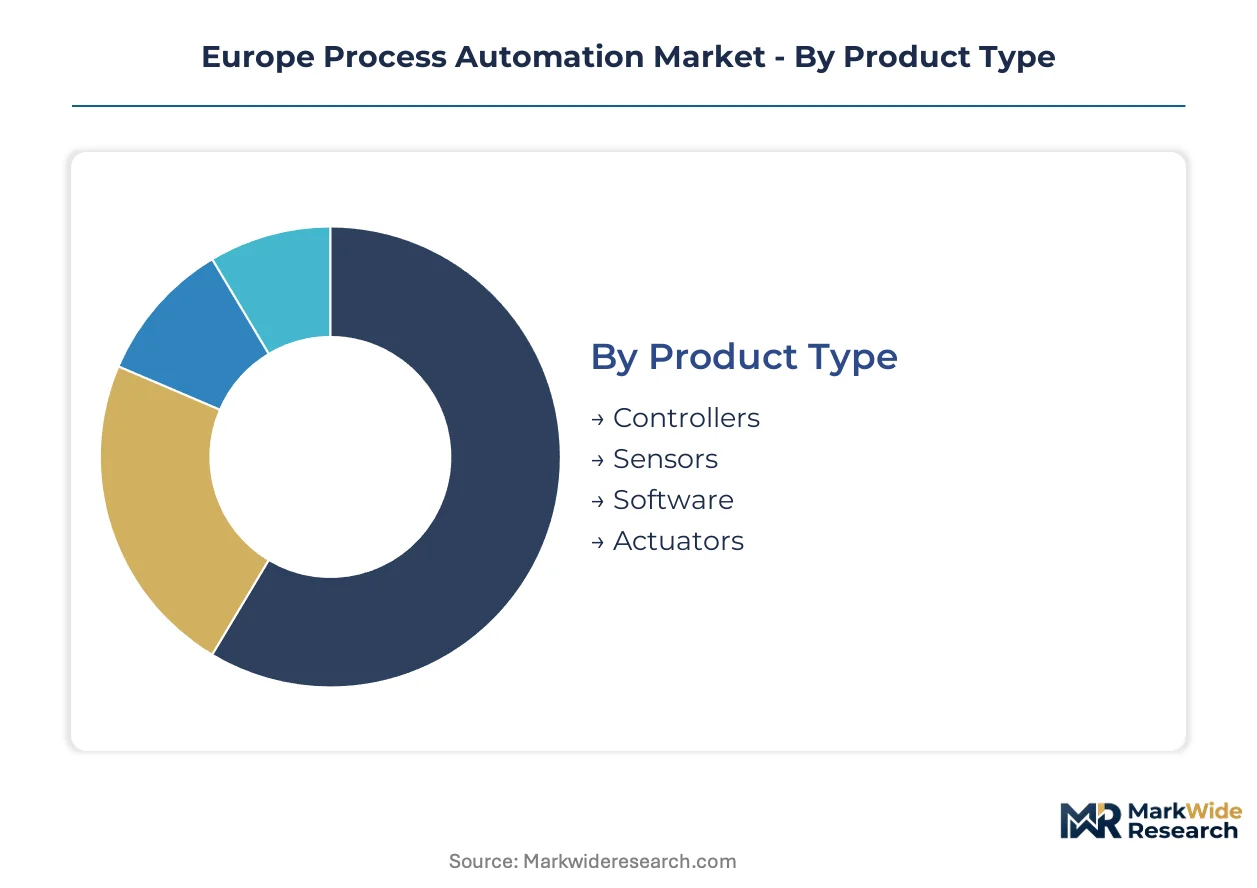
Process automation procurement in Europe fragments across certification regimes, with pharmaceutical and chemical end-users demanding CE-marked hardware and EMA-validated software architectures. Vendors must map product portfolios against these compliance tiers to capture retrofit cycles triggered by the EU Green Deal and F-Gas Regulation.
Product Type:
CE marking under the Machinery Directive and ATEX certification for explosive atmospheres divide this category, with sensors and controllers facing the heaviest conformity assessment burdens in German chemical clusters.
- Controllers:Programmable logic controllers and process automation controllers execute real-time control algorithms with scan cycles under 10 milliseconds. Demand concentrates in automotive paint shops across Bavaria and Baden-Württemberg, where Siemens and ABB platforms anchor production line retrofits driven by energy-efficiency mandates.
- Sensors:Pressure, temperature, and flow transmitters convert physical variables into 4-20 mA or digital fieldbus signals. Irish pharmaceutical manufacturers in Cork and Dublin are prioritizing vendors with pre-validated sensor calibration documentation to accelerate EMA computer system validation timelines.
- Software:Control platforms, digital twin environments, and predictive analytics suites require IEC 62443 cybersecurity certification for critical infrastructure deployments.
- Actuators:Electric and pneumatic valve positioners, motor drives, and robotic manipulators must demonstrate F-Gas Regulation compliance for refrigerant containment in compressor applications.
Leading the category by volume: Controllers. Growing fastest: Software.
Technology:
Deployment maturity spans four decades, with DCS installations in Rotterdam and Antwerp refineries representing sunk capital that resists modular replacement, while edge-native architectures attract greenfield investment in Swiss pharmaceutical facilities.
- Distributed Control Systems:Redundant, fault-tolerant architectures with dedicated controllers per process unit dominate continuous operations in petrochemical complexes. French refineries along the Seine and Rhône corridors maintain these systems despite vendor pressure to migrate toward hybrid architectures.
- SCADA:Supervisory control and data acquisition layers provide centralized visualization across geographically dispersed assets. Dutch natural gas distribution operators are replacing legacy SCADA with encrypted, cloud-connected alternatives to satisfy EN IEC 62443 security level requirements.
- PLC:Compact, rack-mounted controllers execute ladder logic and structured text for discrete and batch manufacturing. Belgian food processors favor modular PLC platforms with integrated safety functions.
- HMI:Touch panels, industrial PCs, and mobile operator interfaces require ergonomic certification under EU machinery directives for extended shift operations.
Dominating installed base: Distributed Control Systems. Expanding most quickly: SCADA with cloud backhaul.
End User:
Regulatory intensity varies sharply, with pharmaceutical and chemical sectors absorbing compliance costs that manufacturing and oil & gas operators can partially externalize through equipment leasing structures.
- Manufacturing:Automotive, electronics, and consumer goods production lines demand high-speed synchronization between robots, conveyors, and quality inspection systems. German OEMs in Stuttgart and Wolfsburg are consolidating supplier panels around vendors offering unified digital twin environments.
- Oil & Gas:Upstream platforms, midstream pipelines, and downstream refineries require explosion-proof equipment certified to ATEX and IECEx standards. North Sea operators face accelerated replacement cycles as aging North Sea infrastructure approaches end-of-design-life.
- Chemicals:Continuous and batch chemical processing demands precise temperature, pressure, and pH control with full batch records for regulatory traceability.
- Pharmaceuticals:Sterile manufacturing, active pharmaceutical ingredient synthesis, and packaging operations require validated automation with 21 CFR Part 11 electronic records compliance.
Generating highest absolute spend: Chemicals. Gaining share fastest: Pharmaceuticals.
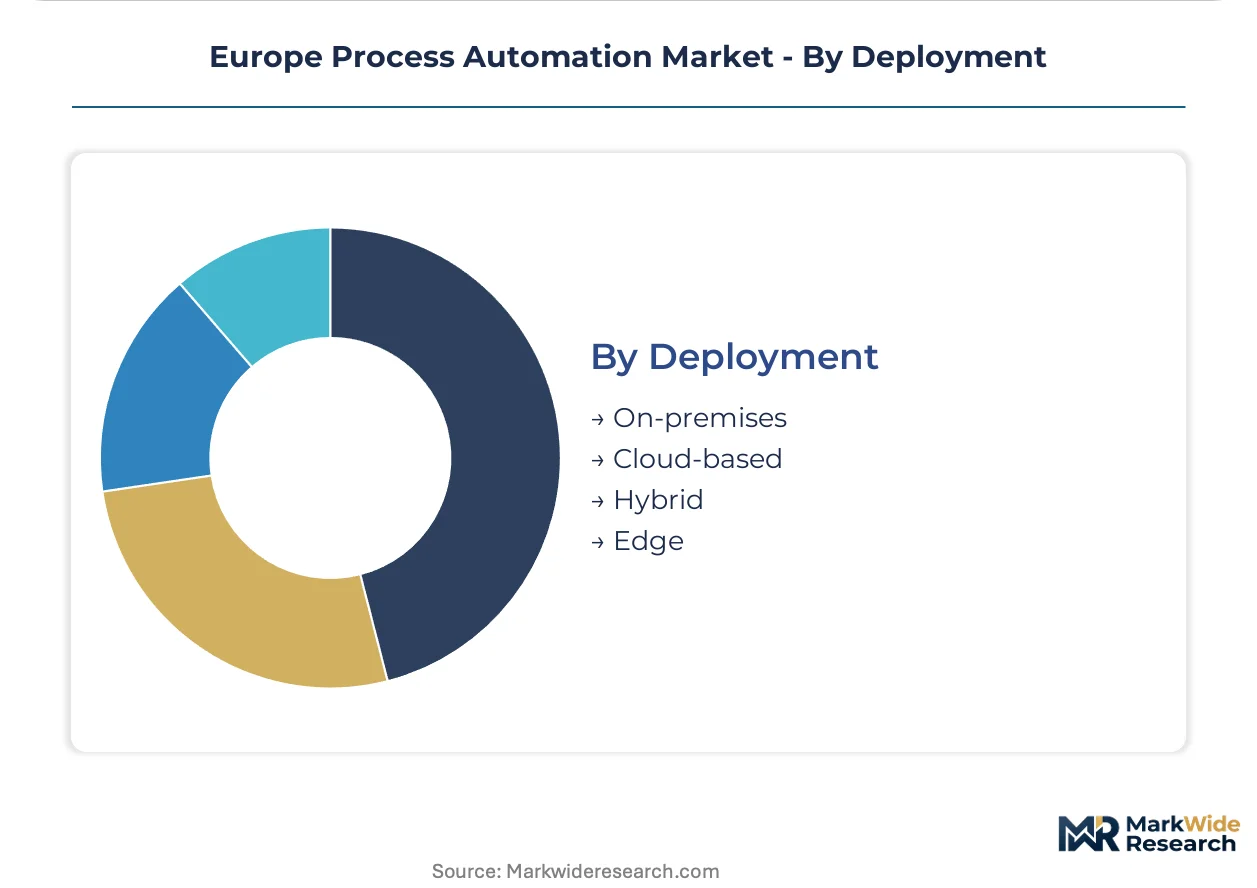
Deployment:
Capital availability and internal IT engineering maturity determine architecture selection, with hybrid and edge deployments commanding premium pricing in Switzerland and the Netherlands where cloud validation frameworks are most advanced.
- On-premises:Fully localized control infrastructure with no external network connectivity remains mandatory for certain defense and critical infrastructure applications. Polish chemical processors in Płock and Police retain on-premises DCS for intellectual property protection.
- Cloud-based:Control-as-a-service models with vendor-managed infrastructure reduce capital expenditure but require validated vendor qualification under EMA guidelines. Swiss pharmaceutical manufacturers in Basel lead European adoption of GxP-compliant cloud automation.
- Hybrid:Split architectures with time-critical control local and optimization analytics cloud-resident balance latency against computational scale.
- Edge:Containerized control applications running on industrial-grade compute nodes at the production line level minimize latency for vision-guided robotics and real-time quality feedback.
Retaining largest installed base: On-premises. Climbing the fastest: Edge-native deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European process automation demand, with German chemical clusters driving retrofit investments in energy-efficient control architectures. Industrial concentration across Northern Europe shapes procurement patterns, while regulatory fragmentation between member states creates compliance arbitrage opportunities for validated system vendors.
Germany
Automotive paint shops in Stuttgart and Wolfsburg demand high-speed synchronization between robots and quality inspection systems. The EU Green Deal mandates energy-efficiency certifications for control valves and compressors, compelling BASF and Bayer facilities in Ludwigshafen and Leverkusen to accelerate DCS replacement cycles.
Netherlands
Rotterdam-Antwerp petrochemical complexes maintain redundant distributed control systems despite vendor pressure toward hybrid architectures. F-Gas Regulation phase-down schedules force refrigerant containment monitoring retrofits across compressor control systems at Shell Pernis and Dow Terneuzen.
Switzerland
Basel pharmaceutical manufacturers lead European adoption of GxP-compliant cloud automation for sterile filling operations. Swissmedic validation requirements and EMA computer system validation guidelines drive demand for pre-calibrated sensor documentation at Novartis and Roche facilities.
France
Seine and Rhône corridor refineries resist modular DCS upgrades without full system replacement due to decades-old installations. ATEX certification requirements for explosive atmospheres dominate procurement criteria at TotalEnergies Dunkirk and ExxonMobil Fos-sur-Mer complexes.
Ireland
Pharmaceutical manufacturers in Cork and Dublin prioritize vendors with validated remote monitoring architectures to reduce on-site infrastructure. EMA guidelines on computer system validation compress vendor qualification timelines for Pfizer Ringaskiddy and Johnson & Johnson Limerick operations.
Europe Process Automation Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across European process automation, with integrated platform vendors facing pressure from specialized component suppliers. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with digital twin portfolios, pure-play automation specialists with deep vertical expertise, and emerging edge-native platform providers. Consolidation momentum concentrates in software-defined architectures, while partnership strategies dominate cloud validation and cybersecurity certification pathways.
Within the diversified industrial tier, Siemens AG and ABB Ltd. exemplify platform-scale positioning across German process industries. Emerson Electric Co. occupies a specialist position in measurement instrumentation and valve automation for European refinery applications. These three anchors represent contrasting approaches to compliance-heavy procurement environments, with each leveraging distinct geographic and technological footholds to defend margin structures against modular, service-unbundled competitors.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Rockwell Automation Inc. |
| ABB Ltd. |
| Mitsubishi Electric Corp. |
| General Electric Co. |
| Siemens AG |
| Honeywell International Inc. |
| Yokogawa Electric Corp. |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
The EU Green Deal energy-efficiency certification gates qualified supply access and premium-tier pricing power for control valve and compressor vendors serving German petrochemical operators. Buyers without validated compliance documentation face exclusion from BASF and Bayer procurement panels, compressing margins for commodity hardware suppliers while amplifying pricing leverage for certified platform vendors.
Pricing Analysis
Outcome-based pricing tied to production uptime and energy yield anchors premium-tier vendor contracts across Dutch refinery automation deployments. Pricing stratifies across CE-ATEX certified premium tiers, EMA-validated software tiers, and commodity hardware tiers, with certification level and after-sales service bundling as primary differentiation drivers. Cost compression in the commodity controller tier intensifies because East Asian semiconductor supply volatility erodes margin buffers. Small Polish chemical processors exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers demonstrate lowest sensitivity due to GxP compliance imperatives.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Milan orchestrate hub-and-spoke patterns for spare parts and controller modules across European process clusters. Manufacturing concentrates in Germany, Switzerland, and the Netherlands for precision instrumentation, while Taiwan and South Korea supply specialized industrial semiconductors for PLC production. Supply chain risk hinges on single-source vulnerability for advanced process node chips. Distribution runs through authorized system integrators with certified technician networks for ATEX-compliant installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge-native control platforms are displacing centralized SCADA architectures across European pharmaceutical and chemical facilities, compressing the window for legacy system monetization. Incumbents and entrants must calibrate positioning around this transition phase.
For Market Incumbents: Extend digital twin subscription models to capture recurring revenue from German automotive paint shop retrofits. Consolidate position through backward integration into edge hardware manufacturing to offset semiconductor supply risk. Prioritize EN IEC 62443 certification investment to defend against modular, service-unbundled competitors penetrating Dutch food processing accounts. For New Entrants and Emerging Players: Cloud-native validation partnerships offer the most penetrable route for GxP-compliant pharmaceutical automation in Ireland and Switzerland. Target underpenetrated Polish chemical corridor expansions with pre-configured, CE-marked controller bundles. Pursue direct-to-plant-engineer digital channels to bypass incumbent system integrator gatekeeping. For Investors and Strategic Acquirers: First-mover cloud validation agreements with Swissmedic and EMA are the leading indicator that edge-native platform vendors will capture disproportionate pharmaceutical spend. Long-term viability favors asset-light software architects with validated compliance documentation over capital-intensive hardware producers. Monitor F-Gas Regulation enforcement intensity as the inflection signal for compressor control system replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Platform Launch | Containerized control applications at the production line level displace centralized SCADA in Swiss sterile filling operations. |
| Digital Twin Integration | Physics-based simulation married with live operational data opens predictive maintenance contracts in German automotive facilities. |
| EN IEC 62443 Certification Pathway | Cybersecurity compliance investment extends procurement cycle capture for critical infrastructure operators in the Netherlands. |
| Backward Integration into Edge Hardware | In-house production of industrial compute nodes insulates margin structures from East Asian semiconductor supply volatility. |
| EMA Validation Partnership | Pre-qualified cloud architectures accelerate vendor onboarding timelines for Pfizer and Johnson & Johnson Irish operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plant engineers, automation procurement leads, system integrators, and aftermarket service heads across German, Dutch, and Swiss industrial clusters. Bottom-up triangulation against Cefic chemical production statistics, EMA computer system validation guidance documents, and SEC 10-K automation vendor disclosures validated volume estimates. Top-down reconciliation with EU Green Deal implementation timelines and F-Gas Regulation phase-down schedules cross-checked demand assumptions.
Data-stream reconciliation across shipment volumes, installed base surveys, and replacement cycle indicators informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user industry, and deployment mode, with regulatory compliance tier and cloud validation status as industry-specific stratifiers. CAGRs derived from regression analysis against energy-efficiency mandate implementation curves and pharmaceutical capital expenditure patterns, incorporating semiconductor supply elasticity assumptions for controller production constraints.
The model holds under steady EU regulatory enforcement and stable East Asian semiconductor supply; deviation in trade policy or F-Gas Regulation acceleration would shift replacement cycle timing. Forecasts reflect documented assumptions regarding cloud validation adoption rates and cybersecurity compliance timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
UV Curing System Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
United States Factory Automation and Industrial Controls Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Conveyor-Free Sortation Modules Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Embedded Automation Computers Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
India Warehouse Automation Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Material Handling Robotics Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Smart Escalator Market