
 Public Cloud Application Services Market | 2026-2036
Public Cloud Application Services Market Size, Share, and Industry Trends Forecast 2026-2036
Public Cloud Application Services Market Outlook
The EU Corporate Sustainability Reporting Directive is repositioning procurement criteria for cloud services across European enterprises. Amazon Web Services anchors its competitive stance through massive renewable energy commitments powering data center expansion. Microsoft Azure leverages deep enterprise relationships to sustain hybrid cloud deployment momentum. Google Cloud Platform differentiates through AI-optimized infrastructure targeting specialized analytics workloads.
Public Cloud Application Services encompass on-demand software delivery, development platforms, and infrastructure resources accessed via internet protocols with service-level agreements guaranteeing availability, latency, and throughput parameters. These services eliminate capital expenditure on physical hardware while enabling elastic scaling of compute, storage, and application logic based on real-time demand fluctuations. Software as a Service retains the largest revenue share among service types due to its subscription accessibility for non-technical users. Platform as a Service captures expanding margins as developers demand pre-configured environments for containerized application deployment. Multi-tenant deployment models dominate operational economics through shared resource utilization, though single-tenant configurations persist in regulated sectors requiring data isolation.
ISO 27001 certification requirements and the EU AI Act are tightening data governance and algorithmic transparency standards for cloud providers serving European enterprises. The US SEC cybersecurity disclosure rules are compelling publicly traded customers to scrutinize vendor risk management practices before contract execution. India's Digital Personal Data Protection Act is establishing localization mandates that influence regional data center investment patterns. Stakeholders must evaluate how evolving cross-border data flow restrictions will reshape service architecture decisions and geographic redundancy strategies.
Market Dynamics
Enterprise migration from on-premise ERP to SaaS platforms is compressing deployment cycles while forcing providers to absorb integration complexity that previously fell on customer IT departments.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements are accelerating procurement of cloud-native governance tools among European financial services and healthcare providers.
- Container orchestration maturation:Kubernetes-native platforms are displacing lift-and-shift migrations, pulling enterprise developers toward pre-configured deployment environments.
- India's legacy ERP replacement wave:Manufacturing and retail conglomerates are retiring on-premise SAP and Oracle systems for subscription-based alternatives, concentrating demand in Mumbai and Bangalore.
Market Restraints
- Cross-border data localization:India's Digital Personal Data Protection Act and comparable mandates in Indonesia and Vietnam are fragmenting architectural decisions and duplicating infrastructure investment.
- Specialized talent scarcity:Cloud security architecture and FinOps disciplines command 40-60% wage premiums in secondary technology markets, constraining mid-market adoption velocity.
- Energy input cost volatility:Data center power purchase agreements face renegotiation pressure as renewable energy certificate markets tighten in Germany and Texas.
Strategic Opportunities
- Healthcare AI inference at the edge:Federated learning deployments for diagnostic imaging are creating demand for distributed cloud nodes that process PHI without centralization.
- ISO 27701 certification gaps:Privacy information management systems remain underdeployed among mid-tier SaaS vendors, opening differentiation pathways for early certifiers.
- Carbon-aware workload scheduling:Temporal shifting of compute to low-carbon intensity hours is converging with spot pricing mechanisms to create new procurement optimization layers.
Industry Challenges
- Multi-cloud FinOps complexity:Enterprise buyers struggle to attribute costs across AWS, Azure, and GCP environments, delaying governance tool procurement decisions.
- Legacy mainframe interconnection:Financial institutions in Frankfurt and Singapore face 18-24 month integration timelines to bridge core banking systems with modern API gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Cloud Application Services Market |
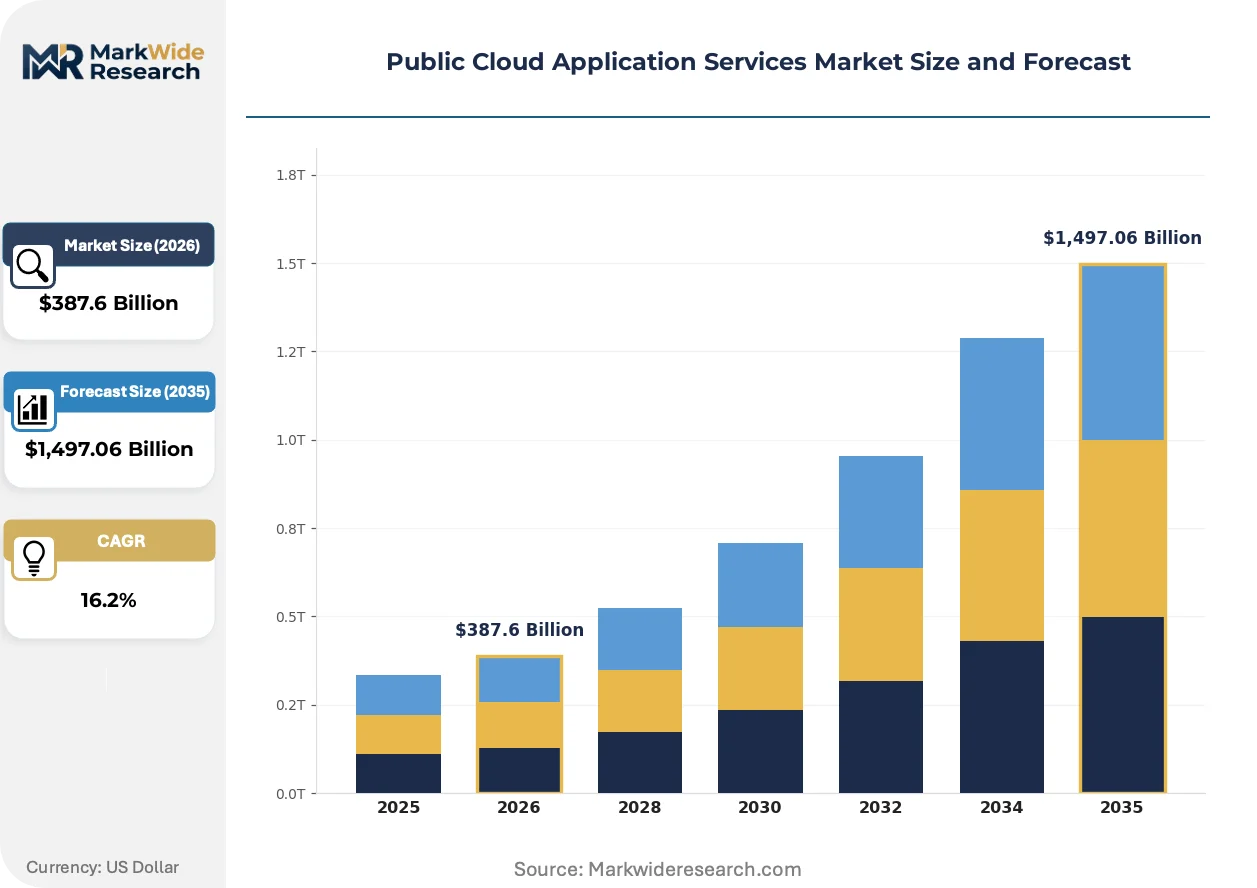
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,497.06 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service End User: Small Businesses, Enterprises, Government Agencies, Educational Institutions Deployment Model: Single-Tenant, Multi-Tenant, Hybrid Cloud, Community Cloud Integration Level: API Integration, Cloud-Native, Third-Party Solutions, Legacy Systems |
| Companies Covered | Microsoft Azure, Amazon Web Services (AWS), Google Cloud Platform, Oracle Cloud Infrastructure, Salesforce, SAP, ServiceNow, IBM Cloud, Alibaba Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Cloud Application Services Market Strategic Shifts
Platform engineering disciplines are displacing traditional DevOps organizations, embedding infrastructure-as-product capabilities directly into application teams and compressing the boundary between development and operations functions.
WebAssembly runtime environments are unifying serverless and container execution models, enabling healthcare and fintech developers to deploy portable modules across edge and hyperscale locations without recompilation. Hospital systems in the Netherlands and insurance carriers in Switzerland are piloting these workloads for claims processing automation. This convergence is collapsing the distinction between function-as-a-service and microservice architectures, forcing platform providers to consolidate pricing and SLA structures.
The EU Corporate Sustainability Reporting Directive is mandating granular emissions disclosure from cloud procurement, compelling Frankfurt and Amsterdam-based enterprises to demand hourly carbon intensity data from their providers. Scope 3 reporting requirements are filtering down through supply chains, affecting mid-market SaaS vendors who previously lacked measurement infrastructure. Financial services clusters in Luxembourg and Dublin are responding fastest, embedding sustainability criteria into RFP scoring matrices ahead of 2025 filing deadlines.
Consumption-based contracts are displacing committed-use discounts as the dominant enterprise procurement mechanism, particularly among retail and logistics buyers facing demand volatility. Annual upfront commitments are giving way to monthly true-up arrangements with tiered rate cards. This pattern is most pronounced in India, where e-commerce platforms and third-party logistics providers prioritize elasticity over rate predictability during festival-season demand spikes.
Public Cloud Application Services Market Segmentation
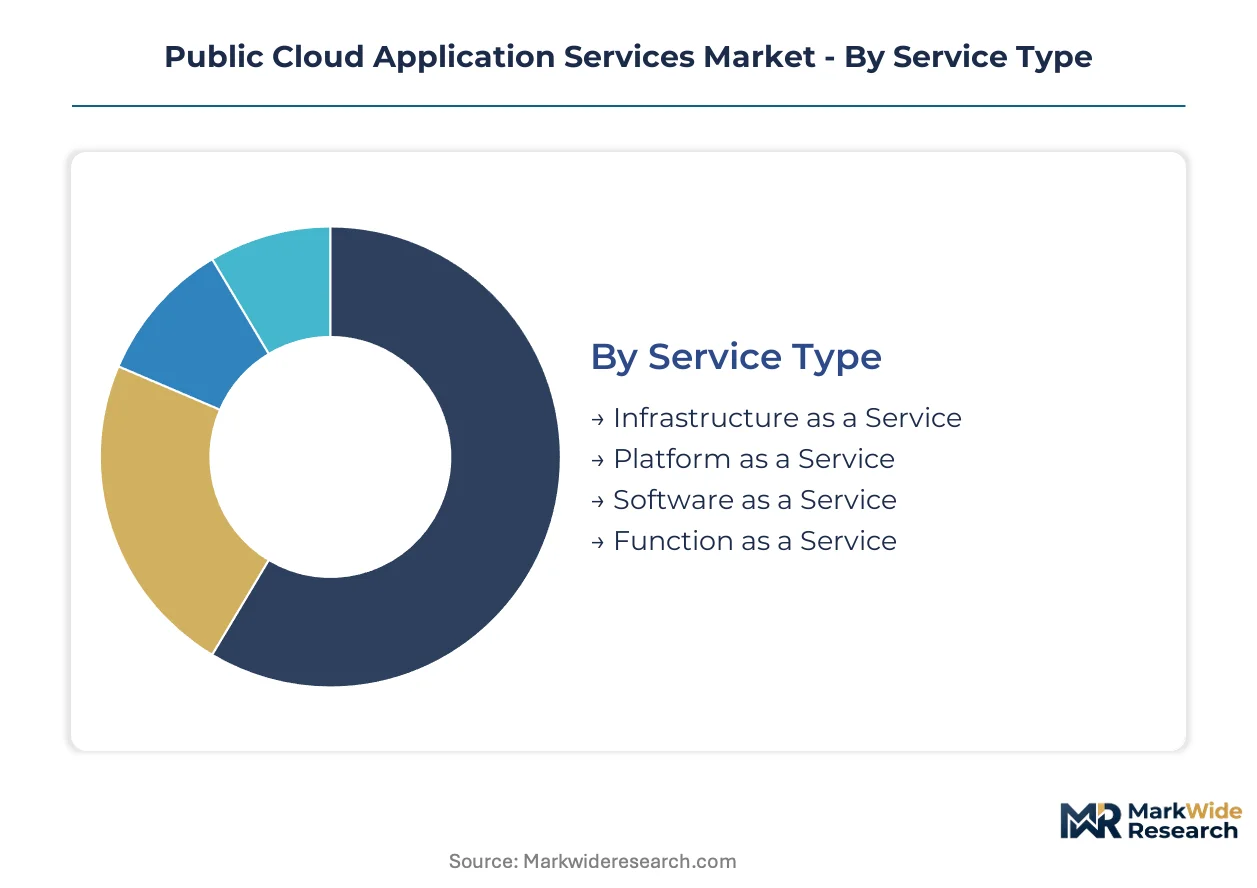
Cloud procurement decisions hinge on workload characteristics, compliance posture, and integration complexity rather than uniform platform selection. Buyers evaluate service tiers against data sovereignty requirements, legacy system interdependencies, and developer velocity targets. Segmentation reveals where margin concentrates and which architectural patterns are displacing incumbent deployment models.
Service Type:
Enterprise buyers select service tiers based on technical ownership boundaries and capital efficiency targets, trading control for speed.
- Software as a Service:Pre-configured applications delivered through subscription licensing eliminate infrastructure management overhead. Healthcare providers in Germany and retail conglomerates in India are consolidating patient management and ERP workloads here, prioritizing rapid deployment over customization depth.
- Platform as a Service:Managed runtime environments abstract container orchestration and middleware configuration from development teams. Kubernetes-native platforms are pulling financial services developers in Singapore and the Netherlands toward pre-configured deployment stacks, displacing self-managed infrastructure.
- Infrastructure as a Service:Raw compute, storage, and networking resources provisioned through APIs retain appeal for workloads requiring fine-grained control over hardware specifications.
- Function as a Service:Event-driven execution models charge per invocation rather than provisioned capacity, suiting intermittent batch processing and IoT data ingestion pipelines.
Software as a Service leads on scale; Platform as a Service leads on momentum.
End User:
Organizational scale determines procurement sophistication, contract structure, and governance tooling requirements.
- Enterprises:Multi-divisional organizations with centralized procurement functions negotiate enterprise licensing agreements spanning thousands of seats. Manufacturing conglomerates in Mumbai and Bangalore are retiring on-premise SAP systems for subscription alternatives, concentrating demand volume.
- Small Businesses:Resource-constrained organizations prioritize per-seat pricing and minimal configuration overhead. Local retail networks and professional services firms across secondary Indian cities favor month-to-month arrangements without committed-use discounts.
- Government Agencies:Public sector buyers mandate ISO 27001 certification and data residency guarantees, often requiring single-tenant isolation.
- Educational Institutions:Universities and research organizations leverage academic pricing tiers and grant-funded procurement mechanisms for research computing workloads.
Enterprises dominate absolute spend; Small Businesses are expanding most quickly as self-service onboarding tools mature.
Deployment Model:
Data isolation requirements and regulatory jurisdiction shape architectural decisions more than cost optimization alone.
- Multi-Tenant:Shared infrastructure pools deliver operational efficiency through resource overcommitment and automated scaling. SaaS providers serving European SMEs rely on this model to maintain competitive unit economics under CSRD disclosure pressure.
- Single-Tenant:Dedicated environments satisfy data sovereignty mandates and audit requirements in regulated sectors. Swiss insurance carriers and Frankfurt-based financial institutions specify this architecture for claims processing and core banking workloads.
- Hybrid Cloud:Split workloads between on-premise infrastructure and public cloud resources, preserving latency-sensitive operations locally.
- Community Cloud:Shared infrastructure restricted to specific industry verticals or regulatory frameworks, common among healthcare consortiums.
Multi-Tenant leads on scale; Single-Tenant leads on momentum as localization mandates proliferate.
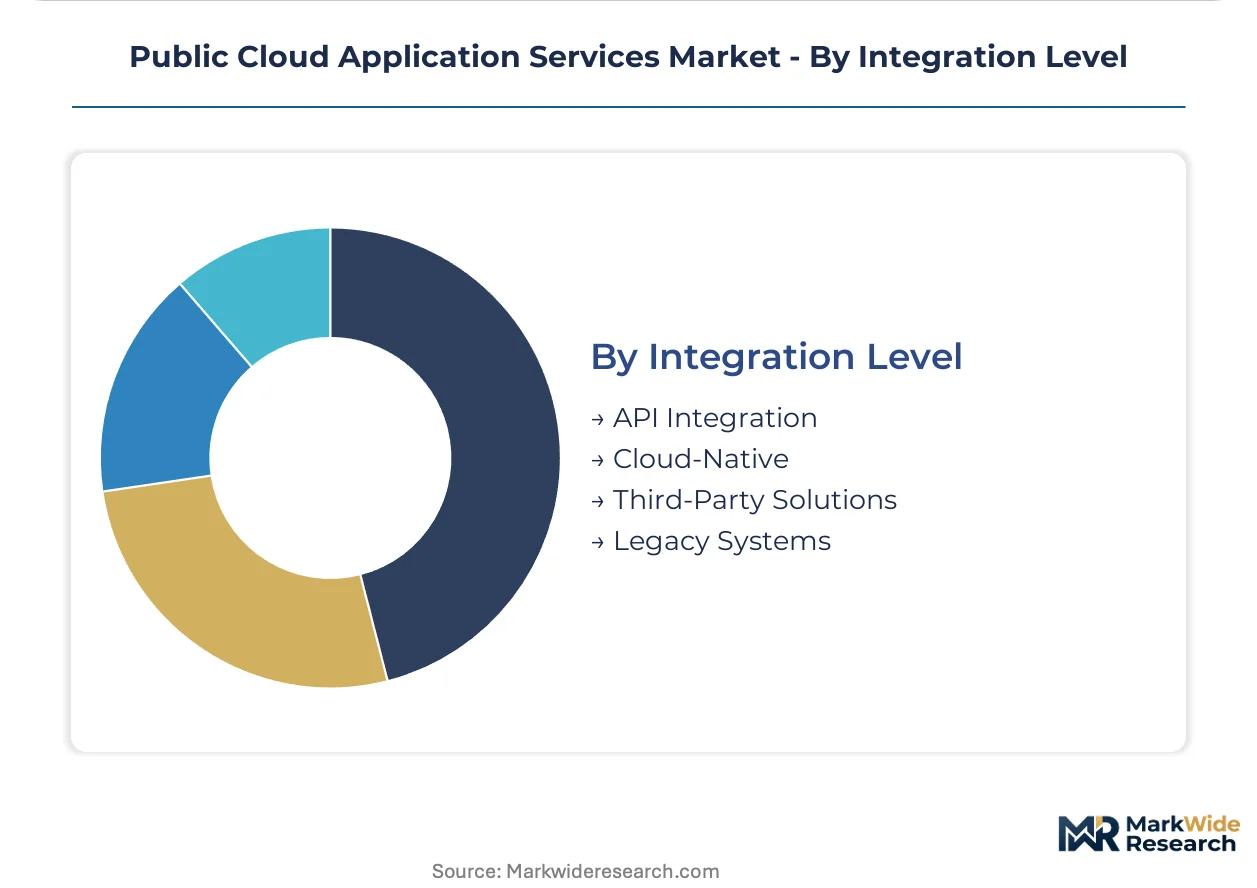
Integration Level:
Legacy system entanglement and developer skill availability determine migration pathway selection.
- API Integration:REST and GraphQL connectivity layers bridge modern cloud services with incumbent systems. Logistics platforms in Rotterdam and e-commerce operators in Bangalore deploy these interfaces to synchronize warehouse management with customer-facing applications.
- Cloud-Native:Microservices architectures built on managed Kubernetes and serverless functions maximize elasticity. Fintech developers in Singapore favor this pattern for payment processing workloads requiring sub-second scaling.
- Third-Party Solutions:Pre-built connectors and integration-platform-as-a-service tools reduce custom development for common enterprise applications.
- Legacy Systems:Direct mainframe and COBOL environment interconnection persists where replacement timelines extend across multiple budget cycles.
API Integration leads on scale; Cloud-Native leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud architects and DevOps specialists cluster in Seattle, Bangalore, and Frankfurt, anchoring regional delivery capacity for hyperscale deployments.
United States
Enterprise SaaS procurement concentrates among Fortune 500 manufacturers and healthcare networks migrating Epic and Cerner workloads to cloud-native environments. The SEC cybersecurity disclosure rules compel publicly traded buyers to scrutinize vendor risk management practices before contract execution. Seattle and Northern Virginia host the densest concentrations of data center investment, with power purchase agreements now incorporating hourly carbon intensity tracking.
Germany
Automotive OEMs and industrial machinery producers demand ISO 27001-certified platforms for connected vehicle data and predictive maintenance workloads. The EU AI Act and CSRD disclosure mandates reshape procurement criteria, requiring algorithmic transparency documentation from cloud providers. Frankfurt anchors financial services migration, with Commerzbank and Deutsche Börse specifying single-tenant architectures for core banking systems.
India
Manufacturing conglomerates in Mumbai and Bangalore retire on-premise SAP and Oracle ERP systems for subscription-based alternatives, concentrating demand volume. The Digital Personal Data Protection Act establishes localization mandates that influence regional data center investment patterns from Microsoft and Amazon. Hyderabad and Pune emerge as secondary hubs where mid-market enterprises prioritize month-to-month arrangements without committed-use discounts.
Singapore
Wealth management platforms and commodity trading houses require sub-second latency for algorithmic execution, pulling fintech developers toward managed Kubernetes environments. The Monetary Authority of Singapore's technology risk management guidelines enforce granular vendor oversight for systemically important financial institutions. Marina Bay and Changi Business Park host specialized cloud nodes processing cross-border payment flows between ASEAN markets and European clearinghouses.
Switzerland
Private banking groups and reinsurance carriers mandate data residency guarantees for client portfolio analytics and claims processing automation. Swissmedic and FINMA oversight frameworks require audit trails demonstrating PHI isolation for healthcare AI inference workloads. Zurich and Geneva clusters pilot federated learning deployments for diagnostic imaging, processing sensitive data without centralization to centralized hyperscale facilities.
Public Cloud Application Services Market Competitive Environment
Capital-heavy infrastructure operators compete with asset-light platform developers for enterprise wallet share, creating a tiered structure where hyperscale providers absorb fixed costs while specialized vendors capture niche margins. The vendor base separates into three strategic archetypes: full-stack hyperscalers owning silicon-to-software integration, vertical SaaS specialists embedding industry-specific compliance logic, and regional champions leveraging data sovereignty mandates. Dominant competitive moves include renewable energy-powered capacity expansion and strategic partnerships bridging legacy mainframe environments with modern API gateways.
Among hyperscale infrastructure providers, Microsoft Azure, Amazon Web Services, and Google Cloud Platform exemplify the capital-intensive archetype, each anchoring distinct competitive vectors through enterprise relationship depth, renewable energy commitments, and AI-optimized hardware configurations respectively.
| Leading Market Players |
|---|
| Microsoft Azure |
| Amazon Web Services (AWS) |
| Google Cloud Platform |
| Oracle Cloud Infrastructure |
| Salesforce |
| SAP |
| ServiceNow |
| IBM Cloud |
| Alibaba Cloud |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ISO 27701-certified hyperscalers and uncertified mid-tier SaaS vendors manifests in both contract premiums and data center investment patterns across Germany and India. European financial services buyers absorb higher per-seat costs for single-tenant architectures while Indian e-commerce platforms prioritize spot-priced multi-tenant capacity during festival demand spikes.
Pricing Analysis
Bundled enterprise licensing agreements encompassing compute, storage, and governance tooling command premium positioning against unbundled per-service procurement. Pricing stratifies across dedicated single-tenant, reserved multi-tenant, and spot-priced consumption tiers, with ISO 27001 certification and data residency guarantees as primary differentiation drivers. Cost compression in reserved capacity pools is intensifying because hyperscalers renegotiate renewable energy purchase agreements in Texas and Germany. Small businesses in secondary Indian cities exhibit highest price sensitivity, while Frankfurt-based financial institutions prioritize compliance over unit cost.
Supply Chain Analysis
Cloud security architecture and FinOps specialist scarcity in Bangalore, Hyderabad, and Pune constrains delivery velocity for mid-market deployments. Infrastructure provisioning draws from Taiwan for advanced silicon, Ireland for EU data center equipment, and domestic Indian manufacturing for edge node assembly. Single-source vulnerability in specialized GPU supply chains for AI training workloads threatens capacity expansion timelines. Distribution runs through direct hyperscaler sales organizations for enterprise accounts and self-service portals for small business acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in governance-tooling premiums and carbon-aware workload arbitrage as buyers absorb compliance-driven cost premiums. Renewable energy certificate markets and spot pricing convergence create new pricing power layers for infrastructure operators.
For Market Incumbents: Deepen vertical integration into renewable energy generation to lock in power purchase agreement rates ahead of certificate market tightening in Germany and Texas. Expand ISO 27701 certification coverage across mid-tier SaaS portfolios before EU AI Act disclosure mandates harden procurement criteria. Container orchestration platform consolidation represents the primary substitution threat requiring defensive capability investment. For New Entrants and Emerging Players: Kubernetes-native governance tooling for EU AI Act compliance presents the most penetrable white-space target among European financial services and healthcare providers. Carbon-aware workload scheduling algorithms for spot market arbitrage offer second-mover advantage in retail and logistics verticals. Partner with established hyperscaler marketplaces to bypass direct enterprise sales cycle complexity. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier SaaS vendors lack ISO 27701 certification infrastructure ahead of CSRD disclosure deadlines. Long-term viability favors platforms with embedded compliance logic and renewable energy contract structures. Watch for inflection in hyperscaler capital expenditure guidance toward edge node deployment as federated learning adoption accelerates in Swiss and Dutch healthcare systems.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27701 Certification Investment | Privacy management certification opens differentiation pathways ahead of EU AI Act enforcement. |
| Renewable Energy Power Purchase Agreement | Long-term clean energy contracts anchor carbon disclosure compliance for CSRD-mandated European buyers. |
| Kubernetes-Native Platform Launch | Pre-configured container environments displace self-managed infrastructure among Singapore fintech developers. |
| Single-Tenant Architecture Expansion | Dedicated environments satisfy Swiss FINMA and German BaFin data isolation requirements for core banking. |
| Carbon-Aware Workload Scheduling | Temporal compute shifting converges with spot pricing to create procurement optimization for Indian e-commerce platforms. |
Study Parameters
Bottom-up enterprise workload modeling reconciled against top-down hyperscaler capacity tracking forms the analytical core of this study. Primary interviews with cloud architects, IT procurement officers, platform engineers, and compliance officers at healthcare networks and financial institutions across Germany, India, Singapore, Switzerland, and the United States combined with secondary validation from SEC filings, hyperscaler capital expenditure disclosures, EU regulatory filings, and ISO certification databases. Triangulation between demand-side deployment timelines and supply-side infrastructure investment patterns ensures cross-verification of market sizing assumptions.
Input-output matrices map service type, deployment model, and integration complexity against end-user scale and regional regulatory frameworks across the analysis window. Segmentation dimensions include organization size tier, vertical industry, data sovereignty requirements, and legacy system interdependency. CAGRs derive from regression analysis of historical migration velocity and projected ERP replacement cycles, with specific weighting for India's Digital Personal Data Protection Act localization mandates and EU AI Act compliance tooling demand.
The model holds under stable cross-border data flow regimes and renewable energy certificate market liquidity; deviation in tariff escalation or carbon accounting rule changes would shift infrastructure investment patterns and pricing trajectories. Forecasts reflect documented assumptions regarding enterprise SaaS migration velocity and hyperscaler margin structures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Server Virtualization Market
Cloud Computing
Cloud ELN Service Market
Cloud Computing
Data Virtualization Cloud Market
Cloud Computing
Cloud Integration Software Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
Global Cloud Collaboration Market
Cloud Computing
Cloud Management Market
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Virtual Machines Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Community Cloud Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Platform As a Service (Paas) Market
Cloud Computing
Cloud IDE Market