
 Cloud ECS Market | 2026-2036
Cloud ECS Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud ECS Market Insights
Arm-based silicon is rebalancing Cloud ECS compute economics as hyperscalers migrate from x86-dominant fleets to custom processor architectures. Amazon Web Services leverages Graviton chip in-house design to anchor cost-per-compute advantages across its Elastic Compute Service portfolio. Microsoft Azure sustains Cobalt processor R&D intensity to differentiate performance-per-watt metrics against legacy instruction sets. Google Cloud competes through Axion CPU deployment, positioning its Cloud ECS offerings for AI training and inference workloads.
Cloud Elastic Compute Service denotes on-demand virtualized server capacity provisioned through internet-accessible data centers, typically metered by vCPU cores, memory allocation, and egress bandwidth with sub-minute provisioning APIs. The architecture enables enterprises to elastically scale compute resources without capital-intensive hardware procurement, serving primary purposes in web application hosting, batch processing, and containerized microservices orchestration. Public cloud deployment captures the dominant margin pool as hyperscale operators amortize infrastructure across millions of tenants, while hybrid cloud configurations attract regulated industries requiring on-premises sovereignty with burst capacity to off-premises nodes. IaaS service type leads volume consumption as organizations retain control over operating systems and middleware, though PaaS adoption accelerates among development teams seeking managed Kubernetes and serverless abstraction layers.
ISO 27001 certification requirements shape Cloud ECS procurement criteria for European enterprises subject to GDPR data governance audits, while NIST SP 800-145 frameworks guide United States federal agency cloud migration assessments through FedRAMP authorization pathways. China's MIIT enforces GB standards for cross-border data flows, compelling multinational Cloud ECS providers to establish sovereign infrastructure zones within mainland facilities. Stakeholders must monitor evolving encryption-in-transit mandates and carbon disclosure regulations as these compliance dimensions increasingly determine vendor eligibility and total cost of ownership calculations.
Market Dynamics
Arm-based processor migration is rebalancing Cloud ECS compute economics as hyperscalers migrate from x86-dominant fleets to custom silicon architectures, compressing cost-per-compute benchmarks and forcing workload portability recalibration across provider ecosystems.
Growth Catalysts
- GDPR data governance audits:European enterprises mandate ISO 27001 certification for Cloud ECS procurement, expanding compliant provider eligibility pools and standardizing security baselines across continental deployments.
- Container orchestration maturation:Kubernetes-native workload portability standards enable financial services institutions to modernize core banking infrastructure without vendor lock-in constraints.
- Singapore data localization mandates:Sovereign cloud requirements tighten across ASEAN financial hubs, compelling infrastructure investment in jurisdiction-bound availability zones.
Market Restraints
- Silicon supply concentration:Advanced node semiconductor fabrication concentrates in Taiwan and South Korea, exposing Cloud ECS providers to geopolitical disruption risk in processor procurement pipelines.
- Cross-border data friction:China's MIIT enforces GB standards for cross-border flows, fragmenting multinational workload orchestration across incompatible regulatory perimeters.
- Energy cost volatility:Data center power purchasing agreements face natural gas price fluctuation exposure, compressing margin structures in compute-intensive regions.
Strategic Opportunities
- Carbon disclosure regulation tailwinds:EU CSRD mandates scope emissions reporting, creating premium positioning for Cloud ECS providers with verified renewable energy matching and transparent PUE metrics.
- Edge-AI inference convergence:5G MEC deployments combine with lightweight container runtimes to enable sub-10ms latency workloads for autonomous systems and industrial robotics.
- India PLI scheme incentives:Domestic data center construction subsidies attract hyperscaler investment in Mumbai and Chennai metro corridors, reducing latency to South Asian enterprise demand.
Industry Challenges
- FedRAMP authorization timelines:United States federal agency cloud migrations face 12-18 month certification cycles, compressing contract velocity for public sector Cloud ECS vendors.
- Legacy mainframe integration complexity:Financial institutions struggle to replatform COBOL-dependent core systems onto containerized microservices without transaction integrity degradation.
- Multi-cloud networking skill scarcity:Enterprise IT organizations lack sufficient platform engineering expertise to manage Istio service mesh configurations across heterogeneous provider environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud ECS Market |
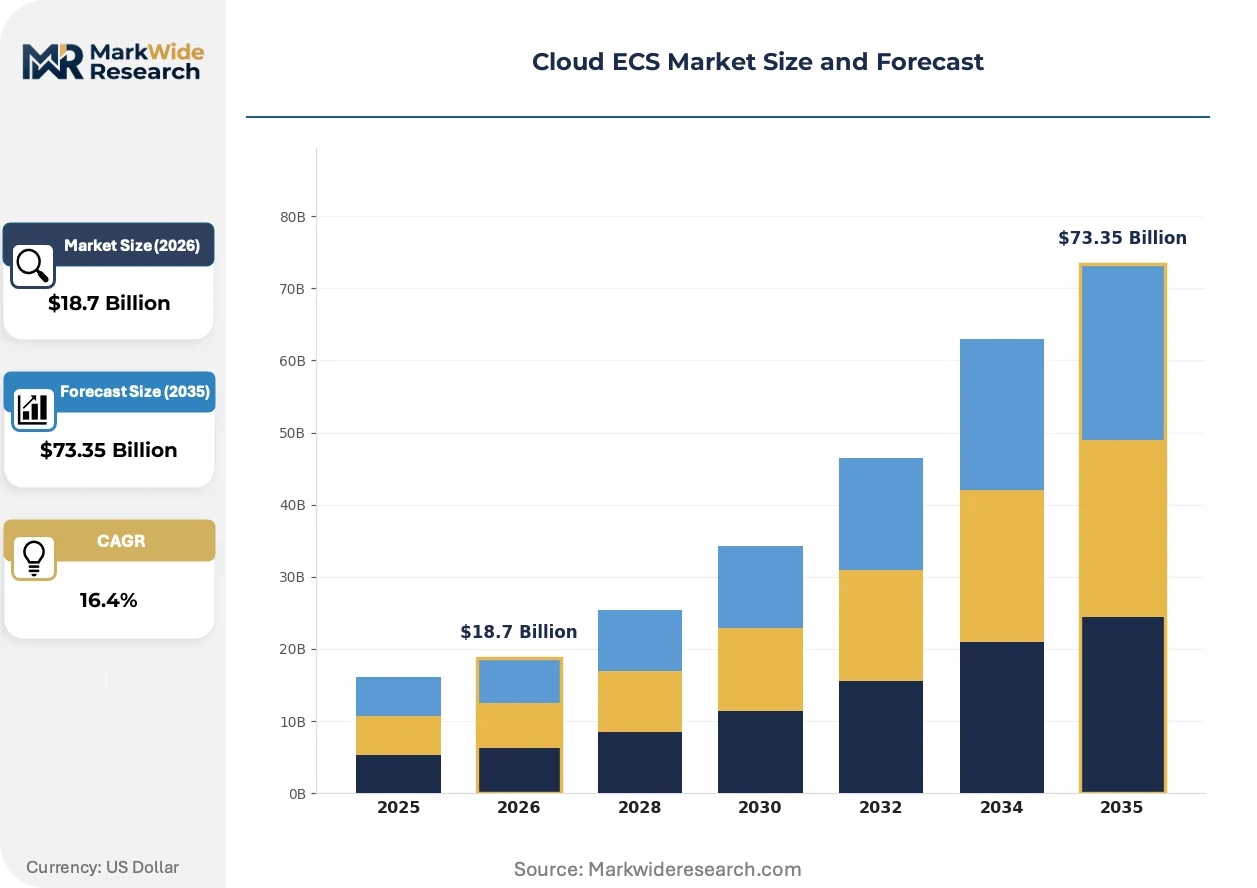
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, DaaS End User: SMEs, Large Enterprises, Government Agencies, Startups Solution Type: Backup Solutions, Disaster Recovery, Data Storage, Compute Services |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Alibaba Cloud, Oracle Cloud Infrastructure, IBM Cloud, Salesforce, OVHcloud, DigitalOcean, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud ECS Market Trends and Innovations
Workload abstraction layers are actively fragmenting Cloud ECS procurement patterns as buyers prioritize portable orchestration over provider-native tooling, compressing switching costs and standardizing API-driven infrastructure consumption models.
WebAssembly runtime environments are modularizing edge compute deployment patterns by enabling language-agnostic binary execution with near-native performance. Industrial IoT operators in Germany adopt Wasm modules for factory-floor analytics, reducing container startup latency from seconds to milliseconds. This architecture is modularizing how Cloud ECS providers package microservices, collapsing the boundary between serverless functions and long-running virtualized instances.
EU AI Act risk classification frameworks impose documentation and transparency obligations on high-risk AI systems hosted in Cloud ECS environments. Providers must implement model registry audit trails and explainability interfaces for automated decision-making workloads. German automotive manufacturers and French healthcare AI startups face the steepest compliance ramps, accelerating investment in MLOps governance tooling.
Reserved capacity trading marketplaces are emerging as secondary channels for Cloud ECS compute commitments. Enterprises with underutilized three-year reserved instances resell surplus capacity through broker platforms, displacing direct provider purchasing for variable workloads. This behavior concentrates among United States SaaS vendors with seasonal demand patterns, where financial engineering teams optimize committed spend utilization through internal market mechanisms.
Cloud ECS Market Segmentation
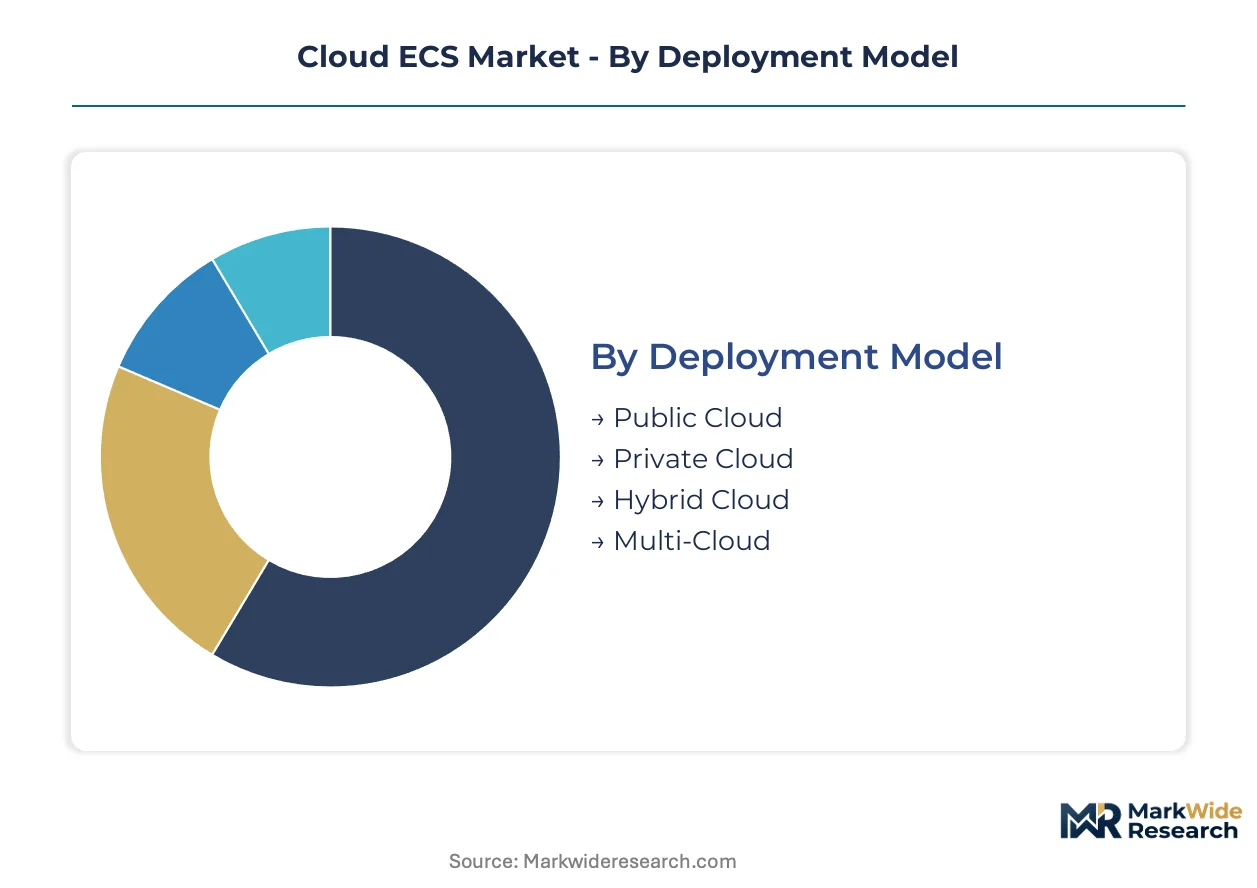
Cloud ECS procurement patterns diverge sharply across deployment architectures and organizational scale, with workload portability requirements and regulatory sovereignty dictating segment selection. The analysis below maps how infrastructure abstraction layers, service granularity, and end-user sophistication reshape vendor positioning and margin capture across the ecosystem.
Deployment Model:
Standalone infrastructure deployments dominate enterprise procurement where data residency mandates require dedicated resource isolation, while embedded multi-cloud configurations serve workloads demanding provider-agnostic failover.
- Public Cloud:Shared infrastructure pools amortize capital expenditure across millions of tenants, enabling sub-minute provisioning APIs for web application hosting and batch processing workloads. Financial services institutions in Singapore leverage public Cloud ECS for non-core banking functions while maintaining sovereign zones for transactional data, balancing cost efficiency against MIIT-style localization requirements.
- Hybrid Cloud:Burst capacity architectures connect on-premises sovereignty with off-premises elasticity, attracting regulated industries requiring FedRAMP-authorized federal workloads alongside commercial cloud scalability. German automotive manufacturers deploy hybrid configurations to keep proprietary design data within KBA-audited facilities while pushing rendering workloads to hyperscale nodes.
- Private Cloud:Single-tenant dedicated infrastructure serves defense contractors and healthcare systems demanding HIPAA-compliant isolation with guaranteed resource reservation.
- Multi-Cloud:Workload portability across AWS, Azure, and GCP deployments reduces vendor lock-in for SaaS vendors with seasonal demand volatility.
Volume placements concentrate in Public Cloud; the faster expansion belongs to Hybrid Cloud.
Service Type:
Control-retention preferences segment the market, with infrastructure-level abstraction attracting platform engineering teams while managed services accelerate developer velocity.
- IaaS:Bare-metal virtualization with tenant-managed operating systems and middleware dominates enterprise lift-and-shift migrations, preserving existing configuration management investments. United States federal agencies route IaaS procurement through FedRAMP authorization pathways, compressing contract velocity but standardizing security baselines across civilian and defense departments.
- PaaS:Container orchestration and serverless abstraction layers eliminate infrastructure provisioning overhead, enabling French healthcare AI startups to deploy EU AI Act-compliant model registries without platform engineering specialization.
- SaaS:Fully managed application delivery abstracts all infrastructure decisions, accelerating time-to-value for line-of-business procurement.
- DaaS:Desktop virtualization streams secure workstation environments to distributed workforces, gaining traction among Indian IT services firms with PLI-supported domestic data center presence.
Revenue concentration sits with IaaS; PaaS climbs the fastest as Kubernetes-native standards mature.
End User:
Procurement sophistication and compliance burden create distinct buying behaviors across organizational maturity stages.
- Large Enterprises:Multi-year reserved capacity commitments with custom SLAs dominate procurement, supported by dedicated cloud center of excellence teams negotiating enterprise discount programs. German manufacturers anchor this segment, leveraging ISO 27001 certification requirements to standardize security baselines across continental deployments.
- Government Agencies:FedRAMP, StateRAMP, and sovereign cloud mandates dictate vendor eligibility, with 12-18 month authorization cycles filtering provider pools to established hyperscalers.
- SMEs:Pay-as-you-go consumption without committed spend attracts price-sensitive adopters prioritizing operational flexibility over strategic negotiation.
- Startups:Credits programs and venture-backed scaling incentives drive initial platform selection, with portability concerns emerging at Series C funding stages.
Contract value concentrates with Large Enterprises; Government Agencies expand most quickly as NIST SP 800-145 frameworks accelerate cloud-first mandates.
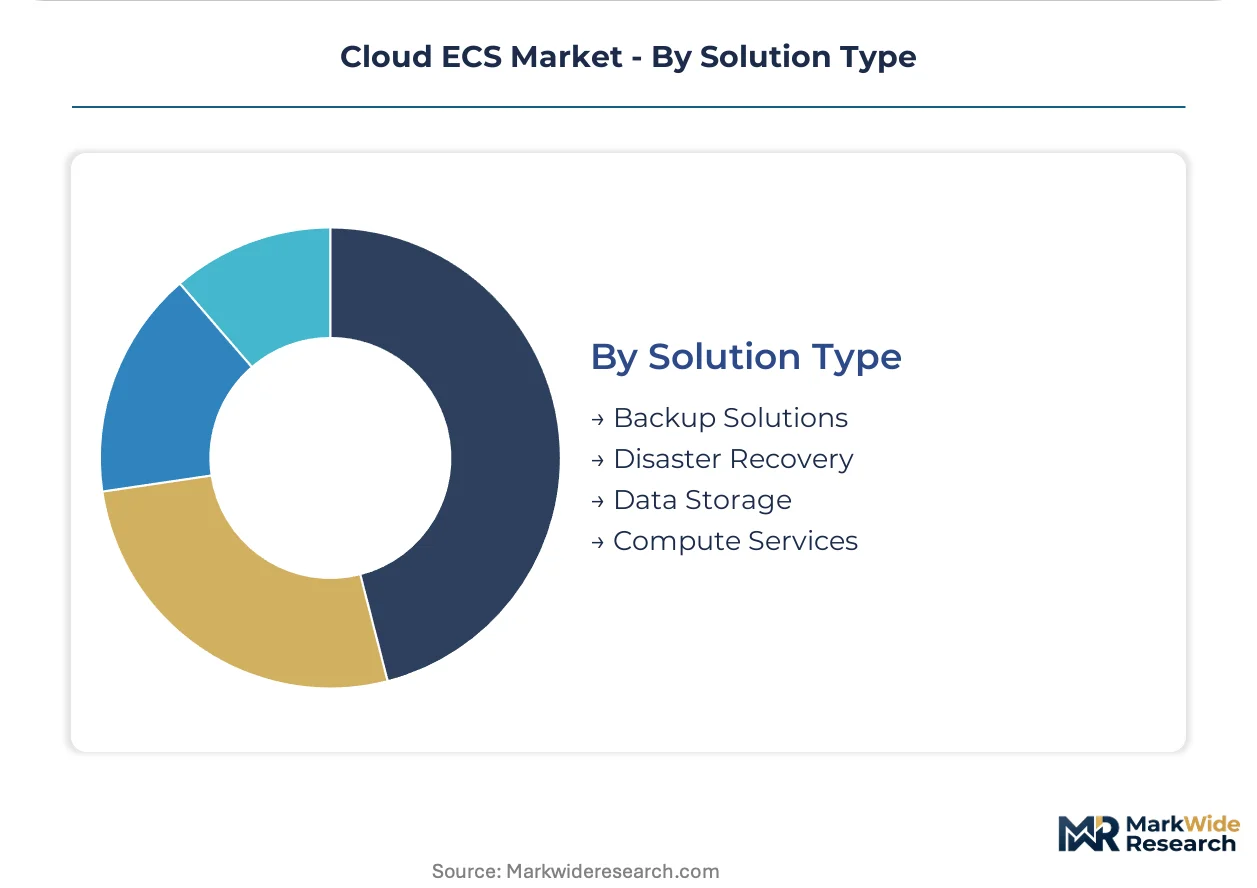
Solution Type:
Workload criticality determines solution selection, with business continuity requirements commanding premium positioning against commodity compute.
- Compute Services:Virtualized CPU and GPU resources form the foundational revenue layer, with Arm-based Graviton, Cobalt, and Axion processors rebalancing cost-per-compute economics. AI training and inference workloads in Singapore's ASEAN financial hub drive GPU cluster deployment, positioning specialized instances for the steepest demand trajectory.
- Disaster Recovery:Automated failover with sub-hour RTO guarantees protects revenue-critical systems, commanding 3-5x pricing multiples against primary compute.
- Data Storage:Object, block, and file tiering optimizes cost against access patterns, with EU CSRD carbon disclosure mandates favoring providers with verified renewable energy matching.
- Backup Solutions:Immutable snapshot retention satisfies ransomware recovery requirements, accelerating among United States healthcare systems facing HIPAA breach notification pressures.
Revenue share pools in Compute Services; Disaster Recovery gains share fastest as operational resilience budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States, Germany, and Singapore concentrate Cloud ECS demand as sovereign cloud requirements tighten data localization mandates across financial services and regulated industries. Hyperscalers anchor infrastructure investment in these jurisdictions to capture enterprise workload migration and compliance-driven procurement.
United States
Federal agency cloud-first mandates and financial services modernization propel demand across civilian and defense sectors. NIST SP 800-145 frameworks guide FedRAMP authorization pathways, compressing contract velocity for public sector vendors. Northern Virginia data center clusters absorb hyperscaler expansion as power purchasing agreements secure renewable energy matching for carbon disclosure compliance.
Germany
Automotive manufacturers and industrial machinery producers drive sovereign cloud adoption for proprietary design data protection. KBA audit requirements and EU AI Act risk classification frameworks impose documentation obligations on high-risk AI systems. Bavaria and Baden-Württemberg host specialized availability zones serving factory-floor analytics and edge-AI inference workloads.
Singapore
ASEAN financial hub status attracts GPU cluster deployment for AI training and inference across banking and fintech sectors. Monetary Authority of Singapore guidelines enforce operational resilience standards for systemically important institutions. Marina Bay and Changi data center corridors concentrate infrastructure investment to serve latency-sensitive regional workloads.
China
Domestic cloud providers capture enterprise workload migration as MIIT enforces GB standards for cross-border data flows. Dual carbon goals accelerate renewable energy matching requirements for data center operators. Beijing-Tianjin-Hebei and Yangtze River Delta clusters expand sovereign infrastructure zones to retain multinational workload orchestration within mainland facilities.
India
IT services firms and SaaS vendors scale domestic capacity under PLI scheme subsidies for data center construction. RBI guidelines on data localization drive financial services infrastructure investment. Mumbai and Chennai metro corridors reduce latency to South Asian enterprise demand as hyperscalers establish captive renewable energy supply.
Cloud ECS Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale operators commanding consolidated positions in public cloud infrastructure while regional sovereign providers fragment specialized compliance-driven procurement. Three archetypes dominate: full-stack hyperscalers with custom silicon design capabilities, sovereign cloud specialists with jurisdiction-bound availability zones, and developer-centric platforms with lightweight container orchestration. Competitive moves concentrate on Arm-based processor R&D intensity and strategic partnerships with telecommunications carriers for 5G MEC edge deployment.
Among full-stack hyperscalers, Amazon Web Services, Microsoft Azure, and Google Cloud occupy positions defined by custom processor architectures—Graviton, Cobalt, and Axion respectively—rebalancing cost-per-compute economics against legacy x86 instruction sets. These entities exemplify the scale-driven archetype where in-house silicon design anchors margin compression and workload portability standards.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Alibaba Cloud |
| Oracle Cloud Infrastructure |
| IBM Cloud |
| Salesforce |
| OVHcloud |
| DigitalOcean |
| Others |
Pricing and Supply Chain Analysis
Captive silicon design at hyperscalers anchors supply position and pricing power by compressing cost-per-compute benchmarks below x86-dependent competitors. AWS Graviton, Azure Cobalt, and Google Axion processors enable margin expansion while forcing workload portability recalibration across provider ecosystems.
Pricing Analysis
Volume commitments separate reserved-instance discounts from on-demand premiums, with three-year contracts capturing 40-60% savings against spot pricing. Price differentiation hinges on certification tier—FedRAMP-authorized workloads command 2-3x multiples over commercial tiers—and Arm-based processor deployment. Cost compression in standard compute tiers intensifies as Graviton-class silicon displaces legacy x86 fleets. SMEs exhibit highest price sensitivity, optimizing pay-as-you-go consumption without committed spend, while government agencies accept premium positioning for sovereign compliance guarantees.
Supply Chain Analysis
Direct-to-hyperscale channels handle enterprise demand above 10,000 vCPU cores, bypassing distributor markups for reserved capacity negotiations. Advanced node fabrication concentrates in Taiwan and South Korea, with CoWoS packaging capacity constraining GPU cluster deployment timelines. Supply chains draw from silicon wafers, memory modules, and power distribution units as core inputs. Single-source vulnerability at TSMC exposes procurement pipelines to geopolitical disruption risk. Distribution runs through systems integrators for hybrid cloud configurations requiring on-premises hardware deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cloud ECS market functions as a vertical-integration race where custom processor R&D intensity determines margin capture. Players pursue upstream control over semiconductor design to escape foundry cost structures and differentiate performance-per-watt metrics.
For Market Incumbents: To counter Arm-based silicon migration by hyperscalers, x86-dependent providers must accelerate Cobalt-class in-house processor programs or secure exclusive foundry capacity agreements. Certification investment in FedRAMP High and StateRAMP authorization pathways defends public sector eligibility pools against emerging sovereign cloud specialists.
For New Entrants and Emerging Players: EU AI Act risk classification frameworks in Germany open a window for MLOps governance tooling providers serving automotive and healthcare AI compliance ramps. Edge-AI inference convergence in Singapore's 5G MEC deployments represents the most penetrable white space, with lightweight WebAssembly runtime packaging as the go-to-market angle for sub-10ms latency workloads.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform engineering tooling acquisitions by hyperscalers seeking multi-cloud management capabilities. Long-term viability favors sovereign cloud specialists with jurisdiction-bound availability zones in ASEAN financial hubs. Monitor India PLI scheme subsidy disbursement velocity as inflection indicator for domestic data center construction momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Custom Processor Deployment | Graviton-class silicon compresses AWS cost-per-compute benchmarks below Azure and GCP x86 fleets. |
| FedRAMP Authorization Investment | 12-18 month certification cycles filter provider pools to established hyperscalers with federal cloud expertise. |
| Sovereign Zone Expansion | Singapore data localization mandates attract Marina Bay infrastructure investment for ASEAN financial services. |
| Edge-AI Partnership | 5G MEC deployments with Deutsche Telekom enable sub-10ms latency for German industrial robotics workloads. |
| Reserved Capacity Marketplace | Secondary broker platforms displace direct provider purchasing for seasonal United States SaaS demand patterns. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cloud center of excellence directors, platform engineering leads, federal procurement officers, and hyperscaler solution architects. SEC 10-K capex disclosures, FedRAMP authorization databases, and EU CSRD emissions reports provided demand-side validation. Bottom-up triangulation across deployment model, service type, and end-user segmentation reconciled with top-down market sizing.
Data-stream reconciliation across hyperscaler infrastructure investment disclosures, enterprise IT spending surveys, and sovereign cloud procurement databases calibrated volume and value outputs. Deployment architecture, organization scale, processor architecture, and regional regulatory cluster dimensions structured the analytical framework. CAGRs derived from elasticity modeling of vCPU core consumption against GDP-correlated enterprise software spending. AI training workload intensity and edge-AI inference adoption curves served as industry-specific forecast inputs across the projection horizon.
Caveats apply where Taiwan semiconductor fabrication disruption or MIIT cross-border data flow enforcement could materially shift the outlook. Forecasts reflect assumptions regarding Arm processor migration velocity and renewable energy matching compliance trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Distributed Cloud Market
Cloud Computing
Cloud VPN Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
Cloud Load Balancers Market
Cloud Computing
Cloud API Market
Cloud Computing
Healthcare Cloud Infrastructure Market
Cloud Computing
Spain Cloud Computing Market
Cloud Computing
Cloud Infrastructure-As-A-Service Market
Cloud Computing
Consumer Cloud Subscription Market
Cloud Computing
Global Multi Cloud Management Market
Cloud Computing
AI Platform Cloud Service Market
Cloud Computing
Global Personal Cloud Market
Cloud Computing
Platform As a Service (Paas) Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
Cloud Continuum Market
Cloud Computing
Cloud Management Market