
 Cloud Microservice and Application Market | 2026-2036
Cloud Microservice and Application Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Microservice and Application Market Outlook
Cloud-native DevOps talent scarcity is reorganizing how enterprises procure managed services and platform engineering support. Amazon Web Services, Inc. dominates public cloud infrastructure for microservice workloads through its pioneering serverless compute portfolio. Microsoft Corporation leverages deep enterprise relationships to anchor hybrid Kubernetes deployments across regulated industries. Google LLC specializes in container orchestration tooling and data-intensive application modernization for analytics-driven sectors.
Cloud microservices and applications constitute independently deployable software components communicating via APIs, typically packaged in containers with orchestration through systems like Kubernetes enabling automated scaling and fault isolation. Their primary commercial purpose is accelerating software delivery velocity while improving resilience in distributed systems. Hybrid Cloud deployments capture the largest margin pools as enterprises balance data sovereignty with elastic capacity, while Kubernetes technology leads growth by becoming the de facto standard for container orchestration across multi-cloud estates. Managed Services within the service type dimension sustains pricing power as skills gaps force buyers toward outsourced platform operations.
FDA oversight of software-as-medical-device and HIPAA security rule enforcement shape how healthcare microservices handle patient data encryption and audit logging. The SEC's cybersecurity disclosure rules and EU GDPR data-localization mandates further constrain architecture choices for financial and cross-border applications. Stakeholders must weigh sovereign cloud requirements against the operational complexity of maintaining federated Kubernetes control planes spanning disparate regulatory jurisdictions.
Market Dynamics
Container orchestration standardization around Kubernetes is compressing vendor differentiation and forcing managed service providers to compete on platform engineering depth rather than proprietary runtime advantages.
Growth Catalysts
- EU AI Act compliance mandates:Financial services firms in Frankfurt and Paris are containerizing AI inference pipelines to satisfy auditability requirements for automated credit decisions.
- API-first architecture adoption:Healthcare systems undergoing digital transformation are decomposing monolithic EHR systems into microservices to enable modular interoperability.
- Cloud-native fintech clusters:Concentrated demand from San Francisco and New York payment processors is driving specialized Kubernetes service provider expansion.
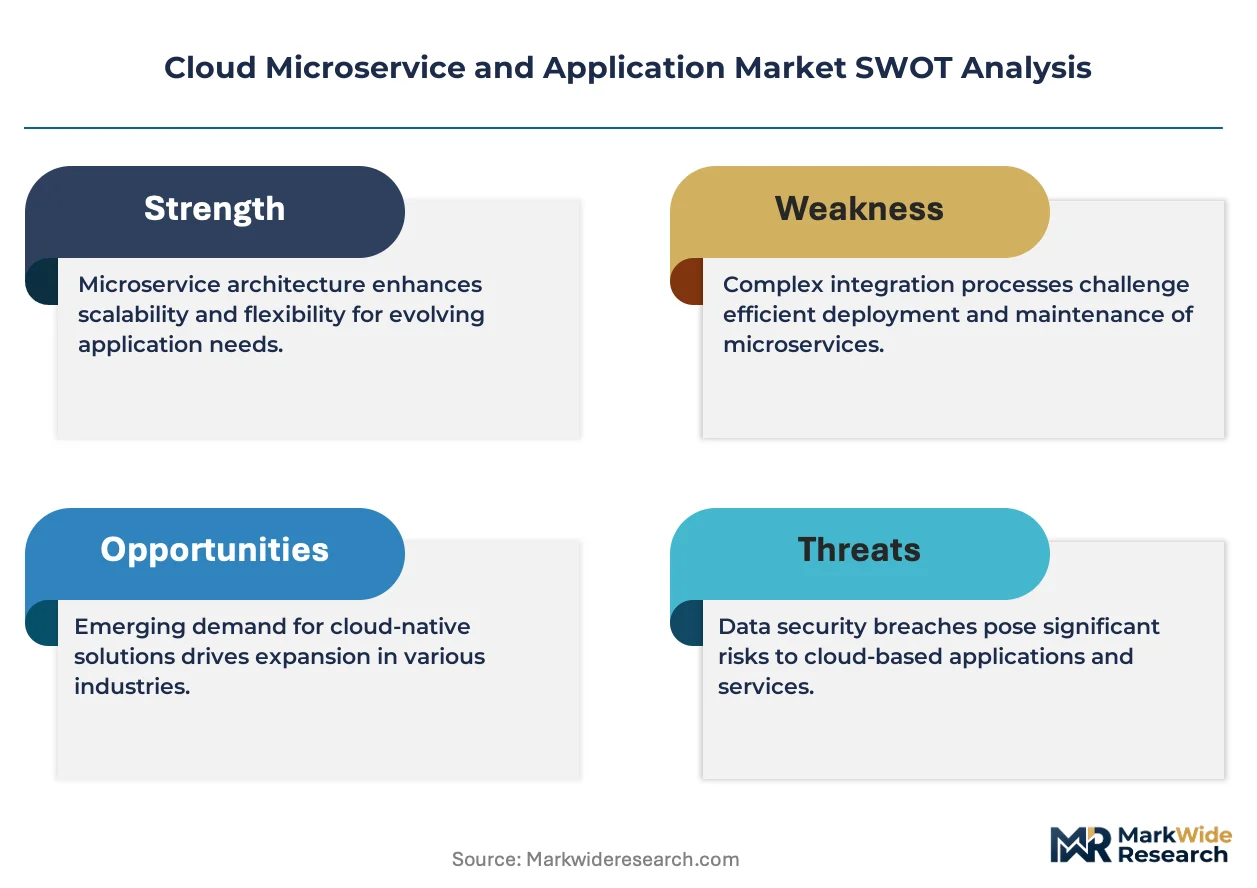
Market Restraints
- Platform engineering talent scarcity:Certified Kubernetes administrator availability constraints in secondary US metros are inflating managed services procurement costs.
- Cross-border data localization:GDPR territorial requirements and emerging sovereign cloud mandates in France and Germany are fragmenting deployment architectures.
- Serverless cold-start latency:Event-driven compute limitations continue blocking latency-sensitive trading system migration from containerized long-running processes.
Strategic Opportunities
- Federated Kubernetes control planes:Multi-cluster orchestration tooling enabling compliance-aware workload distribution across US-EU-Japan boundaries represents unclaimed white space.
- Software-as-medical-device microservices:FDA 21 CFR Part 820 quality system requirements for diagnostic algorithms are creating specialized platform engineering demand.
- Edge container orchestration:5G network slicing deployments in South Korea and Japan are pulling lightweight K3s distributions into manufacturing floor automation.
Industry Challenges
- Service mesh complexity overhead:Istio and Linkerd deployment expertise gaps are extending production timelines for zero-trust microservice communications.
- Observability toolchain fragmentation:Incompatible telemetry standards between OpenTelemetry, Prometheus, and vendor-native solutions are forcing redundant instrumentation investments.
- Legacy mainframe API bridging:COBOL system wrapper development for core banking microservice migration remains bottlenecked by scarce domain-specific engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Microservice and Application Market |
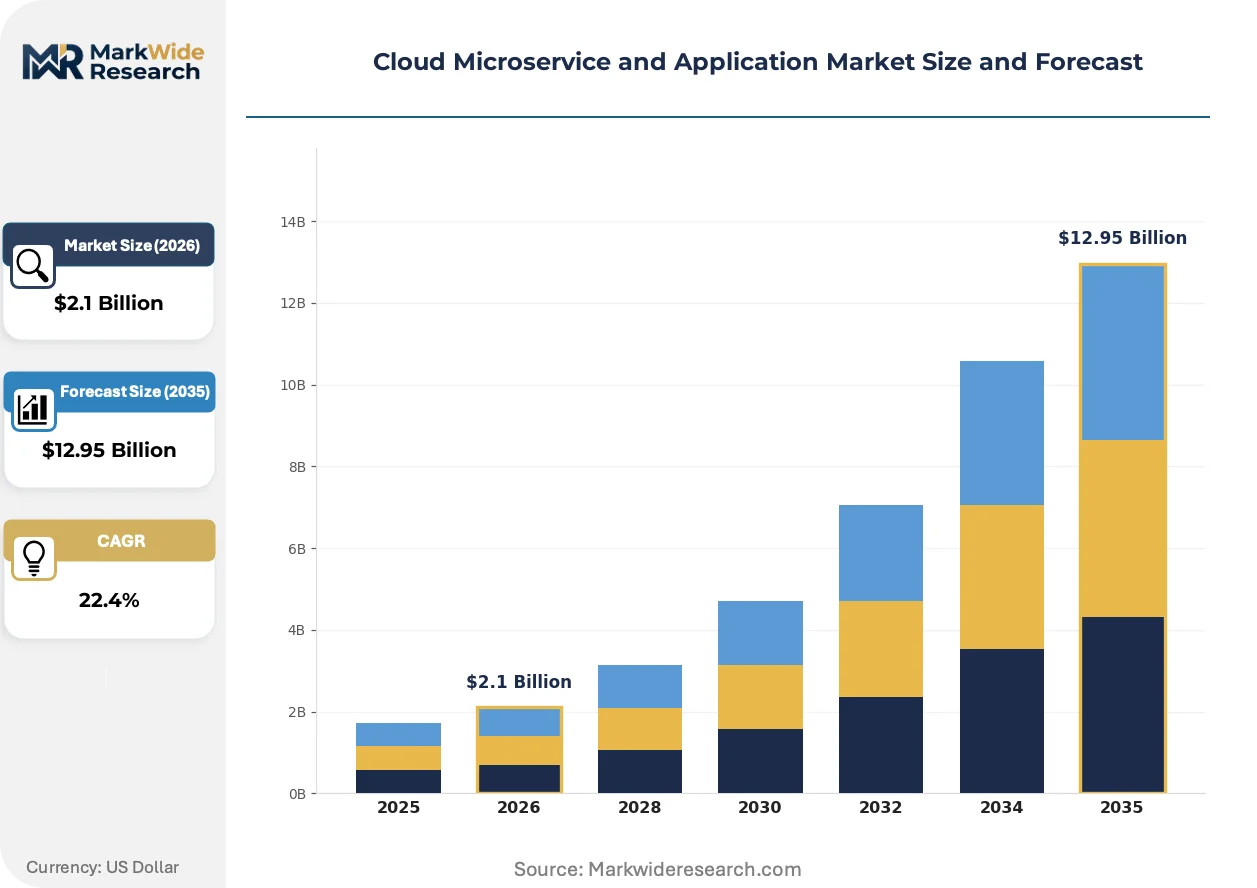
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $12.95 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Large Enterprises, Small and Medium Enterprises, Startups, Government Agencies Technology: Containers, Kubernetes, Serverless, API Management Service Type: Consulting, Implementation, Managed Services, Integration |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, Google LLC, IBM Corporation, Salesforce Inc., Oracle Corporation, Broadcom Inc., Red Hat, Inc., VMware, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Microservice and Application Market Strategic Shifts
Platform engineering is maturing from DevOps tooling aggregation into disciplined internal product management, with infrastructure-as-code practices hardening into reusable golden paths.
WebAssembly runtime modules are bifurcating container deployment strategies. Edge computing vendors in Tokyo and Seoul are adopting Wasm for sub-100ms cold-start requirements in industrial IoT gateways. This runtime compression is enabling microservice density previously unreachable with traditional containerd configurations.
The SEC's cybersecurity disclosure rules are mandating material incident reporting within four business days. Asset managers in New York are restructuring microservice audit logging to capture chain-of-custody evidence for API access patterns. Healthcare entities subject to HIPAA are extending these patterns to patient data access microservices.
Platform engineering teams are consolidating procurement authority previously distributed across application development squads. Large US retailers are displacing ad-hoc cloud console access with curated internal developer portals vending pre-approved service templates. This centralization is most pronounced in regulated sectors where compliance attestation requirements accompany every infrastructure provisioning request.
Cloud Microservice and Application Market Segmentation
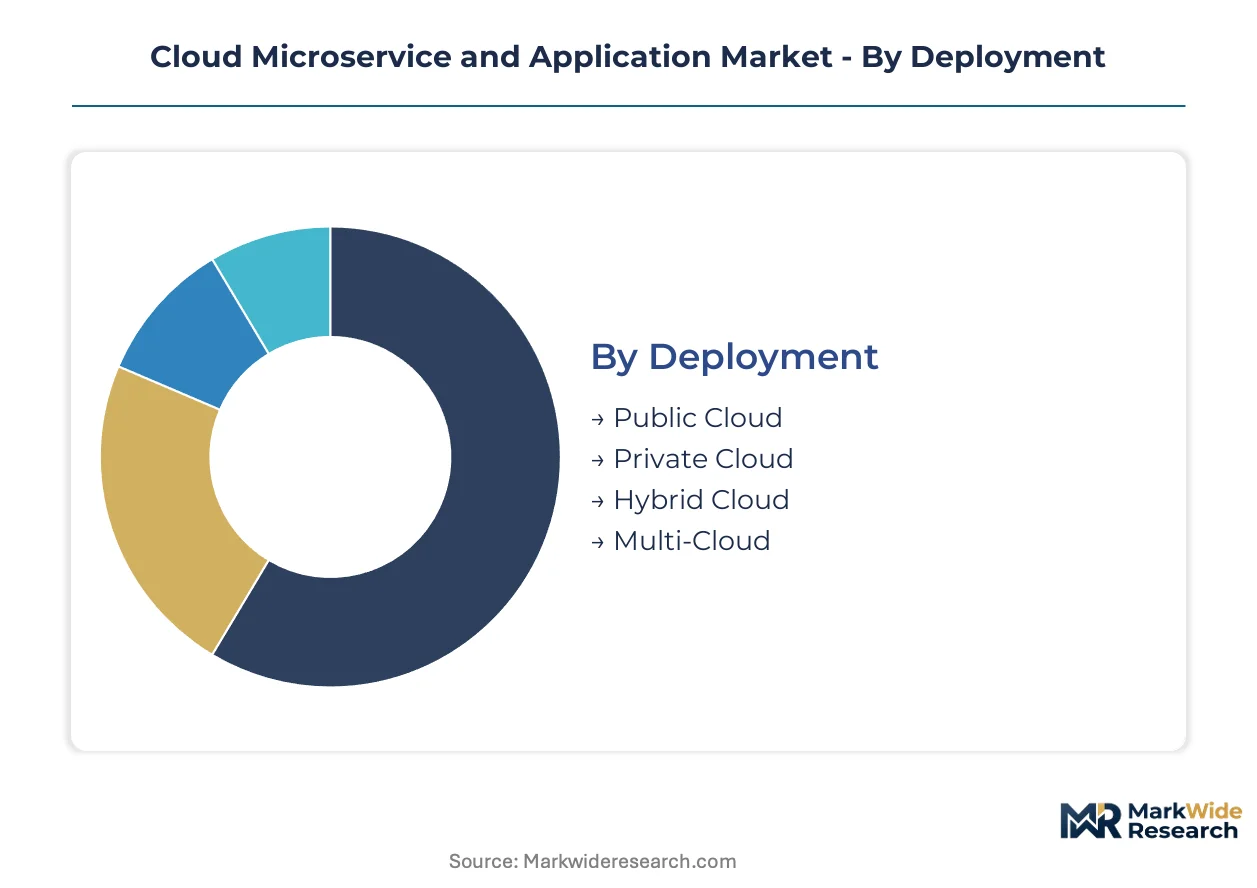
Cloud microservice segmentation reveals where vendor profitability diverges from raw workload volume. Deployment architecture choices determine compliance exposure and operational complexity premiums. Technology layer selections expose capability gaps that reshape procurement patterns across regulated industries.
Deployment:
Margin pools concentrate in configurations balancing data sovereignty with elastic scaling economics.
- Public Cloud:Shared infrastructure delivers lowest unit compute costs through hyperscale operational efficiencies. Demand concentrates among San Francisco and New York fintech startups prioritizing speed-to-market over compliance overhead. AWS, Microsoft Azure, and Google Cloud Platform capture the bulk of containerized workload migration from on-premise data centers.
- Hybrid Cloud:Split architectures command sustained pricing premiums by addressing regulated sector requirements for sensitive data containment alongside burst capacity. Financial services firms in Frankfurt and London deploy Kubernetes control planes across on-premise and public cloud boundaries to satisfy EU AI Act auditability mandates.
- Private Cloud:Single-tenant infrastructure serves defense contractors and healthcare systems with HIPAA-driven encryption requirements.
- Multi-Cloud:Federated deployments across AWS, Azure, and GCP reduce vendor lock-in exposure for Fortune 500 technology procurement teams.
The dominant share belongs to Public Cloud, while Hybrid Cloud is closing the gap fastest through regulated sector procurement expansion.
End User:
Customer scale determines platform engineering service attachment rates and contract renewal velocity.
- Large Enterprises:Complex procurement processes favor established vendors with compliance certification depth. Banking conglomerates in New York and London drive managed Kubernetes service contracts exceeding three-year terms.
- Small and Medium Enterprises:Resource constraints push mid-market buyers toward fully managed platform services rather than in-house DevOps team construction.
- Startups:Venture-backed technology firms in Tel Aviv and Bangalore prioritize serverless compute to minimize pre-revenue infrastructure burn.
- Government Agencies:FedRAMP and sovereign cloud requirements constrain supplier pools to cleared infrastructure providers.
Large Enterprises retain the deepest penetration, yet Startups are expanding most quickly as venture deployment accelerates.
Technology:
Standardization dynamics compress differentiation at the runtime layer while tooling abstraction creates value capture opportunities.
- Kubernetes:Container orchestration has achieved de facto standard status, forcing vendors to compete on control plane management expertise rather than proprietary runtime advantages. Platform engineering teams at US retailers and German automotive manufacturers standardize on upstream Kubernetes distributions to avoid distribution-specific lock-in.
- Containers:Docker-compatible packaging formats enable workload portability across cloud boundaries, reducing migration friction for multi-cloud strategies.
- Serverless:Event-driven compute architectures from AWS Lambda and Azure Functions attract event-processing workloads with intermittent invocation patterns.
- API Management:Gateway and service mesh tooling addresses microservice communication complexity in healthcare system decompositions.
Kubernetes holds the installed base leadership, though API Management is climbing the fastest as service mesh adoption accelerates.
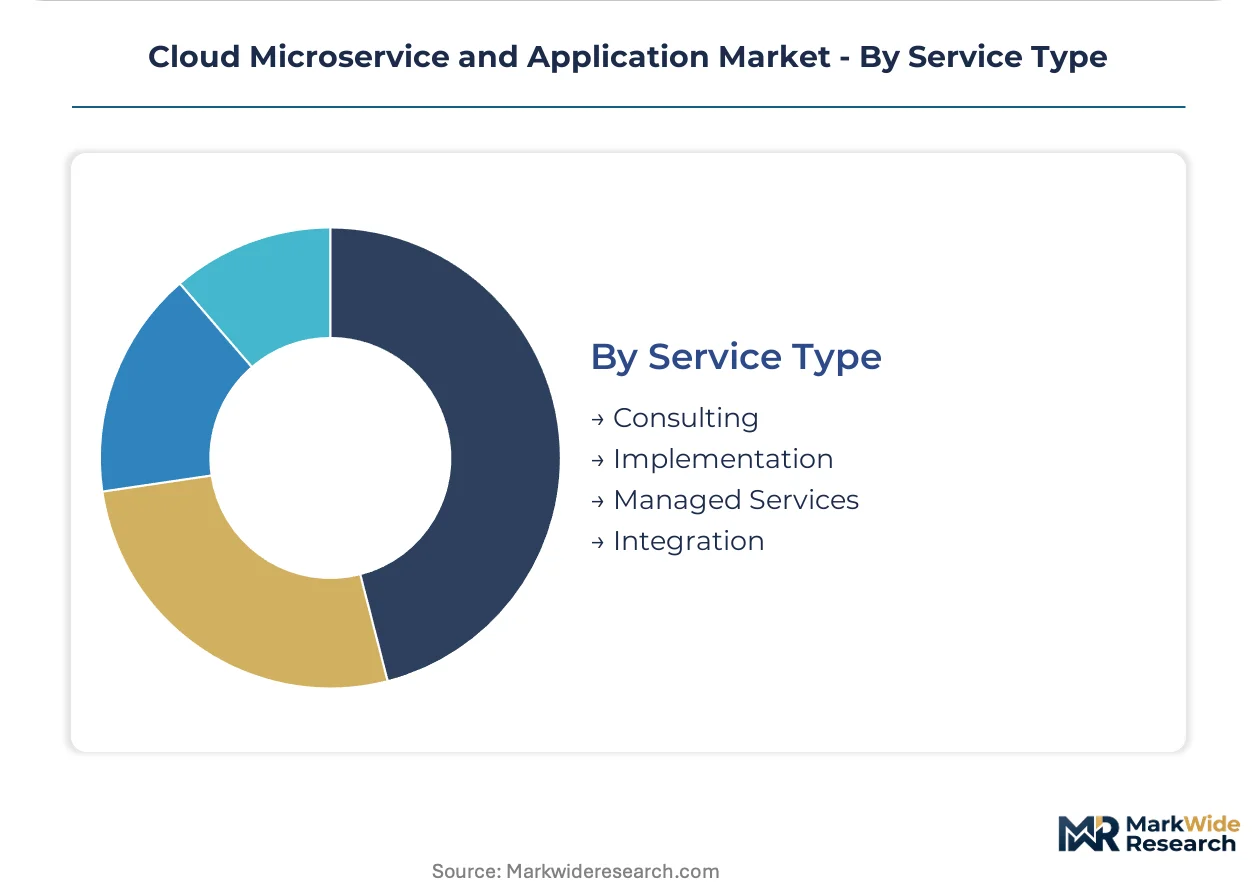
Service Type:
Skills scarcity reorganizes procurement toward outsourced operational responsibility.
- Managed Services:Twenty-four by seven platform operations contracts capture recurring revenue premiums as certified Kubernetes administrator availability constraints persist. Financial services institutions in Singapore and Sydney outsource entire container platform lifecycles to specialized providers.
- Consulting:Architecture assessment and migration planning engagements establish vendor relationships preceding long-term managed service transitions.
- Implementation:Initial deployment projects for cloud-native transformation programs carry fixed-scope pricing with defined milestone deliverables.
- Integration:Legacy system API bridging connects COBOL mainframes to modern microservice fabrics in core banking modernization programs.
Managed Services commands the dominant revenue position, while Integration is gaining share fastest through mainframe modernization urgency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States buyers prioritize speed-to-market through public cloud serverless architectures, while European procurement emphasizes sovereign data containment and auditability mandates. Asian markets blend high-volume container deployment with edge-native orchestration for manufacturing automation.
United States
Financial services institutions in Manhattan and San Francisco drive Kubernetes managed services procurement for payment processing modernization. SEC cybersecurity disclosure rules mandate four-day incident reporting timelines for asset managers. Cloud-native fintech clusters in New York and the Bay Area anchor specialized platform engineering provider expansion.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg deploy hybrid Kubernetes control planes for connected vehicle data pipelines. EU AI Act compliance requirements containerize automated credit decision systems in Frankfurt banking centers. Industrial software vendors in Munich specialize in regulated workload orchestration tooling.
United Kingdom
London-based insurance underwriters migrate monolithic policy systems to API-first microservice architectures. Financial Conduct Authority operational resilience rules enforce strict recovery time objectives for critical digital services. Edinburgh and Manchester fintech clusters concentrate specialized DevOps consulting demand.
Japan
Tokyo manufacturing conglomerates adopt lightweight K3s distributions for 5G-enabled factory floor automation. METI data sovereignty guidelines push sensitive industrial workloads toward domestic cloud regions. Osaka-based electronics producers pioneer WebAssembly runtime modules for sub-100ms edge computing requirements.
India
Bangalore and Hyderabad technology services firms build captive Kubernetes platforms for global banking clients. RBI data localization mandates require domestic storage of payment transaction records. Mumbai financial institutions accelerate containerization of core banking modernization programs.
Cloud Microservice and Application Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud providers commanding infrastructure primitives while platform engineering specialists capture managed services premiums. The upper tier consolidates around serverless compute and container orchestration primitives. Three archetypes dominate: hyperscale infrastructure operators, enterprise software incumbents with hybrid cloud portfolios, and open-source distribution vendors. Competitive moves center on multi-cloud federation tooling development and vertical-specific compliance certification acquisition.
Within the hyperscale tier, Amazon Web Services, Inc. and Microsoft Corporation anchor public cloud infrastructure provisioning for containerized workloads. Google LLC occupies a position emphasizing data-intensive application modernization and analytics-native orchestration tooling. These three entities exemplify the integrated leader archetype through combined infrastructure, platform, and managed services depth.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Salesforce Inc. |
| Oracle Corporation |
| Broadcom Inc. |
| Red Hat, Inc. |
| VMware, Inc. |
| Others |
Value Chain & Pricing Dynamics
Hyperscale operational efficiencies in public cloud infrastructure compress unit compute costs while concentrating pricing power among AWS, Microsoft Azure, and Google Cloud Platform. This scale dynamic forces smaller managed service providers toward specialized platform engineering premiums to escape commodity compression.
Pricing Analysis
Long-term managed services contracts dominate enterprise procurement, with three-year platform operations agreements commanding recurring revenue premiums over spot consulting engagements. Price differentiation rests on Kubernetes certification depth and vertical-specific compliance attestation—FedRAMP-authorized providers extract 40-60% premiums over uncertified competitors. Cost compression in public cloud compute tiers intensifies as hyperscalers compete for fintech workload migration. Mid-market enterprises exhibit highest price sensitivity, while regulated financial institutions prioritize auditability over unit cost.
Supply Chain Analysis
The United States and India anchor global Kubernetes talent pipelines, with Bangalore and Hyderabad technology services firms supplying platform engineering capacity to Western banking clients. Germany and Japan feed specialized industrial automation expertise into edge container orchestration deployments. Supply chain vulnerability centers on certified administrator scarcity in secondary US metros, forcing buyers toward outsourced lifecycle management. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels, with managed service providers increasingly vending through curated internal developer portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud microservices sit in early-cycle expansion as EU AI Act compliance mandates force containerization of previously monolithic AI inference systems across Frankfurt and Paris banking centers.
For Market Incumbents: Shield installed base relationships by deepening FedRAMP and HIPAA certification portfolios before emerging platform engineering specialists capture regulated sector procurement. Consolidate channel control through internal developer portal standardization that displaces ad-hoc cloud console access. Vertical integration into specialized compliance tooling—particularly FDA 21 CFR Part 820 quality system modules—creates switching costs against pure-play orchestration vendors. For New Entrants and Emerging Players: Differentiate on federated Kubernetes control plane expertise spanning US-EU-Japan boundaries, the most penetrable white space as multi-cloud procurement accelerates. Target software-as-medical-device microservices in Boston and Research Triangle Park healthcare clusters where FDA oversight creates specialized platform engineering demand. Pursue channel partnerships with systems integrators holding existing COBOL modernization relationships rather than direct enterprise sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed Kubernetes service providers with three-year platform operations contracts exceeding 80% renewal rates. Long-term viability favors vendors combining hyperscaler-agnostic tooling with vertical-specific compliance depth. Watch certified Kubernetes administrator availability constraints as the inflection signal—persistent scarcity validates outsourced platform operations premiums, while rapid certification supply expansion threatens managed service pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Internal developer portal deployment at US retailers consolidates procurement authority previously distributed across squads. |
| Acquisition of Specialist Firm | COBOL wrapper development capability addresses core banking modernization bottlenecks in London and New York. |
| Strategic Partnership | Hyperscaler marketplace listings extend reach to mid-market buyers lacking direct vendor procurement processes. |
| Geographic Expansion | Tokyo and Seoul edge computing presence captures 5G-enabled manufacturing automation demand from K3s distributions. |
| Product Launch | WebAssembly runtime modules for sub-100ms cold-start requirements differentiate industrial IoT gateway offerings. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with CTOs, platform engineering directors, IT procurement officers, and Kubernetes administrators at financial services and healthcare institutions; and secondary validation against SEC hyperscaler capex disclosures, GitHub contribution velocity metrics, and cloud-native foundation project roadmaps. Bottom-up workload deployment estimates triangulated against top-down infrastructure spending projections.
Across the analysis window, the forecasting framework modeled deployment architecture, organization size, vertical compliance complexity, and regional regulatory cluster segmentation. CAGRs derived from trend extrapolation of container adoption curves and managed services attach rates, with Kubernetes certification pipeline data and EU AI Act implementation timelines as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale infrastructure investment or accelerated sovereign cloud mandate enforcement would require recalibration. Forecasts reflect assumptions around talent scarcity persistence and regulatory compliance trajectory. Recalibration cycles align with material shifts in certification supply, cross-border data localization policy, and serverless runtime performance benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Marketing Cloud Platform Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Automotive Cloud Based Solutions Market
Cloud Computing
Dbaas and Cloud Database Market
Cloud Computing
Global Cloud Based ITSM Market
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Serverless Computing Market
Cloud Computing
Private Cloud Market
Cloud Computing
Cloud Based Information Governance Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
India Cloud Computing Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Cloud Computing Services Market
Cloud Computing
South Korea Cloud Computing Market