
 Cloud Migration Services Market | 2026-2036
Cloud Migration Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Migration Services Market Intelligence
Capital-intensity divergence between hyperscale infrastructure operators and boutique consultancies is bifurcating competitive dynamics across the sector. Amazon Web Services leverages its native cloud stack to dominate infrastructure-led migration engagements. IBM sustains differentiation through its hybrid cloud platform and mainframe modernization heritage. Accenture anchors premium positioning by combining managed services with industry-specific regulatory expertise.
Cloud migration services encompass the systematic transfer of applications, data, and workloads from on-premises or legacy environments to cloud infrastructure, typically involving assessment, replatforming, refactoring, and post-migration optimization phases with strict uptime and security parameters. The primary purpose is enabling operational scalability, cost elasticity, and access to cloud-native capabilities without disrupting business continuity. Public cloud deployment models command the largest revenue pool due to pay-as-you-go economics, while hybrid cloud architectures capture expanding margin pools as enterprises seek workload portability between private and public environments. Replatforming services within the service type dimension are gaining traction fastest as organizations balance speed-to-cloud against transformation depth.
FCC guidelines on data sovereignty, EU GDPR cross-border transfer rules, and HIPAA security requirements for healthcare workloads collectively shape compliance architecture within migration project scopes. ISO 27001 certification and SOC 2 attestation function as baseline market-access credentials that filter vendor eligibility for enterprise and government contracts. Stakeholders must monitor evolving AI governance frameworks and quantum-resistant encryption standards as these will redefine security postures for next-generation cloud environments.
Market Dynamics
Legacy mainframe estates at financial institutions and manufacturing conglomerates are generating forced-migration pressure as vendor support contracts expire and technical debt compounds operational risk. This expiration wave is concentrating demand around replatforming specialists capable of preserving business logic while extracting workloads from proprietary hardware.
Growth Catalysts
- EU AI Act compliance deadlines:European enterprises must demonstrate algorithmic transparency and data lineage, requiring cloud-native audit trails that on-premises infrastructure cannot provide. Migration projects now embed AI governance checkpoints from assessment phase.
- Industrial IoT data gravity:German automotive and machinery producers are relocating manufacturing execution systems to edge-cloud hybrids to process sensor streams with sub-10ms latency. This workload category demands specialized migration tooling for time-series databases.
- Quantum-resistant cryptography mandates:NIST post-quantum standards are prompting federal contractors and financial services firms to rebuild encryption layers within cloud environments rather than retrofit aging on-premise hardware security modules.
Market Restraints
- Specialized talent scarcity:Mainframe COBOL expertise required for deconstruction phases commands premium rates exceeding standard cloud architect compensation by significant multiples, inflating project costs.
- Cross-border data transfer friction:GDPR adequacy decisions for non-EU cloud regions create architectural constraints that fragment unified migration strategies into jurisdiction-specific workstreams.
- Hyperscale vendor concentration:Three infrastructure providers control dominant shares of certified government cloud regions, limiting negotiation leverage for enterprise procurement teams.
Strategic Opportunities
- India's data localization requirements:RBI and TRAI mandates for financial and telecom data residency are creating demand for in-country cloud regions and localized migration service capabilities.
- Healthcare FHIR interoperability:HIPAA-aligned cloud environments capable of hosting standardized electronic health record exchanges represent underpenetrated whitespace as hospital systems consolidate.
- Carbon accounting integration:CSRD emissions disclosure rules are positioning cloud migration as a decarbonization lever, with workload optimization services bundled into sustainability reporting offerings.
Industry Challenges
- Application dependency mapping:Decades of undocumented interconnections between legacy systems create discovery phases that extend project timelines unpredictably.
- Parallel-run validation requirements:Financial services regulators mandate extended shadow-mode operation that doubles infrastructure spend during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Migration Services Market |
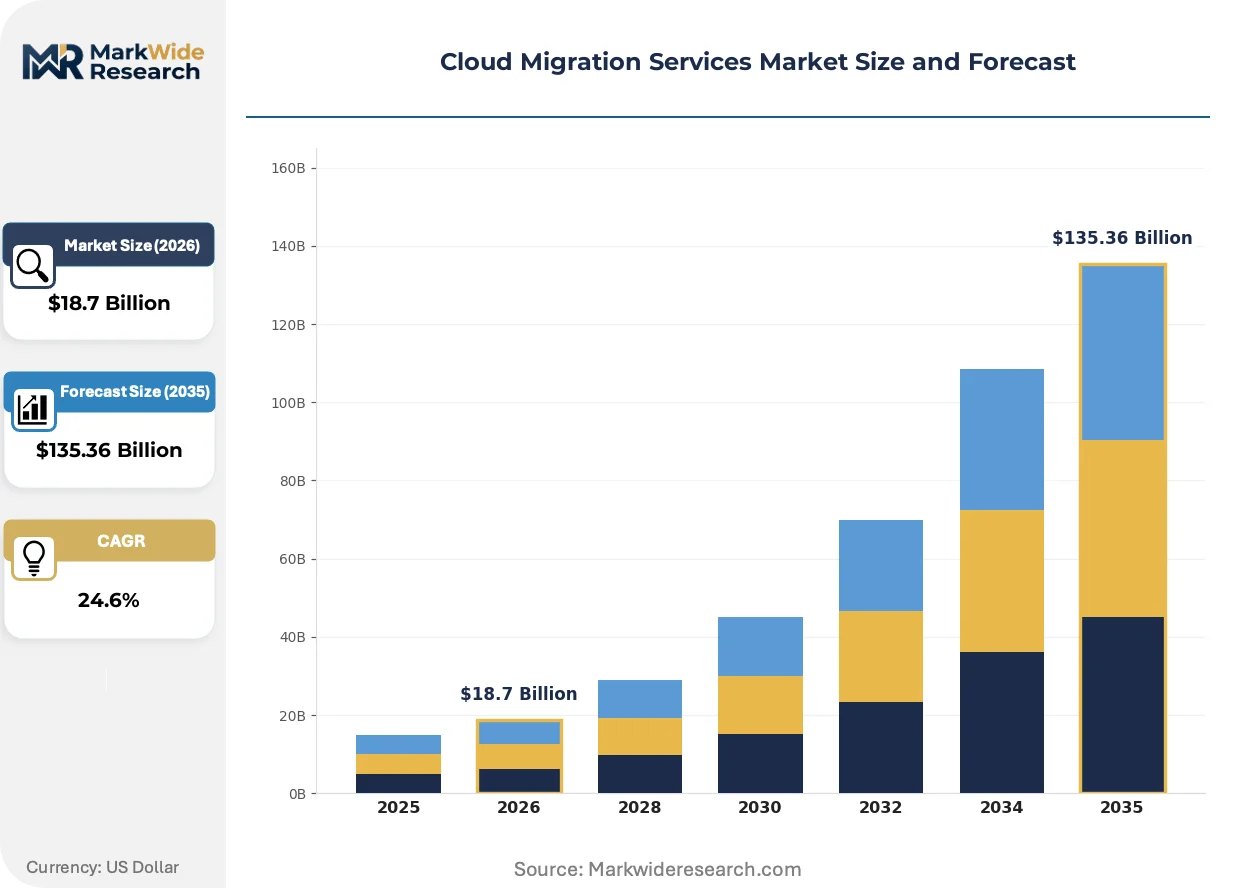
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Lift-and-Shift, Replatforming, Refactoring, Cloud-Native Development Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Migration Strategy: Cloud Adoption Framework, Outage Management, Data Migration, Application Modernization |
| Companies Covered | Amazon Web Services, IBM, Microsoft, Google, Accenture, Capgemini, Cognizant, NTT Data, Wipro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Migration Services Market Strategic Shifts & Innovations
Containerization and Kubernetes orchestration are rewriting migration methodology, enabling incremental workload movement rather than monolithic cutover events. This technical shift is compressing risk windows and expanding the addressable market to mid-tier enterprises previously priced out of transformation programs.
Immutable infrastructure patterns is supplanting configuration management approaches for stateful workload migration. Financial services firms in Frankfurt and Singapore are adopting GitOps pipelines to provision cloud environments with auditable version control. This methodology is compressing compliance documentation cycles from quarterly to continuous.
EU AI Act risk classification tiers are mandating algorithmic impact assessments prior to cloud deployment for high-risk automation systems. Healthcare diagnostic AI and credit scoring engines face elevated scrutiny. German and French enterprises are embedding legal-review checkpoints into migration runbooks.
Consumption-based engagement models are displacing fixed-fee transformation contracts in the mid-market segment. Systems integrators now offer workload-hour pricing indexed to actual cloud resource utilization. This shift is most visible among UK and Netherlands-based professional services firms serving private equity portfolio companies.
Cloud Migration Services Market Segmentation
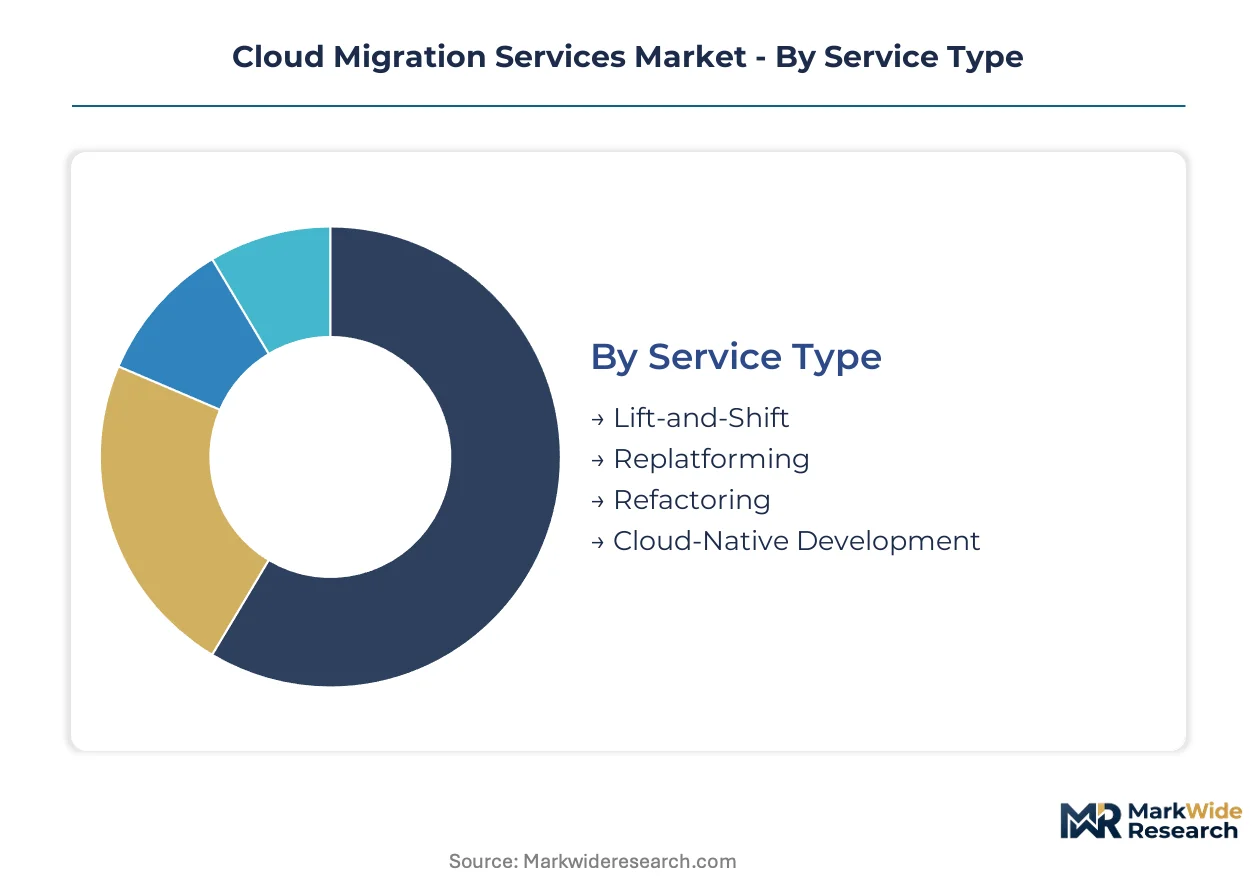
Cloud migration services fragment across multiple technical and commercial dimensions that determine project economics, risk profiles, and vendor selection criteria. Understanding these segment boundaries clarifies where specialized capabilities command premium pricing versus commoditized execution.
Service Type:
Margin pools concentrate in transformation-intensive engagements where business logic preservation intersects with cloud-native capability extraction.
- Replatforming:Workloads undergo targeted modifications to leverage cloud infrastructure without full architecture rewrites. German automotive manufacturers and financial institutions in Frankfurt drive concentrated demand as they seek to extract manufacturing execution systems and core banking platforms from aging mainframes while preserving compliance certifications.
- Refactoring:Applications are restructured into microservices or serverless architectures to maximize cloud-native elasticity. Healthcare systems consolidating diagnostic AI platforms and credit scoring engines under EU AI Act risk classification tiers are rotating investment toward this segment to embed algorithmic auditability from infrastructure foundation.
- Lift-and-Shift:Rapid workload relocation with minimal modification, prioritizing speed over optimization.
- Cloud-Native Development:Ground-up application construction using containerization and Kubernetes orchestration from inception.
Replatforming holds installed capacity. Refactoring is rotating up the share rankings.
Deployment Model:
Architecture choices increasingly fragment by data sovereignty mandates and latency requirements rather than pure cost optimization.
- Hybrid Cloud:Workload portability spans private infrastructure and public hyperscale regions, enabling sensitive data retention on-premises while bursting compute to cloud. Industrial IoT deployments across German machinery producers and edge-cloud manufacturing execution systems in automotive supply chains are expanding most quickly as sub-10ms latency requirements collide with GDPR cross-border transfer constraints.
- Public Cloud:Pay-as-you-go economics dominate volume metrics, though margin compression intensifies as hyperscale providers internalize migration tooling.
- Private Cloud:Dedicated infrastructure serves defense contractors, classified government workloads, and financial services firms with quantitative trading latency sensitivities.
- Multi-Cloud:Deliberate distribution across AWS, Azure, and GCP regions reduces vendor lock-in and satisfies geographic redundancy requirements for systemically important financial institutions.
Public cloud dominates transaction volume. Hybrid cloud is climbing the fastest in margin contribution.
End User:
Procurement sophistication and compliance burden scale inversely with organizational size, reshaping vendor engagement models.
- Large Enterprises:Complex legacy estates, mandatory parallel-run validation periods, and board-level risk governance define engagement scope. Financial services firms facing quantum-resistant cryptography mandates and manufacturing conglomerates with expiring mainframe support contracts anchor premium service tier demand.
- SMEs:Consumption-based pricing and standardized assessment frameworks are displacing fixed-fee contracts. Private equity portfolio companies in the UK and Netherlands are gaining share fastest as systems integrators develop workload-hour pricing indexed to actual cloud resource utilization.
- Government Agencies:FedRAMP, IL5, and comparable national security certifications filter vendor eligibility.
- Educational Institutions:Research computing and student information systems drive seasonal migration waves aligned with academic calendars.
Large enterprises hold installed capacity. SMEs are gaining share fastest in net new contract flow.
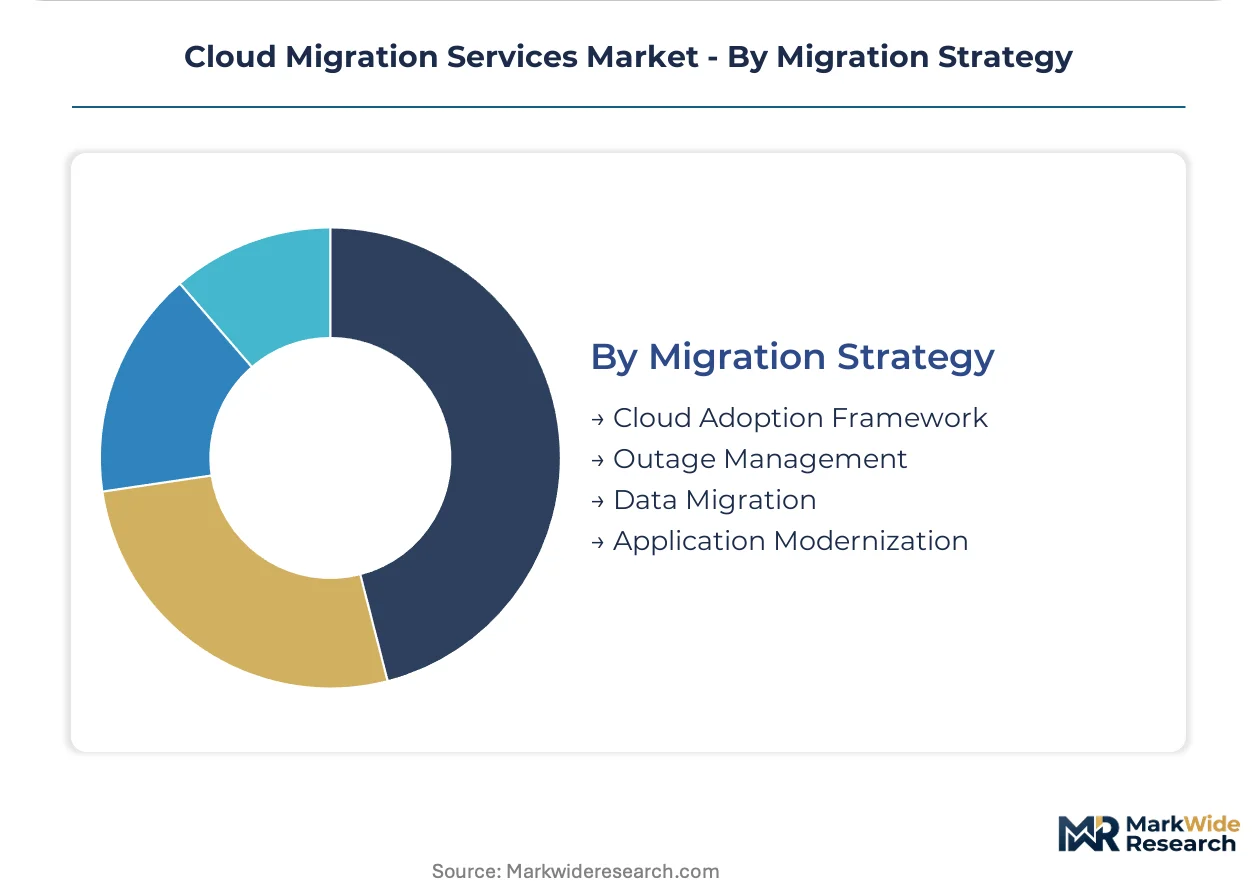
Migration Strategy:
Methodology selection determines project risk windows, regulatory documentation burden, and post-migration operational resilience.
- Application Modernization:Legacy codebase transformation into containerized, API-first architectures. Financial services firms in Singapore and Frankfurt adopting GitOps pipelines for immutable infrastructure provisioning are expanding most quickly as compliance documentation cycles compress from quarterly to continuous.
- Data Migration:Structured and unstructured data transfer with integrity validation, encryption-in-transit, and lineage preservation for GDPR and HIPAA audit trails.
- Cloud Adoption Framework:Structured assessment-to-optimization methodologies aligned with AWS Well-Architected, Microsoft Cloud Adoption Framework, or equivalent vendor programs.
- Outage Management:Cutover planning, rollback procedures, and business continuity protocols for mission-critical system transitions.
Application modernization holds installed capacity. Cloud adoption framework is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity, driving workload-hour pricing and consumption-based contracts. German and US enterprises prioritize compliance architecture and quantum-resistant security over cost, accepting premium positioning for regulated migrations.
United States
Federal contractors and financial services firms in New York and Chicago are rebuilding encryption layers under NIST post-quantum standards. HIPAA security requirements for healthcare workloads shape compliance architecture across hospital system consolidations. The Washington DC metro corridor anchors government cloud migration demand through FedRAMP certification requirements.
Germany
Industrial conglomerates in Stuttgart and Munich are replatforming manufacturing execution systems onto hybrid cloud architectures for sub-10ms latency processing. EU AI Act compliance deadlines mandate algorithmic transparency checkpoints embedded from assessment phase. The Frankfurt financial cluster drives quantum-resistant cryptography mandates for core banking platform migrations.
United Kingdom
Private equity portfolio companies in London and the Southeast are adopting consumption-based engagement models with workload-hour pricing indexed to actual utilization. GDPR cross-border transfer rules fragment unified migration strategies into jurisdiction-specific workstreams. The Manchester-Leeds corridor expands mid-market systems integrator presence for standardized assessment frameworks.
India
RBI and TRAI data localization mandates for financial and telecom data residency are creating demand for in-country cloud regions and localized migration capabilities. Systems integrators in Bangalore and Hyderabad develop captive delivery centers for replatforming specialists. The Mumbai-Pune industrial belt concentrates manufacturing execution system migrations for automotive supply chains.
Singapore
Financial services firms adopting GitOps pipelines for immutable infrastructure provisioning compress compliance documentation cycles from quarterly to continuous. Monetary Authority of Singapore guidelines on operational resilience mandate extended shadow-mode validation for mission-critical system transitions. The island city-state anchors Asia-Pacific regulatory technology migration demand for algorithmic auditability.
Cloud Migration Services Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hyperscale infrastructure operators leveraging native cloud stacks against boutique consultancies commanding premium rates for mainframe modernization heritage. Three strategic archetypes dominate: hyperscale platform owners bundling migration tooling, global systems integrators combining managed services with regulatory expertise, and regional specialists offering jurisdiction-specific compliance capabilities. Competitive moves concentrate on strategic partnerships with semiconductor manufacturers and vertical integration into sovereign cloud infrastructure.
Within the integrated platform tier, Amazon Web Services exemplifies hyperscale infrastructure-led positioning, while IBM occupies a distinctive space through hybrid cloud heritage and mainframe modernization capabilities. Accenture anchors premium systems integrator positioning by combining managed services with industry-specific regulatory expertise across EU AI Act and GDPR compliance frameworks.
| Leading Market Players |
|---|
| Amazon Web Services |
| IBM |
| Microsoft |
| Accenture |
| Capgemini |
| Cognizant |
| NTT Data |
| Wipro |
| Others |
Cost & Logistics Intelligence
Consumption-based workload-hour pricing locks in supply access to hyperscale cloud regions while anchoring price visibility to actual resource utilization rather than fixed transformation fees. This contract-structure pattern dominates mid-market engagements in the United Kingdom and Netherlands where private equity portfolio companies demand cost elasticity aligned to cloud consumption patterns.
Pricing Analysis
Post-migration optimization and managed services revenue tiers now drive lifetime value as initial migration fees compress under competitive pressure. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification depth—FedRAMP and ISO 27001 tiers command substantial premiums over baseline SOC 2 offerings. Cost compression in lift-and-shift commoditized tiers is intensifying because hyperscale providers internalize migration tooling and bundle basic assessment services at near-zero marginal cost. SMEs exhibit acute price sensitivity, while German industrial conglomerates and US federal contractors accept premium positioning for quantum-resistant cryptography and data sovereignty guarantees.
Supply Chain Analysis
Strait of Malacca submarine cable transit underwrites connectivity costs for Asia-Pacific cloud region access, creating logistics chokepoint exposure for latency-sensitive manufacturing execution system migrations. Talent supply concentrates in India, Poland, and Romania where systems integrators maintain captive delivery centers for replatforming specialists. Raw material dependencies span mainframe COBOL expertise, Kubernetes-certified platform engineers, and AI governance legal specialists. Single-source vulnerability sits with hyperscale infrastructure operators controlling certified government cloud regions in concentrated geographic footprints. Distribution runs through global systems integrator networks and boutique consultancies with jurisdiction-specific regulatory capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mainframe modernization expertise functions as the critical scarcity asset, with decades of undocumented COBOL business logic residing in shrinking talent pools that cannot expand through standard training pipelines.
For Market Incumbents: Secure exclusive access to retiring mainframe specialists through acquisition of boutique consultancies with COBOL heritage, while building captive training pipelines for cloud-native platform engineering. Defensive moves must counter hyperscale providers internalizing migration tooling and bundling assessment services at marginal cost. Capacity addition in India and Poland anchors delivery scale for mid-market workload-hour pricing engagements. For New Entrants and Emerging Players: Carbon accounting integration services represent the most penetrable white-space where incumbents under-serve CSRD emissions disclosure requirements across European manufacturing. Target healthcare FHIR interoperability implementations in US hospital system consolidations where HIPAA-aligned cloud environments remain underpenetrated. Go-to-market positioning as sustainability reporting bundlers rather than pure infrastructure migrators unlocks procurement budget access outside traditional IT spend categories. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized replatforming boutiques with mainframe modernization heritage and established regulatory certification portfolios. Long-term viability hinges on algorithmic auditability capabilities as EU AI Act enforcement tightens. Acquisition target archetypes combine COBOL expertise with cloud-native platform engineering under unified delivery models. Watch NIST post-quantum cryptography mandate adoption timelines as inflection indicator for encryption-layer rebuild demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mainframe Specialist Acquisition | Captures irreplaceable COBOL expertise before competitor consolidation exhausts available targets. |
| Sovereign Cloud Region Buildout | Satisfies RBI and TRAI data localization mandates for financial services captive delivery. |
| GitOps Pipeline Integration | Compresses compliance documentation cycles for Frankfurt and Singapore financial services clients. |
| Carbon Accounting Service Bundling | Positions migration as CSRD decarbonization lever for European industrial procurement. |
| Quantum-Resistant Cryptography Certification | Enables premium pricing for NIST-aligned federal contractor and financial services engagements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud architects, mainframe modernization specialists, regulatory compliance officers, and enterprise procurement leads at financial services and industrial conglomerates. Secondary validation drew from hyperscaler capex disclosures, SEC filings of systems integrators, EU AI Act implementation guidance, and NIST post-quantum cryptography standard documentation. Bottom-up project pipeline analysis triangulated against top-down market sizing from infrastructure spend allocation surveys.
Across the analysis window, the forecasting framework modeled service type segmentation by transformation depth, deployment architecture by data sovereignty requirements, and end-user scale by compliance burden sophistication. CAGRs were derived from regression analysis of historical migration project completion rates against cloud infrastructure adoption curves. Industry-specific inputs included mainframe support contract expiration schedules and EU AI Act risk classification tier implementation timelines.
Forecasts assume regulatory continuity in EU AI Act enforcement, NIST post-quantum cryptography mandates, and RBI data localization requirements; material policy shifts would require re-modeling of infrastructure investment and talent allocation assumptions. Scenario risks encompass GDPR adequacy decision withdrawals, hyperscale vendor concentration regulatory intervention, and quantum computing timeline acceleration. Practitioners should keep alternative scenarios live as AI governance enforcement intensity and cryptography standard adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Telecom Cloud Market
Cloud Computing
Global Cloud Collaboration Market
Cloud Computing
Cloud Based Information Governance Market
Cloud Computing
AI Platform Cloud Service Market
Cloud Computing
Global Distributed Cloud Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
Cloud Enablement Market
Cloud Computing
SME Cloud Market
Cloud Computing
Cloud Management Market
Cloud Computing
Cloud Integration Software Market
Cloud Computing
Private Cloud Market
Cloud Computing
Global Cloud Office Services Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Community Cloud Market
Cloud Computing
North America Cloud Computing Market