
 Mucormycosis Market | 2026-2036
Mucormycosis Market Size, Share, and Industry Trends Forecast 2026-2036
Mucormycosis Market Analysis
Hospital procurement of antifungal therapies is rotating toward specialty care centers managing complex immunocompromised cases. Pfizer Inc. leverages its established hospital formulary relationships to sustain access across acute care networks. Merck & Co., Inc. anchors its position through manufacturing scale in parenteral antifungal production. Biocon Limited differentiates via cost-engineered biosimilar capabilities that compete on price in emerging markets.
Mucormycosis constitutes an aggressive angioinvasive fungal infection caused by Mucorales order fungi, requiring prompt intravenous antifungal intervention and surgical debridement to prevent mortality. The condition primarily threatens immunosuppressed populations including uncontrolled diabetics, hematologic malignancy patients, and solid organ transplant recipients. Amphotericin B retains dominance as the first-line therapeutic backbone despite nephrotoxicity constraints that drive posaconazole growth in maintenance settings. Pulmonary infection applications command premium pricing due to intensive care requirements, while cutaneous infection segments offer volume expansion through earlier detection protocols. Hospital pharmacies capture the dominant distribution margin pool given the parenteral administration requirements and cold-chain logistics involved.
FDA orphan drug designations and EMA accelerated assessment pathways shape development incentives for novel antifungal agents targeting resistant Mucorales strains. India's CDSCO manufacturing standards and BIS quality certifications govern export eligibility for domestic producers serving regulated markets. Stakeholders must monitor resistance surveillance data and regulatory exclusivity timelines to prioritize pipeline investments.
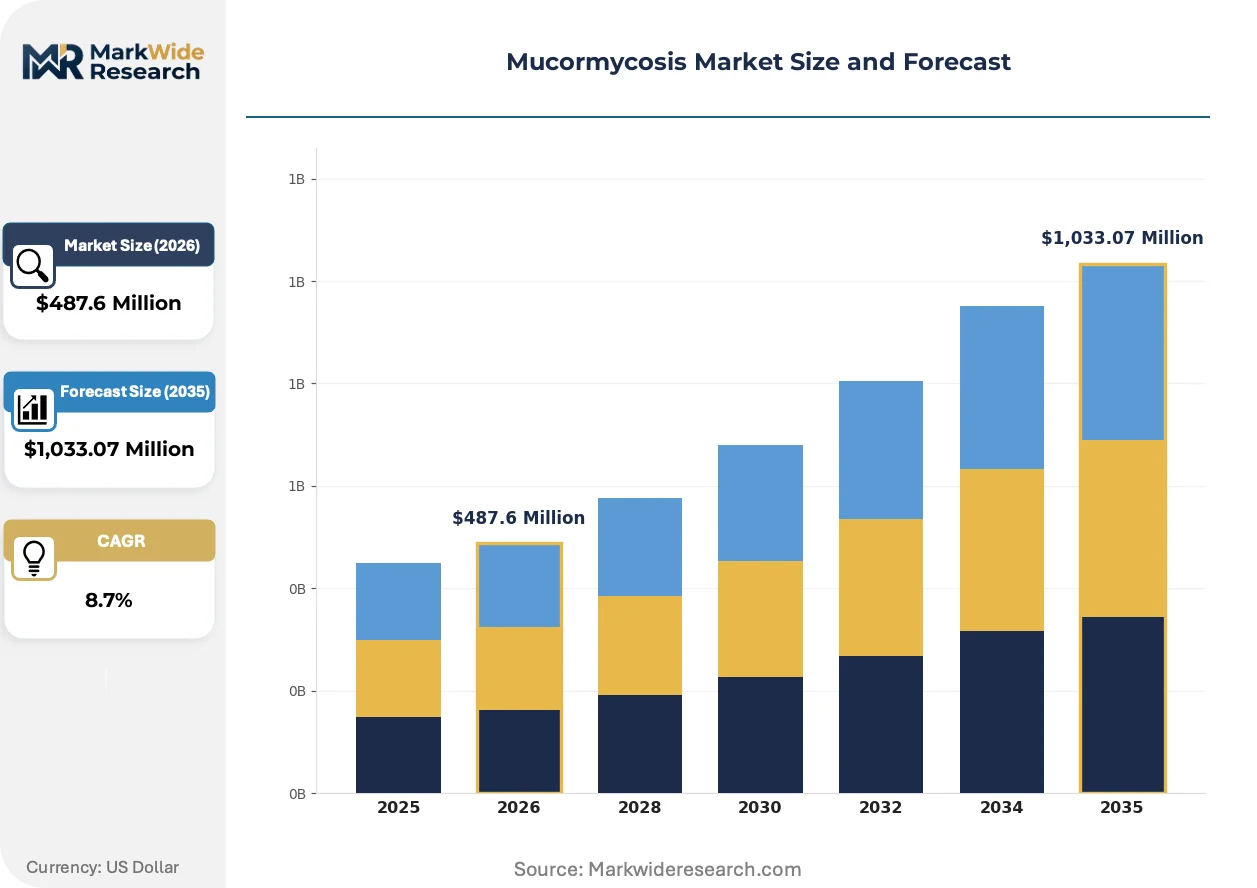
Market Dynamics
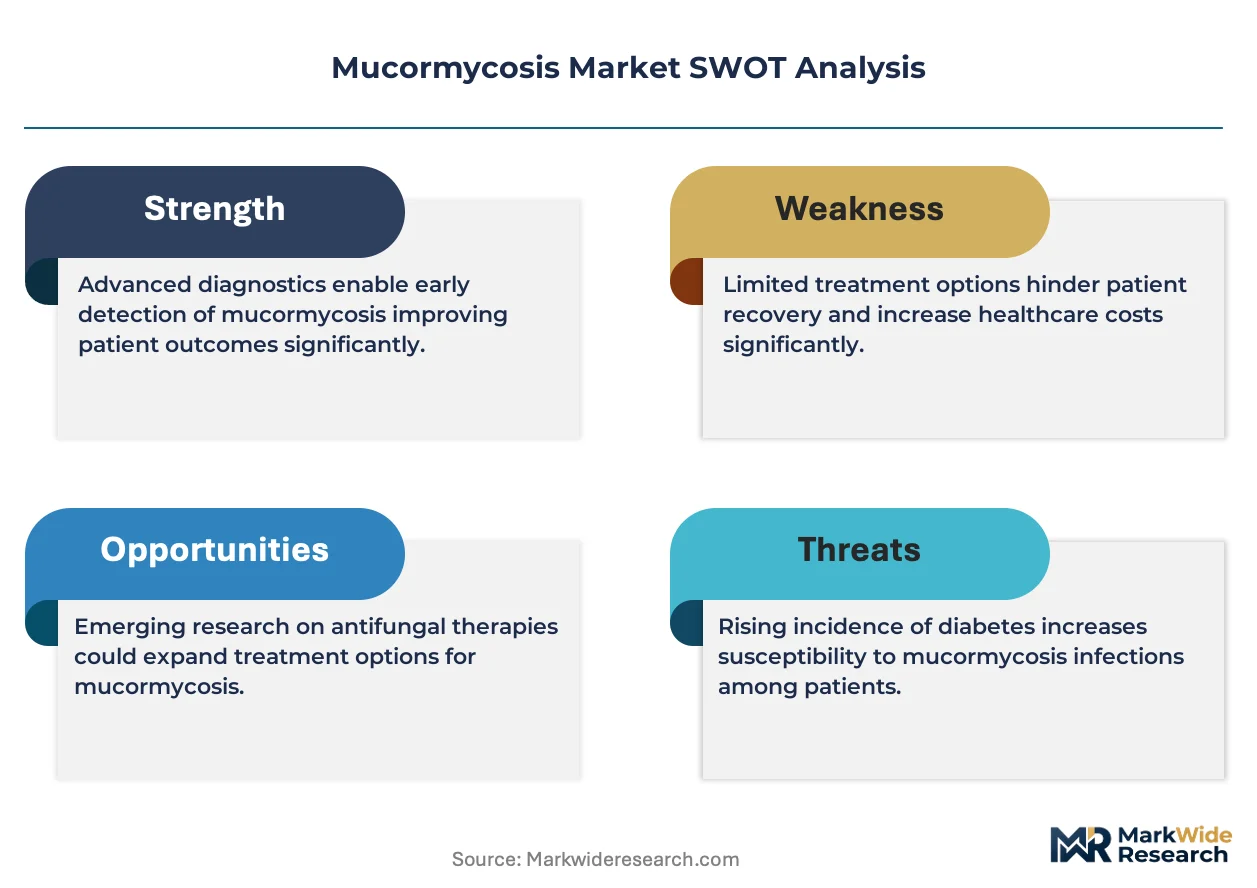
Hospital formulary consolidation is concentrating purchasing power among integrated delivery networks, compressing supplier margins while elevating cold-chain logistics requirements for parenteral antifungal therapies.
Growth Catalysts
- India's PLI scheme:Domestic pharmaceutical manufacturing incentives are expanding regional supply capabilities for amphotericin B formulations, reducing import dependency for acute care networks.
- Uncontrolled diabetes prevalence:Rising diabetic populations in Brazil and India are expanding the addressable patient base requiring prophylactic and curative antifungal intervention.
- FDA orphan drug designation:Development incentives for novel Mucorales-targeting agents are accelerating pipeline investment despite limited commercial patient volumes.
Market Restraints
- Amphotericin B nephrotoxicity:Renal toxicity constraints limit treatment duration and force costly monitoring protocols in intensive care settings.
- API supply concentration:Active pharmaceutical ingredient production for polyene antifungals clusters in select Asian manufacturing hubs, exposing formulators to single-source vulnerability.
- Posaconazole substitution pressure:Triazole maintenance therapy is displacing extended amphotericin B courses in stable patients, compressing revenue per treated case.
Strategic Opportunities
- CDSCO export certification:Indian manufacturers meeting BIS quality standards can access regulated European and North American markets through EMA mutual recognition pathways.
- Cutaneous early detection protocols:Dermatology and wound care channels represent underpenetrated entry points for topical and oral antifungal prophylaxis before angioinvasive progression.
- Liposomal formulation advances:Nanotechnology-enabled drug delivery systems are improving therapeutic indices and enabling outpatient transition for select patient cohorts.
Industry Challenges
- Mycology diagnostic expertise scarcity:Histopathology and culture identification capabilities are concentrated in tertiary academic centers, delaying treatment initiation in community hospitals.
- Cold-chain infrastructure capex:Parenteral antifungal stability requirements demand continuous refrigeration investment across distribution networks and ward-level storage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mucormycosis Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amphotericin B, Posaconazole, Isavuconazole, Echinocandins End User: Hospitals, Clinics, Research Institutions, Homecare Application: Chronic Rhinosinusitis, Pulmonary Infection, Cutaneous Infection, Disseminated Infection Distribution Channel: Pharmacies, Online Retail, Hospital Pharmacies, Specialty Stores |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Novartis AG, Sanofi, Abbott Laboratories, Biocon Limited, Cadila Pharmaceuticals Limited, Gilead Sciences, Teva Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mucormycosis Market Emerging Trajectories
Novel drug delivery technologies are reshaping therapeutic administration patterns, while regulatory acceleration pathways and procurement centralization are restructuring competitive access dynamics across acute care networks.
Liposomal amphotericin B formulations are miniaturizing particle size distributions to enhance tissue penetration and reduce infusion-related toxicity. Tertiary care centers in India and the United States are adopting these advanced delivery systems for hematologic malignancy patients with breakthrough mucormycosis. The technology is miniaturizing treatment windows and enabling earlier hospital discharge protocols that reduce per-case reimbursement exposure.
EMA accelerated assessment pathways are compressing review timelines for antifungal agents targeting resistant Mucorales strains with limited therapeutic alternatives. European hospital pharmacies are gaining earlier access to novel polyenes and triazoles through these expedited frameworks. Pulmonary infection applications command priority regulatory attention given intensive care mortality burdens and the absence of approved alternatives to amphotericin B backbone therapy.
Integrated delivery networks are consolidating formulary decisions through centralized pharmacy and therapeutics committees, displacing individual hospital purchasing autonomy. Specialty care centers managing transplant and oncology populations are capturing disproportionate contract allocation through volume commitments and outcome-based purchasing frameworks. This concentration is most visible in United States academic medical centers and Brazilian private hospital chains where procurement centralization has compressed supplier negotiation cycles.
Mucormycosis Market Segmentation
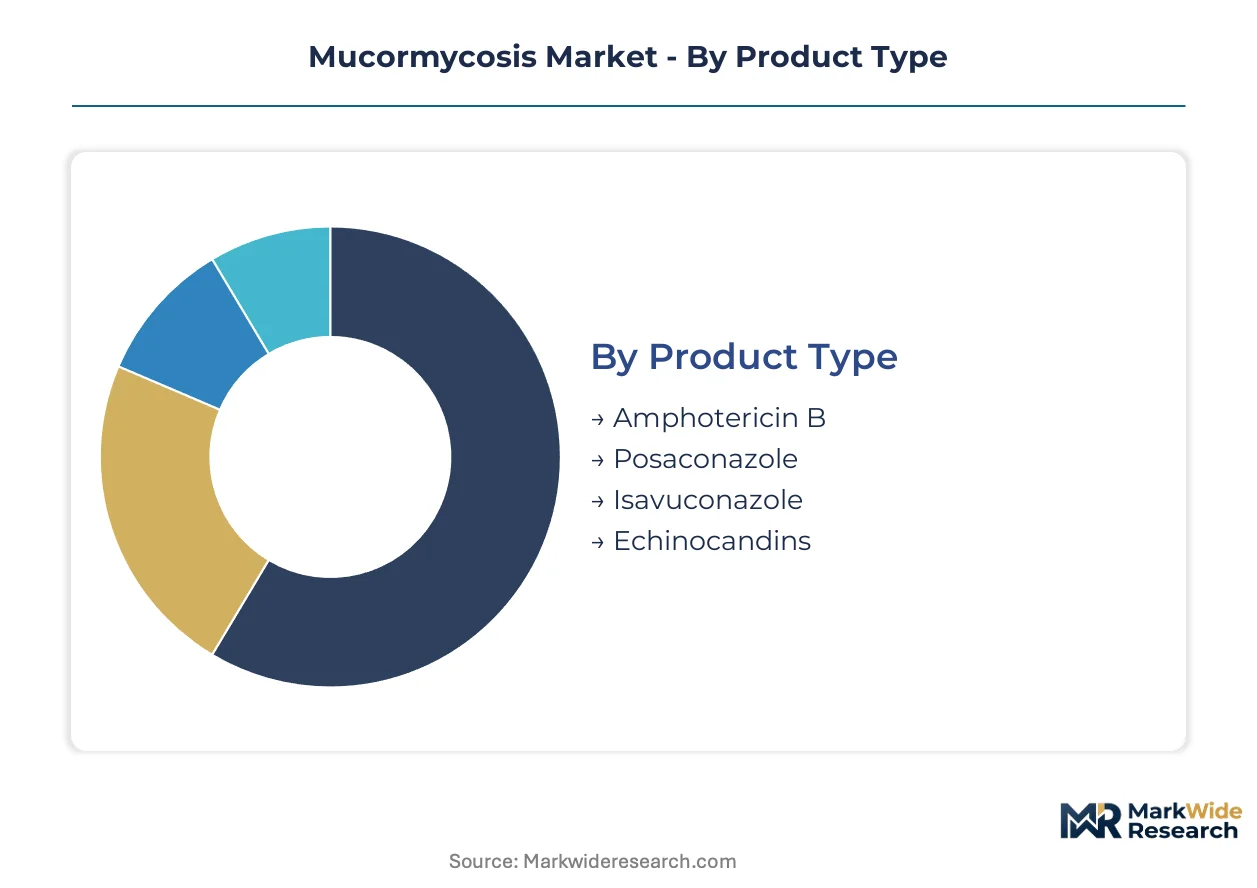
Mucormycosis treatment pathways fragment across acute intervention and maintenance phases, with channel access and patient acuity determining product selection. Segmentation reveals how hospital formulary power concentrates revenue in parenteral therapies while outpatient transitions create openings for oral alternatives.
Product Type:
Polyene and triazole antifungals flow through distinct channel tiers—hospital pharmacies dominate parenteral amphotericin B, while retail and specialty pharmacies capture maintenance-phase posaconazole and isavuconazole volumes.
- Amphotericin B:Liposomal and conventional formulations serve as first-line backbone therapy for angioinvasive disease. Demand concentrates in tertiary care centers across India, Brazil, and the United States where uncontrolled diabetes and hematologic malignancy patient volumes drive acute admissions. Nephrotoxicity monitoring requirements lock this segment into intensive care settings with premium pricing.
- Posaconazole:Oral and intravenous formulations enable step-down therapy after initial stabilization. Brazilian private hospital chains and US academic medical centers are expanding prophylactic use in transplant populations, displacing extended amphotericin B courses and compressing per-case revenue.
- Isavuconazole:Broad-spectrum triazole with improved renal safety profile for maintenance therapy.
- Echinocandins:Adjunctive therapy in combination regimens for refractory pulmonary infections.
By volume, amphotericin B leads. By growth pace, posaconazole is expanding most quickly.
End User:
Customer concentration follows treatment complexity—surgical debridement and parenteral administration requirements anchor revenue in institutional settings, while homecare penetration remains limited to stable oral maintenance patients.
- Hospitals:Integrated delivery networks and specialty care centers capture the dominant share of acute intervention revenue. India's tertiary care facilities in Delhi, Mumbai, and Hyderabad manage concentrated diabetes-related case burdens through centralized procurement under CDSCO quality standards.
- Clinics:Outpatient infusion centers and wound care facilities are expanding access for stable patients requiring extended therapy.
- Research Institutions:Academic medical centers in the United States and Europe drive off-label protocol development and resistance surveillance.
- Homecare:Limited to oral azole maintenance in immunocompetent patients with completed surgical management.
Hospitals command margin concentration. Homecare shows the steepest expansion trajectory from minimal base.
Application:
Anatomical site determines acuity, pricing tier, and channel mix—rhinocerebral and pulmonary presentations require inpatient management, while cutaneous detection protocols create earlier intervention opportunities.
- Pulmonary Infection:Angioinvasive lung involvement demands immediate intensive care admission with liposomal amphotericin B and surgical consultation. US academic medical centers and Brazilian private chains report highest mortality burdens and premium reimbursement for these cases.
- Cutaneous Infection:Trauma-associated and nosocomial skin presentations enable earlier detection through dermatology and wound care channels. India's expanding diabetic foot care programs are building screening infrastructure that captures cases before hematogenous dissemination.
- Chronic Rhinosinusitis:Rhinocerebral extension from sinus origin requires combined surgical and medical management.
- Disseminated Infection:Multi-organ involvement in profoundly immunosuppressed patients with highest mortality.
Pulmonary applications lead by revenue per case. Cutaneous detection protocols are gaining share fastest through earlier identification.
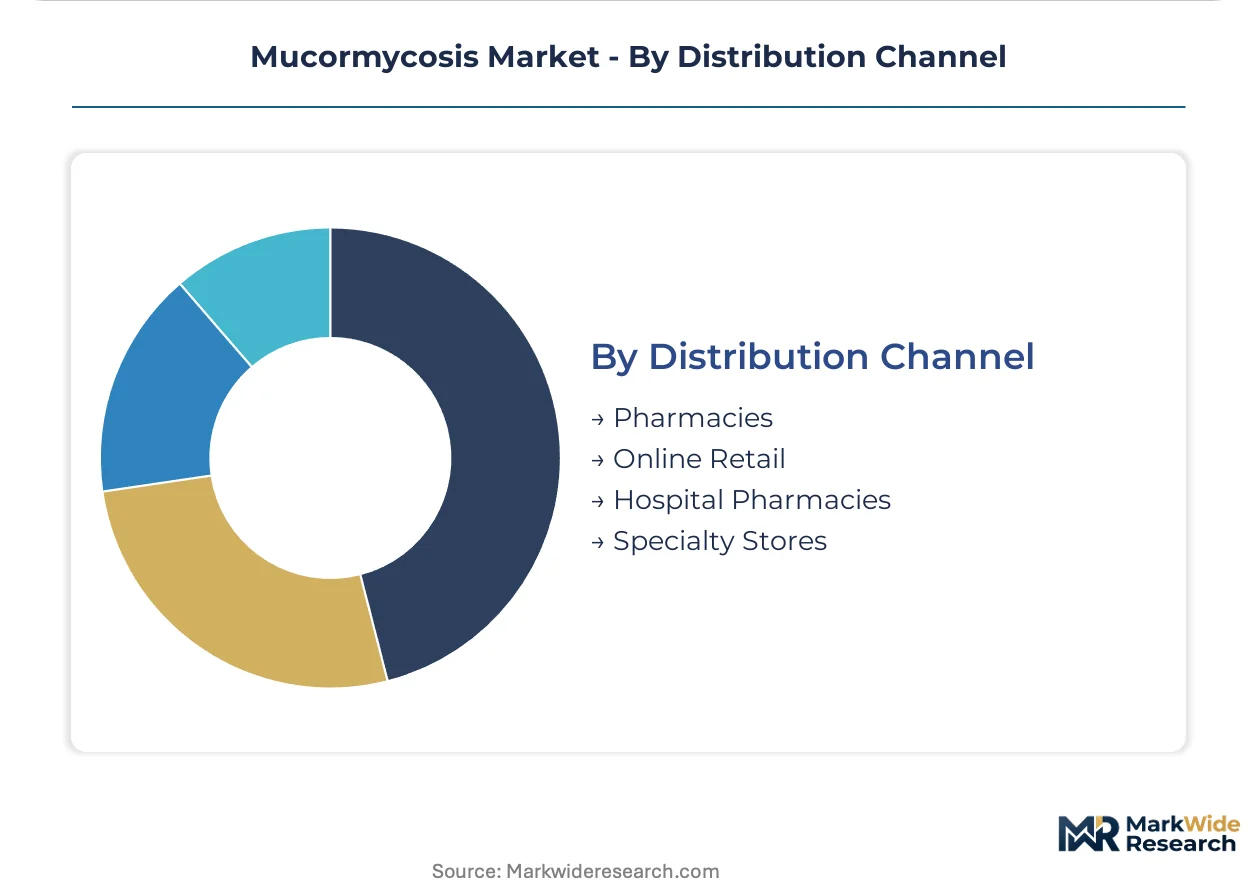
Distribution Channel:
Cold-chain requirements and formulary consolidation reshape channel economics—hospital pharmacies capture parenteral volumes while retail and online channels compete for stable outpatient maintenance.
- Hospital Pharmacies:Cold-chain infrastructure and parenteral compounding capabilities concentrate amphotericin B distribution. Integrated delivery networks in the United States and hospital chains in Brazil are centralizing procurement through pharmacy and therapeutics committees.
- Pharmacies:Community and specialty retail channels capture oral azole maintenance prescriptions post-discharge.
- Online Retail:Direct-to-patient delivery expanding for chronic prophylaxis in remote geographies.
- Specialty Stores:Limited role in wound care product adjacencies for cutaneous infection management.
Hospital pharmacies dominate value capture. Online retail is climbing the fastest from emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports amphotericin B formulations to Brazil, Nigeria, and Southeast Asian acute care networks, establishing the dominant trade-flow corridor for parenteral antifungal therapies.
United States
Hematologic malignancy centers and solid organ transplant programs drive concentrated demand for liposomal amphotericin B. FDA orphan drug designations accelerate pipeline access for resistant Mucorales therapies. Academic medical centers in Boston, New York, and Houston anchor procurement centralization through integrated delivery networks.
India
Uncontrolled diabetes prevalence and post-COVID mucormycosis surveillance infrastructure sustain elevated case volumes requiring surgical and medical intervention. CDSCO manufacturing standards and PLI scheme incentives expand domestic amphotericin B production capacity. Tertiary care clusters in Delhi, Mumbai, and Hyderabad manage concentrated diabetes-related burdens through centralized hospital procurement.
Brazil
Private hospital chains and transplant centers generate sustained demand for posaconazole prophylaxis in immunosuppressed populations. ANVISA regulatory pathways govern import and distribution of novel antifungal agents. São Paulo and Rio de Janeiro metropolitan areas concentrate specialty care infrastructure and formulary decision-making authority.
Germany
Hematology-oncology centers and transplant units drive maintenance-phase azole consumption following acute amphotericin B stabilization. EMA accelerated assessment pathways compress review timelines for novel Mucorales-targeting agents. University hospitals in Berlin, Munich, and Heidelberg coordinate resistance surveillance and off-label protocol development.
Japan
Aging immunocompromised populations and expanding transplant programs sustain prophylactic antifungal demand. PMDA review frameworks govern market entry for novel polyene and triazole formulations. Tokyo, Osaka, and Nagoya medical centers concentrate diagnostic mycology expertise and parenteral therapy administration.
Mucormycosis Market Vendor Landscape
Listed leaders compete with private specialists across hospital formulary access and manufacturing scale. Pfizer, Merck, and Novartis anchor the consolidated tier through established acute care relationships and parenteral production infrastructure. Mid-tier generic houses and biosimilar specialists compete on price in emerging markets with cost-engineered formulations. Competitive moves center on liposomal formulation licensing and integrated delivery network contracting consolidation.
Within the multinational pharmaceutical tier, Pfizer Inc. and Merck & Co., Inc. occupy positions defined by hospital formulary anchoring and manufacturing scale. Biocon Limited exemplifies the emerging-market specialist archetype, competing through cost-engineered production capabilities. These three entities represent distinct strategic postures: formulary dominance, manufacturing depth, and price-access positioning respectively.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| Sanofi |
| Abbott Laboratories |
| Biocon Limited |
| Cadila Pharmaceuticals Limited |
| Gilead Sciences |
| Teva Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
CDSCO manufacturing standards and BIS quality certifications gate both supplier qualification and price differentiation simultaneously, creating tiered access to regulated markets where liposomal formulation capabilities command substantial premiums over conventional amphotericin B. Hospital formulary consolidation amplifies this dynamic, concentrating purchasing power among integrated delivery networks that negotiate volume-based contracts while excluding uncertified manufacturers from premium tier consideration.
Pricing Analysis
Current-generation liposomal amphotericin B formulations carry substantial premiums over conventional polyene therapies, while next-generation nanotechnology-enabled delivery systems are entering at super-premium positioning. Three-tier pricing structure across premium liposomal, standard conventional, and economy generic formulations dominates hospital procurement. Price differentiation rests on nephrotoxicity profiles and cold-chain stability specifications, with Brazilian private chains and US academic medical centers showing lowest price sensitivity for critical-care applications. Cost compression in conventional amphotericin B is intensifying because Indian PLI scheme incentives are expanding domestic manufacturing capacity.
Supply Chain Analysis
Container availability constraints on India-Brazil and India-Nigeria trade lanes are elevating inbound logistics costs for parenteral antifungal shipments requiring continuous cold-chain maintenance. Active pharmaceutical ingredient production clusters in India and China, with formulation finishing in the United States and Germany, create geographic concentration exposure. Raw material dependencies on fermentation-derived polyene compounds, specialized lipid excipients, and pharmaceutical-grade solvents feed from agricultural and petrochemical supply bases. Single-source vulnerability in liposomal formulation technology creates supply chain risk. Distribution runs through hospital pharmacy networks with direct manufacturer contracting, bypassing wholesale intermediaries for temperature-sensitive parenteral therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across this market as diagnostic mycology expertise scarcity creates geographic niches where early detection protocols can capture cases before tertiary care referral. Uncontrolled diabetes prevalence expansion in emerging markets generates addressable patient volumes outside established hospital network dominance.
For Market Incumbents: Fortify hospital formulary anchoring through integrated delivery network contracting consolidation, securing multi-year volume commitments with specialty care centers managing transplant and oncology populations. Liposomal formulation licensing agreements provide defensive moats against posaconazole substitution pressure. Manufacturing scale investments in Indian CDSCO-certified facilities address API supply concentration risks while capturing PLI scheme benefits. For New Entrants and Emerging Players: Differentiate on cutaneous early detection protocols, building dermatology and wound care channel relationships before angioinvasive progression forces tertiary care referral. India's expanding diabetic foot care programs represent the most penetrable geography for topical and oral antifungal prophylaxis entry. Direct-to-hospital sales models bypassing consolidated procurement committees offer viable go-to-market angles for cost-engineered biosimilar formulations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed generic pharmaceutical houses possessing Indian manufacturing footprints and emerging market distribution networks. Long-term viability hinges on resistance surveillance infrastructure and pipeline positioning for novel Mucorales-targeting agents. Acquisition targets with liposomal formulation capabilities and CDSCO export certification demonstrate defensive value. The signal to watch is EMA accelerated assessment pathway designations for breakthrough antifungal therapies.| Strategic Initiative | Industry Significance |
|---|---|
| Liposomal Formulation Licensing | Enables hospital discharge protocols that reduce per-case reimbursement exposure for US academic medical centers. |
| CDSCO Export Certification Investment | Opens EMA mutual recognition pathways for Indian manufacturers serving regulated European markets. |
| Integrated Delivery Network Contracting | Captures volume commitments from Brazilian private hospital chains consolidating formulary decisions. |
| Cutaneous Detection Protocol Development | Builds dermatology channel access before rhinocerebral or pulmonary progression forces intensive care admission. |
| Cold-Chain Infrastructure Expansion | Addresses parenteral antifungal stability requirements across distribution networks and ward-level storage. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital formulary directors, CDSCO regulatory affairs leads, parenteral manufacturing plant managers, and hematology-oncology clinicians. Secondary validation drew from FDA orphan drug designation filings, EMA accelerated assessment pathway records, ClinicalTrials.gov protocol registries, and Indian PLI scheme beneficiary disclosures. Bottom-up patient volume modeling triangulated against top-down pharmaceutical revenue estimates.
Across the analysis window, forecasts employed segmented modeling by treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs were derived from patient epidemiology projections, therapy penetration assumptions, and pricing trajectory analysis. Forecast inputs incorporated uncontrolled diabetes prevalence trends, transplant program expansion rates, and resistance surveillance data from tertiary academic centers.
The analysis sits within stated boundaries; outcomes outside sustained immunocompromised patient volume growth, stable regulatory exclusivity timelines, and intact cold-chain infrastructure investment would require recalibration. Forecasts reflect documented assumptions regarding posaconazole substitution rates and liposomal formulation adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Glioblastoma Multiforme (GBM) Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Amoxicillin Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Cancer RNA Expression Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Cell and Tissue Preservation Market