
 X-Linked Hypophosphatemia Market | 2026-2036
X-Linked Hypophosphatemia Market Size, Share, and Industry Trends Forecast 2026-2036
X-Linked Hypophosphatemia Market Outlook
Aftermarket patient support and adherence program revenue is tilting toward integrated care platforms that bundle drug delivery with bone mineral monitoring. Ultragenyx Pharmaceutical Inc leverages its rare disease commercial infrastructure to sustain direct-to-patient logistics across North America. Kyowa Kirin Co., Ltd anchors its position through deep specialization in endocrinology and mineral metabolism. Ascendis Pharma competes via extended-release technology platforms that reduce injection frequency for chronic XLH management.
X-linked hypophosphatemia is a phosphate-wasting disorder caused by pathogenic variants in the PHEX gene, resulting in elevated fibroblast growth factor 23 levels, hypophosphatemia, and defective bone mineralization that manifests as rickets in children and osteomalacia in adults. The condition demands lifelong therapeutic intervention to restore phosphate homeostasis and prevent skeletal deformity. Hormonal therapies dominate current prescribing patterns, while gene therapy represents the fastest-growing development category as investigators target durable correction of FGF23 dysregulation. Pediatric patients constitute the primary addressable population, though adult patient segments expand as awareness of persistent disease burden improves.
FDA orphan drug designation and breakthrough therapy pathways shape clinical development economics, while EMA pediatric investigation plans mandate age-appropriate study designs that extend market exclusivity timelines. The EU AI Act introduces compliance considerations for algorithmic diagnostic tools that identify XLH from biochemical patterns. Stakeholders must monitor regulatory convergence between FDA and EMA on gene therapy manufacturing standards and decide whether to prioritize platform investments in antisense oligonucleotides or CRISPR-based approaches.
Market Dynamics
The X-Linked Hypophosphatemia market pivots on the tension between chronic phosphate replacement paradigms and durable gene correction approaches, with regulatory incentives for rare disease innovation accelerating pipeline diversification beyond conventional hormonal therapy.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market exclusivity provisions de-risk development economics for PHEX-targeted biologics, drawing venture capital into mineral metabolism programs previously abandoned for commercial uncertainty.
- Pediatric Investigation Plans:EMA-mandated age-stratified study designs extend data protection timelines while forcing adult indication expansion, broadening addressable populations across the European Economic Area.
- Endocrinology Referral Networks:Concentrated specialist infrastructure in the United States, Germany, and Japan compresses time-to-diagnosis for pediatric rickets presentations, accelerating therapy initiation before skeletal deformity progression.
Market Restraints
- Recombinant Protein Manufacturing Concentration:Single-source contract manufacturing organizations in Switzerland and Singapore create supply vulnerability for FGF23-targeting monoclonal antibodies requiring mammalian cell culture.
- Phosphate Binder Substitution:Generic sevelamer and lanthanum carbonate erode pricing power for mild-to-moderate hypophosphatemia cases in cost-sensitive health systems, limiting biologic therapy to refractory populations.
- Biopsy-Dependent Diagnosis:Required bone histomorphometry and genetic confirmation protocols delay treatment initiation by 4-12 months in under-resourced regions lacking molecular pathology capacity.
Strategic Opportunities
- Adult Osteomalacia Expansion:Persistent skeletal pain and fracture burden in diagnosed-but-untreated adult XLH patients represents a therapy-naive segment exceeding pediatric prevalence in developed markets.
- Direct-to-Patient Logistics:Cold-chain home delivery platforms bypass hospital pharmacy intermediaries, capturing adherence program revenue previously ceded to specialty distributors.
- CRISPR-ASO Convergence:Liver-targeted base editing combined with chemically modified oligonucleotides offers potential single-administration FGF23 suppression, displacing lifelong injection burden.
Industry Challenges
- Rare Disease Trial Recruitment:PHEX variant heterogeneity and geographic patient dispersion necessitate multi-national protocols with divergent ethics review timelines, extending Phase II enrollment by 18-24 months.
- Biomarker Standardization:Discordant fibroblast growth factor 23 assay platforms across central laboratories corrupt cross-trial comparability, complicating regulatory submissions and payer technology assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Linked Hypophosphatemia Market |
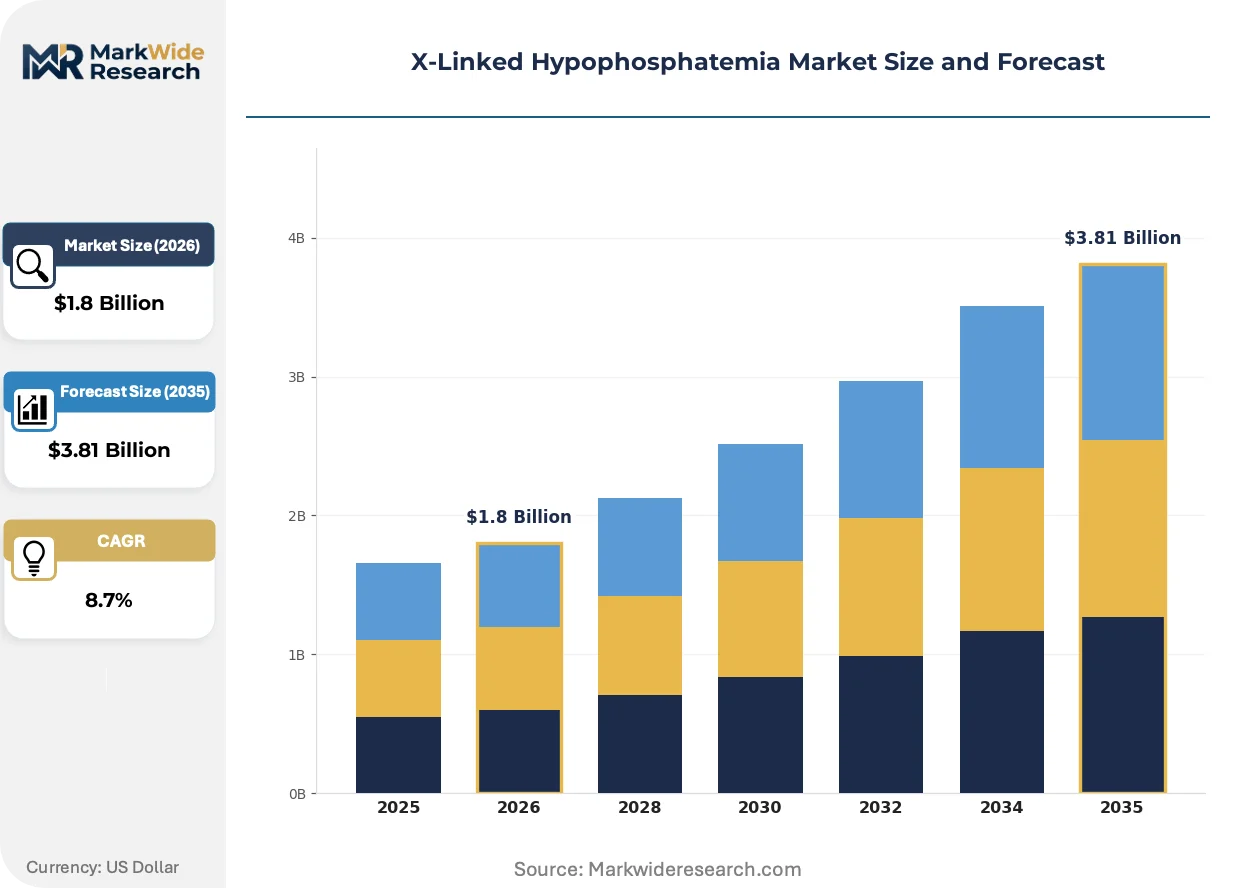
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapies, Nutritional Supplements, Antibodies, Gene Therapy End User: Pediatric Patients, Adult Patients, Caregivers, Healthcare Providers Delivery Mode: Injectables, Oral Tablets, Infusions, Topical Applications Application: Clinical Trials, Routine Management, Patient Education, Research Studies |
| Companies Covered | Ultragenyx Pharmaceutical Inc, Kyowa Kirin Co., Ltd, Ascendis Pharma, BioMarin Pharmaceutical Inc, Chiesi Farmaceutici, Novartis AG, Radius Health, Inc., Pfizer, Novo Nordisk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Linked Hypophosphatemia Market Strategic Shifts
Gene therapy platforms are virtualizing chronic disease management paradigms in mineral metabolism, while regulatory frameworks for rare disease manufacturing and algorithmic diagnostics reshape competitive entry requirements.
Extended-release transdermal delivery systems for phosphate-active hormones are virtualizing the injection frequency burden that has constrained adult adherence. Pediatric endocrinology practices in the United States and Germany are piloting these platforms for patients transitioning from parental to self-administered care. The technology is virtualizing compliance metrics as a differentiated value proposition in payer contract negotiations.
EMA's AI Act implementation creates compliance obligations for diagnostic algorithms that flag XLH from biochemical pattern recognition in electronic health records. Developers must document training data provenance and algorithmic interpretability for notified body review before clinical deployment. France's ANSM and Germany's BfArM are issuing divergent guidance on real-world evidence acceptance for AI-augmented diagnosis, fragmenting European go-to-market strategies.
Integrated care platforms now bundle drug delivery with home-based bone mineral density monitoring, displacing the hospital-centric follow-up model that has dominated XLH management. Specialty pharmacies are capturing patient relationship ownership from academic medical centers in the United States and Japan. This channel migration concentrates in markets with established remote therapeutic monitoring reimbursement codes.
X-Linked Hypophosphatemia Market Segmentation
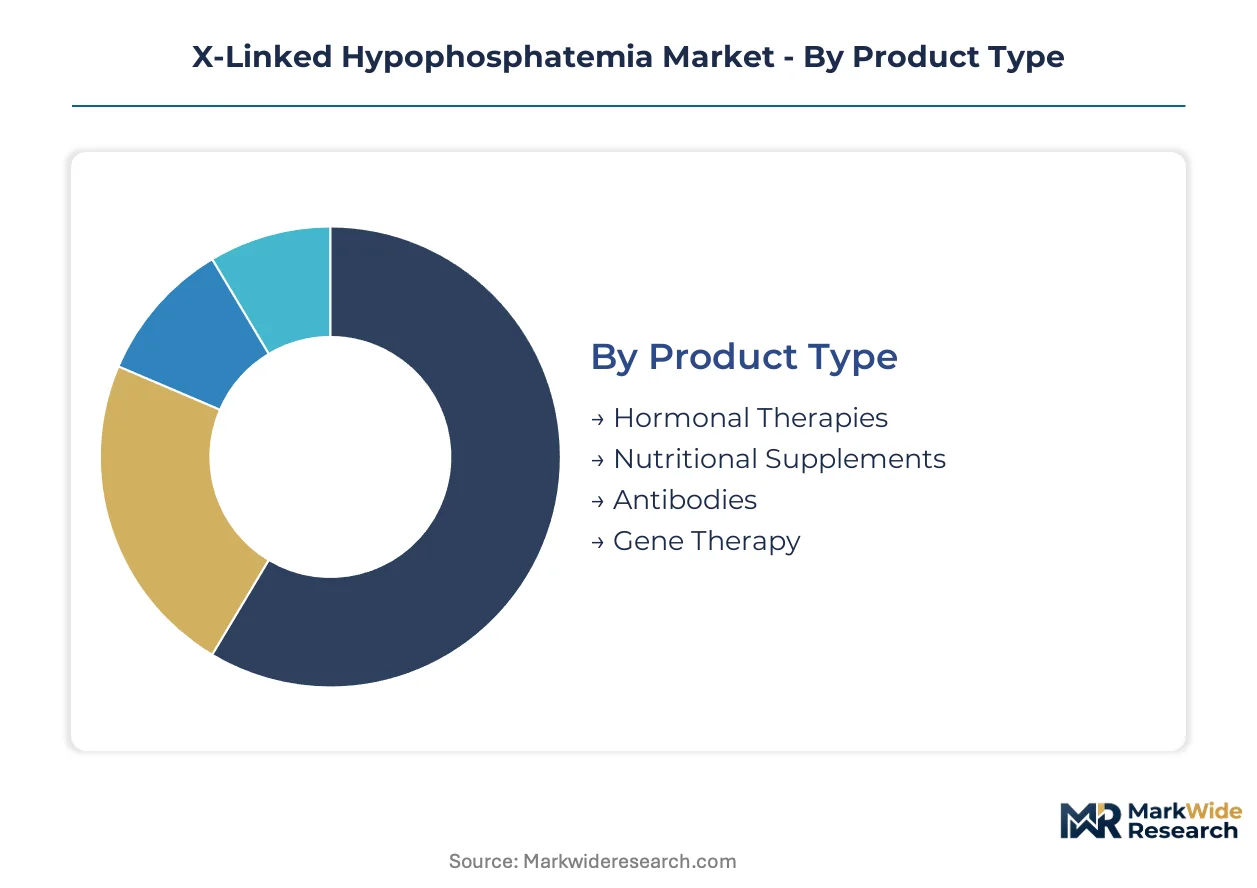
XLH market segmentation reveals divergent commercial rhythms across therapeutic modalities. Hormonal therapies command established revenue streams while gene therapy platforms compress multi-year treatment cycles into single-administration events, fundamentally altering patient lifetime value calculations for manufacturers.
Product Type:
Cycle times vary dramatically across this category, with chronic administration therapies generating recurring revenue against one-time curative interventions that front-load economic returns.
- Hormonal Therapies:Comprising phosphate-active hormones and FGF23-neutralizing biologics administered via subcutaneous injection. Demand concentrates in pediatric endocrinology practices across the United States and Germany, where specialist referral networks compress diagnosis-to-treatment intervals. Reimbursement frameworks in these markets favor chronic therapy paradigms with established billing codes.
- Gene Therapy:Liver-targeted viral vectors and base-editing platforms designed for single-administration FGF23 correction. Development pipelines concentrate in Massachusetts and Basel biotech clusters, drawn by FDA orphan drug exclusivity and EMA pediatric investigation plan incentives. Manufacturing scale-up constraints currently limit commercial availability.
- Antibodies:Monoclonal constructs targeting circulating FGF23 protein.
- Nutritional Supplements:Phosphate and vitamin D formulations for adjunctive management.
Hormonal Therapies anchors the volume base while Gene Therapy gains share at the steepest rate.
End User:
Cost-tier stratification separates high-acuity pediatric populations requiring intensive monitoring from adult segments with unmet therapy demand and lower per-patient intervention intensity.
- Pediatric Patients:Children with active rickets and skeletal deformity progression requiring growth-plate monitoring. Treatment centers in Boston, Heidelberg, and Tokyo maintain dedicated XLH clinics with multi-disciplinary teams. Parental adherence support programs drive ancillary service revenue.
- Adult Patients:Diagnosed-but-untreated individuals with persistent osteomalacia, bone pain, and fracture burden. This segment exceeds pediatric prevalence in developed markets yet remains therapy-naive due to historical disease awareness gaps. Specialty pharmacies in the United States are deploying direct-to-patient logistics to capture this expansion.
- Caregivers:Family members managing home injection protocols and dietary compliance.
- Healthcare Providers:Endocrinologists, geneticists, and orthopedic surgeons coordinating care.
Pediatric Patients anchors the volume base while Adult Patients climbs the fastest as awareness campaigns penetrate primary care settings.
Delivery Mode:
Application context dictates modality selection, with hospital-based infusion requirements contrasting against self-administered platforms that shift care settings toward home environments.
- Injectables:Subcutaneous devices for FGF23-targeting biologics and phosphate-active hormones. Extended-release formulations from Copenhagen and California developers are reducing injection frequency from daily to weekly or monthly intervals. Pediatric transition programs in Germany pilot these platforms for adolescent self-management.
- Oral Tablets:Phosphate salts and activated vitamin D analogues for baseline mineral replacement. Generic sevelamer and lanthanum carbonate substitution in cost-sensitive health systems limits biologic penetration to refractory cases.
- Infusions:Hospital-administered therapies requiring cardiac monitoring.
- Topical Applications:Transdermal hormone delivery systems in early clinical development.
Injectables anchors the volume base while Oral Tablets maintains stable share in emerging markets with limited specialty pharmacy infrastructure.
Application:
Volume concentration varies by purpose, with routine management generating steady throughput against episodic research and education activities with irregular cadence.
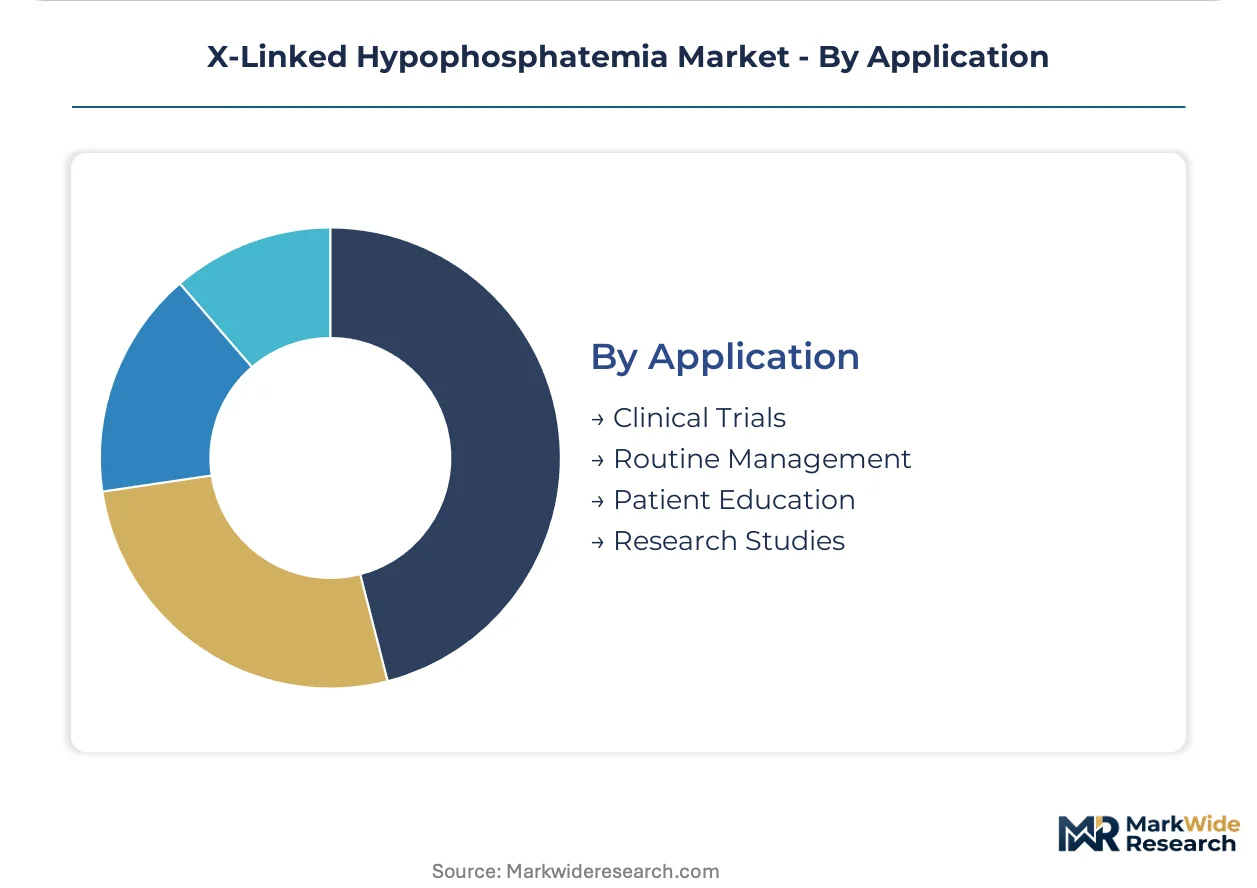
- Routine Management:Longitudinal care protocols encompassing phosphate homeostasis restoration, skeletal monitoring, and complication prevention. Integrated care platforms now bundle drug delivery with home-based bone mineral density monitoring, displacing hospital-centric follow-up models in the United States and Japan.
- Clinical Trials:PHEX-targeted intervention studies across Phase I-III development. Multi-national protocols face 18-24 month enrollment extensions due to variant heterogeneity and geographic patient dispersion.
- Patient Education:Adherence programs and disease awareness initiatives.
- Research Studies:Natural history registries and biomarker validation projects.
Routine Management anchors the volume base while Clinical Trials expands most quickly as gene therapy pipelines diversify beyond conventional hormonal approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets, with the United States and Germany prioritizing biologic FGF23-targeting therapies while Japan maintains stronger reliance on phosphate replacement protocols and adult osteomalacia screening programs.
United States
Pediatric endocrinology referral networks in Boston and New York Metro compress diagnosis-to-treatment intervals for childhood rickets presentations. FDA orphan drug exclusivity provisions and breakthrough therapy pathways accelerate PHEX-targeted biologics through clinical development. Ultragenyx Pharmaceutical Inc leverages its rare disease commercial infrastructure to sustain direct-to-patient logistics across North America.
Germany
Heidelberg and Hamburg maintain dedicated XLH clinics with multi-disciplinary teams managing growth-plate monitoring for pediatric populations. EMA pediatric investigation plans mandate age-stratified study designs that extend data protection timelines while forcing adult indication expansion. Extended-release transdermal delivery systems pilot in German adolescent transition programs for self-administered care.
Japan
Tokyo and Osaka specialist centers concentrate demand for FGF23-neutralizing biologics administered via subcutaneous injection. PMDA fast-track pathways for rare diseases align with METI industrial policy supporting domestic biotech manufacturing. Kyowa Kirin Co., Ltd anchors its position through deep specialization in endocrinology and mineral metabolism.
Switzerland
Basel biotech clusters concentrate gene therapy development pipelines drawn by EMA regulatory proximity and Swissmedic rare disease expertise. Single-source contract manufacturing organizations in Swiss territory create supply vulnerability for mammalian cell culture-dependent FGF23-targeting monoclonal antibodies. Geneva-based clinical research organizations coordinate multi-national protocols addressing PHEX variant heterogeneity.
United Kingdom
London and Cambridge maintain natural history registries and biomarker validation projects supporting clinical trial recruitment. MHRA alignment with EMA pediatric investigation plans facilitates parallel regulatory submissions for age-appropriate study designs. NHS England specialized commissioning frameworks concentrate XLH care in designated supraregional centers.
X-Linked Hypophosphatemia Market Competitive Environment
Capability concentration sits with biotech specialists possessing rare disease commercial infrastructure; scale advantage sits with diversified pharmaceutical incumbents with established endocrinology portfolios. The market structure tiers into three distinct archetypes: gene therapy platform developers pursuing single-administration FGF23 correction, extended-release formulation specialists reducing injection burden, and integrated care platform operators bundling drug delivery with remote monitoring. Dominant competitive moves include strategic partnerships between biotech innovators and specialty pharmacy distributors, plus portfolio diversification into adult osteomalacia segments previously underserved by pediatric-focused developers.
Within the rare disease biotech tier, Ultragenyx Pharmaceutical Inc and Ascendis Pharma exemplify contrasting technology strategies for chronic XLH management. Kyowa Kirin Co., Ltd occupies a distinct position as a Japan-based specialist with concentrated expertise in mineral metabolism and endocrinology therapeutic areas. Among diversified pharmaceutical incumbents, Novartis AG and Pfizer represent scale-driven players with existing endocrinology franchises that could extend into FGF23-targeting indications through licensing or acquisition.
| Leading Market Players |
|---|
| Ultragenyx Pharmaceutical Inc |
| Kyowa Kirin Co., Ltd |
| Ascendis Pharma |
| BioMarin Pharmaceutical Inc |
| Chiesi Farmaceutici |
| Novartis AG |
| Radius Health, Inc. |
| Pfizer |
| Novo Nordisk |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in mammalian cell culture facilities across Switzerland and Singapore concentrates manufacturing leverage for FGF23-targeting biologics, forcing developers to accept premium contract rates that cascade into end-product pricing postures. This utilization squeeze rewards vertically integrated players with captive production while squeezing margins for asset-light innovators dependent on single-source CDMO relationships.
Pricing Analysis
Long-term offtake agreements between biotech developers and specialty pharmacy distributors dominate XLH therapeutic procurement, displacing spot-market purchasing that characterized earlier phosphate replacement eras. Three-tier pricing structure across premium biologics, standard hormonal therapies, and economy generic binders separates insured pediatric populations from cost-sensitive adult segments in emerging markets. Pricing pressure stems from sevelamer and lanthanum carbonate substitution in mild-to-moderate cases, compressing biologic penetration to refractory populations. Pediatric endocrinology practices demonstrate lowest price sensitivity due to bundled reimbursement codes, while adult primary care channels exhibit acute responsiveness to out-of-pocket cost exposure.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates supply risk planning for FGF23-neutralizing monoclonal antibodies, with Basel-based CDMOs serving as single-source nodes for multiple pipeline candidates. Manufacturing gravity centers on Switzerland, Singapore, and Massachusetts, with each jurisdiction offering distinct regulatory proximity advantages. Raw material dependencies span recombinant protein media, viral vector plasmids, and chemically modified oligonucleotides. Distribution runs through cold-chain specialty pharmacy networks that bypass hospital intermediaries, concentrating patient relationship ownership in United States and Japanese markets with established remote therapeutic monitoring reimbursement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
XLH therapeutic development sits in early-cycle expansion as adult osteomalacia awareness campaigns penetrate primary care settings, creating therapy-naive demand that exceeds pediatric prevalence in developed markets.
For Market Incumbents: Build regulatory data moats through pediatric investigation plan completions that extend exclusivity timelines and complicate biosimilar entry. Secure backward integration into viral vector manufacturing to reduce dependency on Basel and Singapore CDMOs. Expand indication labels into adult fracture prevention before gene therapy platforms achieve commercial scale, capturing lifetime value from diagnosed-but-untreated populations. For New Entrants and Emerging Players: Geographic underpenetration in French and Spanish specialist networks offers white-space entry with lower competitive density than German or United States clusters. Target adult osteomalacia segments where historical disease awareness gaps have left patients therapy-naive despite skeletal burden. Deploy direct-to-patient logistics partnerships as primary go-to-market angle, displacing hospital-centric follow-up models. For Investors and Strategic Acquirers: Capital is best deployed toward gene therapy platform developers with liver-targeted base editing capabilities and existing EMA pediatric investigation plan approvals. Five-to-ten year viability hinges on manufacturing scale-up execution rather than clinical efficacy alone. Watch FDA gene therapy manufacturing guidance convergence with EMA standards as the critical inflection signal for portfolio reallocation between antisense and CRISPR modalities.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pediatric Investigation Plan Completion | Extends data protection timelines while mandating adult indication expansion across European Economic Area markets. |
| Direct-to-Patient Cold Chain Deployment | Captures adherence program revenue from academic medical centers in United States and Japanese reimbursement environments. |
| Extended-Release Formulation Development | Reduces injection frequency burden that has constrained adult adherence in chronic mineral metabolism management. |
| Gene Therapy Manufacturing Scale-Up | Overcomes single-source CDMO bottlenecks in Switzerland and Singapore for FGF23-targeting viral vectors. |
| Adult Osteomalacia Awareness Campaign | Penetrates primary care settings to capture therapy-naive diagnosed populations exceeding pediatric prevalence. |
Study Parameters
A spread of perspectives from pediatric endocrinologists, regulatory affairs leads at rare disease biotechs, specialty pharmacy distribution executives, and payer access specialists converged on the working assumptions underlying this analysis. Primary interview findings were cross-validated against FDA orphan drug designation databases, EMA pediatric investigation plan registries, ClinicalTrials.gov PHEX-targeted study records, and hospital procurement databases tracking FGF23 assay platform utilization. Bottom-up patient prevalence estimates and top-down revenue triangulation across therapeutic modalities were reconciled to establish forecast anchors.
Demand-supply balance modeling across the analysis window incorporated treatment line stratification, dosage form differentiation, administration route preferences, and regional regulatory cluster variations. CAGRs were derived from segment-level growth trajectory convergence, with gene therapy platforms assessed separately from chronic hormonal paradigms due to fundamentally different patient lifetime value profiles. Forecast inputs included biomarker assay standardization progress, reimbursement code expansion for remote therapeutic monitoring, and CDMO capacity utilization signals.
Practitioners should monitor gene therapy manufacturing guidance convergence between FDA and EMA, biomarker assay platform harmonization progress, and adult indication label expansion rates for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Testicular Cancer Drugs Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Asia-Pacific Bacteriophages Therapy Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Global Human Embryonic Stem Cells Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Anti-Cathepsin B Market
Medical Biotechnology
Global Mononucleosis Diagnostic Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
AI in Pharma and Biotech Market