
 Molecular Biomarkers for Cancer Detection Market | 2026-2036
Molecular Biomarkers for Cancer Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Biomarkers for Cancer Detection Market Foresight
A capital-intensity divergence between players is reorganizing competitive tiers in molecular biomarker supply. F. Hoffmann-La Roche Ltd. leverages its vertically integrated diagnostics platform to dominate high-throughput sequencing workflows. Thermo Fisher Scientific Inc. anchors its position through captive reagent manufacturing and global distribution infrastructure. Illumina Inc. differentiates via proprietary next-generation sequencing instrument ecosystems that lock in consumable recurring revenue.
Molecular biomarkers for cancer detection comprise measurable biological indicators—circulating tumor DNA, protein expression profiles, or epigenetic modifications—analyzed through standardized assay platforms to identify malignancy presence, subtype classification, or therapeutic response probability. Blood-based tests capture the fastest expansion as liquid biopsy platforms minimize invasive tissue acquisition while enabling serial monitoring; tissue-based tests retain margin concentration in companion diagnostic co-development partnerships with oncology drug sponsors. Next-generation sequencing segments lead technology value pools due to multiplexed panel scalability, while PCR segments sustain volume leadership in point-of-care and resource-limited settings where turnaround time governs clinical utility.
The FDA regulates analytical validity and clinical utility claims through its in vitro diagnostic and companion diagnostic pathways, while the EMA's IVDR transition in Europe elevates conformity assessment burdens for CE-marked biomarker assays. China's NMPA accelerates priority review for innovative tumor diagnostic products under its breakthrough device designation. Stakeholders must monitor regulatory divergence between jurisdictions as divergent evidentiary standards for clinical validation reshape market access timelines and localization requirements.
Market Dynamics
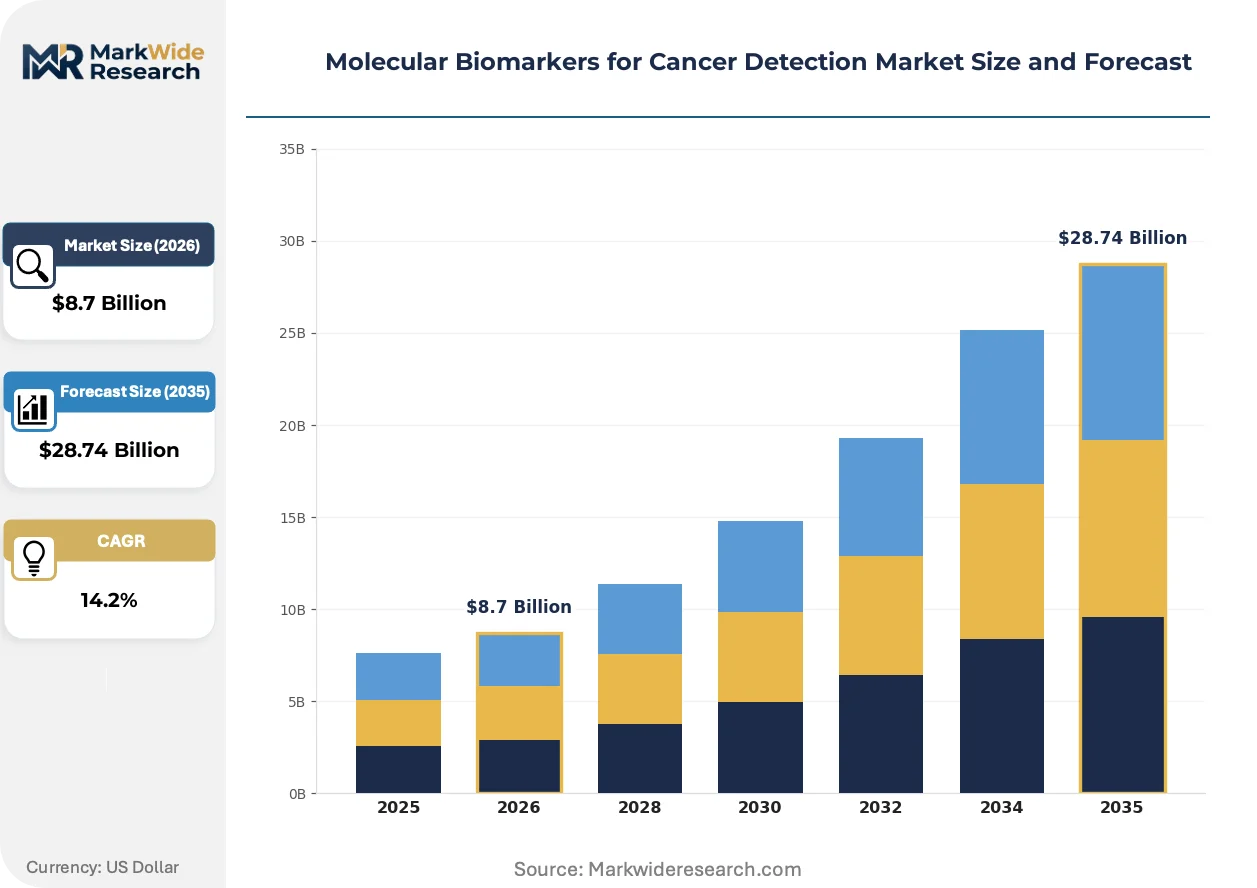
Liquid biopsy platforms are compressing the addressable market for tissue-based companion diagnostics while simultaneously expanding total screening volumes through serial monitoring protocols. This technological substitution is redrawing competitive boundaries between centralized laboratories and decentralized point-of-care testing networks.
Growth Catalysts
- IVDR Conformity Transition:The European Union's In Vitro Diagnostic Regulation elevates clinical evidence standards for CE-marked assays, accelerating consolidation among manufacturers with robust quality management systems and filtering lower-tier competitors from the commercial landscape.
- Clinical Laboratory Network Expansion:Integrated health systems in the United States are centralizing biomarker testing volumes into high-throughput reference laboratories, creating demand density that justifies capital deployment for automated NGS workflows and associated informatics infrastructure.
- Epigenetic Modification Detection:Methylation-based biomarker panels are capturing physician preference for early-stage malignancy screening due to superior specificity profiles compared with circulating tumor DNA alone, driving protocol adoption in oncology departments.
Market Restraints
- Reagent Supply Concentration:Enzyme and oligonucleotide manufacturing for PCR and sequencing workflows concentrates among a limited supplier base in Germany and the United States, exposing assay producers to input cost volatility and allocation risk during demand surges.
- Analytical Validation Burden:The FDA's evidentiary requirements for clinical utility claims in oncology indications demand prospective clinical trials with substantial enrollment, extending commercialization timelines and compressing effective patent life for novel biomarker signatures.
- Imaging-First Diagnostic Pathway:Radiological screening protocols for lung and breast malignancies retain institutional preference in many health systems, creating substitution resistance against blood-based alternatives despite comparable sensitivity metrics.
Strategic Opportunities
- China NMPA Priority Review:The breakthrough device designation for innovative tumor diagnostics compresses regulatory review timelines, enabling first-mover positioning in a market where centralized hospital procurement creates rapid volume scaling for approved assays.
- Multi-Cancer Early Detection Panels:Convergence of machine learning classification algorithms with expanded methylation marker sets is enabling single-test screening across multiple malignancy types, opening reimbursement negotiations with payors seeking population health management tools.
- Direct-to-Consumer Channel Development:Telemedicine platforms and employer wellness programs are creating novel distribution pathways for low-complexity biomarker screening, bypassing traditional hospital-based laboratory networks and capturing price-insensitive consumer segments.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical interpretation of complex NGS outputs requires hybrid expertise in molecular biology and computational pathology, a skill combination concentrated among academic medical centers and scarce in community laboratory settings.
- Laboratory Information System Integration:Biomarker assay data must interface with electronic health record platforms and oncology clinical decision support tools, creating implementation friction where legacy IT architectures lack interoperability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Biomarkers for Cancer Detection Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood-Based Tests, Tissue-Based Tests, Urine-Based Tests, Diagnostic Imaging Application: Oncology, Drug Discovery, Personalized Medicine, Prognostics Technology: Next-Generation Sequencing, PCR, Microarray, Mass Spectrometry End User: Hospitals, Clinical Laboratories, Research Institutions, Diagnostic Centers |
| Companies Covered | F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., QIAGEN N.V., Illumina Inc., Abbott Laboratories Inc., Bio-Rad Laboratories, Inc., Becton, Dickinson and Company, Agilent Technologies Inc., Myriad Genetics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Biomarkers for Cancer Detection Market Shifts & Advancements
Next-generation sequencing workflows are fragmenting into distinct performance tiers as clinical applications diverge between high-complexity comprehensive genomic profiling and rapid turnaround hotspot testing. This specialization is reshaping instrument purchasing patterns and consumable revenue models across the supply base.
Digital PCR technology is bifurcating the liquid biopsy market between ultra-sensitive rare mutation detection and standardized copy number quantification. Academic medical centers and pharmaceutical sponsors are adopting droplet-based digital PCR for minimal residual disease monitoring and clinical trial patient stratification. This adoption pattern is compressing the addressable market for quantitative real-time PCR in high-sensitivity applications while expanding total accessible volume through new clinical indications.
The FDA's expanding companion diagnostic approval framework is tightening evidentiary requirements for co-development partnerships between assay manufacturers and oncology drug sponsors. This regulatory evolution is forcing biomarker companies to commit capital earlier in pharmaceutical pipelines and accept milestone-dependent revenue structures. Small-to-mid-cap diagnostic developers with limited balance sheet capacity face exclusion from these partnerships, consolidating co-development activity among vertically integrated platforms.
Oncology departments are unbundling biomarker testing decisions from centralized pathology committee oversight, granting treating physicians direct authority to order comprehensive genomic profiling. This behavioral shift is compressing the influence of laboratory medical directors on test selection and accelerating adoption of multi-gene panels over single-analyte assays. The United States exhibits the most pronounced decentralization, where prior authorization requirements for Medicare reimbursement create administrative friction that physician practices seek to minimize through streamlined ordering protocols.
Molecular Biomarkers for Cancer Detection Market Segmentation
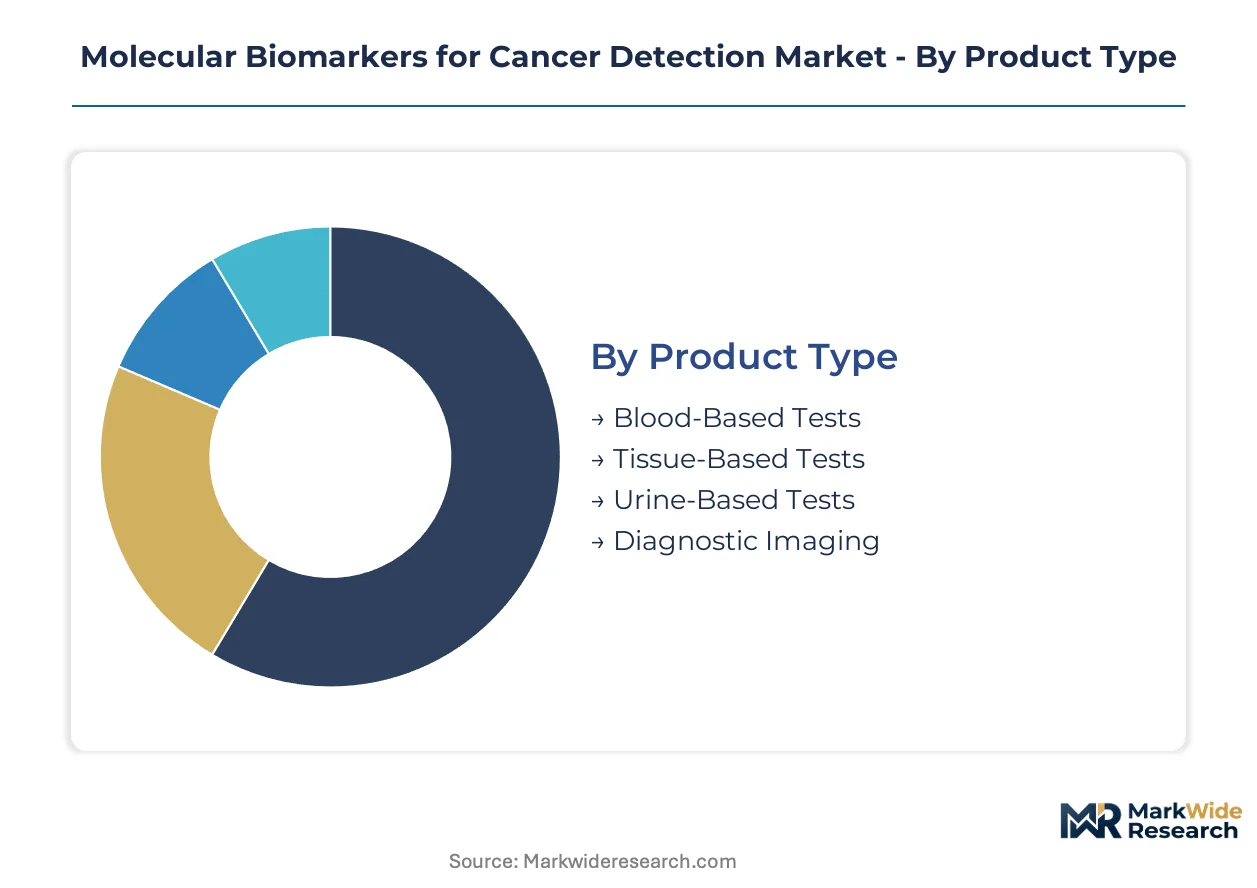
Segmentation in molecular biomarkers for cancer detection reflects divergent regulatory pathways, technology maturities, and site-of-care economics. Understanding these divisions enables stakeholders to align capital deployment with reimbursement velocity and clinical adoption curves.
Product Type:
FDA's liquid biopsy approval framework and EMA's IVDR conformity requirements create divergent commercialization timelines across specimen categories, reshaping manufacturer portfolio priorities.
- Blood-Based Tests:Circulating tumor DNA and methylation panels analyzed through standardized phlebotomy protocols enable serial monitoring without invasive tissue acquisition. Demand concentrates in United States integrated health systems where Medicare reimbursement for multi-cancer early detection is advancing through parallel review pathways.
- Tissue-Based Tests:Formalin-fixed paraffin-embedded specimens undergo comprehensive genomic profiling through centralized pathology workflows. Companion diagnostic co-development partnerships with oncology drug sponsors sustain margin concentration despite compression from liquid biopsy substitution.
- Urine-Based Tests:Non-invasive specimen collection for urological malignancy screening leverages prostate and bladder cancer biomarker signatures.
- Diagnostic Imaging:Radiological protocols retain institutional preference for initial malignancy detection in lung and breast indications.
Established volume favors tissue-based workflows; emerging adoption favors blood-based alternatives.
Application:
End-use economics separate high-throughput screening protocols from precision therapeutic selection, with reimbursement density varying sharply across clinical versus research contexts.
- Oncology:Malignancy detection, subtype classification, and therapeutic response prediction constitute the core revenue pool. United States hospital systems drive centralized testing volumes through prior authorization requirements that favor comprehensive genomic profiling over sequential single-analyte ordering.
- Personalized Medicine:Patient-specific treatment selection based on biomarker stratification commands premium pricing in immuno-oncology indications.
- Drug Discovery:Pharmaceutical sponsors utilize biomarker assays for patient stratification in clinical trials and companion diagnostic co-development.
- Prognostics:Minimal residual disease monitoring and recurrence prediction represent expanding clinical utility beyond initial diagnosis.
Screening applications scale through volume; therapeutic selection commands margin.
Technology:
Capital intensity and consumable recurring revenue models differentiate platform economics, with multiplexing capability determining competitive positioning in high-complexity versus rapid-turnaround segments.
- Next-Generation Sequencing:Massively parallel sequencing of multiplexed gene panels enables comprehensive genomic profiling with scalable throughput. Academic medical centers in the United States anchor instrument purchasing for oncology departments unbundling test decisions from centralized pathology oversight.
- PCR:Quantitative real-time and digital PCR variants sustain volume leadership in point-of-care and resource-limited settings where turnaround time governs clinical utility.
- Microarray:Hybridization-based detection of copy number variation and single nucleotide polymorphism retains niche applications in standardized screening panels.
- Mass Spectrometry:Protein expression profiling and metabolite detection address specific malignancy signatures outside nucleic acid-based workflows.
NGS captures technology value pools; PCR sustains geographic reach.
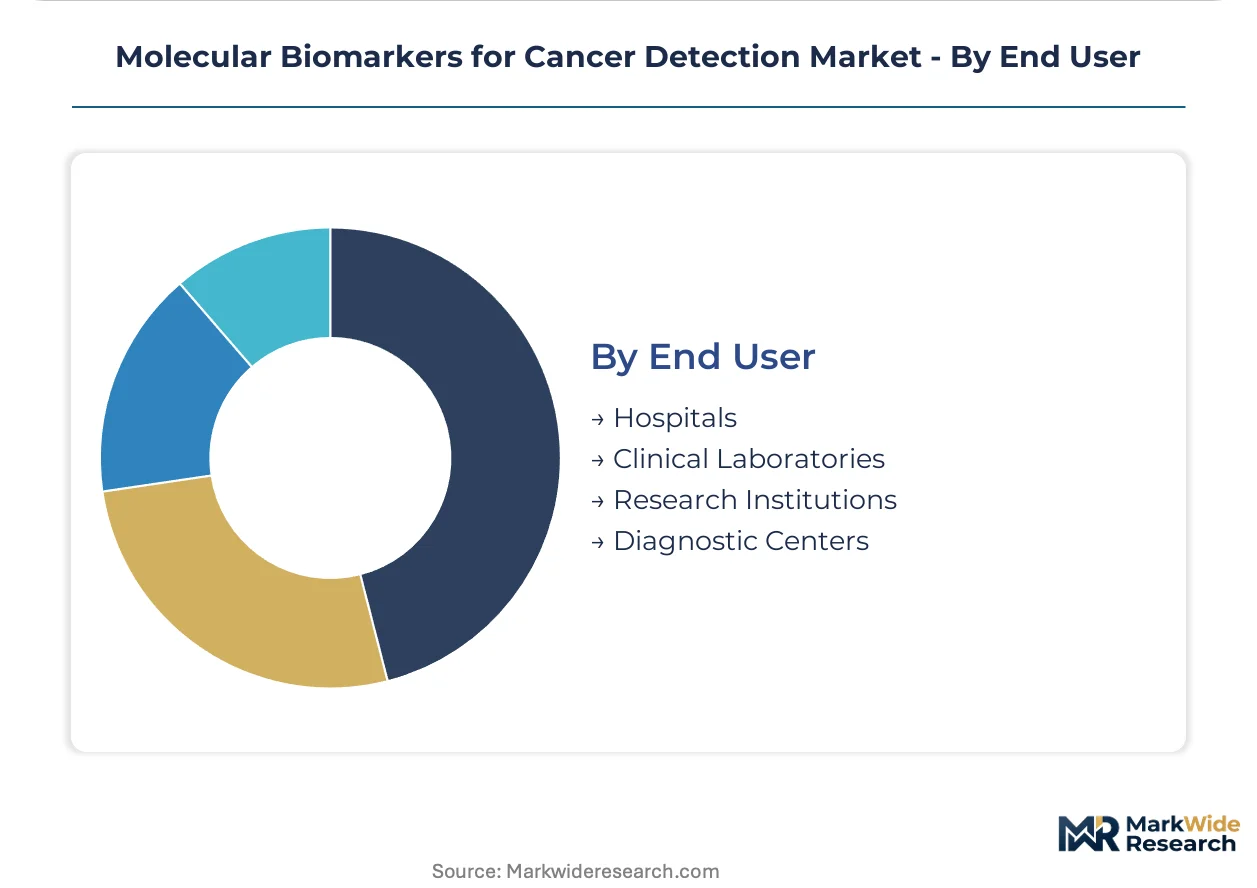
End User:
Site-of-care consolidation and informatics infrastructure requirements concentrate purchasing authority among entities with captive laboratory networks and integrated electronic health record systems.
- Clinical Laboratories:High-throughput reference laboratories within integrated health systems justify automated NGS workflows and associated bioinformatics infrastructure through demand density. United States centralized networks are scaling liquid biopsy adoption for early-stage screening protocols.
- Hospitals:In-house pathology departments retain tissue-based testing for urgent therapeutic decision-making.
- Diagnostic Centers:Independent facilities focus on standardized, high-volume assays with rapid turnaround requirements.
- Research Institutions:Academic medical centers concentrate hybrid expertise in molecular biology and computational pathology for biomarker discovery and clinical trial stratification.
Laboratory networks concentrate purchasing volume; hospital pathology retains strategic tests.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States buyers absorb premium pricing for comprehensive genomic profiling, while Chinese procurement favors cost-optimized panels and European purchasing balances quality standards against reimbursement constraints.
United States
Medicare reimbursement pathways for multi-cancer early detection and integrated health system consolidation drive centralized testing volumes. The FDA's expanding companion diagnostic framework accelerates commercialization timelines for liquid biopsy platforms. The Boston-Cambridge corridor anchors biomarker discovery activity, with academic medical centers scaling automated NGS workflows.
China
Centralized hospital procurement creates rapid volume scaling for approved tumor diagnostic assays. The NMPA's breakthrough device designation compresses regulatory review timelines for innovative products. The Yangtze River Delta region concentrates manufacturing capacity for PCR reagents and sequencing consumables.
Germany
Reference laboratory networks prioritize analytical quality systems for CE-marked assay adoption. The EMA's IVDR transition elevates conformity assessment burdens, filtering lower-tier competitors from procurement lists. The Munich-Stuttgart axis hosts precision medicine clusters advancing methylation-based screening protocols.
Japan
Aging demographics and universal health coverage sustain screening program volumes for early-stage malignancy detection. The PMDA prioritizes review for oncology companion diagnostics aligned with immuno-oncology drug launches. The Tokyo-Osaka corridor concentrates pharmaceutical-sponsored biomarker co-development partnerships.
United Kingdom
NHS England's genomic medicine service centralizes biomarker testing into designated laboratory hubs. The MHRA's post-Brexit regulatory framework maintains alignment with EMA evidentiary standards while streamlining domestic approval pathways. The Cambridge-London corridor anchors CRISPR-based diagnostic development and clinical trial stratification services.
Molecular Biomarkers for Cancer Detection Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in molecular biomarker supply. Vertically integrated diagnostics platforms dominate high-throughput sequencing workflows through captive reagent manufacturing and global distribution infrastructure. Specialist developers concentrate on proprietary assay content and algorithmic classification tools. Competitive moves center on companion diagnostic co-development partnerships and regulatory approval velocity for multi-cancer early detection panels.
Within the integrated diagnostics tier, F. Hoffmann-La Roche Ltd. and Thermo Fisher Scientific Inc. exemplify scale-driven positioning through instrument-reagent ecosystems and reference laboratory networks. Illumina Inc. occupies a distinct position anchoring next-generation sequencing platform supply with consumable recurring revenue models. These three entities represent divergent strategic archetypes: full vertical integration, reagent-distribution dominance, and platform technology lock-in respectively.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| Illumina Inc. |
| Abbott Laboratories Inc. |
| Bio-Rad Laboratories, Inc. |
| Becton, Dickinson and Company |
| Agilent Technologies Inc. |
| Myriad Genetics, Inc. |
| Others |
Supply & Pricing Matrix
Long-term reagent supply contracts with take-or-pay provisions dominate procurement strategies for high-throughput sequencing consumables, locking United States clinical laboratories into fixed-price commitments that insulate against enzyme and oligonucleotide cost volatility while constraining supplier switching flexibility.
Pricing Analysis
Consumable recurring revenue from proprietary sequencing reagent cartridges drives lifetime value capture for platform manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by test complexity and volume commitment, with academic medical centers absorbing premium comprehensive genomic profiling rates while community laboratories gravitate toward cost-optimized PCR panels. Cost compression in standard-tier assays is intensifying because of reagent supply concentration among German and United States manufacturers. Hospital pathology departments exhibit lowest price sensitivity due to urgent therapeutic decision-making requirements; independent diagnostic centers face highest sensitivity due to Medicare reimbursement rate compression.
Supply Chain Analysis
Inbound logistics costs from trans-Pacific shipping lanes and European air freight corridors expose assay manufacturers to container availability fluctuations and port congestion at Rotterdam and Los Angeles. Enzyme manufacturing concentrates in Germany and the United States; oligonucleotide synthesis clusters in South Korea and China; sequencing instrument assembly centers on the United States and Singapore. Critical dependencies include thermostable polymerases, fluorescent probe chemistries, and silicon chip-based flow cells. Single-source vulnerability from sole-qualified suppliers of modified nucleotides creates allocation risk during demand surges. Distribution runs through captive direct sales forces for premium platforms and third-party laboratory distributors for standardized reagent kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States integrated health systems that centralize biomarker testing volumes into designated reference laboratory networks, compressing vendor negotiation leverage and favoring suppliers with captive informatics infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into methylation panel manufacturing and algorithmic classification software to offset liquid biopsy substitution pressure. Expand capacity in China Yangtze River Delta region to capture NMPA breakthrough device designation volume scaling. Prioritize companion diagnostic co-development partnerships with immuno-oncology drug sponsors to lock in assay content exclusivity.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers regulatory velocity advantage for multi-cancer early detection panel developers lacking legacy infrastructure. Target direct-to-consumer channel development through telemedicine platforms and employer wellness programs as the most penetrable white-space segment. Pursue white-label manufacturing partnerships with established clinical laboratory networks to bypass capital-intensive instrument placement requirements.
For Investors and Strategic Acquirers: Specialist biomarker assay developers with proprietary methylation marker sets and machine learning classification algorithms represent priority acquisition targets for platform consolidation plays. Long-term viability hinges on reimbursement pathway establishment for screening indications beyond Medicare parallel review. Signal to watch: NMPA priority review queue depth as inflection indicator for China market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Locks in assay content exclusivity with FDA-aligned oncology drug sponsors. |
| Multi-Cancer Early Detection Panel Launch | Opens Medicare reimbursement negotiations for population health management tools. |
| Liquid Biopsy Platform Integration | Compresses tissue-based test substitution while expanding serial monitoring volumes. |
| China NMPA Breakthrough Designation Pursuit | Accelerates regulatory timelines in centralized hospital procurement markets. |
| Bioinformatics Infrastructure Acquisition | Addresses clinical interpretation talent scarcity in community laboratory settings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with clinical laboratory directors, hospital pathology committee chairs, regulatory affairs leads at diagnostics manufacturers, and GPO contracts managers, cross-validated against FDA 510(k) filings, EMA IVDR submission databases, CMS Medicare reimbursement determinations, and hospital procurement contract records, with bottom-up test volume modeling triangulated against top-down market sizing.
Across the analysis window, forecasts incorporate segmentation by specimen type, technology platform, end-user site-of-care, and regional regulatory cluster, with CAGRs derived from test volume elasticity modeling and pricing trajectory assumptions, incorporating NMPA review queue velocity, Medicare coverage determination timelines, and IVDR conformity assessment completion rates as industry-specific inputs.
Underlying assumptions cover stable Medicare reimbursement rates for multi-cancer early detection and uninterrupted reagent supply from German and United States manufacturing hubs, with deviation risk concentrated in FDA evidentiary requirement tightening and trans-Pacific logistics disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Next-Generation Sequencing Data Analysis Market
Genomics
Global Gene Amplification Technologies Market
Genomics
Forensic Genomics Market
Genomics
Molecular Breeding Market
Genomics
Global Molecular Cytogenetics Market
Genomics
Dna Polymerase Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
Oligonucleotide Pool Market
Genomics
Predisposition Biomarkers Market
Genomics
Whole Genome Amplification Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
NGS Automation Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market