
 T Cell-Specific Surface Glycoprotein CD28 Antibody Market | 2026-2036
T Cell-Specific Surface Glycoprotein CD28 Antibody Market Size, Share, and Industry Trends Forecast 2026-2036
T Cell-Specific Surface Glycoprotein CD28 Antibody Market Insights
Subscription-based access to antibody characterization databases is shifting how research institutions procure CD28-targeting reagents. Thermo Fisher Scientific leverages its analytical instrument installed base to bundle antibody supply with proteomics platforms. Regeneron Pharmaceuticals anchors its position through proprietary VelociSuite technologies that accelerate monoclonal discovery timelines. Johnson & Johnson Innovative Medicine competes via integrated development capabilities spanning discovery through late-stage immuno-oncology trials.
The T Cell-Specific Surface Glycoprotein CD28 Antibody comprises immunoglobulin constructs engineered to bind the CD28 costimulatory receptor on T lymphocytes, typically manufactured through Chinese hamster ovary cell culture with subsequent protein A chromatography purification; these reagents modulate T cell activation thresholds for therapeutic and analytical applications. Monoclonal antibody formats dominate current supply owing to batch consistency requirements in regulated therapeutic settings, while recombinant antibody segments attract investment for reduced immunogenicity profiles in next-generation constructs. Research institutions represent the most price-sensitive end user category, whereas pharmaceutical companies concentrate purchasing power around GMP-certified supply agreements.
FDA's Center for Biologics Evaluation and Research and EMA's Committee for Medicinal Products for Human Use enforce comparability protocol standards that dictate manufacturing documentation burdens for CD28 antibody developers. ISO 13485 quality management requirements and WHO prequalification pathways further shape market access for diagnostic-grade reagents versus therapeutic-grade materials. Stakeholders must monitor evolving biosimilar guidance frameworks and cell therapy co-development partnerships to anticipate shifts in antibody specification requirements and commercial prioritization.
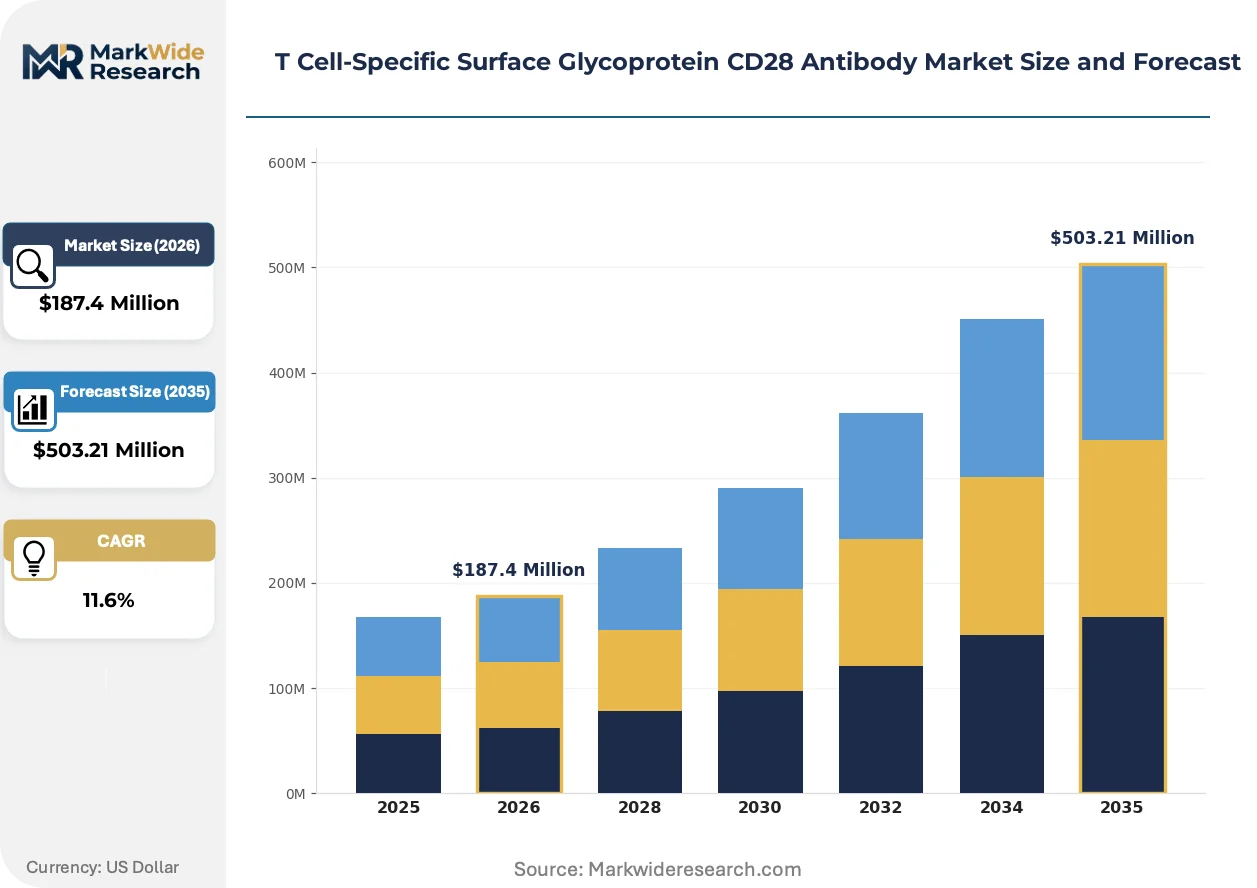
Market Dynamics
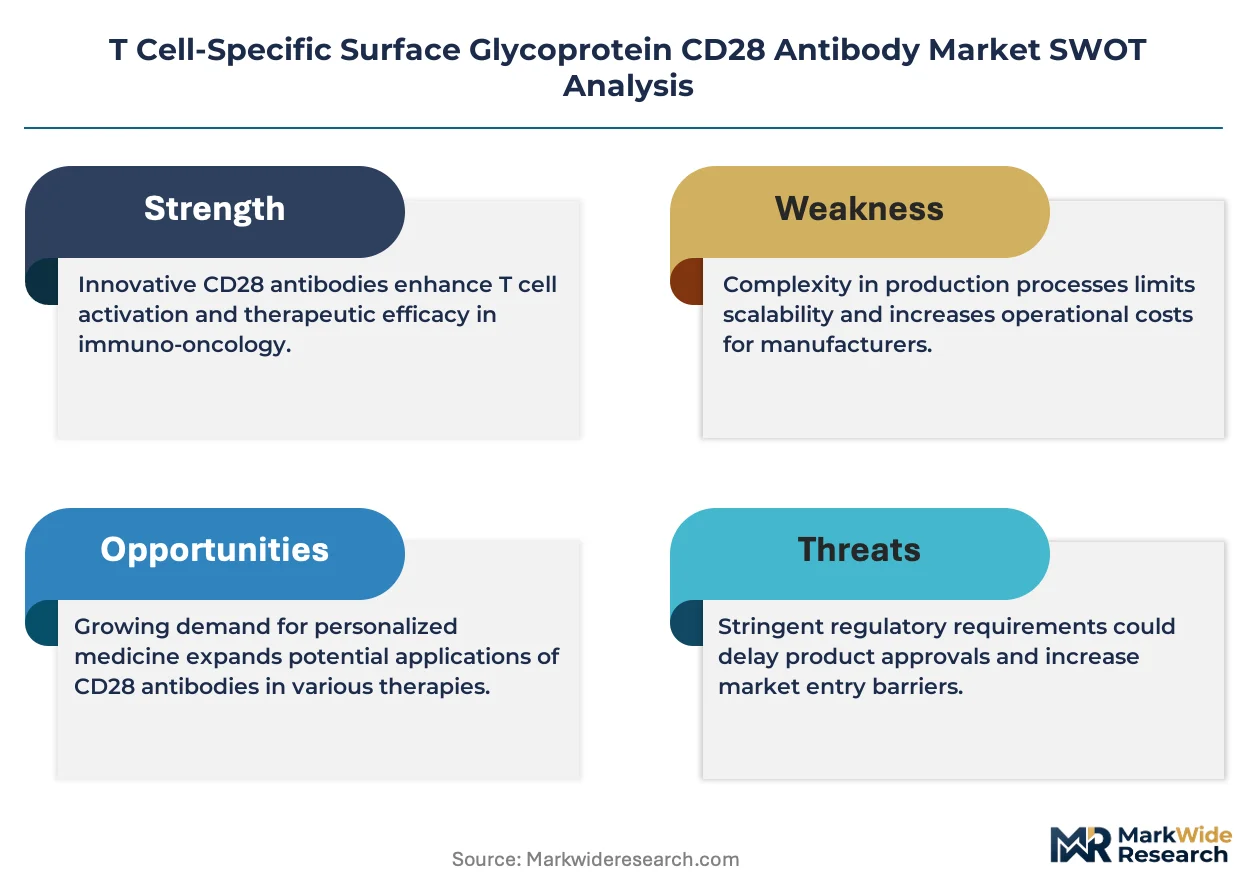
Accelerated approval pathways for biologics are compressing development timelines while intensifying competition for GMP-certified manufacturing slots among CD28 antibody developers.
Growth Catalysts
- FDA Accelerated Approval:The pathway reduces Phase III duration for immuno-oncology biologics, pulling forward revenue recognition for developers targeting CD28 costimulatory mechanisms.
- Cell Therapy Pipelines:CAR-T and TCR-T programs require CD28 antibodies as critical reagents for ex vivo T cell activation, creating sustained demand from contract development organizations.
- Chinese Hamster Ovary Cell Culture:Advances in fed-batch and perfusion bioreactor systems are lifting titers for complex immunoglobulin constructs, expanding economically viable supply.
Market Restraints
- Protein A Chromatography Resin Costs:Purification-grade resins command premium pricing with limited supplier diversity, compressing gross margins for research-grade antibody producers.
- ISO 13485 Certification Burden:Diagnostic-grade reagents require quality management system validation that extends commercialization timelines by 18-24 months relative to research-use-only materials.
- Recombinant Antibody Substitution:Next-generation constructs with reduced immunogenicity profiles threaten displacement of traditional monoclonal formats in therapeutic applications.
Strategic Opportunities
- EMA PRIME Designation:Priority medicines status offers enhanced regulatory support for CD28-targeting candidates addressing unmet immuno-oncology needs.
- Japan's Sakigake Pathway:PMDA's early approval system creates first-mover advantages for developers willing to anchor clinical development in Japanese trial sites.
- Single-Cell Analysis Convergence:Integration of CD28 antibodies with spatial transcriptomics platforms opens analytical applications beyond traditional flow cytometry.
Industry Challenges
- Comparability Protocol Complexity:Manufacturing changes for CHO-derived antibodies require extensive analytical characterization to satisfy FDA Center for Biologics Evaluation and Research standards.
- Biosimilar Guidance Uncertainty:Evolving FDA and EMA frameworks for biologic similarity create licensing risk for second-generation CD28 antibody entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | T Cell-Specific Surface Glycoprotein CD28 Antibody Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibody, Polyclonal Antibody, Recombinant Antibody, Conjugated Antibody Application: Targeted Therapy, Research Studies, Diagnostic Assays, Immunotherapy End User: Pharmaceutical Companies, Research Institutions, Clinical Laboratories, Biotech Firms Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | Rondo Therapeutics, Regeneron Pharmaceuticals, Johnson & Johnson Innovative Medicine, OPKO Health, Becton Dickinson and Company, Thermo Fisher Scientific, Eli Lilly and Company, Genentech (Roche), Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
T Cell-Specific Surface Glycoprotein CD28 Antibody Market Trends and Innovations
Recombinant expression systems and modular purification architectures are redistributing production capacity away from centralized biologics manufacturing toward distributed, platform-agnostic supply models.
Baculovirus expression systems are decentralizing production of smaller antibody fragments for research applications, enabling academic core facilities and mid-sized CROs to bypass traditional bulk procurement from centralized CHO manufacturers. Fragment crystallizable (Fc)-deficient constructs now constitute the fastest-growing format segment as developers seek reduced effector function in T cell modulation applications. This shift is compressing minimum order quantities and shortening fulfillment cycles for catalog antibody supply.
EMA's Committee for Medicinal Products for Human Use issued revised comparability guidelines in 2023 that mandate enhanced glycan profiling for immunoglobulin therapeutics, forcing CD28 antibody developers to invest in high-resolution mass spectrometry capabilities. The industrial consequence is a bifurcation between developers with captive analytical infrastructure and those dependent on contract testing laboratories. Therapeutic-grade manufacturers in Germany and Switzerland are responding by consolidating quality control functions under single-site certification to reduce documentation burden.
Consolidated purchasing agreements are displacing spot-market transactions among pharmaceutical end users, with immuno-oncology trial sponsors negotiating multi-year antibody supply contracts tied to clinical milestone achievement. CROs serving Phase I/II cell therapy studies are consolidating vendor panels to three preferred suppliers per antibody target, squeezing catalog distributors dependent on transactional revenue. This concentration is most visible in the United States, where National Cancer Institute-designated cancer centers have standardized CD28 antibody specifications across cooperative group trials.
T Cell-Specific Surface Glycoprotein CD28 Antibody Market Segmentation
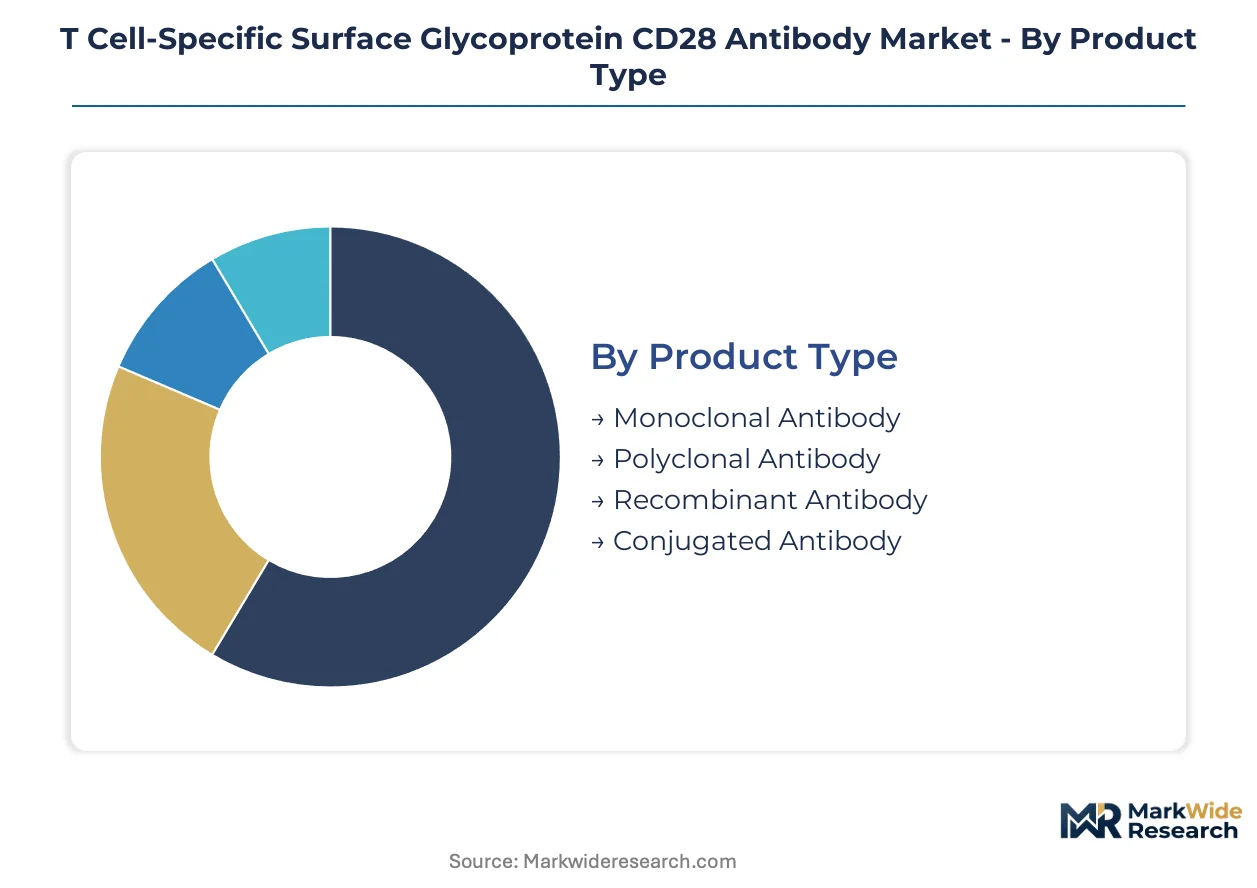
CD28 antibody procurement patterns diverge sharply across therapeutic versus analytical applications, with manufacturing standards and regulatory burdens creating distinct commercial tiers. Understanding these segment boundaries clarifies where pricing power concentrates and which customer categories drive specification evolution.
Product Type:
Volume production concentrates on established immunoglobulin formats, while premium positioning attaches to engineered constructs with reduced immunogenicity profiles.
- Monoclonal Antibody:Immunoglobulin constructs derived from single B-cell clones with defined specificity for CD28 epitopes. GMP-certified supply agreements from pharmaceutical companies in the United States and Germany anchor demand, driven by batch consistency mandates for therapeutic applications.
- Recombinant Antibody:Genetically engineered constructs produced through vector-based expression systems with modular Fc domains. Biotech firms in Switzerland and Massachusetts are concentrating purchasing here, attracted by reduced immunogenicity risk in next-generation immuno-oncology pipelines.
- Polyclonal Antibody:Heterogeneous immunoglobulin pools recognizing multiple CD28 epitopes.
- Conjugated Antibody:CD28-binding constructs linked to fluorophores, enzymes, or cytotoxic payloads.
Mature deployment sits with Monoclonal Antibody formats. Newer deployment is concentrated in Recombinant Antibody segments.
Application:
Commercial gravity shifts from analytical workflows toward therapeutic development as cell therapy pipelines mature.
- Immunotherapy:Clinical applications modulating T cell costimulation for cancer treatment. CAR-T and TCR-T developers in the United States and Japan are driving specification requirements, compelled by FDA and PMDA accelerated approval pathways for biologics.
- Research Studies:Academic and preclinical investigations of T cell activation mechanisms. National Cancer Institute-designated centers concentrate demand, constrained by grant-funded procurement cycles and price sensitivity.
- Targeted Therapy:Precision therapeutic interventions against CD28-expressing pathologies.
- Diagnostic Assays:Clinical laboratory detection and monitoring applications.
Established revenue concentration rests with Research Studies. Steepest expansion trajectory is occurring in Immunotherapy.
End User:
Customer scale determines contract structure, with large pharma consolidating supply agreements while fragmented academic buyers sustain spot-market channels.
- Pharmaceutical Companies:Integrated drug developers with captive manufacturing or preferred CMO relationships. Multi-year antibody supply contracts tied to clinical milestones dominate procurement in the United States and Germany.
- Biotech Firms:Venture-backed developers dependent on outsourced manufacturing and CDMO partnerships. Cell therapy specialists in Cambridge, Massachusetts and Basel, Switzerland are expanding fastest, pressured by compressed fundraising timelines.
- Research Institutions:Universities and academic medical centers with federal or institutional funding.
- Clinical Laboratories:Diagnostic service providers with ISO 13485 quality requirements.
Contract standardization is most advanced among Pharmaceutical Companies. Procurement innovation is concentrated in Biotech Firms.
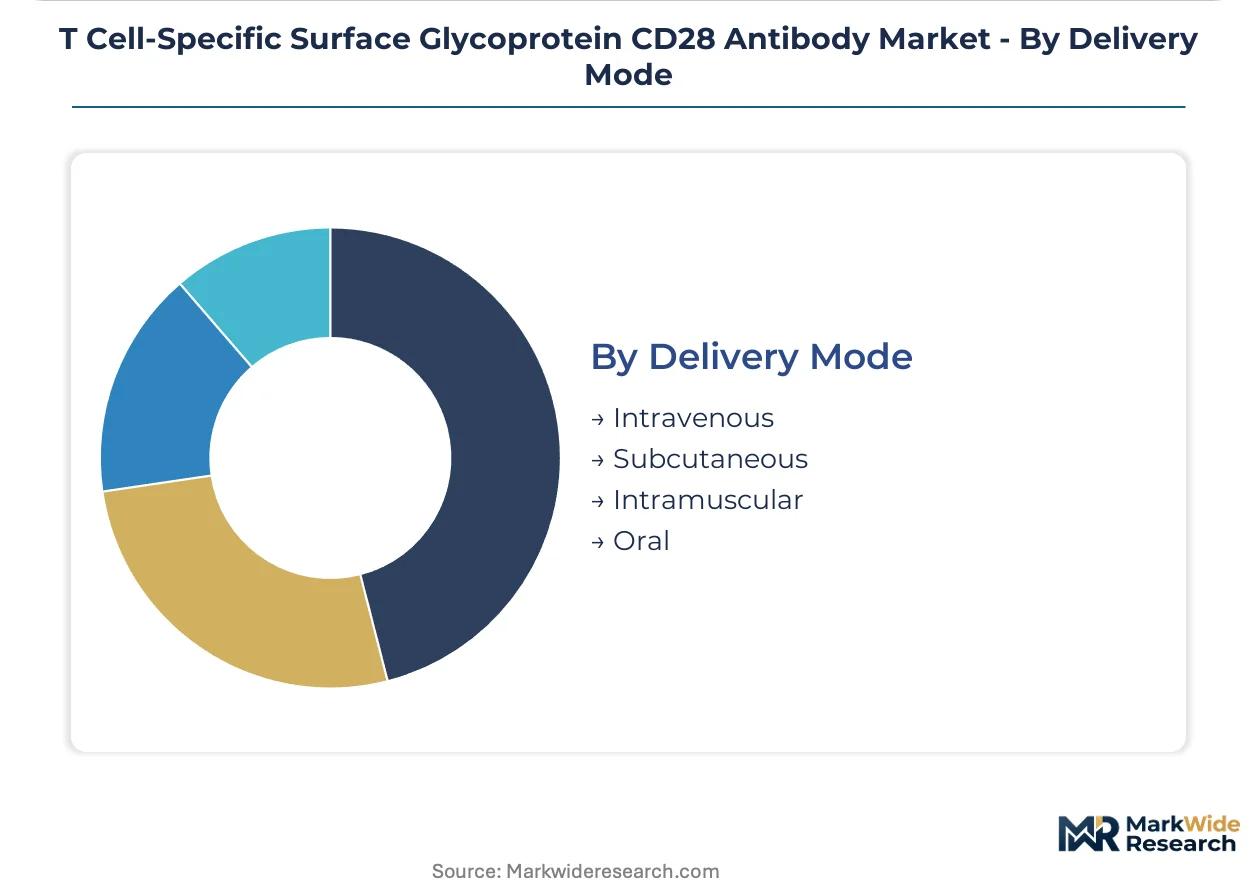
Delivery Mode:
Route of administration dictates formulation complexity and stability requirements, with parenteral formats commanding manufacturing investment.
- Intravenous:Direct bloodstream infusion requiring sterile liquid formulations with extended shelf stability. Therapeutic-grade manufacturers in Germany and Switzerland anchor supply, responding to EMA comparability protocol standards for immunoglobulin therapeutics.
- Subcutaneous:Tissue-layer injection enabling outpatient administration with reduced clinical infrastructure. Japanese developers are prioritizing this route through PMDA's Sakigake early approval pathway for patient-convenient formats.
- Intramuscular:Depot-forming injections with sustained release characteristics.
- Oral:Gastrointestinal delivery with bioavailability challenges for large protein constructs.
Regulatory precedent is strongest for Intravenous administration. Development investment is shifting toward Subcutaneous formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of CD28 antibodies concentrates in German and Swiss biologics manufacturing hubs, while consumption pulls toward United States clinical trial sites and Japanese cell therapy developers. This geographic split shapes regulatory strategy and supply chain configuration across the market.
United States
National Cancer Institute-designated cancer centers drive specification requirements for CD28 antibodies in CAR-T and TCR-T programs. FDA's Center for Biologics Evaluation and Research accelerates approval timelines through breakthrough therapy designation, compressing procurement cycles for therapeutic-grade reagents. Cambridge, Massachusetts and the San Francisco Bay Area anchor biotech firm concentration, with venture-backed developers outsourcing manufacturing to specialized CDMOs.
Germany
Therapeutic-grade antibody manufacturing dominates output from Baden-Württemberg and Bavaria, where EMA comparability protocol standards enforce rigorous glycan profiling requirements. The country's national pharmaceutical regulator maintains alignment with centralized European authorization procedures. Heidelberg and Munich clusters integrate analytical instrumentation with bioprocessing capabilities, serving as supply anchors for GMP-certified immunoglobulin production.
Switzerland
Basel anchors recombinant antibody development for reduced immunogenicity constructs, with Swissmedic oversight harmonized with EMA guidelines through bilateral recognition agreements. Biotech specialists concentrate purchasing power around modular Fc domain technologies. The Zürich region complements this with proteomics platform integration, bundling antibody supply with analytical services.
Japan
PMDA's Sakigake early approval pathway creates first-mover advantages for subcutaneous formulation development, pulling clinical trial investment toward Kanto and Kansai regions. METI coordinates industrial policy supporting cell therapy infrastructure. Osaka and Tokyo metropolitan areas concentrate demand from domestic pharmaceutical developers seeking patient-convenient administration routes.
United Kingdom
London and Cambridge clusters sustain research-grade antibody demand through academic medical center procurement, constrained by grant-funded budget cycles. The Medicines and Healthcare products Regulatory Agency applies UK-specific biosimilar guidance post-Brexit, creating documentation complexity for cross-border supply. Oxford and Manchester regions contribute preclinical discovery workflows requiring catalog antibody access.
T Cell-Specific Surface Glycoprotein CD28 Antibody Market Competitive Landscape
Top-tier vendors anchor multi-year GMP-certified supply agreements, while mid-tier research reagent suppliers compete on catalog breadth and fulfillment speed. The market structure stratifies across therapeutic-grade manufacturers with captive analytical infrastructure and distributed academic suppliers dependent on spot-market transactions. Three archetypes dominate: integrated pharmaceutical developers with in-house biologics capabilities, specialized CDMOs serving cell therapy pipelines, and analytical platform vendors bundling antibodies with instrumentation. Competitive moves concentrate on strategic partnerships with immuno-oncology trial sponsors and consolidation of vendor panels by contract research organizations.
Among integrated pharmaceutical developers, Regeneron Pharmaceuticals and Johnson & Johnson Innovative Medicine exemplify the tier characterized by end-to-end development capabilities from discovery through late-stage trials. Thermo Fisher Scientific occupies a distinct position bridging analytical instrumentation with reagent supply, representing the platform-agnostic archetype. These three entities collectively illustrate how competitive positioning diverges between therapeutic development depth and research tool ecosystem breadth.
| Leading Market Players |
|---|
| Rondo Therapeutics |
| Regeneron Pharmaceuticals |
| Johnson & Johnson Innovative Medicine |
| OPKO Health |
| Becton Dickinson and Company |
| Thermo Fisher Scientific |
| Eli Lilly and Company |
| Genentech (Roche) |
| Bio-Rad Laboratories |
| Others |
Pricing and Supply Chain Analysis
CHO cell culture specialists in Germany and Switzerland command wage premiums that widen spreads between GMP-certified therapeutic-grade antibodies and research-use catalog materials. Labor-cost differentials between these biologics manufacturing hubs and emerging analytical service centers in Asia-Pacific compress margins for mid-tier suppliers while sustaining three-tier pricing stratification across premium, standard, and economy certification levels.
Pricing Analysis
Margin tightening in research-grade supply traces to Protein A resin cost inflation and catalog distributor consolidation. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified therapeutic batches from ISO 13485 diagnostic-grade and research-use-only materials. Price differentiation rests on glycan profiling documentation depth and FDA comparability protocol compliance. Research institutions exhibit acute price sensitivity, whereas pharmaceutical companies absorb premiums for multi-year supply agreements tied to clinical milestones.
Supply Chain Analysis
Returns and refurbishment flows for analytical instrumentation bundles create secondary antibody reagent channels that bypass traditional CHO manufacturers. Supply concentrates in Germany, Switzerland, and the United States, with Baden-Württemberg and Bavaria anchoring therapeutic-grade immunoglobulin output. Raw material dependencies center on Chinese-sourced Protein A chromatography resins, serum-free media formulations, and high-resolution mass spectrometry consumables. Single-source vulnerability in resin supply exposes producers to procurement disruptions. Distribution runs through consolidated vendor panels at CROs and cooperative group purchasing agreements at National Cancer Institute-designated centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protein A resin supply constraints prop pricing power for manufacturers with captive purification infrastructure. Capacity bottlenecks in GMP-certified CHO bioreactor slots sustain contract premiums across the analysis window.
For Market Incumbents: Hedge against recombinant antibody substitution by deepening analytical infrastructure investments and securing multi-year resin offtake agreements. Regeneron Pharmaceuticals and Johnson & Johnson Innovative Medicine demonstrate defensive positioning through VelociSuite acceleration capabilities and integrated immuno-oncology trial networks. Backward integration into high-resolution mass spectrometry capabilities reduces contract testing laboratory dependency. For New Entrants and Emerging Players: The price-point gap between Swiss recombinant antibody premiums and catalog monoclonal economy tiers offers white-space entry at mid-market ISO 13485 diagnostic-grade positioning. Target academic medical center core facilities in the United Kingdom and Japan seeking alternatives to bundled Thermo Fisher Scientific supply. Pursue baculovirus expression system specialization for fragment crystallizable-deficient constructs serving spatial transcriptomics integration. For Investors and Strategic Acquirers: Re-rating potential sits with CDMOs possessing EMA PRIME-designated project pipelines given accelerated approval pathway traction. Long-term viability over the next decade hinges on cell therapy co-development partnership density and biosimilar guidance navigation capabilities. Watch for EMA comparability protocol enforcement intensity as inflection signal for quality management system investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Expands capacity for CAR-T activation reagents serving FDA breakthrough therapy-designated trials. |
| Regulatory Approval Pathway | EMA PRIME designation accelerates CD28-targeting immuno-oncology candidate development timelines. |
| Backward Integration | Captive Protein A resin supply secures margin protection against supplier concentration risk. |
| Platform Integration | Spatial transcriptomics bundling opens analytical applications beyond traditional flow cytometry. |
| Geographic Expansion | PMDA Sakigake pathway entry captures first-mover positioning in subcutaneous formulation development. |
Research Methodology
Multi-period observation of FDA accelerated approval designations, EMA comparability guideline revisions, and CD28 antibody procurement patterns anchored the trend analysis, supplemented by interviews with biologics manufacturing executives, regulatory affairs specialists at CHO CDMOs, academic core facility directors, and cell therapy pipeline managers. Secondary validation drew from FDA Center for Biologics Evaluation and Research filings, EMA Committee for Medicinal Products for Human Use guidance documents, ClinicalTrials.gov immuno-oncology protocol registries, and ISO 13485 certification databases. Bottom-up antibody demand modeling triangulated against top-down biologics market sizing.
Input-output matrices mapped CHO culture titers, Protein A resin throughput constraints, and glycan profiling analytical capacity against therapeutic-grade versus research-grade demand segments across the projection horizon. Segmentation dimensions spanned monoclonal versus recombinant antibody formats, immunotherapy versus analytical applications, and pharmaceutical company versus research institution end users. CAGRs derived from regression analysis of historical biologics approval velocities and cell therapy pipeline expansion rates, with sensitivity testing around biosimilar guidance uncertainty and resin supply disruption scenarios.
Underlying measurement precision varies by segment; GMP-certified therapeutic-grade supply carries tighter precision than research-use catalog materials due to contract visibility. Forecasts reflect assumptions regarding FDA and EMA accelerated pathway continuity, CHO culture productivity trajectories, and academic funding stability. Material deviation in resin supply availability, comparability protocol enforcement intensity, or cell therapy clinical trial suspension rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Asia-Pacific Bacteriophages Therapy Market
Medical Biotechnology
Cancer Antigens Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Antimicrobial Peptides Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
CMO and CDMO Biotechnology Market