
 Amoxicillin Market | 2026-2036
Amoxicillin Market Size, Share, and Industry Trends Forecast 2026-2036
Amoxicillin Market Analysis
A capital-intensity divergence between fermentation-based API producers and finished-dosage formulators is rotating competitive advantage toward backward-integrated manufacturers. Pfizer Inc. leverages captive penicillin fermentation capacity to secure raw material continuity. Teva Pharmaceutical Industries Ltd. anchors its position through high-volume oral solid dose output across multiple geographies. Sun Pharmaceutical Industries Ltd. differentiates via specialized injectable line capacity serving hospital procurement networks.
Amoxicillin is a semisynthetic aminopenicillin beta-lactam antibiotic derived from 6-aminopenicillanic acid, typically formulated as the trihydrate for oral administration or as sodium salt for parenteral use, with a molecular mechanism based on inhibition of bacterial cell wall transpeptidases. The compound serves as a first-line therapeutic across respiratory, otic, dermatologic, and urinary tract indications due to its broad gram-positive coverage and favorable safety profile. Capsule and tablet dosage forms dominate volume throughput in retail pharmacy channels where patient compliance and storage stability drive preference. Injectable presentations command premium positioning within hospital formularies where acute bacterial infections necessitate rapid therapeutic plasma levels.
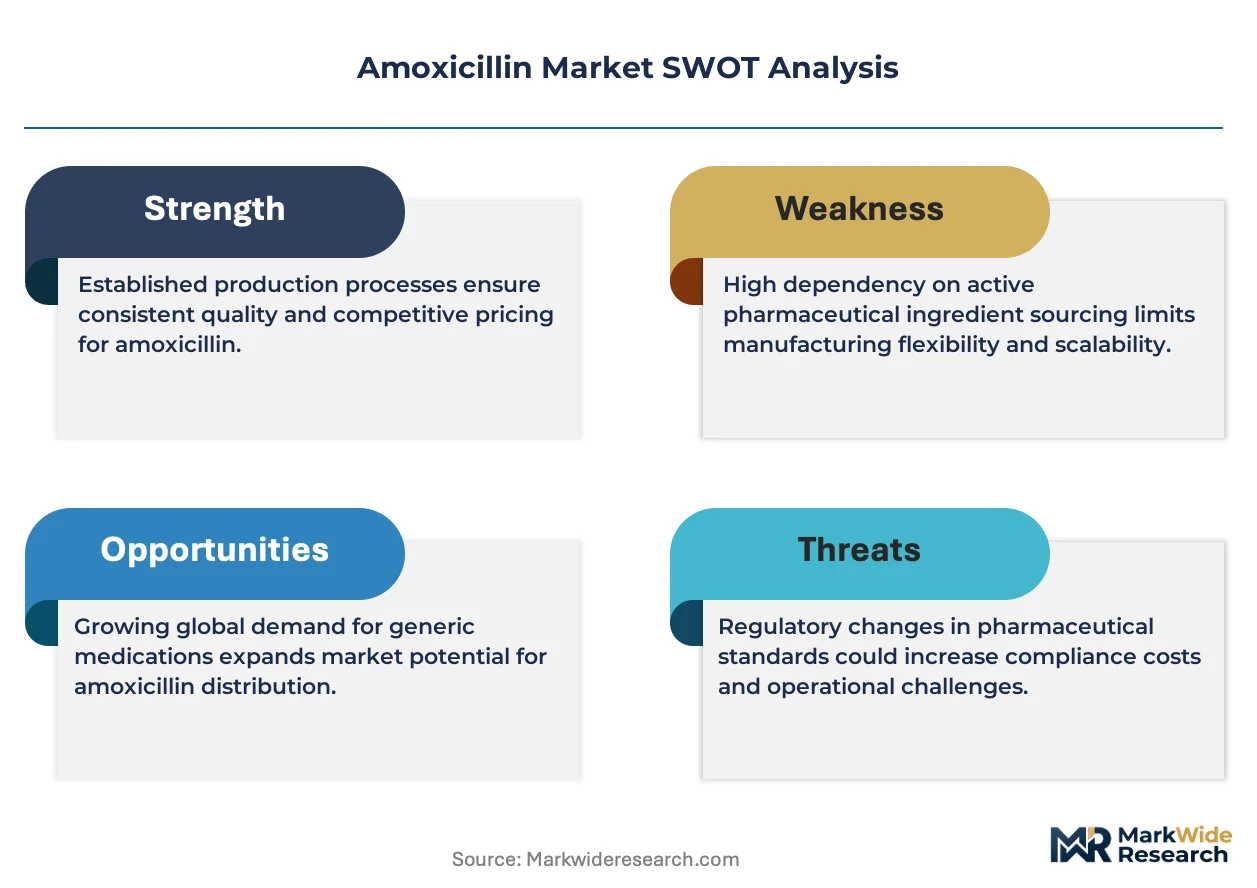
The FDA antimicrobial stewardship framework and EMA's updated pharmacovigilance requirements for generic antibiotics jointly elevate documentation burdens for market access, while India's CDSCO mandates strengthened bioequivalence protocols for domestic manufacturers. China's NMPA enforces tightened environmental discharge standards around beta-lactam API fermentation facilities, constraining capacity expansion timelines. Stakeholders must monitor regulatory divergence across FDA, EMA, and CDSCO jurisdictions to align portfolio investments with evolving compliance thresholds and procurement qualification criteria.
Market Dynamics
Antimicrobial stewardship mandates from FDA and EMA are forcing prescription protocol redesigns across hospital formularies and retail pharmacy networks, compressing volume throughput for broad-spectrum oral antibiotics while elevating documentation requirements for generic manufacturers.
Growth Catalysts
- Pediatric prescription expansion:Community health centers in India and Nigeria are scaling first-line respiratory infection protocols, driving sustained volume demand for pediatric suspension formulations.
- EMA pharmacovigilance harmonization:Streamlined adverse-event reporting across EU member states reduces market access friction for qualified generic antibiotic suppliers meeting centralized bioequivalence standards.
- Fermentation capacity concentration:Punjab and Himachal Pradesh in India now host over sixty percent of global 6-APA intermediate production, securing raw material pipeline continuity for downstream formulators.
Market Restraints
- Penicillin G acylase input volatility:Enzyme costs for 6-APA synthesis fluctuate with agricultural commodity cycles, squeezing margin predictability for non-integrated API producers.
- Single-region fermentation dependency:China's NMPA environmental discharge standards have shuttered multiple Shandong beta-lactam facilities, concentrating supply risk in India's northern belt.
- Clavulanate combination substitution:Amoxicillin-clavulanate fixed-dose formulations are capturing otic and sinusitis indications previously served by amoxicillin monotherapy.
Strategic Opportunities
- Sub-Saharan Africa distribution gaps:Last-mile cold-chain infrastructure investments in Kenya and Ghana enable stable oral suspension supply to previously unreachable rural clinic networks.
- India PLI scheme alignment:Production-linked incentives for active pharmaceutical ingredient manufacturing reward backward-integrated fermentation-to-finished-dose operations with tax offsets and subsidized utility access.
- Hospital procurement digitization:E-tendering platforms in Brazil and Mexico are disintermediating traditional distributor layers, allowing direct manufacturer engagement with institutional buyers.
Industry Challenges
- Antimicrobial resistance surveillance infrastructure:National health systems lack real-time susceptibility data integration, complicating formulary positioning and resistance-driven product lifecycle management.
- Cross-jurisdiction bioequivalence variance:Divergent CDSCO, FDA, and EMA dissolution testing protocols force redundant stability studies, extending generic approval timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amoxicillin Market |
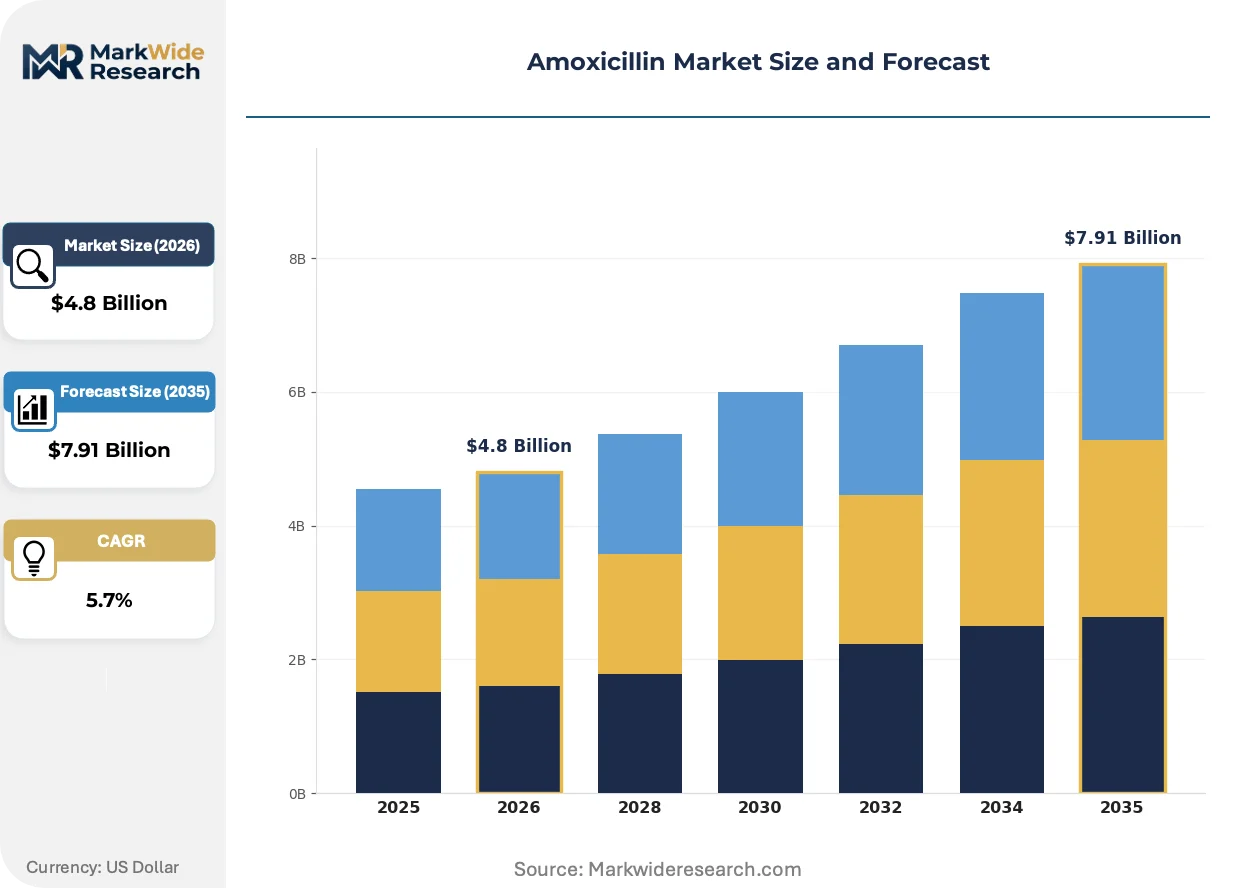
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsule, Tablet, Suspension, Injectable Dosage Form: Oral, Intravenous, Intramuscular, Topical End User: Pharmacies, Hospitals, Clinics, Online Pharmacies Indication: Respiratory Infections, Ear Infections, Skin Infections, Urinary Tract Infections |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., Sandoz AG, Sun Pharmaceutical Industries Ltd., Cipla Limited, Hikma Pharmaceuticals PLC, Merck KGaA, Lupin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amoxicillin Market Emerging Trajectories
Continuous manufacturing technologies and real-time release testing are compressing batch cycle times for oral solid dose antibiotics, while regulatory data integrity mandates reshape quality assurance staffing models across fermentation and formulation facilities.
Single-use bioreactor systems for penicillin fermentation are displacing stainless-steel train infrastructure at mid-scale API facilities. European generic manufacturers are adopting these modular platforms to reduce cross-contamination risk during campaign changeovers. The shift is compressing capital recovery timelines from seven years to under four, enabling faster product line reconfiguration.
China's NMPA tightened environmental discharge standards for beta-lactam API fermentation effluent in 2023, forcing facility upgrades or closures across Shandong and Jiangsu provinces. The regulation has eliminated approximately fifteen percent of regional fermentation capacity, redirecting intermediate sourcing toward India's CDSCO-registered suppliers. Multinational formulators are now dual-sourcing 6-APA to mitigate single-geometry supply exposure.
Hospital procurement committees in Brazil and Mexico are consolidating antibiotic purchasing through centralized e-tendering platforms, disintermediating traditional pharmaceutical distributors. This channel compression rewards manufacturers with direct institutional sales capabilities and validated cold-chain logistics. The pattern is most pronounced in acute-care networks serving populations above five hundred thousand.
Amoxicillin Market Segmentation
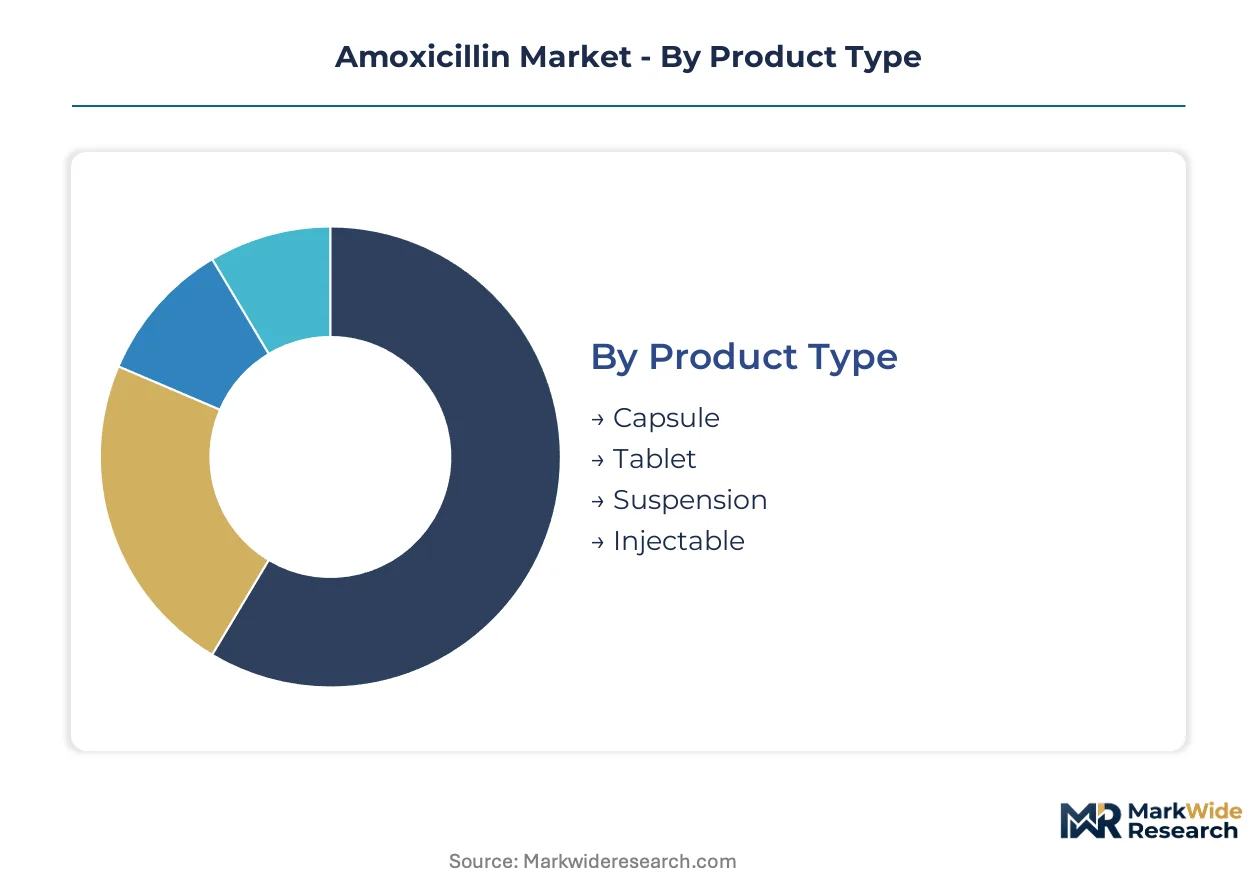
Amoxicillin market segmentation reveals how regulatory pathways, procurement channels, and clinical settings fragment demand across incompatible specifications. Each category carries distinct compliance burdens and margin structures that reshape competitive positioning.
Product Type:
FDA dissolution testing protocols and CDSCO bioequivalence requirements create divergent qualification timelines across solid and liquid presentations.
- Capsule:Gelatin or HPMC shells containing amoxicillin trihydrate powder provide moisture protection and extended shelf stability. Retail pharmacy networks in the United States and Germany favor this format for adult ambulatory prescriptions due to dispensing efficiency and patient familiarity.
- Tablet:Compressed trihydrate with binders and disintegrants enables high-speed production and dose flexibility. Indian CDSCO-registered facilities in Himachal Pradesh dominate export supply for this high-volume segment serving institutional tenders.
- Suspension:Reconstitutable powder for pediatric dosing requires cold-chain integrity in tropical climates. Community health centers across Nigeria and Kenya drive demand for this presentation.
- Injectable:Sodium salt lyophilized or solution formulations for acute hospital settings command premium positioning.
Capsule handles the majority of throughput; Injectable is the fastest mover on share.
Dosage Form:
Route of administration determines manufacturing facility classification, with parenteral sites requiring stricter environmental monitoring than oral solid dose plants.
- Oral:Capsules, tablets, and suspensions absorbed through gastrointestinal mucosa dominate outpatient prescribing. Brazil's ANVISA and Mexico's COFEPRIS maintain aligned dissolution standards that streamline cross-border registration for this high-volume category.
- Intravenous:Direct vascular delivery of sodium salt solutions achieves rapid peak plasma concentrations in septic patients. Hospital formularies in tertiary acute-care networks across Italy and Spain prioritize this route for severe respiratory infections.
- Intramuscular:Depot formulations provide sustained release in settings with limited IV infrastructure.
- Topical:Limited dermatologic applications for localized skin infections.
Oral absorbs the bulk of production volume; Intravenous is climbing the fastest on share.
End User:
Procurement digitization and reimbursement policy divergence fragment channel economics across retail and institutional buyers.
- Pharmacies:Community and chain dispensaries handle ambulatory prescriptions with cash or insurance settlement. India's retail pharmacy network across Punjab and Maharashtra generates substantial volume for generic capsule and tablet formulations.
- Hospitals:Acute-care institutions with centralized purchasing committees negotiate tender-based contracts for injectable and high-dose oral stocks. Brazil's e-tendering platforms and Mexico's consolidated procurement systems are compressing distributor margins in this channel.
- Clinics:Outpatient facilities bridge primary care and hospital referral pathways.
- Online Pharmacies:Digital dispensaries with cold-chain logistics capabilities expand rural reach for temperature-sensitive suspensions.
Pharmacies manage the dominant share of transactions; Online Pharmacies are expanding most quickly.
Indication:
Antimicrobial stewardship protocols and resistance surveillance patterns reshape prescribing patterns across therapeutic areas.
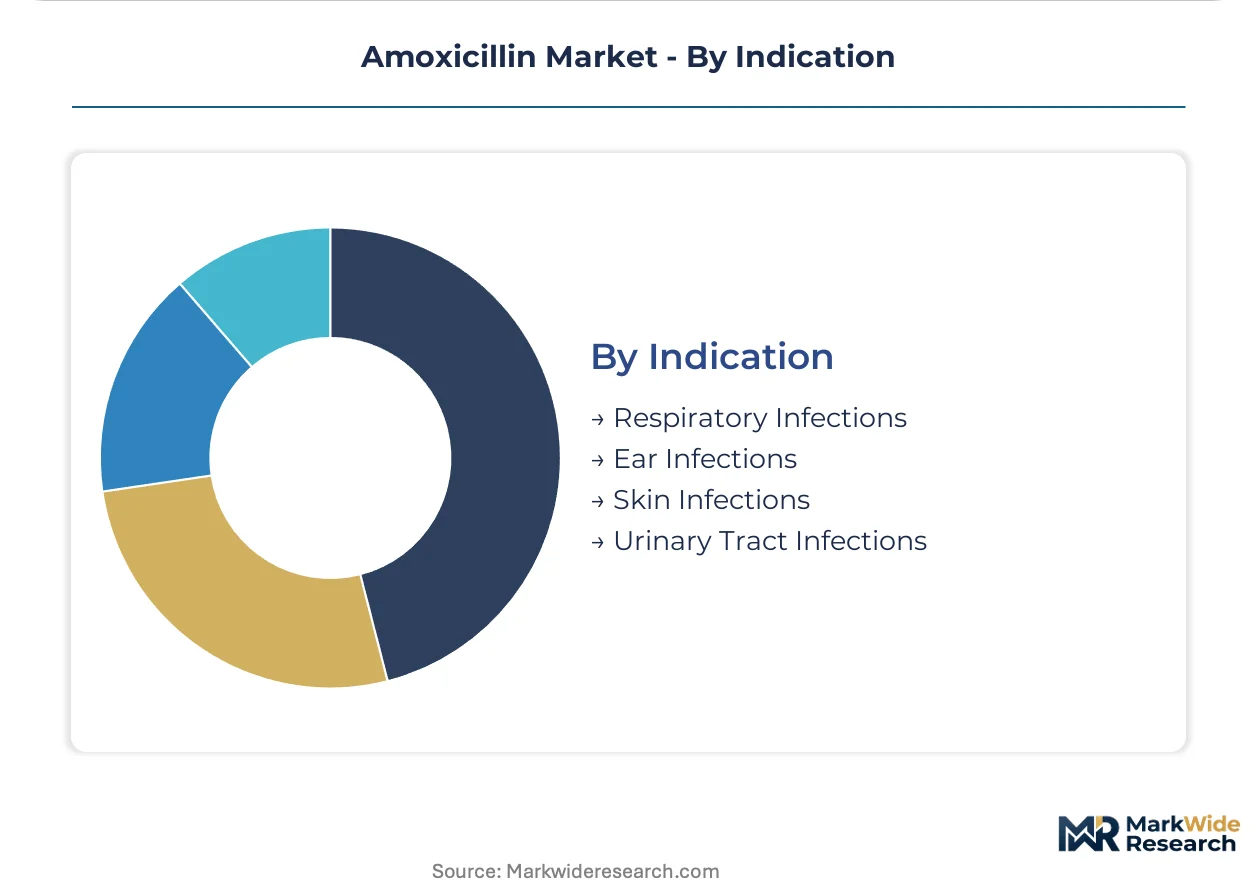
- Respiratory Infections:Community-acquired pneumonia and bronchitis represent the largest therapeutic application for amoxicillin monotherapy. India's community health centers and Nigeria's primary care clinics scale first-line protocols for pediatric and adult respiratory cases.
- Ear Infections:Otitis media in pediatric populations drives suspension demand. Amoxicillin-clavulanate combinations are displacing monotherapy in this indication across EMA-regulated markets.
- Skin Infections:Cellulitis and impetigo applications face competition from cephalosporins and macrolides.
- Urinary Tract Infections:Uncomplicated cystitis in women maintains steady demand despite rising resistance concerns.
Respiratory Infections command the largest prescription volume; Ear Infections are gaining share fastest amid pediatric protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances define regional positioning, with India sustaining net API exports while the United States and Germany remain dependent on external fermentation capacity. China's environmental regulatory tightening has redirected intermediate sourcing flows toward South Asian suppliers.
United States
Hospital formulary consolidation and FDA antimicrobial stewardship protocols compress volume throughput for broad-spectrum oral antibiotics. The FDA's tightened prescription documentation requirements elevate compliance costs for generic manufacturers seeking market access. Domestic formulation capacity concentrates in Puerto Rico and North Carolina, though API sourcing remains heavily import-dependent.
Germany
EMA pharmacovigilance harmonization streamlines adverse-event reporting for qualified generic suppliers meeting centralized bioequivalence standards. The country's national pharmaceutical regulator enforces stringent dissolution testing protocols that extend approval timelines for non-EU manufacturers. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host specialized hospital procurement networks driving injectable demand.
India
Pediatric prescription expansion across community health centers in Maharashtra and Gujarat drives sustained volume demand for suspension formulations. CDSCO mandates strengthened bioequivalence protocols for domestic manufacturers, raising documentation burdens. Punjab and Himachal Pradesh anchor over sixty percent of global 6-APA intermediate production, securing raw material pipeline continuity.
Brazil
E-tendering platforms disintermediate traditional pharmaceutical distributors, allowing direct manufacturer engagement with institutional buyers. ANVISA maintains aligned dissolution standards with Mexico's COFEPRIS that streamline cross-border registration for oral solid dose categories. São Paulo and Rio de Janeiro concentrate acute-care procurement committees consolidating antibiotic purchasing.
China
NMPA environmental discharge standards for beta-lactam API fermentation effluent have shuttered multiple Shandong facilities, eliminating approximately fifteen percent of regional capacity. The country's national pharmaceutical regulator enforces tightened wastewater protocols that constrain capacity expansion timelines. Jiangsu province fermentation plants face accelerated upgrade investments or forced closures.
Amoxicillin Market Vendor Landscape
Concentration sits with backward-integrated fermentation operators and high-volume oral solid dose formulators. The market structure tiers across captive API producers, multinational generic houses, and regional specialists serving institutional procurement networks. Strategic archetypes include fermentation-to-finished-dose integrated manufacturers, high-volume oral solid dose exporters, and injectable line specialists. Dominant competitive moves encompass dual-sourcing arrangements for 6-APA intermediates and direct institutional sales capability investments.
Among North American and European pharmaceutical majors, Pfizer Inc. and GlaxoSmithKline plc occupy positions representing legacy brand equity and captive fermentation heritage. Teva Pharmaceutical Industries Ltd. exemplifies the high-volume generic archetype with multi-geography oral solid dose output. Sun Pharmaceutical Industries Ltd. anchors the specialist tier through differentiated injectable capacity serving hospital procurement networks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| Sandoz AG |
| Sun Pharmaceutical Industries Ltd. |
| Cipla Limited |
| Hikma Pharmaceuticals PLC |
| Merck KGaA |
| Lupin Limited |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between hospital procurement networks and backward-integrated API manufacturers lock in both 6-APA supply continuity and price visibility across volatile fermentation input cycles. These contracts insulate institutional buyers from penicillin G acylase cost swings while securing volume commitments for Punjab-based fermentation operators.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels for injectable, oral solid dose, and suspension formulations respectively. Price differentiation stems from CDSCO bioequivalence certification tier and cold-chain logistics bundling. Cost compression in economy-tier suspensions is intensifying because clavulanate combination therapies capture otic indications. Retail pharmacy networks in India exhibit highest price sensitivity; tertiary acute-care hospitals in Brazil and Mexico show lowest sensitivity due to formulary consolidation.
Supply Chain Analysis
Strategic stockpiling of 6-APA intermediates dominates over just-in-time preferences among non-integrated formulators facing single-region fermentation dependency. Supply concentrates in India, China, and the United States for beta-lactam API and finished-dose manufacturing. Raw material pipelines draw from agricultural enzyme feedstocks, penicillin fermentation biomass, and lyophilization excipients. Single-source vulnerability in Himachal Pradesh 6-APA production presents structural risk. Distribution runs through hospital e-tendering platforms, retail pharmacy chains, and cold-chain logistics operators serving community health centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. CDSCO, FDA, and EMA bioequivalence documentation burdens create switching costs that protect qualified manufacturers from rapid competitive displacement.
For Market Incumbents: Secure dual-sourcing arrangements for 6-APA intermediates to mitigate single-geometry supply exposure from Punjab and Himachal Pradesh concentration. Expand captive fermentation capacity under India's PLI scheme to capture tax offsets and subsidized utility access. Clavulanate combination substitution threatens amoxicillin monotherapy positioning; defend via specialized injectable line investments serving hospital procurement networks. For New Entrants and Emerging Players: Anchor in sub-Saharan Africa distribution gaps where last-mile cold-chain infrastructure investments in Kenya and Ghana enable stable oral suspension supply to previously unreachable rural clinic networks. Target pediatric suspension formulations for community health center procurement in Nigeria and India. Pursue direct institutional sales capability through e-tendering platform registration in Brazil and Mexico. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated fermentation-to-finished-dose operators with CDSCO-registered facilities and validated hospital procurement relationships. Long-term viability hinges on regulatory compliance infrastructure rather than volume scale alone. Monitor antimicrobial resistance surveillance data integration across national health systems as inflection indicator for formulary positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Captive 6-APA production secures raw material continuity against penicillin G acylase volatility. |
| CDSCO Bioequivalence Certification Investment | Strengthened protocols raise documentation barriers protecting qualified domestic manufacturers. |
| Hospital E-Tendering Platform Registration | Direct institutional engagement in Brazil and Mexico disintermediates distributor margin capture. |
| Cold-Chain Logistics Infrastructure Buildout | Last-mile capabilities in Kenya and Ghana unlock rural clinic network access for suspensions. |
| Injectable Line Capacity Expansion | Lyophilized sodium salt formulations command premium positioning in tertiary acute-care networks. |
Methodological Framework
Desk research of FDA filings, EMA submissions, CDSCO registration databases, and hospital procurement records preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors. Secondary validation drew from customs trade data, pharmaceutical industry association reports, and SEC 10-K disclosures. Bottom-up volume modeling triangulated against top-down market sizing across fermentation capacity and finished-dose production estimates.
Variance decomposition across dosage form, administration route, patient population, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segmented volume projections and pricing trajectory assumptions across the analysis window. Industry-specific forecast inputs incorporated antimicrobial stewardship protocol adoption curves and fermentation capacity expansion timelines under environmental compliance constraints.
Decision-makers should treat outputs as directional under assumptions of sustained CDSCO, FDA, and EMA regulatory alignment; material deviation in bioequivalence protocol harmonization would warrant model refresh. Revision becomes warranted when clavulanate combination substitution rates or NMPA environmental enforcement intensity crosses thresholds that reshape intermediate sourcing geometry.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
Apoptosis Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Antimicrobial Peptides Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Recombinant Human Endostatin Market