
 Global Microalbumin Test Market | 2026-2036
Global Microalbumin Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microalbumin Test Market Foresight
Leasing-based instrument placement is narrowing the competitive field for capital-constrained laboratories. Danaher Corporation leverages extensive distribution networks to sustain installed-base revenues across clinical chemistry platforms. Roche Diagnostics anchors European market presence through integrated analyzer-immunoassay systems. Siemens Healthineers competes on automation density in high-throughput hospital laboratories.
Microalbumin tests detect low concentrations of albumin in urine, typically below 30 mg per 24-hour collection, serving as an early biomarker for renal dysfunction and vascular complications. Immunoassay kits dominate routine laboratory workflows due to standardization and regulatory familiarity, while test strips capture growth in decentralized settings where speed outweighs analytical sensitivity. Point-of-care deployment is expanding fastest among end-user categories as health systems shift toward preventive monitoring outside traditional laboratory infrastructure.
The FDA governs in vitro diagnostic premarket pathways and clinical laboratory standards under CLIA, while the EMA's in vitro diagnostic regulation recalibrates conformity requirements across European member states. Japan's PMDA maintains distinct quality management system certifications that shape market entry timelines for foreign manufacturers. Stakeholders must weigh regional regulatory divergence against platform standardization strategies when allocating product development resources.
Market Dynamics
Leasing-based instrument placement is consolidating purchasing power among capital-constrained laboratories, compressing vendor margins while locking in long-term consumable commitments across clinical chemistry platforms.
Growth Catalysts
- Chronic disease screening protocols:Mature protocols in the United States, Germany, and Japan are embedding microalbumin testing into routine diabetes and hypertension management, creating stable demand pull from primary care networks.
- CLIA regulatory pathway:The FDA's Clinical Laboratory Improvement Amendments framework provides predictable premarket clearance timelines, reducing regulatory uncertainty for immunoassay kit manufacturers entering the US market.
- Point-of-care decentralization:Health systems are shifting preventive monitoring outside traditional laboratory infrastructure, expanding rapid diagnostic format adoption in physician offices and retail clinics.
Market Restraints
- Analyzer capital intensity:High-throughput hospital laboratories face substantial upfront investment for integrated analyzer-immunoassay systems, limiting upgrade frequency to 7-10 year cycles.
- European regulatory recalibration:The EMA's In Vitro Diagnostic Regulation is extending conformity assessment timelines, creating market entry friction for non-EU manufacturers without notified body relationships.
- Test strip sensitivity limitations:Decentralized settings accepting speed over analytical precision generate false-negative risks for early-stage renal dysfunction, constraining clinical confidence in non-laboratory deployment.
Strategic Opportunities
- Japan's PMDA certification pathways:Distinct quality management system requirements create first-mover advantages for manufacturers establishing local regulatory expertise ahead of competitors.
- Home-based monitoring convergence:Integration of smartphone-connected readers with lateral flow test strips is opening direct-to-consumer channels previously inaccessible to laboratory-centric vendors.
- Preventive reimbursement expansion:Germany's statutory health insurance framework is expanding coverage for early biomarker screening, reducing out-of-pocket barriers for at-risk populations.
Industry Challenges
- Cross-platform standardization gaps:Variability in albumin reference ranges across immunoassay manufacturers complicates longitudinal patient monitoring and inter-laboratory result reconciliation.
- Legacy system integration:Hospital laboratories with entrenched automation density face workflow disruption when incorporating point-of-care data streams into centralized laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microalbumin Test Market |
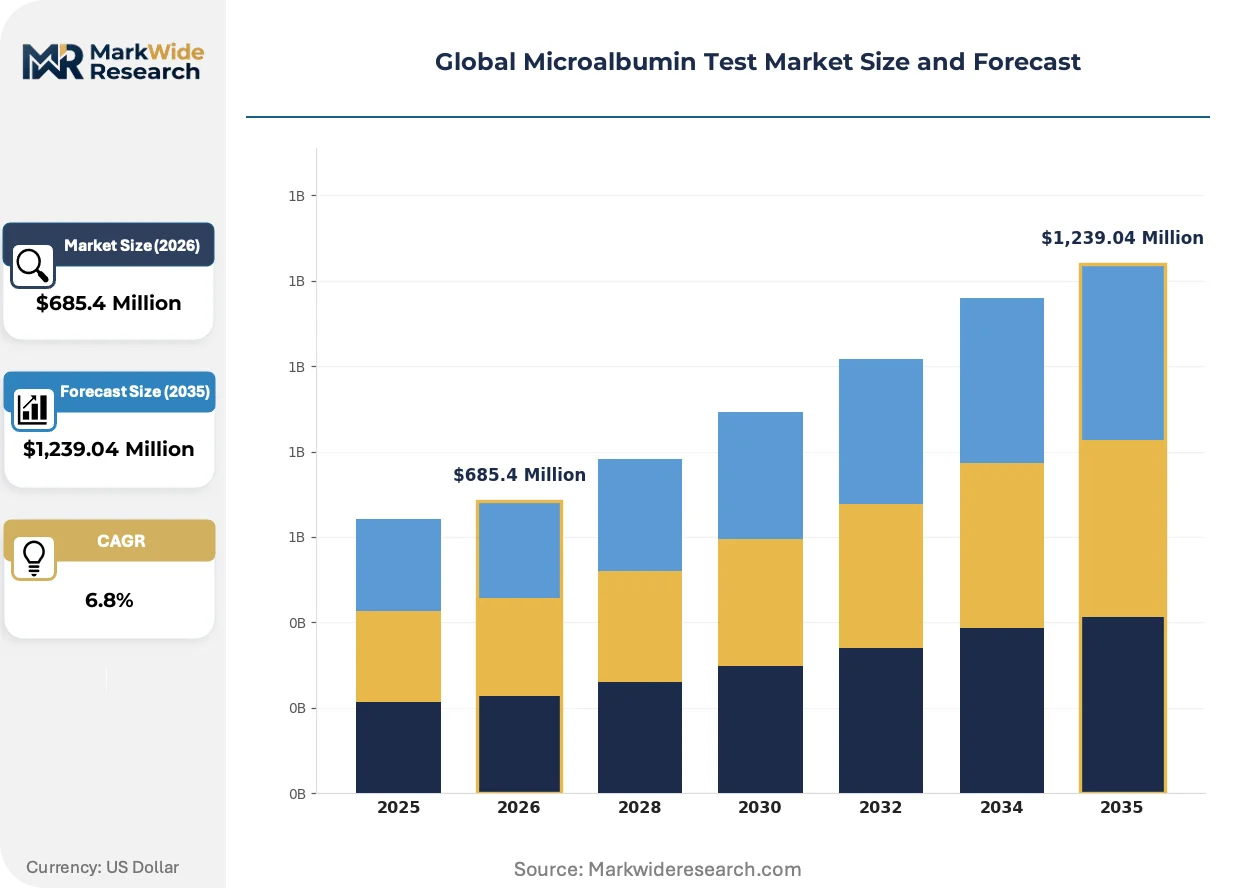
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Strips, Immunoassay Kits, Turbidimetric Assays, ELISA Kits, Chromatographic Assays Application: Diabetes Monitoring, Kidney Disease Detection, Cardiovascular Risk Assessment, Hypertension Management, Prenatal Screening End User: Diagnostic Laboratories, Research Institutes, Point-of-Care Centers, Specialty Clinics, Blood Testing Centers Deployment: Laboratory Testing, Home Testing Kits, Hospital Testing, Mobile Testing Units, Corporate Health Screening |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Roche Diagnostics, Acon Laboratories, PerkinElmer, Abbott Laboratories, Bayer AG, QuidelOrtho Corporation, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microalbumin Test Market Shifts & Advancements
Diagnostic platform architecture is fragmenting along speed-versus-precision axes, with vendors pursuing divergent technical strategies to capture distinct care settings rather than unified market dominance.
Biosensor technology is hybridizing electrochemical detection with microfluidic sample handling to deliver laboratory-grade sensitivity in handheld formats. Community health centers and retail clinic chains are piloting these devices for same-visit kidney risk stratification. This convergence is compressing the traditional boundary between central laboratory and near-patient testing workflows.
The EMA's In Vitro Diagnostic Regulation is mandating expanded clinical evidence packages for Class C devices, including microalbumin immunoassays. Manufacturers are restructuring quality management systems to accommodate post-market surveillance obligations. High-throughput analyzer vendors with existing European notified body relationships are absorbing compliance costs more efficiently than point-of-care specialists.
Health system procurement committees are unbundling instrument placement from reagent supply contracts, reversing decades of bundled pricing conventions. Independent service organizations are capturing maintenance revenue previously retained by original equipment manufacturers. This shift is most pronounced in United States hospital systems with centralized supply chain governance and multi-site laboratory networks.
Global Microalbumin Test Market Segmentation
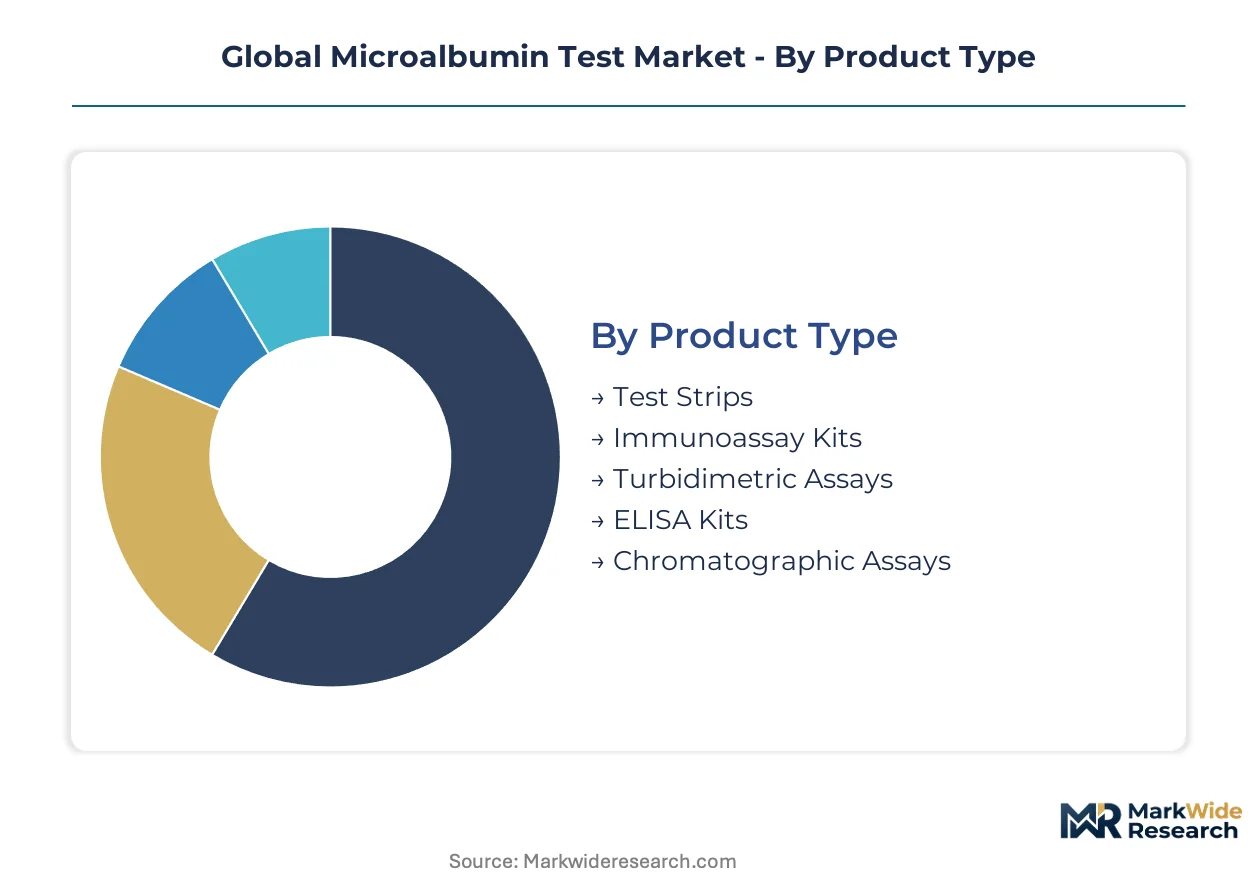
Microalbumin testing platforms fragment across precision tiers, care settings, and user technical capabilities. Vendors optimize product architectures for distinct workflow constraints rather than universal deployment. Procurement committees evaluate segments against capital intensity, regulatory clearance breadth, and interoperability with existing laboratory information systems.
Product Type:
Mature immunoassay formats dominate centralized laboratory procurement, while emerging biosensor platforms capture decentralized growth corridors.
- Immunoassay Kits:Chemiluminescent and immunoturbidimetric methods deliver standardized quantification with traceability to reference materials. Hospital laboratories in the United States and Germany specify these for diabetes management protocols requiring documented precision. CLIA moderate-complexity certification locks in vendor relationships through multi-year reagent contracts.
- Test Strips:Lateral flow chemistry enables qualitative or semi-quantitative screening without analyzer capital expenditure. Point-of-care centers in Japan's community health networks deploy these for same-visit kidney risk stratification, though sensitivity limitations constrain clinical confidence for early-stage detection.
- Turbidimetric Assays:Nephelometric detection principles integrate with clinical chemistry analyzers for high-throughput batch processing. Diagnostic laboratories specify these for integrated metabolic panels.
- ELISA Kits:Enzyme-linked immunosorbent assays serve research institutes requiring customizable protocols and batch flexibility. Academic medical centers maintain these for translational studies.
- Chromatographic Assays:High-performance liquid chromatography methods isolate albumin from interfering proteins in complex matrices. Reference laboratories deploy these for disputed or arbitration testing.
Immunoassay kits handle the majority of throughput; test strips are expanding most quickly on share.
Application:
Volume concentrates in chronic disease surveillance, with emerging applications in preventive screening and maternal-fetal medicine.
- Diabetes Monitoring:Annual microalbumin screening is embedded in American Diabetes Association care standards for type 1 and type 2 patients. Primary care networks in the United States generate predictable demand through HEDIS quality metrics tied to reimbursement. Test frequency escalates with disease duration and glycemic control deterioration.
- Kidney Disease Detection:Early nephropathy identification drives immunoassay volume in nephrology referral pathways. German statutory health insurance expanded coverage for biomarker screening, reducing cost barriers for at-risk populations. KDIGO guidelines mandate quantitative confirmation of dipstick-positive findings.
- Cardiovascular Risk Assessment:Microalbuminuria correlates with endothelial dysfunction and future cardiac events. Cardiology clinics in Japan incorporate testing into integrated risk scores.
- Hypertension Management:Renal damage surveillance complements blood pressure control protocols. Specialty clinics specify high-sensitivity methods for resistant hypertension workups.
- Prenatal Screening:Preeclampsia risk stratification employs urinary albumin-to-creatinine ratios. Obstetric networks pilot point-of-care formats for remote monitoring.
Diabetes monitoring commands the largest absolute volume; kidney disease detection is climbing the fastest as screening protocols mature.
End User:
Customer technical sophistication spans reference-grade analytical capability to consumer-operated devices with smartphone connectivity.
- Diagnostic Laboratories:Centralized facilities with CLIA certification or EMA IVDR compliance perform the bulk of quantitative testing. Multi-site networks in the United States consolidate purchasing through group purchasing organizations, compressing vendor margins while locking in long-term consumable commitments.
- Point-of-Care Centers:Physician offices and retail clinics prioritize speed over analytical sensitivity for same-visit decision-making. Japan's PMDA quality management system requirements create first-mover advantages for manufacturers establishing local regulatory expertise.
- Research Institutes:Academic and commercial R&D operations demand batch flexibility and custom assay development. Funding cycles drive irregular procurement patterns.
- Specialty Clinics:Nephrology, endocrinology, and cardiology practices require rapid turnaround for treatment adjustment. Workflow integration with electronic health records shapes vendor selection.
- Blood Testing Centers:Collection-focused operations forward samples to reference laboratories. Logistics partnerships determine market access.
Diagnostic laboratories handle the majority of throughput; point-of-care centers are gaining share fastest through health system decentralization.
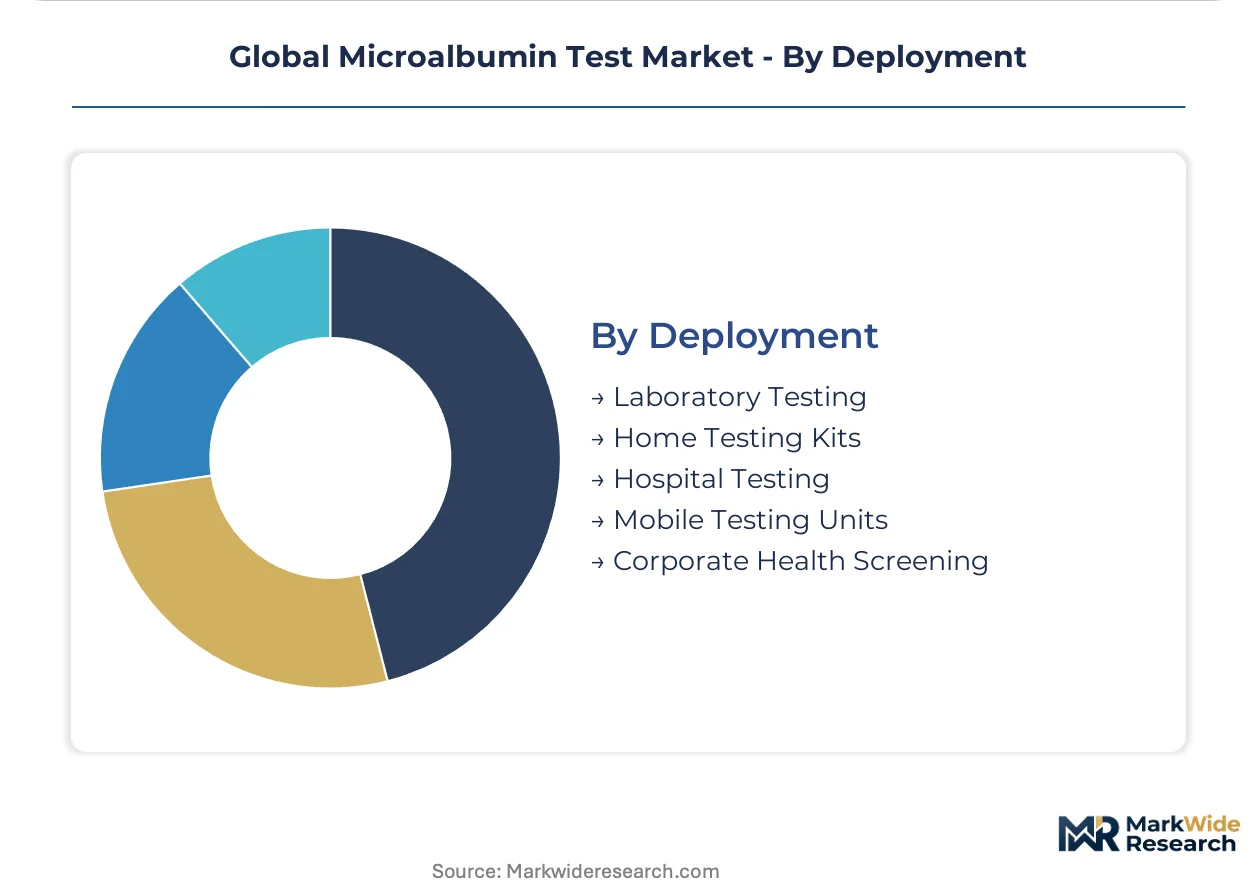
Deployment:
Physical infrastructure requirements range from capital-intensive analyzer installations to disposable kit distribution.
- Laboratory Testing:Centralized processing maintains analytical precision through controlled environmental conditions and trained technologist oversight. Hospital systems with entrenched automation density face workflow disruption when incorporating external data streams.
- Hospital Testing:Inpatient and emergency departments require stat capability for acute kidney injury evaluation. STAT laboratory integration with clinical decision support systems drives platform selection.
- Home Testing Kits:Direct-to-consumer channels leverage smartphone-connected readers with lateral flow strips. Germany's statutory health insurance framework is expanding coverage for home-based monitoring, reducing out-of-pocket barriers.
- Mobile Testing Units:Community health outreach and occupational health screening deploy portable analyzers. Corporate health screening programs in Japan utilize these for annual employee examinations.
- Corporate Health Screening:Employer-sponsored wellness programs embed kidney risk assessment into preventive care bundles. Procurement emphasizes cost-per-test over analytical sensitivity.
Laboratory testing handles the majority of throughput; home testing kits are the fastest mover on share through smartphone connectivity convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and diagnostic laboratory networks concentrate purchasing power in the United States, Germany, and Japan. These three markets embed microalbumin testing into chronic disease reimbursement protocols. Emerging demand surfaces in China's tier-two cities and India's corporate health screening programs.
United States
American Diabetes Association care standards mandate annual microalbumin screening for diabetic patients, generating predictable volume through primary care networks. The FDA's Clinical Laboratory Improvement Amendments framework provides moderate-complexity certification pathways that lock vendors into multi-year reagent contracts. Boston's medical technology corridor anchors immunoassay kit development, with Massachusetts General Hospital and Brigham and Women's Hospital piloting integrated analyzer systems for high-throughput processing.
Germany
German statutory health insurance expanded coverage for early biomarker screening, reducing patient cost barriers for at-risk populations. The EMA's In Vitro Diagnostic Regulation recalibrates conformity assessment timelines, favoring manufacturers with existing notified body relationships. Baden-Württemberg's industrial cluster around Heidelberg and Mannheim concentrates clinical chemistry analyzer production, with Siemens Healthineers maintaining automation density leadership in hospital laboratories across the state.
Japan
Japan's community health networks deploy point-of-care formats for same-visit kidney risk stratification in aging populations. The PMDA maintains distinct quality management system certifications that extend market entry timelines for foreign manufacturers. Tokyo's Kanto region anchors diagnostic platform development, with academic medical centers in Osaka's Kansai corridor validating smartphone-connected reader integration for home-based monitoring pilots.
China
China's tier-two cities are expanding chronic disease screening infrastructure as diabetes prevalence climbs in urban populations. The NMPA governs in vitro diagnostic premarket approval with timelines that favor domestic manufacturers over multinational entrants. Shanghai's Yangtze River Delta cluster hosts joint ventures between local distributors and European analyzer vendors, while Shenzhen's hardware ecosystem produces lateral flow test strip components for regional supply chains.
India
India's corporate health screening programs embed kidney risk assessment into annual employee wellness bundles for IT and manufacturing sectors. The country's national pharmaceutical regulator evaluates diagnostic kit imports against local quality benchmarks. Maharashtra's Mumbai-Pune corridor concentrates private diagnostic laboratory chains, with Bangalore's Karnataka emerging as a hub for telemedicine-integrated home testing kit distribution.
Global Microalbumin Test Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent speed-versus-precision axes. The vendor base separates into three tiers: integrated diagnostic conglomerates with installed-base leverage, mid-scale immunoassay specialists, and point-of-care strip manufacturers. Strategic moves concentrate on leasing-based instrument placement to lock consumable commitments, and unbundling service contracts from reagent supply to capture maintenance revenue.
Among integrated diagnostic conglomerates, Danaher Corporation and Roche Diagnostics exemplify channel-controlling archetypes with extensive distribution networks and analyzer-immunoassay system integration. Siemens Healthineers occupies a position in automation density leadership for high-throughput hospital laboratories. Thermo Fisher Scientific represents the scale-driven end with clinical chemistry platform breadth. These four entities anchor competitive dynamics through installed-base revenues and multi-year consumable contracts.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Roche Diagnostics |
| Acon Laboratories |
| PerkinElmer |
| Abbott Laboratories |
| Bayer AG |
| QuidelOrtho Corporation |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Antibody reagent production concentrates in China and South Korea, concentrating margin capture with contract manufacturers who supply immunoassay kit vendors across the United States, Germany, and Japan. This upstream concentration forces downstream diagnostic conglomerates to absorb cost volatility through long-term consumable contracts while competing on analyzer placement terms.
Pricing Analysis
Certification grade creates the primary spread between CLIA moderate-complexity, CE-IVDR Class C, and PMDA-certified product tiers. Three-tier pricing structure across premium, standard, and economy levels segments by analytical sensitivity and automation integration, with hospital laboratories showing lowest price sensitivity due to bundled reagent commitments. Cost compression in point-of-care strips is intensifying because of smartphone-connected reader commoditization.
Supply Chain Analysis
Export control regimes on microfluidic fabrication equipment limit technology transfer to emerging manufacturing hubs, constraining supply diversification. Antibody reagents, nitrocellulose membranes, and electrochemical sensor substrates draw from concentrated production in China, South Korea, and Japan. Single-source vulnerability in specialized antibody supply creates exposure to quality variability. Distribution runs through regional diagnostic distributors with GPO relationships in the United States and direct hospital contracts in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through multi-site laboratory networks and group purchasing organizations in the United States, compressing vendor margins while extending contract lock-in periods. This consolidation demands differentiated strategic responses across stakeholder positions.
For Market Incumbents: Build installed-base moats through analyzer-immunoassay system integration with embedded software workflows that raise switching costs for hospital laboratories. Expand CLIA-certified reagent manufacturing capacity in Massachusetts to reduce antibody supply exposure. Deepen backward integration into nitrocellulose membrane production to capture margin pools currently retained by Chinese substrate suppliers. For New Entrants and Emerging Players: India's corporate health screening programs represent underpenetrated demand with lower regulatory barriers than United States or European hospital procurement. Target telemedicine-integrated home testing kit distribution through Bangalore's digital health infrastructure. Pursue PMDA quality management system certification ahead of competitors to establish first-mover positioning in Japan's community health networks. For Investors and Strategic Acquirers: Capital is best deployed toward point-of-care biosensor specialists with smartphone connectivity IP and existing European notified body relationships. Long-term viability hinges on regulatory clearance breadth across FDA, EMA, and PMDA pathways rather than single-market dominance. Watch for reimbursement expansion signals in Germany's statutory health insurance framework as inflection indicators for home-based monitoring adoption.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Certification Pathway | Quality management system investment opens Japan's aging-population diagnostic demand. |
| Hospital System Partnership | Multi-year reagent contracts with GPO-affiliated networks lock in consumable revenue streams. |
| Software Companion Development | Smartphone-connected reader integration enables direct-to-consumer channel bypass of laboratory infrastructure. |
| CE Marking Pathway | IVDR Class C compliance maintains European market access amid recalibrated conformity timelines. |
| Reimbursement Strategy | Statutory health insurance coverage expansion in Germany reduces patient out-of-pocket barriers. |
Research Methodology
Initial hypotheses were tested against primary input from hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at diagnostic manufacturers and refined through secondary validation. Sources included FDA 510(k) filings, EMA IVDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up instrument placement and reagent volume estimates were triangulated against top-down market sizing from analyzer installed-base analysis.
Demand-supply balance across immunoassay kits, test strips, and biosensor platforms anchored the analytical framework over the projection horizon. Segmentation modeled product type, application, end user, and deployment mode dimensions with regional regulatory cluster differentiation. CAGRs were derived from installed-base growth rates and consumable pull-through assumptions, incorporating diabetes prevalence trajectories and chronic disease screening protocol maturation as disease-specific inputs.
Practitioners should monitor reimbursement policy shifts, regulatory clearance timeline extensions, and antibody supply quality incidents for early signals of forecast deviation. Forecasts reflect assumptions about CLIA certification stability, IVDR implementation pace, and point-of-care adoption curves. Material shifts in Medicare coverage determination for home-based microalbumin monitoring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Glioblastoma Multiforme (GBM) Market
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
X-Linked Hypophosphatemia Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Albendazole Drugs Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Asparaginase Market