
 Genetic Material Market | 2026-2036
Genetic Material Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Material Market Insights
The EU Green Deal is expanding disclosure obligations for bioproduction chemicals, compelling genetic material suppliers to requalify solvent and reagent supply chains. Thermo Fisher Scientific leverages its vertically integrated life sciences platform to sustain dual-source plasmid manufacturing across multiple continents. Illumina anchors high-throughput sequencing demand by controlling instrument placement and consumable pull-through in clinical and research labs. QIAGEN differentiates through sample preparation automation that locks in recurring nucleic acid purification revenues.
Genetic material comprises nucleic acid polymers—DNA, RNA, plasmids, and oligonucleotides—typically synthesized through phosphoramidite chemistry or amplified via bacterial fermentation, with purity grades ranging from research-grade to GMP-certified for human therapeutic use. These molecules serve as the fundamental substrates for gene editing, diagnostic amplification, and therapeutic manufacturing across biotechnology workflows. DNA and plasmid segments dominate current value capture due to their centrality in viral vector production and cell therapy engineering, while oligonucleotide demand accelerates fastest as antisense and siRNA therapeutics advance through late-stage pipelines. CRISPR technology occupies the highest-margin application tier because guide RNA and donor template sourcing command premium pricing tied to therapeutic exclusivity timelines.
FDA enforces Current Good Manufacturing Practice for active pharmaceutical ingredients, including nucleic acids intended for human administration, while EMA's ATMP framework imposes additional traceability and potency verification standards for gene therapy substrates. ISO 13485 and ISO 20387 biobanking standards further constrain supplier qualification pathways, particularly for diagnostic-grade genetic material deployed in regulated clinical assays. Stakeholders must monitor how emerging gene editing therapies reshape supplier qualification burdens and raw material specification thresholds.
Market Dynamics
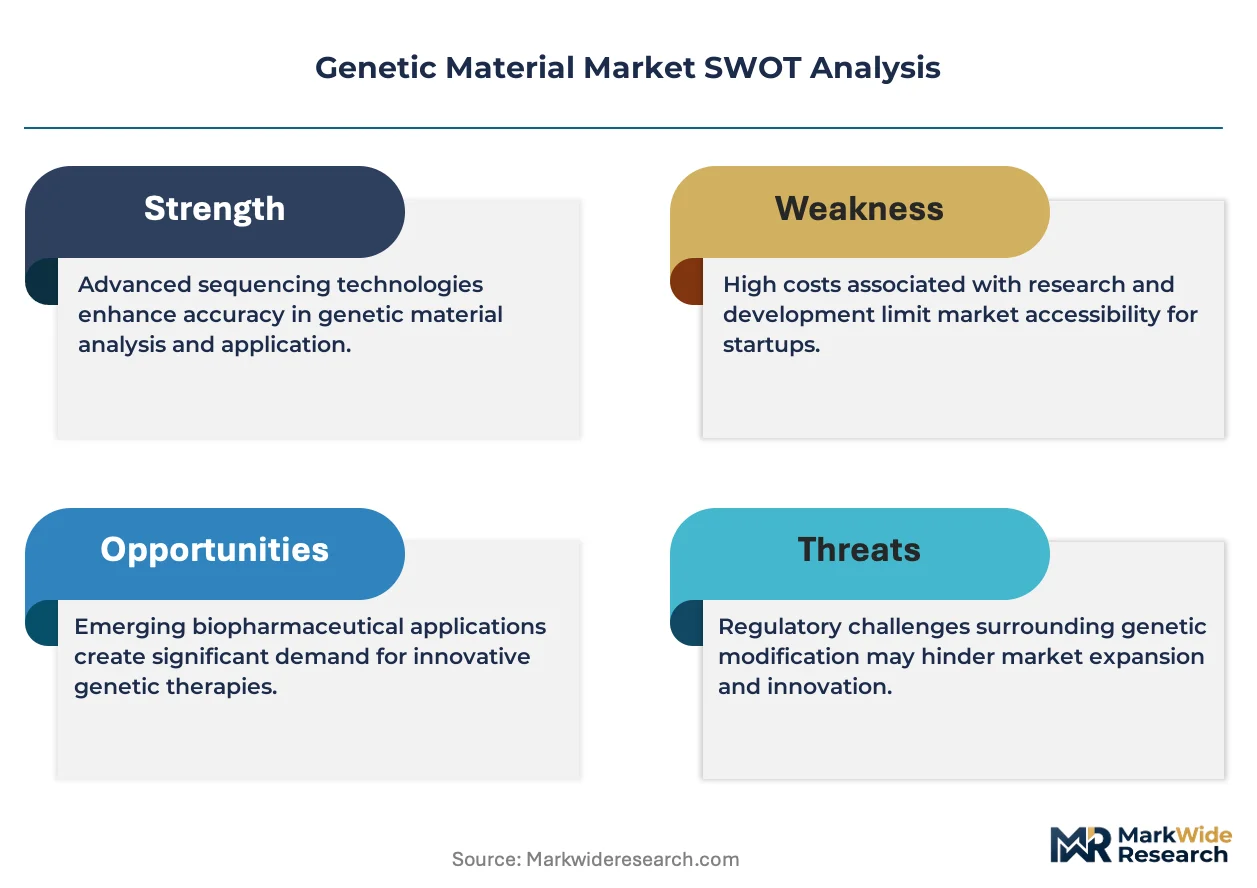
The FDA's accelerated approval pathways for nucleic acid therapeutics are compressing supplier qualification timelines while simultaneously elevating raw material specification thresholds, forcing genetic material vendors to reengineer manufacturing footprints.
Growth Catalysts
- ATMP Framework Enforcement:EMA's traceability mandates for gene therapy substrates are pulling GMP-certified plasmid volumes across European contract manufacturing networks.
- Cell Therapy Pipeline Expansion:CD19-directed CAR-T programs are consuming viral vector-grade DNA at rates that outstrip current fermentation capacity.
- CRISPR Therapeutic Maturation:Guide RNA synthesis demand is electrifying phosphoramidite chemistry throughput requirements in North American production facilities.
Market Restraints
- Phosphoramidite Supply Concentration:Key reagent precursors remain captive to German and Swiss specialty chemical houses, exposing synthesis costs to EUR/USD volatility.
- GMP Facility Scarcity:FDA-inspected cleanroom capacity for plasmid fermentation concentrates in Massachusetts and California, creating geographic chokepoints.
- Batch Release Timelines:Potency verification for nucleic acid APIs under ICH Q5A extends lead times beyond therapeutic development schedules.
Strategic Opportunities
- Singapore Biomanufacturing Hub:EDB incentives for cell therapy infrastructure are attracting plasmid suppliers to establish Asia-Pacific GMP footprints.
- Automated Oligonucleotide Synthesis:Flow chemistry integration with real-time quality analytics is collapsing cost curves for mid-scale therapeutic-grade production.
- EU Green Deal Compliance Services:Solvent recycling and bioproduction chemical disclosure verification represent emerging revenue streams for qualified contract manufacturers.
Industry Challenges
- Phosphoramidite Chemist Shortage:Specialized synthesis expertise required for ultra-high-purity oligonucleotide production remains concentrated among retiring technical cohorts.
- Multi-Site Qualification Burden:ISO 13485 and ISO 20387 biobanking standards impose redundant audit requirements across distributed manufacturing networks.
- Guide RNA IP Thickets:CRISPR licensing complexity from Broad Institute and UC Berkeley patent estates is delaying therapeutic program timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Material Market |
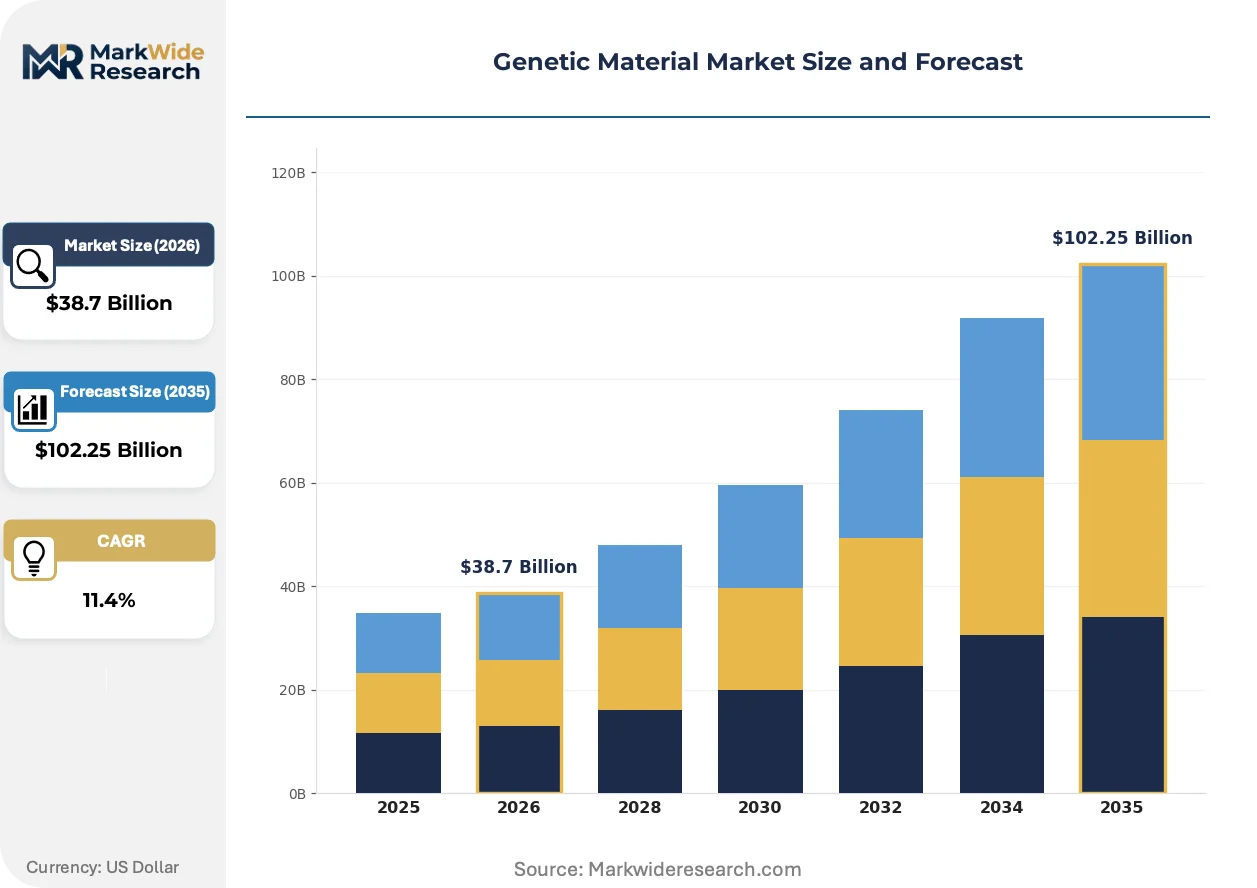
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA, RNA, Plasmids, Oligonucleotides Application: Genetic Engineering, Therapeutics, Research, Diagnostics End User: Pharmaceuticals, Academic Institutions, Biotechnology Firms, Contract Research Organizations Technology: CRISPR, Sequencing, PCR, Gene Synthesis |
| Companies Covered | Thermo Fisher Scientific Inc., Illumina, Inc., Abbott Laboratories, Bio-Rad Laboratories, Inc., F. Hoffmann-La Roche Ltd, QIAGEN, Eurofins Scientific, Danaher, Agilent Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Material Market Trends and Innovations
Continuous manufacturing architectures are displacing batch fermentation for plasmid DNA, while regulatory data integrity requirements are forcing digital transformation of quality management systems across supplier tiers.
Enzymatic DNA synthesis is electrifying the production of complex gene sequences that phosphoramidite chemistry cannot access efficiently. Synthetic biology startups are adopting this platform for therapeutic construct development. The technology is compressing timelines for personalized cancer vaccine programs by eliminating bacterial cloning steps.
EMA's ATMP framework revisions are tightening potency assay requirements for nucleic acid starting materials. European contract manufacturers must now demonstrate sequence-specific functional activity rather than relying solely on purity metrics. Gene therapy developers are responding by integrating analytical development earlier into supplier qualification protocols.
Biopharmaceutical procurement teams are consolidating genetic material vendors to reduce qualification overhead. Large-cap cell therapy developers are awarding multi-year sole-source contracts for GMP plasmid supply. This concentration is most visible in the United States, where FDA breakthrough therapy designations are compressing raw material sourcing decisions into compressed program timelines.
Genetic Material Market Segmentation
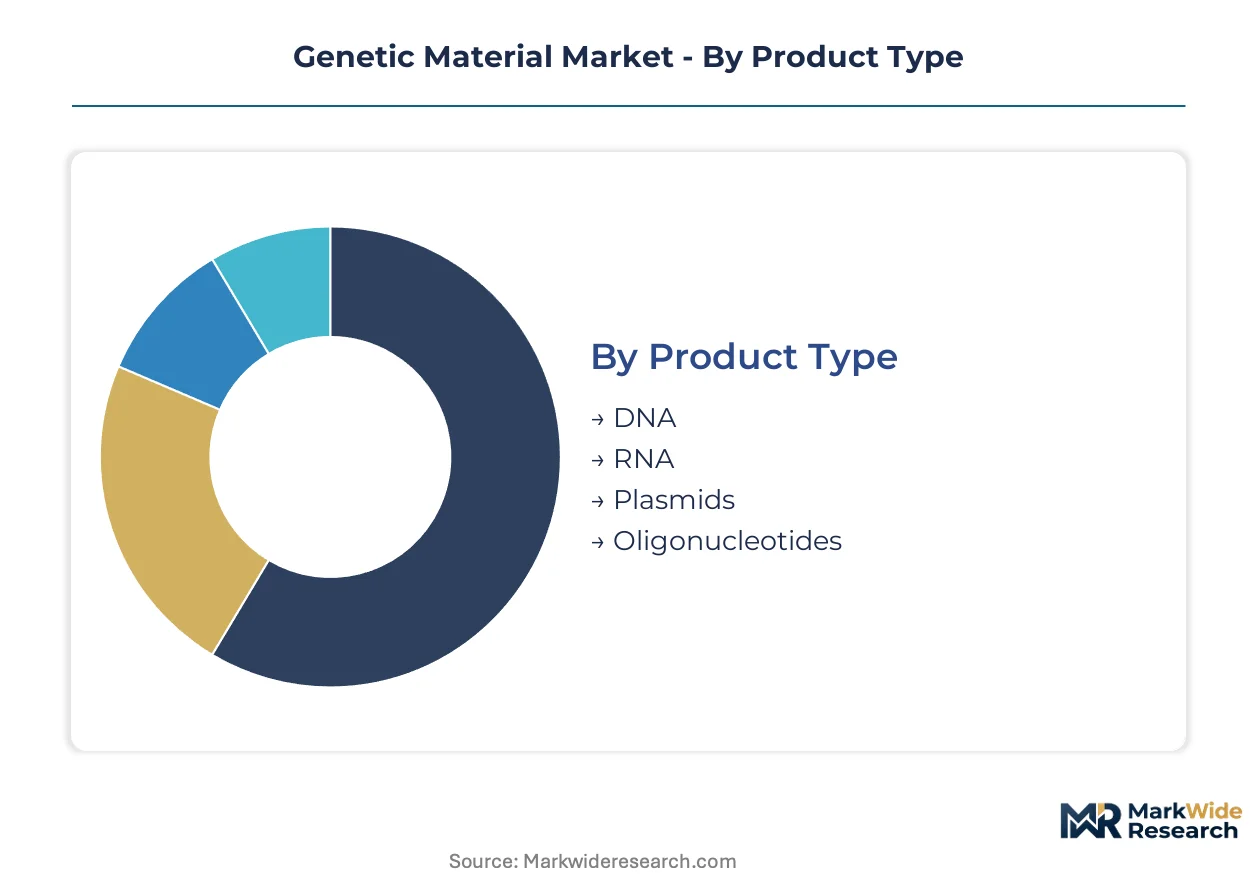
Segmentation in genetic materials reveals how manufacturing capabilities and regulatory requirements fragment across use cases. Suppliers must align purification grades, documentation packages, and capacity scales to distinct customer workflows rather than serving homogeneous demand.
Product Type:
Supply concentration varies sharply across molecular formats, with fermentation-based production dominating some categories while chemical synthesis controls others.
- DNA:Chromosomal and genomic DNA extracts serve as PCR templates and cloning substrates. Viral vector manufacturers in Massachusetts and California are pulling research-grade and GMP-certified genomic DNA at volumes that strain agarose purification capacity.
- RNA:Messenger RNA, total RNA, and guide RNA span synthetic and enzymatic production modalities. mRNA therapeutic developers are locking in multi-year supply agreements for N1-methylpseudouridine-modified transcripts ahead of FDA breakthrough therapy deadlines.
- Plasmids:Circular DNA vectors propagate in bacterial hosts for transfection and protein expression. EMA's ATMP traceability mandates are forcing European contract manufacturers to dual-source GMP plasmid fermentation across Swiss and German facilities.
- Oligonucleotides:Short synthetic sequences enable primers, probes, and antisense therapeutics through phosphoramidite chemistry. Singapore's EDB incentives are attracting automated oligonucleotide synthesis platforms to establish Asia-Pacific GMP footprints.
Plasmids absorb the bulk of installed fermentation capacity; oligonucleotides are expanding most quickly as therapeutic-grade synthesis scales.
Application:
End-use specifications diverge across regulatory boundaries, with human therapeutic applications imposing the steepest purity and documentation burdens on suppliers.
- Genetic Engineering:CRISPR construct assembly and viral vector packaging require sequence-verified substrates. Cell therapy developers are consolidating plasmid vendors to reduce ISO 13485 qualification overhead across distributed manufacturing networks.
- Therapeutics:Nucleic acid APIs for human administration face FDA Current Good Manufacturing Practice enforcement. Antisense and siRNA programs are electrifying phosphoramidite chemistry throughput requirements in North American production facilities.
- Research:Non-GMP grades support discovery biology and preclinical validation. Academic procurement teams prioritize cost efficiency over batch documentation, fragmenting supplier relationships across catalog distributors.
- Diagnostics:Clinical-grade nucleic acids power PCR assays and sequencing panels. ISO 20387 biobanking standards constrain supplier qualification pathways for diagnostic-grade material deployed in regulated clinical assays.
Therapeutics commands the steepest price premiums; diagnostics is gaining share fastest as liquid biopsy and infectious disease testing expand.
End User:
Customer scale and procurement sophistication segment the vendor landscape, with large-cap developers extracting volume commitments that mid-tier suppliers cannot match.
- Pharmaceuticals:Integrated drug developers source GMP nucleic acids for commercial therapeutic manufacturing. CD19-directed CAR-T programs are consuming viral vector-grade DNA at rates that outstrip current fermentation capacity.
- Academic Institutions:University labs purchase research-grade materials through distributor channels. Budget constraints fragment purchasing across multiple catalog suppliers rather than consolidating for volume discounts.
- Biotechnology Firms:Venture-backed startups bridge discovery and clinical phases with flexible sourcing strategies. Gene therapy developers are integrating analytical development earlier into supplier qualification protocols to meet EMA potency assay revisions.
- Contract Research Organizations:CROs provide outsourced manufacturing and testing services requiring dual inventory positions. Multi-site qualification burdens under ISO 13485 and ISO 20387 standards impose redundant audit requirements across distributed manufacturing networks.
Pharmaceuticals anchor procurement volume; biotechnology firms are scaling fastest as cell and gene therapy venture funding concentrates.
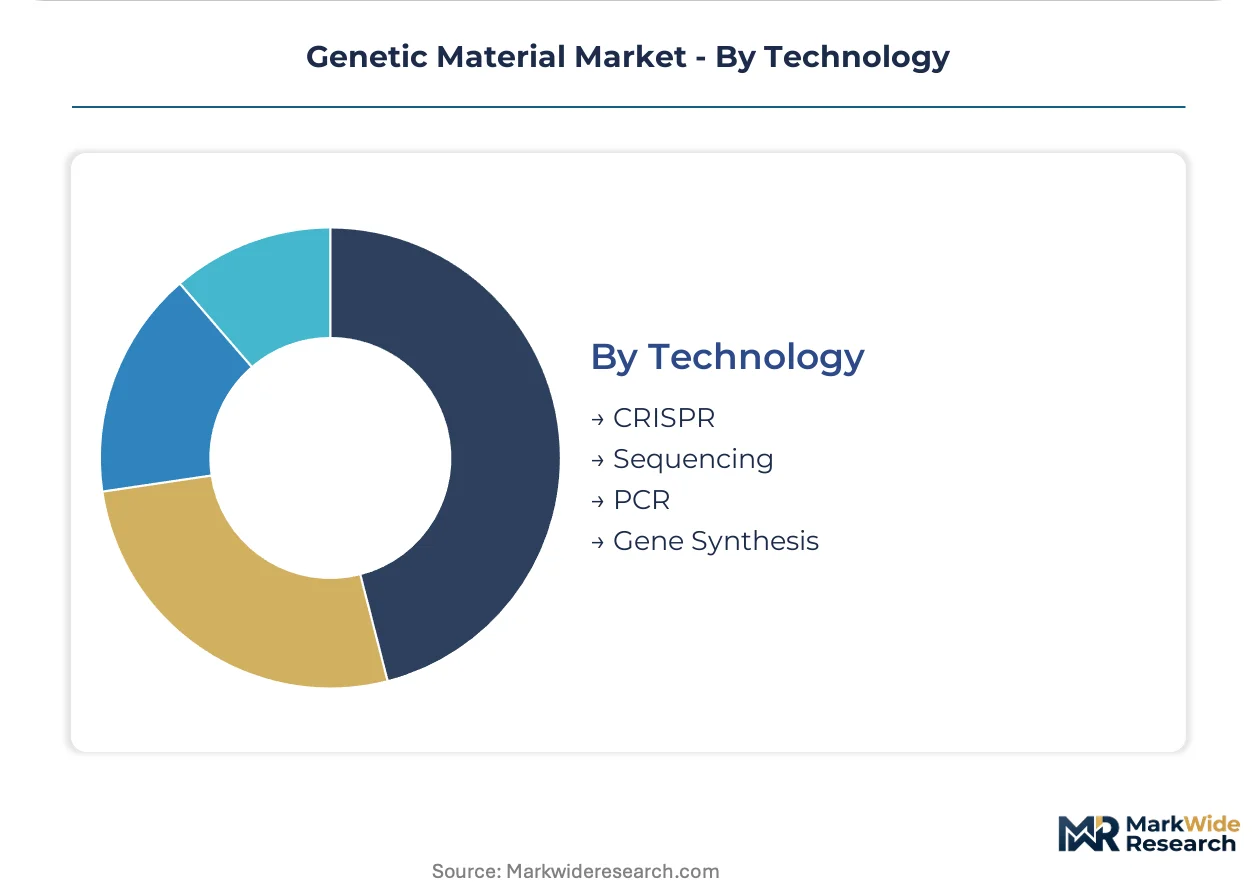
Technology:
Platform selection determines reagent pull-through and instrument lock-in, with sequencing and CRISPR creating the most durable supplier relationships.
- CRISPR:Guide RNA and donor template sourcing command premium pricing tied to therapeutic exclusivity timelines. Guide RNA IP thickets from Broad Institute and UC Berkeley patent estates are delaying therapeutic program timelines.
- Sequencing:Next-generation and Sanger platforms consume library preparation kits and flow cells. Illumina anchors high-throughput demand by controlling instrument placement and consumable pull-through in clinical and research labs.
- PCR:Amplification workflows require primers, polymerases, and probe chemistries. Diagnostic manufacturers are consolidating oligonucleotide vendors to secure supply continuity for infectious disease assay production.
- Gene Synthesis:De novo DNA construction spans phosphoramidite and enzymatic methodologies. Enzymatic synthesis is compressing timelines for personalized cancer vaccine programs by eliminating bacterial cloning steps.
Sequencing dominates current reagent pull-through; gene synthesis is climbing the fastest as enzymatic platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square corridor concentrates cell therapy developers consuming GMP plasmid volumes that outstrip regional fermentation capacity. FDA breakthrough therapy designations are compressing raw material procurement timelines across Massachusetts and California clusters.
United States
CD19-directed CAR-T programs in Massachusetts and California are pulling viral vector-grade DNA at rates exceeding installed fermentation capacity. FDA accelerated approval pathways for nucleic acid therapeutics elevate raw material specification thresholds while compressing supplier qualification timelines. The Greater Boston biotech corridor anchors North American demand for GMP-certified genetic material.
Germany
EMA's ATMP traceability mandates are forcing contract manufacturers to dual-source GMP plasmid fermentation across Swiss and German facilities. REACH framework disclosure requirements for bioproduction chemicals compel solvent supply chain requalification. The Rhine-Main biopharma cluster around Frankfurt hosts concentrated oligonucleotide synthesis capacity serving European therapeutic developers.
Switzerland
Specialty chemical houses in Basel control phosphoramidite precursor supply for oligonucleotide synthesis across European production networks. Swissmedic enforces potency verification standards that extend batch release timelines for nucleic acid APIs. The Basel-Zurich corridor anchors continental supply of ultra-high-purity reagents for therapeutic-grade manufacturing.
Singapore
EDB incentives for cell therapy infrastructure are attracting plasmid suppliers to establish Asia-Pacific GMP footprints. The country's national pharmaceutical regulator aligns with international standards to accelerate therapeutic program approvals. Tuas Biomedical Park hosts expanding fermentation capacity serving regional gene therapy developers.
China
NMPA reform pathways for innovative biologics are pulling CRISPR guide RNA demand through domestic synthesis platforms. Dual carbon goals pressure solvent-intensive phosphoramidite chemistry operations toward process efficiency investments. The Suzhou BioBAY cluster concentrates enzymatic DNA synthesis startups targeting personalized cancer vaccine programs.
Genetic Material Market Competitive Landscape
The competitive structure tilts toward vertically integrated life sciences conglomerates controlling instrument placement and consumable pull-through. Tier-one players anchor high-throughput sequencing demand by locking in recurring reagent revenues across clinical and research labs. Mid-scale specialists compete on automated sample preparation and purification workflows. Dominant competitive moves span capacity expansion in Asia-Pacific GMP zones and strategic partnerships for enzymatic synthesis technology access.
Among diversified life sciences conglomerates, Thermo Fisher Scientific Inc. exemplifies the vertically integrated archetype spanning plasmid manufacturing across multiple continents. Illumina, Inc. anchors the sequencing-platform tier by controlling instrument ecosystems that drive consumable demand. QIAGEN occupies a position within the sample-preparation automation segment, locking in recurring nucleic acid purification revenues through integrated workflow solutions.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Illumina, Inc. |
| Abbott Laboratories |
| Bio-Rad Laboratories, Inc. |
| F. Hoffmann-La Roche Ltd |
| QIAGEN |
| Eurofins Scientific |
| Danaher |
| Agilent Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
GMP-certification grade bifurcation splits the genetic material market into premium therapeutic tiers and commoditized research segments, with FDA and EMA compliance thresholds determining both price floors and supplier qualification pathways. This divergence concentrates pricing power among vertically integrated incumbents controlling multi-continent fermentation networks while fragmenting procurement across catalog distributors for non-regulated grades.
Pricing Analysis
Throughput-linked value capture anchors pricing for high-purity nucleic acids, with therapeutic-grade plasmids and guide RNA commanding premiums tied to batch yield consistency and regulatory documentation depth. Pricing stratifies across GMP-certified, research-grade, and economy tiers based on purity verification protocols and ISO 13485 certification status. Cost compression in research-grade oligonucleotides is intensifying as automated phosphoramidite synthesis platforms expand capacity. Academic procurement teams exhibit highest price sensitivity, while pharmaceutical developers prioritize supply continuity over unit economics.
Supply Chain Analysis
ISO 20387 biobanking standards and FDA Current Good Manufacturing Practice requirements gate supplier qualification, concentrating GMP plasmid fermentation in Massachusetts, California, and Swiss facilities. Phosphoramidite precursor supply draws from German and Swiss specialty chemical houses, with enzymatic DNA synthesis feedstocks emerging from Suzhou BioBAY clusters. Single-source vulnerability permeates ultra-high-purity reagent supply, exposing synthesis costs to EUR/USD volatility. Distribution runs through direct procurement contracts for pharmaceutical developers and distributor channels for academic institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The genetic material market functions as a cost-of-compliance arena where EMA's ATMP traceability mandates erect substantial barrier-to-entry moats for qualified GMP suppliers. Regulatory documentation burdens favor incumbents with established audit histories and multi-site certification portfolios.
For Market Incumbents: To counter phosphoramidite chemist attrition, deploy automated flow chemistry platforms with embedded real-time quality analytics to collapse production cost curves. Secure backward integration into solvent recycling infrastructure to preempt EU Green Deal disclosure penalties. Dual-source fermentation capacity across Singapore and Swiss facilities to dilute geographic chokepoint risk.
For New Entrants and Emerging Players: Launch via enzymatic DNA synthesis platforms targeting personalized cancer vaccine developers seeking compressed construct timelines. Penetrate the Asia-Pacific GMP plasmid supply gap where EDB incentives attract infrastructure investment but qualified fermentation capacity remains scarce. Position around EU Green Deal compliance services as emerging revenue streams for contract manufacturers.
For Investors and Strategic Acquirers: Re-rating potential sits with automated sample-preparation specialists given diagnostic liquid biopsy expansion and ISO 20387 biobanking standard enforcement. Long-term viability hinges on therapeutic-grade nucleic acid API positioning within cell and gene therapy supply chains. Monitor CRISPR guide RNA IP resolution between Broad Institute and UC Berkeley patent estates as inflection signal for therapeutic program acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Capacity Expansion | FDA-inspected cleanroom additions in Massachusetts and California address viral vector-grade DNA supply deficits for CD19-directed CAR-T programs. |
| Enzymatic Synthesis Platform Integration | De novo DNA construction technology eliminates bacterial cloning steps, compressing personalized cancer vaccine development timelines. |
| Asia-Pacific Manufacturing Footprint | Singapore EDB incentives attract plasmid suppliers establishing regional GMP fermentation capacity serving gene therapy developers. |
| EU Green Deal Compliance Services | Solvent recycling and bioproduction chemical disclosure verification create defensible revenue streams for qualified European contract manufacturers. |
| Automated Oligonucleotide Synthesis | Flow chemistry integration with real-time analytics collapses cost curves for mid-scale therapeutic-grade phosphoramidite production. |
Research Methodology
Multi-period observation of plasmid fermentation capacity utilization, phosphoramidite precursor pricing volatility, and nucleic acid therapeutic pipeline advancement anchored the trend analysis, supplemented by interviews with gene therapy supply chain directors, GMP facility quality leads, diagnostic assay developers, and academic procurement managers. Secondary validation drew from FDA filings, EMA ATMP framework revisions, ClinicalTrials.gov nucleic acid therapeutic entries, and SEC 10-K disclosures from listed life sciences conglomerates. Bottom-up segment sizing triangulated against top-down therapeutic market projections.
Segment-weighting across product type, application, end user, and technology dimensions structured the analytical framework across the analysis window. Modeled categories spanned DNA, RNA, plasmids, and oligonucleotides by molecular format; genetic engineering, therapeutics, research, and diagnostics by end-use; with CRISPR, sequencing, PCR, and gene synthesis platforms as technology anchors. CAGRs derived from regression analysis of historical procurement volumes against therapeutic pipeline stage transitions and regulatory approval velocity.
EMA potency assay requirement revisions, CRISPR licensing resolution timelines, and phosphoramidite supply concentration shifts are the dominant revision risks to modeled projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Microbiome Sequencing Market
Genomics
Genomic Biomarkers Market
Genomics
United States DNA Sequencing Products Market
Genomics
DNA Methylation Market
Genomics
Global Gene Amplification Technologies Market
Genomics
Digital Genome Market
Genomics
Retail Genomics Market
Genomics
Global Nutrigenomics Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
Global Single-Cell Genome Sequencing Market
Genomics
Genetic Analysis Services Market
Genomics
NGS Automation Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Gene Sequencing Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market