
 Qpcr Instruments Market | 2026-2036
Qpcr Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Qpcr Instruments Market Intelligence
The EU Medical Device Regulation is pivoting molecular diagnostic equipment toward stricter post-market surveillance and clinical evidence standards. Thermo Fisher Scientific leverages its vertically integrated reagent-instrument ecosystem to sustain installed-base loyalty across European reference laboratories. F. Hoffmann-La Roche Ltd. anchors its competitive position through proprietary assay-to-platform lock-in strategies. Bio-Rad Laboratories, Inc. differentiates via open-architecture thermal cycler designs that accommodate third-party chemistries.
Quantitative polymerase chain reaction instruments are thermal cyclers equipped with optical detection systems that measure fluorescence emission during amplification cycles, typically operating across 96-well or 384-well formats with ramp rates exceeding five degrees Celsius per second. Their primary commercial purpose is absolute or relative nucleic acid quantification for gene expression profiling, pathogen load determination, and genetic variant detection. Standalone real-time PCR systems dominate current revenue pools due to their flexibility across research and clinical workflows, while digital PCR segments capture premium pricing in liquid biopsy and rare-mutation applications where absolute quantification eliminates standard-curve dependency. Multiplex fluorescent technologies lead adoption in pharmaceutical quality-control settings where throughput efficiency determines capital allocation priorities.
The US FDA regulates qPCR instruments as Class II medical devices under 21 CFR requirements, while the EU MDR mandates notified-body certification and unique device identification for in-vitro diagnostic platforms. China's NMPA implements GB standard compliance testing for imported molecular diagnostic equipment, creating divergent approval timelines that shape manufacturer geographic sequencing strategies. Stakeholders must monitor evolving harmonization efforts between FDA and EMA qualification standards for companion diagnostic co-development programs.
Market Dynamics
The qPCR instruments market is being fundamentally restructured by the FDA's companion diagnostic guidance expansion, which mandates instrument qualification upgrades for oncology co-development programs and forces capital redeployment toward regulatory-compliant platforms.
Growth Catalysts
- Companion diagnostic mandates:The FDA's evolving guidance on CDx co-development is compelling pharmaceutical sponsors to qualify qPCR platforms earlier in drug pipelines, expanding installed-base commitments across contract research organizations.
- Infectious disease surveillance infrastructure:Public health laboratories in Germany, the United States, and China are consolidating molecular testing networks around standardized real-time PCR architectures to enable pathogen genomic monitoring.
- Digital PCR transition:Absolute quantification capabilities are overtaking traditional standard-curve methods in liquid biopsy workflows, creating upgrade cycles among precision medicine reference laboratories.
Market Restraints
- Optical component supply concentration:Photomultiplier tube and LED sourcing concentrates among Japanese and German specialty component suppliers, exposing instrument manufacturers to extended lead times.
- EU MDR certification friction:The Medical Device Regulation's stricter clinical evidence requirements for Class IIa/IIb in-vitro diagnostic platforms are elongating approval timelines and inflating regulatory affairs overhead.
- Digital PCR price compression:Droplet-based absolute quantification systems command three to five-fold premiums over real-time PCR, constraining adoption to well-capitalized academic medical centers and limiting mid-tier laboratory access.
Strategic Opportunities
- Point-of-care decentralization:Miniaturized thermal cycler architectures are penetrating physician office laboratories and urgent care networks in the United States, displacing send-out molecular testing models.
- China NMPA pathway optimization:Streamlined GB standard compliance testing for imported molecular diagnostic equipment is enabling faster geographic sequencing for manufacturers with established European or US regulatory dossiers.
- Multiplex assay convergence:Integration of high-plex chemistries with open-architecture instrumentation is creating differentiation pathways for third-party assay developers serving pharmaceutical quality-control segments.
Industry Challenges
- Bioinformatics integration complexity:Laboratory information management system connectivity and cloud-based analysis pipeline deployment require specialized IT infrastructure investments that strain mid-sized clinical laboratory capital budgets.
- Reagent-instrument compatibility verification:Cross-platform chemistry validation demands extensive analytical performance studies, consuming technical resources and delaying assay transfer between instrument generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qpcr Instruments Market |
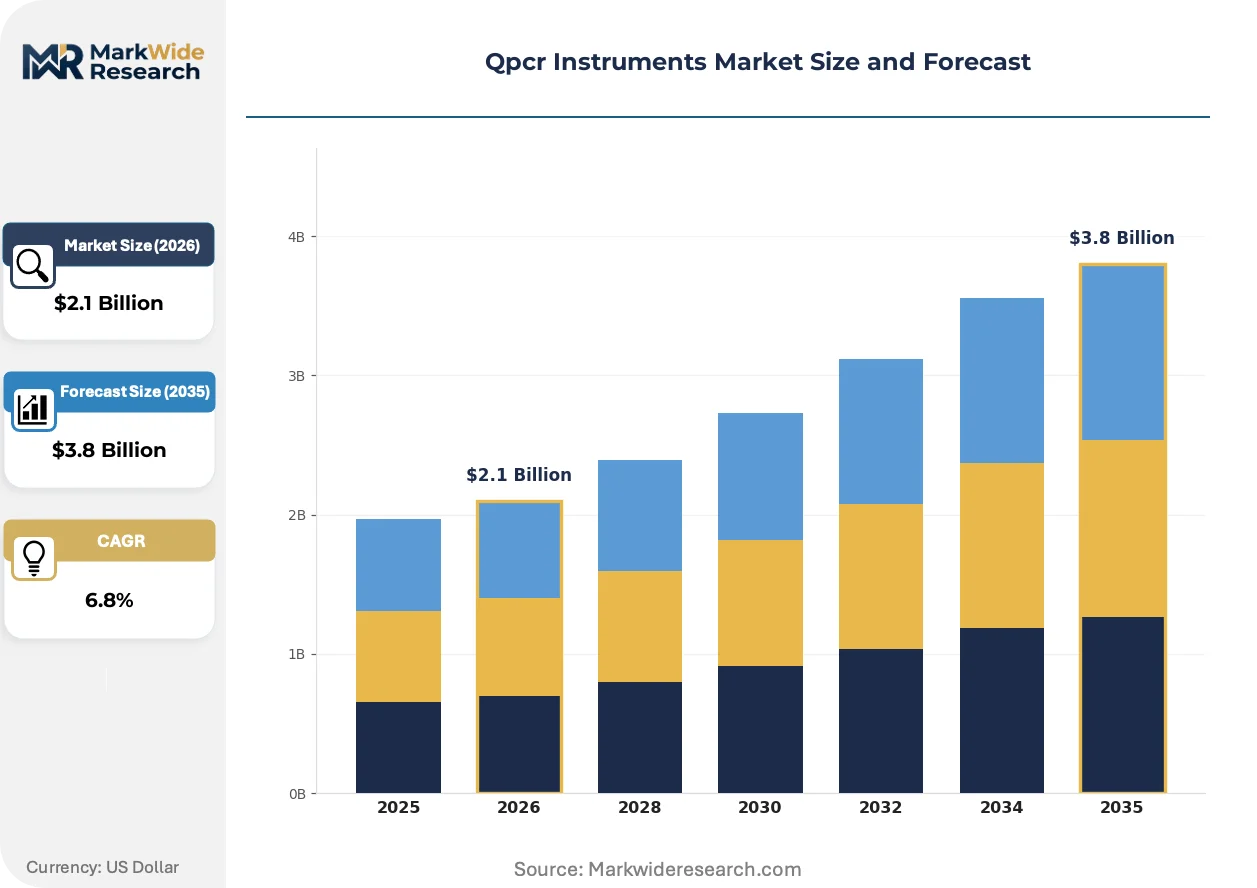
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated Systems, Real-Time PCR, Digital PCR Technology: Fluorescent, Colorimetric, Reverse Transcription, Multiplex End User: Research Institutions, Clinical Laboratories, Biotechnology Companies, Pharmaceutical Companies Application: Genetic Research, Drug Development, Diagnostics, Environmental Testing |
| Companies Covered | Thermo Fisher Scientific, Inc., F. Hoffmann-La Roche Ltd., Bio-Rad Laboratories, Inc., Agilent Technologies, Inc., QIAGEN N.V., Danaher Corporation, Abbott Laboratories Inc., Bio Molecular Systems, Azure Biosystems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qpcr Instruments Market Strategic Shifts & Innovations
Instrument architecture is converging around modular optical detection systems and cloud-native analysis platforms, compressing the traditional separation between hardware procurement and software subscription models. Three developments are commanding strategic attention.
Next-generation digital PCR platforms incorporating nanopartitioning microfluidics are overtaking droplet-based methods in rare-mutation detection sensitivity. Reference laboratories in oncology companion diagnostic programs are adopting these systems for circulating tumor DNA quantification. The shift is compressing competitive differentiation around absolute quantification accuracy rather than throughput specifications.
The EU AI Act's risk classification framework for medical device software is mandating algorithmic transparency documentation for qPCR analysis modules. Manufacturers must now submit training data provenance and performance validation protocols for machine learning-enhanced cycle threshold interpretation. European notified bodies are prioritizing review resources toward high-risk diagnostic algorithm submissions, creating approval queue dynamics that favor established regulatory affairs capabilities.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships in United States hospital network molecular diagnostics. Integrated delivery networks are standardizing on single-vendor thermal cycler fleets to compress service contract complexity and training overhead. The concentration is most visible in multi-hospital systems exceeding five hundred beds, where capital committee approval timelines have compressed from eighteen to nine months.
Qpcr Instruments Market Segmentation
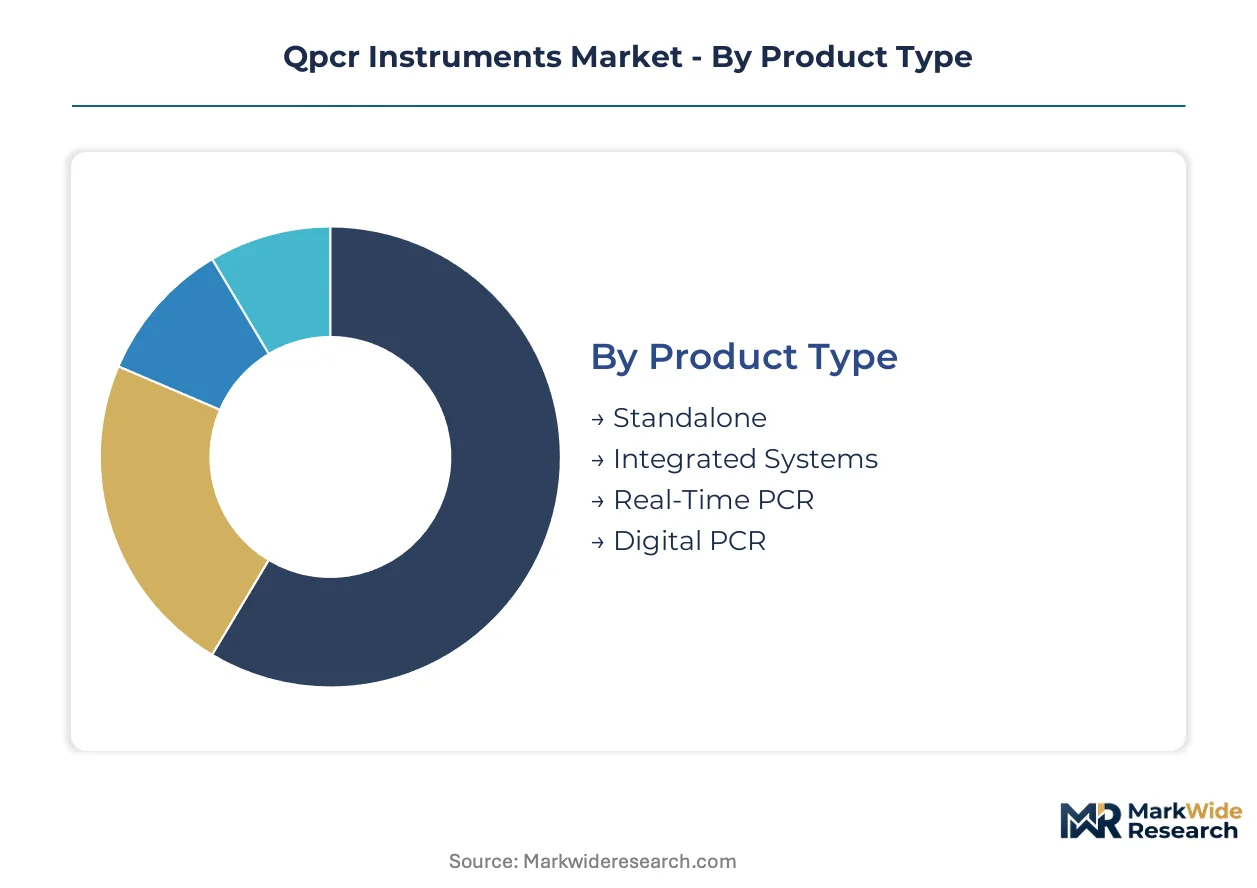
Segmentation in the qPCR instruments market reveals how thermal cycler architectures align with distinct workflow requirements across research and clinical environments. Product configuration, detection chemistry, and end-use setting collectively determine capital allocation patterns and upgrade cycles.
Product Type:
Standalone systems dominate laboratory floors where flexibility across assay chemistries matters, while integrated platforms serve high-throughput environments seeking workflow compression.
- Standalone:Modular thermal cyclers with swappable optical blocks accommodate 96-well and 384-well formats across research institutions and reference laboratories. Demand concentrates in the United States and Germany where multi-assay flexibility justifies dedicated benchtop footprint.
- Integrated Systems:Pre-integrated nucleic acid extraction-to-detection platforms compress hands-on time in clinical diagnostic laboratories. China's NMPA certification pathways are accelerating placements in tertiary hospital molecular diagnostic centers seeking reduced technician intervention.
- Real-Time PCR:Fluorescence-monitoring thermal cyclers with continuous data acquisition support gene expression and pathogen load workflows. These systems anchor installed bases across European contract research organizations.
- Digital PCR:Microfluidic-partitioning platforms enable absolute quantification without standard curves. Premium positioning limits current volume to oncology companion diagnostic programs and liquid biopsy reference laboratories.
Volume placements concentrate in Standalone configurations; the faster expansion belongs to Digital PCR.
Technology:
Detection chemistry selection hinges on multiplexing depth requirements and reagent cost structures across application segments.
- Fluorescent:Probe-based and intercalating dye systems capture emission spectra during amplification cycles. SYBR Green and TaqMan chemistries dominate pharmaceutical quality-control settings where sensitivity thresholds are well-characterized.
- Colorimetric:Endpoint visualization methods reduce optical system complexity for resource-limited settings. These technologies are gaining traction in point-of-care molecular diagnostics where instrument cost constraints are acute.
- Reverse Transcription:RNA-to-cDNA conversion modules integrated into thermal cycling protocols support viral load quantification and gene expression profiling. Clinical laboratories in infectious disease surveillance networks prioritize these capabilities.
- Multiplex:Multi-target amplification with spectrally distinct fluorophores compresses per-sample costs in high-throughput screening environments. Drug development pipelines are standardizing on 4-plex and 6-plex configurations to accelerate biomarker panel validation.
Fluorescent detection commands the largest installed base; Multiplex configurations are climbing the fastest in pharmaceutical segments.
End User:
Capital availability and regulatory sophistication shape procurement patterns across customer categories.
- Research Institutions:Academic laboratories prioritize open-architecture platforms compatible with diverse chemistries and third-party assay protocols. Funding cycles from NIH and European Research Council influence replacement timing.
- Clinical Laboratories:Hospital-based and independent diagnostic facilities require FDA-cleared or CE-IVD-marked systems for reimbursed testing. The EU MDR transition is elongating procurement decision timelines as laboratories await notified-body certifications.
- Biotechnology Companies:Discovery-stage and clinical-stage firms balance flexibility with throughput in platform selection. These buyers favor rental and reagent-rental business models to preserve capital for pipeline assets.
- Pharmaceutical Companies:Quality-control and companion diagnostic co-development programs demand validated, audit-ready systems with comprehensive documentation packages. Thermo Fisher and Roche platforms anchor these environments through integrated reagent-instrument ecosystems.
Clinical Laboratories represent the deepest installed base; Biotechnology Companies are expanding most quickly as molecular diagnostic pipelines mature.
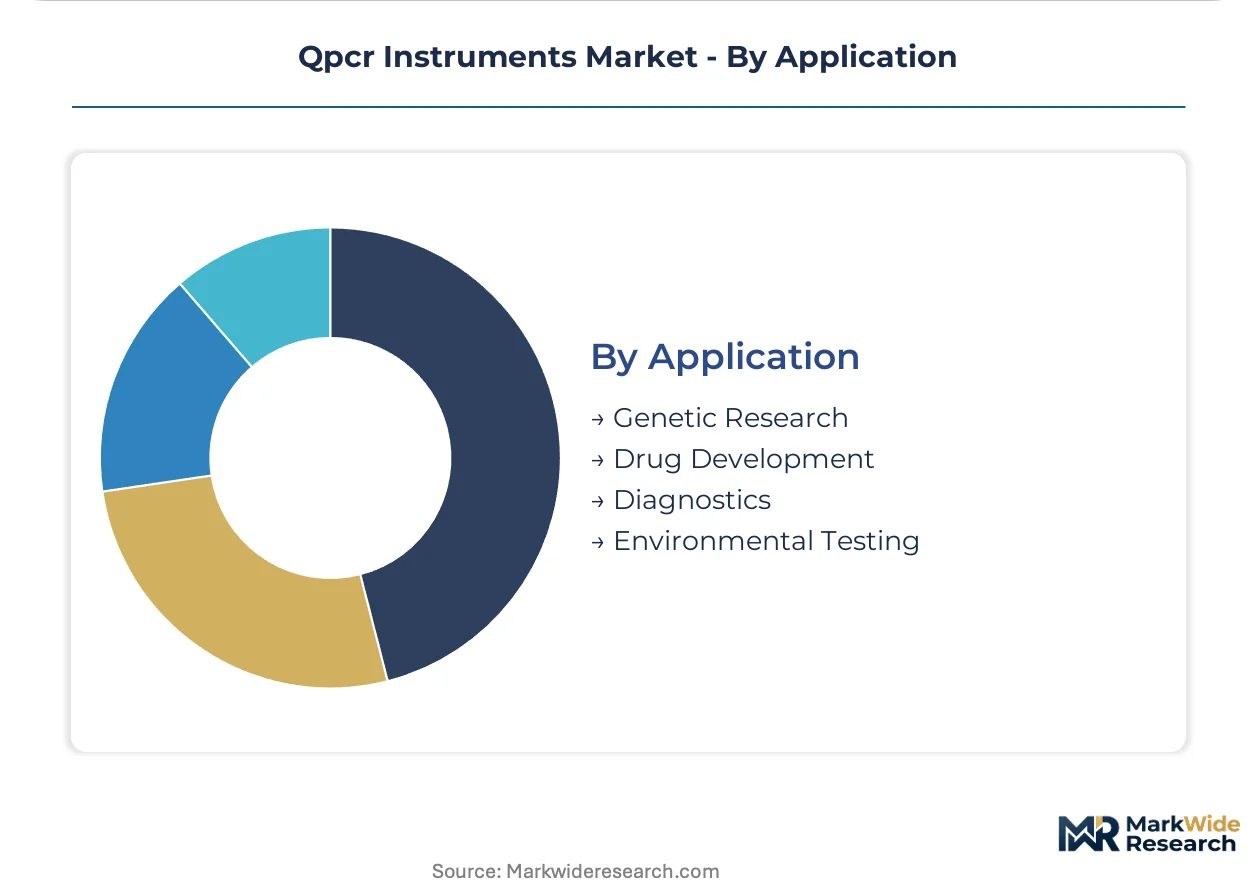
Application:
Workflow specificity determines optical configuration, throughput requirements, and software validation standards.
- Genetic Research:Gene expression profiling and genotyping applications require flexible thermal cycling protocols and multi-format compatibility. Research institutions in the United States and Germany anchor demand for high-resolution melt analysis capabilities.
- Drug Development:Pharmacokinetic biomarker validation and potency assay support demand compliant documentation and audit trails. Pharmaceutical sponsors are qualifying platforms earlier in development pipelines under FDA companion diagnostic guidance.
- Diagnostics:Infectious disease detection and oncology companion testing require regulatory-cleared instruments with locked assay protocols. China's public health laboratory consolidation is standardizing on unified real-time PCR architectures.
- Environmental Testing:Water quality and food safety applications prioritize ruggedized thermal cyclers with simplified maintenance protocols. These segments favor cost-optimized platforms over premium research-grade systems.
Diagnostics captures the highest unit volume; Drug Development is gaining share fastest as companion diagnostic mandates deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square corridor concentrates precision medicine infrastructure that drives North American qPCR instrument procurement, with academic medical centers and contract research organizations anchoring regional demand patterns.
United States
FDA companion diagnostic mandates are compelling pharmaceutical sponsors to qualify thermal cycler platforms earlier in oncology drug pipelines. The agency's evolving guidance on co-development programs is reshaping instrument qualification requirements across contract research organizations. Research Triangle Park in North Carolina hosts consolidated molecular diagnostic testing networks that standardize on unified real-time PCR architectures for pathogen genomic surveillance.
Germany
Public health laboratories in Berlin and Munich are consolidating molecular testing networks around standardized qPCR platforms to enable national pathogen genomic monitoring capabilities. The EU Medical Device Regulation mandates notified-body certification and unique device identification for in-vitro diagnostic platforms, elongating approval timelines. The Rhine-Main biotechnology cluster around Frankfurt anchors pharmaceutical quality-control demand for multiplex fluorescent systems.
China
Tertiary hospital molecular diagnostic centers in Shanghai and Beijing are accelerating placements of integrated extraction-to-detection platforms to reduce technician intervention. The National Medical Products Administration implements GB standard compliance testing for imported molecular diagnostic equipment, creating divergent approval timelines. The Suzhou biomedical industrial park hosts domestic manufacturers developing localized thermal cycler production capacity.
Japan
Reference laboratories in Tokyo and Osaka are adopting digital PCR platforms for circulating tumor DNA quantification in oncology companion diagnostic programs. The Pharmaceuticals and Medical Devices Agency maintains stringent quality management system requirements for molecular diagnostic equipment imports. The Kobe biomedical innovation cluster concentrates precision medicine infrastructure investment from both domestic and multinational instrument suppliers.
United Kingdom
Academic research institutions in Cambridge and London prioritize open-architecture thermal cycler platforms compatible with diverse chemistries and third-party assay protocols. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for in-vitro diagnostic platform certifications. The Oxford-Cambridge arc anchors gene expression profiling demand from European Research Council-funded laboratories.
Qpcr Instruments Market Key Industry Players
The competitive structure tilts toward vertically integrated conglomerates with captive reagent ecosystems. Thermo Fisher Scientific and Roche anchor premium positioning through proprietary assay-to-platform lock-in strategies that sustain installed-base loyalty. Bio-Rad Laboratories occupies a differentiated niche via open-architecture designs accommodating third-party chemistries. Two dominant competitive moves are reshaping positioning: strategic partnerships between instrument manufacturers and pharmaceutical sponsors for companion diagnostic co-development, and geographic expansion through streamlined regulatory dossier leveraging across FDA, EMA, and NMPA pathways.
Among the named players, Thermo Fisher Scientific, Inc. and F. Hoffmann-La Roche Ltd. exemplify the integrated reagent-instrument archetype that dominates pharmaceutical quality-control and clinical diagnostic segments. Bio-Rad Laboratories, Inc. represents the open-system alternative that research institutions and third-party assay developers favor for chemistry flexibility. These three entities collectively illustrate how competitive positioning stratifies between ecosystem lock-in and modular accessibility across end-use segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Bio-Rad Laboratories, Inc. |
| Agilent Technologies, Inc. |
| QIAGEN N.V. |
| Danaher Corporation |
| Abbott Laboratories Inc. |
| Bio Molecular Systems |
| Azure Biosystems Inc. |
| Others |
Cost & Logistics Intelligence
Consolidated procurement through United States hospital group purchasing organizations is compressing capital committee timelines and forcing manufacturers to bundle service contracts with instrument placements, which tightens margins across mid-tier thermal cycler suppliers and accelerates backward integration into captive reagent production.
Pricing Analysis
Throughput-based value anchors dominate qPCR instrument pricing, with pharmaceutical quality-control buyers paying premiums for validated documentation packages and locked assay protocols. Three-tier pricing structure across premium, standard, and economy levels separates oncology companion diagnostic platforms from research-grade open-architecture systems and point-of-care miniaturized units. Cost compression in the mid-tier research segment is intensifying because Chinese domestic manufacturers are expanding localized production capacity. Academic laboratories exhibit highest price sensitivity due to NIH funding cycle constraints, while pharmaceutical sponsors show lowest sensitivity given co-development program qualification requirements.
Supply Chain Analysis
Dual-sourcing mandates from European reference laboratories are compelling instrument manufacturers to qualify secondary suppliers for photomultiplier tubes and precision thermal cycling components. Optical detection subsystems draw from Japan, Germany, and the United States, while thermal cycling hardware sources from China and Mexico. Single-source vulnerability concentrates in Japanese photomultiplier tube suppliers, exposing extended lead times during demand surges. Distribution runs through direct manufacturer relationships in research segments and consolidated procurement channels in United States hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The qPCR instruments market is becoming a vertical-integration race where control over reagent-instrument compatibility determines installed-base loyalty and pricing power.
For Market Incumbents: Extend proprietary assay-to-platform lock-in strategies by deepening reagent ecosystem investments and accelerating companion diagnostic co-development partnerships with oncology sponsors. Digital PCR entrants threaten premium positioning in liquid biopsy workflows. Certification investment in EU MDR and China NMPA pathways preserves geographic expansion optionality. For New Entrants and Emerging Players: Nanopartitioning microfluidics platforms offer a technology-first wedge into rare-mutation detection segments where absolute quantification accuracy commands premium positioning. Point-of-care decentralization in United States urgent care networks represents the most penetrable white space. Reagent-rental business models reduce capital barriers for biotechnology company buyers. For Investors and Strategic Acquirers: Re-rating potential sits with open-architecture platform specialists given multiplex assay convergence trends and third-party chemistry validation demand. Long-term viability over the next decade hinges on cloud-native analysis platform integration and AI-enhanced cycle threshold interpretation capabilities. Watch FDA companion diagnostic guidance expansion velocity as the key inflection signal for co-development program pipeline depth.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Locks pharmaceutical sponsors into qualified qPCR platforms earlier in oncology drug pipelines under FDA guidance mandates. |
| EU MDR Certification Pathway Investment | Accelerates European market access for integrated extraction-to-detection platforms amid stricter clinical evidence requirements. |
| Cloud-Native Analysis Platform Launch | Compresses hardware-software separation and enables recurring revenue streams from machine learning-enhanced interpretation modules. |
| China NMPA GB Standard Compliance | Enables faster geographic sequencing for manufacturers with established FDA or European regulatory dossiers in tertiary hospital networks. |
| Multiplex Assay Integration Program | Creates differentiation pathways for third-party developers serving pharmaceutical quality-control and biomarker panel validation segments. |
Research Approach
Multi-period observation of instrument placement volumes, regulatory submission timelines, and reagent-instrument bundling patterns anchored the trend analysis, supplemented by interviews with molecular diagnostic laboratory directors, pharmaceutical quality-control managers, regulatory affairs specialists at notified bodies, and thermal cycler procurement officers at United States group purchasing organizations. Secondary validation drew from FDA 510(k) filings, EMA IVD guidance documents, China NMPA registration databases, and hospital capital expenditure disclosures. Bottom-up thermal cycler unit demand modeling triangulated against top-down molecular diagnostic market sizing.
Input-output matrix framing connected segmentation dimensions including product configuration, detection chemistry, end-use setting, and regional regulatory cluster to value projections across the analysis window. CAGRs were derived from fitted growth curves applied to normalized baseline data. Forecast inputs incorporated companion diagnostic mandate expansion trajectories and digital PCR technology substitution elasticities.
Several conditions sit outside the modeled scope, including unannounced regulatory guidance revisions, supply disruptions from geopolitical events affecting Japanese optical component suppliers, and breakthrough advances in next-generation sequencing cost parity. Forecasts reflect assumptions about continued reimbursement stability for molecular diagnostic testing. Deviation in FDA companion diagnostic enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Lab Automation in Bioanalysis Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Genetic Analyzer Systems Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
Cell Disruption Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Micro-Bioreactors Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Amino Acid Analyzer Market
Biotechnology Equipment
Cell Proliferation Kit Market