
 Fluorescence in-Situ Hybridization Probe Market | 2026-2036
Fluorescence in-Situ Hybridization Probe Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescence in-Situ Hybridization Probe Market Intelligence
The emergence of instrument leasing and reagent rental models is reshaping competitive positioning among diagnostic laboratories. This allows smaller labs to access high-throughput platforms without large capital outlays, expanding the user base beyond large hospitals. Thermo Fisher Scientific Inc. leverages its broad portfolio of instruments and consumables to support these flexible procurement models. F. Hoffmann-La Roche Ltd. differentiates through its focus on companion diagnostics for targeted cancer therapies, bundling probes with specific drug regimens.
Fluorescence in-situ hybridization probes consist of nucleic acid sequences, often 20-50 base pairs long, attached to fluorescent reporter molecules. These probes bind to specific DNA or RNA targets within intact cells, enabling the visualization of genetic material under a fluorescent microscope. DNA probes for cancer diagnosis applications currently constitute the largest market segment by revenue. However, RNA probes utilized in microbial detection and infectious disease research are poised for significant expansion.
The market is governed by stringent regulatory frameworks for in-vitro diagnostics. In the United States, the FDA's 510(k) clearance process applies to many clinical probes, while in Europe, compliance with the In Vitro Diagnostic Regulation (IVDR) and CE marking is mandatory. China's National Medical Products Administration (NMPA) imposes distinct approval requirements for market entry. Vendors must navigate these divergent regulatory pathways while investing in probe customization to meet specific clinical and research demands.
Market Dynamics
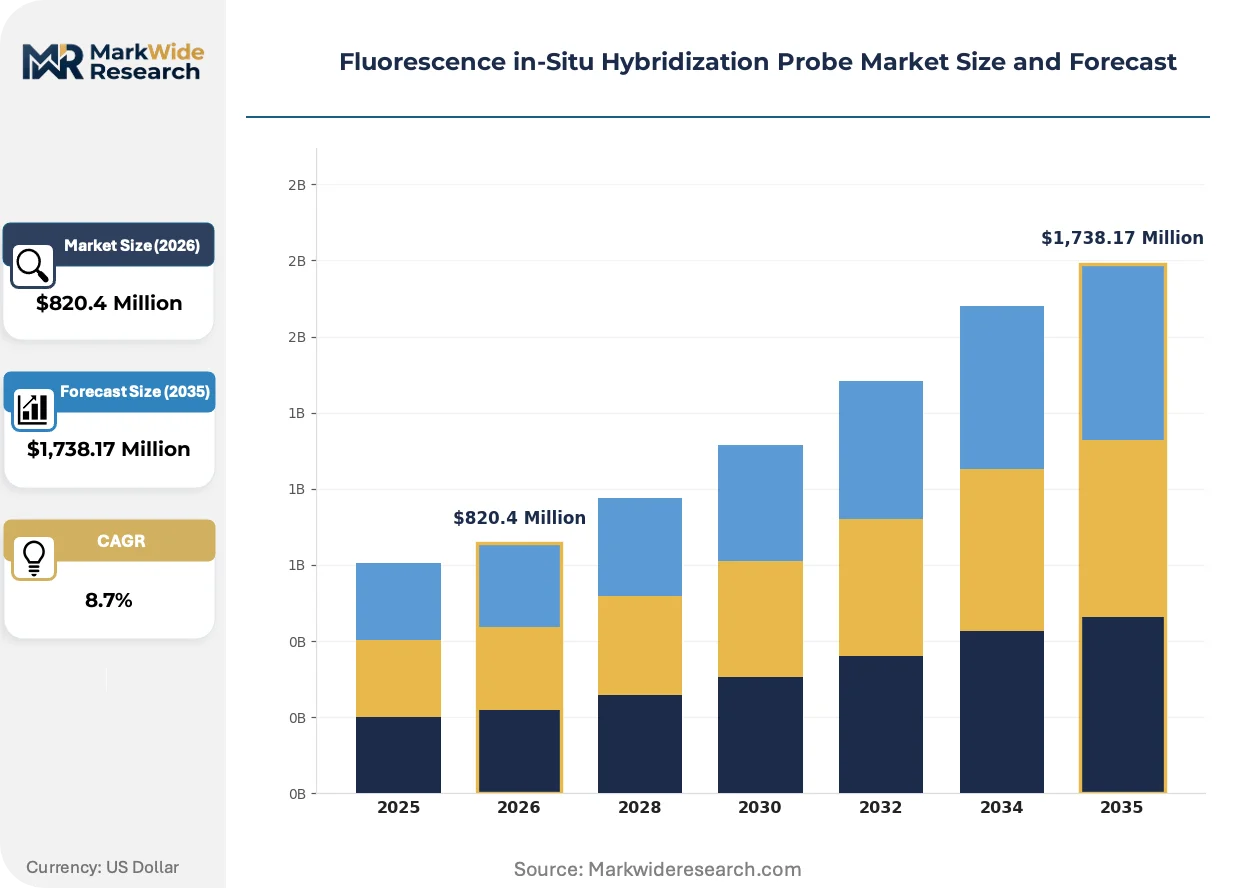
The market's central dynamic is the push toward automation and multiplexing in genetic analysis. This technological shift is expanding the clinical utility of FISH probes beyond traditional cytogenetics, enabling high-throughput screening for complex diseases and driving demand in specialized diagnostic centers.
Growth Catalysts
- Companion Diagnostics:Regulatory frameworks from the FDA and EMA are increasingly linking the approval of targeted cancer therapies to the availability of a specific companion diagnostic test, creating a direct demand pull for associated FISH probes.
- Oncology Research:The rising prevalence of solid tumors fuels research into complex genetic aberrations. This drives probe utilization in academic and pharmaceutical laboratories, particularly in research clusters within the United States and Japan.
- Advanced Fluorophores:The development of brighter and more photostable fluorescent molecules enables the creation of multiplex probe panels. This allows for the simultaneous detection of multiple genetic targets, improving diagnostic efficiency and information density.
Market Restraints
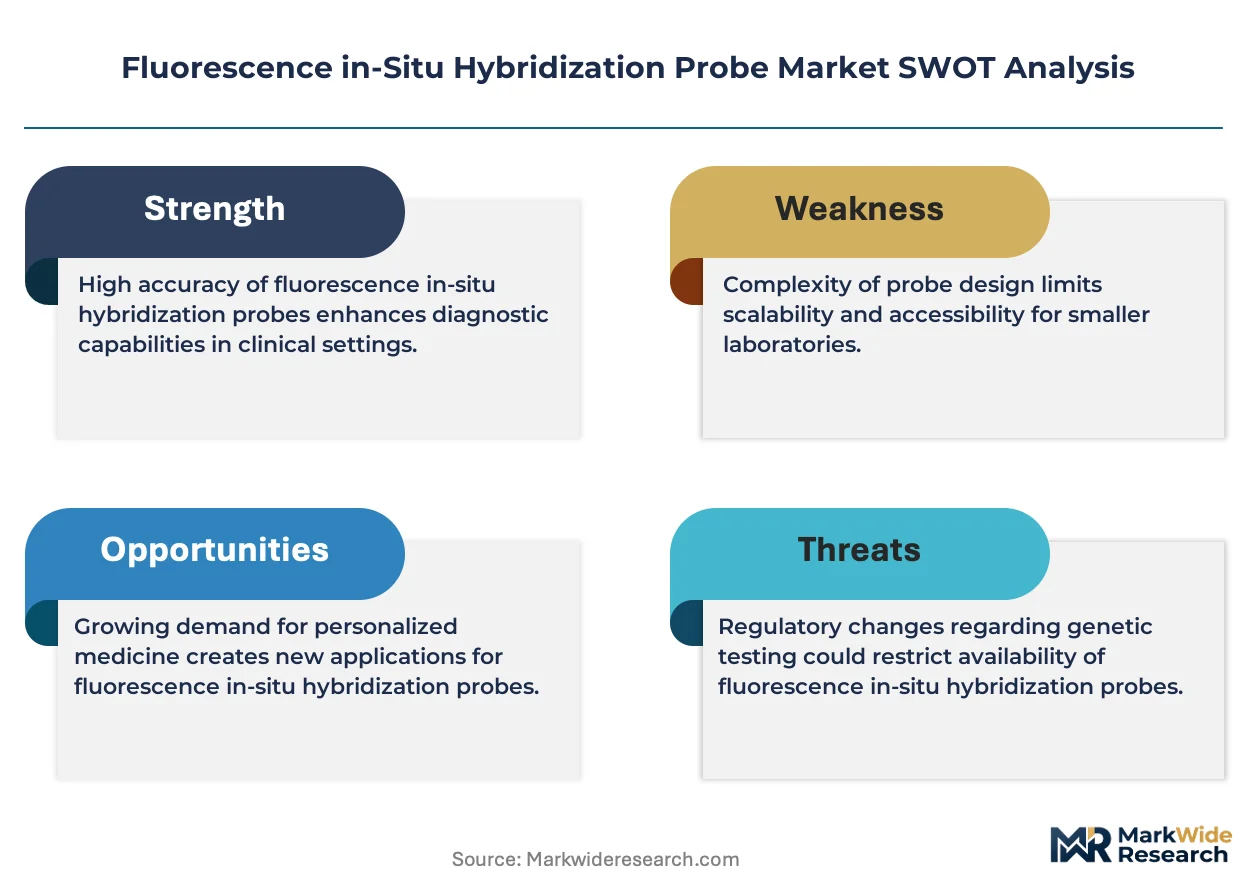
- High System Costs:The significant capital investment required for automated FISH imaging and analysis systems remains a substantial barrier to adoption for smaller laboratories and hospitals with limited budgets.
- Technical Limitations:Signal fading and background autofluorescence can complicate image analysis, especially in formalin-fixed paraffin-embedded (FFPE) tissues, requiring advanced imaging software and skilled technicians to ensure accurate interpretation.
- Probe Customization Complexity:Developing and validating custom probes for rare genetic targets or novel research applications is a time-consuming and expensive process, limiting their widespread availability beyond specialized vendors.
Strategic Opportunities
- RNA Probe Applications:The application of RNA-targeted probes for the rapid detection of infectious pathogens, such as viruses and bacteria in clinical samples, represents a significant area for market expansion beyond oncology.
- Digital Pathology Integration:Combining FISH imaging with artificial intelligence algorithms offers the potential to automate signal counting and pattern recognition, reducing interpretation time and improving diagnostic consistency across laboratories.
- Emerging Market Penetration:Increasing healthcare investments and the establishment of advanced diagnostic centers in countries like Brazil and South Korea create new geographic markets for both standard and automated FISH solutions.
Industry Challenges
- Skilled Personnel Shortage:A deficit of qualified cytogeneticists and molecular pathologists capable of accurately interpreting complex or atypical FISH signal patterns poses a significant operational bottleneck for diagnostic laboratories.
- Protocol Standardization:Variations in tissue preparation, hybridization protocols, and scoring criteria between different labs can lead to inter-laboratory discrepancies, challenging the reproducibility of results for clinical trials and routine diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescence in-Situ Hybridization Probe Market |
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $1,738.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Probe Type: DNA Probes, RNA Probes, Molecular Beacons, FISH Probes End User: Research Laboratories, Hospitals, Diagnostic Centers, Academic Institutions Technology: Fluorescent Microscopy, Next-Generation Sequencing, In Situ Sequencing, Imaging Systems Application: Genetic Testing, Cancer Diagnosis, Microbial Detection, Chromosomal Abnormality Analysis |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies, Inc., PerkinElmer Inc., Abbott Laboratories, Inc., F. Hoffmann-La Roche Ltd., QIAGEN, BioDot, Horizon Diagnostics, LGC Biosearch Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescence in-Situ Hybridization Probe Market Strategic Shifts & Innovations
Automation in sample processing and digital image analysis is transforming FISH from a specialized, manual technique into a more standardized, high-throughput diagnostic tool. This evolution is lowering barriers to entry and expanding the scope of clinical questions that can be addressed with spatial genetic analysis.
Quantum dot (QD) nanocrystals are emerging as superior alternatives to traditional organic fluorophores for probe labeling. Their exceptional brightness and resistance to photobleaching allow for more sensitive detection and robust multiplexing capabilities. Advanced oncology research centers are adopting QD-based probes to simultaneously visualize multiple gene fusions or copy number variations, and this technology is hybridizing conventional FISH with high-content imaging to extract more data from a single tissue section.
Europe's In Vitro Diagnostic Regulation (IVDR) is imposing more rigorous validation requirements on probe manufacturers. The regulation mandates stricter clinical evidence and performance evaluation, particularly for probes used in cancer diagnosis and companion diagnostics. This affects vendors selling into the EU, who must now invest heavily in updated technical files and post-market surveillance systems to maintain CE marking and market access.
A transition from direct capital equipment sales toward instrument leasing and reagent rental agreements is altering purchasing patterns. This model allows laboratories to access state-of-the-art automated FISH systems by converting large capital expenditures into predictable operational costs. The shift is most prominent in the competitive North American and European diagnostic markets, enabling smaller labs to compete with larger institutions on testing capabilities.
Fluorescence in-Situ Hybridization Probe Market Segmentation
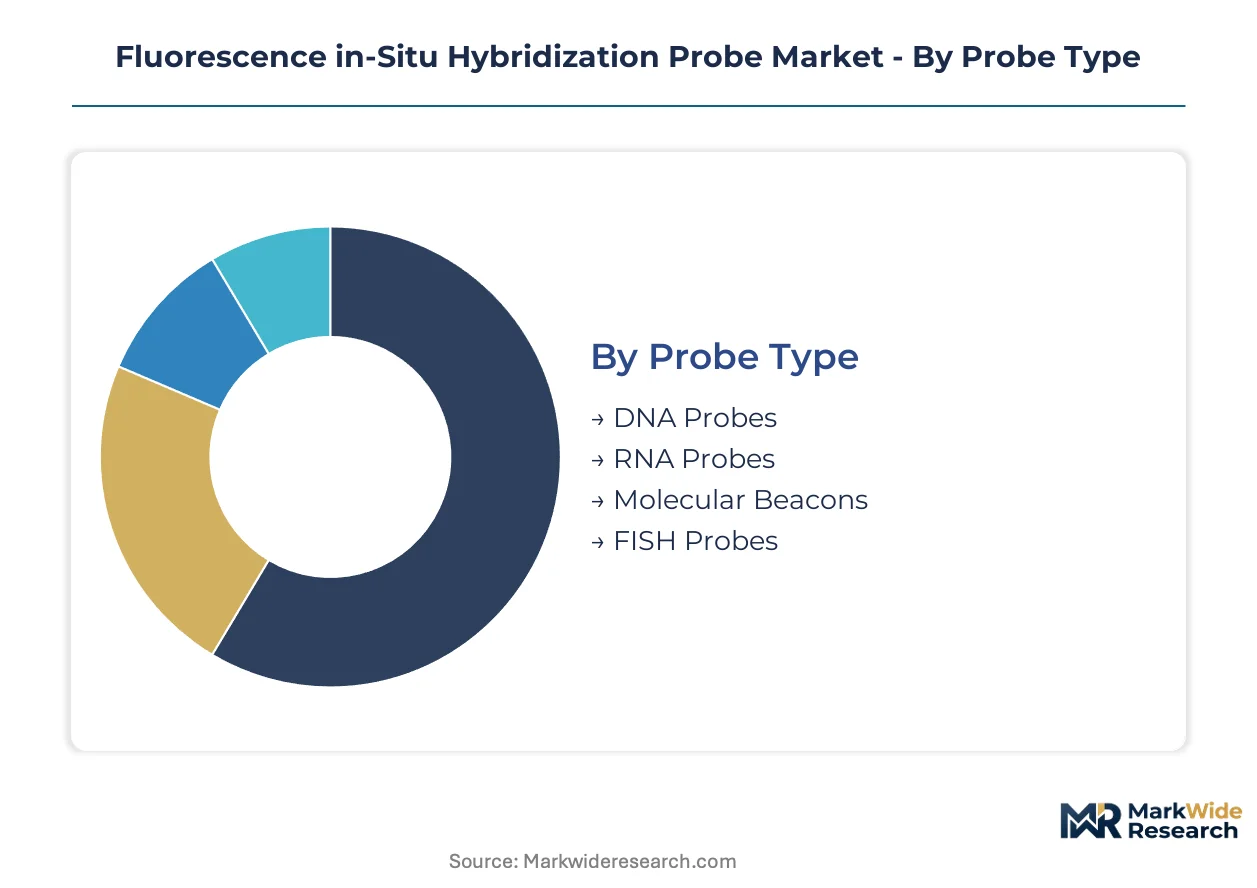
The Fluorescence in-Situ Hybridization Probe Market is dissected into distinct segments to illuminate the varied technological applications and end-user demands shaping its trajectory. Understanding these segments provides a granular view of where innovation is occurring and which areas represent significant commercial opportunities. This detailed breakdown helps stakeholders identify specific growth pockets and tailor strategic investments.
Probe Type:
The market for Fluorescence in-Situ Hybridization probes is primarily differentiated by the nucleic acid sequence and reporter molecule composition.
- DNA Probes:These probes consist of labeled DNA sequences designed to bind to specific DNA targets within chromosomes or genes. Demand for DNA probes is concentrating in cancer diagnosis, particularly for identifying solid tumor aberrations in the United States and Japan.
- RNA Probes:Composed of labeled RNA sequences, these probes target specific RNA molecules, including mRNA or ribosomal RNA, allowing for gene expression analysis or pathogen detection. RNA probes are experiencing significant expansion in microbial detection and infectious disease research across Europe.
- Molecular Beacons:These hairpin-shaped oligonucleotide probes possess a fluorophore and quencher, emitting fluorescence only upon binding to a complementary target sequence. Molecular beacons find utility in real-time PCR applications and live-cell imaging studies.
- FISH Probes:This broad category encompasses various fluorescently labeled nucleic acid sequences used to detect and localize specific DNA or RNA sequences within cells. FISH probes are fundamental tools in cytogenetics and molecular pathology laboratories.
DNA Probes hold installed capacity. RNA Probes are rotating up the share rankings.
End User:
Customer type significantly influences procurement patterns and technology adoption within the market.
- Diagnostic Centers:These specialized facilities provide clinical testing services, utilizing FISH probes for high-volume genetic analysis and disease diagnosis. Demand is concentrating in specialized diagnostic centers in Germany and the United States, seeking high-throughput automated systems.
- Research Laboratories:Academic and pharmaceutical research institutions employ FISH probes for basic science, drug discovery, and biomarker identification. Oncology research, especially in the United States and Japan, fuels probe utilization for complex genetic aberration studies.
- Hospitals:Clinical pathology and cytogenetics departments within hospitals use FISH probes for patient diagnosis, prognosis, and treatment monitoring. Hospitals are increasingly adopting FISH for companion diagnostics, driven by targeted cancer therapies.
- Academic Institutions:Universities and colleges integrate FISH technology into their research and educational programs, training future scientists and clinicians. These institutions contribute to early-stage probe development and validation.
Diagnostic Centers continue to drive immediate revenue generation. Hospitals are steadily increasing their utilization of advanced FISH techniques.
Technology:
The technological landscape defines the capabilities and efficiency of genetic analysis platforms.
- Imaging Systems:These systems include automated microscopes, digital cameras, and image analysis software designed to capture, process, and interpret fluorescent signals from FISH probes. Automated imaging systems are expanding accessibility for clinical use in diagnostic centers.
- Next-Generation Sequencing:While primarily a sequencing technology, NGS can be integrated with FISH workflows for comprehensive genetic analysis, particularly for detecting complex genomic rearrangements. NGS integration is enabling high-throughput screening for complex diseases.
- Fluorescent Microscopy:The foundational technology for visualizing FISH signals, fluorescent microscopes use specific light sources and filters to excite fluorophores and detect emitted light. This technology remains a standard in many research and clinical settings.
- In Situ Sequencing:This emerging technology enables direct sequencing of nucleic acids within intact cells or tissue sections, offering spatial resolution of genetic information. In Situ Sequencing holds promise for advanced oncology research.
Fluorescent Microscopy represents the foundational technology. Imaging Systems are expanding most quickly in clinical settings.
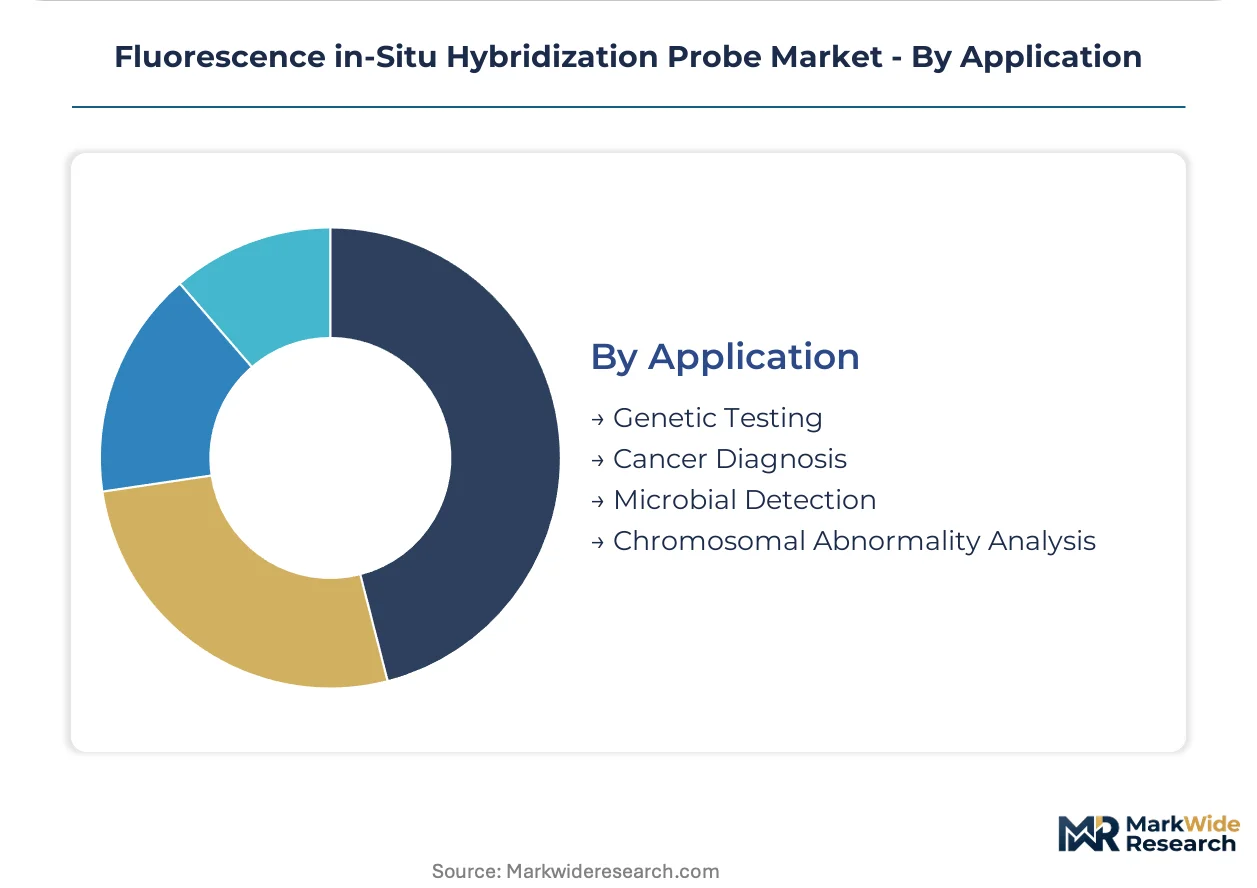
Application:
The primary use cases for FISH probes dictate specific design requirements and regulatory pathways.
- Cancer Diagnosis:FISH probes are extensively used to detect chromosomal abnormalities, gene amplifications, and translocations associated with various cancers, especially solid tumors. This application currently constitutes the largest market segment by revenue across global diagnostic centers.
- Microbial Detection:RNA-targeted probes offer rapid and specific identification of bacteria, viruses, and other pathogens directly in clinical samples. This application is poised for significant expansion, particularly in infectious disease research and diagnostics.
- Genetic Testing:This broad application involves using FISH probes to identify genetic disorders, inherited conditions, and developmental abnormalities. Genetic testing supports prenatal diagnosis and postnatal assessment in specialized clinics.
- Chromosomal Abnormality Analysis:FISH is a standard method for detecting numerical and structural chromosomal changes, such as aneuploidy, deletions, and translocations. Cytogenetics laboratories widely employ this analysis for diagnostic purposes.
Cancer Diagnosis remains the largest application by volume. Microbial Detection is climbing the fastest in terms of new research and clinical adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in specialized diagnostic centers and research laboratories drives regional demand for fluorescence in-situ hybridization probes. These facilities, particularly in developed economies, prioritize high-throughput genetic analysis and advanced diagnostic capabilities. Emerging markets also show potential as healthcare infrastructure develops.
United States
United States demand for FISH probes is strong in cancer diagnosis, particularly for solid tumors, and extensive oncology research. The FDA's 510(k) clearance process governs many clinical probes, ensuring diagnostic accuracy. Major biotech hubs like Boston-Cambridge and the San Francisco Bay Area host significant research clusters advancing probe development and application.
Germany
Germany's specialized diagnostic centers are key consumers, seeking high-throughput automated systems for genetic analysis. Compliance with the In Vitro Diagnostic Regulation (IVDR) and CE marking is mandatory for market access. Research institutions and diagnostic facilities in cities like Munich and Berlin are integrating advanced FISH technologies into routine clinical workflows.
Japan
Japanese demand centers on cancer diagnosis, especially for solid tumors, and robust oncology research into complex genetic aberrations. The Pharmaceuticals and Medical Devices Agency (PMDA) imposes specific approval requirements for in-vitro diagnostics. Research clusters in Tokyo and Kyoto contribute significantly to early-stage probe development and validation studies.
China
China's increasing healthcare investments and the establishment of advanced diagnostic centers drive new market penetration for FISH solutions. The National Medical Products Administration (NMPA) imposes distinct approval requirements for market entry. Major economic regions like the Yangtze River Delta and Pearl River Delta are seeing expansion of diagnostic services.
South Korea
South Korea exhibits rising demand due to its establishment of advanced diagnostic centers and active infectious disease research. The Ministry of Food and Drug Safety (MFDS) regulates medical devices, including FISH probes, for clinical use. The Seoul Capital Area is a hub for medical technology innovation and clinical trials, supporting market growth.
Fluorescence in-Situ Hybridization Probe Market Key Industry Players
Channel-controlling players compete with product-specialist players across the fluorescence in-situ hybridization probe market, creating a dynamic competitive environment. The market exhibits a tiered structure, with large diversified conglomerates providing comprehensive solutions alongside specialized manufacturers focusing on niche applications. Archetypes include broad-portfolio providers, targeted diagnostic developers, and emerging technology innovators. Competitive moves involve strategic partnerships for market access, continuous portfolio diversification to address evolving clinical needs, and investment in automated imaging systems.
Broad-portfolio providers like Thermo Fisher Scientific Inc. exemplify the strategy of leveraging extensive instrument and consumable offerings across diverse diagnostic workflows. F. Hoffmann-La Roche Ltd. occupies a distinct position, anchoring its competitive strategy around companion diagnostics, bundling probes with specific drug regimens for targeted cancer therapies. Companies such as QIAGEN also sit within the group of established diagnostic solution providers, offering a range of molecular testing products and expanding their global footprint. These entities often focus on integrating advanced technologies to enhance diagnostic efficiency and expand clinical utility.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies, Inc. |
| PerkinElmer Inc. |
| Abbott Laboratories, Inc. |
| F. Hoffmann-La Roche Ltd. |
| QIAGEN |
| BioDot |
| Horizon Diagnostics |
| LGC Biosearch Technologies |
Cost & Logistics Intelligence
Undercapacity in specialized probe manufacturing drives supplier behavior and influences pricing postures for custom FISH solutions. This market's pricing dynamics are closely tied to the complexity of probe design and the regulatory burden associated with clinical applications.
Pricing Analysis
Cost-plus contracts, often indexed to raw material nucleic acid synthesis costs, govern long-term supply agreements for high-volume FISH probe orders. The dominant pricing model incorporates value-based elements for highly specialized or companion diagnostic probes. Price differentiation stems from the level of customization required for rare genetic targets and the regulatory certification, such as FDA 510(k) clearance or IVDR compliance. Pricing softness emerges in commoditized, standard FISH panels due to increasing automation and competition among established providers. Academic institutions typically exhibit the highest price sensitivity, while specialized diagnostic centers prioritize diagnostic accuracy and turnaround time over marginal cost savings for critical tests.
Supply Chain Analysis
Single-source vulnerability for advanced fluorophores, particularly novel quantum dots, poses a significant structural risk across the FISH probe supply chain. Geographic supply concentration for high-purity oligonucleotide synthesis reagents resides primarily in the United States, Germany, and Japan, reflecting advanced chemical manufacturing capabilities. Key raw material dependencies include specialized fluorescent dyes, nucleic acid building blocks, and enzymes for probe labeling. Distribution runs through a dual model, with major players like Thermo Fisher Scientific Inc. utilizing direct sales channels and smaller, specialized firms relying on a network of regional distributors to reach diverse end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fluorescence in-Situ Hybridization Probe Market presents a fragmentation opportunity, driven by the demand-side shift towards highly specific companion diagnostics for targeted cancer therapies.
For Market Incumbents: Harden existing market positions by integrating AI-driven digital pathology solutions to enhance interpretation efficiency and reduce turnaround times. Deepen vertical integration into advanced fluorophore synthesis to mitigate single-source supply risks for proprietary dyes. The threat from emerging technology innovators offering novel detection methods necessitates continuous R&D investment. Leverage regulatory certification investment, particularly for IVDR compliance, to secure and expand market access across Europe.
For New Entrants and Emerging Players: Establish a beachhead in RNA probe applications for microbial detection, leveraging rapid turnaround times for infectious disease diagnostics. Target white-space opportunities within in situ sequencing for advanced oncology research, offering spatial genetic insights. The most penetrable segment for new players remains custom probe development for niche or rare genetic targets. A focused go-to-market angle emphasizing superior signal-to-noise ratios and multiplexing capabilities can differentiate offerings.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated FISH imaging systems, reflecting the need for significant investment in high-throughput platforms. The market exhibits strong long-term viability, driven by the expanding landscape of precision medicine and personalized diagnostics over the next decade. Target acquisition archetypes include specialized software developers for AI-powered image analysis or manufacturers of novel, photostable fluorophores. Increasing regulatory approvals for companion diagnostics serves as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Partner with pharmaceutical companies to co-develop companion diagnostics for novel targeted therapies. |
| Regulatory Approval Pathway | Accelerate FDA 510(k) and IVDR compliance for new probe panels, ensuring broad market access. |
| Manufacturing Scale-Up | Invest in automated oligonucleotide synthesis to reduce production costs for high-volume standard probes. |
| Software Companion Development | Integrate AI algorithms with imaging systems to automate FISH signal interpretation for diagnostic centers. |
| Geographic Expansion | Target advanced diagnostic centers in emerging markets like China and South Korea for automated solutions. |
Research Approach
Operator-level perspectives from cytogeneticists, molecular pathologists, and diagnostic lab directors anchored the qualitative base for this analysis. This primary research involved in-depth interviews with industry stakeholders, validated through extensive secondary research. Secondary data sources included FDA 510(k) clearance records, EMA IVDR compliance documents, NMPA approval databases, and peer-reviewed academic publications. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Scenario-bracketing across conservative and optimistic growth trajectories defined the quantitative forecast model. This analysis integrated a robust analytical framework across the analysis window, segmenting the market by probe type, end-user, underlying technology, and application area. Further segmentation occurred by regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected market dynamics, with key inputs including global cancer incidence rates and the pipeline of targeted cancer therapies requiring companion diagnostics.
Stress conditions across probe development costs and regulatory approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technological advancements and clinical adoption rates. Unforeseen shifts in regulatory frameworks, particularly for in-vitro diagnostics, or accelerated adoption of alternative genetic analysis techniques could revise projections. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Proteomics Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Northern Blotting Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Global Organoids Market
Biomedical Technology
Human Reproductive Technologies Market
Biomedical Technology
Oligonucleotide Synthesis Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Exosomes Market