
 Clarithromycin Market | 2026-2036
Clarithromycin Market Size, Share, and Industry Trends Forecast 2026-2036
Clarithromycin Market Analytics
Azithromycin substitution pressure is realigning clarithromycin economics in community-acquired pneumonia protocols, particularly where atypical coverage remains essential. Teva Pharmaceutical Industries leverages its generic macrolide portfolio to sustain hospital formulary positioning across North American and European markets. Sun Pharmaceutical Industries anchors its competitive stance through backward integration into API production, controlling cost structures for emerging market tenders. Abbott Laboratories differentiates via established brand recognition in pediatric oral suspension segments where prescriber familiarity drives repeat purchasing.
Clarithromycin is a semisynthetic 14-membered ring macrolide antibiotic derived from erythromycin, formulated as the 6-O-methyl derivative with enhanced acid stability and improved oral bioavailability approaching approximately 55 percent; it functions by binding to the 50S ribosomal subunit to inhibit bacterial protein synthesis, primarily serving respiratory, skin, and Helicobacter pylori eradication therapies. Tablets dominate volume due to manufacturing scale and stability advantages in long-dated hospital contracts, while oral suspension captures margin concentration in pediatric and geriatric populations where swallowing difficulties limit solid-dose adoption. Injectable formulations occupy a narrower but strategically defended niche in severe nosocomial infections where enteral absorption is compromised.
FDA bioequivalence standards and WHO prequalification requirements shape generic entry timelines and API sourcing decisions for clarithromycin manufacturers targeting regulated markets. India's CDSCO and China's NMPA enforce evolving impurity profiling protocols that filter substandard suppliers from export eligibility. EMA pharmacovigilance frameworks for QT prolongation risk are tightening label requirements and prescriber education obligations across European markets. Stakeholders must monitor regulatory divergence between stringent and emerging markets to optimize portfolio allocation and manufacturing site qualification strategies.
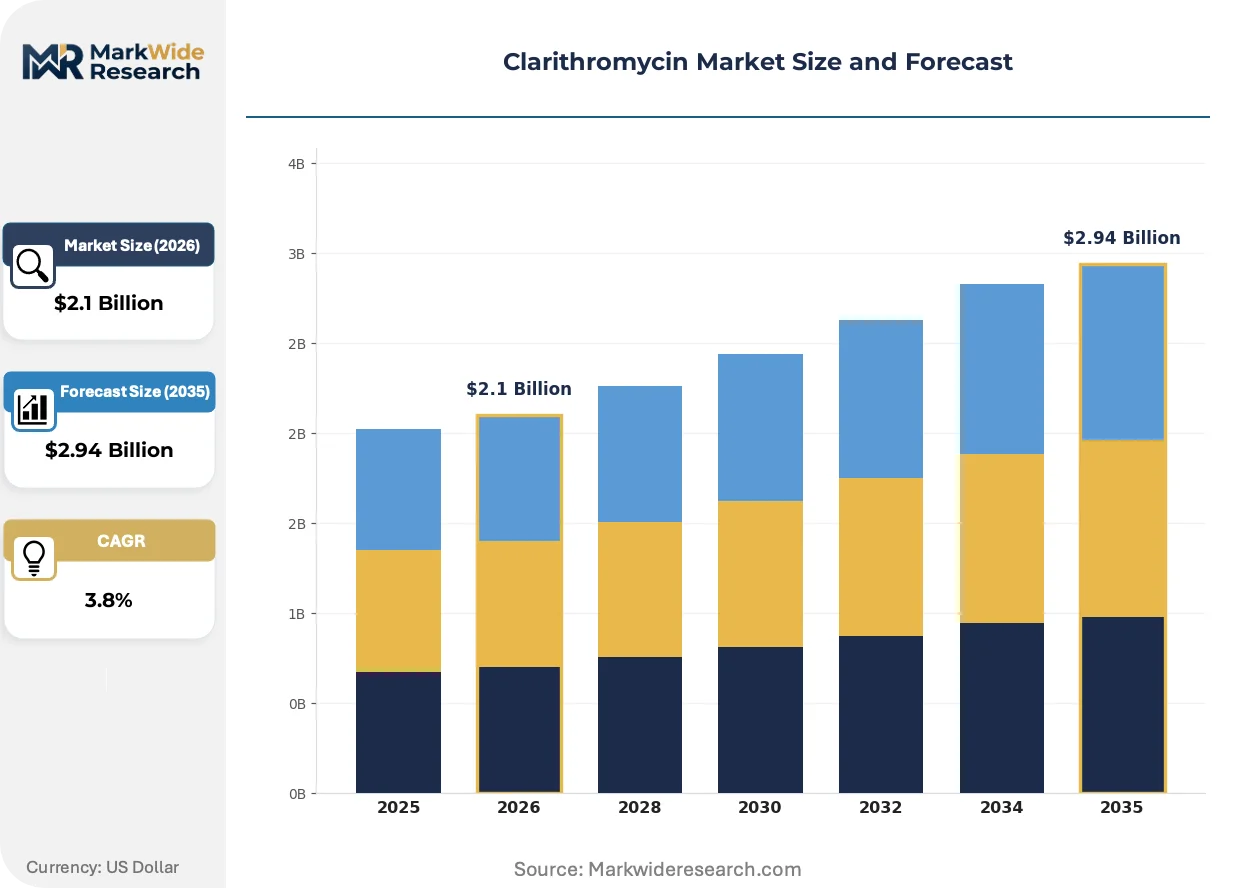
Market Dynamics
Azithromycin substitution pressure is compressing clarithromycin utilization in community-acquired pneumonia protocols, forcing manufacturers to defend positioning through atypical coverage differentiation and pediatric formulation specialization.
Growth Catalysts
- WHO Essential Medicines List inclusion:The WHO designation sustains institutional procurement volumes across public health systems and humanitarian supply chains, insulating demand from commercial volatility.
- Pediatric respiratory protocol evolution:Hospital formulary expansion of oral suspension formulations is creating volume concentration in acute care settings where swallowing difficulties limit tablet adoption.
- India API-to-formulation integration:Domestic manufacturers serving both regulated and emerging markets are compressing cost structures and accelerating tender responsiveness.
Market Restraints
- Azithromycin substitution economics:The broader-spectrum macrolide is capturing share in outpatient respiratory infections where atypical coverage is non-essential, eroding clarithromycin volume in primary care.
- QT prolongation pharmacovigilance:EMA tightening of label requirements and prescriber education obligations is constraining utilization in cardiac-risk populations.
- API sourcing concentration:Quality benchmarking under FDA bioequivalence standards and WHO prequalification is filtering substandard suppliers and lengthening qualification timelines.
Strategic Opportunities
- Helicobacter pylori eradication protocols:Triple-therapy regimens incorporating clarithromycin retain guideline endorsement in regions where metronidazole resistance is prevalent, sustaining demand in gastroenterology.
- CDSCO impurity profiling evolution:India's tightening export eligibility standards are creating competitive moats for compliant manufacturers against non-qualified rivals.
- Geriatric swallowing difficulty segments:Oral suspension formulations are capturing margin concentration in aging populations where solid-dose adherence fails.
Industry Challenges
- Bioequivalence study execution:FDA requirements for generic macrolide approval demand specialized clinical pharmacology expertise that contract research organizations struggle to staff.
- Manufacturing site qualification:Divergent regulatory standards between stringent and emerging markets force parallel validation investments that strain mid-cap API producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clarithromycin Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Oral Suspension, Injectable Therapy Area: Respiratory Infections, Skin Infections, Gastrointestinal Infections, Ear Infections End User: Hospitals, Clinics, Retail Pharmacies, Online Pharmacies Distribution Channel: Direct Sales, Wholesalers, Online Retail, Pharmacies |
| Companies Covered | Abbott Laboratories, Abbvie, Teva Pharmaceutical Industries, Sandoz, Mylan, Sun Pharmaceutical Industries, Takeda Pharmaceuticals, Aurobindo Pharma, Cipla Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clarithromycin Market Evolving Landscape
Formulation technology advances and regulatory quality escalation are reshaping competitive differentiation in macrolide antibiotics, with acid-stable derivatives and impurity-controlled synthesis commanding procurement preference.
Extended-release clarithromycin formulations are overtaking immediate-release tablets in hospital contracting where dosing compliance and reduced pill burden drive formulary decisions. Large health systems in North America are consolidating purchases around modified-release technologies that simplify nursing protocols. This shift is compressing margins for legacy tablet manufacturers unable to demonstrate bioequivalence equivalence.
REACH-aligned impurity profiling is tightening API sourcing standards for European market entry, with ECHA substance of very high concern designations extending to residual solvent categories. Manufacturers are reconfiguring synthesis routes to eliminate dichloromethane and toluene carryover. Generic filers targeting EMA centralized procedures are prioritizing green chemistry certifications in supplier qualification.
Hospital procurement consolidation is fragmenting distributor influence as pharmacy and therapeutics committees centralize macrolide selection authority. Regional buying cooperatives are displacing wholesaler-mediated contracting in the United States, compressing rebate capture for non-preferred manufacturers. This concentration is most visible in integrated delivery networks where formulary standardization across 50-plus facility footprints eliminates local physician preference variation.
Clarithromycin Market Segmentation
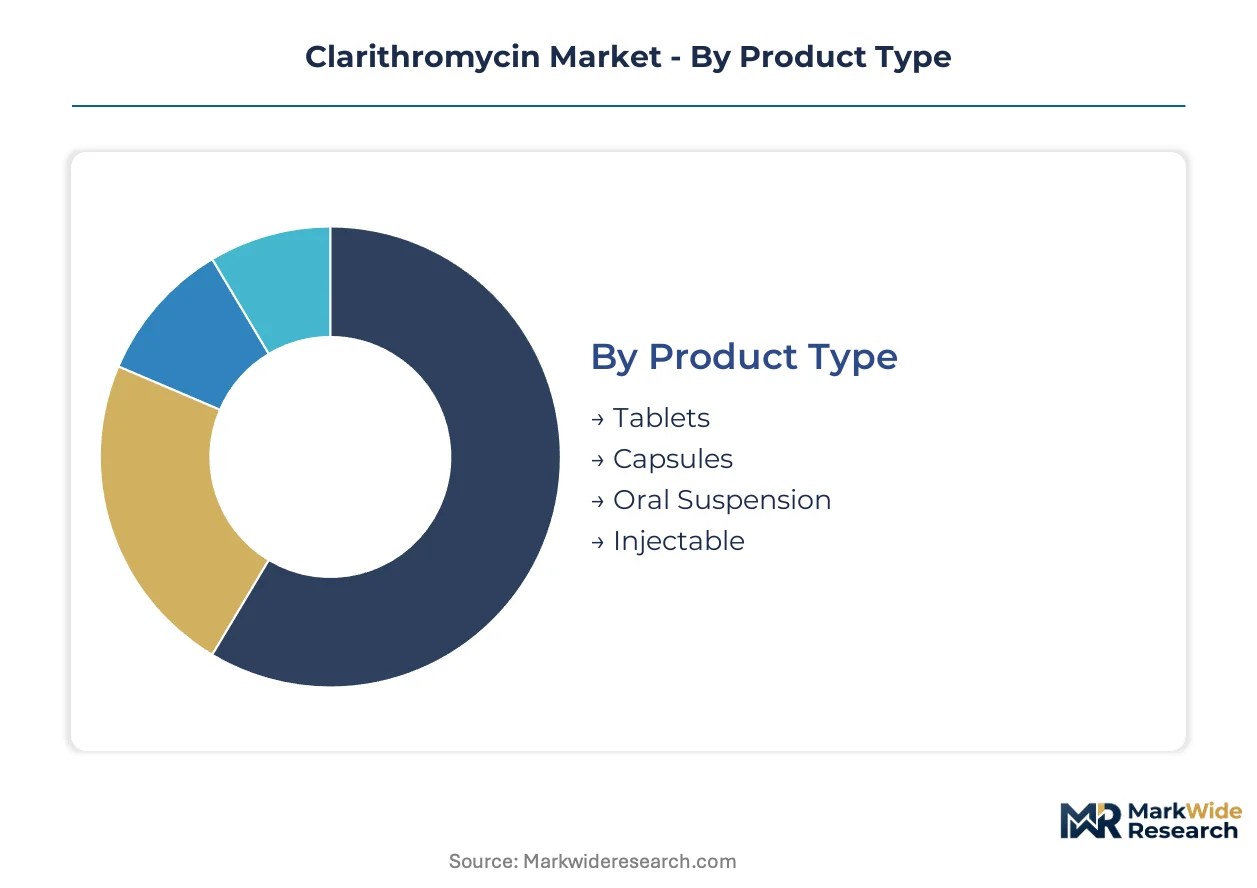
Clarithromycin demand fragments across formulation technologies, therapeutic applications, and procurement channels that each impose distinct manufacturing and regulatory requirements. Manufacturers must align production capabilities with the specific stability, bioavailability, and distribution constraints governing each segment.
Product Type:
Formulation chemistry dictates acid stability, dosing convenience, and manufacturing capital intensity across the clarithromycin portfolio.
- Tablets:Immediate-release and extended-release solid-dose formulations leverage mature compression technology and long-dated stability profiles that satisfy hospital contracting requirements. North American integrated delivery networks concentrate procurement around modified-release tablets where reduced pill burden drives formulary compliance.
- Oral Suspension:Pediatric and geriatric populations with swallowing difficulties generate concentrated demand for reconstitutable powder formulations where prescriber familiarity with specific brands influences repeat purchasing. Hospital pediatric protocols are expanding volume concentration in acute care settings.
- Capsules:Gelatin-encapsulated clarithromycin offers intermediate positioning between tablet convenience and suspension flexibility for adult populations with mild dysphagia.
- Injectable:Lyophilized powder for intravenous administration serves severe nosocomial infections where enteral absorption is compromised, occupying a narrow but strategically defended niche in intensive care.
Tablets lead on scale; oral suspension leads on momentum.
Therapy Area:
Clinical guideline positioning and resistance patterns determine regional demand concentration across infectious disease categories.
- Respiratory Infections:Community-acquired pneumonia and atypical pathogen coverage sustain clarithromycin utilization where azithromycin substitution pressure remains incomplete. European hospital protocols retain macrolide positioning for Legionella and Mycoplasma coverage.
- Gastrointestinal Infections:Helicobacter pylori eradication regimens incorporating clarithromycin retain endorsement in regions where metronidazole resistance is prevalent, particularly in Asia-Pacific gastroenterology practice.
- Skin Infections:Erythromycin-susceptible Staphylococcus and Streptococcus coverage supports outpatient dermatology prescribing where penicillin allergy limits beta-lactam alternatives.
- Ear Infections:Pediatric otitis media protocols in primary care settings generate seasonal demand fluctuation tied to respiratory virus circulation patterns.
Respiratory applications anchor volume; gastrointestinal indications are climbing the fastest.
End User:
Procurement authority and reimbursement pathways fragment clarithromycin demand across institutional and retail settings.
- Hospitals:Pharmacy and therapeutics committees centralize macrolide selection authority, with formulary standardization across multi-facility networks eliminating local physician preference variation. Regional buying cooperatives in the United States displace wholesaler-mediated contracting.
- Retail Pharmacies:Community dispensing captures outpatient respiratory and skin infection volume where generic substitution economics dominate purchasing decisions.
- Clinics:Urgent care and primary care settings generate concentrated pediatric respiratory demand tied to seasonal acute illness patterns.
- Online Pharmacies:Direct-to-patient distribution channels are gaining share in chronic H. pylori therapy refill compliance and geographic access extension.
Hospitals command procurement scale; online pharmacies are gaining share fastest.
Distribution Channel:
Channel economics and regulatory compliance requirements shape manufacturer route-to-market investments.
- Direct Sales:Manufacturer-contracted hospital supply agreements capture large-volume institutional procurement with price transparency and rebate structures that compress distributor margins.
- Wholesalers:Three-step distribution retains relevance in fragmented retail pharmacy markets where inventory consolidation and credit extension remain valued.
- Pharmacies:Brick-and-mortar dispensing maintains dominant outpatient volume capture, particularly for acute infection therapies requiring same-day initiation.
- Online Retail:E-commerce platforms are expanding geographic reach for maintenance therapies and reorder convenience in chronic eradication protocols.
Direct sales lead on contract value; online retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors API-to-formulation manufacturing for clarithromycin, with Indian producers supplying regulated and emerging markets through integrated production corridors. FDA bioequivalence requirements and WHO prequalification standards filter supplier eligibility across export destinations. Regulatory divergence between stringent and emerging markets shapes site qualification investments and portfolio allocation decisions.
United States
Hospital procurement consolidation through integrated delivery networks concentrates macrolide purchasing authority, with pharmacy and therapeutics committees standardizing formulary selection across multi-facility footprints. FDA bioequivalence requirements for generic clarithromycin approval demand specialized clinical pharmacology expertise that contract research organizations struggle to staff. New Jersey-based Teva Pharmaceutical Industries leverages its generic macrolide portfolio to sustain hospital formulary positioning.
Germany
EMA pharmacovigilance frameworks for QT prolongation risk tighten label requirements and prescriber education obligations, constraining utilization in cardiac-risk populations. REACH-aligned impurity profiling under ECHA standards filters API sourcing for European market entry, with residual solvent designations extending to dichloromethane and toluene categories. Baden-Württemberg chemical clusters reconfigure synthesis routes to eliminate solvent carryover and secure green chemistry certifications.
India
Domestic API-to-formulation manufacturers compress cost structures and accelerate tender responsiveness for both regulated and emerging markets. CDSCO impurity profiling evolution tightens export eligibility standards, creating competitive moats for compliant manufacturers against non-qualified rivals. Maharashtra-based Sun Pharmaceutical Industries anchors competitive positioning through backward integration into API production, controlling cost structures for emerging market tenders.
China
NMPA enforcement of evolving impurity profiling protocols filters substandard suppliers from export eligibility, lengthening qualification timelines for API producers. Dual carbon goals drive green chemistry investments in macrolide synthesis, with manufacturers eliminating high-residual solvent processes. Zhejiang and Jiangsu pharmaceutical clusters concentrate clarithromycin API production for domestic formulation and regulated market export.
Japan
PMDA quality benchmarks for generic macrolide approval sustain high-barrier market entry, with bioequivalence studies demanding specialized expertise. METI industrial policy supports domestic pharmaceutical manufacturing resilience, with clarithromycin retained in respiratory and H. pylori eradication protocols. Osaka-Kobe pharmaceutical corridor maintains formulation capabilities for hospital and retail distribution channels.
Clarithromycin Market Competitive Landscape
Global majors compete with regional champions across API sourcing and formulation specialization, producing a tiered structure where scale-driven players defend hospital contracts while integrated specialists capture emerging market tenders. The vendor base fragments across backward-integrated Indian producers, North American generic portfolio holders, and European quality-focused manufacturers. Three archetypes dominate: API-integrated cost leaders, brand-recognition pediatric specialists, and hospital formulary incumbents. Capacity expansion and green chemistry certification represent the dominant competitive moves as regulatory quality barriers escalate.
Among North American portfolio holders, Abbott Laboratories exemplifies brand-recognition positioning in pediatric oral suspension segments where prescriber familiarity drives repeat purchasing. Israeli-based Teva Pharmaceutical Industries and Indian-based Sun Pharmaceutical Industries occupy distinct archetype positions—Teva as hospital formulary incumbent across North American and European markets, Sun as API-integrated cost leader serving regulated and emerging market tenders. These three companies represent the competitive spectrum without exhausting the participant base.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Abbvie |
| Teva Pharmaceutical Industries |
| Sandoz |
| Mylan |
| Sun Pharmaceutical Industries |
| Takeda Pharmaceuticals |
| Aurobindo Pharma |
| Cipla Ltd |
| Others |
Value Network & Pricing Analysis
Extended-release formulation technology migration is simultaneously elevating manufacturing capital requirements and concentrating procurement leverage among integrated delivery networks capable of absorbing volume commitments. This dual shift compresses margin structures for legacy tablet producers while rewarding API-to-formulation manufacturers with cost control depth.
Pricing Analysis
Input-cost pass-through from erythromycin-derived intermediates and residual solvent compliance investments flows into contract-based long-term offtake structures dominating hospital procurement. Price differentiation hinges on FDA bioequivalence tier certification and backward integration depth, with generic filers facing acute pressure from azithromycin substitution economics. Cost compression in immediate-release tablets is intensifying because integrated delivery networks consolidate purchasing authority. Retail pharmacy buyers exhibit highest price sensitivity; pediatric oral suspension segments show lowest sensitivity due to prescriber brand loyalty.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled macrolide batches remain minimal given long-dated stability profiles, though REACH-aligned solvent recovery mandates in Europe are creating refurbishment economics for dichloromethane-laden waste streams. API production concentrates in India, China, and Italy, with formulation finishing distributed across regional hubs. Synthesis routes draw from erythromycin base, methylating agents, and specialized fermentation feedstocks. Single-source vulnerability around Zhejiang and Jiangsu pharmaceutical clusters poses structural risk. Distribution runs through direct manufacturer-hospital contracts in North America, displacing traditional wholesaler mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clarithromycin manufacturing economics favor geographic arbitrage between India's CDSCO-compliant export corridors and Europe's REACH-regulated formulation finishing, exploiting cost differentials in impurity profiling and green chemistry certification.
For Market Incumbents: Deepen backward integration into fermentation-derived erythromycin base production to defend margin position against Sun Pharmaceutical Industries' cost leadership. Secure EMA centralized procedure approvals before REACH solvent restrictions tighten further. Prioritize extended-release bioequivalence dossiers to capture integrated delivery network formulary slots.
For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the lowest-friction route to bypass entrenched wholesaler relationships. Target geriatric swallowing difficulty segments in Japan and Germany where oral suspension penetration lags pediatric benchmarks. Pursue WHO prequalification status to unlock humanitarian supply chain access.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Indian API producers facing CDSCO impurity profiling compliance costs. Long-term viability rests on clarithromycin's retention in H. pylori eradication protocols against rising metronidazole resistance. Monitor azithromycin susceptibility surveillance data for inflection signals on macrolide substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Chemistry Certification | ECHA REACH compliance secures European API sourcing eligibility against solvent-restricted rivals. |
| Extended-Release Bioequivalence Dossier | FDA approval unlocks integrated delivery network contracting where pill burden drives formulary decisions. |
| Backward Integration into Fermentation | Captive erythromycin base production insulates margin from intermediate price volatility. |
| WHO Prequalification Pathway | Humanitarian procurement eligibility sustains volume through institutional purchasing cycles. |
| Pediatric Formulation Specialization | Oral suspension brand loyalty defends pricing power against generic tablet substitution. |
Research Methodology
Direct dialogue with regulatory affairs leads, hospital formulary directors, API procurement managers, and contract research organization executives grounded qualitative insights in operational reality. Secondary validation drew from FDA ANDA filings, EMA centralized procedure assessments, CDSCO export notifications, and WHO prequalification records. Bottom-up demand modeling triangulated against top-down therapeutic protocol analysis.
Bottom-up volume estimates by dosage form, therapy area, and procurement channel converged with top-down therapeutic guideline adoption trajectories across the projection horizon. Segmentation dimensions included formulation technology, administration route, patient population age bracket, and regional regulatory cluster. CAGRs derived from protocol evolution rates, resistance pattern surveillance, and tender award velocity. Forecast inputs incorporated azithromycin substitution elasticity and CDSCO impurity profiling enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for extended-release formulation dominance would alter the outlook if immediate-release tablets retain hospital preference. Forecasts reflect assumptions on regulatory divergence persistence and macrolide resistance surveillance continuity. Practitioners should monitor EMA pharmacovigilance bulletins and Indian export inspection rejection rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
AI in Pharma and Biotech Market
Medical Biotechnology
Isogenic Cell Lines Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Crude Heparin Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Glioblastoma Multiforme (GBM) Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Anti-Cathepsin B Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market