
 Global Antisense and Rnai Therapeutics Market | 2026-2036
Global Antisense and Rnai Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antisense and Rnai Therapeutics Market Foresight
A specialized nucleic acid chemist workforce shortage is reorganizing how drug developers allocate manufacturing capacity across North America and Europe. Alnylam Pharmaceuticals leverages its integrated rare disease commercial infrastructure to sustain first-mover advantages in ATTR amyloidosis. Ionis Pharmaceuticals anchors its position through broad neurology partnerships and royalty-bearing licensing structures. Arrowhead Pharmaceuticals competes via targeted RNAi triggers against liver-expressed genes, differentiating its platform through endogenous gene silencing mechanisms.
Antisense and RNAi therapeutics comprise synthetic oligonucleotide or double-stranded RNA molecules designed to bind complementary messenger RNA sequences, triggering degradation or translational blockade through RNase H recruitment or RISC-mediated cleavage. These modalities address previously undruggable targets by intervening at the post-transcriptional level, with chemical modifications such as phosphorothioate backbones and 2'-O-methoxyethyl ribose enhancing metabolic stability and reducing immunostimulatory effects. Small interfering RNA commands the largest value share as approved therapies for hereditary transthyretin amyloidosis and primary hyperoxaluria validate commercial scalability. Lipid nanoparticle delivery dominates current revenue generation, though conjugated ligand platforms targeting hepatocyte asialoglycoprotein receptors represent the fastest-expanding technology segment due to simplified manufacturing and reduced dosing frequency.
FDA, EMA, and PMDA frameworks govern oligonucleotide approval pathways, with each regulator applying distinct benefit-risk thresholds for first-in-class genetic medicines that shape trial design and label expansion strategies. ISO 13485 and ICH Q5A standards further constrain contract manufacturing organization selection, filtering participants by viral safety testing and continuous process verification capabilities. Stakeholders must monitor how regulator convergence on long-term follow-up requirements for gene-silencing therapies reshapes post-market commitment burdens and portfolio prioritization timelines.
Market Dynamics
Specialized nucleic acid chemist scarcity is compressing manufacturing capacity allocation timelines and forcing developers to restructure their North American and European production footprints.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses development timelines for genetic medicines by enabling surrogate endpoint-based submissions. Developers targeting hereditary transthyretin amyloidosis leverage this mechanism to reach patients faster.
- Lipid Nanoparticle Scale-Up:Manufacturing advances in encapsulation chemistry reduce batch-to-batch variability. Contract manufacturing organizations with ISO 13485 certification capture expanded outsourcing demand from mid-stage biopharmaceutical firms.
- Japan's PMDA Adaptive Licensing:The framework permits conditional market entry based on early-phase efficacy signals. Japanese developers of primary hyperoxaluria therapies utilize this structure to generate real-world evidence while commercializing.
Market Restraints
- Phosphoramidite Supply Concentration:Raw material synthesis for oligonucleotide backbones depends on a limited supplier base concentrated in Germany and Switzerland. Price volatility in specialty reagents squeezes gross margins for emerging platform companies.
- RNase H Mechanism Limitations:Antisense oligonucleotides require nuclear delivery for pre-mRNA targeting, restricting addressable transcript populations. Cytoplasmic mRNA remains inaccessible to this modality without conjugation modifications.
- EMA Long-Term Follow-Up Mandates:Post-market surveillance requirements for gene-silencing therapies extend fifteen to twenty years. These commitment burdens deter portfolio prioritization for indications with limited patient populations.
Strategic Opportunities
- Central Nervous System Delivery:Conjugated ligand platforms targeting transferrin receptors enable blood-brain barrier penetration. Developers in the United States are advancing clinical candidates for Huntington's disease and Alzheimer's disease using this approach.
- India's CDSCO Streamlined Pathways:The regulator's emerging framework for orphan genetic medicines offers abbreviated review timelines. Local partnerships with contract research organizations reduce trial costs for hepatocyte-targeted RNAi triggers.
- Continuous Manufacturing Integration:Flow chemistry for oligonucleotide synthesis converges with real-time quality analytics. This technology pairing reduces facility footprint requirements and enables distributed production models.
Industry Challenges
- Nucleic Acid Chemist Talent Gap:Phosphorothioate stereochemistry optimization and 2'-modification pattern design require specialized expertise unavailable in standard medicinal chemistry training programs. Recruitment competition intensifies between Boston and Basel clusters.
- Viral Safety Validation Burden:ICH Q5A compliance for contract manufacturing organization selection demands extensive documentation of raw material sourcing and in-process testing protocols. Facility qualification timelines extend twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antisense and Rnai Therapeutics Market |
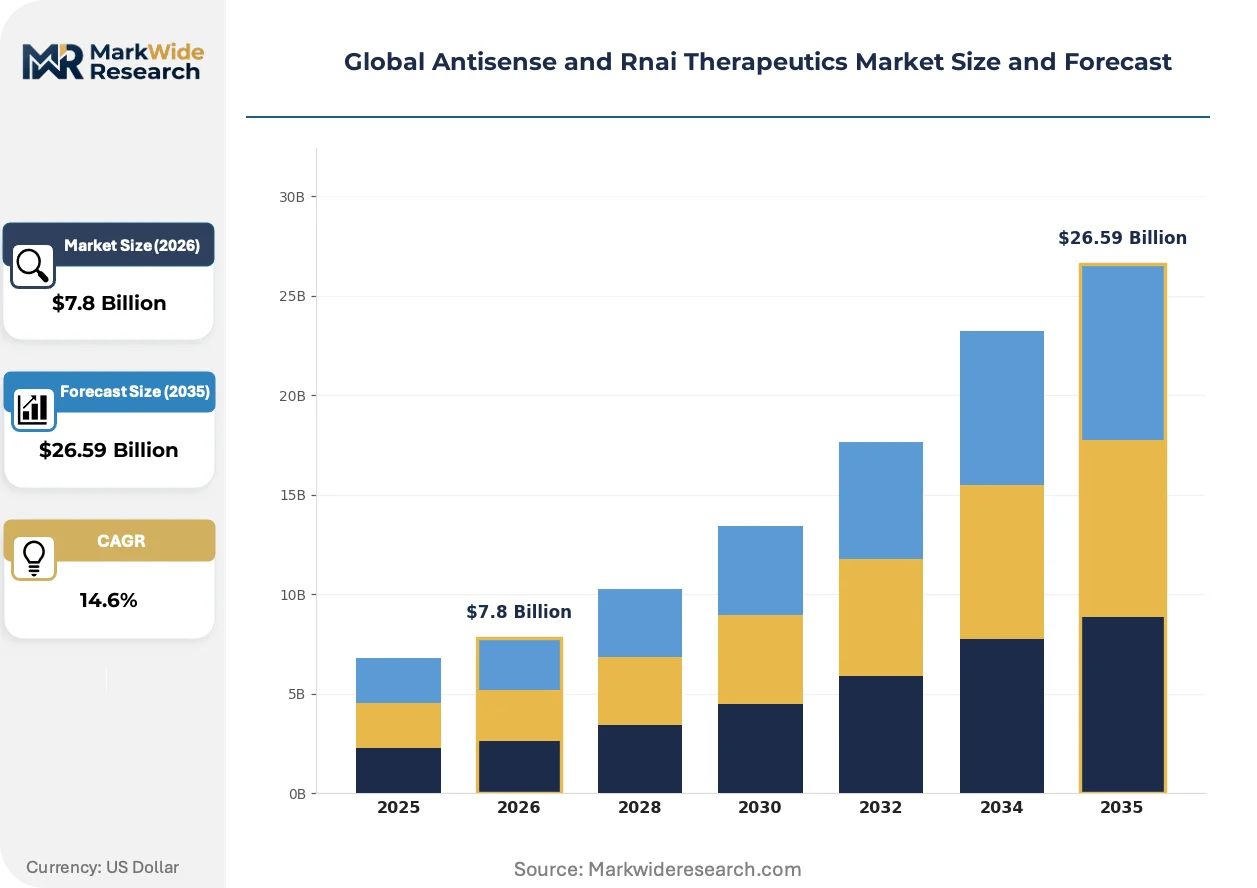
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $26.59 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antisense Oligonucleotides, Small Interfering RNA, MicroRNA, Short Hairpin RNA, Aptamers Therapy Area: Genetic Disorders, Neurological Conditions, Infectious Diseases, Metabolic Disorders, Rare Diseases End User: Research Laboratories, Biopharmaceutical Companies, Academic Institutions, Contract Research Organizations Delivery Mode: Lipid Nanoparticles, Viral Vectors, Conjugated Ligands, Electrical Methods, Polymer-based Systems |
| Companies Covered | Alnylam Pharmaceuticals, Ionis Pharmaceuticals, Arrowhead Pharmaceuticals, Sarepta Therapeutics, Silence Therapeutics, Arbutus Biopharma, Wave Life Sciences, Dicerna Pharmaceuticals, Sirnaomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antisense and Rnai Therapeutics Market Shifts & Advancements
GalNAc conjugation chemistry is displacing lipid nanoparticle systems as the dominant liver-targeting modality, reshaping platform economics and manufacturing infrastructure investments across the sector.
GalNAc-siRNA conjugates bind hepatocyte asialoglycoprotein receptors with high affinity, enabling subcutaneous dosing at milligram quantities rather than intravenous infusion of lipid nanoparticle formulations. Biopharmaceutical developers in the United States and Germany are advancing second-generation candidates using this architecture, attracted by simplified supply chains and reduced cold-chain dependencies. This chemistry is displacing earlier delivery technologies from the hereditary transthyretin amyloidosis treatment paradigm and compressing competitive timelines for follow-on indications.
EMA's adaptive licensing framework for advanced therapy medicinal products permits iterative label expansion based on accumulating safety data. The mechanism reduces regulatory risk for first-in-class genetic medicines by enabling commercial revenue generation during confirmatory trial execution. Developers targeting rare metabolic disorders in European markets utilize this pathway to accelerate patient access while satisfying post-authorization evidence requirements.
Hospital procurement committees in Japan and Germany now require health technology assessment submissions prior to formulary inclusion for novel oligonucleotide therapies. This behavioral shift elevates real-world evidence generation to a pre-launch priority, displacing traditional key opinion leader engagement as the primary access lever. Manufacturers respond by embedding patient registry infrastructure into phase three trial designs, particularly for chronic dosing indications in amyloidosis and hyperoxaluria.
Global Antisense and Rnai Therapeutics Market Segmentation
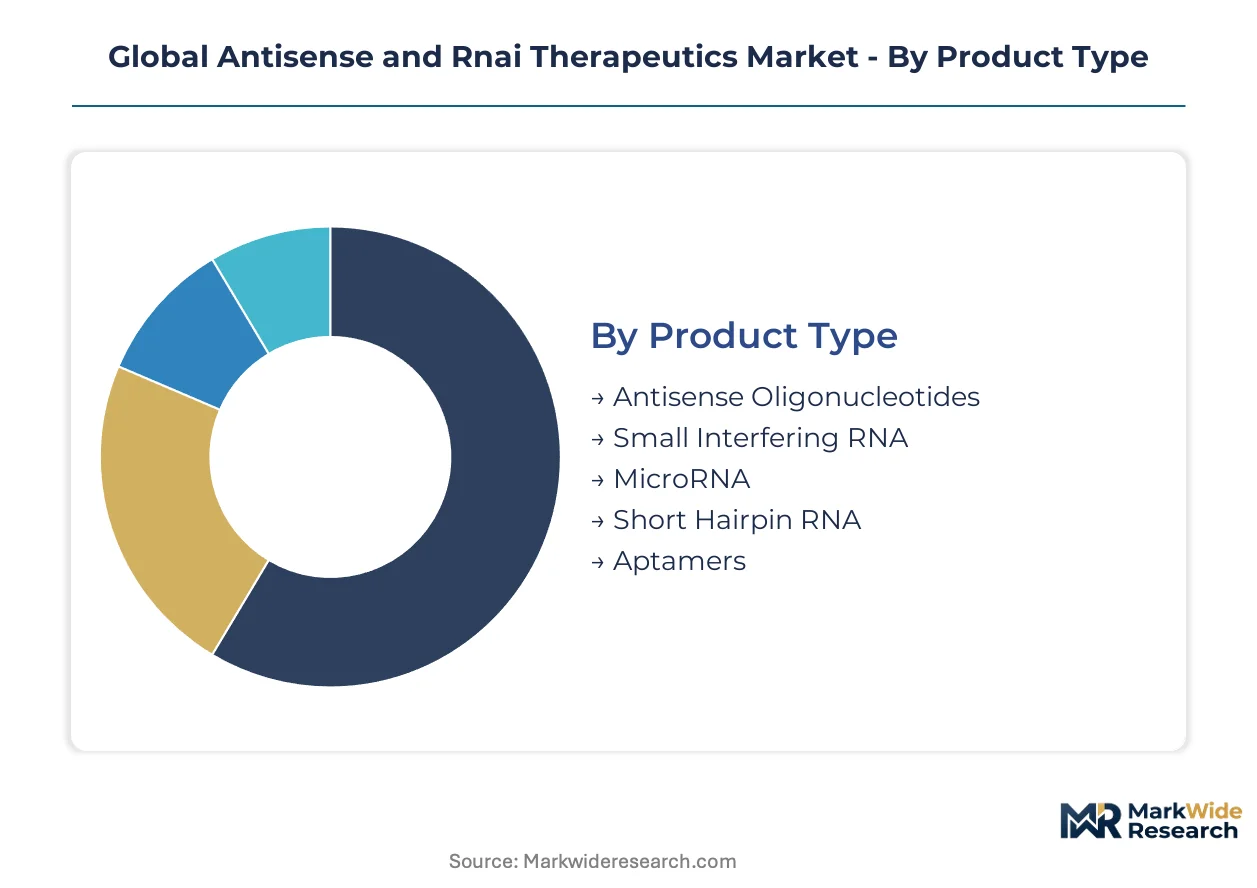
Segmentation in the antisense and RNAi therapeutics market determines manufacturing scale, regulatory pathway selection, and channel economics. Product type and delivery mode choices cascade through therapy area prioritization and end-user contracting structures. Understanding these interdependencies enables capacity planning and partnership targeting.
Product Type:
Channel economics vary sharply across product types, with intravenous formulations requiring hospital-based administration while subcutaneous candidates shift volume toward specialty pharmacy distribution.
- Small Interfering RNA:Double-stranded RNA molecules trigger RISC-mediated cleavage of complementary mRNA sequences. Demand concentrates in the United States and Germany for hereditary transthyretin amyloidosis, where GalNAc conjugation enables quarterly subcutaneous dosing. FDA accelerated approval pathways validate commercial scalability for this modality.
- Antisense Oligonucleotides:Single-stranded synthetic oligomers recruit RNase H to degrade target transcripts. Japanese and German markets anchor uptake for spinal muscular atrophy and Huntington's disease applications, constrained by nuclear delivery requirements and extended treatment durations.
- MicroRNA:Endogenous small RNAs regulating multiple mRNA targets simultaneously.
- Short Hairpin RNA:Vector-expressed hairpin precursors processed into functional siRNA.
- Aptamers:Single-stranded nucleic acid molecules folding into defined three-dimensional structures for target binding.
Small interfering RNA dominates installed base. Antisense oligonucleotides is where expansion concentrates.
Therapy Area:
Cost tier stratification separates chronic dosing indications with recurring revenue from one-time gene therapy alternatives, reshaping portfolio prioritization and pricing negotiations.
- Genetic Disorders:Inherited monogenic conditions including transthyretin and hyperoxaluria subtypes. United States and Japan concentrate demand where PMDA adaptive licensing and FDA breakthrough designations compress access timelines.
- Neurological Conditions:Central nervous system targets requiring blood-brain barrier penetration. United States developers lead in Huntington's and Alzheimer's disease candidates using transferrin receptor conjugation.
- Metabolic Disorders:Enzyme deficiency and substrate accumulation diseases.
- Rare Diseases:Orphan indications with limited patient populations and premium pricing.
- Infectious Diseases:Viral RNA targeting for chronic hepatitis and emerging pathogens.
Genetic disorders captures the largest revenue share. Neurological conditions is climbing the fastest as CNS delivery platforms mature.
End User:
Customer type determines specification requirements, with biopharmaceutical companies demanding GMP-grade material and regulatory documentation while academic users prioritize research-scale flexibility.
- Biopharmaceutical Companies:Integrated drug developers and platform technology firms advancing proprietary pipelines. Contract manufacturing organization partnerships in Germany and Switzerland concentrate supply relationships for commercial-scale production.
- Contract Research Organizations:Service providers managing preclinical and clinical trial execution. United States and Indian CROs expand oligonucleotide service capabilities to capture outsourced development demand.
- Research Laboratories:Discovery-stage institutions investigating novel targets and mechanisms.
- Academic Institutions:University-based research programs with grant-funded procurement.
Biopharmaceutical companies dominate installed base. Contract research organizations is where expansion concentrates.
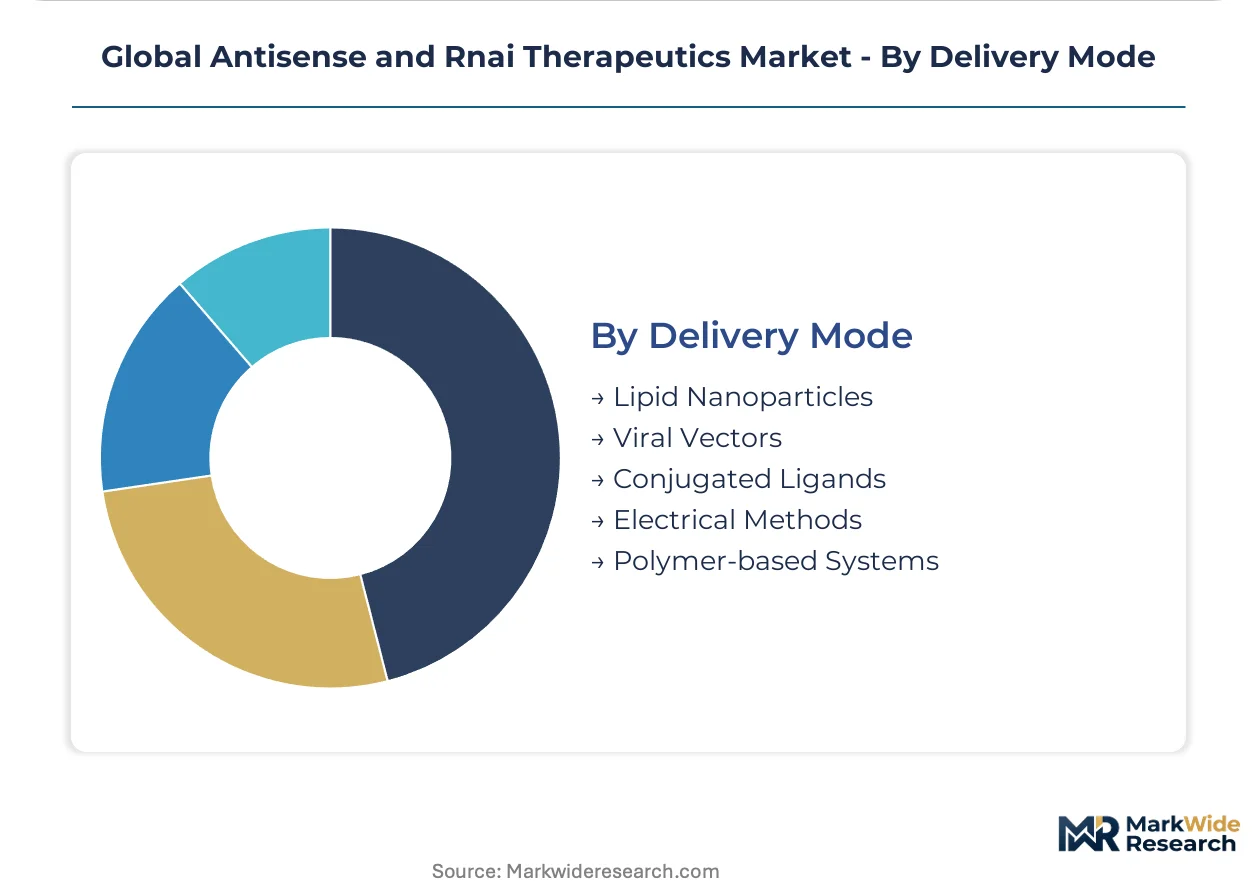
Delivery Mode:
Supply concentration in lipid nanoparticle manufacturing is forcing developers toward conjugated ligand alternatives with simplified chemistry and reduced cold-chain dependencies.
- Conjugated Ligands:GalNAc and transferrin receptor targeting moieties enabling tissue-specific uptake. United States and German manufacturing capacity is expanding most quickly for hepatocyte-targeted siRNA conjugates with subcutaneous administration profiles.
- Lipid Nanoparticles:Encapsulation systems protecting nucleic acids from serum degradation. Japanese and United States demand centers on intravenous formulations for liver and splenic delivery, constrained by batch-to-batch variability and frozen storage requirements.
- Viral Vectors:Adeno-associated and lentiviral systems for persistent expression.
- Polymer-based Systems:Cationic and biodegradable polymers complexing nucleic acids.
- Electrical Methods:Electroporation and iontophoresis for local tissue delivery.
Lipid nanoparticles dominates installed base. Conjugated ligands is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor the United States as the dominant geography, though manufacturing capacity constraints and regulatory divergence across Germany, Japan, Switzerland, and India reshape competitive positioning.
United States
Hereditary transthyretin amyloidosis and primary hyperoxaluria therapies drive concentrated demand. FDA breakthrough therapy and accelerated approval designations compress development timelines for genetic medicines. Greater Boston and San Diego biotech clusters house specialized nucleic acid chemistry talent pools that Alnylam Pharmaceuticals and Ionis Pharmaceuticals leverage for integrated discovery and commercial infrastructure.
Germany
EMA adaptive licensing frameworks attract developers seeking iterative label expansion for rare metabolic disorders. Phosphoramidite raw material synthesis concentrates in German and Swiss supplier bases, creating price volatility exposure for emerging platform companies. The Rhine-Main and Munich metropolitan regions host contract manufacturing organizations with ISO 13485 certification and continuous process verification capabilities.
Japan
PMDA adaptive licensing permits conditional market entry for primary hyperoxaluria therapies based on early-phase efficacy signals. Specialized infusion center infrastructure matures fastest in Tokyo and Osaka metropolitan areas. Japanese developers generate real-world evidence during commercialization to satisfy post-authorization commitment requirements.
Switzerland
Swissmedic regulatory frameworks align with EMA standards while offering streamlined access to European markets. Basel anchors continental nucleic acid chemistry expertise, with recruitment competition intensifying between Swiss and Boston clusters for phosphorothioate stereochemistry specialists. Contract manufacturing organizations leverage Swiss precision manufacturing heritage for viral safety validation and ICH Q5A compliance.
India
CDSCO streamlined pathways for orphan genetic medicines offer abbreviated review timelines and reduced trial costs. Hyderabad and Bengaluru contract research organizations expand oligonucleotide service capabilities to capture outsourced development demand from mid-stage biopharmaceutical firms. Local partnerships enable hepatocyte-targeted RNAi trigger development at reduced cost structures.
Global Antisense and Rnai Therapeutics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Integrated rare disease commercial infrastructure separates first-mover platforms from follow-on entrants. Three archetypes dominate: vertically integrated biopharmaceuticals with proprietary delivery platforms, royalty-bearing platform licensors with broad neurology partnerships, and targeted RNAi trigger specialists competing via endogenous gene silencing mechanisms. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as specialized nucleic acid chemist scarcity forces restructuring of North American and European production footprints.
Within the integrated platform tier, Alnylam Pharmaceuticals and Ionis Pharmaceuticals exemplify contrasting archetypes—one leveraging captive commercial infrastructure for ATTR amyloidosis, the other anchoring position through partnership-based royalty structures. Arrowhead Pharmaceuticals occupies a position among targeted RNAi trigger specialists, differentiating through liver-expressed gene focus. These three entities represent the competitive spectrum from fully integrated to partnership-dependent models.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals |
| Ionis Pharmaceuticals |
| Arrowhead Pharmaceuticals |
| Sarepta Therapeutics |
| Silence Therapeutics |
| Arbutus Biopharma |
| Wave Life Sciences |
| Dicerna Pharmaceuticals |
| Sirnaomics |
| Others |
Supply & Pricing Matrix
ISO 13485 certification gates contract manufacturing organization selection while simultaneously stratifying price tiers, as facilities with viral safety validation capabilities command substantial premiums over standard GMP operations. This dual filtering mechanism concentrates procurement power among developers with established quality infrastructure, compressing margins for emerging platform companies seeking initial commercial-scale supply.
Pricing Analysis
United States formulations trade at substantial premiums over Indian and Chinese equivalents, reflecting cold-chain logistics and specialized infusion center infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates FDA-approved therapies from EMA-conditional and CDSCO-streamlined alternatives. Pricing pressure stems from phosphoramidite raw material volatility concentrated in German and Swiss supplier bases. Academic research laboratories exhibit highest price sensitivity, while integrated biopharmaceutical companies prioritize supply security over unit cost.
Supply Chain Analysis
Phosphoramidite synthesis expertise concentrates in Germany and Switzerland, creating single-source vulnerability for oligonucleotide backbone production. Manufacturing draws from phosphorothioate stereochemistry inputs, 2'-modification reagents, and GalNAc ligand precursors sourced through specialized chemical suppliers. Tariff exposure runs through European raw material corridors into North American formulation facilities. Distribution runs through contract manufacturing organizations with ICH Q5A compliance, filtering participants by twelve-to-eighteen-month qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antisense and RNAi therapeutics market is recovering from manufacturing capacity constraints as FDA accelerated approval pathways normalize development timelines and attract renewed biopharmaceutical investment.
For Market Incumbents: Shield proprietary GalNAc conjugation platforms through patent thickets around hepatocyte-targeting ligand chemistry, while expanding captive manufacturing capacity in Boston and Basel clusters to offset nucleic acid chemist scarcity. Prioritize ISO 13485 certification investments at European contract manufacturing partners to maintain quality-tier pricing differentiation against emerging Indian competitors. For New Entrants and Emerging Players: Central nervous system delivery capabilities represent the most penetrable white-space segment, as blood-brain barrier penetration remains technically unresolved for most incumbents. Target Huntington's disease and Alzheimer's disease applications using transferrin receptor conjugation approaches. Establish partnerships with United States-based academic medical centers to access specialized infusion infrastructure without capital-intensive facility builds. For Investors and Strategic Acquirers: FDA breakthrough therapy designation reshapes the acquisition landscape by validating de-risked clinical assets with compressed regulatory timelines. Five-to-ten-year viability hinges on pipeline diversification beyond liver-expressed gene targets. Monitor EMA adaptive licensing framework adoption rates as the primary signal for European market access risk reduction.| Strategic Initiative | Industry Significance |
|---|---|
| GalNAc Conjugation Platform Expansion | Enables subcutaneous dosing at Alnylam Pharmaceuticals, displacing intravenous lipid nanoparticle administration. |
| Continuous Manufacturing Integration | Flow chemistry adoption at German contract manufacturing organizations reduces facility footprint requirements. |
| CNS Delivery Partnership Formation | Transferrin receptor conjugation collaborations advance Huntington's disease candidates through blood-brain barrier penetration. |
| Regulatory Pathway Diversification | PMDA adaptive licensing utilization generates Japanese real-world evidence during commercialization phases. |
| Specialized Workforce Development | Phosphorothioate stereochemistry training programs address nucleic acid chemist scarcity in Boston clusters. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and contract manufacturing organization technical directors anchored the qualitative base. Primary interview findings triangulated against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Secondary validation incorporated bottom-up patient population modeling with top-down biopharmaceutical revenue segmentation.
Sensitivity analysis tested forecast robustness across therapy area prioritization scenarios, delivery mode substitution rates, and regional regulatory cluster adoption patterns. The analytical framework modeled small interfering RNA, antisense oligonucleotide, and emerging modality segments across genetic disorder, neurological condition, and metabolic disorder applications. CAGRs derived from patent expiration impacts, label expansion probabilities, and manufacturing capacity absorption curves.
Forecasts assume regulatory continuity in FDA accelerated approval, EMA adaptive licensing, and PMDA conditional entry frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Global Hormone Refractory Breast Cancer Market
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Iga Nephropathy (Igan) Market