
 Bioinformatics in IVD Testing Market | 2026-2036
Bioinformatics in IVD Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Bioinformatics in IVD Testing Market Analysis
Computational biology PhD talent is collapsing across contract research organizations, forcing diagnostics firms to rebuild pipelines with automated variant interpretation tools. Thermo Fisher Scientific leverages its Ion Torrent platform integration to anchor clinical bioinformatics workflows in oncology panels. Illumina sustains dominance through DRAGEN acceleration hardware that compresses secondary analysis turnaround times. QIAGEN N.V. competes with clinically curated knowledge bases that differentiate its interpretation services from open-source alternatives.
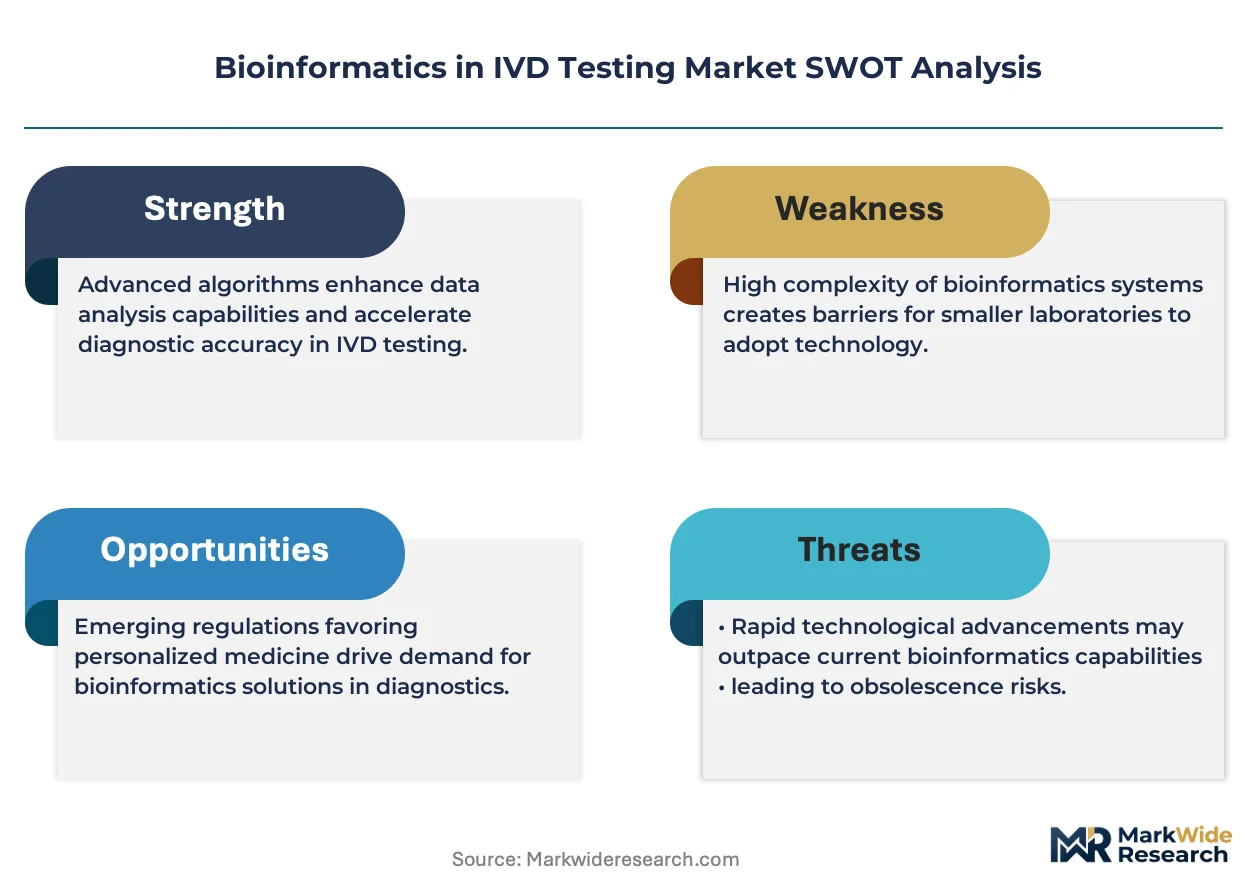
Bioinformatics in IVD Testing encompasses computational algorithms, statistical models, and software architectures that process raw molecular data from in vitro diagnostic instruments into clinically actionable reports, typically operating on FASTQ-to-VCF pipelines with variant allele frequency thresholds below five percent for somatic mutation detection. The primary purpose is to transform complex multi-omics datasets into standardized diagnostic outputs that pathologists and clinicians can act upon without manual bioinformatics intervention. Software Tools and Platforms capture the dominant share of product-type revenue as labs prioritize integrated workflow environments over point solutions. Services are expanding fastest as mid-sized hospitals outsource variant interpretation and regulatory documentation to specialized vendors rather than building captive bioinformatics units.
FDA software-as-a-medical-device frameworks and HIPAA data governance requirements shape how cloud-based bioinformatics platforms architect patient data flows and audit trails. EMA's In Vitro Diagnostic Regulation and ISO 13485 quality management standards govern European market access, forcing algorithm developers to generate clinical evidence through prospective analytical validation studies. Stakeholders must monitor whether reimbursement pathways for algorithm-only diagnostic contributions crystallize before committing capital to proprietary variant classification engines.
Market Dynamics
FDA's evolving software-as-a-medical-device guidance is compressing algorithm validation timelines while academic medical centers demand real-time variant interpretation pipelines that bypass manual curation bottlenecks.
Growth Catalysts
- HIPAA-compliant cloud architectures:Clinical laboratories in the United States are migrating secondary analysis workloads to FedRAMP-authorized platforms, eliminating on-premise server capex barriers for mid-sized hospitals.
- Oncology panel expansion:Solid tumor profiling programs at academic medical centers now require automated somatic variant classification to match molecular tumor board review cycles.
- EMA In Vitro Diagnostic Regulation harmonization:European reference laboratories are consolidating bioinformatics procurement to vendors with ISO 13485-certified quality management systems, accelerating vendor selection decisions.
Market Restraints
- GPU compute cost volatility:Cloud-based variant calling pipelines face unpredictable per-sample processing costs as NVIDIA datacenter pricing fluctuates, squeezing gross margins for high-throughput sequencing services.
- PhD computational biology talent scarcity:Contract research organizations in North America and Europe report 40% vacancy rates for variant curation specialists, forcing diagnostic firms to absorb retraining costs.
- FDA premarket submission complexity:Algorithm developers must generate prospective analytical validation studies for each intended use indication, extending time-to-revenue by 18-24 months for novel biomarker classifiers.
Strategic Opportunities
- Liquid biopsy minimal residual disease monitoring:Cell-free DNA analysis workflows for post-treatment cancer surveillance remain underpenetrated in community hospital laboratories, creating white space for turnkey bioinformatics-as-a-service models.
- Pharmacogenomic reporting mandates:United States payer coverage policies for preemptive PGx testing are expanding, requiring automated CYP450 haplotype calling and drug interaction prediction modules.
- AI-assisted variant classification convergence:Large language models trained on ClinVar submissions are displacing rule-based ACMG criteria interpretation, enabling laboratories to reallocate PhD-level curators to complex cases.
Industry Challenges
- LIMS-to-pipeline integration complexity:Legacy laboratory information management systems at mid-sized hospitals lack API-native connectivity to cloud bioinformatics platforms, requiring costly middleware development.
- Multi-omics data harmonization:Integrating DNA sequencing, RNA expression, and proteomic outputs into unified diagnostic reports demands specialized bioinformatics architecture expertise that resides primarily at academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioinformatics in IVD Testing Market |
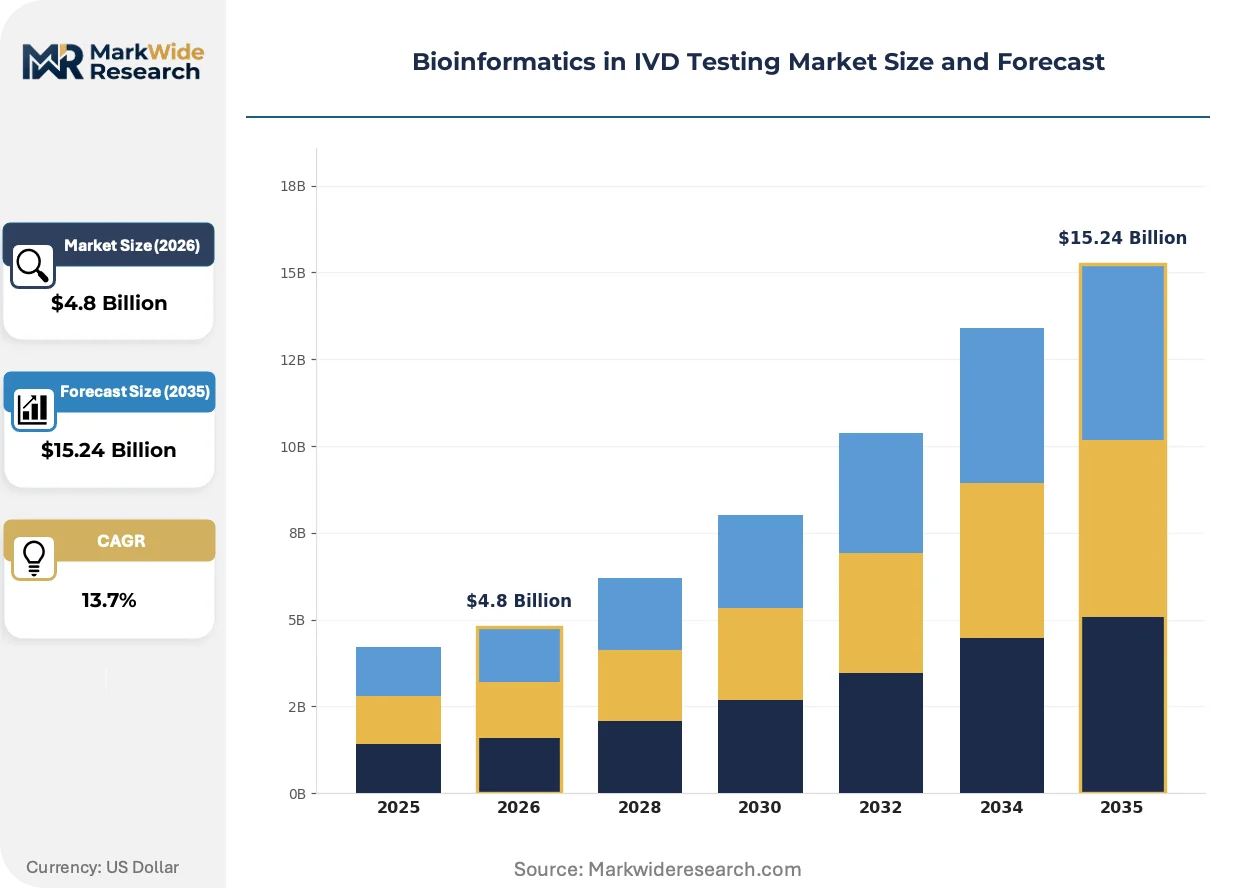
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Tools, Databases, Services, Platforms Application: Genomic Testing, Proteomic Analysis, Drug Development, Clinical Diagnostics End User: Diagnostics Labs, Healthcare Institutions, Research Organizations, Pharmaceutical Companies Technology: NGS, Microarrays, PCR, CRISPR |
| Companies Covered | Thermo Fisher Scientific Inc, Illumina Inc, QIAGEN N.V, Agilent Technologies Inc, Roche Holding AG, Bio-Rad Laboratories Inc, PerkinElmer Inc, BGI Genomics Co Ltd, DNAnexus Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioinformatics in IVD Testing Market Emerging Trajectories
Hardware acceleration and federated learning architectures are compressing analysis turnaround times while regulatory frameworks force algorithm developers toward prospective clinical validation models rather than retrospective database mining.
DRAGEN field-programmable gate array acceleration is displacing CPU-based secondary analysis pipelines in high-volume clinical laboratories. Reference labs processing more than ten thousand samples monthly are standardizing on hardware-accelerated germline and somatic variant calling to reduce per-sample compute costs by an order of magnitude. This displacement is compressing the competitive window for software-only bioinformatics vendors that lack silicon partnerships.
EMA's In Vitro Diagnostic Regulation is mandating clinical evidence standards for algorithm-only diagnostic contributions that previously operated under laboratory-developed test exemptions. European notified bodies now require prospective analytical validation studies with defined reference materials for variant classification algorithms, forcing developers to rebuild evidence packages. Medium-sized reference laboratories in Germany and France are responding by consolidating procurement to vendors with existing IVDR technical documentation.
Hospital procurement committees are unbundling bioinformatics software licenses from sequencing instrument contracts, creating independent evaluation criteria for variant interpretation modules. Community health systems in the United States are replacing bundled vendor solutions with best-of-breed pipeline components selected through separate RFP processes. This pattern is most visible in the Southeast and Midwest regions where hospital consolidation has centralized molecular pathology purchasing authority.
Bioinformatics in IVD Testing Market Segmentation
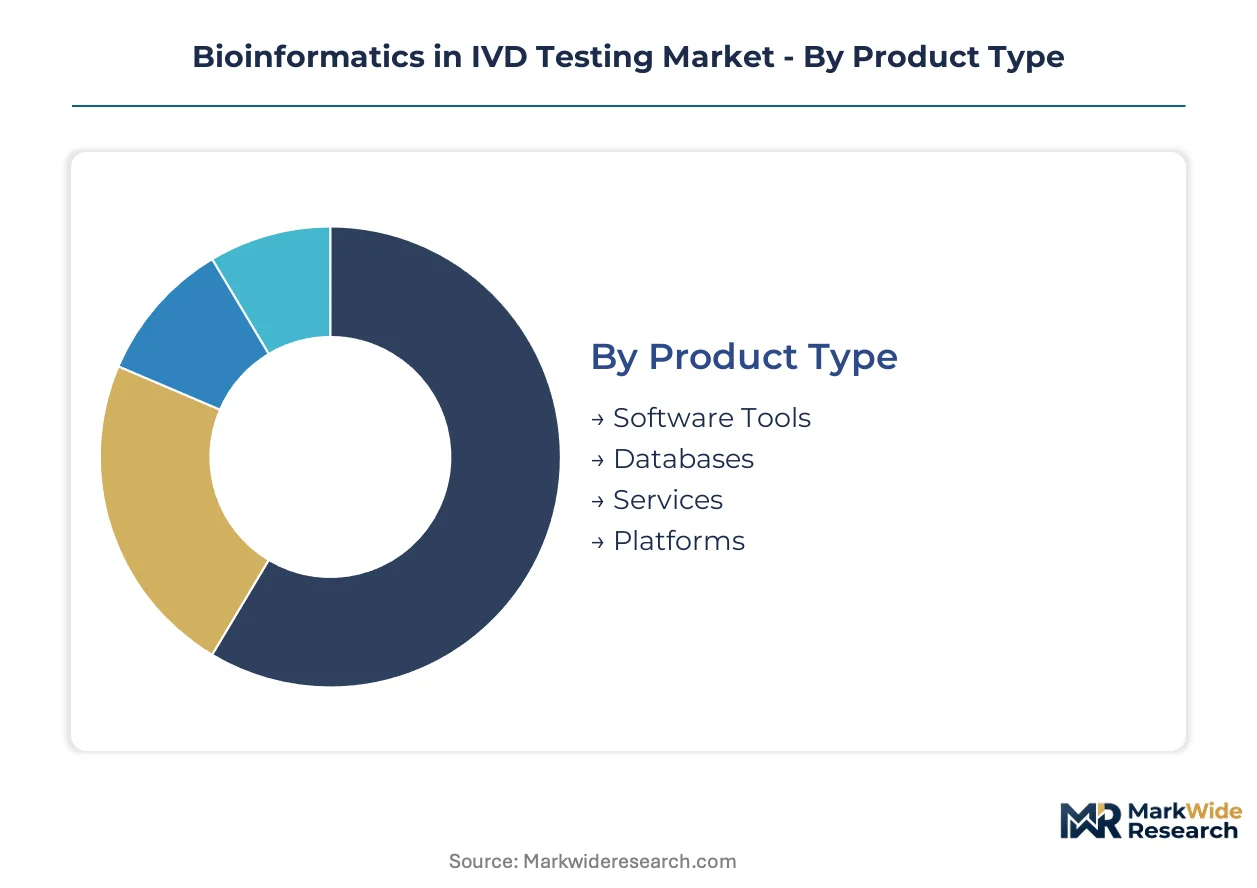
Bioinformatics in IVD Testing segments reveal divergent margin structures across the value chain. Software platforms command recurring revenue streams while services absorb talent scarcity costs. Technology choices determine hardware partnerships and regulatory pathways.
Product Type:
Margin pools concentrate in integrated platforms that bundle interpretation engines with regulatory documentation support, while standalone databases face commoditization pressure from open-source alternatives.
- Software Tools:Variant calling algorithms and visualization modules process FASTQ-to-VCF pipelines with allele frequency thresholds below five percent. Academic medical centers in the United States prioritize automated somatic classification to match molecular tumor board review cycles, compressing manual curation bottlenecks.
- Platforms:End-to-end workflow environments integrate secondary analysis, tertiary interpretation, and clinical reporting with LIMS connectivity. Mid-sized hospitals in the Southeast and Midwest regions of the United States are unbundling these from sequencing instrument contracts through separate RFP processes.
- Services:Outsourced variant interpretation and IVDR technical documentation generation for European market access.
- Databases:Clinically curated knowledge bases for variant pathogenicity classification competing against open-source repositories.
Software Tools holds installed capacity. Services is rotating up the share rankings.
Application:
Volume concentrates in diagnostic workflows where reimbursement pathways exist, while drug development applications require bespoke algorithm validation that extends sales cycles.
- Clinical Diagnostics:Standardized somatic and germline variant reporting for oncology, cardiology, and rare disease indications with established CPT coding. Community hospital laboratories face LIMS-to-pipeline integration complexity that favors turnkey platform procurement over custom builds.
- Genomic Testing:Population-scale screening programs and preemptive pharmacogenomic testing with automated CYP450 haplotype calling. United States payer coverage policies for PGx are expanding, requiring drug interaction prediction modules.
- Proteomic Analysis:Multi-omics data harmonization combining mass spectrometry outputs with genomic profiles for unified diagnostic reports.
- Drug Development:Biomarker discovery and companion diagnostic algorithm development with prospective analytical validation for FDA premarket submissions.
Clinical Diagnostics dominates current throughput. Genomic Testing is climbing the fastest.
End User:
Procurement authority patterns split between centralized hospital system purchasing and distributed research organization acquisition with distinct contracting timelines.
- Diagnostics Labs:High-throughput reference laboratories processing ten thousand-plus samples monthly standardizing on hardware-accelerated pipelines. These facilities demand FedRAMP-authorized cloud architectures to eliminate on-premise server capex.
- Healthcare Institutions:Academic medical centers building in-house bioinformatics capacity with real-time interpretation pipelines. Talent scarcity forces these institutions to absorb retraining costs for computational biology PhD vacancies.
- Research Organizations:Contract research organizations facing forty percent vacancy rates for variant curation specialists.
- Pharmaceutical Companies:Companion diagnostic co-development partnerships requiring ISO 13485-certified quality management systems.
Diagnostics Labs commands capital deployment. Healthcare Institutions is gaining share fastest.
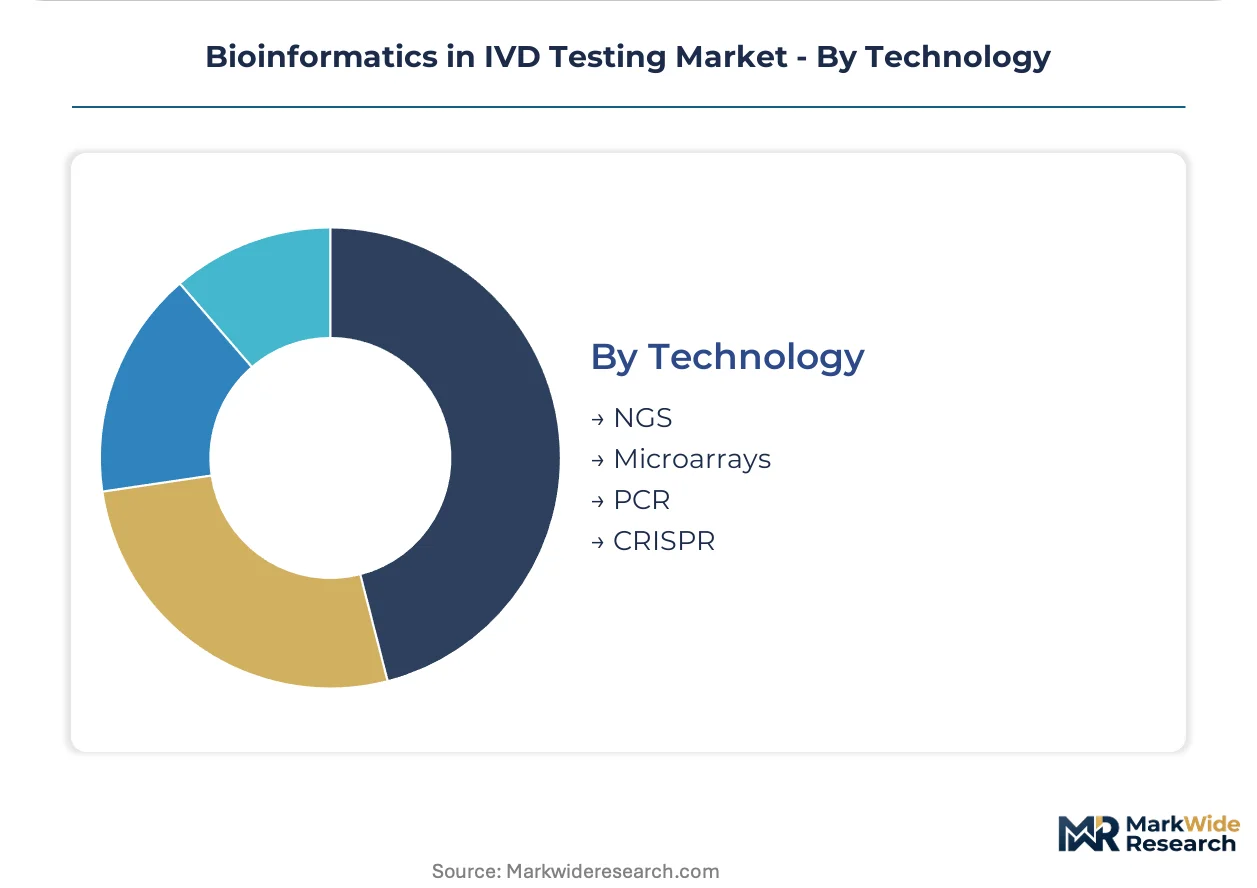
Technology:
Hardware acceleration partnerships determine competitive positioning as CPU-based pipelines face displacement by FPGA and GPU architectures.
- NGS:Next-generation sequencing generates raw molecular data requiring FASTQ-to-VCF secondary analysis with DRAGEN FPGA acceleration displacing CPU-based workflows. High-volume clinical laboratories achieve order-of-magnitude per-sample compute cost reductions through silicon partnerships.
- PCR:Targeted amplification for liquid biopsy minimal residual disease monitoring with cell-free DNA analysis workflows. Community hospital laboratories remain underpenetrated for post-treatment cancer surveillance, creating white space for turnkey bioinformatics-as-a-service models.
- Microarrays:Genotyping arrays for pharmacogenomic screening and copy number variation detection with established reimbursement.
- CRISPR:Gene editing validation and off-target analysis with emerging clinical diagnostic applications.
NGS anchors installed capacity. PCR is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States laboratories prioritize cloud-native architectures and real-time variant interpretation, while European facilities emphasize IVDR-compliant quality systems and German reference labs concentrate on hardware-accelerated pipelines.
United States
Academic medical centers in Boston and New York Metro are building captive bioinformatics capacity with automated somatic classification pipelines. FDA software-as-a-medical-device guidance is compressing algorithm validation timelines for developers seeking premarket clearance. The Southeast and Midwest hospital consolidation wave is centralizing molecular pathology procurement authority through separate RFP processes for interpretation modules.
Germany
Reference laboratories in Bavaria and North Rhine-Westphalia are standardizing on ISO 13485-certified vendors to satisfy IVDR technical documentation requirements. EMA's In Vitro Diagnostic Regulation is mandating prospective analytical validation studies with defined reference materials. The Berlin-Brandenburg cluster is emerging as a procurement consolidation hub for medium-sized labs outsourcing variant curation.
United Kingdom
NHS Genomic Medicine Service is driving standardized bioinformatics procurement across England's seven genomic laboratory hubs. The Medicines and Healthcare products Regulatory Agency is aligning software guidance with FDA frameworks for AI-based diagnostic algorithms. London and Cambridge biotech clusters are specializing in companion diagnostic co-development partnerships with pharmaceutical sponsors.
China
BGI Genomics and hospital-affiliated laboratories in Beijing-Tianjin-Hebei and Yangtze River Delta are deploying population-scale NGS interpretation pipelines. NMPA is tightening software-as-medical-device classification for variant calling algorithms used in clinical settings. The Shenzhen biotech corridor is concentrating cloud-based bioinformatics-as-a-service models for tier-two city hospitals.
Japan
PMDA is establishing precedents for AI-assisted variant classification through Sakigake fast-track designations for oncology diagnostic algorithms. METI funding is accelerating hardware-accelerated pipeline adoption at university hospitals in Kanto and Kansai regions. The Tokyo-Osaka corridor is specializing in liquid biopsy minimal residual disease monitoring workflows for post-treatment cancer surveillance.
Bioinformatics in IVD Testing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with sequencing platform vendors controlling hardware-software bundled contracts while pure-play bioinformatics vendors compete on interpretation accuracy. The market structure reflects consolidation around three archetypes: instrument-integrated platforms, cloud-native interpretation services, and clinically curated knowledge base providers. Dominant competitive moves include unbundling software licenses from sequencing contracts and forming silicon partnerships for FPGA acceleration.
Among instrument-integrated leaders, Thermo Fisher Scientific Inc and Illumina Inc exemplify the platform-architecture archetype through their respective Ion Torrent and DRAGEN hardware-software ecosystems. QIAGEN N.V occupies a position within the knowledge base tier, representing clinically curated interpretation services that differentiate from open-source alternatives. These three entities anchor the competitive structure, with each representing distinct strategic positioning around hardware integration, computational acceleration, or clinical curation depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Illumina Inc |
| QIAGEN N.V |
| Agilent Technologies Inc |
| Roche Holding AG |
| Bio-Rad Laboratories Inc |
| PerkinElmer Inc |
| BGI Genomics Co Ltd |
| DNAnexus Inc |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day validation timelines for FDA software-as-a-medical-device submissions compress procurement cycles and concentrate pricing power with vendors holding pre-cleared algorithm portfolios. This lead-time compression favors integrated platform providers over point-solution developers, reshaping how hospital systems negotiate bioinformatics contracts.
Pricing Analysis
Long-term SaaS subscriptions with annual tiered licensing dominate bioinformatics procurement, though spot project-based engagements persist for IVDR technical documentation services. Price differentiation rests on ISO 13485 certification status and FedRAMP authorization level, with premium tiers commanding substantial uplifts for automated variant classification modules. Pricing pressure stems from GPU compute cost volatility squeezing high-throughput sequencing service margins. Community hospital laboratories exhibit highest price sensitivity, while academic medical centers prioritize turnaround time over per-sample fees.
Supply Chain Analysis
Inbound logistics costs for NVIDIA A100 and H100 datacenter GPUs fluctuate with transpacific container availability and Taiwan Strait shipping lane congestion. Silicon supply concentrates in Taiwan, South Korea, and the United States, with FPGA fabrication drawing from TSMC and Samsung foundry capacity. Supply chain risk centers on single-source dependency for specialized AI accelerators used in DRAGEN field-programmable gate array pipelines. Distribution runs through direct enterprise sales channels and cloud marketplace procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioinformatics in IVD Testing functions as a service-attach market where recurring interpretation revenue expands faster than sequencing hardware sales, with variant curation-as-a-service growing fastest among mid-sized hospitals.
For Market Incumbents: Shield installed base relationships through ISO 13485 certification investments that lock out smaller competitors from European IVDR procurement. Deepen silicon partnerships with NVIDIA and Xilinx to secure FPGA allocation priority during supply constraints. Consolidate interpretation accuracy leadership by embedding large language models trained on ClinVar submissions before open-source alternatives mature. For New Entrants and Emerging Players: IVDR technical documentation outsourcing gaps at medium-sized German and French reference laboratories represent immediate white-space opportunity. Liquid biopsy minimal residual disease monitoring workflows remain underpenetrated in community hospital settings, offering fastest path to recurring revenue. Pursue bioinformatics-as-a-service models with turnkey cloud deployment to bypass LIMS integration complexity that stalls traditional software sales. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical companion diagnostic divisions seeking to monetize proprietary variant classification algorithms developed for internal pipeline programs. Long-term viability hinges on regulatory moat depth rather than raw interpretation accuracy. Monitor FDA premarket submission clearance velocity as inflection signal—accelerating approval timelines validate platform scalability, while stagnation indicates evidence-generation cost barriers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Premarket Submission | Clears automated variant classification algorithms for clinical diagnostic use. |
| Silicon Partnership Formation | Secures FPGA allocation priority with NVIDIA and Xilinx for DRAGEN acceleration. |
| ISO 13485 Certification Investment | Unlocks European IVDR procurement at German and French reference laboratories. |
| Liquid Biopsy Workflow Launch | Captures post-treatment cancer surveillance demand in community hospital settings. |
| LLM Training Data Acquisition | Builds proprietary ClinVar-trained models that displace rule-based ACMG interpretation. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with molecular pathology directors, bioinformatics pipeline engineers, hospital GPO contracts managers, and IVDR regulatory affairs specialists. Secondary validation drew from FDA 510(k) and De Novo submission databases, EMA IVDR technical documentation filings, CMS Medicare reimbursement schedules, and hospital procurement RFP records. Bottom-up sample-level throughput estimates triangulated against top-down market sizing from sequencing instrument installed base analysis.
Across the analysis window, the forecast framework modeled volume and value trajectories through segmented projections across product type, application, end user, and technology dimensions. CAGRs were derived from fitted growth curves anchored to historical adoption rates and regulatory approval velocity. Industry-specific inputs included NGS sample processing volumes, cloud compute cost indices, and computational biology PhD hiring vacancy rates reported by contract research organizations.
Material uncertainties — reimbursement pathway crystallization for algorithm-only diagnostic contributions, GPU datacenter pricing volatility, and FDA software guidance revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and talent scarcity persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
AI in Life Science Analytics Market
Bioinformatics
Global Biological Data Visualization Market
Bioinformatics
Global Chemoinformatics Market
Bioinformatics
North America Computational Biology Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
South Korea Computational Biology Market
Bioinformatics
Global Bioinformatics Services Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
China Computational Biology Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
Bioinformatics Market
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
US Computational Biology Market
Bioinformatics
Bioinformatics Software Market
Bioinformatics
Germany Computational Biology Market