
 Whole Genome Amplification Market | 2026-2036
Whole Genome Amplification Market Size, Share, and Industry Trends Forecast 2026-2036
Whole Genome Amplification Market Outlook
Clinical diagnostics is broadening its share of whole genome amplification demand as precision medicine protocols expand across oncology and rare disease programs. Thermo Fisher Scientific leverages its reagent manufacturing scale to supply high-volume hospital networks. QIAGEN anchors its position through specialized sample preparation workflows that integrate with downstream sequencing platforms. Illumina, Inc. competes by controlling instrument placement in core genomic facilities worldwide.
Whole genome amplification refers to methods that generate microgram quantities of DNA from picogram inputs without sequence bias, typically employing phi29 DNA polymerase in multiple displacement amplification or thermal-cycling polymerase systems. These techniques enable single-cell genomics, forensic profiling from degraded samples, and microbial characterization from low-biomass clinical specimens. Multiple displacement amplification dominates research settings due to superior fidelity and longer amplicon lengths, while polymerase chain reaction retains cost advantages in routine diagnostic workflows. Reagents and kits capture the largest margin pools because consumable pull-through ties directly to instrument installed bases.
FDA oversight of laboratory-developed tests shapes clinical adoption pathways, while the EMA's In Vitro Diagnostic Regulation reclassifies genome amplification products across European member states. ISO 13485 certification requirements filter supplier access to regulated diagnostic markets. Stakeholders must monitor evolving premarket submission expectations as multiplexed amplification panels migrate from research-only to diagnostic claims.
Market Dynamics
The transition from PCR-based workflows to multiple displacement amplification is compressing cost-per-sample thresholds while expanding addressable specimen types in clinical diagnostics.
Growth Catalysts
- Precision medicine protocols:Oncology and rare disease programs in the United States are integrating whole genome amplification into standard diagnostic pathways, creating pull-through demand for companion reagent kits.
- EMA In Vitro Diagnostic Regulation:The reclassification framework across European member states is streamlining market entry for validated amplification products, reducing regulatory fragmentation.
- Single-cell genomics:Academic research institutions are scaling MDA workflows for lineage tracing studies, generating sustained consumable volume.
Market Restraints
- Phi29 polymerase supply concentration:Production of the core enzyme clusters among contract fermentation facilities in Denmark and Germany, exposing buyers to batch-to-batch variability.
- FDA laboratory-developed test oversight:Premarket submission requirements for multiplexed amplification panels extend commercialization timelines by 18-24 months.
- PCR cost floor:Thermal-cycling systems retain a 40-60% price advantage in high-volume screening applications, limiting MDA penetration in routine workflows.
Strategic Opportunities
- India's CDSCO diagnostic pathway:The centralized regulator is establishing fast-track approval for imported amplification reagents, opening access to a hospital network of over 75,000 facilities.
- Forensic degraded sample analysis:Law enforcement agencies in Japan are adopting MDA for cold case DNA recovery, creating a specialized application segment.
- ISO 13485 certification arbitrage:Contract manufacturers in South Korea are building certified capacity to serve mid-tier diagnostic firms lacking in-house quality systems.
Industry Challenges
- Bioinformatics integration complexity:Clinical laboratories face workflow friction when connecting amplification outputs to downstream variant interpretation pipelines.
- Phi29 fidelity standardization:Absence of harmonized error-rate benchmarks across suppliers complicates cross-study reproducibility claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whole Genome Amplification Market |
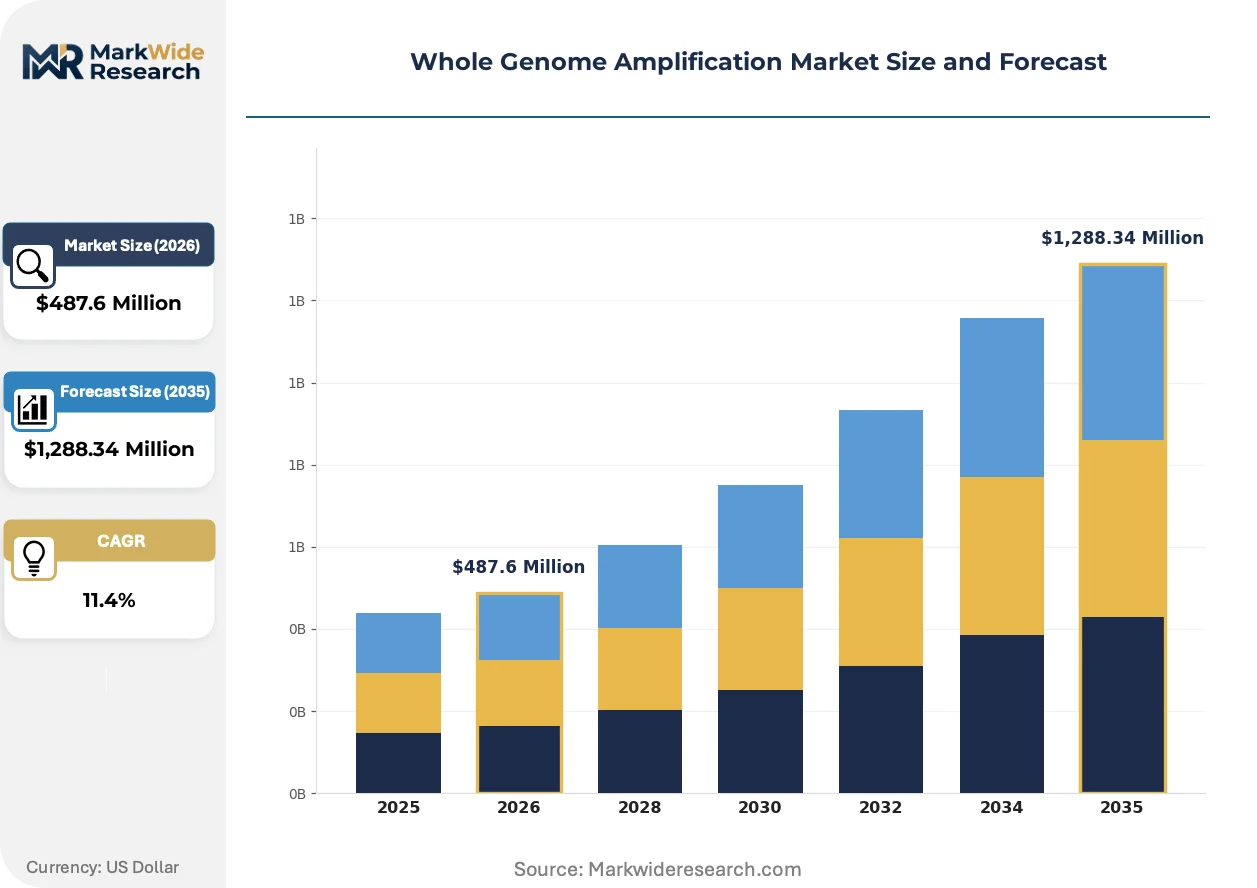
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Polymerase Chain Reaction, Isothermal Amplification, Multiple Displacement Amplification, LAMP Application: Genomic Research, Clinical Diagnostics, Forensic Analysis, Microbial Genomics End User: Research Institutions, Hospitals, Forensic Labs, Biotech Companies Delivery Mode: Reagents, Kits, Instruments, Software |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific, QIAGEN, Sigma-Aldrich, PerkinElmer, Inc., Roche Diagnostics, Bio-Rad Laboratories, Danaher Corporation, LGC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whole Genome Amplification Market Strategic Shifts
Workflow automation and regulatory harmonization are converging to reshape how amplification products reach end users, with instrument-reagent bundling emerging as the dominant commercial architecture.
Multiple displacement amplification is absorbing volume from traditional PCR workflows in prenatal testing laboratories. Hospital networks in Germany and Switzerland are consolidating purchasing around integrated MDA-sequencing platforms. This technology convergence is compressing the installed base of standalone thermal cyclers while expanding per-sample reagent pull-through.
The FDA's evolving framework for laboratory-developed tests is forcing diagnostic developers to separate research-use-only claims from clinical validation data. Amplification kit suppliers must now maintain dual SKU portfolios. High-complexity reference laboratories in the United States are responding by building internal clinical validity dossiers ahead of submission deadlines.
Buying committees at integrated delivery networks are consolidating vendor relationships around full-stack genomic workflows. Standalone reagent suppliers are losing shelf space to instrument-anchored consumable programs. This concentration is most visible in the United States, where NIH-funded academic medical centers are prioritizing single-source procurement to simplify compliance auditing.
Whole Genome Amplification Market Segmentation
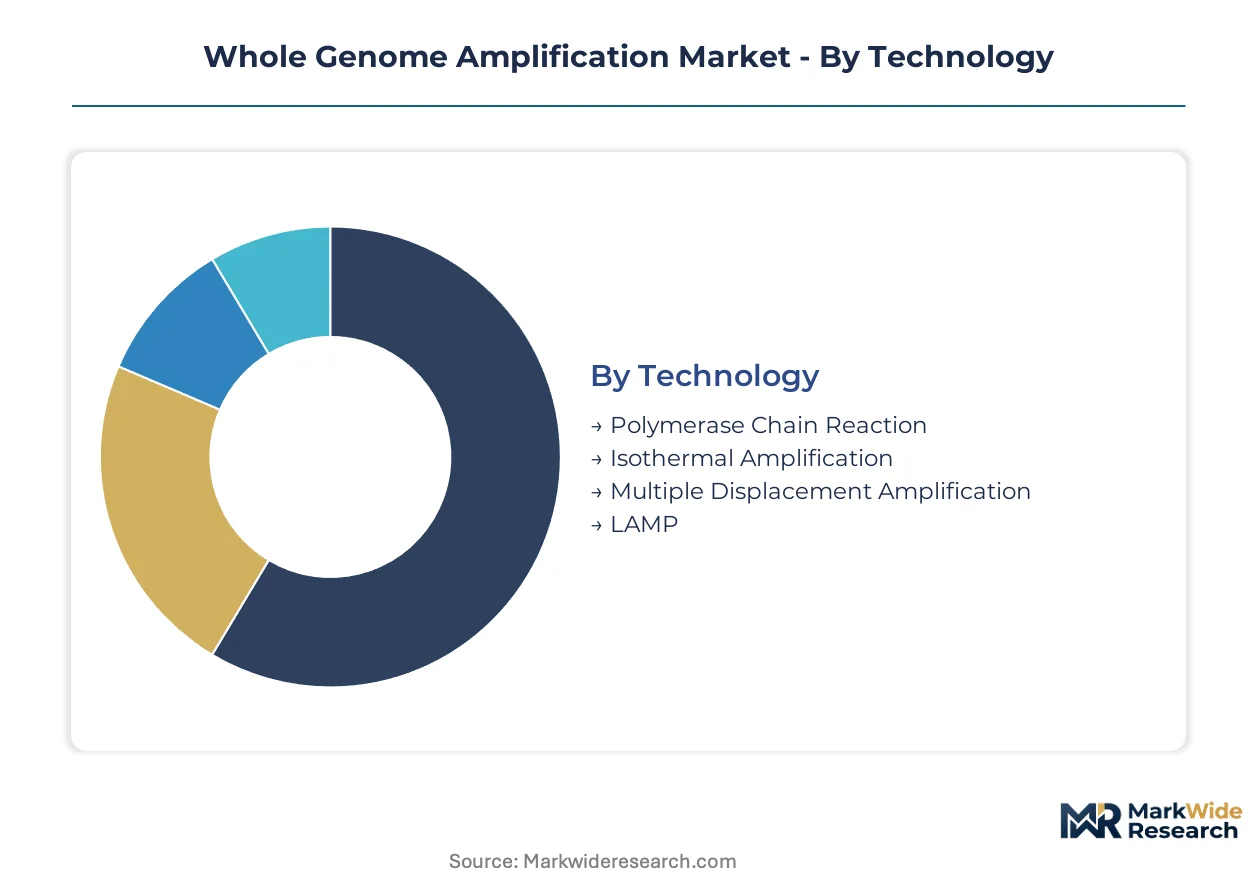
Technology choice in whole genome amplification dictates fidelity, throughput, and regulatory pathway. Segment boundaries blur as vendors bundle reagents with instruments to capture recurring revenue streams.
Technology:
Upgrade cycles accelerate as laboratories replace thermal-cycling infrastructure with isothermal platforms.
- Multiple Displacement Amplification:Phi29 DNA polymerase drives this isothermal method, generating microgram yields from picogram inputs with minimal sequence bias. United States oncology centers are standardizing MDA for circulating tumor DNA workflows, though phi29 supply concentration in Danish and German fermentation facilities creates procurement risk.
- Polymerase Chain Reaction:Thermal-cycling systems remain entrenched in high-volume screening due to 40-60% cost advantages over isothermal alternatives. Routine diagnostic laboratories in India and Brazil continue expanding PCR capacity for infectious disease panels.
- Isothermal Amplification:Enzymatic methods operating at constant temperature reduce instrument complexity and enable point-of-care deployment.
- LAMP:Loop-mediated isothermal amplification offers visual detection without specialized equipment, penetrating resource-limited settings.
Volume placements concentrate in Polymerase Chain Reaction; the faster expansion belongs to Multiple Displacement Amplification.
Application:
Cost tier separation sharpens as premium-priced clinical diagnostics diverge from grant-funded research workflows.
- Clinical Diagnostics:Precision medicine protocols in oncology and rare disease programs require validated amplification workflows with FDA 510(k) or EMA MDR clearance. United States hospital networks are consolidating purchasing around integrated MDA-sequencing platforms, compressing standalone thermal cycler installations.
- Genomic Research:Academic institutions drive consumable volume through single-cell lineage tracing and population-scale sequencing projects. NIH-funded centers prioritize reagent flexibility over regulatory certification.
- Forensic Analysis:Law enforcement agencies in Japan and Germany adopt MDA for degraded sample recovery from cold cases.
- Microbial Genomics:Low-biomass clinical specimens and environmental sampling propel demand for high-fidelity whole genome amplification.
Revenue concentration sits with Clinical Diagnostics; Microbial Genomics shows the steepest expansion trajectory.
End User:
Customer type determines procurement authority, with integrated delivery networks consolidating vendor relationships.
- Research Institutions:Academic medical centers and university core facilities generate sustained reagent demand through multi-year sequencing initiatives. These buyers prioritize technical flexibility and publication-grade reproducibility over regulatory documentation.
- Hospitals:Clinical laboratories within integrated delivery networks command standardized workflows and single-source procurement to simplify compliance auditing. EMA MDR implementation is forcing separation of research-use-only from clinical-validation SKUs.
- Forensic Labs:Government-funded facilities require chain-of-custody documentation and specialized degradation-resistant protocols.
- Biotech Companies:Cell therapy developers and synthetic biology firms purchase amplification reagents at scale for manufacturing quality control.
Procurement volume clusters in Research Institutions; Hospitals are gaining share fastest as precision medicine protocols expand.
Delivery Mode:
Margin structure favors consumables, with instrument placement driving recurring reagent pull-through.
- Reagents:Enzymes, buffers, and nucleotides capture the largest margin pools due to batch-to-batch variability sensitivity and limited supplier alternatives for phi29 polymerase.
- Kits:Pre-formulated reaction assemblies reduce laboratory preparation time and standardize results across multi-site studies. Biotech companies in South Korea and Singapore favor certified kit formats for GMP-adjacent workflows.
- Instruments:Thermal cyclers and isothermal amplification platforms face replacement pressure as integrated MDA-sequencing systems displace standalone equipment.
- Software:Bioinformatics pipelines connecting amplification outputs to variant interpretation remain underdeveloped, creating workflow friction.
Kit shipments dominate current volume; Software represents the fastest-climbing category as laboratories demand automated analysis integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina concentrates phi29 polymerase fermentation capacity alongside FDA-cleared amplification kit manufacturing, drawing contract research organizations and precision medicine startups into a tax-advantaged biomedical corridor.
United States
NIH-funded academic medical centers in Boston and San Francisco drive consumable volume through single-cell genomics consortia. FDA oversight of laboratory-developed tests extends commercialization timelines for multiplexed amplification panels. The Research Triangle Park corridor anchors domestic phi29 polymerase fermentation capacity.
Germany
Hospital networks in Bavaria and Baden-Württemberg consolidate purchasing around integrated MDA-sequencing platforms for prenatal testing workflows. EMA In Vitro Diagnostic Regulation implementation forces separation of research-use-only from clinical-validation SKUs. Heidelberg and Munich host reference laboratories scaling multiple displacement amplification for rare disease programs.
China
NMPA fast-track pathways for imported amplification reagents accelerate market entry for hospital networks in Shanghai and Beijing. Domestic biotech firms in Suzhou and Shenzhen build ISO 13485-certified manufacturing capacity for mid-tier diagnostic companies. The Yangtze River Delta cluster concentrates instrument-anchored consumable programs.
Japan
Law enforcement agencies in Tokyo and Osaka adopt multiple displacement amplification for cold case DNA recovery from degraded forensic specimens. METI funding for genomic medicine infrastructure expands core facility placements in Kansai and Kanto regions. Osaka-based forensic institutes standardize chain-of-custody protocols for MDA workflows.
India
CDSCO fast-track approval pathways for imported amplification reagents open access to hospital networks exceeding 75,000 facilities. Diagnostic laboratories in Maharashtra and Karnataka expand PCR capacity for infectious disease panels while evaluating MDA migration. Hyderabad and Bengaluru clusters attract contract manufacturing for GMP-adjacent kit formats.
Whole Genome Amplification Market Competitive Environment
Top-tier vendors anchor instrument-reagent bundling programs, while mid-tier specialists compete on regulatory certification speed and geographic niche penetration. The vendor base stratifies across three tiers: diversified life science conglomerates controlling sequencing instrument installed bases, focused sample preparation specialists integrating with downstream platforms, and regional contract manufacturers building certified capacity for private-label supply. Consolidation pressure intensifies as integrated delivery networks reduce vendor counts to simplify compliance auditing. Strategic moves concentrate on M&A for regulatory dossier acquisition and capacity expansion in ISO 13485-certified fermentation facilities.
Among diversified life science conglomerates, Thermo Fisher Scientific and QIAGEN exemplify contrasting archetypes: the former leverages reagent manufacturing scale for high-volume hospital network supply, while the latter anchors position through specialized sample preparation workflows. Illumina, Inc. occupies a distinct tier controlling instrument placement in core genomic facilities worldwide. These three entities represent the dominant competitive anchors, with their strategic positioning shaping procurement patterns across precision medicine and research segments.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific |
| QIAGEN |
| Sigma-Aldrich |
| PerkinElmer, Inc. |
| Roche Diagnostics |
| Bio-Rad Laboratories |
| Danaher Corporation |
| LGC Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between ISO 13485-validated clinical reagents and research-use consumables manifests in both pricing premiums and supply chain redundancy requirements. Buyers in United States hospital networks absorb 25-40% markups for FDA-cleared SKUs while accepting single-source phi29 polymerase dependencies from Danish and German fermentation facilities.
Pricing Analysis
Short lead-time premiums command 15-30% markups over spot inventory for phi29 DNA polymerase lots, compressing margins for biotech companies with just-in-time manufacturing schedules. The dominant pricing structure runs on tiered premium-standard-economy levels, with FDA 510(k) clearance and EMA MDR certification driving differentiation between clinical and research grades. Cost compression in standard-tier PCR reagents is intensifying because thermal-cycling commoditization attracts Indian and Brazilian diagnostic laboratories. Research institutions show highest price sensitivity due to grant-funded procurement cycles, while cell therapy developers demonstrate lowest sensitivity given GMP-adjacent quality requirements.
Supply Chain Analysis
Single-source vulnerability sits with phi29 DNA polymerase fermentation capacity concentrated in Denmark and Germany, exposing buyers to batch-to-batch variability without qualified secondary suppliers. Raw material dependencies center on recombinant enzyme production, pharmaceutical-grade nucleotides, and sterile buffer formulations. Supply chain risk hinges on regulatory restriction as EMA MDR reclassification forces SKU separation and extended validation timelines. Distribution runs through instrument-anchored consumable programs controlled by sequencing platform vendors, marginalizing standalone reagent suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into phi29 polymerase fermentation represents the decisive upstream lever as vendors race to decouple from Danish and German contract manufacturing dependencies.
For Market Incumbents: Anticipate margin compression from PCR-to-MDA workflow migration by securing captive phi29 production capacity in Research Triangle Park or Bavaria. Defensive consolidation should prioritize ISO 13485-certified kit manufacturers in South Korea to preempt mid-tier diagnostic firms from building internal quality systems. Channel control through instrument-reagent bundling remains essential as integrated delivery networks reduce vendor counts. For New Entrants and Emerging Players: Forensic-grade MDA protocols for degraded DNA recovery offer a technology-first wedge into Japanese law enforcement agencies with specialized chain-of-custody requirements. White-space targets include CDSCO fast-track pathways for India's 75,000-facility hospital network and GMP-adjacent kit formats for Singapore biotech manufacturing. Go-to-market positioning should emphasize point-of-care isothermal platforms bypassing thermal-cycler infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with ISO 13485-certified contract manufacturers given EMA MDR implementation timelines and diagnostic SKU separation mandates. Long-term viability across the analysis window favors entities with backward integration into fermentation capacity or exclusive phi29 supply agreements. Watch FDA premarket submission clearance rates for multiplexed amplification panels as the inflection indicator for clinical diagnostics pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phi29 Fermentation | Captive enzyme production insulates vendors from Danish and German supply concentration risks. |
| FDA 510(k) Clearance Pathway | Clinical validation separates premium-priced diagnostic SKUs from research-use commoditization. |
| EMA MDR Certification Investment | European market access requires SKU separation and quality system documentation. |
| Instrument-Reagent Bundling Program | Sequencing platform control secures recurring consumable pull-through from hospital networks. |
| CDSCO Fast-Track Registration | Indian regulatory pathway opens 75,000-facility hospital network to imported amplification reagents. |
Study Parameters
Multi-period observation of NIH funding disbursements, EMA MDR implementation timelines, and phi29 polymerase procurement patterns anchored the trend analysis, supplemented by interviews with laboratory directors at academic medical centers, regulatory affairs leads at diagnostic kit manufacturers, GPO contracts managers at integrated delivery networks, and fermentation facility operators in Denmark and Germany. Secondary validation drew from FDA 510(k) filings, EMA MDR submissions, CDSCO approval databases, and SEC filings of diversified life science conglomerates. Bottom-up reagent shipment estimates triangulated against top-down precision medicine protocol expansion projections.
Input-output matrices modeled volume and value across technology type, application tier, end-user procurement authority, and geographic regulatory cluster throughout the forecast period. CAGRs derived from segmented growth rate reconciliation against macro healthcare expenditure trends. Industry-specific forecast inputs included single-cell genomics consortium funding cycles and forensic MDA adoption curves in Japanese law enforcement agencies.
Several conditions sit outside the modeled scope, including unforeseen phi29 polymerase manufacturing disruptions, abrupt FDA laboratory-developed test policy reversals, and sequencing platform vendor consolidation beyond current instrument-anchored consumable programs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
DNA Sequencing Services Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Genomic Biomarkers Market
Genomics
Cancer Biomarkers Market
Genomics
United States DNA Sequencing Products Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
DNA Sequencing Market
Genomics
DNA Methylation Market
Genomics
Alagille Syndrome Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
Microarray Biochips Market
Genomics
North America DNA Sequencing Products Market