
 Morgellons Disease Market | 2026-2036
Morgellons Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Morgellons Disease Market Outlook
The WHO's expanding focus on neglected tropical and emerging skin disorders is pivoting research attention toward contested dermatological conditions. Sun Pharmaceutical Industries Ltd. anchors its presence through sustained investment in anti-parasitic and antimicrobial R&D pipelines. Teva Pharmaceutical Industries Ltd. leverages generic manufacturing scale to supply cost-conscious healthcare systems managing symptomatic treatment protocols.
Morgellons disease presents as a dermatological condition characterized by dermal sensations, fiber-like extrusions, and persistent skin lesions, with treatment protocols targeting symptom modulation rather than established etiological pathways. Oral medications dominate current prescribing patterns due to systemic bioavailability and established reimbursement pathways, while topical treatments capture concentrated demand among patients seeking localized relief without systemic exposure. Complementary therapies represent the fastest-expanding category as integrative medicine protocols gain traction within research institutions and specialized clinics.
The FDA maintains oversight of all pharmaceutical interventions, while the NIH's sporadic research initiatives shape funding availability for investigative treatments. Clinicians and developers must monitor evolving diagnostic criteria from dermatological societies and adapt trial endpoints to align with shifting regulatory expectations for contested conditions.
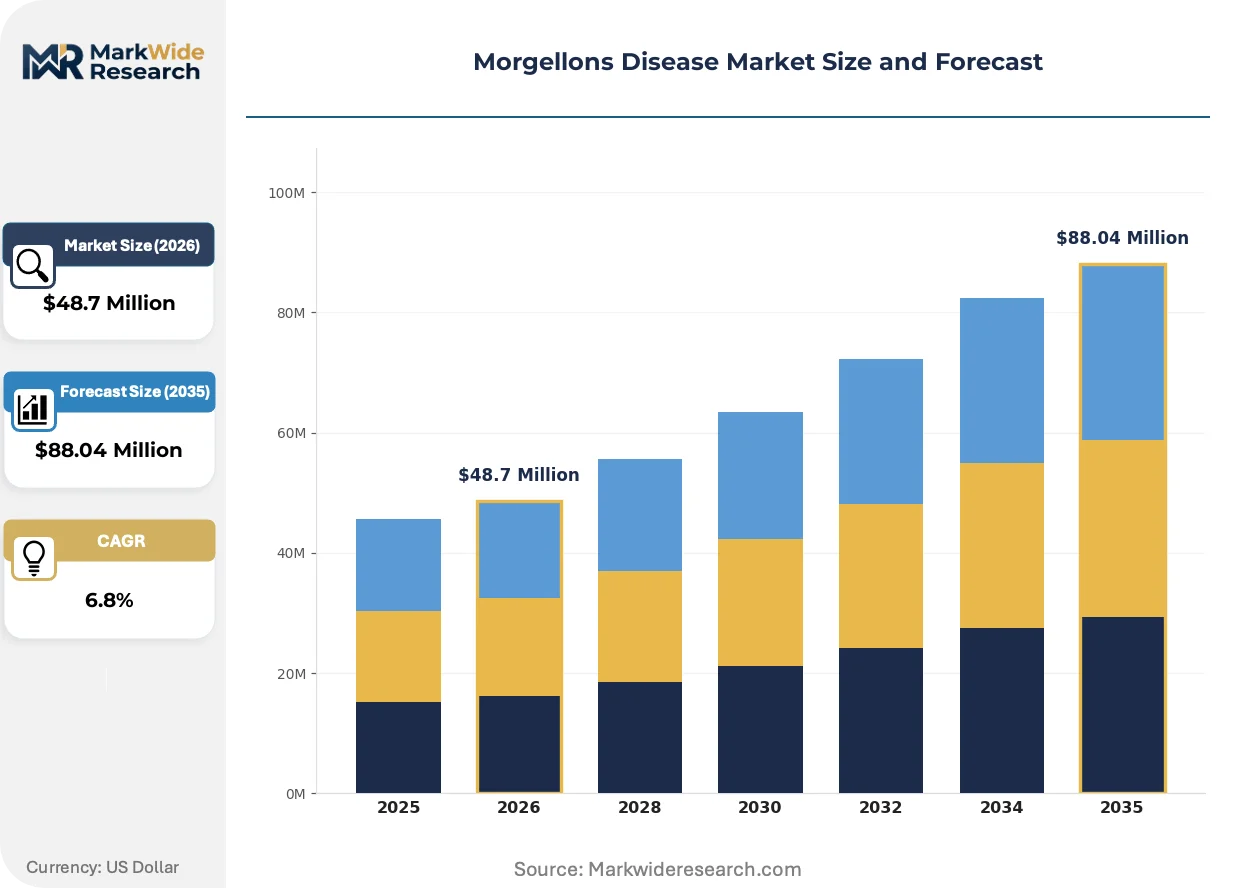
Market Dynamics
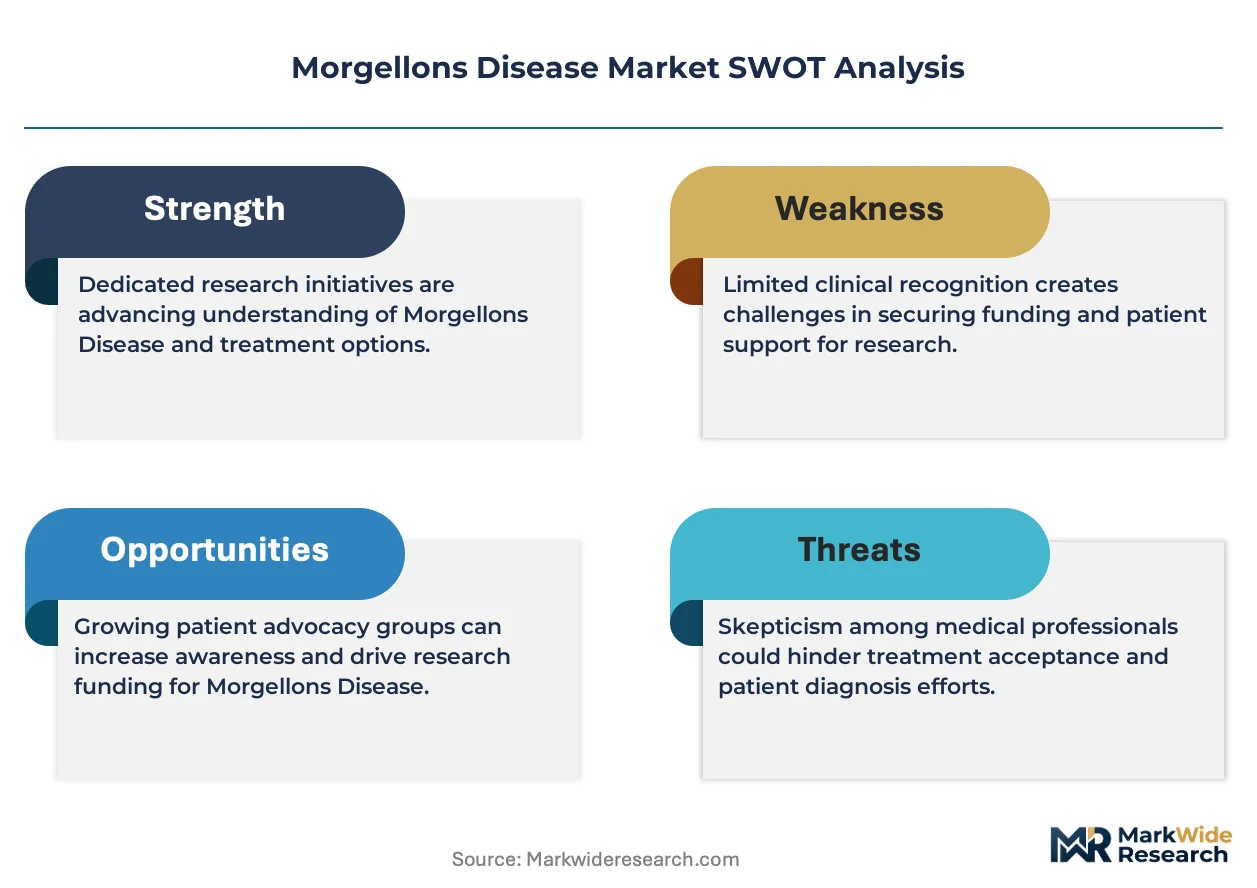
The Morgellons Disease Market is shaped by the tension between patient advocacy networks demanding recognition and medical institutions maintaining diagnostic skepticism, creating fragmented treatment pathways and uneven research funding distribution.
Growth Catalysts
- NIH Research Initiatives:The National Institutes of Health's sporadic funding programs for contested dermatological conditions are legitimizing investigative protocols and attracting academic research centers to the field.
- Telemedicine Expansion:Remote dermatology consultations are connecting geographically dispersed patients with specialized clinicians, reducing diagnostic delays for individuals reporting fiber-like dermal extrusions.
- Complementary Therapy Integration:Integrative medicine protocols at major university hospitals are incorporating symptom management approaches that address the psychodermatological dimensions of patient presentations.
Market Restraints
- Diagnostic Controversy:The absence of ICD-10-CM classification for Morgellons disease blocks standardized insurance reimbursement and limits pharmaceutical investment in targeted drug development.
- Research Funding Volatility:Federal budget cycles create unpredictable NIH allocation patterns, forcing academic researchers to abandon longitudinal studies mid-progress.
- Clinician Skepticism:Dermatological societies' ambiguous position statements deter physician engagement, concentrating willing providers in a handful of specialized clinics across the United States.
Strategic Opportunities
- Biomarker Discovery Programs:Advanced proteomic screening technologies applied to fiber samples could yield objective diagnostic criteria that satisfy FDA evidentiary standards for novel therapeutic indications.
- Patient Registry Infrastructure:Federated data collection networks spanning multiple states would enable natural history studies that attract pharmaceutical development partnerships.
- Medicaid Waiver Pathways:State-level experimental treatment authorizations for contested conditions create reimbursement footholds before federal coverage determinations.
Industry Challenges
- Cross-Disciplinary Training Deficits:Clinicians possessing simultaneous expertise in dermatopathology, infectious disease, and psychodermatology remain exceptionally scarce, constraining trial enrollment capacity.
- Specimen Collection Standardization:The absence of validated protocols for fiber preservation and analysis introduces variability that undermines multi-site study comparability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morgellons Disease Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Medications, Antimicrobial Agents, Complementary Therapies Delivery Mode: Transdermal, Oral, Inhalation, Injection End User: Patients, Healthcare Providers, Research Institutions, Pharmaceutical Companies Treatment Protocol: Conventional Therapy, Alternative Therapy, Symptomatic Relief, Integrated Care |
| Companies Covered | Anant Pharmaceuticals Pvt. Ltd., Sun Pharmaceutical Industries Ltd., Taj Pharmaceuticals Limited, Teva Pharmaceutical Industries Ltd., Pfizer Inc., Lilly USA, LLC, Vasudha Pharma, Novartis AG, Dr. Reddy’s Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morgellons Disease Market Strategic Shifts
Digital pathology platforms and artificial intelligence-assisted dermal imaging are transforming how contested skin conditions are documented and analyzed, shifting diagnostic authority toward quantifiable visual evidence.
Confocal laser scanning microscopy is decentralizing diagnostic capability by enabling high-resolution subsurface skin imaging without invasive biopsy procedures. Community dermatology practices in Texas and California are adopting these systems to capture real-time lesion architecture. This technology is compressing the referral pathway between primary presentation and specialist consultation.
The FDA's evolving guidance on unclassified dermal disorders is forcing pharmaceutical sponsors to redesign trial endpoints around patient-reported outcome measures rather than objective lesion resolution. Developers must now demonstrate symptomatic improvement across multiple domains including pruritus severity and quality-of-life indices. Dermatology CROs specializing in psychodermatology trials are absorbing this regulatory complexity.
Patient-directed research funding is displacing traditional academic grant mechanisms as the primary revenue source for Morgellons-focused investigations. Crowdfunding campaigns organized through dedicated advocacy platforms are underwriting exploratory studies at university medical centers. This shift is most visible in California and Florida, where organized patient networks maintain direct relationships with investigative clinicians.
Morgellons Disease Market Segmentation
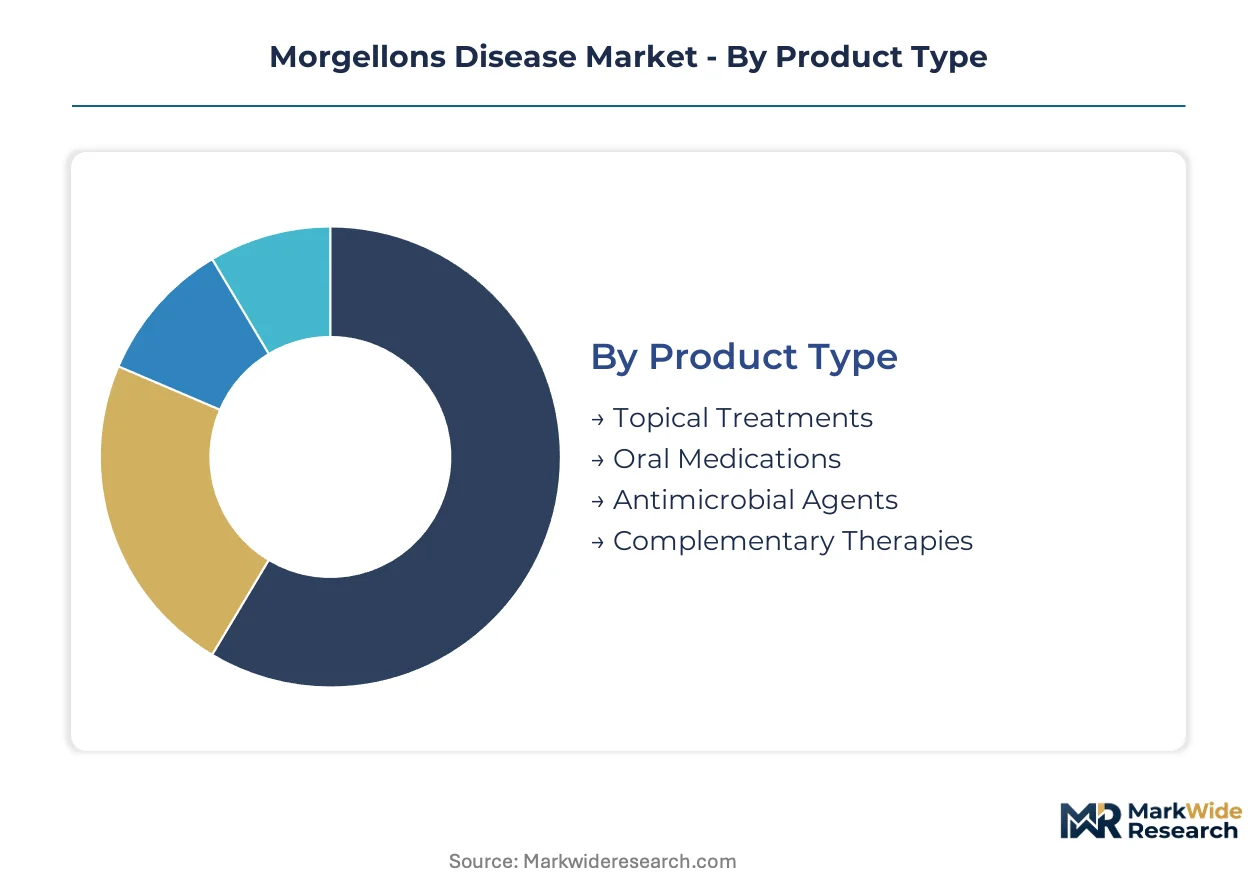
Segmentation in the Morgellons Disease Market reflects the contested diagnostic status of this condition. Treatment protocols fragment across conventional and alternative pathways as clinicians navigate between dermatological intervention and psychodermatological support. Understanding these divisions reveals where pharmaceutical investment concentrates and where patient-directed funding flows.
Product Type:
Prescription patterns shift as patients cycle through symptomatic treatments before finding partial relief, creating upgrade dynamics across formulation categories.
- Oral Medications:Systemic bioavailability drives prescribing volume among dermatologists and infectious disease specialists managing refractory presentations. Demand clusters in California and Texas where specialized clinics maintain established reimbursement relationships with commercial insurers for off-label antidepressant and antiparasitic protocols.
- Complementary Therapies:Integrative medicine departments at university hospitals are incorporating acupuncture, herbal protocols, and nutritional supplementation into formal treatment algorithms. Florida and Arizona patient advocacy networks channel crowdfunding directly to investigators exploring these modalities, bypassing traditional NIH funding mechanisms.
- Topical Treatments:Localized corticosteroid and antimicrobial creams serve patients seeking symptom control without systemic exposure.
- Antimicrobial Agents:Prescription antiparasitics and broad-spectrum antibiotics target suspected infectious etiologies in investigative protocols.
Volume placements concentrate in Oral Medications; the faster expansion belongs to Complementary Therapies.
Delivery Mode:
Route selection tracks patient tolerance thresholds and the availability of compounding pharmacies capable of customizing formulations for contested indications.
- Oral:Tablets and capsules dominate commercial dispensing through retail pharmacy chains with established prior authorization workflows.
- Transdermal:Patches and creams bypass first-pass metabolism for patients reporting gastrointestinal sensitivity to systemic agents.
- Injection:Subcutaneous and intramuscular delivery supports hospital-based protocols for severe presentations requiring supervised administration.
- Inhalation:Nebulized formulations remain experimental, pursued by a handful of research institutions examining respiratory-dermal interaction hypotheses.
Prescription volume favors Oral delivery; Inhalation protocols are climbing the fastest within investigative settings.
End User:
Stakeholder influence over purchasing decisions varies sharply between institutional procurement and individual out-of-pocket expenditure.
- Healthcare Providers:Dermatology clinics and infectious disease practices in the United States drive formulary negotiations for symptomatic management agents. The Cleveland Clinic and Mayo Clinic anchor multi-site prescription patterns through their integrated care networks.
- Patients:Direct-to-consumer expenditure dominates categories lacking ICD-10-CM classification, with individuals in California and Florida spending substantially on compounded formulations and alternative protocols unavailable through standard insurance channels.
- Research Institutions:Academic medical centers procure specialized reagents and imaging technologies for biomarker discovery programs.
- Pharmaceutical Companies:Sponsors acquire diagnostic platforms and patient registry infrastructure to support exploratory trials.
Transaction volume concentrates among Healthcare Providers; the steepest expansion trajectory belongs to direct Patient procurement.
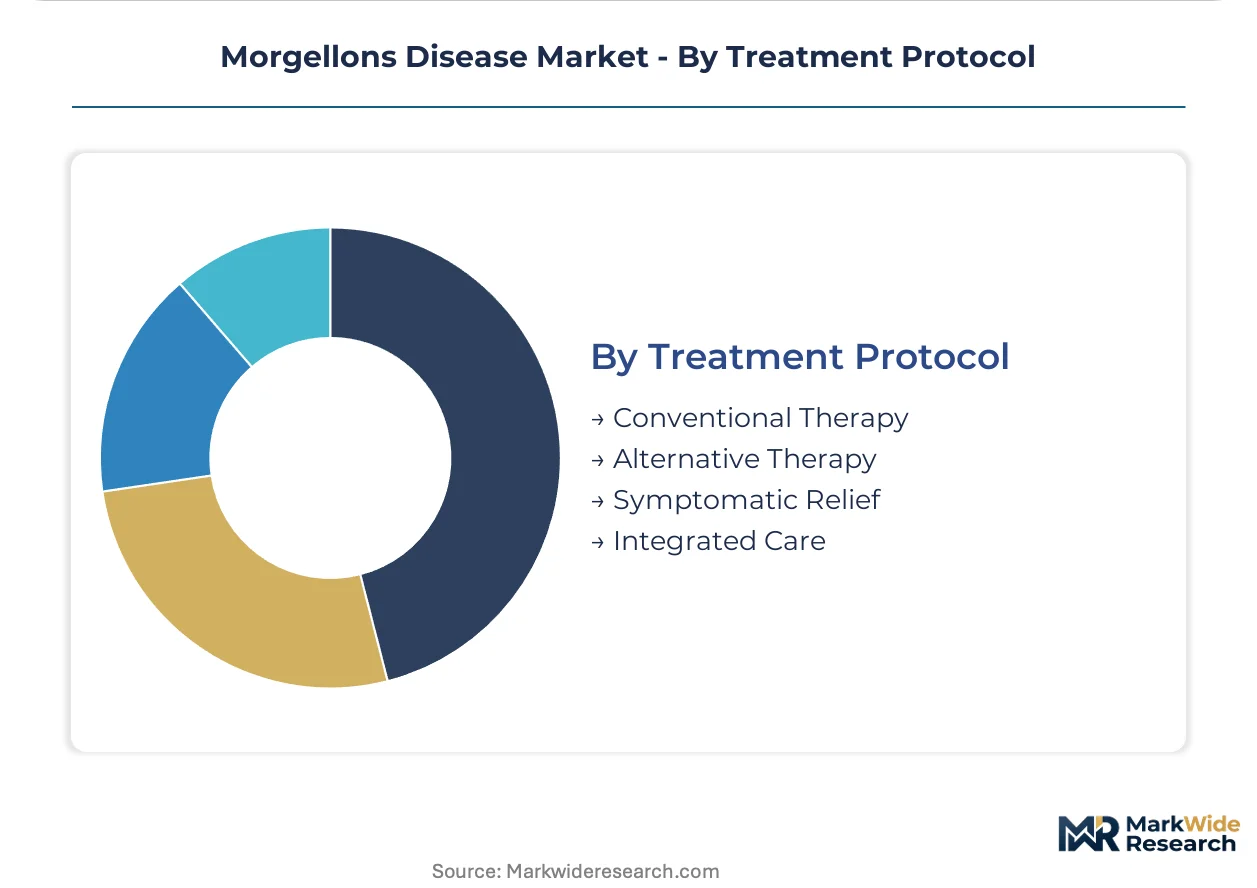
Treatment Protocol:
Protocol selection reflects institutional positioning on the psychodermatology spectrum and willingness to engage contested diagnostic frameworks.
- Symptomatic Relief:Antipruritic and analgesic protocols dominate community dermatology practices seeking to manage patient distress without committing to etiological claims. The University of California San Francisco and University of Miami programs standardize these approaches across affiliated clinics.
- Integrated Care:Coordinated dermatology-psychiatry protocols at Johns Hopkins and Stanford are producing the most comprehensive outcome datasets, attracting pharmaceutical sponsor interest for trial design consultation.
- Conventional Therapy:Standard dermatological interventions target lesion management and secondary infection prevention.
- Alternative Therapy:Non-pharmacological approaches including light therapy and biofeedback operate outside insurance reimbursement structures.
Patient enrollment concentrates in Symptomatic Relief protocols; Integrated Care models are gaining share fastest among research-oriented institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the most concentrated patient advocacy infrastructure for contested dermatological conditions in North America. The metropolitan corridor between Southern California and the Texas Medical Center in Houston generates the majority of documented clinical encounters. Research funding flows through decentralized networks rather than traditional academic channels.
United States
Patient advocacy networks in California and Florida channel crowdfunding directly to university medical centers exploring biomarker discovery. The FDA maintains oversight of all pharmaceutical interventions while the NIH allocates sporadic research grants for contested conditions. Johns Hopkins and Stanford anchor multi-site integrated care protocols that attract pharmaceutical sponsor interest.
Germany
EMA regulatory frameworks for unclassified dermal disorders influence trial design standards adopted across European research institutions. The country's national pharmaceutical regulator evaluates exploratory protocols for symptomatic treatments through centralized assessment procedures. Heidelberg and Berlin host dermatology research clusters examining psychodermatological dimensions of contested presentations.
United Kingdom
NHS commissioning frameworks create uneven access to specialized dermatology services for patients presenting with fiber-like dermal extrusions. The Medicines and Healthcare products Regulatory Agency oversees compassionate use pathways for off-label protocols in refractory cases. London's academic medical centers maintain observational registries that feed into European natural history datasets.
Canada
Health Canada guidance on unclassified conditions shapes provincial coverage determinations for symptomatic management agents. Provincial health authorities in Ontario and British Columbia fund limited investigative protocols through academic research grants. Toronto's dermatology residency programs incorporate contested condition presentations into psychodermatology training curricula.
Australia
TGA regulatory pathways for novel dermatological indications attract exploratory trial proposals from Asia-Pacific sponsors. Medicare reimbursement gaps force substantial out-of-pocket expenditure for patients seeking specialized consultations. Sydney and Melbourne host the primary clinical research infrastructure for skin disorder investigations in the Southern Hemisphere.
Morgellons Disease Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with established dermatology and psychiatric portfolios. Market concentration remains moderate as no single developer maintains a dedicated Morgellons-specific pipeline. Three strategic archetypes dominate: generic manufacturers supplying off-label protocols, branded pharmaceutical firms with psychodermatology expertise, and emerging biotech ventures pursuing biomarker-driven approaches. Competitive moves center on portfolio diversification into contested indications and strategic partnerships with patient advocacy networks for trial recruitment.
Among India-based pharmaceutical manufacturers, Sun Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd. occupy positions within the generic supply archetype for symptomatic management agents. Teva Pharmaceutical Industries Ltd. represents the scale-driven manufacturing tier serving cost-conscious healthcare systems. These entities exemplify how geographic manufacturing concentration supports decentralized prescribing patterns across North American and European markets.
| Leading Market Players |
|---|
| Anant Pharmaceuticals Pvt. Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Taj Pharmaceuticals Limited |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Lilly USA, LLC |
| Vasudha Pharma |
| Novartis AG |
| Dr. Reddy's Laboratories Ltd. |
| Others |
Value Chain & Pricing Dynamics
Patient-directed procurement networks in California and Florida anchor demand concentration for compounded formulations and alternative protocols, sustaining premium pricing tiers for treatments lacking ICD-10-CM classification and standard insurance reimbursement pathways.
Pricing Analysis
Value-based pricing anchors on symptomatic relief outcomes rather than etiological resolution, with cost differentiation driven by FDA oversight status and compounding pharmacy certification tiers. Pricing pressure intensifies as generic manufacturers scale production of off-label antiparasitic and antidepressant protocols for cost-conscious healthcare systems. Research institutions exhibit the lowest price sensitivity due to grant-funded procurement, while individual patients face the highest burden from direct out-of-pocket expenditure on unclassified condition treatments.
Supply Chain Analysis
FDA and EMA qualification requirements gate active pharmaceutical ingredient sourcing from India, China, and the United States, with specialized compounding pharmacies serving as critical intermediaries for customized formulations. Supply chains draw from antimicrobial and psychotropic compound feedstocks, with fiber analysis reagents and confocal imaging equipment adding specialized procurement layers. Single-source vulnerability concentrates in certified compounding facilities serving contested diagnostic indications. Distribution runs through hospital-based specialty pharmacies and direct-to-patient compounding networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Morgellons Disease Market operates as a vertical-integration race where control over patient registry infrastructure and biomarker discovery platforms determines competitive positioning, with upstream leverage residing in federated data collection networks that attract pharmaceutical development partnerships.
For Market Incumbents: Deploy patient advocacy relationship deepening to secure trial enrollment pipelines against emerging biotech ventures pursuing biomarker-driven approaches. Incumbent pharmaceutical conglomerates should consolidate positions in psychodermatology expertise while adding compounding pharmacy partnerships to capture direct-to-patient revenue streams currently flowing to alternative protocol providers. For New Entrants and Emerging Players: Launch via telemedicine-integrated distribution models targeting the Texas Medical Center and Southern California corridor where diagnostic protocol adoption concentrates fastest. White-space opportunities sit in Medicaid waiver pathway navigation and AI-assisted dermal imaging platforms for community dermatology practices seeking to compress referral timelines without specialist consultation dependency. For Investors and Strategic Acquirers: The window for entry favors vertically integrated platforms combining patient registry infrastructure with diagnostic technology assets. Long-term viability hinges on biomarker discovery validation that satisfies FDA evidentiary standards for contested condition therapeutic indications. The inflection signal to monitor is NIH funding allocation stabilization that would enable longitudinal study completion and pharmaceutical sponsor commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Discovery Program | FDA validation of objective diagnostic criteria would unlock pharmaceutical development partnerships and standardize trial endpoints. |
| Patient Registry Infrastructure | Federated data networks spanning California, Texas, and Florida enable natural history studies that attract sponsor investment. |
| Telemedicine Platform Integration | Remote dermatology consultations reduce diagnostic delays for geographically dispersed patients reporting fiber-like dermal extrusions. |
| Compounding Pharmacy Partnership | Direct-to-patient formulation access captures revenue currently flowing to alternative protocol providers outside insurance channels. |
| Medicaid Waiver Navigation | State-level experimental treatment authorizations create reimbursement footholds before federal coverage determinations for contested conditions. |
Study Parameters
FDA filings, ClinicalTrials.gov records, and NIH grant databases formed the secondary backbone, cross-referenced with primary interviews involving dermatology clinic directors, compounding pharmacy operators, patient advocacy network coordinators, and regulatory affairs specialists at pharmaceutical sponsors. Bottom-up prescription volume modeling and top-down healthcare expenditure triangulation validated segmentation outputs across treatment protocols and delivery modes.
Historical trendline analysis of symptomatic management agent prescribing patterns informed projection frameworks across the analysis window, with segmentation modeling incorporating product type, delivery mode, end user category, and treatment protocol dimensions. CAGRs were derived from volume-weighted growth trajectory synthesis, with forecast inputs including telemedicine adoption curves and complementary therapy integration rates at university medical centers.
Diagnostic criteria revision, NIH funding allocation volatility, and FDA guidance evolution on unclassified dermal disorders are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in biomarker discovery validation status or patient registry infrastructure deployment scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
X-Linked Hypophosphatemia Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Cancer RNA Expression Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
Testicular Cancer Drugs Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market