
 Insulin Management System Market | 2026-2036
Insulin Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin Management System Market Foresight
Modular pump-and-sensor bundling is restructuring how patients and payers evaluate total cost of therapy. Medtronic leverages integrated closed-loop platforms to anchor its position in tethered systems. Insulet Corporation specializes in tubeless patch pump architectures that reduce training burden. Dexcom competes through transmitter-agnostic sensor designs that pair with multiple insulin delivery devices.
An insulin management system comprises devices, software, and disposable interfaces that measure glucose, calculate dosing algorithms, and deliver insulin with defined accuracy thresholds typically within 15 mg/dL for continuous monitors. These systems serve the commercial purpose of reducing glycemic variability and preventing hypoglycemic events in ambulatory and acute settings. Continuous glucose monitors command the largest installed base among product types, while mobile health solutions represent the fastest-expanding margin pool as cloud integration enables remote dose titration by clinicians. Homecare end users generate the highest volume demand, though hospitals retain premium pricing power for inpatient hyperglycemia protocols.
FDA interoperability standards, the EU Medical Device Regulation, and Japan's PMDA software-as-medical-device guidance collectively determine which platforms achieve market access and reimbursement eligibility. FDA's iCGM classification creates a de facto technical bar that filters out non-interoperable sensors, while MDR clinical evidence requirements extend approval timelines for European entrants. Stakeholders must monitor whether emerging automated dosing algorithms trigger new premarket review categories as software autonomy crosses regulatory thresholds.
Market Dynamics
Interoperability mandates from the FDA's iCGM classification are forcing device manufacturers to abandon proprietary sensor-pump pairings and adopt open-architecture glucose data standards that enable third-party algorithm integration.
Growth Catalysts
- Homecare Self-Management:Patients with type 1 diabetes in the United States are migrating from clinical settings to ambulatory pump-and-sensor systems that support remote dose titration. Reimbursement codes for continuous glucose monitors now cover non-intensive insulin users, expanding addressable populations.
- MDR Clinical Evidence Pathways:The EU Medical Device Regulation's post-market surveillance requirements are accelerating real-world evidence collection that validates closed-loop algorithm performance. This regulatory framework creates competitive moats for systems with established safety databases.
- Tubeless Patch Pump Adoption:Wearable pump architectures eliminate infusion set management burdens that previously limited patient adherence. Endocrinology practices in Germany report reduced nursing support hours following patch pump deployment.
Market Restraints
- Disposable Supply Concentration:Sensor manufacturing for continuous glucose monitors depends on limited suppliers of glucose-oxidase enzyme formulations, creating vulnerability to batch variability and price volatility in the enzyme input market.
- FDA Premarket Review Burden:Automated insulin dosing algorithms that cross autonomy thresholds trigger de novo classification pathways that extend development timelines by 18-24 months compared to predicate device clearances.
- Substitution by Non-Pharmacologic Interventions:Beta-cell replacement therapies and stem-derived islet transplantation programs in academic medical centers threaten long-term demand for exogenous insulin delivery systems among select patient cohorts.
Strategic Opportunities
- Underpenetrated Type 2 Intensive Insulin Users:Japan's aging diabetes population remains underserved by advanced insulin delivery despite high CGM penetration in type 1, creating whitespace for simplified closed-loop systems with reduced training requirements.
- Cloud-Integrated Dose Advisory Services:Software-as-medical-device platforms that enable clinician-supervised remote algorithm adjustments represent a recurring revenue model distinct from capital equipment sales.
- Dual-Hormone System Convergence:Integration of glucagon delivery modules with existing insulin pump infrastructure addresses hypoglycemia risk that limits algorithm aggressiveness in current single-hormone configurations.
Industry Challenges
- Algorithm Validation Talent Scarcity:Development of safe automated dosing systems requires rare expertise combining endocrinology clinical knowledge with control systems engineering, constraining R&D velocity for mid-tier device manufacturers.
- Legacy EHR Integration Complexity:Hospital procurement committees demand seamless data flow between insulin delivery devices and existing electronic health record architectures, forcing vendors to maintain costly interface engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin Management System Market |
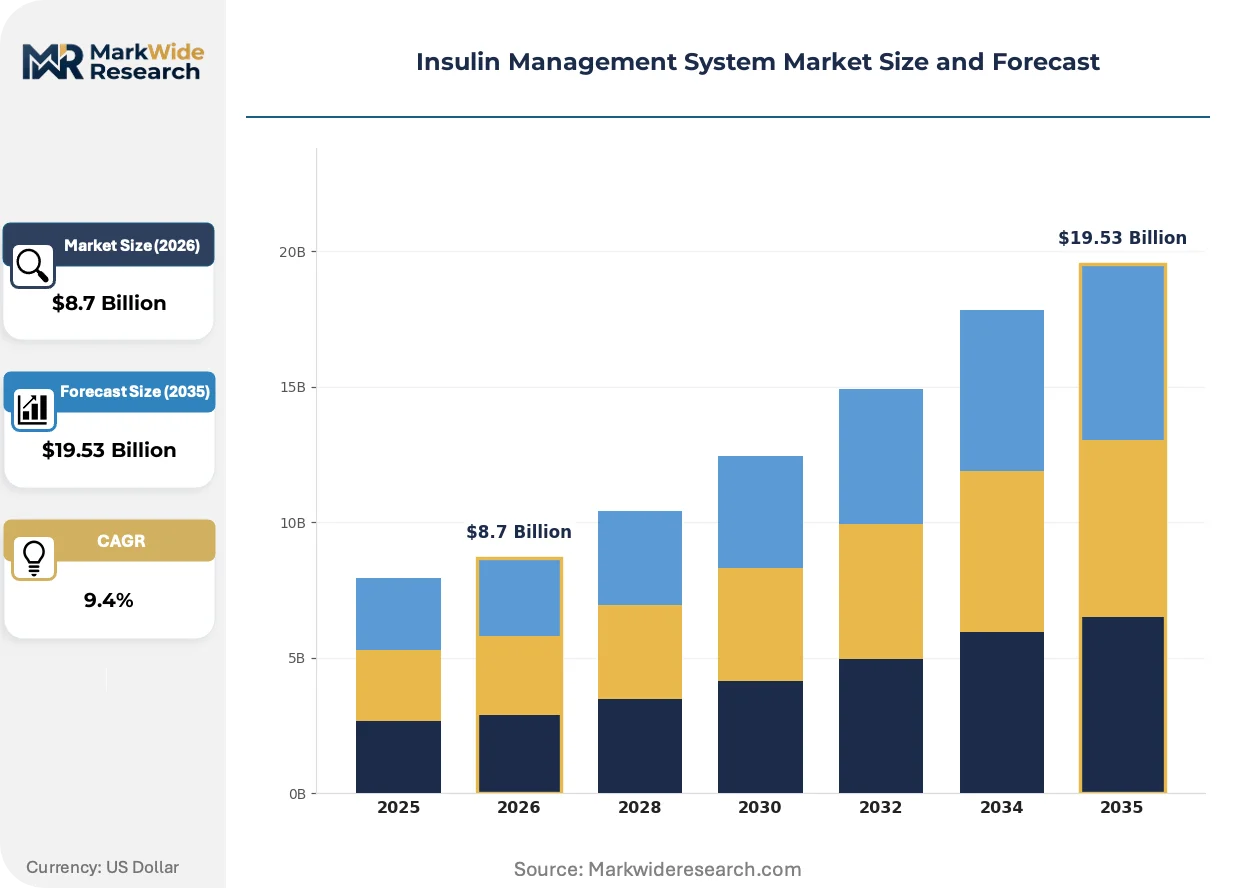
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Pens, Continuous Glucose Monitors, Insulin Pumps, Mobile Apps Delivery Mode: Subcutaneous, Intravenous, Inhalation, Oral End User: Homecare, Hospitals, Diabetes Clinics, Long-term Care Facilities Technology: Automated Dosing, Cloud Integration, Wearable Devices, Mobile Health Solutions |
| Companies Covered | Medtronic, Insulet Corporation, Tandem Diabetes Care, Hoffmann-La Roche, Abbott Laboratories, Ypsomed, Novo Nordisk, Dexcom, Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin Management System Market Shifts & Advancements
Algorithmic autonomy is advancing faster than liability frameworks can adapt, creating tension between clinical efficacy gains and prescriber comfort with unsupervised dosing decisions.
Artificial pancreas systems are unifying glucose sensing, predictive algorithms, and insulin delivery into single-platform architectures that reduce patient cognitive burden. Pediatric endocrinology centers in the United States are adopting these integrated systems at accelerating rates as caregiver confidence builds. This convergence is unifying what were previously separate device procurement decisions into bundled therapy contracts that lock in multi-year disposable revenue streams.
The EU Medical Device Regulation's software classification guidance is redefining which algorithm updates require new conformity assessments. Manufacturers must now distinguish between cosmetic interface changes and functional modifications affecting dose calculations. Systems with machine-learning components face heightened scrutiny in Germany and France, where notified bodies demand explicit validation protocols for adaptive algorithm behavior.
Patients are consolidating purchasing decisions around ecosystem compatibility rather than standalone device performance. Retail pharmacy channels in the United States are displacing traditional durable medical equipment suppliers as primary distribution points for sensor-and-supply resupply. This channel migration is most visible in Medicare Advantage populations where payers steer members toward preferred formulary configurations with integrated remote monitoring benefits.
Insulin Management System Market Segmentation
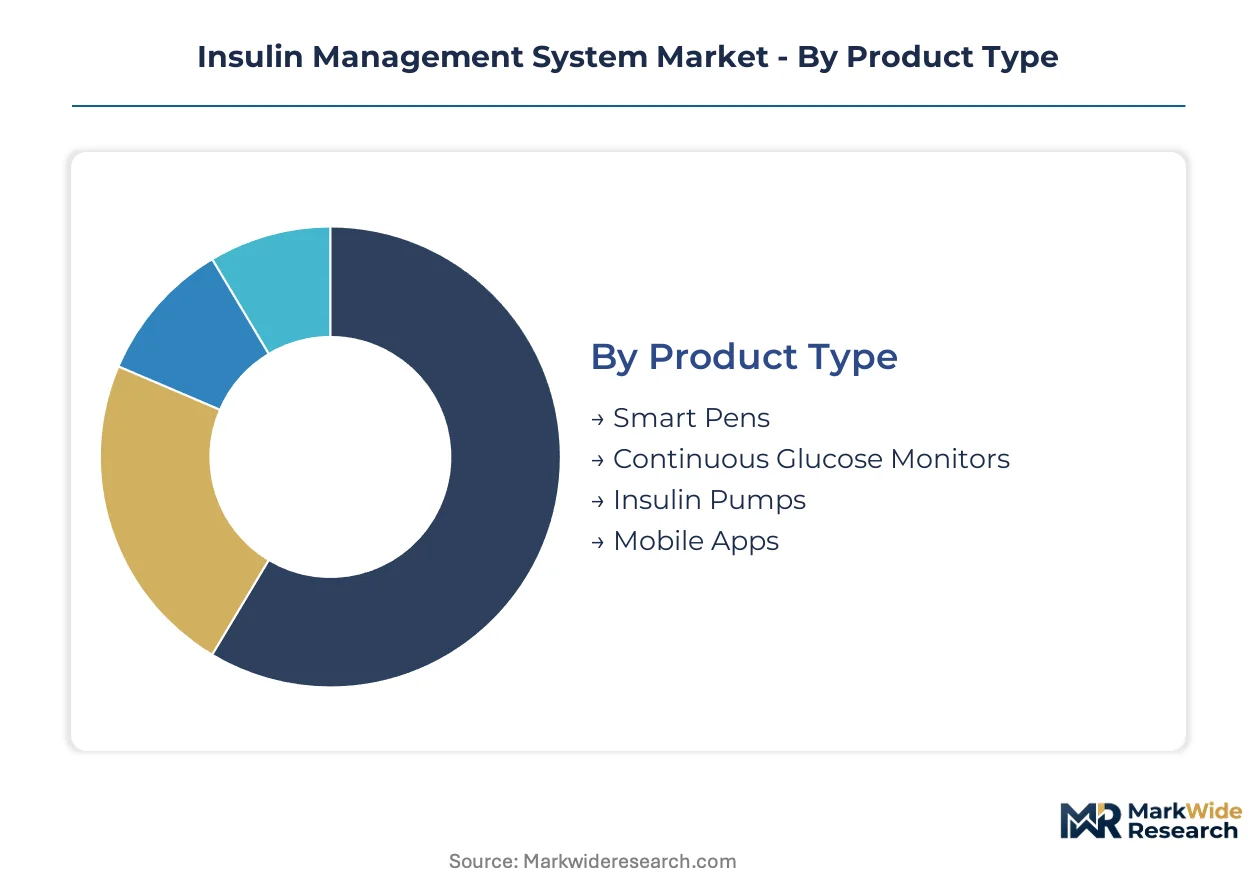
Insulin management systems fragment across four distinct axes that determine capital deployment, reimbursement pathways, and competitive moats. Product type and technology layers command the highest R&D intensity, while delivery mode and end-user configuration dictate distribution economics and regulatory burden.
Product Type:
Capital intensity peaks with integrated closed-loop platforms requiring sensor-pump-algorithm convergence, while disposable-centric segments demand manufacturing scale rather than upfront development spend.
- Continuous Glucose Monitors:Electrochemical sensors with glucose-oxidase enzyme layers transmit interstitial glucose readings every 1-5 minutes via radio frequency to receivers or smartphones. Demand concentrates in Medicare Advantage populations across the United States where reimbursement codes now cover non-intensive insulin users, though sensor manufacturing depends on limited enzyme formulation suppliers creating input volatility.
- Insulin Pumps:Motor-driven reservoir systems deliver basal and bolus insulin through subcutaneous infusion sets with programmable dosing algorithms. Tethered systems anchor hospital procurement in Germany, while tubeless patch architectures reduce nursing support hours in ambulatory settings.
- Smart Pens:Bluetooth-enabled injection devices log dose timing and volume for clinician review. These devices bridge multiple daily injection patients toward digital tracking without pump commitment.
- Mobile Apps:Software platforms aggregate glucose data, carbohydrate logging, and insulin dose calculations for pattern recognition. FDA software-as-medical-device guidance determines which algorithm features trigger premarket review.
Continuous Glucose Monitors absorb the bulk of installed capacity; Mobile Apps are expanding most quickly.
Delivery Mode:
Route of administration determines biopharmaceutical stability requirements, device engineering constraints, and the regulatory classification of combination products.
- Subcutaneous:Insulin absorption through adipose tissue via infusion sets or injection needles remains the dominant delivery pathway. Patch pump adoption in Germany's endocrinology practices demonstrates reduced training burden versus traditional tethered systems.
- Intravenous:Direct bloodstream delivery enables rapid glycemic control in acute care settings. Intensive care units in Japan's tertiary hospitals retain premium pricing for these inpatient hyperglycemia protocols.
- Inhalation:Pulmonary insulin delivery bypasses injection burden but requires lung function screening. Limited commercial penetration reflects reimbursement restrictions and physician familiarity gaps.
- Oral:Gastrointestinal insulin formulations face enzymatic degradation challenges that constrain bioavailability. Development programs focus on permeation enhancers and protective encapsulation technologies.
Subcutaneous systems command the dominant share of ambulatory volume; Intravenous delivery maintains the steepest pricing premium per patient-day.
End User:
Procurement authority and reimbursement mechanisms diverge sharply between institutional purchasers and individual patients, reshaping sales force deployment and channel strategy.
- Homecare:Patients self-manage pump-and-sensor systems with remote clinician oversight. United States reimbursement expansion to non-intensive insulin users is broadening addressable populations beyond traditional type 1 diabetes.
- Hospitals:Inpatient hyperglycemia protocols demand seamless EHR integration that forces vendors to maintain costly interface engineering teams. Procurement committees prioritize data flow compatibility over standalone device performance.
- Diabetes Clinics:Specialized endocrinology practices serve as adoption gatekeepers for advanced system upgrades. These settings generate concentrated influence on patient device selection.
- Long-term Care Facilities:Skilled nursing environments face staff turnover challenges that complicate device training and troubleshooting. Simplified closed-loop systems with reduced interface complexity address this constraint.
Homecare settings generate the highest absolute volume; Diabetes Clinics concentrate the strongest influence on technology migration decisions.
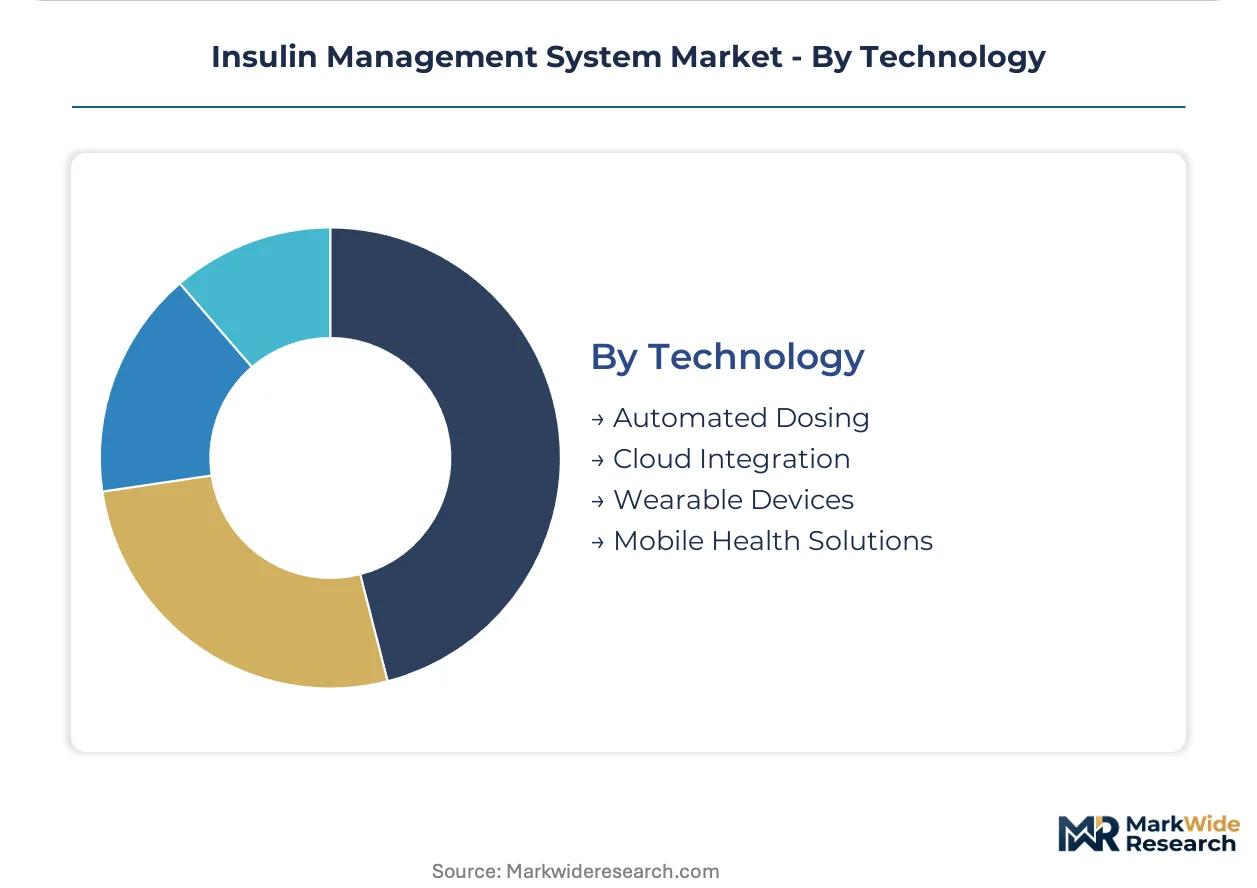
Technology:
Software autonomy levels determine regulatory classification burden, with machine-learning components triggering heightened scrutiny from notified bodies in Germany and France.
- Automated Dosing:Closed-loop algorithms adjust insulin delivery based on predictive glucose models without patient initiation. FDA de novo classification pathways extend development timelines when autonomy thresholds cross into unsupervised dosing.
- Cloud Integration:Remote data repositories enable clinician-supervised dose titration and algorithm adjustments. This architecture supports recurring revenue models distinct from capital equipment sales.
- Wearable Devices:Skin-adherent pump and sensor form factors eliminate tubing and reduce physical burden. Tubeless architectures are displacing traditional durable medical equipment suppliers in United States retail pharmacy channels.
- Mobile Health Solutions:Smartphone-based platforms aggregate multi-device data streams for pattern visualization and decision support. Japan's PMDA software-as-medical-device guidance shapes which features achieve market access.
Automated Dosing captures the dominant share of R&D investment; Cloud Integration is climbing the fastest as payers steer members toward remote monitoring benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in the United States and Germany while patient demand spreads across aging populations in Japan and reimbursement-expanding markets. Production of glucose-oxidase sensors and precision pump motors tilts toward established med-tech corridors, whereas consumption patterns track diabetes prevalence and payer willingness to cover closed-loop systems.
United States
Medicare Advantage plans now reimburse continuous glucose monitors for non-intensive insulin users, broadening addressable populations beyond traditional type 1 diabetes. FDA's iCGM interoperability classification creates technical barriers that filter out non-compliant sensors from market access. Minneapolis and Boston med-tech clusters anchor sensor-pump integration R&D, with Massachusetts General Hospital protocols influencing national adoption standards for automated dosing algorithms.
Germany
Endocrinology practices report reduced nursing support hours following tubeless patch pump deployment in ambulatory settings. EU Medical Device Regulation post-market surveillance requirements accelerate real-world evidence collection that validates closed-loop performance. Baden-Württemberg's precision engineering corridor supplies electrochemical sensor components to device manufacturers across the Rhine-Neckar metropolitan region.
Japan
Aging type 2 diabetes populations remain underserved by advanced insulin delivery despite high CGM penetration in type 1, creating whitespace for simplified closed-loop systems. PMDA software-as-medical-device guidance shapes which algorithm features achieve market access and reimbursement eligibility. Tokyo and Osaka diabetes clinics serve as gatekeepers for technology upgrades, with Kansai region hospitals piloting dual-hormone system protocols.
United Kingdom
NHS England's technology appraisal pathways determine which integrated systems receive formulary placement in secondary care trusts. MHRA alignment with EU MDR software classification creates parallel regulatory burdens for algorithm updates. London's academic medical centers concentrate artificial pancreas clinical trials, while Manchester and Birmingham procurement committees prioritize EHR integration compatibility in hospital purchasing decisions.
Switzerland
Swissmedic's medical device conformity assessment procedures attract manufacturers seeking streamlined European market entry for novel pump architectures. Basel's pharmaceutical-device convergence corridor hosts engineering talent pools that span insulin formulation and delivery mechanism development. Zurich canton hospitals maintain premium pricing power for inpatient hyperglycemia protocols requiring intravenous delivery systems.
Insulin Management System Market Competitive Landscape
The competitive structure tilts toward integrated platform providers with established safety databases and interoperable sensor architectures. Market concentration is pronounced at the top tier where closed-loop systems command bundled therapy contracts, while mid-tier players compete on single-device performance metrics. Two strategic archetypes dominate: diversified med-tech conglomerates leveraging hospital procurement relationships, and diabetes-focused specialists capturing ambulatory self-management demand. Competitive moves center on algorithm licensing partnerships and disposable supply chain captive integration.
Within the integrated-system tier, Medtronic and Tandem Diabetes Care exemplify platform convergence strategies that unify sensing, algorithm, and delivery into single-vendor ecosystems. Dexcom occupies a position as a sensor-agnostic supplier whose transmitter designs pair across multiple insulin delivery devices, representing the interoperability-focused archetype that FDA iCGM standards favor. Among European-based manufacturers, Ypsomed anchors the tubeless patch pump segment with Swiss engineering heritage, while Roche's diagnostics division sits within the diversified conglomerate tier leveraging hospital laboratory relationships for glucose monitoring cross-selling.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Tandem Diabetes Care |
| Hoffmann-La Roche |
| Abbott Laboratories |
| Ypsomed |
| Novo Nordisk |
| Dexcom |
| Braun SE |
| Others |
Supply & Pricing Matrix
Medicare Advantage formulary expansions covering non-intensive insulin users are forcing manufacturers to absorb higher patient acquisition costs while maintaining sensor-pump bundle affordability, compressing margins across ambulatory product tiers and accelerating supply chain rationalization toward captive enzyme formulation production.
Pricing Analysis
Cost-down pressure on integrated closed-loop systems accelerates because FDA interoperability mandates eliminate proprietary sensor-pump premiums. Pricing stratifies across premium closed-loop bundles, standard tethered pump configurations, and economy smart pen tiers. Brand premium and FDA iCGM certification tier drive differentiation. Margin tightening in disposable sensors reflects glucose-oxidase enzyme input volatility. Homecare patients show highest price sensitivity; hospital procurement committees prioritize EHR integration over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from notified bodies under EU MDR are compelling manufacturers to qualify secondary glucose-oxidase enzyme suppliers beyond the dominant Swiss and German specialty chemical houses. Manufacturing concentrates in the United States, Germany, and Switzerland. Electrochemical sensor membranes, precision pump motors, and biocompatible adhesives constitute critical input dependencies. Single-source vulnerability in enzyme formulation supply creates exposure to batch variability. Distribution runs through retail pharmacy channels displacing traditional durable medical equipment suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
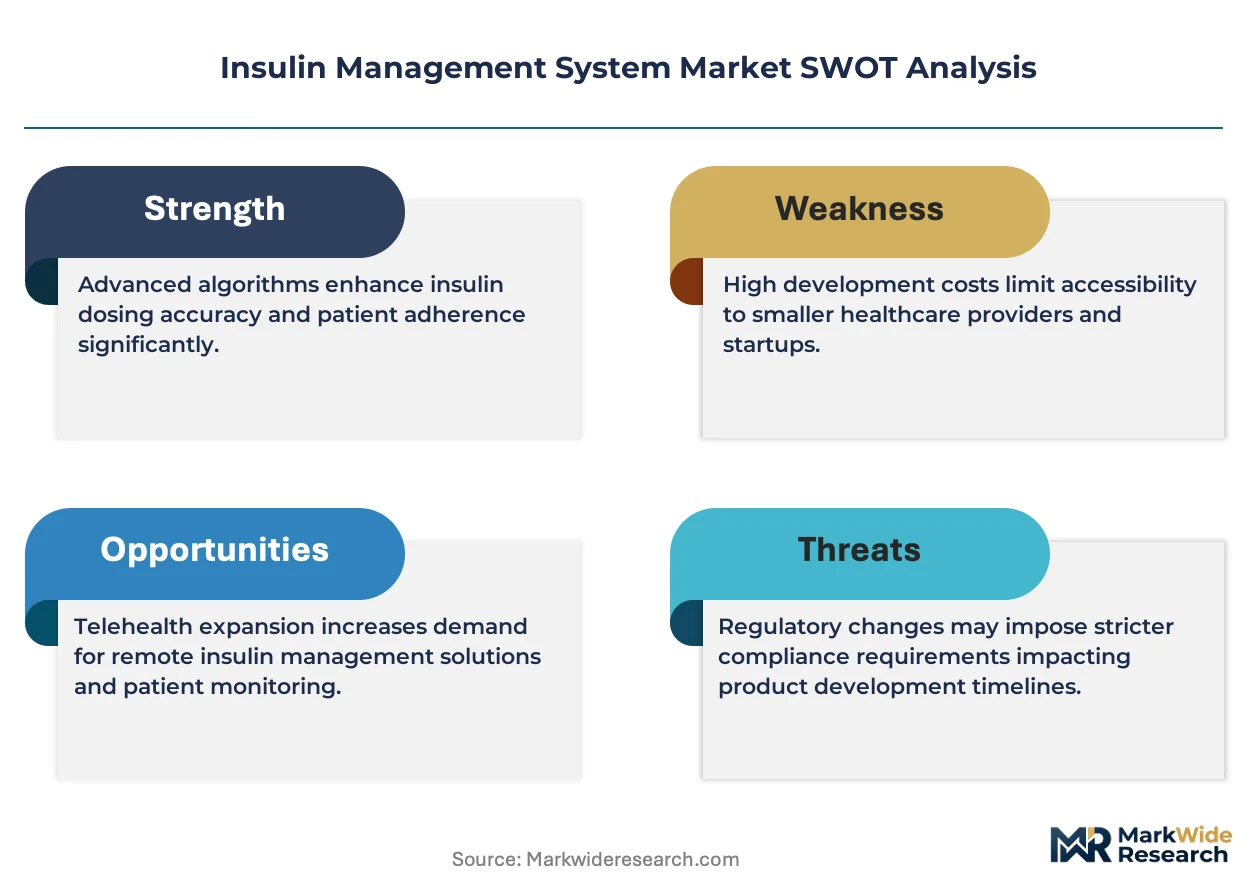
The insulin management system market is consolidating around integrated platform providers with established FDA safety databases, as algorithm validation talent scarcity and extended premarket review timelines force mid-tier device manufacturers toward exit or acquisition.
For Market Incumbents: Acquire specialized control systems engineering teams to address algorithm validation bottlenecks constraining R&D velocity. Deepen backward integration into glucose-oxidase enzyme formulation production to neutralize supply concentration risk. Secure long-term Medicare Advantage formulary placement through bundled remote monitoring service contracts. For New Entrants and Emerging Players: Cloud-native dose advisory platforms with simplified clinician interfaces represent the most penetrable wedge for Japan's aging type 2 diabetes population underserved by advanced insulin delivery. Target long-term care facilities with staff turnover challenges through reduced-complexity closed-loop systems. Pursue hospital procurement committee relationships emphasizing seamless EHR data flow compatibility. For Investors and Strategic Acquirers: Re-rating potential sits with sensor-agnostic platform providers given FDA iCGM interoperability standards favoring open-architecture glucose data exchange. Long-term viability centers on recurring software-as-medical-device revenue models decoupled from capital equipment cycles. Watch for PMDA software classification guidance clarifications as the inflection signal for Japan market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Partnership | Control systems engineering scarcity makes acquired talent pools immediately deployable across multiple device portfolios. |
| CE Marking Pathway Investment | EU MDR post-market surveillance requirements create competitive moats for systems with established clinical evidence databases. |
| Hospital System Partnership | EHR integration demands from procurement committees lock in multi-year disposable revenue through bundled therapy contracts. |
| Software Companion Development | Cloud-integrated dose advisory services enable recurring revenue models distinct from capital equipment sales cycles. |
| Reimbursement Strategy Execution | Medicare Advantage coverage expansion to non-intensive insulin users broadens addressable populations beyond traditional type 1 diabetes. |
Research Methodology
Multi-period observation of FDA 510(k) and de novo clearance trajectories anchored the trend analysis, supplemented by interviews with endocrinologists, hospital biomedical engineers, GPO contracts managers, and diabetes clinic practice administrators. Secondary validation drew from FDA MAUDE adverse event databases, CMS Medicare claims data, EU MDR notified body guidance documents, and PMDA software-as-medical-device consultation minutes. Bottom-up sensor-pump shipment modeling and top-down reimbursement code valuation triangulated market sizing.
Input-output matrices mapped continuous glucose monitor, insulin pump, smart pen, and mobile app volumes against homecare, hospital, diabetes clinic, and long-term care facility end-user demand across the projection horizon. Segmentation dimensions included product type, delivery mode, technology autonomy level, and regional regulatory cluster. CAGRs derived from algorithm adoption curve analysis and payer coverage expansion trajectories. Forecast inputs incorporated glucose-oxidase enzyme supply constraints and FDA premarket review timeline distributions.
Several conditions sit outside the modeled scope, including stem-derived islet transplantation program commercialization timelines and beta-cell replacement therapy regulatory approvals. Forecasts reflect documented assumptions regarding interoperability standard adoption rates and cloud infrastructure reliability. Deviation in FDA automated dosing algorithm classification thresholds or EU MDR notified body capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Vanishing Bone Disease Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Anti-Cathepsin B Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Medroxyprogesterone Market
Medical Biotechnology
Testicular Cancer Drugs Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market