
 Global Prostate Specific Antigen (PSA) Test Market | 2026-2036
Global Prostate Specific Antigen (PSA) Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prostate Specific Antigen (PSA) Test Market Foresight
Silicon-based microfluidic substrates are hardening as the preferred material foundation for next-generation PSA assay platforms, displacing legacy polystyrene well-plate formats. Abbott leverages vertical integration across immunoassay reagent manufacturing to sustain cost advantages in high-throughput diagnostics. Roche differentiates through electrochemiluminescence technology leadership, anchoring premium positioning in automated laboratory systems. Beckman Coulter competes on manufacturing scale, occupying substantial installed-base share in North American hospital laboratories.
Prostate Specific Antigen (PSA) Test denotes a clinical immunoassay measuring glycoprotein kallikrein-3 in serum or plasma, typically quantified in nanograms per milliliter using antibody-antigen binding with enzymatic or chemiluminescent detection. The test serves primary industrial purpose in prostate cancer screening, treatment response monitoring, and biochemical recurrence detection. Total PSA Test and Free PSA Test categories dominate current volume, with Complexed PSA Test representing the fastest-growing segment as laboratories seek improved specificity for intermediate-risk patients. Chemiluminescence Immunoassay technology leads value generation, while ELISA maintains residual presence in resource-constrained settings where instrument capital is limited.
FDA 510(k) clearance pathways and CLIA laboratory certification requirements shape product development timelines and commercial access for PSA test manufacturers. EMA's In Vitro Diagnostic Regulation (IVDR) is forcing European market participants to rebuild technical documentation and clinical evidence packages. ISO 13485 quality management standards govern manufacturing consistency across multinational supply chains. Stakeholders must monitor evolving USPSTF screening recommendation shifts, as guideline changes directly alter reimbursement and physician ordering behavior.
Market Dynamics
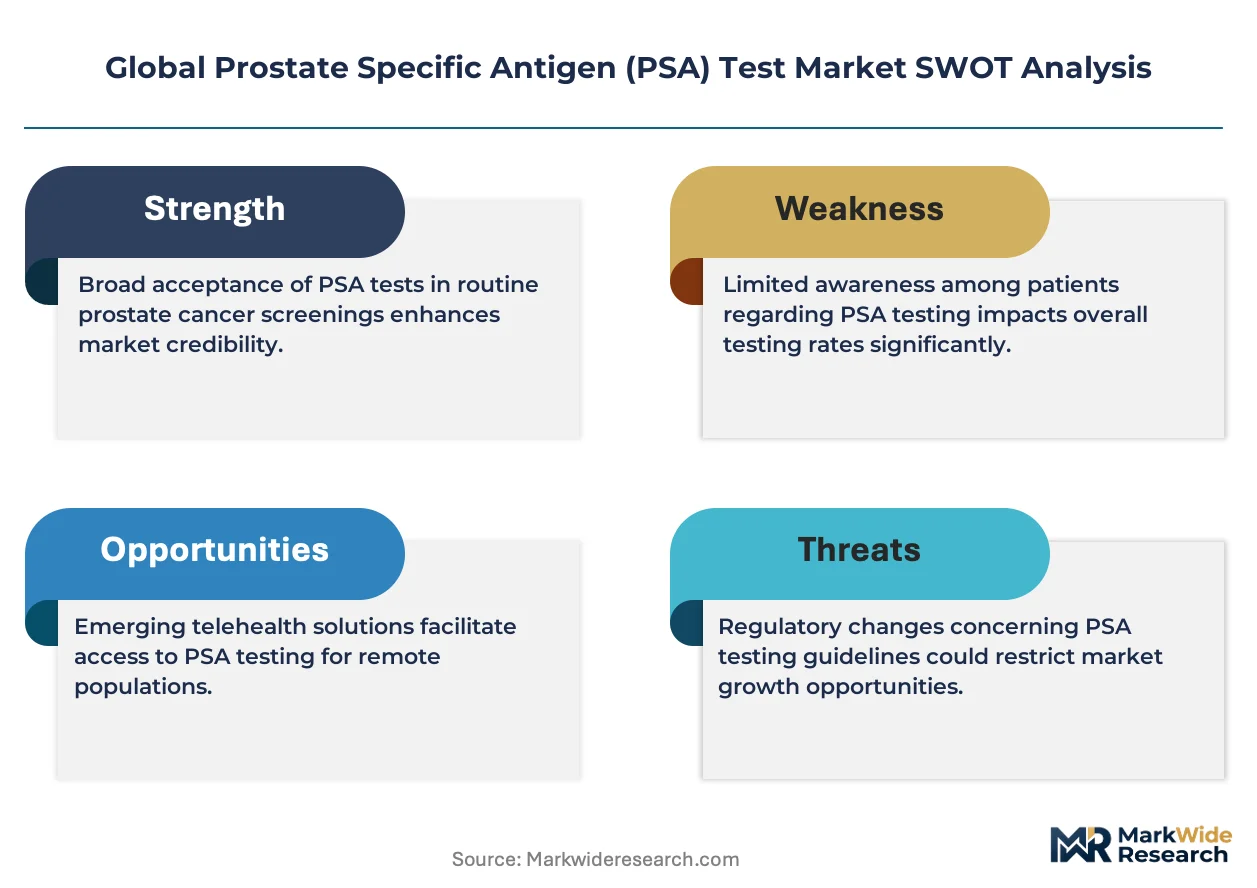
Silicon-based microfluidic substrates are hardening as the dominant material foundation for next-generation PSA assay platforms, compressing capital requirements for laboratory infrastructure while tightening performance standards under evolving FDA guidance.
Growth Catalysts
- Medicare Reimbursement Stability:Sustained CMS coverage policies in the United States preserve high testing volumes in hospital-based diagnostic laboratories. Physician ordering patterns remain anchored to predictable reimbursement schedules.
- EMA IVDR Compliance Deadlines:European manufacturers are accelerating assay revalidation investments ahead of regulatory enforcement windows. Technical documentation rebuilds create near-term demand for certified reference materials.
- Free PSA Ratio Protocols:Urology practices are expanding multi-analyte testing algorithms to reduce unnecessary biopsies. Laboratory information systems integrate decision-support rules for intermediate-risk stratification.
Market Restraints
- Antibody Raw Material Concentration:Monoclonal antibody supply chains cluster among a limited set of bioreactor facilities in Switzerland and the United States. Single-source dependencies create batch-to-batch consistency risks for assay manufacturers.
- USPSTF Guideline Volatility:Periodic reversals in prostate cancer screening recommendations generate reimbursement uncertainty. Medicare Advantage plans adjust coverage policies with 12-18 month lags following guideline releases.
- Point-of-Care Substitution Threat:Lateral flow immunoassay platforms for total PSA are capturing screening volume in primary care settings. Central laboratory testing faces volume erosion in asymptomatic population screening.
Strategic Opportunities
- Brazil ANVISA Pathway Acceleration:Streamlined registration procedures for Class III in vitro diagnostics reduce time-to-market for automated chemiluminescence systems. Private laboratory chains in São Paulo and Rio de Janeiro are consolidating purchasing power.
- Digital Pathology Integration:Artificial intelligence-enabled image analysis converges with liquid biopsy workflows to create multimodal diagnostic protocols. Health systems seek unified platforms combining PSA trends with histopathological pattern recognition.
- Direct-to-Consumer Channel Expansion:Telehealth platforms are unbundling traditional laboratory relationships for monitoring applications. Subscription-based testing models target active surveillance patients requiring quarterly PSA surveillance.
Industry Challenges
- Multiplex Assay Validation Complexity:Simultaneous quantification of PSA, free PSA, and complexed PSA within single reaction chambers demands extended analytical specificity studies. CLIA high-complexity laboratories face 18-24 month development timelines.
- Laboratory Information System Interoperability:Legacy hospital IT architectures require custom middleware development for automated result routing. HL7 FHIR implementation gaps delay real-time integration with electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prostate Specific Antigen (PSA) Test Market |
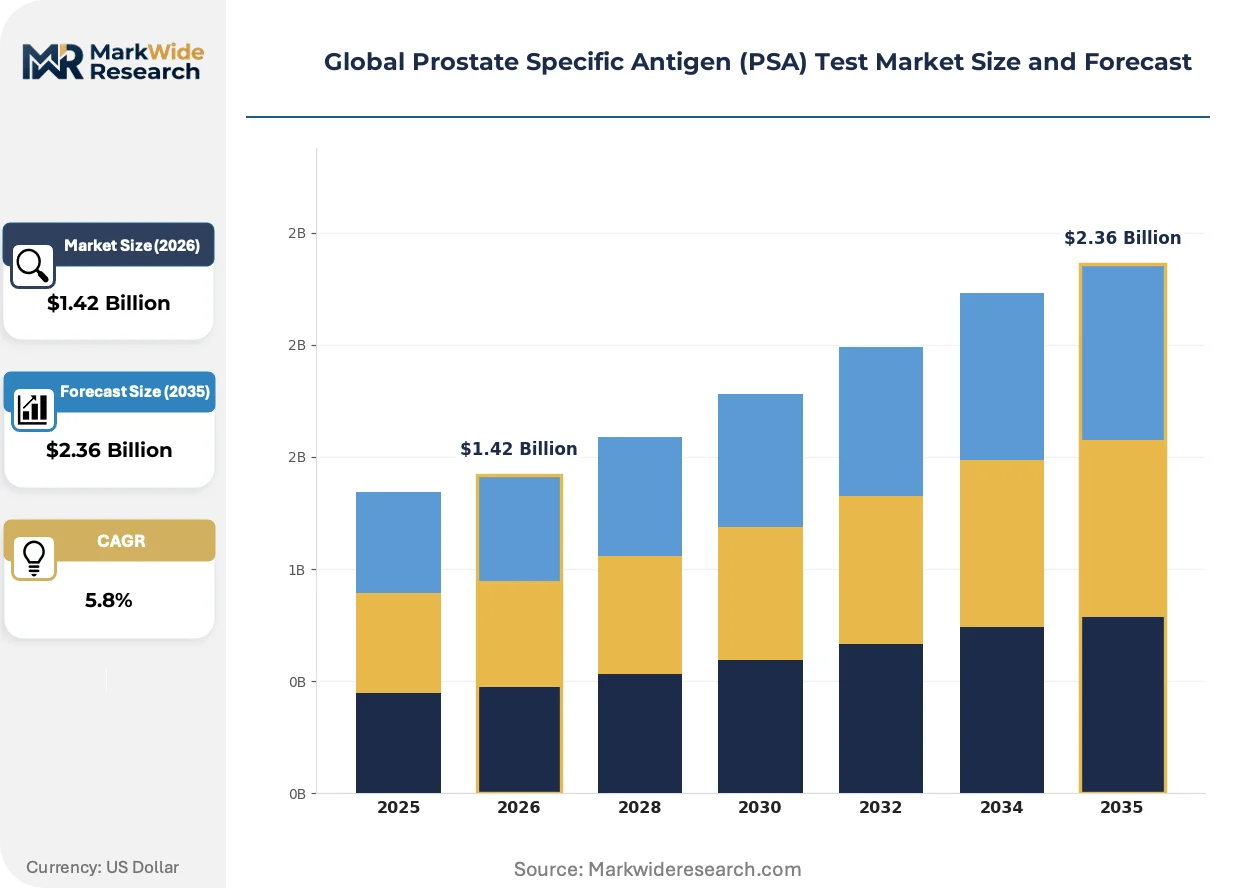
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard PSA Test, Free PSA Test, Complexed PSA Test, Total PSA Test Application: Early Detection, Treatment Monitoring, Recurrence Assessment, Risk Stratification, Prognosis Evaluation End User: Diagnostic Laboratories, Hospitals, Clinics, Cancer Research Centers, Outpatient Centers Technology: Immunoassay, Chemiluminescence Immunoassay, ELISA, Fluorescence Immunoassay, Electrochemiluminescence |
| Companies Covered | Abbott, Beckman Coulter, BIOMÉRIEUX, Roche, SIEMENS Healthineers, DiaSorin, OPKO Health, Bio-Rad Laboratories, Fujirebio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prostate Specific Antigen (PSA) Test Market Shifts & Advancements
Electrochemiluminescence detection architectures are consolidating market preference as laboratories prioritize throughput density and reagent stability over legacy enzymatic formats.
Silicon-based microfluidic substrates are absorbing manufacturing investment from polystyrene well-plate incumbents. Academic medical centers in Germany and Japan are piloting 3D-printed cartridge formats that reduce sample volume requirements to 10 microliters. The technology is absorbing cost structures previously allocated to precision machining of injection-molded components.
EMA's In Vitro Diagnostic Regulation is forcing European market participants to rebuild clinical evidence packages for legacy assays. Manufacturers must demonstrate traceability to certified reference materials and document post-market surveillance systems. Mid-sized Italian and Spanish diagnostic companies are outsourcing technical file preparation to specialized regulatory consultancies.
Hospital procurement committees are consolidating vendor relationships through multi-year reagent rental agreements. Independent reference laboratories in Texas and Florida are displacing instrument purchase models with per-test pricing structures. The shift is most visible in United States health systems pursuing operational expenditure optimization under value-based care contracts.
Global Prostate Specific Antigen (PSA) Test Market Segmentation
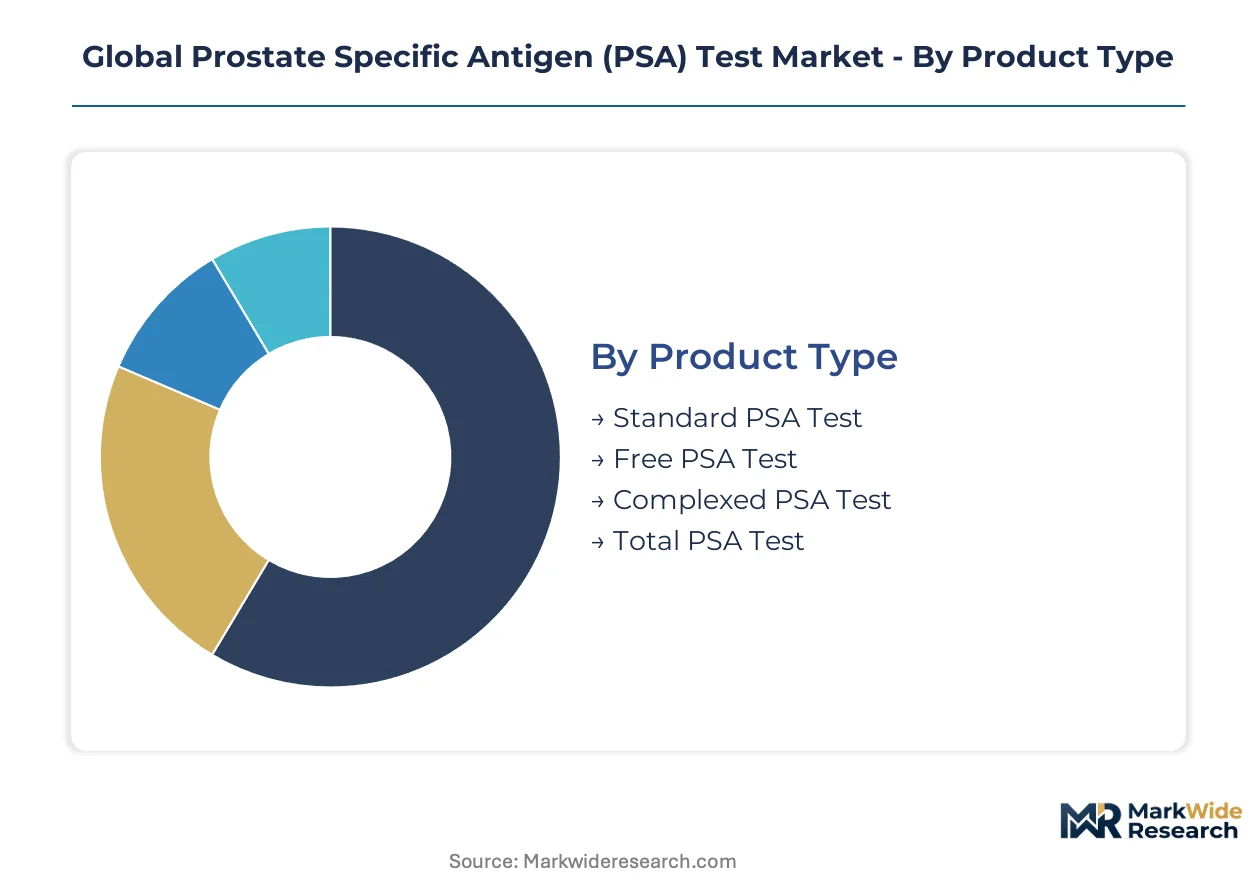
PSA test purchasing decisions fragment across clinical workflow requirements, reimbursement pathways, and laboratory infrastructure constraints. Understanding segment boundaries reveals where manufacturers can defend margin through technology differentiation versus where commoditization pressures dominate.
Product Type:
Clinical utility and reimbursement specificity drive selection among PSA test formats, with urology practices weighing diagnostic yield against biopsy avoidance economics.
- Total PSA Test:Quantifies the complete glycoprotein kallikrein-3 concentration in serum without isoform discrimination. United States hospital laboratories anchor volume here due to Medicare coverage clarity and established ordering protocols in primary care screening.
- Free PSA Test:Measures unbound PSA isoform as a percentage of total PSA to improve specificity in the diagnostic gray zone. German and Japanese urology clinics are expanding multi-analyte algorithms incorporating this ratio to reduce unnecessary prostate biopsies.
- Complexed PSA Test:Detects PSA bound to alpha-1-antichymotrypsin, offering enhanced specificity for intermediate-risk stratification. Demand concentrates in academic medical centers pursuing refined diagnostic pathways.
- Standard PSA Test:Legacy enzymatic format maintaining residual presence in resource-constrained settings where instrument capital replacement cycles extend beyond typical depreciation schedules.
Total PSA Test leads on scale; Complexed PSA Test leads on momentum.
Application:
Reimbursement intensity and test frequency vary sharply across the clinical journey, from asymptomatic screening through terminal care monitoring.
- Early Detection:Population screening applications in asymptomatic men generate the highest absolute test volumes. United States Medicare and private payer coverage policies sustain this segment despite periodic USPSTF guideline volatility.
- Treatment Monitoring:Serial PSA quantification during active therapy requires high analytical precision and rapid turnaround. Oncology practices in France and the United Kingdom prioritize this application for androgen deprivation therapy response assessment.
- Recurrence Assessment:Biochemical relapse detection demands ultra-sensitive assay formats capable of resolving sub-nanogram per milliliter concentrations. Specialized reference laboratories dominate this niche.
- Risk Stratification:Multi-parametric approaches combining PSA density, velocity, and isoform ratios guide biopsy decisions. Adoption accelerates in integrated health systems with embedded decision support tools.
- Prognosis Evaluation:Baseline PSA integration into nomograms predicts metastasis risk and survival outcomes. Academic research protocols drive methodological refinement here.
Treatment Monitoring commands premium pricing; Early Detection absorbs volume concentration.
End User:
Capital intensity and workflow integration requirements separate institutional buyers, with procurement committees weighing reagent rental economics against instrument ownership models.
- Diagnostic Laboratories:High-throughput central facilities processing thousands of PSA tests daily. Beckman Coulter and Roche instrument installed bases concentrate in North American hospital-affiliated laboratories.
- Hospitals:Inpatient and emergency department testing with STAT turnaround requirements. Brazilian private hospital chains in São Paulo are consolidating vendor relationships through multi-year reagent agreements.
- Clinics:Point-of-care and near-patient settings where lateral flow formats threaten central laboratory volume. Primary care networks in Texas and Florida experiment with direct-to-consumer screening models.
- Cancer Research Centers:Methodological validation and biomarker discovery applications requiring custom assay development. German and Japanese academic medical centers pilot silicon microfluidic prototypes.
- Outpatient Centers:Ambulatory surgical and urology specialty sites with moderate test volumes. Reimbursement pressure accelerates consolidation into larger laboratory networks.
Diagnostic Laboratories dominate procurement scale; Clinics represent the steepest expansion trajectory for decentralized formats.
Technology:
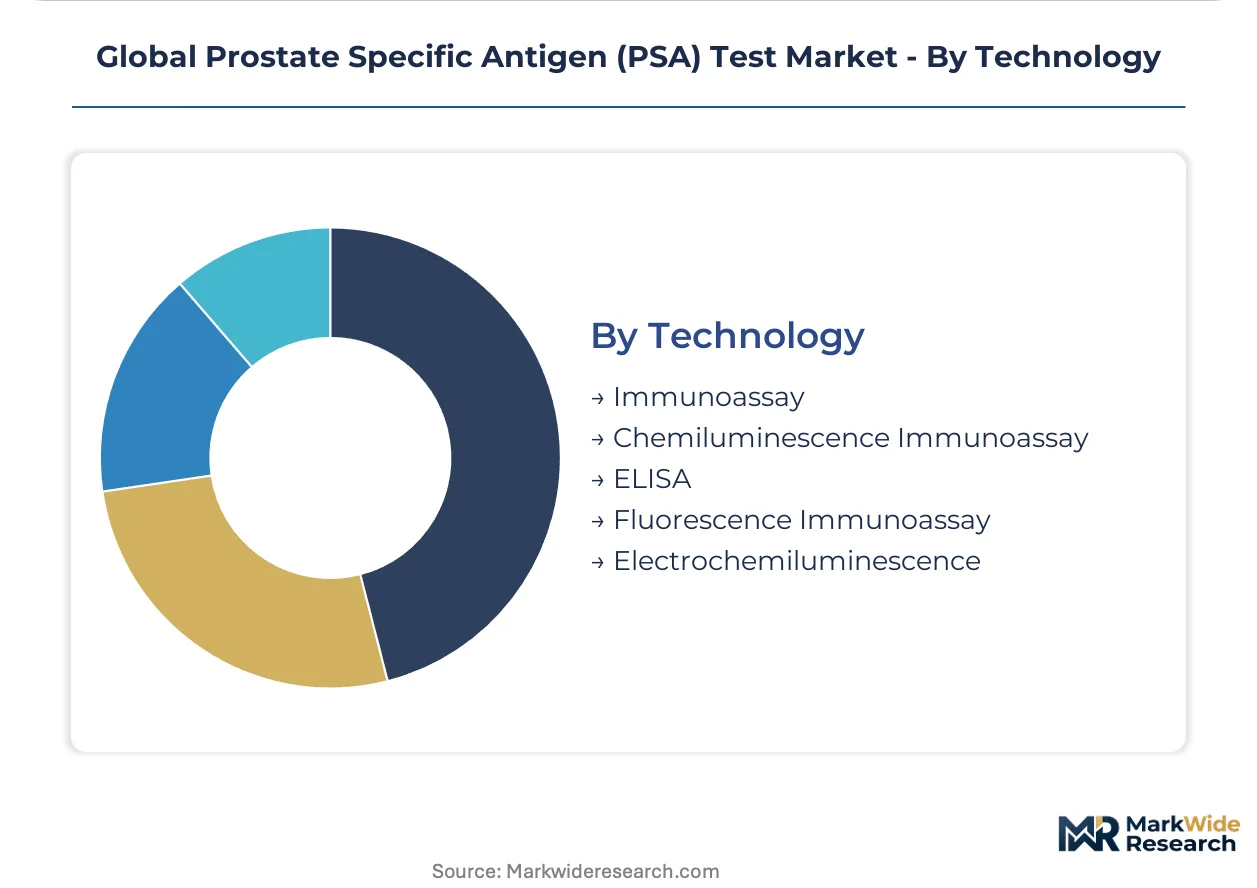
Detection chemistry and signal amplification architecture determine throughput ceiling, reagent stability, and regulatory pathway complexity.
- Chemiluminescence Immunoassay:Enzyme-triggered light emission detection dominates automated high-throughput platforms. Abbott and Siemens Healthineers compete on reagent cost per test in United States health system tenders.
- Electrochemiluminescence:Electrical excitation of ruthenium complexes enables superior precision and dynamic range. Roche anchors premium positioning in European and North American reference laboratories through this technology.
- Immunoassay:Broad category encompassing heterogeneous antibody-antigen binding formats with enzymatic or radioactive detection. Legacy installations persist where capital replacement is deferred.
- ELISA:Enzyme-linked immunosorbent assay maintains presence in low-resource settings and research applications. Manual processing limits clinical adoption in high-volume environments.
- Fluorescence Immunoassay:Fluorophore-labeled antibody detection suits multiplexed and point-of-care configurations. Emerging platforms target primary care screening substitution.
Electrochemiluminescence leads on analytical performance; Chemiluminescence Immunoassay leads on installed base scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-based diagnostic laboratories in the United States anchor PSA test procurement scale, with Medicare reimbursement policies sustaining high testing volumes in metropolitan clusters. Regulatory tightening across multiple geographies is reshaping assay validation requirements and commercial access pathways.
United States
CMS coverage policies preserve predictable reimbursement schedules for hospital laboratories processing thousands of PSA tests daily. FDA 510(k) clearance pathways shape product development timelines for automated chemiluminescence systems. Texas and Florida health systems are consolidating vendor relationships through multi-year reagent rental agreements.
Germany
Academic medical centers in Bavaria and Baden-Württemberg pilot silicon microfluidic prototypes reducing sample volume requirements. EMA's In Vitro Diagnostic Regulation forces manufacturers to rebuild technical documentation and clinical evidence packages. Laboratory networks in the Rhine-Ruhr metropolitan region are accelerating assay revalidation investments ahead of enforcement deadlines.
Japan
Tokyo and Osaka metropolitan clusters concentrate demand for ultra-sensitive assay formats capable of resolving sub-nanogram per milliliter concentrations. PMDA regulatory frameworks govern post-market surveillance systems for imported diagnostic platforms. Chubu region medical device distributors are expanding technical service capabilities for automated laboratory systems.
Brazil
Private laboratory chains in São Paulo and Rio de Janeiro are consolidating purchasing power for automated chemiluminescence platforms. ANVISA streamlined registration procedures for Class III in vitro diagnostics reduce time-to-market for multinational manufacturers. Southeast regional health systems are displacing instrument purchase models with per-test pricing structures.
United Kingdom
Oncology practices in London and the Southeast prioritize serial PSA quantification for androgen deprivation therapy response assessment. MHRA alignment with EMA IVDR standards creates parallel compliance obligations for UK-based reference laboratories. Midlands hospital procurement committees are integrating decision-support rules for intermediate-risk stratification protocols.
Global Prostate Specific Antigen (PSA) Test Market Competitive Landscape
Global majors compete with regional champions across technology platforms and procurement channel access, creating a tiered structure where scale-driven players anchor high-throughput laboratory segments while specialists occupy niche ultra-sensitive applications. The vendor base separates into three strategic archetypes: integrated diagnostics conglomerates with captive reagent manufacturing, precision instrument specialists leveraging electrochemiluminescence differentiation, and emerging microfluidic platform developers. Dominant competitive moves include multi-year reagent rental agreements displacing capital purchase models and regulatory consultancy outsourcing to accelerate EMA IVDR technical file preparation.
Among integrated diagnostics conglomerates, Abbott and Roche occupy positions exemplifying divergent technology anchoring strategies, with the former representing vertical control across immunoassay reagent supply chains and the latter sitting within premium-tier electrochemiluminescence positioning. Beckman Coulter anchors the scale-driven archetype in North American hospital laboratory procurement. These three entities collectively illustrate how competitive positioning separates across manufacturing integration depth, detection chemistry specialization, and installed-base geographic concentration.
| Leading Market Players |
|---|
| Abbott |
| Beckman Coulter |
| BIOMÉRIEUX |
| Roche |
| SIEMENS Healthineers |
| DiaSorin |
| OPKO Health |
| Bio-Rad Laboratories |
| Fujirebio |
| Others |
Supply & Pricing Matrix
Monoclonal antibody raw material costs flow from Swiss and United States bioreactor facilities through assay manufacturers into tiered reagent pricing for hospital laboratories, with batch-to-batch consistency premiums separating high-throughput diagnostic chains from resource-constrained settings.
Pricing Analysis
Input-cost pass-through from concentrated antibody supply chains governs reagent pricing structures across electrochemiluminescence and chemiluminescence platforms. Three-tier pricing structure across premium, standard, and economy levels separates Roche's precision positioning from Abbott's vertical cost control and Beckman Coulter's scale-driven per-test economics. Pricing pressure stems from Medicare reimbursement stability requirements compressing margin expansion opportunities. Independent reference laboratories in Texas and Florida exhibit highest price sensitivity, while academic medical centers in Germany and Japan absorb premiums for ultra-sensitive assay formats.
Supply Chain Analysis
Direct-to-hospital procurement channels handle high-throughput diagnostic laboratory demand, with reagent rental agreements displacing capital purchase models across United States health systems. Monoclonal antibody production concentrates in Switzerland and the United States, while silicon microfluidic substrate fabrication centers on Germany and Japan. Supply chain risk manifests in single-source bioreactor dependencies creating batch variability exposure for assay manufacturers. Distribution runs through multinational diagnostic conglomerates with captive reagent manufacturing and regional distributor networks serving Brazilian and United Kingdom laboratory markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EMA IVDR compliance investments in Europe and streamlined ANVISA pathways in Brazil, with regulatory cost differentials favoring early-mover positioning in Latin American automated diagnostics expansion.
For Market Incumbents: Anticipate point-of-care lateral flow substitution threats by accelerating silicon microfluidic platform development and securing multi-year reagent rental agreements with United States hospital procurement committees. Backward integration into antibody bioreactor capacity mitigates single-source supply risks from Swiss and United States facilities. Electrochemiluminescence technology leadership at Roche and manufacturing scale advantages at Beckman Coulter provide defensive moats against emerging microfluidic entrants.
For New Entrants and Emerging Players: Telehealth-integrated direct-to-consumer channels offer the lowest barrier to entry for active surveillance patient monitoring applications, bypassing entrenched hospital laboratory relationships. Brazil's private laboratory consolidation in São Paulo and Rio de Janeiro presents the most penetrable geography for automated chemiluminescence system introduction. Digital pathology integration partnerships with artificial intelligence-enabled image analysis platforms create differentiated multimodal diagnostic protocols without requiring full instrument platform development.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized Italian and Spanish diagnostic companies face EMA IVDR technical documentation rebuild costs exceeding standalone operational capacity. Long-term viability favors precision instrument specialists with electrochemiluminescence differentiation or integrated diagnostics conglomerates with captive reagent supply chains. Acquisition target archetypes include silicon microfluidic platform developers with 10-microliter sample volume prototypes and regulatory consultancy-outsourced European assay manufacturers. Watch USPSTF screening recommendation reversals as inflection indicators altering Medicare reimbursement trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Microfluidic Platform Development | German and Japanese academic medical centers pilot 10-microliter sample volume formats displacing polystyrene well-plate incumbents. |
| EMA IVDR Technical File Outsourcing | Mid-sized Italian and Spanish diagnostic companies accelerate compliance timelines through specialized regulatory consultancy partnerships. |
| Multi-Year Reagent Rental Agreements | Texas and Florida health systems optimize operational expenditure under value-based care contracts through consolidated vendor relationships. |
| Digital Pathology Integration | Artificial intelligence-enabled image analysis converges with liquid biopsy workflows for unified multimodal diagnostic platforms. |
| Direct-to-Consumer Channel Expansion | Telehealth platforms unbundle traditional laboratory relationships for active surveillance patient quarterly PSA monitoring subscriptions. |
Research Methodology
Multiple input streams — hospital laboratory procurement managers, biomedical engineers at academic medical centers, GPO contracts specialists, and regulatory affairs leads at diagnostic manufacturers — were reconciled with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract records. Bottom-up assay volume modeling across product type, application, end user, and technology segments combined with top-down market sizing triangulation.
Historical instrument installation data cross-referenced against expert panel input on replacement cycle timing and reagent consumption rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include assay format, clinical application intensity, laboratory infrastructure tier, detection chemistry architecture, and regional regulatory cluster. CAGRs derived from weighted average of historical trajectory analysis and forward-looking reimbursement policy assumptions, with silicon microfluidic adoption curves and EMA IVDR compliance investment cycles as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for point-of-care lateral flow substitution would alter the outlook for central laboratory volume retention. Forecasts reflect base-case assumptions regarding Medicare reimbursement stability and FDA guidance evolution on prostate cancer biomarker validation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
Neglected Tropical Diseases Diagnosis Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
Europe Breast Cancer Screening Tests Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Australia in-Vitro Diagnostics Market
Diagnostics
Professional Diagnostics Market