
 Eye Testing Equipment Market | 2026-2036
Eye Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Testing Equipment Market Intelligence
Hospital procurement departments are unwinding their historical preference for manual phoropters as automated diagnostic suites capture larger capital allocations. Carl Zeiss Meditec AG leverages its Jena manufacturing heritage to dominate high-end optical coherence tomography platforms. EssilorLuxottica anchors the retail channel through vertically integrated eye care networks spanning franchise optometry. Topcon Corporation specializes in fundus camera systems that compete on imaging resolution against semiconductor-grade sensor suppliers.
Eye testing equipment comprises diagnostic instruments that measure visual acuity, refractive error, intraocular pressure, and retinal morphology using calibrated light sources, precision optics, and digital sensor arrays operating at micrometer-scale resolutions. Autorefractors and visual field analyzers lead product category revenue due to their centrality in glaucoma management protocols, while phoropters retain steady replacement demand from independent optical clinics. Digital technology segments capture margin pools through software-enabled diagnostics, whereas manual equipment persists in emerging-market price-sensitive procurement.
FDA 510(k) clearance requirements shape product development timelines for devices entering the United States, while EU MDR recertification under the European Commission's revised framework elevates clinical evidence burdens for ophthalmic device manufacturers. ISO 10993 biocompatibility standards and IEC 60601 electrical safety protocols further constrain design freedom for multinational suppliers. Stakeholders must monitor how artificial intelligence diagnostic algorithms trigger new premarket review categories across major health authorities.
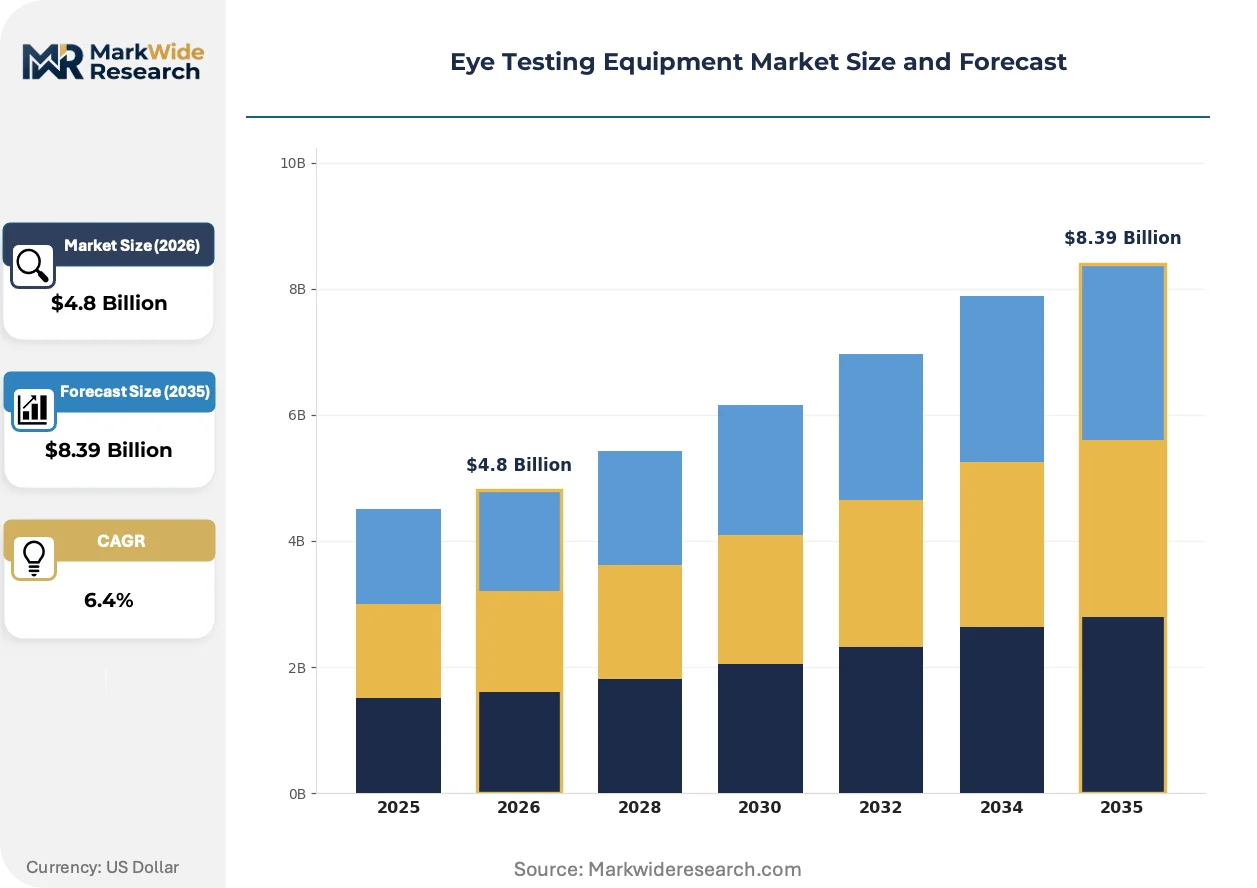
Market Dynamics
Hospital procurement departments are unwinding their historical preference for manual phoropters as automated diagnostic suites capture larger capital allocations. FDA 510(k) clearance pathways and EU MDR recertification timelines are compressing product development cycles.
Growth Catalysts
- EU MDR recertification:The European Commission's revised framework elevates clinical evidence burdens, accelerating consolidation among manufacturers with robust quality management systems.
- Glaucoma management protocols:Autorefractors and visual field analyzers lead product category revenue due to their centrality in diagnostic workflows across hospital ophthalmology departments.
- Germany's precision optics cluster:Demand concentrates around Jena and Oberkochen, where precision manufacturing heritage supports high-end optical coherence tomography platform development.
Market Restraints
- ISO 10993 biocompatibility standards:Material selection constraints for patient-contact components limit design freedom and extend validation timelines for multinational suppliers.
- Semiconductor-grade sensor suppliers:Concentration in East Asian sensor fabrication creates input cost volatility and supply security exposure for fundus camera manufacturers.
- IEC 60601 electrical safety protocols:Stringent electromagnetic compatibility requirements add certification overhead that disadvantages smaller equipment vendors.
Strategic Opportunities
- Artificial intelligence diagnostic algorithms:Software-enabled diagnostics capture margin pools as health authorities develop new premarket review categories for AI-augmented devices.
- Independent optical clinics:Phoropters retain steady replacement demand from price-sensitive procurement in emerging markets outside established hospital networks.
- Vertically integrated eye care networks:Franchise optometry channels offer captive demand for bundled diagnostic and lens dispensing solutions.
Industry Challenges
- Software-hardware integration complexity:Legacy manual equipment in installed bases creates interoperability friction for automated diagnostic suite rollouts.
- Clinical evidence generation capacity:EU MDR's elevated clinical investigation requirements strain regulatory affairs functions at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Testing Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autorefractors, Phoropters, Visual Field Analyzers, Ophthalmoscopes Technology: Digital, Optical, Automated, Manual Application: Routine Eye Exams, Specialty Procedures, Research Studies, Education End User: Hospitals, Optical Clinics, Research Institutions, Retail Outlets |
| Companies Covered | Alcon Inc., Carl Zeiss Meditec AG, Topcon Corporation, NIDEK Co., Ltd., EssilorLuxottica, Bausch & Lomb Incorporated, Canon Medical Systems USA, Haag-Streit Holding AG, HEINE Optotechnik GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Testing Equipment Market Strategic Shifts & Innovations
Digital sensor arrays operating at micrometer-scale resolutions are displacing analog detection methods across ophthalmic diagnostics. Three distinct vectors are reshaping competitive positioning: component miniaturization, regulatory framework evolution, and procurement model transformation.
Optical coherence tomography hardware is miniaturizing through silicon photonics integration and MEMS mirror fabrication. Portable diagnostic platforms are penetrating independent optical clinics and mobile screening programs at accelerating velocity. This form factor compression is enabling point-of-care deployment models that bypass traditional hospital capital equipment procurement channels.
EU MDR recertification under the European Commission's revised framework elevates post-market surveillance obligations for ophthalmic device manufacturers. Clinical evidence generation requirements now extend across the full product lifecycle rather than concentrating at premarket submission. High-end imaging platforms face the steepest compliance cost escalation, favoring suppliers with established notified body relationships.
Hospital procurement departments are consolidating vendor relationships around automated diagnostic suite suppliers capable of delivering integrated hardware-software-service bundles. Independent optical clinics retain price-sensitive spot purchasing for standalone phoropters and autorefractors. Germany's precision optics cluster demonstrates this bifurcation most acutely, with university hospitals negotiating enterprise agreements while rural practices maintain fragmented supplier portfolios.
Eye Testing Equipment Market Segmentation
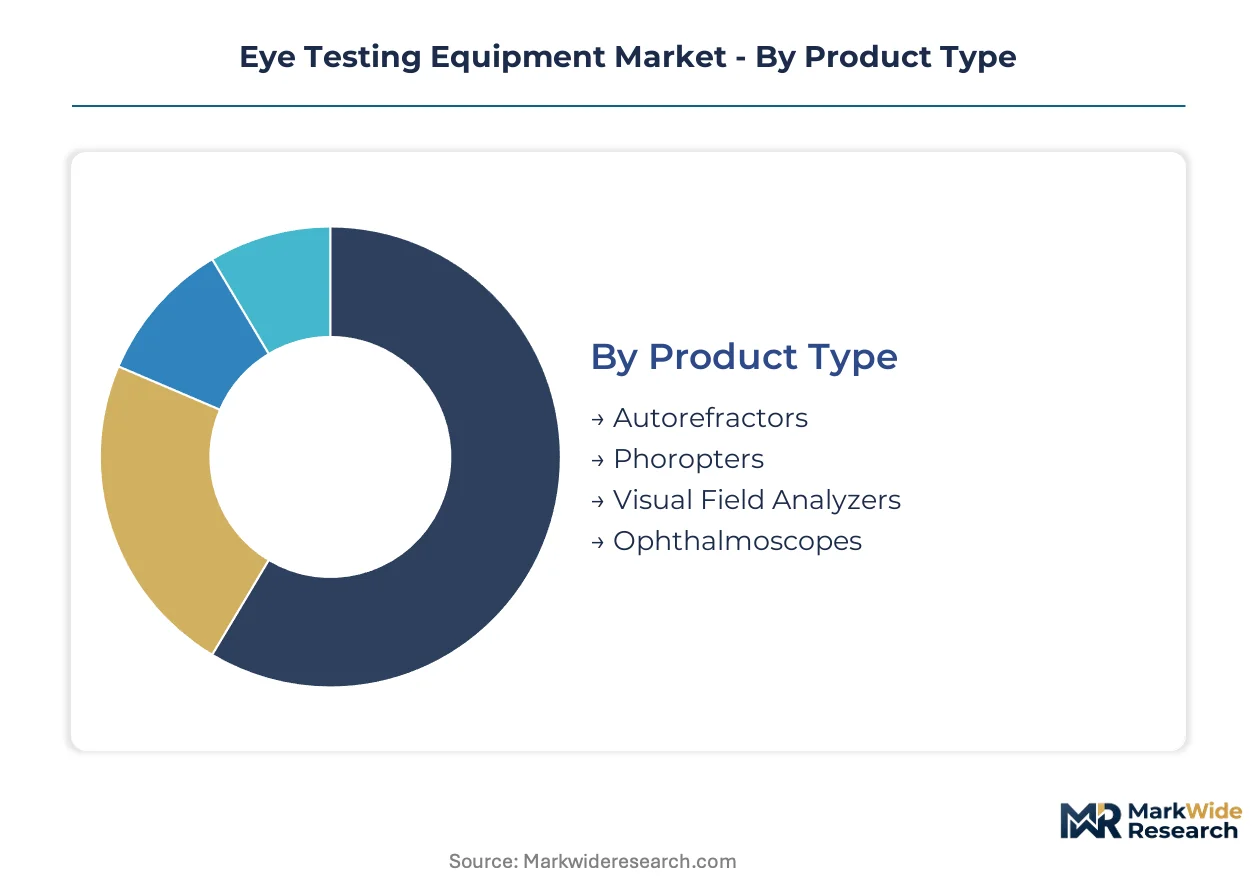
Segmentation reveals how procurement patterns diverge between institutional buyers seeking integrated diagnostic suites and independent practices prioritizing standalone affordability. Equipment specifications, technology maturity, and end-user scale collectively determine margin capture across supplier portfolios.
Product Type:
Autorefractors and visual field analyzers concentrate in hospital procurement channels across Germany and the United States, while phoropters retain fragmented demand from independent optical clinics in price-sensitive markets.
- Autorefractors:These instruments measure refractive error through infrared light projection and sensor-based wavefront analysis, eliminating subjective patient responses. Demand clusters in hospital ophthalmology departments throughout Germany's Jena precision optics corridor, driven by glaucoma management protocol standardization requiring objective baseline measurements.
- Visual Field Analyzers:Perimetry systems map peripheral and central vision sensitivity using calibrated light stimulus presentation with automated threshold algorithms. Procurement concentrates in United States academic medical centers pursuing FDA 510(k) cleared devices for longitudinal glaucoma progression monitoring, constrained by EU MDR recertification timelines for European installations.
- Phoropters:Manual refractive testing devices combining multiple lens powers in mechanical rotary assemblies persist in emerging-market optical clinics where capital constraints limit automated suite adoption.
- Ophthalmoscopes:Direct and indirect fundus examination instruments utilizing halogen or LED illumination with precision optics for retinal visualization serve mobile screening programs and primary care integration initiatives.
Autorefractors command the established base. The steepest expansion runs through visual field analyzers.
Technology:
Digital and automated platforms capture margin premiums in institutional procurement, whereas manual equipment sustains volume in markets with constrained reimbursement infrastructure.
- Digital:Sensor-array-based diagnostic platforms with software-enabled image processing and cloud connectivity enable remote consultation workflows. Adoption accelerates in United States hospital networks pursuing integrated electronic health record connectivity, though IEC 60601 electromagnetic compatibility certification adds development overhead for multinational suppliers.
- Automated:Motorized alignment and measurement systems reduce operator dependence while standardizing output consistency across variable clinical settings. Demand concentrates in Germany's university hospital procurement programs seeking workflow efficiency gains through reduced examination duration.
- Optical:Precision lens and mirror-based detection methods without electronic sensor conversion persist in specialized research applications requiring absolute measurement stability.
- Manual:Operator-dependent mechanical instruments with minimal electronic components dominate replacement cycles in independent optical clinics across price-sensitive geographies.
Digital platforms capture the premium tier. Automated systems are climbing the fastest.
Application:
Routine examination volumes anchor replacement demand, while specialty procedure applications concentrate in tertiary referral centers with concentrated capital budgets.
- Routine Eye Exams:Standard visual acuity, refractive error, and intraocular pressure assessments form the procedural foundation for general ophthalmology and optometry practice. Equipment procurement concentrates in high-volume optical clinic chains throughout the United States seeking standardized diagnostic protocols across distributed locations.
- Specialty Procedures:Advanced diagnostic protocols for glaucoma, macular degeneration, and diabetic retinopathy management require high-resolution imaging and functional measurement capabilities. Demand clusters in German and United States academic medical centers with dedicated retina and glaucoma subspecialty divisions.
- Research Studies:Investigational applications requiring modified protocols and enhanced measurement precision drive limited-volume procurement from institutional research funding.
- Education:Training program equipment needs prioritize durability and standardization over cutting-edge specification for optometry and ophthalmology residency programs.
Routine eye exams command the established base. Specialty procedures show the steepest expansion trajectory.
End User:
Hospital procurement departments consolidate vendor relationships around automated suite suppliers, while optical clinics fragment purchasing across standalone instrument specialists.
- Hospitals:Integrated health systems with centralized capital allocation prioritize automated diagnostic suites capable of enterprise-wide service and maintenance contracts. Procurement concentrates in Germany's university hospital networks and United States academic medical centers with dedicated ophthalmology service lines.
- Optical Clinics:Independent and franchise-affiliated practices with decentralized purchasing authority select standalone instruments based on immediate price and financing availability. Demand fragments across rural and suburban locations throughout the United States and Western Europe outside major metropolitan hospital referral zones.
- Research Institutions:University and government laboratory procurement prioritizes measurement precision and protocol flexibility over cost optimization for investigational applications.
- Retail Outlets:Vertically integrated eyewear chains with captive optometry services pursue bundled diagnostic and lens dispensing solutions through single-source supplier relationships.
Optical clinics command the established base. Hospital procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors Germany's precision optics export corridor, while the Los Angeles-Long Beach port complex handles the largest volume of ophthalmic device imports into the United States. These maritime gateways sustain differentiated procurement patterns across Atlantic and Pacific basin markets.
United States
FDA 510(k) clearance timelines compress product development cycles for domestic manufacturers serving academic medical centers. Hospital procurement departments in the Cleveland Clinic and Mayo Clinic networks consolidate vendor relationships around automated diagnostic suite suppliers. The FDA's evolving guidance on AI-augmented devices is reshaping premarket submission requirements for software-enabled diagnostics.
Germany
EU MDR recertification obligations elevate post-market surveillance burdens for manufacturers headquartered in the Jena precision optics cluster. Carl Zeiss Meditec AG leverages Oberkochen fabrication heritage to dominate high-end optical coherence tomography platform development. The country's notified body relationships favor established suppliers with robust quality management systems.
Japan
PMDA regulatory pathways shape domestic market entry for fundus camera manufacturers competing on imaging resolution. Topcon Corporation and NIDEK Co., Ltd. anchor production concentration in the Tokyo-Osaka industrial corridor. METI industrial policy supports precision optics R&D through targeted funding for semiconductor-grade sensor integration.
China
NMPA registration requirements extend validation timelines for multinational suppliers seeking access to tertiary hospital procurement channels. Domestic manufacturers concentrate in the Yangtze River Delta, serving price-sensitive optical clinic networks with manual phoropter alternatives. The country's dual carbon goals are accelerating energy efficiency standards for diagnostic equipment manufacturing.
India
CDSCO medical device regulations are converging toward global harmonization, compressing approval timelines for imported autorefractor platforms. Independent optical clinics in Maharashtra and Karnataka states drive fragmented demand for standalone manual instruments. The PLI scheme for medical devices offers production-linked incentives for domestic manufacturing scale-up.
Eye Testing Equipment Market Key Industry Players
Concentration sits with precision optics specialists and diversified healthcare conglomerates that command hospital procurement channels through integrated hardware-software-service bundles. The vendor base stratifies across three tiers: heritage optics houses with century-long manufacturing pedigrees, vertically integrated eyewear networks capturing retail channel demand, and specialized diagnostic instrument manufacturers competing on imaging resolution specifications. Dominant competitive moves include portfolio diversification into AI-enabled diagnostics and strategic partnerships with semiconductor-grade sensor suppliers to secure component supply.
Among heritage precision optics fabricators, Carl Zeiss Meditec AG exemplifies the high-end platform archetype through its Jena manufacturing heritage, while Haag-Streit Holding AG occupies a position within the Swiss specialist tier. Topcon Corporation and NIDEK Co., Ltd. represent Japanese precision engineering capabilities in fundus camera and perimetry system development. EssilorLuxottica sits within the vertically integrated network archetype, anchoring retail channel demand through captive optometry services.
| Leading Market Players |
|---|
| Alcon Inc. |
| Carl Zeiss Meditec AG |
| Topcon Corporation |
| NIDEK Co., Ltd. |
| EssilorLuxottica |
| Bausch & Lomb Incorporated |
| Canon Medical Systems USA |
| Haag-Streit Holding AG |
| HEINE Optotechnik GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
FDA 510(k) clearance tiers gate both supplier qualification and price differentiation in the United States, compressing development timelines for premium platforms while channeling price-sensitive procurement toward manually certified alternatives. Hospital procurement departments exploit this bifurcation to negotiate bundled service contracts for automated suites, whereas independent optical clinics fragment purchasing across standalone instruments with minimal regulatory overhead.
Pricing Analysis
Volume-discount tiering structures dominate hospital system procurement, with enterprise agreements for automated diagnostic suites commanding premium positioning against spot-market phoropter transactions. Price differentiation hinges on FDA 510(k) clearance grade and after-sales service bundling, with electromagnetic compatibility certification adding measurable overhead. Cost compression in the manual equipment tier intensifies as East Asian manufacturers expand export capacity. Independent optical clinics exhibit acute price sensitivity, while academic medical centers prioritize workflow integration over unit economics.
Supply Chain Analysis
Inbound logistics costs through the Los Angeles-Long Beach port complex have elevated landed costs for semiconductor-grade sensor arrays sourced from Japanese and South Korean fabrication facilities. Component supply draws from Germany's precision optics cluster around Jena, Japanese MEMS mirror manufacturers, and Taiwanese sensor foundries. Single-source vulnerability concentrates in CMOS image sensor supply, where East Asian fabrication dominance creates exposure. Distribution runs through hospital GPO contracts, franchise optometry networks, and independent dealer channels serving rural practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-augmented diagnostic algorithms that health authorities are developing new premarket review categories to accommodate, threatening hardware-centric margin pools.
For Market Incumbents: Shield core revenue by deepening backward integration into semiconductor-grade sensor supply through strategic partnerships with Japanese and South Korean fabrication facilities. Accelerate FDA 510(k) submissions for software-enabled diagnostics to preempt algorithmic substitution. Channel control through exclusive hospital system partnerships remains the priority defensive lever against emerging platform competitors. For New Entrants and Emerging Players: Differentiate on portable diagnostic form factors targeting mobile screening programs and rural optical clinics outside established hospital procurement networks. White-space penetration concentrates in India's fragmented independent clinic sector and China's price-sensitive tertiary hospital procurement. A direct-to-practice go-to-market angle bypasses GPO consolidation that favors incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates with underperforming ophthalmic device divisions lacking AI diagnostic capabilities. Long-term viability centers on software-hardware integration depth rather than standalone instrument manufacturing scale. Monitor FDA guidance evolution on AI-augmented device categories as the critical inflection signal for portfolio reallocation toward algorithmic diagnostic platforms.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Accelerated consolidation favors manufacturers with established notified body relationships in Germany. |
| Hospital System Partnership | Enterprise agreements with Cleveland Clinic and Mayo Clinic networks lock in automated suite deployment. |
| Semiconductor Sensor Supply Agreement | Long-term contracts with Japanese and South Korean foundries reduce input cost volatility for fundus cameras. |
| AI Diagnostic Algorithm Development | FDA's evolving premarket guidance creates first-mover advantage in software-enabled diagnostics. |
| Mobile Screening Platform Launch | Portable OCT miniaturization penetrates rural optical clinics outside traditional capital equipment channels. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital ophthalmology department heads, independent optical clinic proprietors, biomedical equipment procurement managers, and GPO contract specialists. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body registries, hospital capital expenditure disclosures, and German precision optics trade association publications. Bottom-up equipment shipment analysis triangulated against top-down healthcare capital spending estimates.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, technology maturity tier, end-user scale, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and procurement budget elasticity assessments. Industry-specific inputs included glaucoma protocol standardization rates, semiconductor sensor foundry capacity expansion, and EU MDR recertification timeline compression.
Decision-makers should treat outputs as directional under assumptions of stable FDA 510(k) review timelines and continued EU MDR implementation without major regulatory rollback; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as AI diagnostic algorithm classification frameworks and East Asian sensor supply security conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Global Radioimmunoassay Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Ultrasound-Guided Breast Biopsy Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market