
 Global Transplant Diagnostics Market | 2026-2036
Global Transplant Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transplant Diagnostics Market Foresight
EU MDR is expanding the cost-of-entry calculus for transplant diagnostic manufacturers seeking CE-marked distribution across European transplant networks. Thermo Fisher Scientific leverages its end-to-end molecular workflow portfolio to sustain leadership in histocompatibility testing workflows. F. Hoffmann-La Roche anchors its position through integrated immunoassay platforms deployed across high-volume transplant centers. Illumina competes by extending next-generation sequencing into donor-recipient compatibility protocols that reduce ambiguous typing results.
Transplant diagnostics encompasses the laboratory methods and analytical systems used to assess donor-recipient histocompatibility, monitor graft function, and detect post-transplant infections through molecular, serological, and cellular techniques operating at allele-level resolution. These systems serve the primary commercial purpose of reducing organ rejection incidence and optimizing immunosuppressive therapy selection through precise immune profiling. Molecular diagnostics commands the deepest margin pools given its technical complexity and reimbursement premiums for sequencing-based typing. PCR-based methods retain volume dominance in routine HLA genotyping, while next-generation sequencing represents the fastest-expanding technology segment as centers transition from Sanger methods for higher-resolution allele definition.
FDA oversight of companion diagnostic validation, EU MDR technical documentation requirements, and Japan PMDA quality management standards collectively shape product development timelines and commercial access pathways for transplant assay manufacturers. The FDA's evolving stance on laboratory-developed tests is forcing restructuring of how hospital-based HLA laboratories validate and report typing results. Stakeholders must monitor regulatory divergence between the FDA's risk-based framework and EU MDR's stricter clinical evidence requirements as they allocate R&D funding across geographic markets.
Market Dynamics
The transition from Sanger sequencing to next-generation sequencing platforms is compressing turnaround times for high-resolution HLA typing while forcing academic medical centers to restructure laboratory capital allocation and staffing models around automated molecular workflows.
Growth Catalysts
- EU MDR enforcement:Stricter clinical evidence requirements for CE-marked transplant assays are accelerating hospital laboratory consolidation around validated molecular platforms.
- Solid organ program expansion:Academic medical centers in the United States, Germany, and Japan are extending molecular surveillance protocols beyond HLA matching into post-transplant infection monitoring.
- Companion diagnostic evolution:FDA guidance updates are embedding precision diagnostics deeper into immunosuppressive therapy selection protocols.
Market Restraints
- Sequencing reagent cost volatility:Consumable pricing for NGS library preparation kits creates margin pressure on high-throughput HLA laboratories.
- Supply concentration in thermal cyclers:PCR instrument manufacturing clusters in specific East Asian manufacturing hubs expose procurement to logistics disruptions.
- EU MDR technical documentation burden:Extended validation timelines for CE-marked assays delay commercial access across European transplant networks.
Strategic Opportunities
- Cloud-based bioinformatics:Remote allele interpretation services enable smaller transplant centers to access NGS-grade typing without capital investment.
- Japan's PMDA quality pathways:Streamlined approval frameworks for precision diagnostics create faster market entry for validated molecular assays.
- Donor-derived cell-free DNA:Emerging surveillance applications for graft injury detection expand addressable testing volume beyond compatibility testing.
Industry Challenges
- Bioinformatics specialist scarcity:Allele-level sequence interpretation requires computational biology expertise that outpaces current training pipeline output.
- Legacy LIMS integration:Hospital information systems built around serological workflows resist seamless data exchange with NGS platforms.
- Cross-platform standardization delays:Divergent file formats between sequencing instrument vendors complicate multi-site registry data sharing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transplant Diagnostics Market |
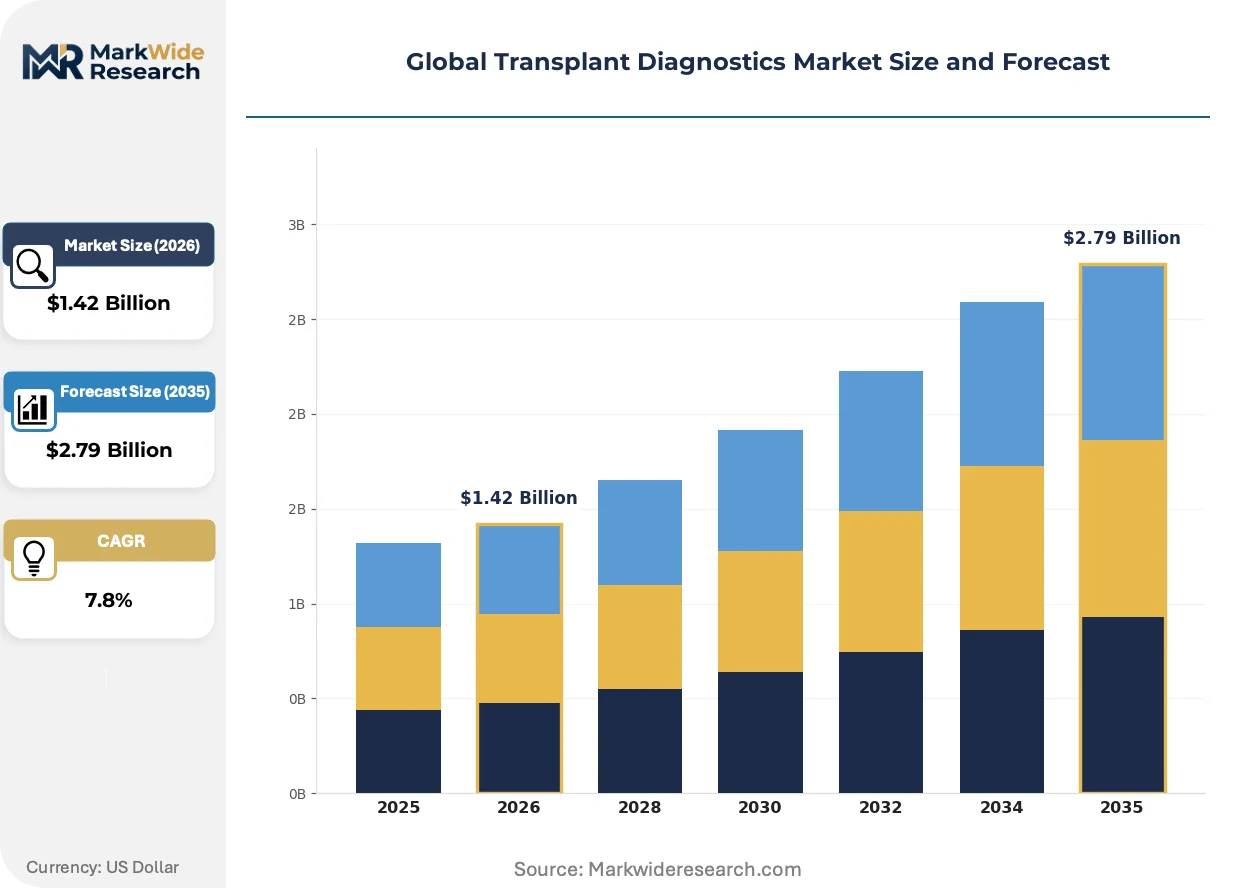
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Molecular Diagnostics, Histocompatibility Testing, Biopsy Analysis Technology: PCR, Next-Generation Sequencing, Flow Cytometry, Microarray, Mass Spectrometry Application: Organ Rejection Monitoring, Graft Survival Prediction, Donor-Recipient Compatibility, Infection Detection End User: Transplant Centers, Diagnostic Laboratories, Research Institutions, Specialty Clinics |
| Companies Covered | Thermo Fisher Scientific, F. Hoffmann-La Roche, Illumina, Abbott Laboratories, QIAGEN, Becton, Dickinson and Company, Bio-Rad Laboratories, Werfen (Immucor), bioMérieux SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transplant Diagnostics Market Shifts & Advancements
Next-generation sequencing is compressing the resolution gap between research-grade and clinical-grade HLA typing while regulatory frameworks on three continents simultaneously tighten evidence standards. These forces are reshaping how transplant laboratories procure, validate, and operationalize molecular diagnostics.
NGS-based HLA genotyping is decentralizing high-resolution typing from centralized reference laboratories into hospital-based molecular pathology departments. Mid-sized transplant programs in the United States and Germany are adopting benchtop sequencers to reduce send-out turnaround times. This shift is compressing the market for regional HLA reference services while expanding recurring consumable revenue for platform vendors.
EU MDR clinical evidence requirements are extending validation timelines for CE-marked transplant diagnostics. Manufacturers must now generate prospective performance data across diverse donor-recipient populations before market authorization. High-complexity molecular assays face the steepest documentation burden, favoring established players with regulatory affairs infrastructure over emerging competitors.
Transplant center procurement teams are unbundling after-sales service contracts from instrument purchase agreements. Buyers in Japan and Germany now negotiate separate pricing for installation, training, and ongoing technical support. This behavior is most visible among academic medical centers with dedicated biomedical engineering departments capable of self-maintaining sequencers and thermal cyclers.
Global Transplant Diagnostics Market Segmentation
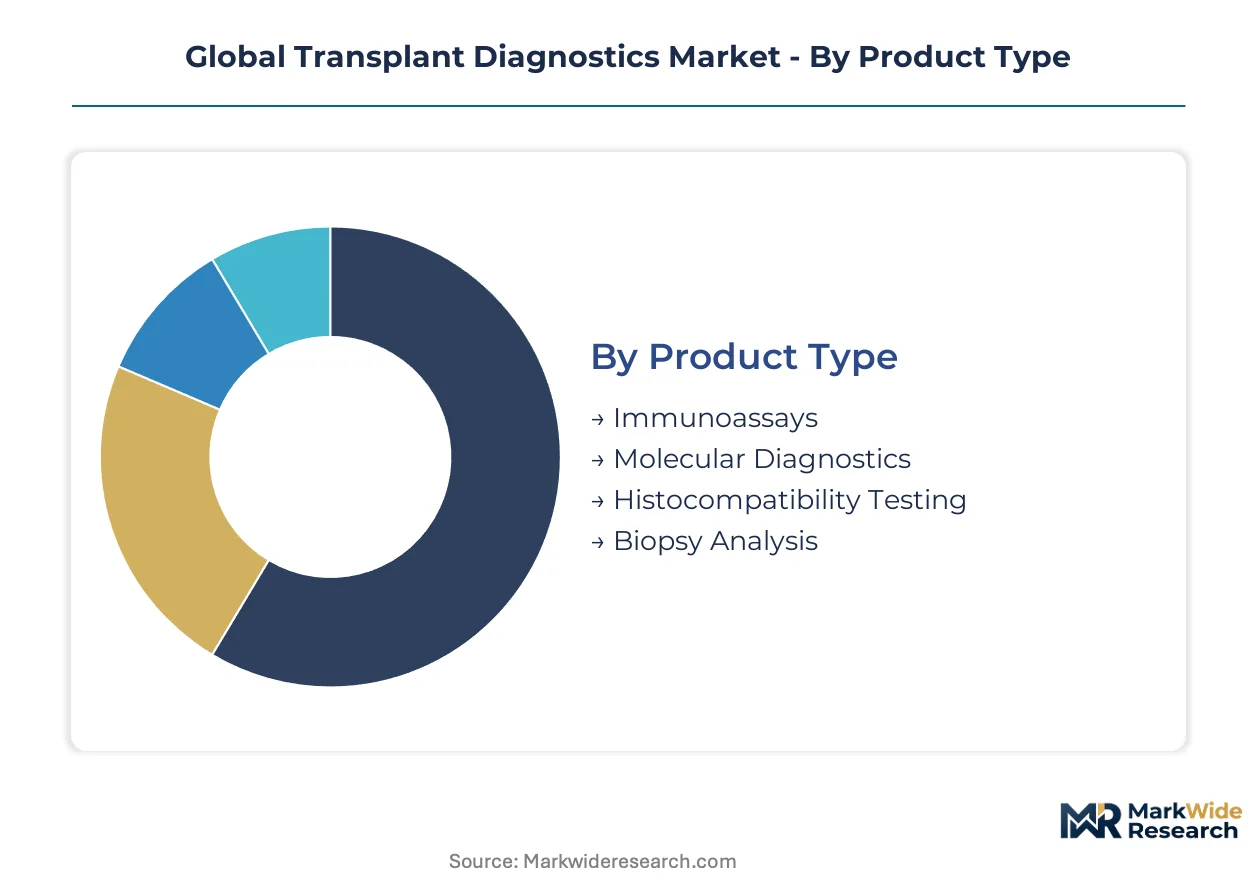
Transplant diagnostics segmentation reflects divergent capital intensity, regulatory pathways, and reimbursement models across testing modalities. Product architecture choices determine whether laboratories centralize workflows around automated platforms or distribute testing across specialized units.
Product Type:
Standardization dominates immunoassay and histocompatibility segments, while molecular diagnostics and biopsy analysis retain higher customization variance across transplant programs.
- Molecular Diagnostics:Nucleic acid amplification and sequencing platforms enable allele-level HLA genotyping and viral load quantification. United States academic medical centers concentrate procurement around automated library preparation systems to reduce manual handling errors. Reagent rental agreements and per-test pricing models dominate commercial terms.
- Histocompatibility Testing:Serological and molecular methods for donor-recipient matching operate at the technical core of transplant programs. Germany's university hospitals maintain in-house HLA laboratories with dedicated technical staff rather than outsourcing to reference networks. Regulatory validation burdens favor established platform vendors with EU MDR technical documentation infrastructure.
- Immunoassays:Enzyme-linked and chemiluminescent assays for antibody detection and immunosuppressant monitoring.
- Biopsy Analysis:Histopathological and molecular characterization of graft tissue samples.
Most installed capacity flows through Histocompatibility Testing. Expansion is steepest in Molecular Diagnostics.
Technology:
Cost tier separation distinguishes high-throughput sequencing investments from lower-capital cytometry and spectrometry deployments.
- PCR:Thermal cycling amplification remains the volume workhorse for HLA genotyping and viral surveillance. Japan's transplant networks standardize on real-time PCR platforms with integrated sample-to-result automation to address staffing constraints. Consumable contracts typically span 3-5 year terms with minimum volume commitments.
- Next-Generation Sequencing:Massively parallel sequencing delivers phased allele resolution exceeding Sanger methods. Mid-sized United States transplant programs in Texas and Florida are adopting benchtop sequencers to eliminate send-out delays. Bioinformatics interpretation costs now exceed sequencing chemistry as the dominant operational expense.
- Flow Cytometry:Single-cell analysis for lymphocyte subset enumeration and crossmatch assays.
- Microarray:Solid-phase antibody screening and SNP-based HLA typing.
- Mass Spectrometry:Proteomic and metabolomic profiling for graft dysfunction biomarker discovery.
PCR retains the largest installed base. Next-Generation Sequencing is climbing the fastest in new capital allocations.
Application:
Customer type alignment separates routine compatibility testing from specialized surveillance and prediction services.
- Organ Rejection Monitoring:Serial biomarker surveillance detects acute and chronic graft injury before functional decline. United States Medicare reimbursement for donor-derived cell-free DNA testing is accelerating adoption in kidney and heart transplant programs. Testing frequency typically peaks in months 1-6 post-transplant.
- Donor-Recipient Compatibility:Pre-transplant histocompatibility assessment governs organ allocation decisions. Japan's organ procurement organizations mandate high-resolution HLA typing for all deceased donor transplants, creating consistent demand for reference laboratory services. Turnaround time pressure favors local molecular capacity over centralized send-out.
- Graft Survival Prediction:Risk stratification algorithms combining immunological and clinical variables.
- Infection Detection:Post-transplant viral, fungal, and bacterial surveillance through molecular and serological methods.
Donor-Recipient Compatibility commands the deepest historical investment. Organ Rejection Monitoring is gaining share fastest as surveillance protocols extend beyond the immediate peri-transplant period.
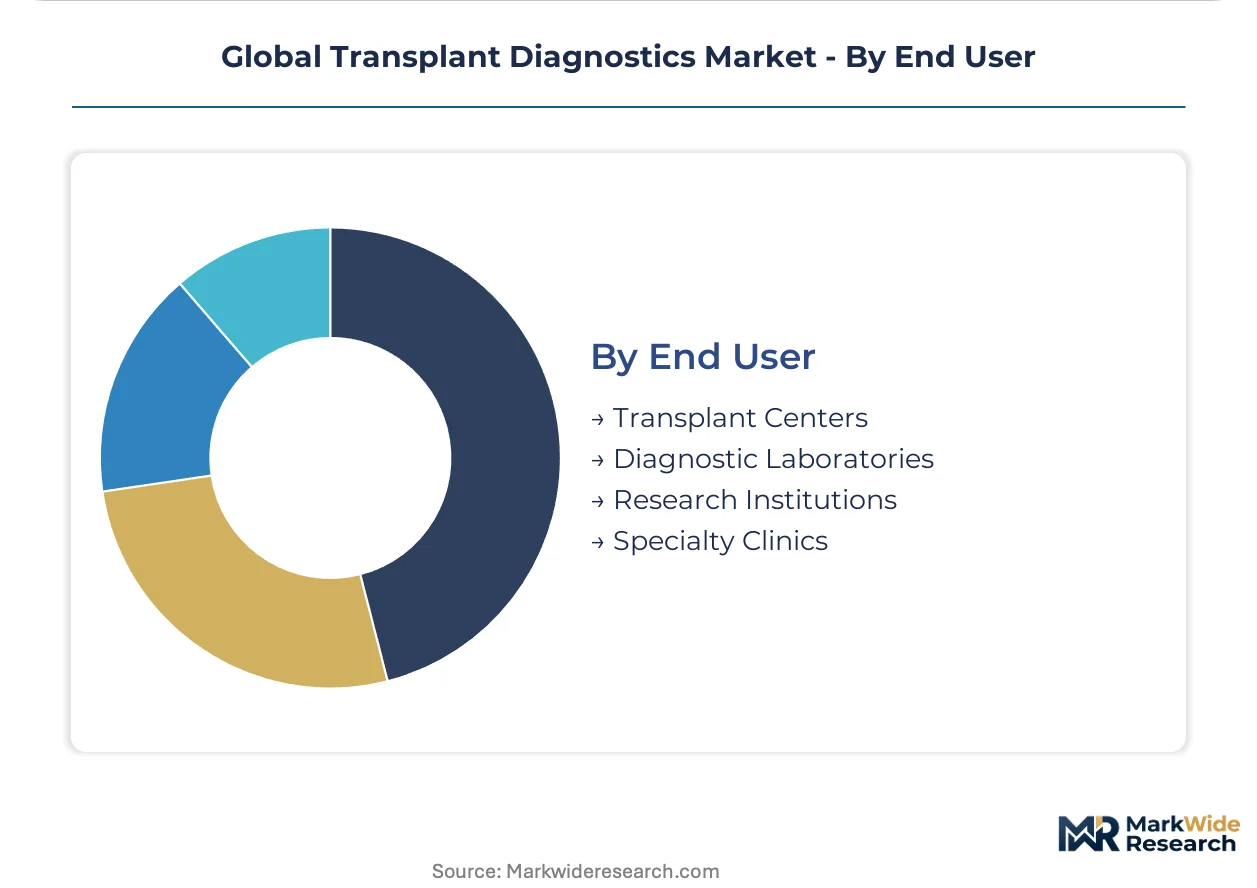
End User:
Geographic concentration of transplant volume shapes procurement scale and platform standardization patterns.
- Transplant Centers:Hospital-based programs performing solid organ transplantation integrate diagnostics into multidisciplinary care workflows. Germany's Charité and Heidelberg University Hospital operate self-contained HLA laboratories with full NGS capability. Capital budgets for molecular platforms compete directly with surgical robotics and imaging equipment.
- Diagnostic Laboratories:Independent and hospital-affiliated reference labs process overflow testing and specialized assays. United States commercial laboratories in North Carolina and California maintain CAP-accredited HLA testing for networks without in-house capacity. Pricing pressure from Medicare's clinical laboratory fee schedule constrains margin expansion.
- Research Institutions:Academic centers conducting transplant immunology studies and assay development.
- Specialty Clinics:Ambulatory settings managing long-term immunosuppression and surveillance.
Transplant Centers host the majority of installed analytical capacity. Diagnostic Laboratories are expanding most quickly as hospital consolidation drives centralized testing strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized molecular pathologists and HLA laboratory directors cluster in transplant-dense metropolitan areas where academic medical centers anchor regional organ procurement networks. Their expertise concentration shapes where diagnostic platforms achieve scale deployment.
United States
Kidney and heart transplant volumes at Cleveland Clinic and Mayo Clinic Rochester drive demand for donor-derived cell-free DNA surveillance assays. FDA companion diagnostic guidance updates reshape how hospital laboratories validate NGS-based HLA typing workflows. Texas Medical Center in Houston operates one of the largest consolidated molecular pathology departments serving multiple transplant programs.
Germany
Charité Berlin and Heidelberg University Hospital maintain self-contained HLA laboratories with full next-generation sequencing capability rather than outsourcing. EU MDR technical documentation requirements extend validation timelines for CE-marked transplant assays entering European distribution. Bavaria's university hospital network standardizes on automated molecular platforms to reduce inter-laboratory variability in high-resolution typing.
Japan
Japan Organ Transplant Network mandates high-resolution HLA typing for all deceased donor procedures, creating consistent reference laboratory demand. PMDA streamlined approval pathways for precision diagnostics accelerate market entry for validated molecular assays. Tokyo's metropolitan transplant centers concentrate procurement of integrated sample-to-result automation systems.
United Kingdom
NHS Blood and Transplant coordinates national histocompatibility testing through regional tissue typing laboratories serving distributed transplant programs. MHRA alignment with EU MDR standards maintains stringent clinical evidence requirements for commercial assay distribution. Greater Manchester's consolidated pathology network demonstrates centralized molecular surveillance at scale.
Canada
Canadian Blood Services operates national HLA typing reference laboratories supporting provincial transplant programs with standardized molecular methods. Health Canada regulatory convergence with FDA frameworks shapes validation protocols for laboratory-developed tests. Ontario's university-affiliated transplant centers lead adoption of cloud-based bioinformatics for allele interpretation.
Global Transplant Diagnostics Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with end-to-end molecular workflow portfolios. Platform vendors with integrated instrument-reagent-bioinformatics offerings capture disproportionate share in high-throughput HLA laboratories. Three archetypes dominate: full-stack molecular workflow providers, specialized histocompatibility reagent suppliers, and sequencing technology specialists. Consolidation through strategic partnerships and technology licensing agreements reshapes access to critical assay content.
Among diversified conglomerates, Thermo Fisher Scientific and F. Hoffmann-La Roche exemplify the full-stack archetype through their integrated platform positions across histocompatibility testing workflows. Illumina occupies a distinct tier as the sequencing technology anchor whose platforms underpin the transition from Sanger methods to next-generation sequencing in donor-recipient compatibility protocols. These three companies represent the competitive core around which mid-sized specialists and regional reagent suppliers orbit.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| Illumina |
| Abbott Laboratories |
| QIAGEN |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories |
| Werfen (Immucor) |
| bioMérieux SA |
| Others |
Supply & Pricing Matrix
Sequencing reagent price indices cascade through transplant diagnostic supply chains into three distinct procurement tiers. Academic medical centers with captive NGS capacity negotiate volume-based consumable contracts, while smaller programs absorb spot-market kit pricing through reference laboratory send-outs.
Pricing Analysis
Bundled after-sales service contracts are unbundling into separately negotiated installation, training, and technical support components. Pricing stratifies across premium automated platforms, standard benchtop systems, and economy-grade PCR thermal cyclers based on throughput capacity and EU MDR certification status. Cost compression in the mid-tier segment is intensifying as Japanese transplant centers demand per-test pricing over capital purchase models. Community hospital laboratories exhibit the highest price sensitivity, deferring NGS adoption until reagent rental terms match PCR economics.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Singapore anchor hub-and-spoke logistics for thermal cycler and sequencing instrument deployment. Manufacturing concentrates in China for PCR plastics, Japan for precision optics, and the United States for proprietary sequencing chemistries. Single-source vulnerability in East Asian thermal cycler component fabrication exposes procurement to logistics disruptions. Distribution runs through authorized dealer networks for installation-heavy platforms and direct-to-laboratory channels for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR clinical evidence requirements and FDA companion diagnostic guidance simultaneously deepen compliance costs and consolidate procurement around validated platforms.
For Market Incumbents: Cement platform loyalty through backward integration into proprietary sequencing chemistries and captive bioinformatics interpretation services. Defend against emerging cloud-based allele interpretation entrants by embedding automated reporting modules directly into hospital LIMS infrastructure. Prioritize EU MDR technical documentation infrastructure as a competitive moat given extended validation timelines for CE-marked assays. For New Entrants and Emerging Players: The premium-to-economy price-point gap in NGS-based HLA typing creates entry space for modular, pay-per-test bioinformatics services targeting mid-sized United States transplant programs without capital budgets. White-space concentration sits in donor-derived cell-free DNA surveillance protocols for heart transplant programs where Medicare reimbursement pathways are stabilizing. Pursue hospital system partnerships rather than direct instrument sales to bypass entrenched procurement relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized histocompatibility reagent suppliers possessing EU MDR-validated assay content but lacking global distribution infrastructure. Long-term viability hinges on regulatory affairs scalability rather than pure technology differentiation. Monitor Japan PMDA approval velocity as an inflection indicator for precision diagnostics market access efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR technical documentation capabilities determine commercial access timelines across European transplant networks. |
| Cloud-Based Bioinformatics Launch | Remote allele interpretation services enable smaller centers to access NGS-grade typing without capital deployment. |
| Hospital System Partnership | Integrated procurement agreements with academic medical centers lock in multi-year consumable revenue streams. |
| Reimbursement Strategy Development | Medicare coverage pathways for donor-derived cell-free DNA testing accelerate adoption in kidney and heart programs. |
| Software Companion Development | FDA-validated algorithmic reporting modules differentiate automated platforms in high-throughput HLA laboratories. |
Research Methodology
Direct dialogue with HLA laboratory directors, transplant center procurement officers, molecular pathology department heads, and regulatory affairs specialists at diagnostic manufacturers grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation summaries, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Bottom-up instrument installation data and top-down market size estimates were triangulated to anchor segmentation outputs.
Bottom-up modeling of installed base by technology platform and consumable throughput assumptions generated volume projections across the analysis window. Segmentation dimensions included product type, technology modality, application purpose, and end-user facility category. CAGRs were derived from weighted average of historical procurement patterns and projected adoption curves for next-generation sequencing displacement of Sanger methods. Forecast inputs incorporated transplant volume projections from organ procurement organizations and reimbursement policy trajectories from CMS and national health technology assessment bodies.
Caveats apply where EU MDR enforcement intensity, FDA laboratory-developed test policy evolution, or sequencing reagent supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding technology transition timelines and regulatory harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Creatinine Test Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Viral Disease Diagnosis Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Connected Diagnostics Market
Diagnostics
Veterinary Diagnostics Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Global Fecal Occult Blood Tests Market