
 Continuous Passive Motion Devices Market | 2026-2036
Continuous Passive Motion Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Passive Motion Devices Market Analysis
Aftermarket service revenue is reshaping how manufacturers capture lifetime value from installed CPM units. DJO Global leverages its extensive clinical support network to sustain recurring maintenance contracts across hospital systems. Furniss Corporation anchors its competitive position through specialized pediatric CPM configurations that larger competitors rarely match. Chattanooga competes aggressively on rental program flexibility, allowing surgical centers to convert capital expenditures into operational budgets.
Continuous passive motion devices are electromechanical rehabilitation systems that cyclically move joints through predetermined arcs at controlled speeds, typically employing DC motors with torque-limiting mechanisms to prevent tissue stress. Their primary commercial purpose is to prevent postoperative joint stiffness, reduce edema formation, and accelerate cartilage healing following arthroplasty or ligament reconstruction procedures. Knee CPM systems dominate installed base volumes due to the high incidence of total knee arthroplasty, while shoulder CPM configurations command premium positioning as shoulder replacement volumes accelerate faster than historical hip and knee trends. Electronic controls represent the fastest-growing technology segment as programmable treatment protocols replace analog dial interfaces in hospital procurement specifications.
FDA 510(k) clearance requirements and ISO 13485 quality system mandates govern device commercialization pathways, with the former demanding substantial equivalence demonstrations that extend development cycles for novel motion ranges. The EU Medical Device Regulation imposes additional clinical evidence burdens on manufacturers seeking CE marking for European rehabilitation center distribution. Stakeholders must monitor how CMS reimbursement coding revisions affect ambulatory surgical center willingness to absorb CPM placement costs within bundled payment frameworks.
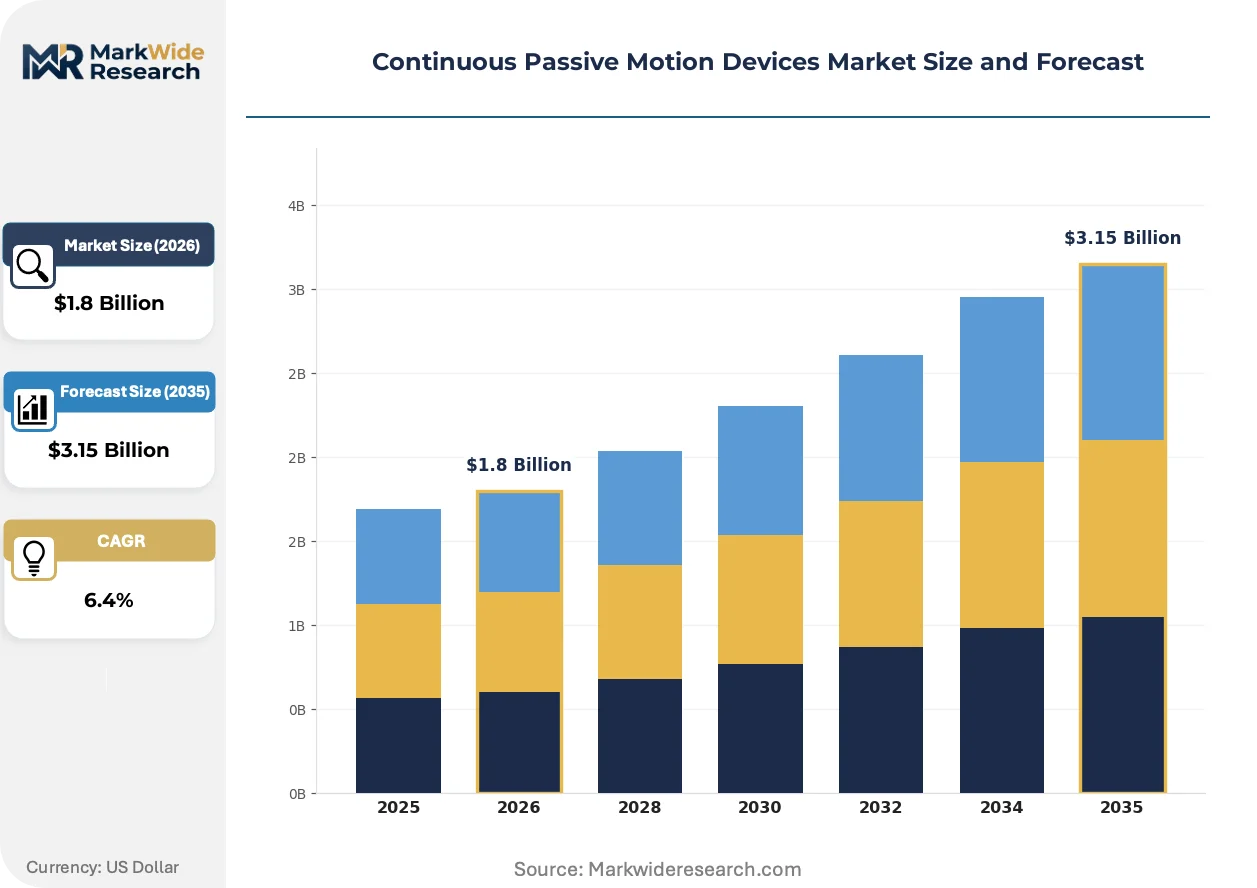
Market Dynamics
Postoperative rehabilitation protocols are hardening around CPM integration as bundled payment frameworks force surgical centers to absorb device placement costs within episode-based reimbursement ceilings. This structural compression is accelerating rental model adoption and aftermarket service bundling across ambulatory settings.
Growth Catalysts
- CMS Bundled Payment Mandates:Medicare's Comprehensive Care for Joint Replacement program pressures hospitals to standardize CPM protocols, driving unit placement in US orthopedic departments.
- Shoulder Arthroplasty Volume Surge:Accelerating shoulder replacement procedures in aging populations expands addressable market for premium shoulder CPM configurations beyond traditional knee dominance.
- ISO 13485 Quality Certification:Standardized quality management requirements streamline supplier qualification processes, reducing procurement friction for certified device manufacturers.
Market Restraints
- DC Motor Supply Concentration:Torque-limiting motor assemblies concentrate in East Asian manufacturing clusters, exposing procurement to logistics volatility and input cost spikes.
- FDA 510(k) Substantial Equivalence Burden:Novel motion range demonstrations extend development cycles, delaying commercialization for next-generation programmable protocols.
- Manual Physical Therapy Substitution:Cost-conscious outpatient clinics in price-sensitive markets retain manual mobilization protocols, limiting CPM penetration in budget-constrained segments.
Strategic Opportunities
- Pediatric Orthopedic Configuration Gap:Specialized sizing and motion calibration for juvenile patients remains underserved, offering white space for anatomically adaptive designs.
- EU Medical Device Regulation Clinical Evidence Pathway:MDR Article 61 evidentiary requirements, once satisfied, create durable competitive moats against non-compliant competitors in European rehabilitation centers.
- Remote Monitoring Integration:Convergence of CPM electromechanics with telehealth platforms enables post-discharge patient tracking, opening ambulatory and home-based deployment channels.
Industry Challenges
- FDA 510(k) Timeline Compression:Predicate device identification and substantial equivalence documentation consume 12-18 month regulatory cycles, straining R&D resource allocation.
- Biomedical Engineer Talent Scarcity:Specialized expertise in torque-limiting mechanism design and rehabilitative biomechanics concentrates at select academic medical centers, constraining product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Passive Motion Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knee CPM, Shoulder CPM, Ankle CPM, Wrist CPM Application: Orthopedic Rehabilitation, Post-Surgery Recovery, Pain Management, Sports Injury Recovery End User: Hospitals, Rehabilitation Centers, Home Care, Physiotherapy Clinics Technology: Motorized Systems, Manual Systems, Electronic Controls, Adjustable Range |
| Companies Covered | DJO Global, Furniss Corporation, Surgi-Care, Bio-Med, BTL Corporate, Chattanooga, Chinesport Rehabilitation, Rimec, OPED GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Passive Motion Devices Market Emerging Trajectories
Programmable treatment protocols are displacing analog dial interfaces across hospital procurement specifications, compressing price premiums for basic electromechanical units while elevating software-enabled configurations. This interface migration reconfigures competitive differentiation toward data integration and protocol customization capabilities.
Electronic control systems are migrating from fixed-speed analog dials to programmable touchscreen interfaces with session logging and remote adjustment capabilities. Hospital procurement committees now specify digital protocol libraries as mandatory evaluation criteria. This technology is migrating from premium-tier shoulder units into mid-range knee configurations, collapsing the historical price stratification between basic and advanced CPM segments.
The EU Medical Device Regulation imposes clinical performance and post-market surveillance obligations that exceed legacy Medical Device Directive requirements. Manufacturers must maintain systematic clinical data registries and periodic safety update reports. Knee CPM systems face the heaviest evidentiary burden given their installed base volume and higher incident reporting exposure.
Rental-to-own conversion structures are displacing outright capital purchase as the dominant acquisition model in US ambulatory surgical centers. Surgical center administrators prefer operational budget treatment over balance sheet capitalization. This preference shift concentrates in multi-site orthopedic networks where device utilization rates vary across facilities.
Continuous Passive Motion Devices Market Segmentation
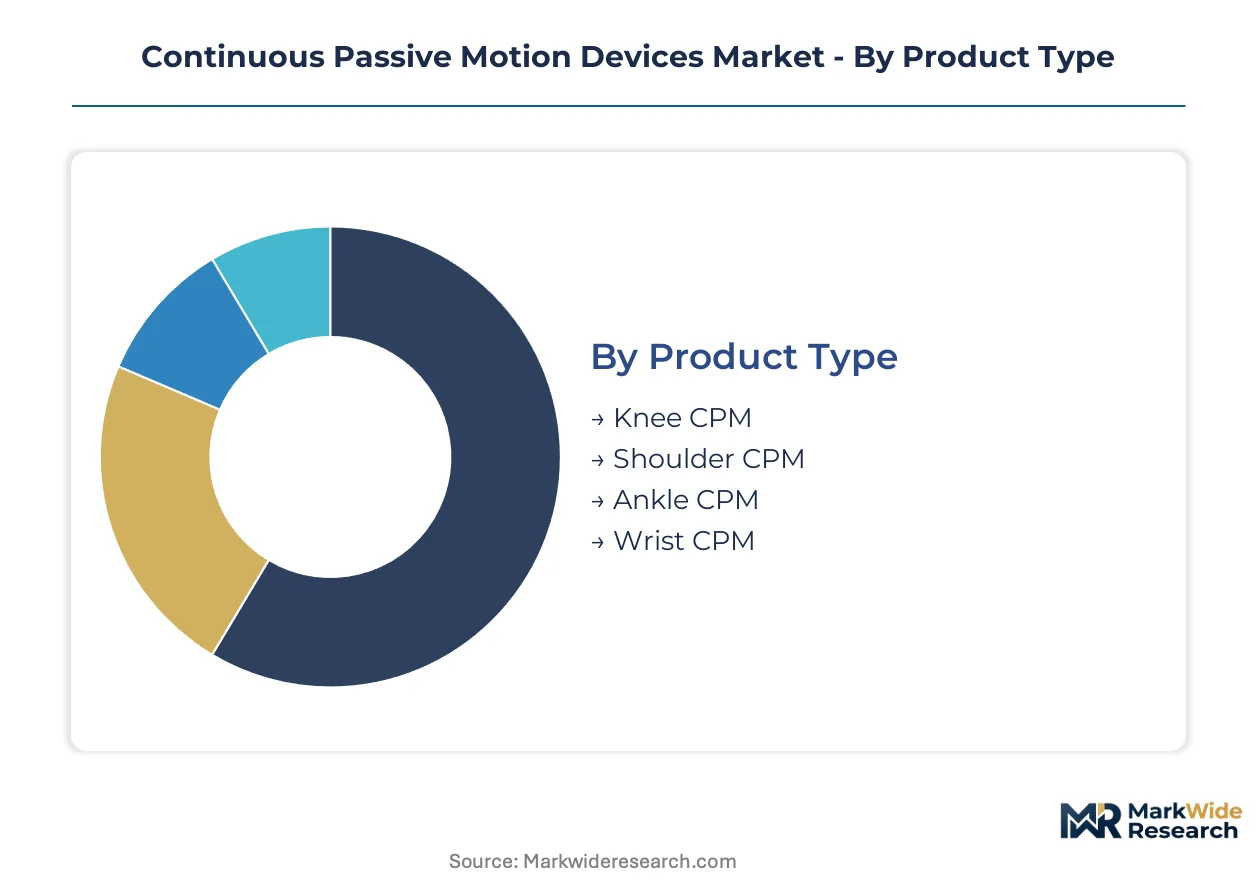
Segmentation in continuous passive motion devices reflects divergent clinical workflows across joint types and care settings. Procurement specifications vary sharply between inpatient orthopedic departments and ambulatory surgical centers, while technology tiers separate premium programmable units from basic electromechanical configurations.
Product Type:
Joint-specific anatomical requirements create distinct engineering specifications and pricing tiers across the product spectrum.
- Knee CPM:These systems employ DC motors with torque-limiting mechanisms calibrated for 0-120 degree flexion arcs typical of total knee arthroplasty protocols. Demand concentrates in United States ambulatory surgical centers where CMS bundled payment mandates standardize postoperative mobilization. Motor assembly supply chains in East Asian manufacturing clusters expose procurement to logistics volatility.
- Shoulder CPM:Configurations accommodate complex rotational patterns through programmable elevation and external rotation axes. Shoulder arthroplasty volume acceleration in aging populations drives premium positioning beyond traditional knee dominance. FDA 510(k) substantial equivalence requirements extend development cycles for novel motion ranges.
- Ankle CPM:Compact electromechanical units address subtalar joint mobilization following fracture fixation or ligament reconstruction.
- Wrist CPM:Specialized configurations target distal radius fracture recovery and carpal tunnel release rehabilitation protocols.
Knee CPM commands the established base. The steepest expansion runs through shoulder CPM configurations.
Application:
Clinical use cases segment by procedural intensity and reimbursement coding structures.
- Orthopedic Rehabilitation:Extended mobilization protocols for chronic joint stiffness employ programmable treatment libraries with session logging capabilities. Rehabilitation centers in Germany and France specify ISO 13485-certified devices under EU Medical Device Regulation procurement frameworks.
- Post-Surgery Recovery:Immediate postoperative deployment prevents arthrofibrosis following arthroplasty or ligament reconstruction. United States hospital systems integrate CPM as standard care under Comprehensive Care for Joint Replacement program requirements.
- Pain Management:Edema reduction applications leverage cyclical motion to enhance lymphatic drainage in outpatient settings.
- Sports Injury Recovery:Accelerated return-to-play protocols target professional athletic training facilities with rental program flexibility.
Post-surgery recovery anchors installed volumes. Pain management applications are climbing the fastest as opioid-sparing protocols expand.
End User:
Facility type determines capital allocation mechanisms and service bundling expectations.
- Hospitals:Inpatient orthopedic departments specify electronic control systems with remote monitoring integration for discharge planning. United States academic medical centers concentrate biomedical engineering expertise for torque-limiting mechanism specification.
- Rehabilitation Centers:European facilities under EU Medical Device Regulation Article 61 requirements demand systematic clinical data registries for knee CPM incident reporting.
- Home Care:Post-discharge deployment channels require telehealth platform convergence for remote patient tracking.
- Physiotherapy Clinics:Cost-conscious outpatient settings in price-sensitive markets retain manual mobilization protocols, limiting penetration.
Hospitals retain the dominant placement share. Home care channels gain share fastest through remote monitoring integration.
Technology:
Control interface sophistication separates procurement specifications across hospital evaluation committees.
- Electronic Controls:Programmable touchscreen interfaces with session logging and remote adjustment capabilities displace analog dials across hospital procurement specifications. Digital protocol libraries now appear as mandatory evaluation criteria in United States multi-site orthopedic networks.
- Motorized Systems:DC motor assemblies with torque-limiting mechanisms deliver predetermined arcs at controlled speeds for tissue stress prevention. Supply concentration in East Asian manufacturing clusters creates input cost exposure.
- Manual Systems:Basic mechanical configurations persist in budget-constrained outpatient clinics with limited capital expenditure authorization.
- Adjustable Range:Anatomically adaptive motion calibration addresses pediatric orthopedic sizing gaps underserved by standard configurations.
Motorized systems command the installed base. Electronic controls are expanding most quickly as programmable protocols collapse historical price stratification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DC motor assembly supply chains cluster in East Asian manufacturing centers, creating logistics exposure for device manufacturers worldwide. Procurement patterns track orthopedic procedure volumes and regulatory reimbursement frameworks across major healthcare markets.
United States
CMS bundled payment mandates through the Comprehensive Care for Joint Replacement program standardize CPM deployment in ambulatory surgical centers. FDA 510(k) clearance pathways govern commercialization timelines for programmable shoulder configurations. The Minneapolis-Saint Paul corridor concentrates biomedical engineering talent for torque-limiting mechanism design.
Germany
EU Medical Device Regulation Article 61 clinical evidence requirements shape procurement specifications for rehabilitation centers in Bavaria and North Rhine-Westphalia. ISO 13485 certification serves as a mandatory supplier qualification criterion under national healthcare procurement frameworks. The Baden-Württemberg region hosts precision motor component fabricators serving orthopedic device OEMs.
China
NMPA medical device registration rules extend market entry timelines for imported electromechanical rehabilitation systems. Domestic manufacturing clusters in Jiangsu and Zhejiang provinces supply DC motor assemblies with torque-limiting mechanisms to global CPM brands. Shanghai-based distributors coordinate aftermarket service networks across Asia-Pacific rehabilitation centers.
Japan
PMDA quality management system inspections impose rigorous post-market surveillance obligations on CPM manufacturers serving aging demographic demand. METI industrial policy supports precision electromechanical component production in the Nagoya-Chubu manufacturing belt. Tokyo academic medical centers concentrate rehabilitative biomechanics research expertise.
United Kingdom
NHS England procurement frameworks prioritize ISO 13485-certified devices with electronic control interfaces for orthopedic department standardization. MHRA vigilance reporting requirements govern post-market safety monitoring for knee CPM systems with substantial installed bases. The Oxford-Cambridge-London corridor concentrates medical technology venture financing for remote monitoring integration.
Continuous Passive Motion Devices Market Vendor Landscape
Full-line orthopedic conglomerates and specialized rehabilitation equipment fabricators split the market between integrated service bundling and anatomical specialization strategies. The vendor base concentrates around three archetypes: multinational device conglomerates with clinical support networks, mid-scale regional specialists with rental program flexibility, and niche pediatric configuration experts. Competitive maneuvering centers on aftermarket service contract penetration and programmable protocol differentiation.
Among the full-line conglomerates, DJO Global exemplifies the service-integrated archetype through its hospital system maintenance contract footprint. Chattanooga occupies a position within the rental-flexibility tier, while Furniss Corporation anchors the pediatric specialization segment. European fabricators including OPED GmbH and Chinesport Rehabilitation sit within the regional-quality-certification cluster, leveraging proximity to EU MDR compliance pathways.
| Leading Market Players |
|---|
| DJO Global |
| Furniss Corporation |
| Surgi-Care |
| Bio-Med |
| BTL Corporate |
| Chattanooga |
| Chinesport Rehabilitation |
| Rimec |
| OPED GmbH |
| Others |
Supply Flow & Price Mechanics
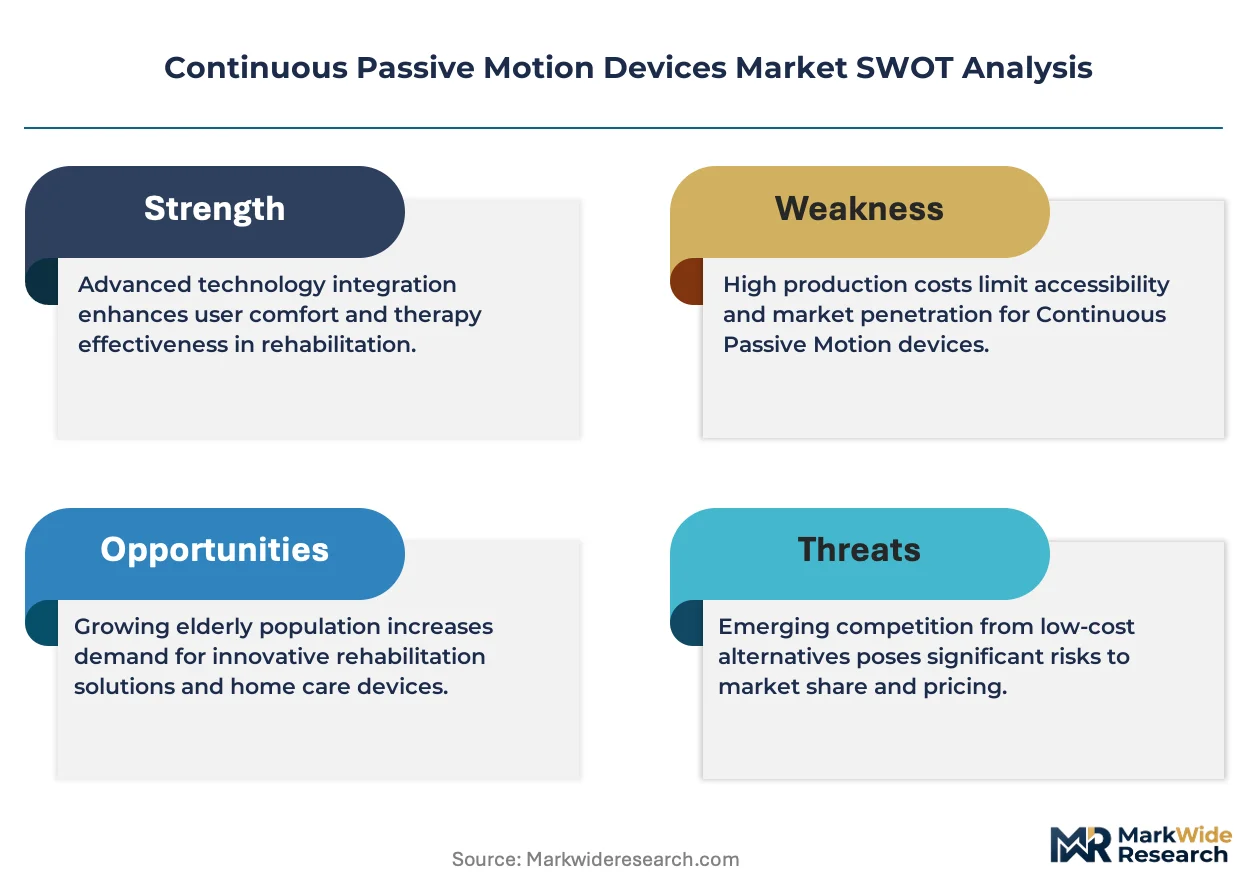
Tariff exposure on precision motor assemblies from East Asian manufacturing clusters compresses margin structures across all pricing tiers while simultaneously forcing procurement diversification into higher-cost regional fabricators. This dual pressure widens spreads between economy electromechanical units and premium programmable configurations as manufacturers pass through input volatility differentially.
Pricing Analysis
FDA 510(k) substantial equivalence requirements dictate the pricing tier structure by extending commercialization timelines and concentrating development overhead in premium shoulder CPM configurations. Three-tier pricing structure across premium, standard, and economy levels separates programmable touchscreen units with remote monitoring from basic motorized systems and manual alternatives. Pricing pressure stems from rental-to-own conversion structures preferred by ambulatory surgical centers seeking operational budget treatment. Price-sensitive physiotherapy clinics in budget-constrained markets retain manual mobilization protocols, while academic medical centers demonstrate lowest sensitivity to premium positioning for ISO 13485-certified electronic control systems.
Supply Chain Analysis
DC motor assemblies with torque-limiting mechanisms feed from concentrated fabrication clusters in Jiangsu and Zhejiang provinces of China, with secondary sourcing from South Korean precision component specialists and Japanese electromechanical producers in the Nagoya-Chubu belt. Raw material dependencies center on rare-earth magnet supply for motor torque calibration, medical-grade aluminum extrusions for frame construction, and specialized polymer bearings for motion arc precision. Single-source vulnerability concentrates in East Asian torque-limiting mechanism suppliers, exposing global manufacturers to logistics chokepoint risk. Distribution runs through Shanghai-based distributors coordinating aftermarket service networks, hospital system GPO contracts, and direct procurement by multi-site orthopedic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in rehabilitative biomechanics and torque-limiting mechanism design concentrates at select academic medical centers, constraining product development velocity and creating asymmetric capability advantages for incumbent manufacturers with established clinical engineering partnerships.
For Market Incumbents: Harden defensive positioning by deepening backward integration into precision motor component supply through captive relationships with Baden-Württemberg fabricators, insulating against East Asian logistics volatility. Fortify ISO 13485 certification moats to exploit EU MDR Article 61 evidentiary barriers that delay non-compliant competitor entry into European rehabilitation centers. Accelerate software companion development for remote monitoring integration to capture post-discharge patient tracking revenue streams before substitute telehealth platforms erode device attachment rates. For New Entrants and Emerging Players: Pediatric orthopedic configurations with anatomically adaptive sizing represent the most penetrable entry point, as specialized motion calibration for juvenile patients remains underserved by full-line conglomerates focused on adult knee and shoulder volumes. EU MDR compliance pathway completion offers durable competitive positioning in German and French rehabilitation centers where procurement specifications mandate systematic clinical data registries. Target hospital system maintenance contract disruption through aggressive aftermarket service bundling that converts capital expenditures into operational budgets preferred by ambulatory surgical center administrators. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive torque-limiting mechanism design capabilities and established FDA 510(k) predicate device libraries. Long-term viability hinges on software-enabled protocol differentiation rather than electromechanical hardware commoditization, favoring acquisition targets with programmable treatment platform development pipelines. Monitor CMS reimbursement coding revisions for bundled payment framework adjustments that signal ambulatory surgical center willingness to absorb CPM placement costs versus rental model acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates commercialization timelines for novel motion range demonstrations in shoulder configurations. |
| CE Marking Pathway | Creates durable competitive moats under EU MDR Article 61 evidentiary requirements for knee CPM systems. |
| Hospital System Partnership | Locks in recurring maintenance contract revenue across multi-site orthopedic networks preferring operational budgets. |
| Software Companion Development | Enables remote patient tracking integration with telehealth platforms for post-discharge deployment channels. |
| Reimbursement Strategy | Aligns CPM protocol standardization with CMS Comprehensive Care for Joint Replacement program mandates. |
Methodological Framework
The analysis maps knee, shoulder, ankle, and wrist CPM configurations alongside electronic control and motorized system technology tiers, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and rehabilitation center procurement leads. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, ISO 13485 certification registries, CMS Medicare reimbursement coding frameworks, and hospital procurement database extracts. Bottom-up unit placement modeling triangulated against top-down orthopedic procedure volume projections from national health statistics repositories.
Assumptions held fixed include FDA regulatory pathway timelines, ISO 13485 certification as mandatory supplier qualification, and CMS bundled payment framework continuity, while variables included shoulder arthroplasty volume acceleration rates and rental-to-own conversion adoption curves across ambulatory surgical centers. The projection horizon spans product type, application, end user, and technology segmentations with geographic disaggregation by national regulatory cluster. CAGRs derived from orthopedic procedure volume elasticity to aging demographic trends and CPM protocol penetration rates in post-surgery recovery settings. Forecast inputs incorporated DC motor supply chain concentration risk and EU MDR clinical evidence burden timelines.
Stress conditions across East Asian logistics disruption scenarios, FDA 510(k) timeline compression events, and CMS reimbursement coding revision cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory pathway acceleration or deceleration, supply chain reconfiguration, and reimbursement framework restructuring. Cross-checking against hospital capital expenditure survey data and ambulatory surgical center operational budget allocation benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Global Corneal Topographers Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
3D Printed Prosthetics Market
Medical Devices
Glass Syringe Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Aortic Cannula Systems Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Kirschner Wires Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
Sleep Apnea Devices Market
Medical Devices
Implantable Collamer Lens Market