
 Global Renal Biomarkers Market | 2026-2036
Global Renal Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Renal Biomarkers Market Analysis
Modular assay panel design is decoupling biomarker testing from fixed-platform contracts, letting buyers mix ELISA, immunoassay, and mass spectrometry components across vendors. Siemens Healthineers anchors its position through integrated analyzer systems that span hospital and laboratory settings. Abbott Laboratories leverages point-of-care immunoassay expertise to compete in decentralized kidney function monitoring. F. Hoffmann-La Roche Ltd sustains leadership in clinical diagnostics through high-throughput automated platforms.
Renal biomarkers are measurable biological indicators—encompassing proteins, metabolites, and genetic markers such as neutrophil gelatinase-associated lipocalin (NGAL), kidney injury molecule-1 (KIM-1), and cystatin C—that signal kidney structure or function changes through quantifiable concentration thresholds in blood or urine. These indicators serve primarily to detect acute kidney injury, monitor chronic kidney disease progression, and stratify patient risk in clinical and pharmaceutical research settings. Immunoassay technology dominates current clinical workflows due to established sensitivity and regulatory familiarity, while mass spectrometry segments are gaining traction in research and precision medicine applications where multiplexed protein quantification delivers superior specificity. Diagnostic laboratories represent the most concentrated end-user margin pool, though contract research organizations are expanding biomarker utilization in pharmaceutical drug development pipelines.
FDA premarket review pathways and EMA's In Vitro Diagnostic Regulation shape product approval timelines and performance validation requirements for commercial assay developers. ISO 13485 quality management standards and CLIA laboratory certification in the United States further constrain market entry for non-compliant manufacturers. Stakeholders must monitor evolving reimbursement codes for novel biomarker panels across Medicare, NHS England, and Japan's MHLW to anticipate revenue model shifts.
Market Dynamics
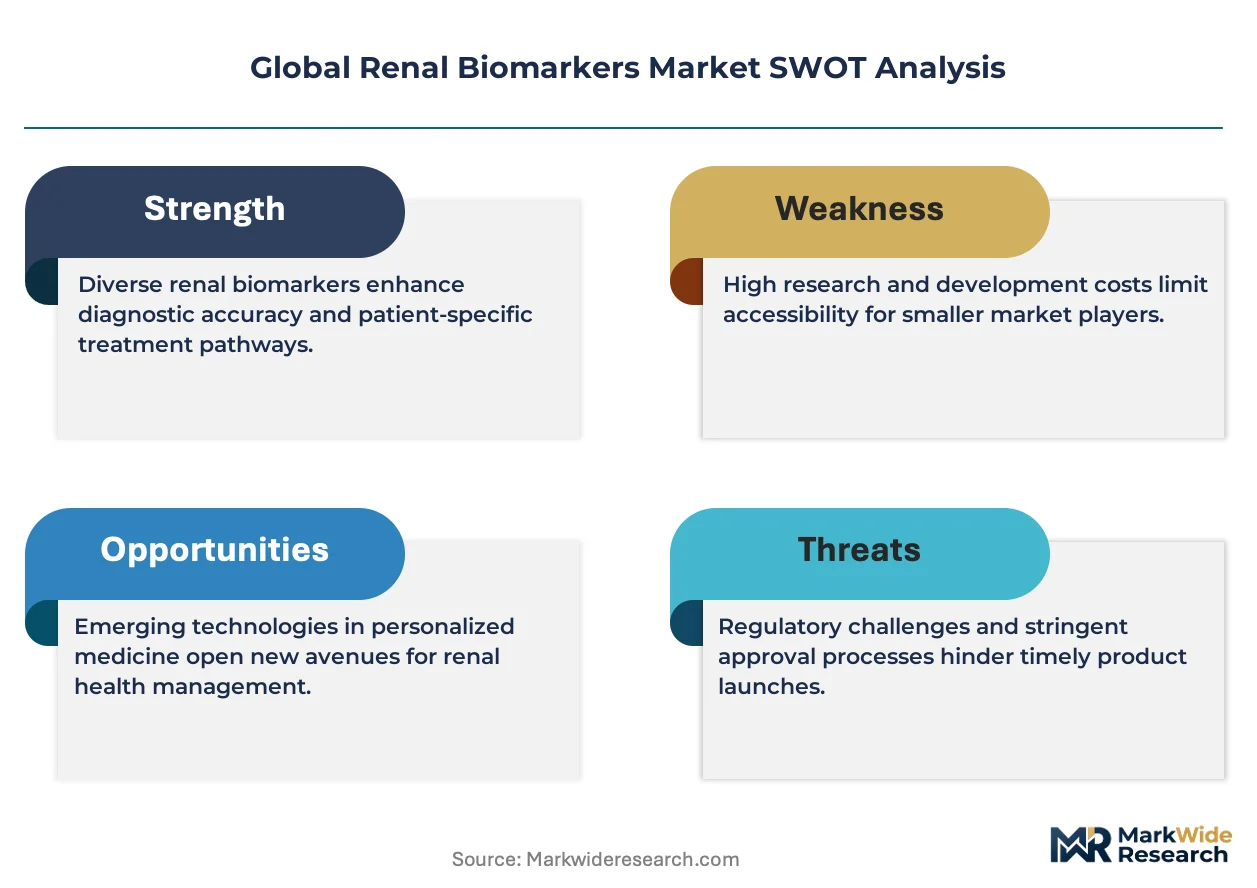
Modular assay architectures are fragmenting purchasing power across the renal biomarker value chain, forcing platform vendors to unbundle reagent contracts from hardware lock-in and ceding margin to specialized component suppliers.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:Streamlined conformity assessment pathways compress validation timelines for novel biomarker panels, accelerating commercialization of NGAL and KIM-1 assays across European diagnostic networks.
- Point-of-care decentralization:Hospital emergency departments and dialysis clinics are deploying compact immunoassay readers at the bedside, reducing central lab turnaround for acute kidney injury triage.
- Mass spectrometry multiplexing:Research laboratories in Germany and Japan are adopting LC-MS/MS workflows for simultaneous protein quantification, driving demand for standardized calibrator kits.
Market Restraints
- Antibody supply concentration:Capture reagent production clusters with a limited set of contract manufacturers in Switzerland and the United States, exposing assay developers to batch variability and allocation constraints.
- Reimbursement code lag:Medicare and NHS England coverage determinations for novel biomarker combinations trail FDA 510(k) clearance by 18-36 months, delaying revenue recognition.
- ELISA platform persistence:Immunoassay infrastructure sunk costs in hospital laboratories slow adoption of mass spectrometry alternatives despite superior analytical specificity.
Strategic Opportunities
- India preventive screening:Expansion of chronic kidney disease detection camps in Maharashtra and Tamil Nadu creates demand for affordable, heat-stable lateral flow assays.
- Companion diagnostic alignment:FDA breakthrough device designation for nephrotoxicity monitoring in oncology trials opens parallel revenue streams for biomarker developers.
- AI-assisted pattern recognition:Integration of machine learning algorithms with multi-analyte panels is automating risk stratification for diabetic kidney disease progression.
Industry Challenges
- Cross-platform harmonization:Variability in calibrator materials between Siemens Healthineers, Abbott, and Roche systems complicates longitudinal patient monitoring across care transitions.
- Specialized field service density:Mass spectrometry installations require trained engineers for maintenance, constraining placement in secondary markets outside Tokyo, Munich, and Boston medical corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Renal Biomarkers Market |
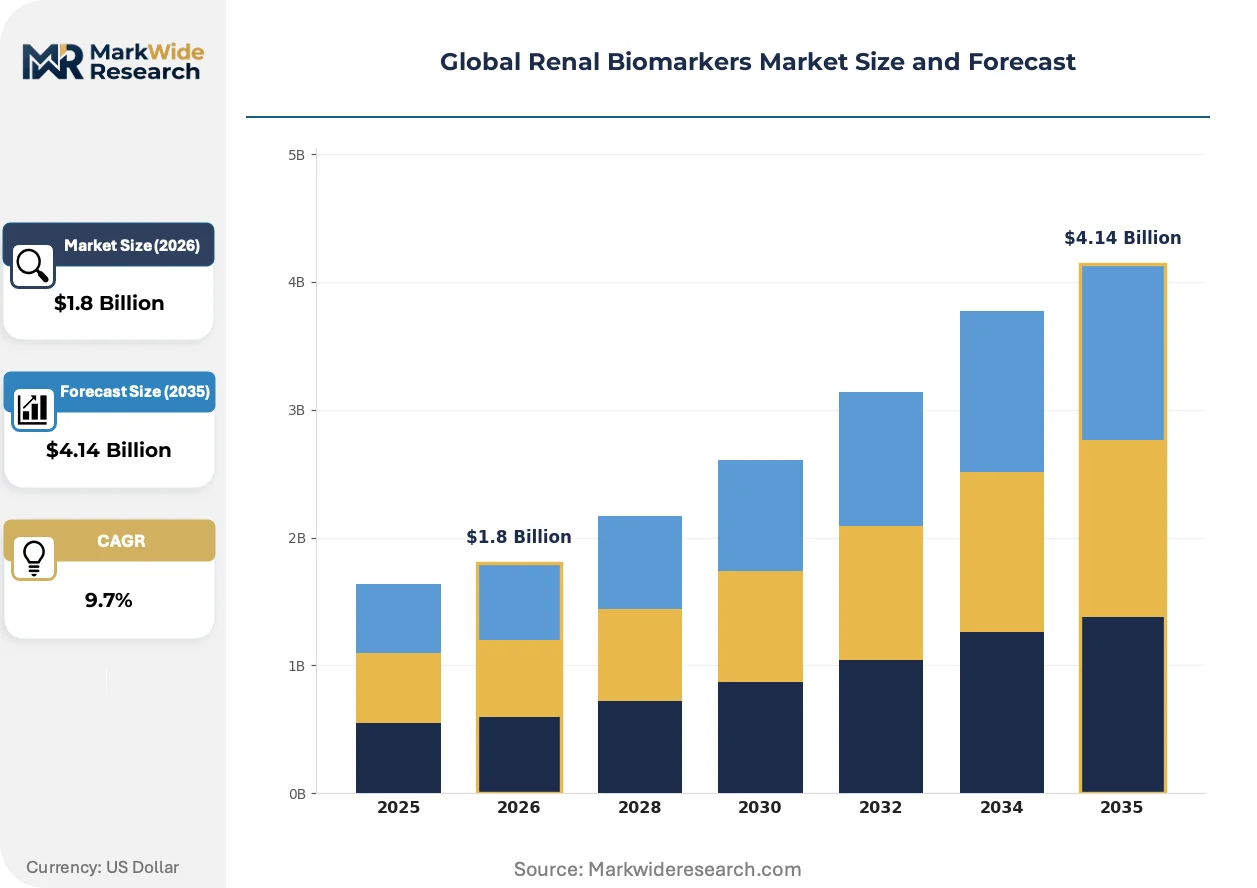
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarkers, Kits, Assays, Reagents Technology: ELISA, PCR, Mass Spectrometry, Immunoassay Application: Clinical Diagnostics, Drug Development, Research, Personalized Medicine End User: Hospitals, Diagnostic Laboratories, Research Institutions, Contract Research Organizations |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Siemens Healthineers AG, Danaher Corporation, Thermo Fisher Scientific Inc., bioMérieux SA, Bio-Rad Laboratories, Inc., Sysmex Corporation, BioPorto Diagnostics A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Renal Biomarkers Market Emerging Trajectories
Digital pathology integration and machine learning classification are compressing the interpretive bottleneck in biomarker quantification, shifting value capture from raw assay sales toward algorithm-enabled diagnostic services.
Automated sample-to-answer platforms are consolidating pre-analytical processing, incubation, and detection into single-instrument workflows. Large reference laboratories in the United States are deploying these systems to offset technologist staffing constraints. The technology is automating error-prone manual pipetting steps and compressing turnaround times for STAT kidney function panels.
REACH chemical registration requirements are tightening specifications for assay reagent stability and transport classification. European manufacturers are reformulating buffer compositions to eliminate substances of very high concern. In vitro diagnostic producers with existing ISO 13485 frameworks are adapting quality management systems to incorporate extended material safety documentation.
Hospital procurement committees are unbundling reagent contracts from analyzer placement agreements, negotiating spot pricing for high-volume biomarker tests. This disintermediation favors specialized assay developers with flexible manufacturing scale over integrated platform vendors. The pattern is most pronounced in German hospital networks seeking to diversify supply risk across multiple immunoassay providers.
Global Renal Biomarkers Market Segmentation
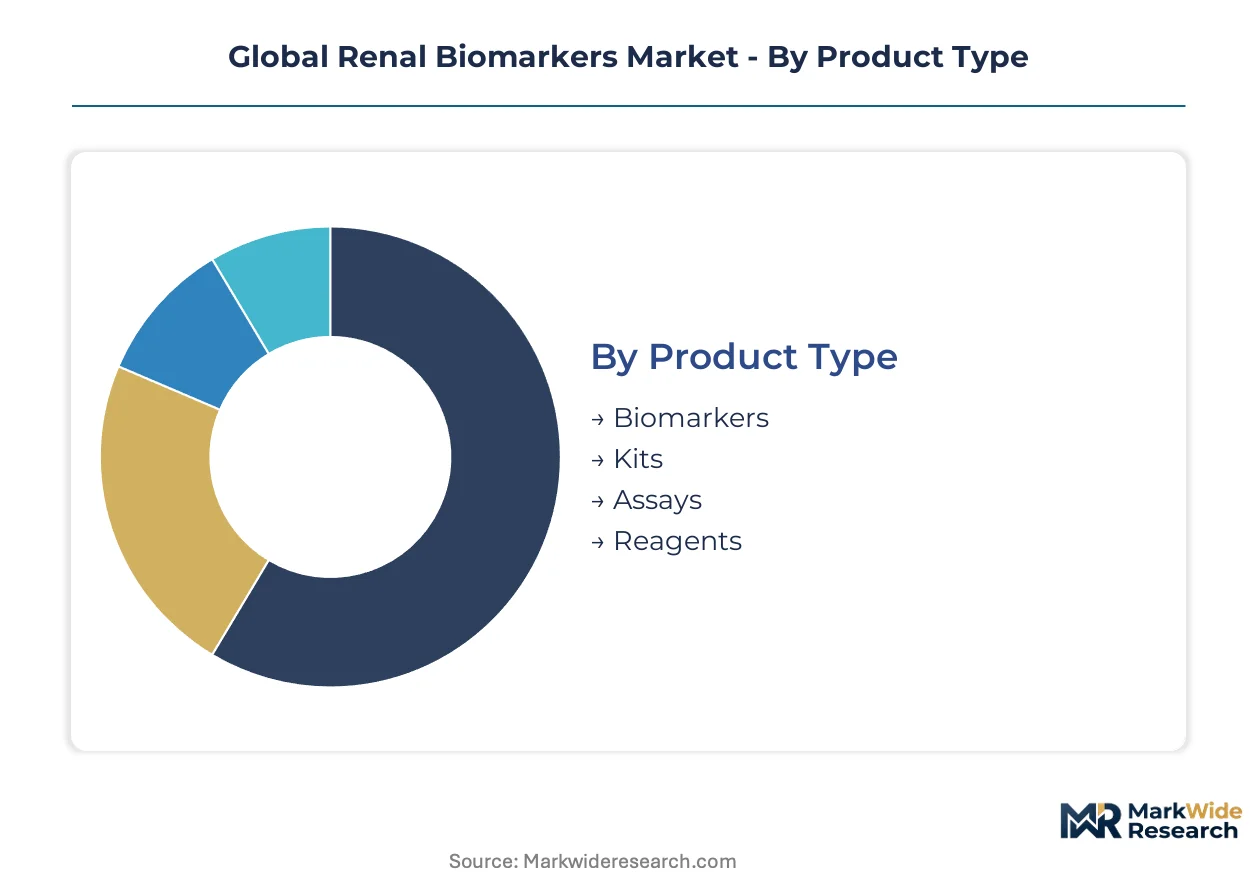
Renal biomarker commercialization paths diverge sharply across product formats and testing modalities. Regulatory burden intensity varies by segment, shaping which manufacturers can compete in hospital versus research settings.
Product Type:
FDA 510(k) clearance and EMA CE marking requirements scale with product complexity, with full assay systems facing multi-year validation timelines that reagent-only suppliers bypass.
- Biomarkers:Purified proteins and synthetic peptides serve as calibrator materials and control substances across NGAL, KIM-1, and cystatin C quantification workflows. Academic medical centers in the United States and Germany drive procurement for standardized reference materials that enable cross-platform harmonization.
- Kits:Pre-configured reagent packs bundle capture antibodies, detection conjugates, and substrate solutions for specific platform formats. Diagnostic laboratories in Japan prioritize kit configurations compatible with existing analyzer footprints to avoid capital replacement cycles.
- Assays:Complete test systems with defined performance specifications require full regulatory dossiers for clinical claims. Contract research organizations absorb the majority of assay volume for pharmaceutical toxicology studies where GLP compliance is mandatory.
- Reagents:Bulk antibody and enzyme preparations supply in-house assay development programs at large reference laboratories. Supply concentration among contract manufacturers in Switzerland and the United States creates allocation risk during demand surges.
Reagents sit at the top of the volume ranking, with assays climbing the fastest as laboratories outsource validation burden to specialized developers.
Technology:
Capital intensity and technical staffing requirements create distinct customer tiers, with high-complexity platforms concentrating in major metropolitan medical corridors.
- ELISA:Enzyme-linked immunosorbent assay workflows dominate hospital laboratory infrastructure through established SOPs and technologist familiarity. Sunk equipment costs in secondary care facilities across the United States and Germany slow displacement despite longer turnaround times.
- PCR:Nucleic acid amplification methods detect genetic polymorphisms associated with drug-induced nephrotoxicity susceptibility. Research institutions in Japan deploy PCR-based panels for pharmacogenomic stratification in oncology trials.
- Mass Spectrometry:LC-MS/MS platforms deliver multiplexed protein quantification with superior analytical specificity for precision medicine applications. Installation density concentrates in Boston, Munich, and Tokyo due to specialized field service engineer requirements.
- Immunoassay:Automated chemiluminescence and electrochemiluminescence systems process high-throughput STAT panels in centralized laboratories. Siemens Healthineers, Abbott, and Roche instrument placements lock in reagent consumption through bundled contracts.
Immunoassay commands the largest installed base, while mass spectrometry gains share fastest among academic medical centers building precision medicine capabilities.
Application:
Reimbursement pathway maturity determines addressable market size, with clinical diagnostics holding established CPT codes while emerging applications await coverage determinations.
- Clinical Diagnostics:Acute kidney injury triage and chronic kidney disease monitoring generate recurring test volume through Medicare and NHS England reimbursement. Point-of-care deployment in emergency departments and dialysis clinics is expanding test access beyond centralized laboratory networks.
- Drug Development:Nephrotoxicity biomarker panels support FDA-mandated safety monitoring in oncology and immunology trials. Contract research organizations in the United States and Germany integrate NGAL and KIM-1 into adaptive trial designs for early risk detection.
- Research:Exploratory biomarker discovery programs at academic medical centers drive demand for flexible assay formats and custom antibody development. Mass spectrometry multiplexing enables simultaneous quantification of novel protein candidates without prior clinical validation.
- Personalized Medicine:Risk stratification algorithms combining multiple analytes with electronic health record data automate diabetic kidney disease progression forecasting. Pilot programs in Japanese and German healthcare systems are validating AI-assisted interpretation workflows.
Clinical diagnostics anchors revenue concentration, with drug development expanding most quickly as FDA breakthrough device designations accelerate companion diagnostic alignment.
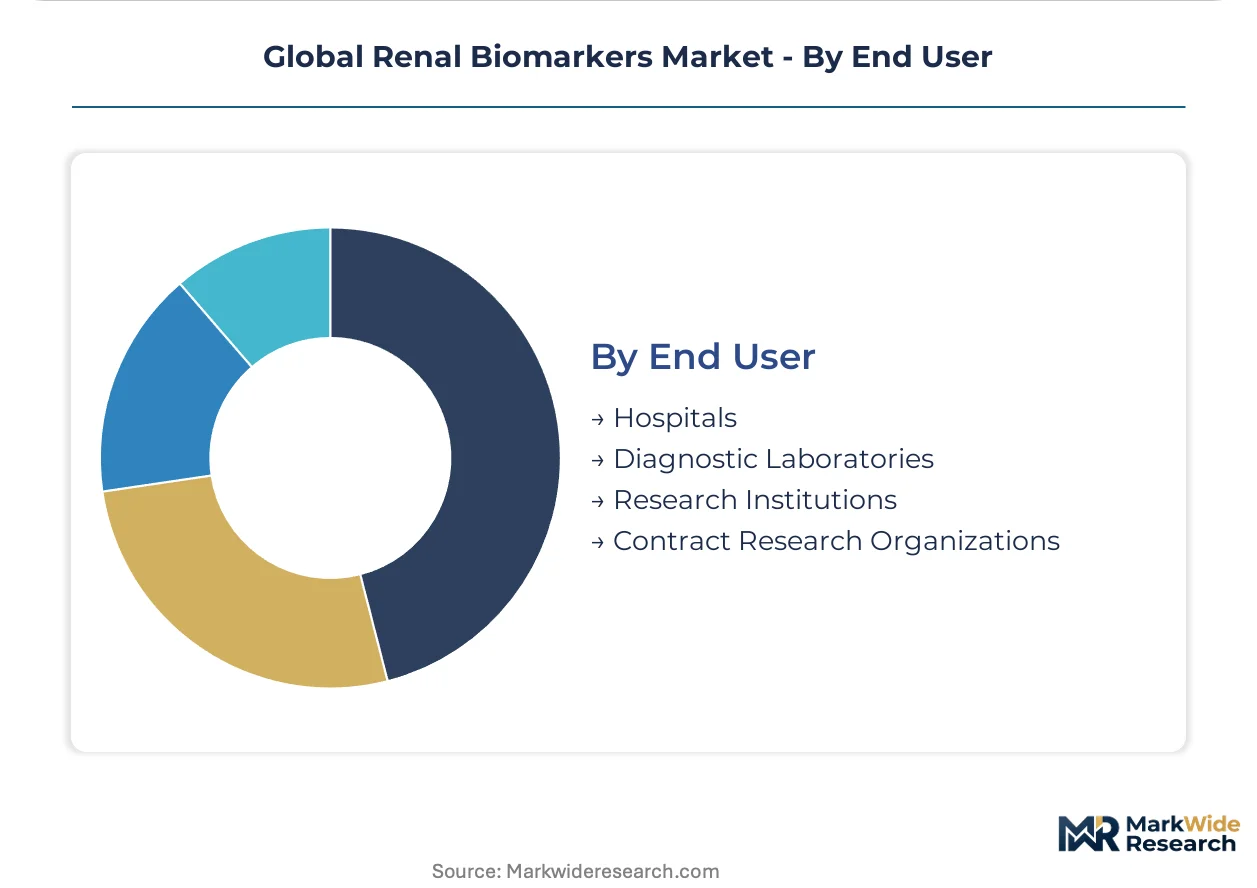
End User:
Purchasing authority and budget structure shape vendor engagement models, with integrated delivery networks negotiating enterprise contracts distinct from institutional procurement.
- Hospitals:Emergency departments and intensive care units deploy point-of-care immunoassay readers for STAT kidney function assessment. Procurement committees are unbundling reagent contracts from analyzer placements to diversify supply risk across multiple vendors.
- Diagnostic Laboratories:Large reference laboratories in the United States automate pre-analytical processing through sample-to-answer platforms that offset technologist staffing constraints. Expanded test menus for early kidney disease detection are driving capital investment in high-throughput systems.
- Research Institutions:Academic medical centers in Germany and Japan adopt mass spectrometry workflows for multiplexed protein quantification in precision medicine studies. Flexible assay configurations support exploratory biomarker discovery without clinical diagnostic claims.
- Contract Research Organizations:Pharmaceutical toxicology services integrate renal biomarker panels into GLP-compliant safety assessment protocols. FDA premarket review pathways for companion diagnostics are accelerating biomarker validation timelines for oncology drug developers.
Diagnostic laboratories generate the highest test volume, with contract research organizations gaining share fastest as pharmaceutical pipeline expansion drives outsourced safety monitoring demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Renal biomarker commercialization traces its clinical validation roots to German academic medical centers and Japanese diagnostic networks, where standardized reference materials for NGAL and cystatin C quantification first achieved regulatory acceptance. These historical foundations established quality benchmarks that now shape procurement decisions across diagnostic laboratories worldwide.
United States
Medicare reimbursement pathways for chronic kidney disease screening drive test volume concentration in large reference laboratories. FDA 510(k) clearance timelines for novel biomarker panels compress as breakthrough device designations accelerate nephrotoxicity monitoring in oncology trials. Boston and San Diego medical corridors host the densest concentration of mass spectrometry installations for precision medicine applications.
Germany
Hospital procurement committees in Bavaria and North Rhine-Westphalia unbundle reagent contracts from analyzer placements, diversifying supply risk across multiple immunoassay vendors. EMA In Vitro Diagnostic Regulation conformity assessments streamline CE marking for NGAL and KIM-1 assays. Munich anchors the highest density of LC-MS/MS workflows for multiplexed protein quantification in European research networks.
Japan
MHLW reimbursement codes for early kidney disease detection expand test access beyond centralized laboratory networks. PMDA consultation pathways for companion diagnostics accelerate biomarker validation timelines for pharmaceutical developers. Tokyo and Osaka metropolitan areas concentrate point-of-care immunoassay deployment in dialysis clinics and emergency departments.
Switzerland
Contract manufacturers in Basel and Zurich regions supply capture reagents that feed assay development pipelines across European diagnostic networks. Swissmedic quality management requirements enforce ISO 13485 compliance that constrains market entry for non-compliant manufacturers. The country's antibody production concentration exposes developers to batch variability during demand surges.
India
State governments in Maharashtra and Tamil Nadu operate chronic kidney disease detection camps that create demand for affordable lateral flow assays. CDSCO import licensing requirements for diagnostic reagents shape vendor selection criteria for hospital procurement committees. Bangalore and Hyderabad research institutions pilot AI-assisted risk stratification for diabetic kidney disease progression.
Global Renal Biomarkers Market Vendor Landscape
The competitive structure tilts toward integrated platform vendors with captive reagent ecosystems. Diagnostic laboratories and hospital networks concentrate purchasing power through multi-year analyzer placement agreements that lock in consumable revenue streams. Three archetypes dominate: diversified conglomerates with full diagnostic portfolios, specialized biomarker assay developers with flexible manufacturing scale, and precision medicine technology providers with mass spectrometry expertise. Competitive moves center on unbundling negotiations to break hardware-reagent ties and strategic partnerships to secure antibody supply allocation.
Among diversified diagnostic conglomerates, F. Hoffmann-La Roche Ltd, Abbott Laboratories, and Siemens Healthineers AG exemplify the integrated platform archetype. Roche represents the high-throughput automated systems tier that sustains leadership in clinical diagnostics through bundled instrument-reagent contracts. Abbott occupies a position at the point-of-care vector, leveraging immunoassay expertise for decentralized kidney function monitoring applications. Siemens Healthineers anchors the hospital-laboratory spanning segment through analyzer systems that consolidate pre-analytical processing and detection workflows. These three entities collectively illustrate how platform breadth and regulatory dossier depth create defensive moats against specialized assay developers seeking to fragment purchasing power.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| bioMérieux SA |
| Bio-Rad Laboratories, Inc. |
| Sysmex Corporation |
| BioPorto Diagnostics A/S |
| Others |
Supply Flow & Price Mechanics
Capture antibody production costs in Swiss and United States contract manufacturing facilities cascade through assay pricing tiers, with high-affinity monoclonal lots commanding premium placement in automated immunoassay platforms while polyclonal alternatives serve cost-sensitive lateral flow applications in Indian screening programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared automated assays from CE-marked kits and unregulated research reagents. Price differentiation hinges on regulatory certification tier and analyzer platform lock-in status. Cost compression in the economy tier is intensifying because Indian state governments negotiate bulk procurement for detection camps. Contract research organizations exhibit lowest price sensitivity due to GLP compliance requirements, while hospital procurement committees in Germany drive hardest bargain for reagent unbundling.
Supply Chain Analysis
Specialized field service engineer availability constraints in secondary metropolitan areas outside Boston, Munich, and Tokyo limit mass spectrometry placement density and shape regional manufacturing footprint decisions. Antibody production concentrates in Switzerland and the United States, with calibrator material sourcing anchored in German academic medical centers. Single-source vulnerability persists for high-affinity capture reagents during demand surges from oncology trial expansion. Distribution runs through diagnostic laboratory networks and contract research organization procurement channels with diverging fulfillment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The renal biomarker market represents a late-cycle quality story where diagnostic laboratories now prioritize cross-platform harmonization and standardized reference materials over raw throughput specifications.
For Market Incumbents: To counter reagent contract unbundling by German hospital procurement committees, pursue backward integration into antibody production through Swiss manufacturing partnerships and accelerate ISO 13485 certification investments that constrain non-compliant competitors from European tender participation. For New Entrants and Emerging Players: Direct-to-laboratory digital procurement platforms enable bypass of established distributor relationships that lock in Siemens Healthineers and Roche placements. Target Maharashtra and Tamil Nadu state health department tenders for heat-stable lateral flow assays, leveraging CDSCO import licensing navigation as differentiated service capability. For Investors and Strategic Acquirers: Roll-up economics work for specialized biomarker assay developers because EMA In Vitro Diagnostic Regulation compliance costs are fragmenting the vendor base below viable scale thresholds. Platform-rollup viability extends across a five-to-ten year window with companion diagnostic alignment serving as the inflection signal to monitor for valuation step-change.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Alignment | FDA breakthrough device designation for nephrotoxicity monitoring accelerates biomarker validation timelines for oncology drug developers. |
| Cross-Platform Harmonization | Standardized calibrator materials enable longitudinal patient monitoring across Siemens Healthineers, Abbott, and Roche system transitions. |
| Point-of-Care Decentralization | Compact immunoassay readers in emergency departments and dialysis clinics reduce central lab turnaround for acute kidney injury triage. |
| AI-Assisted Pattern Recognition | Machine learning integration with multi-analyte panels automates risk stratification for diabetic kidney disease progression forecasting. |
| Antibody Supply Security | Swiss and United States contract manufacturer partnerships mitigate batch variability exposure during pharmaceutical pipeline demand surges. |
Methodological Framework
Multiple input streams — primary interviews with diagnostic laboratory directors, hospital procurement managers, and regulatory affairs specialists; secondary validation against FDA 510(k) filings, EMA CE marking databases, and CMS reimbursement code updates; plus trade data from Swissmedic and PMDA registration records — were reconciled through bottom-up test volume modeling and top-down market sizing triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation dimensions spanning product format, technology platform, application setting, and end-user procurement structure. CAGRs were derived from modeled test volume trajectories and pricing evolution assumptions, incorporating EMA In Vitro Diagnostic Regulation implementation pace and Medicare coverage determination timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for mass spectrometry multiplexing would alter the outlook if specialized field service engineer training programs expand beyond current Boston, Munich, and Tokyo concentration. Forecasts reflect assumptions regarding reimbursement code expansion velocity and antibody supply allocation stability. Material deviation in FDA breakthrough device designation granting rates or Swiss contract manufacturer capacity constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Glucose Tolerance Test Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
EMEA Meningitis Diagnostic Testing Market
Diagnostics
Creatine Kinase Reagent Market
Diagnostics
Liver Function Tests Market
Diagnostics
At-Home Cancer Testing Market