
 Global Consumer Genomics Market | 2026-2036
Global Consumer Genomics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Consumer Genomics Market Foresight
Multi-source sequencing partnerships is shifting how consumer genomics firms secure laboratory capacity and bioinformatics pipelines. Ancestry leverages its proprietary DNA database to sustain subscription-based genealogy services. 23andMe, Inc. anchors its competitive position through FDA-cleared pharmacogenetic reports. Illumina, Inc. dominates upstream instrument supply, controlling the cost structure of most downstream consumer tests.
Consumer genomics encompasses the direct-to-consumer analysis of genetic material—typically via saliva-based DNA collection followed by SNP array or next-generation sequencing—to generate ancestry, health risk, and trait reports without clinician intermediation. The field relies on beadchip microarrays interrogating hundreds of thousands of single nucleotide polymorphisms or low-pass whole genome sequencing achieving coverage depths of 4-30x for imputation-based variant calling. Ancestry Testing occupies the largest volume position due to lower price points and broad demographic appeal, while Pharmacogenomics represents the fastest-expanding application segment as drug-gene interaction awareness spreads among consumers and payers. Whole Genome Sequencing commands premium positioning but remains constrained by interpretation costs and variant-of-uncertain-significance counseling burdens.
The FDA's direct-to-consumer genetic testing oversight framework and the EU's GDPR genetic data protections create divergent compliance requirements across the Atlantic. The FDA's 510(k) and de novo pathways for genetic risk tests shape product development timelines and marketing claims in the United States, while GDPR's special-category data rules impose storage, consent, and portability obligations throughout Europe. ISO 15189 medical laboratory accreditation and CAP proficiency testing standards further discipline analytical validity claims. Stakeholders must monitor evolving reimbursement decisions for pharmacogenomic testing by major US payers and European sickness funds, as coverage expansion would fundamentally alter consumer willingness to pay.
Market Dynamics
The FDA's evolving de novo pathway for direct-to-consumer pharmacogenetic tests is compressing product development timelines while fragmenting competitive positioning between firms with cleared health-risk reports and those confined to ancestry-only offerings.
Growth Catalysts
- Pharmacogenomic reimbursement expansion:UnitedHealth and Anthem coverage decisions for drug-gene interaction testing are converting out-of-pocket demand into insured utilization. Payer adoption accelerates consumer willingness to test.
- SNP array cost collapse:Illumina's beadchip manufacturing scale has driven per-sample genotyping below twenty dollars. Laboratory economics now support sub-hundred-dollar retail pricing.
- Germany's DVG genetic diagnostics framework:The Digitale-Versorgung-Gesetz reimbursement pathway for predictive genetic testing is opening Europe's largest private-pay market to health-risk consumer offerings.
Market Restraints
- Illumina instrument lock-in:Captive supply contracts for NovaSeq and iSeq systems constrain laboratory switching costs. Alternative sequencing platforms lack equivalent throughput for high-volume consumer processing.
- Variant interpretation bottleneck:American College of Medical Genetics guidelines for variants of uncertain significance impose mandatory genetic counseling referrals. Per-case review costs exceed raw sequencing expenses.
- GDPR special-category data rules:Article 9 genetic data protections mandate explicit consent, storage limitation, and portability rights. European operational compliance adds fifteen to twenty percent overhead versus US-only operations.
Strategic Opportunities
- Brazil's ANVISA regulatory modernization:Proposed genetic testing guidance would permit direct-to-consumer health-risk marketing. First-mover positioning in Latin America's largest economy offers database scale advantages.
- Polygenic risk score integration:Convergence of SNP arrays with machine-learned trait prediction is enabling coronary artery disease and type 2 diabetes risk stratification. Wellness platforms represent new distribution channels.
- South Korea's bio-health industry stimulus:MFDS fast-track review for AI-enhanced genetic interpretation tools subsidizes local bioinformatics development. Partnership structures reduce foreign firm regulatory burden.
Industry Challenges
- Bioinformatics talent scarcity:Variant curation and polygenic model development require dual training in statistical genetics and clinical annotation. Compensation inflation in Cambridge and San Francisco clusters squeezes mid-tier laboratory margins.
- FDA 510(k) predicate drift:Changing standards for analytical validity demonstrations force iterative submission amendments. Timeline uncertainty disrupts marketing calendar synchronization with ancestry subscription renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Consumer Genomics Market |
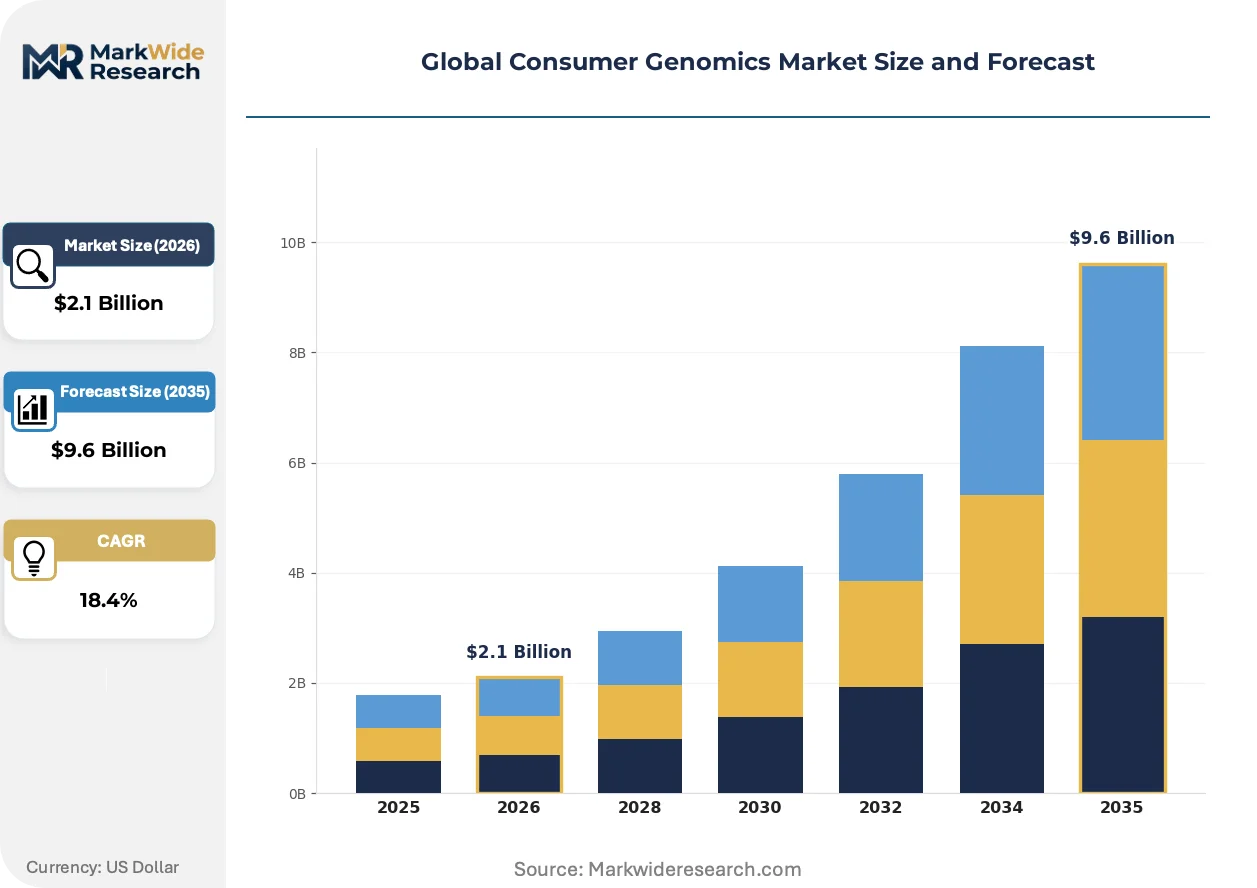
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.6 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Genome Sequencing, Exome Sequencing, Targeted Gene Sequencing, Ancestry Testing, Carrier Screening Application: Personalized Wellness, Nutrigenomics, Pharmacogenomics, Trait Prediction, Genetic Counseling End User: Direct-to-Consumer Services, Healthcare Providers, Research Institutions, Fitness Enthusiasts Distribution Channel: Online Platforms, Specialty Stores, Pharmacies, Clinics |
| Companies Covered | Ancestry, 23andMe, Inc., Illumina, Inc., Myriad Genetics, Inc., Color Genomics, Inc., Gene By Gene, Ltd. (FamilyTree DNA), Helix OpCo LLC, MyHeritage Ltd., Veritas Genetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Consumer Genomics Market Shifts & Advancements
Low-pass whole genome sequencing is displacing SNP arrays as the dominant technical substrate, compressing the cost gap between ancestry-grade genotyping and clinical-grade interpretation while forcing business model recalibration across the value chain.
Low-pass whole genome sequencing at 4-30x coverage depth is unifying ancestry inference and health-risk prediction within single sample workflows. Consumer laboratories in California and Massachusetts are adopting this hybrid architecture to reduce duplicate collection logistics. The technology is unifying previously separate ancestry and health product lines into integrated subscription tiers.
The EU AI Act's high-risk system classification for medical device software is reshaping genetic risk algorithm deployment. Firms serving European consumers must implement conformity assessment procedures for automated variant interpretation. Pharmacogenomic report modules face the steepest compliance burden, driving some US-focused operators to abandon continental market entry.
Employer-sponsored genetic wellness programs are displacing direct retail channels as the fastest-scaling customer acquisition pathway. Human resources departments at self-insured Fortune 500 firms negotiate population-level contracts for preventive health screening. This procurement concentration is most visible in Texas and North Carolina, where large employers pilot medication safety programs for covered workforces.
Global Consumer Genomics Market Segmentation
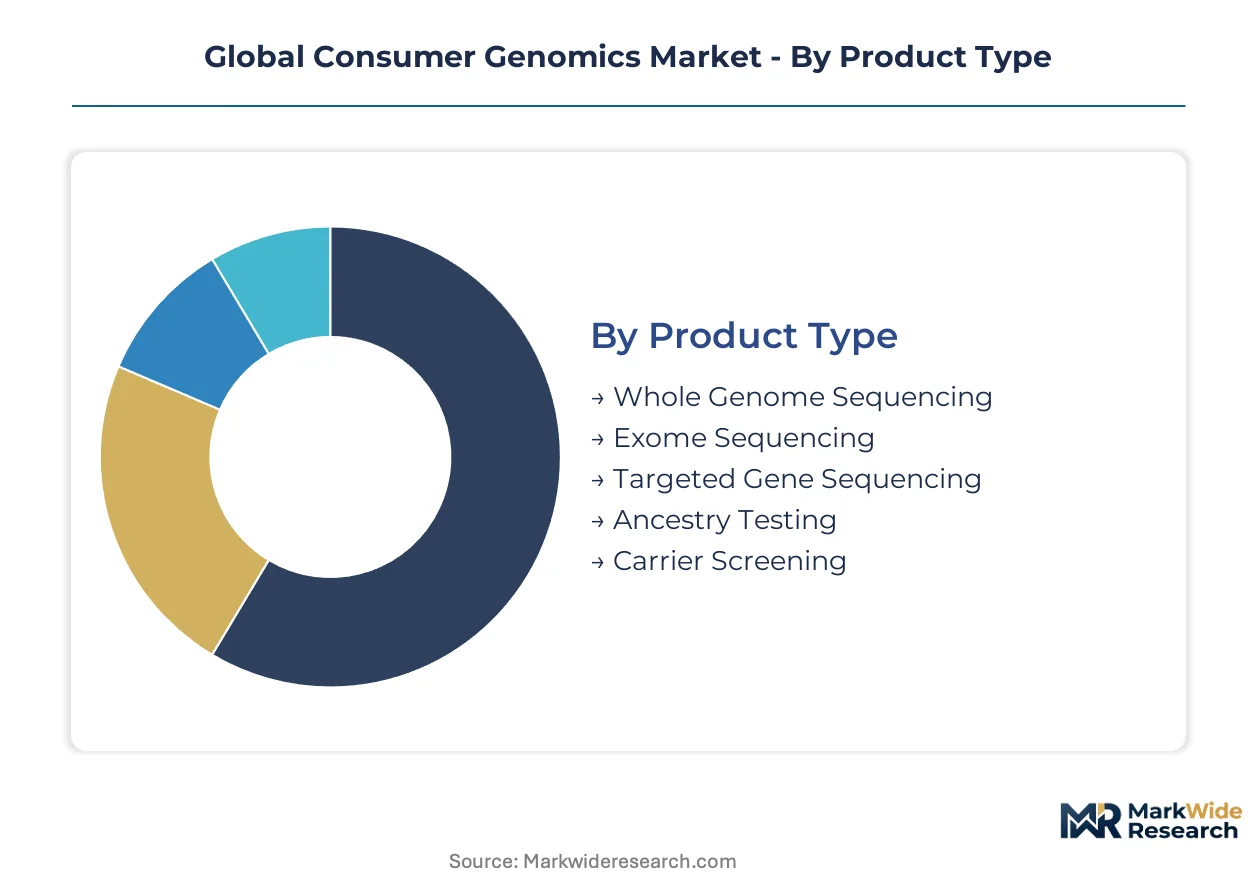
Consumer genomics segmentation reflects divergent buyer priorities across price sensitivity, clinical utility, and data depth. Product architecture choices lock laboratories into specific instrument platforms and bioinformatics pipelines. Application focus determines regulatory pathway complexity and reimbursement eligibility.
Product Type:
Price-performance tradeoffs dominate consumer selection, with coverage depth and variant interpretation scope defining tier boundaries.
- Ancestry Testing:SNP array platforms interrogate hundreds of thousands of markers for ethnic origin inference and relative matching. Demand concentrates in the United States among genealogy hobbyists and immigrant communities seeking geographic roots. Illumina beadchip manufacturing scale has collapsed per-sample costs below twenty dollars, enabling sub-hundred-dollar retail pricing and subscription renewal economics.
- Whole Genome Sequencing:Low-pass workflows at 4-30x coverage depth capture complete nuclear and mitochondrial DNA for imputation-based variant calling. Interpretation costs and variants-of-uncertain-significance counseling burdens constrain volume, though California and Massachusetts laboratories are unifying ancestry and health reporting within single workflows.
- Exome Sequencing:Protein-coding region focus balances diagnostic yield with data manageability for health-risk consumers.
- Targeted Gene Sequencing:Panel-based interrogation of pharmacogenomic or disease-associated loci supports medication safety and carrier screening applications.
- Carrier Screening:Preconception testing for autosomal recessive conditions targets family-planning demographics through clinician-mediated and direct-to-consumer channels.
Ancestry Testing leads on scale; Whole Genome Sequencing leads on momentum.
Application:
Clinical validation status and payer coverage patterns fragment addressable demand across wellness and medical use cases.
- Pharmacogenomics:Drug-gene interaction testing guides warfarin dosing, clopidogrel selection, and psychiatric medication matching. UnitedHealth and Anthem coverage decisions in the United States are converting out-of-pocket demand into insured utilization, accelerating consumer willingness to test. FDA 510(k) and de novo pathways for direct-to-consumer pharmacogenetic reports compress product development timelines while fragmenting competitive positioning between cleared and ancestry-only firms.
- Personalized Wellness:Lifestyle recommendations derived from genetic predispositions for exercise response, sleep architecture, and stress resilience. Corporate wellness programs at self-insured Fortune 500 firms in Texas and North Carolina are displacing direct retail channels as the fastest-scaling customer acquisition pathway.
- Nutrigenomics:Dietary guidance based on metabolic gene variants targets weight management and sports performance segments.
- Trait Prediction:Polygenic risk scores for coronary artery disease and type 2 diabetes enable preventive health stratification through machine-learned algorithms.
- Genetic Counseling:Interpretation services for variants of uncertain significance impose mandatory referrals under American College of Medical Genetics guidelines, with per-case review costs exceeding raw sequencing expenses.
Personalized Wellness leads on scale; Pharmacogenomics leads on momentum.
End User:
Channel control and data ownership terms vary sharply between consumer-directed and institution-mediated purchasing.
- Direct-to-Consumer Services:Saliva-based collection kits sold through online platforms and retail pharmacies eliminate clinician intermediation. Germany's DVG reimbursement pathway for predictive genetic testing is opening Europe's largest private-pay market to health-risk offerings. GDPR Article 9 special-category data protections mandate explicit consent and portability rights, adding fifteen to twenty percent operational overhead versus US-only operations.
- Healthcare Providers:Hospital and clinic-based ordering integrates pharmacogenomic testing into medication management protocols. Payer adoption accelerates consumer willingness to test through covered benefit structures.
- Research Institutions:Academic biobanks and population cohort studies leverage consumer-grade data for genomic epidemiology and polygenic model development.
- Fitness Enthusiasts:Athletic performance optimization through muscle fiber type and injury predisposition analysis targets subscription-based wellness platforms.
Direct-to-Consumer Services leads on scale; Healthcare Providers leads on momentum.
Distribution Channel:
Customer acquisition economics and regulatory exposure differ across digital-native and physical retail pathways.
- Online Platforms:E-commerce direct sales and subscription portals capture the majority of ancestry and wellness testing volume. Brazil's ANVISA regulatory modernization would permit direct-to-consumer health-risk marketing, offering first-mover database scale advantages in Latin America's largest economy.
- Pharmacies:Retail pharmacy placement for pharmacogenomic testing supports medication safety programs and clinician referral networks.
- Specialty Stores:Premium positioning through curated wellness retailers targets gift-giving and health-conscious demographics.
- Clinics:Physician office integration ensures genetic counseling compliance for complex health-risk reporting and reproductive carrier screening.
Online Platforms leads on scale; Pharmacies leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors global consumer genomics innovation, housing headquarters for ancestry platforms, sequencing instrument manufacturers, and venture-backed bioinformatics startups. Laboratory clusters in California and Massachusetts process the majority of North American saliva samples. Regulatory divergence between FDA-cleared health-risk frameworks and Europe's GDPR genetic data protections fragments operational models across jurisdictions.
United States
Employer-sponsored wellness programs at self-insured Fortune 500 firms in Texas and North Carolina drive fastest-scaling customer acquisition. FDA 510(k) and de novo pathways for direct-to-consumer pharmacogenetic reports compress product development timelines. UnitedHealth and Anthem coverage decisions convert out-of-pocket demand into insured utilization, accelerating consumer willingness to test.
Germany
The Digitale-Versorgung-Gesetz reimbursement pathway opens Europe's largest private-pay market to predictive genetic testing. GDPR Article 9 special-category data protections mandate explicit consent and portability rights, adding operational overhead versus US-only operations. Berlin and Munich host emerging bioinformatics laboratories serving DVG-eligible health-risk offerings.
United Kingdom
Genealogy hobbyists and immigrant communities seeking geographic roots sustain ancestry testing volume through online subscription portals. The Medicines and Healthcare products Regulatory Agency oversees in vitro diagnostic frameworks affecting direct-to-consumer health claims. Cambridge clusters concentrate variant curation talent, though compensation inflation squeezes mid-tier laboratory margins.
China
Rising middle-class demand for personalized wellness and preventive health stratification expands addressable consumer base. NMPA regulatory frameworks for genetic testing devices shape product authorization pathways for domestic and foreign operators. Shenzhen and Shanghai laboratories develop low-pass whole genome sequencing workflows for integrated ancestry-health reporting.
Brazil
ANVISA regulatory modernization proposals would permit direct-to-consumer health-risk marketing in Latin America's largest economy. First-mover positioning offers database scale advantages for polygenic risk score development. São Paulo clusters concentrate emerging laboratory capacity for SNP array and sequencing-based consumer testing.
Global Consumer Genomics Market Competitive Landscape
Global majors compete with regional champions across instrument supply, database scale, and regulatory clearance dimensions. The vendor base concentrates around three tiers: upstream sequencing platform manufacturers, integrated direct-to-consumer service providers, and specialized bioinformatics interpretation firms. Strategic archetypes include database-driven subscription platforms, FDA-cleared health-risk report specialists, and laboratory capacity aggregators. Competitive moves center on multi-source sequencing partnerships and pharmacogenomic reimbursement expansion.
Within the integrated service provider tier, Ancestry and 23andMe, Inc. exemplify divergent strategic positioning—one leveraging proprietary DNA database scale for subscription genealogy services, the other anchoring competitive position through FDA-cleared pharmacogenetic reports. Illumina, Inc. occupies the upstream instrument supply position, with NovaSeq and iSeq system deployments controlling cost structures for downstream consumer tests. These three entities represent the dominant competitive archetypes shaping market structure across the analysis window.
| Leading Market Players |
|---|
| Ancestry |
| 23andMe, Inc. |
| Illumina, Inc. |
| Myriad Genetics, Inc. |
| Color Genomics, Inc. |
| Gene By Gene, Ltd. (FamilyTree DNA) |
| Helix OpCo LLC |
| MyHeritage Ltd. |
| Veritas Genetics |
| Others |
Supply & Pricing Matrix
ISO 15189 medical laboratory accreditation gates qualified supply for premium-tier pharmacogenomic testing, separating FDA-cleared health-risk report providers from ancestry-only competitors and compressing margins for laboratories lacking certification investment.
Pricing Analysis
Input-cost pass-through from Illumina beadchip manufacturing scale has collapsed per-sample genotyping below twenty dollars, enabling sub-hundred-dollar retail ancestry pricing. Three-tier pricing structure across premium health-risk subscriptions, standard ancestry services, and economy-grade relative-matching tiers differentiates by FDA clearance status and interpretation depth. Pricing pressure stems from SNP array commoditization forcing laboratories toward low-pass whole genome sequencing workflows. Direct-to-consumer buyers exhibit highest price sensitivity, while employer-sponsored wellness programs at self-insured Fortune 500 firms demonstrate lowest sensitivity due to covered benefit structures.
Supply Chain Analysis
Dual-sourcing requirements for sequencing capacity mandate multi-supplier qualification among California and Massachusetts consumer laboratories seeking operational resilience. Supply concentrates in the United States for NovaSeq and iSeq instrument deployment, in China for Shenzhen-based low-pass workflow development, and in Germany for Berlin bioinformatics laboratory expansion. Raw material dependencies span Illumina beadchip consumables, saliva collection kit polymers, and cloud compute infrastructure for variant interpretation. Single-source vulnerability around Illumina instrument lock-in constrains laboratory switching costs. Distribution runs through online subscription portals for direct-to-consumer ancestry services and human resources procurement channels for employer wellness programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in consumer genomics rests on pharmacogenomic reimbursement converting out-of-pocket demand into insured utilization, compressing customer acquisition costs for FDA-cleared providers.
For Market Incumbents: Hedge against Illumina instrument lock-in by qualifying alternative sequencing platforms for low-pass whole genome sequencing workflows. Secure multi-source bioinformatics partnerships to reduce variant interpretation bottleneck exposure. Diversify beyond ancestry subscription renewals into employer-sponsored wellness procurement channels in Texas and North Carolina. For New Entrants and Emerging Players: Capture Brazil's ANVISA regulatory modernization window for direct-to-consumer health-risk marketing in Latin America's largest economy. Target Germany's DVG reimbursement pathway for predictive genetic testing as Europe's most penetrable private-pay market. Deploy polygenic risk score integration through corporate wellness platform partnerships rather than direct retail competition. For Investors and Strategic Acquirers: Roll-up economics work for bioinformatics interpretation specialists because variant curation talent scarcity in Cambridge and San Francisco clusters prevents rapid organic capability buildout. Focus acquisition screening on laboratories with ISO 15189 accreditation and FDA 510(k) predicate experience. Watch UnitedHealth and Anthem pharmacogenomic coverage expansion decisions as the signal indicating inflection toward insured utilization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates pharmacogenetic report commercialization ahead of ancestry-only competitors. |
| Multi-source Sequencing Partnership | Reduces Illumina instrument lock-in exposure for high-volume consumer processing. |
| Employer Wellness Contracting | Captures Fortune 500 procurement concentration displacing direct retail channels. |
| Polygenic Risk Score Integration | Enables coronary artery disease stratification through machine-learned algorithms. |
| GDPR Compliance Infrastructure | Mandates explicit consent systems for European operational market entry. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with laboratory operations directors, FDA regulatory affairs specialists, payer formulary managers, and bioinformatics pipeline architects informed operational constraints and reimbursement trajectories. Secondary sources include FDA 510(k) filings, EMA in vitro diagnostic guidance, CMS Medicare coverage determinations, and Illumina instrument deployment disclosures. Bottom-up triangulation across laboratory capacity expansion announcements and top-down reconciliation against sequencing consumables revenue data anchored market sizing.
Granularity-level modeling addressed product type tiering across SNP array, low-pass whole genome sequencing, and exome platforms; application segmentation spanning pharmacogenomics, personalized wellness, and trait prediction; and end-user channel differentiation between direct-to-consumer and employer-sponsored procurement. CAGRs were derived from laboratory throughput expansion rates and subscription renewal economics across the projection horizon. Forecast inputs incorporated Illumina beadchip cost curves, DVG reimbursement eligibility expansion, and ANVISA regulatory modernization timelines.
Underlying measurement precision varies by segment; pharmacogenomics carries tighter precision than ancestry testing due to FDA clearance documentation requirements. Forecasts reflect assumptions around payer coverage expansion velocity and regulatory pathway stability. Deviation in FDA 510(k) predicate drift standards or GDPR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Health IT Security Market
Health Informatics
AI in Epidemiology Market
Health Informatics
United States EHR Cloud Computing Market
Health Informatics
Clinical Intelligence Market
Health Informatics
Global Laboratory Information Management System (LIMS) Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
Global E-Health Market
Health Informatics
Allergy Care Market
Health Informatics
Global Healthcare Informatics Market
Health Informatics
Global Ambulatory EHR Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
USA Electronic Health Records (EHR) Market