
 Global Power Management Integrated Circuit (PMIC) Market | 2026-2036
Global Power Management Integrated Circuit (PMIC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Management Integrated Circuit (PMIC) Market Intelligence
Southeast Asia is tilting toward semiconductor packaging and test capacity expansion as multinational firms diversify manufacturing footprints. Texas Instruments leverages its 300mm analog wafer fabs in the United States to sustain cost leadership in high-volume linear regulators. Infineon Technologies anchors its position through in-house production of silicon and silicon carbide substrates for automotive PMICs. ON Semiconductor competes aggressively in battery management ICs for electrified powertrains across North American and European vehicle programs.
Power Management Integrated Circuits are mixed-signal semiconductor devices that regulate voltage, current, and power distribution across electronic systems, typically operating at efficiencies exceeding 90% in switched-mode configurations and integrating multiple rails into single-die or multi-chip packages. Their primary commercial purpose is to maximize energy conversion efficiency while minimizing thermal dissipation and board area in space-constrained electronics. Battery Management ICs command the deepest margin pools within the product type taxonomy due to automotive safety-critical certification requirements and long qualification cycles. Mixed-signal technology leads volume shipments because most applications demand both precise analog sensing and digital control loops on unified die architectures. Data centers represent the fastest-growing application segment as hyperscale operators deploy advanced voltage regulators to support AI accelerator power envelopes.
The U.S. Environmental Protection Agency and the European Union's Ecodesign Directive both enforce minimum efficiency standards for external power supplies, directly shaping PMIC specification requirements across consumer and industrial equipment categories. China's Ministry of Industry and Information Technology promotes domestic GB standards for power semiconductor reliability that influence supplier qualification protocols for local electronics manufacturers. Japan's METI funds next-generation wide-bandgap power electronics development through joint industry-academia programs targeting automotive and renewable energy applications. Stakeholders must monitor how divergent regional efficiency mandates and subsidy structures for domestic semiconductor manufacturing reshape competitive access across major demand centers.
Market Dynamics
Powertrain electrification across automotive OEMs is compressing PMIC qualification cycles while simultaneously demanding automotive-grade reliability certifications that only a handful of foundries can deliver.
Growth Catalysts
- EU Green Deal carbon border adjustments:Industrial equipment manufacturers in Germany and France face mandatory efficiency upgrades, forcing replacement of legacy linear regulators with switched-mode PMIC architectures.
- AI accelerator power envelopes:Hyperscale data center operators in the United States deploy multi-rail voltage regulators to support GPU clusters drawing kilowatt-scale instantaneous loads.
- Domestic foundry capacity expansion:China's MIIT-backed semiconductor fabrication investments create concentrated procurement pull for automotive PMICs serving BYD and CATL supply chains.
Market Restraints
- 300mm analog wafer supply concentration:Advanced BCD-on-silicon processes depend on facilities concentrated in Texas, Taiwan, and Dresden, creating geographic vulnerability to weather or geopolitical disruption.
- Silicon carbide substrate cost volatility:Wide-bandgap material for high-efficiency automotive PMICs remains 3-5x pricier than silicon equivalents, constraining adoption in cost-sensitive consumer segments.
- Automotive functional safety certification friction:ISO 26262 ASIL-D qualification timelines extend 18-24 months, freezing out fabless entrants without established automotive track records.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Contract manufacturers expanding in Tamil Nadu and Karnataka create demand for industrial-grade PMICs in power supplies and motor drives.
- GaN-SiC convergence in server power:Gallium nitride high-frequency switching paired with silicon carbide rectification enables 98%+ efficiency in 48V direct-to-chip architectures.
- Japan METI-funded wide-bandgap programs:Joint industry-academia consortia targeting renewable energy inverters offer technology transfer pathways for PMIC designers.
Industry Challenges
- Mixed-signal design talent scarcity:PMIC development requires simultaneous expertise in precision analog sensing and digital control loop implementation, a skill combination concentrated among veterans at established IDMs.
- Legacy automotive platform integration complexity:Tier-1 suppliers must maintain backward compatibility with 12V electrical architectures while designing for 800V EV powertrains, doubling validation burden.
- IP licensing entanglement in wireless charging:Qi and proprietary fast-charging protocols require patent pools that consume 8-12% of PMIC bill-of-materials for consumer applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Management Integrated Circuit (PMIC) Market |
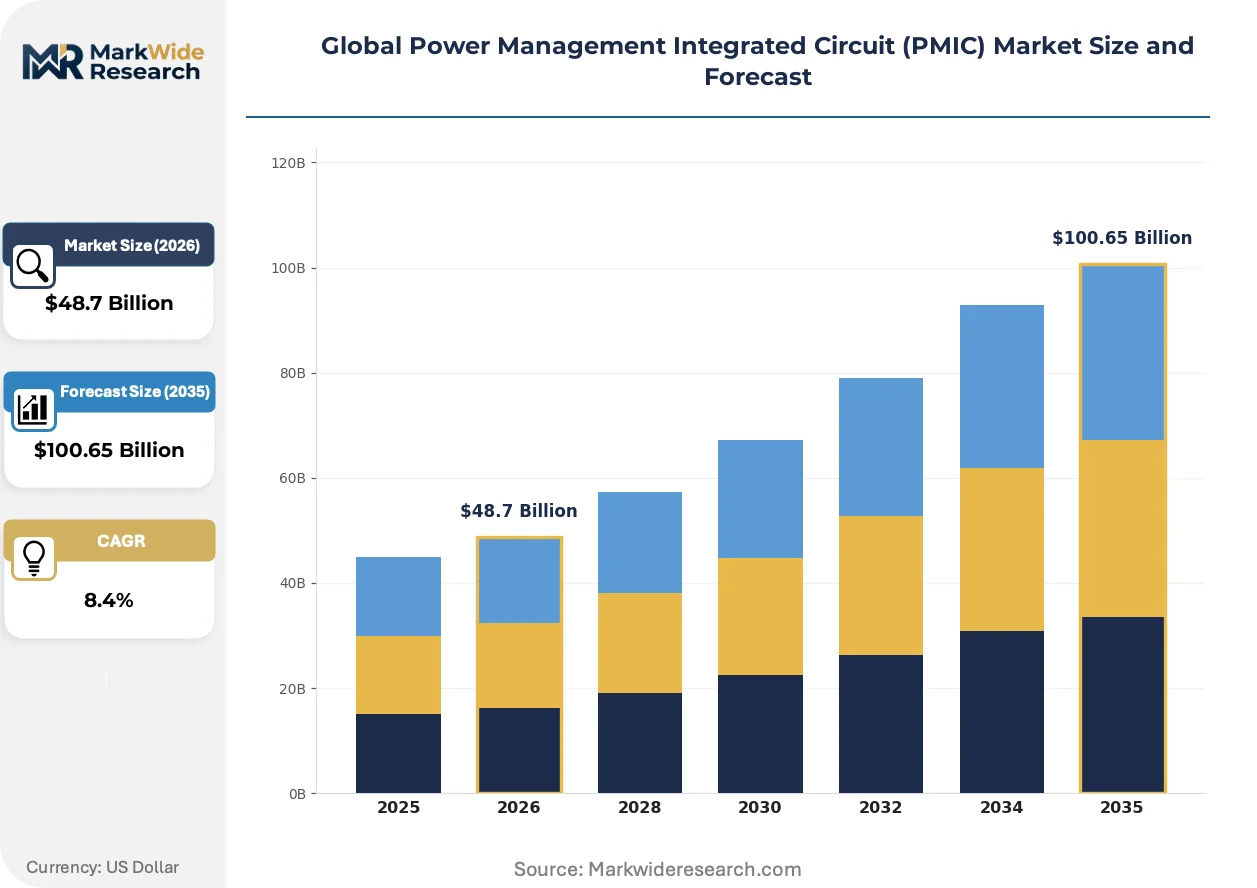
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buck Converters, Boost Converters, Linear Regulators, Battery Management ICs, Voltage References Technology: Analog, Mixed-Signal, Digital, Low Power, High Efficiency Application: Smartphones, Wearable Electronics, Data Centers, Industrial Automation, Consumer Electronics End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Telecommunications Providers, Aerospace Manufacturers |
| Companies Covered | NXP Semiconductors, ON Semiconductor, Texas Instruments, Microchip Technology, ROHM, Analog Devices, STMicroelectronics, Renesas Electronics, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Management Integrated Circuit (PMIC) Market Strategic Shifts & Innovations
Silicon and wide-bandgap semiconductor architectures are converging in PMIC designs that prioritize thermal performance and power density over pure cost minimization.
Multi-phase voltage regulators with digital power management controllers are hybridizing analog sensing precision with firmware-configurable protection thresholds. Data center operators deploying NVIDIA and AMD accelerator clusters adopt these architectures to manage transient load steps exceeding 1000A per microsecond. The technology is compressing time-to-market for custom silicon while fragmenting the traditional analog PMIC vendor base.
REACH restrictions on hazardous substances and the EU's Ecodesign Directive for external power supplies now mandate minimum active-mode efficiency and no-load power consumption limits. Industrial equipment OEMs serving European markets redesign adapter and embedded power architectures to eliminate linear post-regulation stages. Battery charger ICs for consumer electronics face the steepest redesign cycles as manufacturers race to meet 2025 tiered efficiency deadlines.
Hyperscale buyers now specify PMIC architectures in original RFPs rather than delegating power subsystem design to contract manufacturers. This disintermediation concentrates purchasing leverage among Amazon Web Services, Microsoft Azure, and Google Cloud Platform procurement teams. Taiwan-based ODMs respond by pre-integrating voltage regulator modules with thermal and mechanical subsystems to preserve margin position.
Global Power Management Integrated Circuit (PMIC) Market Segmentation
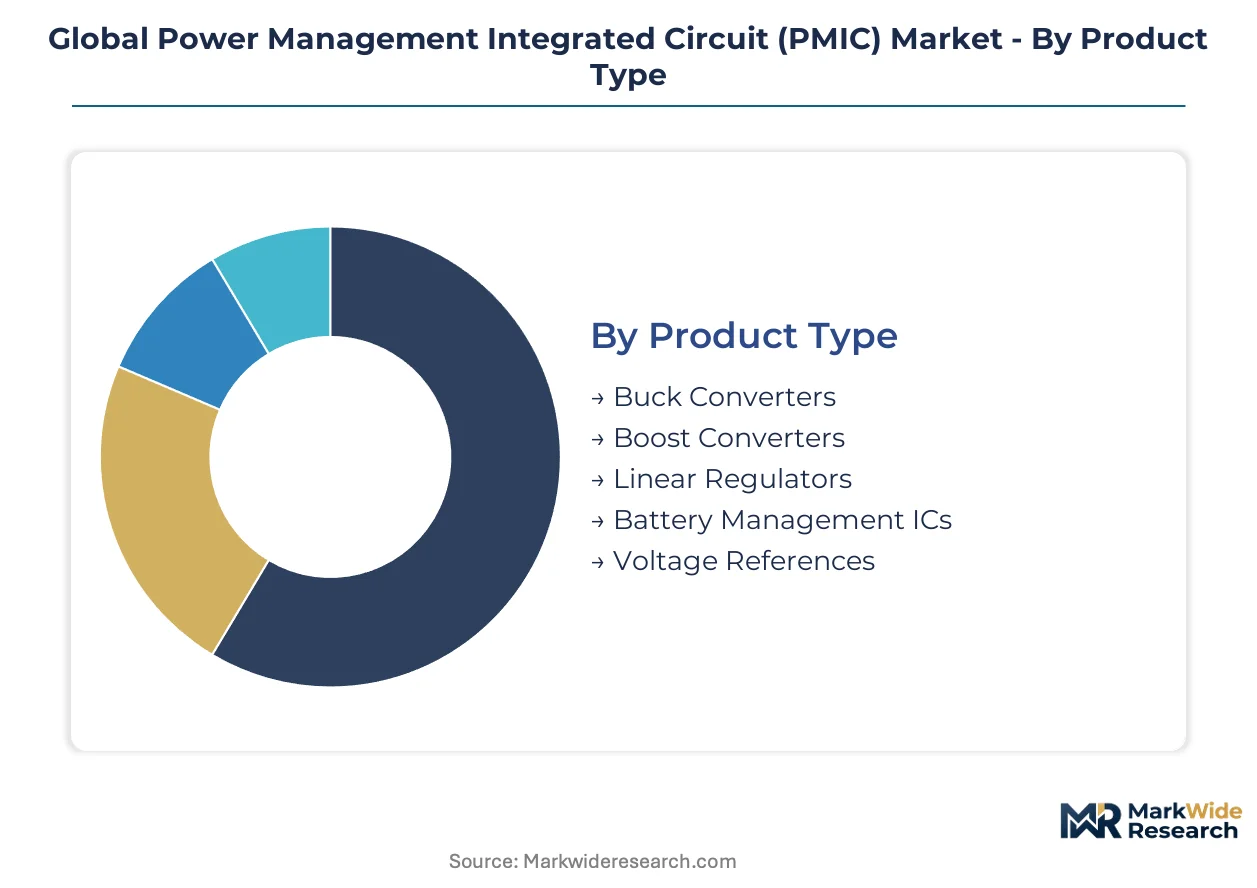
PMIC segmentation reflects divergent technical requirements across voltage regulation tasks, from milliwatt-scale wearable devices to kilowatt-scale data center loads. Each dimension—product architecture, semiconductor technology, application environment, and buyer type—carries distinct margin profiles and qualification barriers that reshape supplier competitive position.
Product Type:
After-sales service intensity varies sharply across PMIC product categories, with automotive-qualified segments demanding decade-long field support commitments while consumer-grade components require minimal technical assistance.
- Battery Management ICs:These integrated circuits monitor cell voltage, temperature, and state-of-charge while balancing series-connected battery stacks through passive or active cell balancing. Demand concentrates in automotive OEMs serving BYD and CATL supply chains in China, where 800V EV architectures require ASIL-D certified battery monitors with sub-millivolt precision.
- Buck Converters:Step-down switching regulators convert higher input voltages to lower output rails with efficiencies exceeding 90% in synchronous rectification configurations. Data center operators in the United States specify multi-phase buck controllers for NVIDIA GPU power delivery, where transient response below 10 microseconds prevents computational errors under load spikes.
- Boost Converters:Step-up architectures raise battery voltages to drive LED backlighting and RF power amplifiers in portable electronics.
- Linear Regulators:Low-dropout devices provide noise-sensitive analog rails where switching ripple would corrupt precision sensor signals.
- Voltage References:Precision bandgap circuits establish absolute voltage standards for ADCs and measurement instrumentation.
Battery Management ICs hold the largest share; momentum sits with Buck Converters.
Technology:
Cost tier stratification in PMIC technology follows wafer process complexity, with advanced BCD-on-silicon commanding 40-60% premiums over standard CMOS implementations.
- Mixed-Signal:Unified die architectures combine precision analog sensing with digital control loops, enabling firmware-configurable protection thresholds and telemetry reporting. Industrial automation OEMs in Germany source mixed-signal PMICs for motor drive controllers, where encoder feedback interfaces demand simultaneous analog signal conditioning and digital protocol handling.
- High Efficiency:Synchronous rectification, adaptive dead-time control, and light-load optimization push conversion efficiency above 95% across wide operating ranges. Data centers in Virginia and Oregon deploy these architectures for 48V direct-to-chip power delivery, where every 0.5% efficiency gain translates to megawatt-scale cooling cost reductions.
- Analog:Pure analog control loops dominate cost-sensitive consumer applications where digital programmability adds unnecessary die area.
- Digital:Fully digital controllers enable complex multi-rail sequencing and PMBus telemetry for enterprise server platforms.
- Low Power:Sub-microamp quiescent current designs extend battery life in medical patches and environmental sensors.
Mixed-Signal dominates volume shipments; High Efficiency is climbing the fastest.
Application:
Application-driven volume concentration in PMIC procurement has shifted toward infrastructure-scale buyers who specify power architectures in original RFPs rather than delegating subsystem design.
- Data Centers:Hyperscale facilities deploy advanced voltage regulators supporting AI accelerator power envelopes drawing kilowatt-scale instantaneous loads. Microsoft Azure and Amazon Web Services procurement teams in the United States now disintermediate traditional ODMs by specifying multi-rail PMIC architectures directly with semiconductor vendors.
- Industrial Automation:Programmable logic controllers, servo drives, and robotic systems demand isolated power supplies with reinforced insulation ratings. German machinery OEMs face EU Green Deal carbon border adjustments forcing replacement of legacy linear regulators with switched-mode PMIC architectures.
- Smartphones:Highly integrated PMICs manage application processor, modem, and display power rails in space-constrained mobile devices.
- Wearable Electronics:Miniaturized power management extends battery life in health-monitoring devices with strict thermal constraints.
- Consumer Electronics:External power adapters and set-top boxes drive high-volume demand for cost-optimized solutions.
Smartphones retain the largest installed base; Data Centers show the steepest expansion trajectory.
End User:
Customer type determines procurement leverage and technical engagement depth, with vehicle assemblers imposing the most stringent qualification protocols.
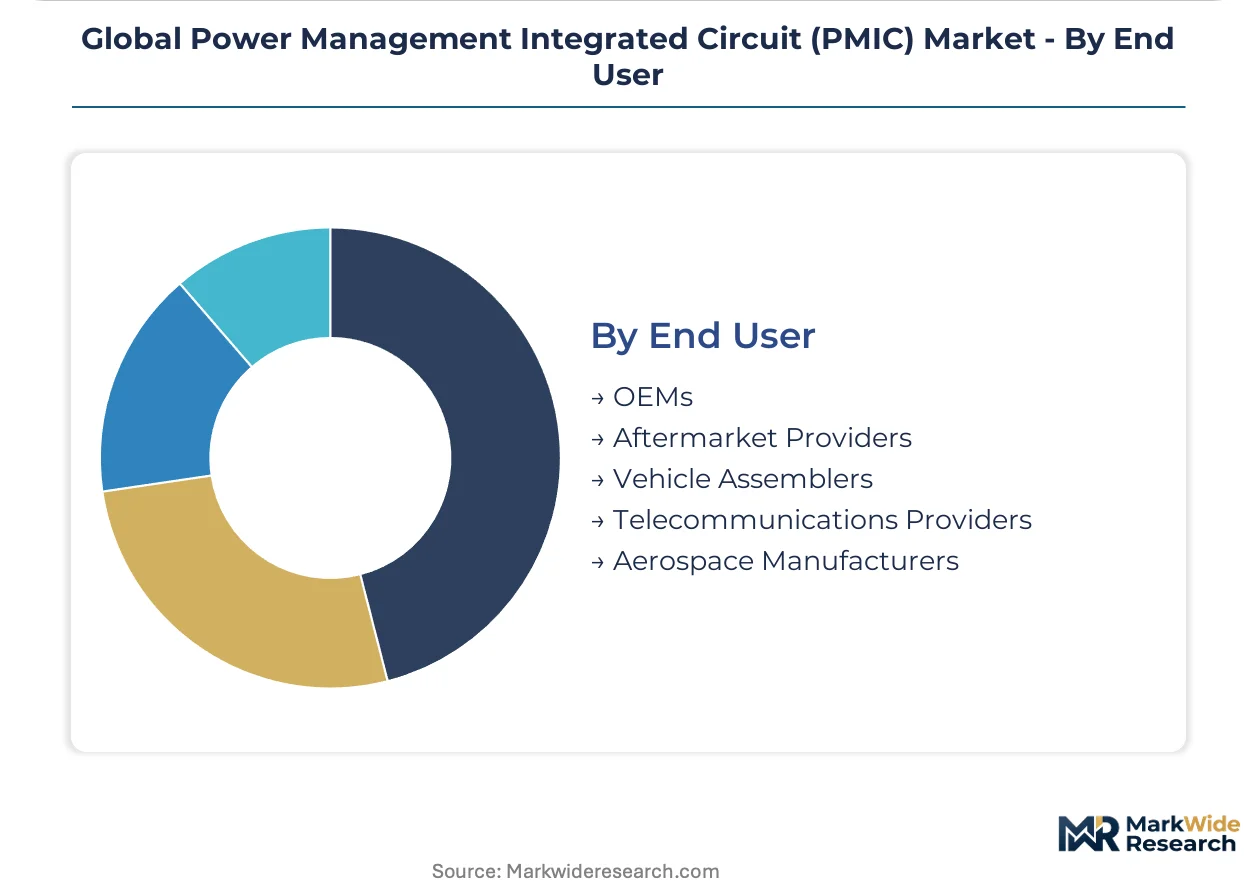
- Vehicle Assemblers:Automotive OEMs and Tier-1 suppliers source PMICs through multi-year platform contracts with ISO 26262 functional safety mandates. European vehicle programs at BMW and Volkswagen require 18-24 month qualification timelines that freeze out fabless entrants without established automotive track records.
- OEMs:Original equipment manufacturers across electronics categories specify PMICs in bill-of-materials with varying technical involvement. Smartphone OEMs in Shenzhen and Taipei exercise concentrated procurement power through direct foundry negotiations.
- Telecommunications Providers:Network infrastructure operators specify power systems for base stations and edge computing nodes.
- Aerospace Manufacturers:Defense and commercial aviation programs demand radiation-tolerant and extended-temperature-range devices.
- Aftermarket Providers:Repair and replacement channels serve legacy equipment with second-source and pin-compatible alternatives.
OEMs represent the broadest demand base; Vehicle Assemblers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through GB standards for power semiconductor reliability that reshape supplier qualification protocols across domestic electronics manufacturing clusters.
China
BYD and CATL procurement teams drive concentrated demand for automotive PMICs serving 800V EV architectures. The Ministry of Industry and Information Technology promotes domestic GB standards that influence supplier qualification for Shenzhen and Shanghai electronics manufacturers. Yangtze River Delta foundry investments create procurement pull concentrated in Jiangsu and Zhejiang provinces.
United States
Hyperscale data center operators deploy multi-rail voltage regulators for AI accelerator clusters drawing kilowatt-scale loads. The Environmental Protection Agency enforces minimum efficiency standards for external power supplies that directly shape PMIC specifications. Texas Instruments leverages 300mm analog wafer fabs concentrated in Richardson and Sherman to sustain cost leadership in high-volume linear regulators.
Germany
Industrial equipment manufacturers face EU Green Deal carbon border adjustments forcing replacement of legacy linear regulators with switched-mode PMIC architectures. The Ecodesign Directive mandates minimum active-mode efficiency limits that redesign adapter and embedded power architectures. Bavarian machinery OEMs in Munich and Nuremberg source mixed-signal PMICs for motor drive controllers requiring encoder feedback interfaces.
Japan
METI funds next-generation wide-bandgap power electronics development through joint industry-academia programs targeting automotive and renewable energy applications. Kanto region semiconductor houses concentrate PMIC design expertise for industrial automation and consumer electronics. Tokyo-based consortia target GaN-SiC convergence in server power applications.
India
The Production Linked Incentive scheme for electronics manufacturing attracts contract manufacturers expanding in Tamil Nadu and Karnataka. Central Electricity Authority standards shape power supply efficiency requirements for industrial equipment. Bengaluru and Chennai clusters create demand for industrial-grade PMICs in power supplies and motor drives serving domestic OEMs.
Global Power Management Integrated Circuit (PMIC) Market Key Industry Players
Capability concentration sits with integrated device manufacturers possessing automotive-grade foundry access; scale advantage sits with analog specialists leveraging 300mm wafer economics. The vendor base stratifies across three tiers: IDMs with captive silicon and silicon carbide substrate production, fabless designers dependent on external foundry capacity, and diversified semiconductor conglomerates with broad analog portfolios. Dominant competitive moves include backward integration into silicon carbide substrate supply and strategic partnerships with hyperscale data center procurement teams.
Among established IDMs, Texas Instruments, Infineon Technologies, and ON Semiconductor exemplify the capability-scale spectrum. Texas Instruments represents the scale-driven archetype through domestic 300mm analog wafer fabrication. Infineon Technologies anchors the vertical integration vector through in-house silicon and silicon carbide substrate production. ON Semiconductor occupies a position within the automotive specialization tier, with its corporate structure reflecting North American fabless-plus-foundry hybrid strategies.
| Leading Market Players |
|---|
| NXP Semiconductors |
| ON Semiconductor |
| Texas Instruments |
| Microchip Technology |
| ROHM |
| Analog Devices |
| STMicroelectronics |
| Renesas Electronics |
| Infineon Technologies |
| Others |
Cost & Logistics Intelligence
300mm analog wafer fabrication capacity concentrated in Texas, Taiwan, and Dresden anchors margin capture downstream, with automotive-grade BCD-on-silicon processes commanding substantial premiums over standard CMOS implementations for battery management and voltage regulation applications.
Pricing Analysis
Geographic price spreads between Richardson, Sherman, and Asian foundry hubs reflect 40-60% cost differentials for mixed-signal PMICs. Three-tier pricing structure across automotive ASIL-D, industrial-grade, and consumer economy levels segments buyers by certification burden and after-sales commitment depth. Cost compression in consumer linear regulators intensifies as Shenzhen smartphone OEMs negotiate direct foundry access. Vehicle assemblers exhibit lowest price sensitivity due to decade-long platform lock-in and functional safety mandates.
Supply Chain Analysis
US export controls on advanced lithography equipment and wide-bandgap substrate technology constrain capacity expansion outside allied manufacturing zones. Silicon carbide ingot supply draws from US, Japanese, and emerging European substrate vendors, while advanced BCD process IP rests on Taiwanese and American foundry networks. Single-source vulnerability concentrates in 300mm analog wafer starts. Distribution runs through Tier-1 automotive suppliers and hyperscale direct procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mixed-signal design expertise combining precision analog sensing with digital control loop implementation has become the constraining asset, with qualified engineering talent concentrated among veterans at established IDMs and only a handful of automotive-certified foundries capable of delivering ASIL-D reliability.
For Market Incumbents: Harden automotive foundry access through captive capacity reservations or joint venture structures with Yangtze River Delta fabrication investments. Deepen silicon carbide substrate supply through backward integration or long-term offtake agreements with emerging European vendors. Lock in hyperscale data center procurement relationships before second-source qualification cycles complete. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-backed electronics manufacturing clusters, where Tamil Nadu and Karnataka contract manufacturers create demand for industrial-grade PMICs without entrenched incumbent relationships. Target motor drive controllers and power supply modules for domestic OEMs, leveraging cost-optimized standard CMOS processes and minimal automotive certification overhead. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fabless designers possessing automotive track records but lacking captive foundry access. Five-to-ten year viability hinges on securing BCD-on-silicon capacity commitments. Watch for MIIT-backed Chinese foundry overcapacity as the inflection signal for margin compression in consumer-tier segments.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Foundry Capacity Reservation | ASIL-D certification timelines freeze out competitors without multi-year wafer commitments. |
| Silicon Carbide Substrate Backward Integration | In-house SiC ingot production anchors margin capture for 800V EV powertrain PMICs. |
| Hyperscale Direct Procurement Partnership | AWS and Azure specification authority disintermediates traditional ODM channel control. |
| GaN-SiC Convergence R&D Program | Tokyo-based METI consortia enable technology transfer for server power efficiency gains. |
| India PLI Electronics Manufacturing Entry | Tamil Nadu cluster demand for industrial PMICs bypasses automotive qualification friction. |
Research Approach
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings. Semiconductor device engineers, automotive Tier-1 procurement leads, hyperscale data center infrastructure planners, and foundry operations directors provided ground-truth on capacity constraints and qualification timelines. SEC 10-K disclosures, EPA efficiency standard dockets, MIIT GB standard publications, and EU Ecodesign Directive implementation reports supplied external validation. Bottom-up segment sizing triangulates against top-down wafer capacity and end-equipment production estimates.
Calibration against historical BCD process adoption curves and automotive platform life cycles shapes the projection framework. Segmentation by product architecture, semiconductor technology, application environment, and buyer type feeds into volume and value modeling across the analysis window. CAGRs derive from equipment production forecasts for EV powertrains, AI server deployments, and industrial automation capex. Silicon carbide substrate cost trajectories and 300mm analog wafer supply expansion schedules serve as key sensitivity inputs.
Sensitivities concentrate around foundry capacity allocation shifts, export control tightening on wide-bandgap materials, and EV platform standardization timelines. Forecasts reflect documented assumptions on qualification cycle durations and regional efficiency mandate enforcement. Material shifts in automotive OEM insourcing strategies or hyperscale vertical integration into custom silicon would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
Audio Power Amplifier IC Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Global Analog Integrated Circuit (IC) Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market