
 Set-Top Box Market | 2026-2036
Set-Top Box Market Size, Share, and Industry Trends Forecast 2026-2036
Set-Top Box Market Analysis
Project finance for bulk operator deployments is narrowing the competitive field to vendors with balance-sheet depth. CommScope Holding leverages its cable infrastructure heritage to sustain operator relationships across North American MSOs. Huawei Technologies anchors large-scale IPTV rollouts through integrated network-equipment bundling in Asia and the Middle East. Samsung Electronics competes on semiconductor vertical integration, controlling chip supply for premium Android-based units.
A set-top box is a dedicated computing appliance that demodulates broadcast signals, decrypts conditional-access content, and renders video output through HDMI interfaces at resolutions up to 4K HDR. Its primary commercial purpose is to bridge carrier networks with consumer display devices while enabling subscription management and interactive services. The satellite product segment retains entrenched positions in rural and emerging-market footprints where terrestrial broadband remains uneconomical. Android technology specialization is accelerating as operators abandon proprietary middleware to reduce software maintenance burdens. Residential end users dominate volume, though commercial hospitality deployments generate superior per-unit margins through customized user-interface requirements.
The FCC's AllVid proceeding and the EU's Radio Equipment Directive shape hardware interoperability mandates that increase certification costs for smaller OEMs. India's BIS compulsory registration scheme and China's MIIT network-access licenses create country-specific compliance layers that delay product launches. Energy-efficiency regulations from the California Energy Commission and analogous EU ecodesign rules are tightening standby-power limits and influencing chipset selection. Stakeholders must monitor whether streaming-app aggregation functions trigger fresh regulatory scrutiny under emerging digital-platform competition frameworks.
Market Dynamics
The transition from proprietary middleware to Android TV stacks is compressing software maintenance costs while fragmenting hardware differentiation, forcing operators to compete on service bundling rather than box specifications.
Growth Catalysts
- Fiber-to-the-Home Deployments:India's Reliance Jio and Bharti Airtel are expanding FTTH networks that require next-generation IP-based set-top units, creating hardware refresh cycles across millions of subscriber lines.
- Interoperability Mandates:The FCC's AllVid proposal and Europe's Radio Equipment Directive are compelling hardware redesigns that standardize interfaces and reduce operator lock-in to single vendors.
- Satellite Proliferation:Rural and emerging-market footprints where terrestrial broadband remains uneconomical continue deploying satellite set-top boxes for pay-TV access.
Market Restraints
- Silicon Supply Concentration:Advanced SoC fabrication for 4K HDR decoding concentrates among a limited pool of foundry operators, exposing procurement to geopolitical export controls.
- Certification Cost Escalation:India's BIS compulsory registration scheme and China's MIIT network-access licenses impose country-specific compliance layers that delay product launches and inflate fixed costs for smaller OEMs.
- Streaming Substitution:Smart TV native applications and HDMI streaming sticks are displacing dedicated set-top hardware in premium residential segments.
Strategic Opportunities
- Hospitality Vertical Expansion:Commercial deployments generate superior per-unit margins through customized user-interface requirements and centralized management platforms for hotel chains.
- Energy-Efficiency Incentives:California Energy Commission standby-power regulations and EU ecodesign rules create competitive openings for vendors with advanced power-management chipsets.
- Middleware Convergence:Android TV and RDK-B integration is collapsing proprietary software stacks, enabling smaller hardware vendors to compete on industrial design rather than platform development.
Industry Challenges
- Legacy Infrastructure Integration:Southeast Asian pay-TV operators upgrading cable infrastructure to IP-based delivery face complex migration timelines and backward-compatibility requirements.
- Conditional Access Fragmentation:Operator-specific DRM schemes and smart-card ecosystems create integration complexity that extends engineering cycles and limits economies of scale.
- Software Talent Scarcity:Android TV customization and security patch maintenance require specialized embedded Linux expertise that concentrates in specific technology clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Set-Top Box Market |
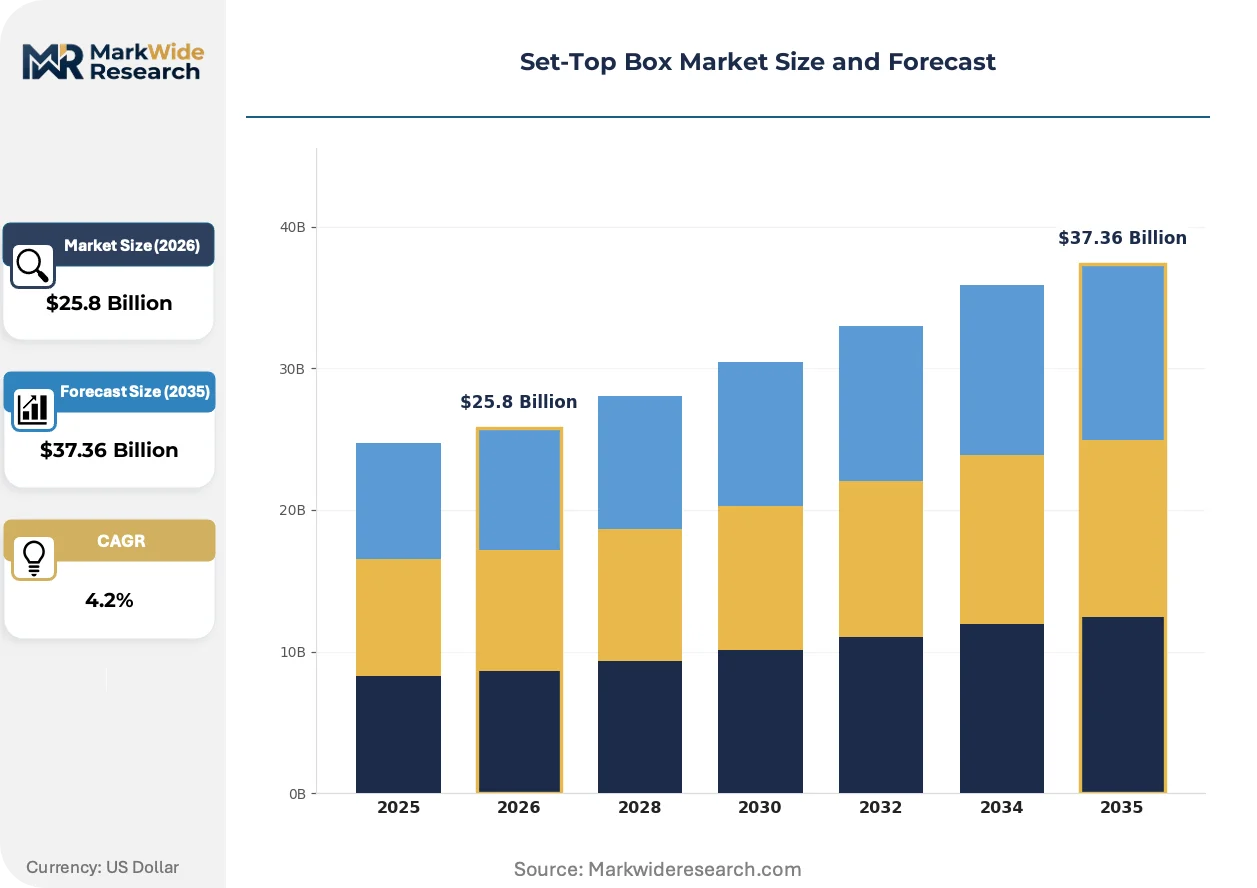
| Market Size in 2026 | $25.8 Billion |
| Market Size in 2035 | $37.36 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite, Cable, IPTV, OTT Technology: Android, Linux, Proprietary, Hybrid End User: Residential, Commercial, Educational, Government Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | CommScope Holding, Huawei Technologies, HUMAX Electronics, Samsung Electronics, Technicolor SA, Sagemcom SAS, Advanced Digital Broadcast, EchoStar Corporation, Roku, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Set-Top Box Market Emerging Trajectories
Android TV specialization is collapsing proprietary middleware ecosystems while regulatory energy-efficiency mandates reshape chipset selection criteria across manufacturing programs.
Android TV is collapsing the traditional middleware stack by providing standardized APIs for streaming aggregation and voice control. North American and European cable operators are adopting RDK-B and Android TV Reference Design kits at accelerating pace. This convergence is collapsing software differentiation as a competitive moat and shifting vendor rivalry toward industrial design and supply-chain execution.
The EU's Ecodesign for Energy-Related Products Directive and California Energy Commission standby-power regulations are tightening operational efficiency thresholds for set-top hardware. Manufacturers must redesign power supplies and select low-leakage SoCs to maintain market access. The residential segment faces the steepest compliance cost increases as volume production magnifies certification burden per model.
Operators are consolidating procurement around streaming-app aggregation platforms that bundle subscription management with content discovery. Hospitality and multi-dwelling unit channels are displacing traditional retail distribution for premium Android-based units. India and Southeast Asia exhibit the most visible procurement concentration as Reliance Jio and regional MSOs negotiate multi-million unit tenders with integrated service requirements.
Set-Top Box Market Segmentation
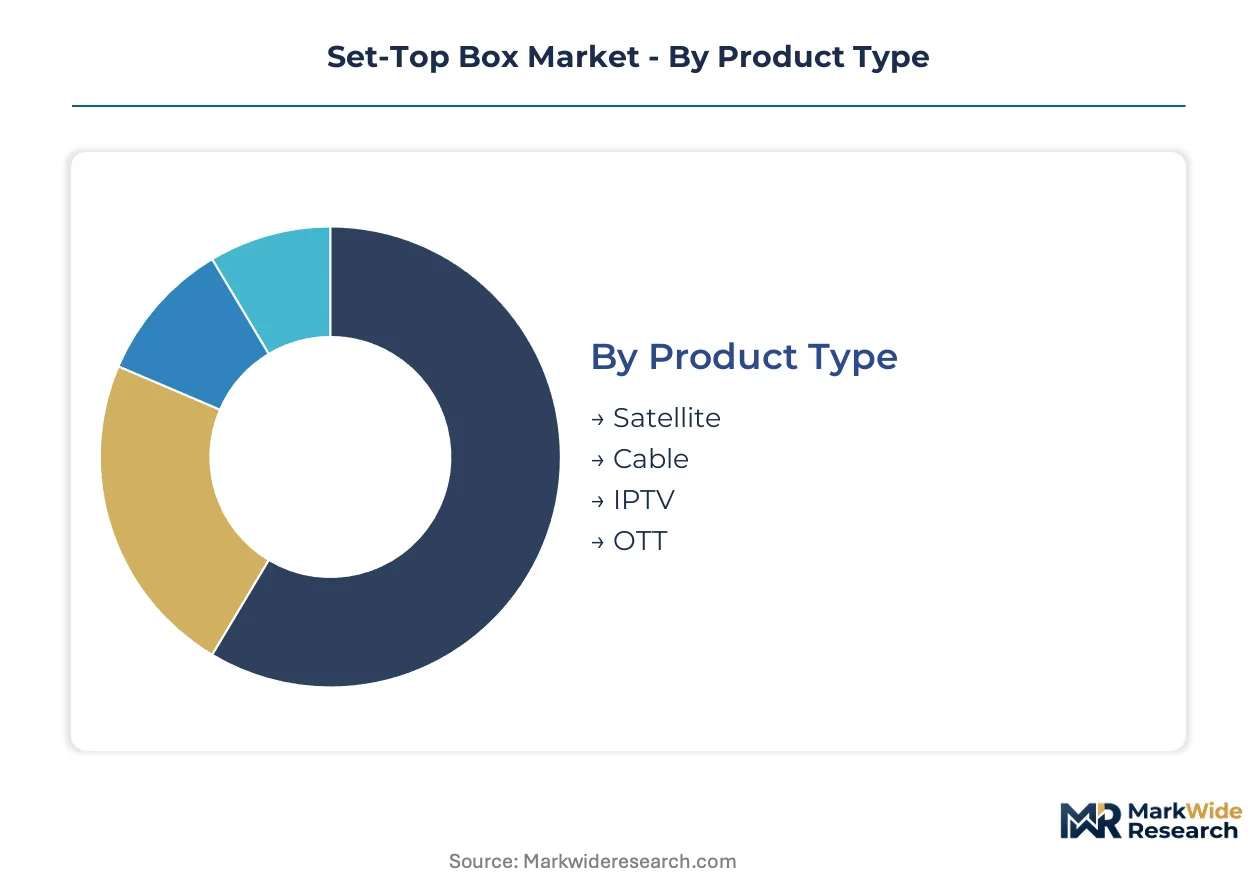
Set-top box segmentation reveals divergent replacement cycles across product architectures and deployment contexts. Hardware refresh timelines stretch from 3-year consumer IPTV cycles to decade-long satellite installations in remote geographies.
Product Type:
Replacement velocity separates satellite infrastructure lasting 8-12 years from IPTV hardware turning over every 36 months in competitive fiber markets.
- Satellite:Units demodulate Ku-band and Ka-band signals for broadcast delivery where terrestrial infrastructure remains uneconomical. Rural India, sub-Saharan Africa, and Latin American mountain regions sustain demand as Reliance Jio and regional operators extend pay-TV reach beyond fiber footprints. Conditional-access integration and outdoor unit weatherproofing extend field life.
- IPTV:IP-based units decode multicast and unicast streams over fiber-to-the-home networks. India's Reliance Jio and Bharti Airtel deployments are driving hardware refresh cycles across millions of subscriber lines as operators compete on 4K HDR service tiers. Android TV middleware adoption accelerates replacement as operators abandon legacy stacks.
- Cable:QAM demodulation equipment serves hybrid fiber-coax networks undergoing DOCSIS upgrades. North American MSOs face backward-compatibility constraints during IP migration.
- OTT:Streaming-optimized devices aggregate subscription applications without traditional broadcast tuners. Smart TV native integration and HDMI stick competition compress standalone unit margins.
Satellite dominates installed base. IPTV is where expansion concentrates.
Technology:
Software maintenance burden varies dramatically across middleware architectures, with proprietary stacks demanding 4x the engineering headcount of standardized platforms.
- Android:Google's reference design collapses proprietary middleware development, enabling operators to deploy voice control and streaming aggregation through standardized APIs. North American cable operators and European telcos are consolidating procurement around Android TV stacks to reduce patch maintenance costs.
- Proprietary:Legacy middleware from established pay-TV operators retains entrenched positions where conditional-access integration and custom user interfaces lock in hardware specifications. Southeast Asian cable operators face complex migration timelines upgrading these systems to IP delivery.
- Linux:Embedded distributions power RDK-B deployments and operator-customized stacks requiring granular security control. Engineering talent scarcity concentrates in specific technology clusters.
- Hybrid:Dual-stack architectures bridge broadcast and broadband delivery during infrastructure transition periods. India's BIS certification requirements add compliance layers to these complex designs.
Proprietary technology dominates installed base. Android is climbing the fastest.
End User:
Margin structure inverts between volume-driven residential deployments and customized commercial installations.
- Residential:Consumer households generate volume demand through operator-subsidized equipment models. India's FTTH expansion and Southeast Asian cable upgrades concentrate procurement activity in subscriber acquisition programs.
- Commercial:Hospitality chains and multi-dwelling units command superior per-unit margins through centralized management platforms and customized user-interface requirements. Hotel property management system integration extends contract values.
- Educational:Campus networks and institutional deployments require bulk licensing and content filtering capabilities. Procurement runs through specialized AV integrators rather than retail channels.
- Government:Public-sector installations emphasize security certification and domestic sourcing requirements. China's MIIT network-access licenses and India's BIS compulsory registration schemes shape vendor eligibility.
Residential dominates installed base. Commercial is gaining share fastest.
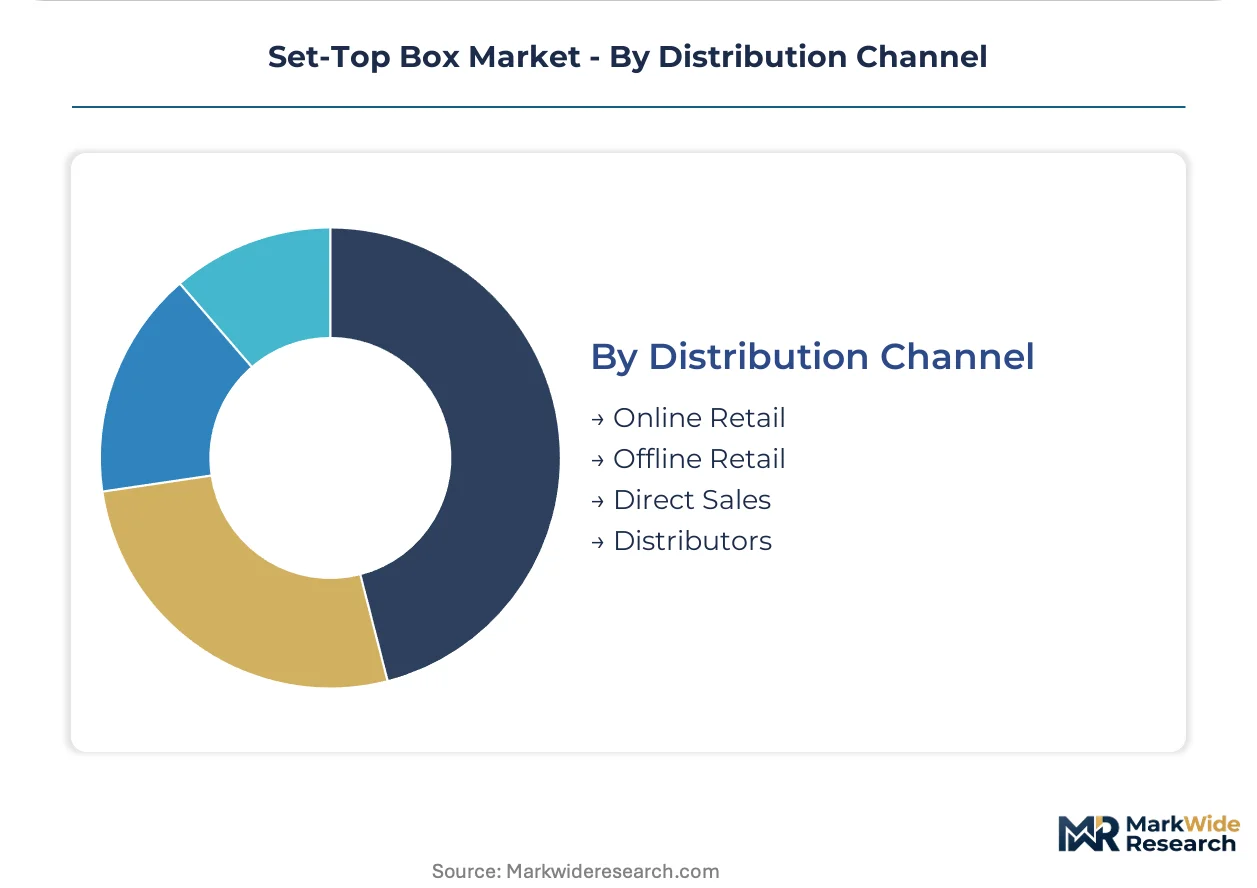
Distribution Channel:
Channel economics shift as operator procurement consolidation displaces retail distribution for premium units.
- Direct Sales:Operator tenders for multi-million unit deployments bypass intermediaries entirely. Reliance Jio and Bharti Airtel negotiate integrated service requirements directly with hardware vendors.
- Distributors:Regional logistics networks serve smaller MSOs and secondary market replacement demand. Inventory carrying costs concentrate working capital requirements.
- Online Retail:E-commerce platforms move OTT streaming devices and unlocked Android boxes to consumer self-install segments. Price transparency compresses margins.
- Offline Retail:Electronics storefronts support subscriber acquisition programs with immediate fulfillment. Foot traffic dependency limits scalability.
Direct sales dominates installed base. Distributors retain replacement demand concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India commands superior pricing leverage through multi-million unit operator tenders, while fragmented procurement across European cable operators erodes vendor margins. Fiber-to-the-home deployment velocity concentrates hardware demand in South Asian metros. Regulatory fragmentation across national certification schemes shapes regional entry costs.
United States
Major cable multiple-system operators drive DOCSIS upgrade cycles requiring backward-compatible set-top hardware. FCC AllVid interoperability mandates force interface standardization that reduces vendor lock-in. Silicon Valley engineering clusters concentrate Android TV middleware development talent for operator reference designs.
India
Reliance Jio and Bharti Airtel negotiate integrated FTTH service tenders requiring next-generation IP set-top units at scale. BIS compulsory registration schemes impose country-specific compliance layers extending product launch timelines. Mumbai and Delhi-NCR serve as procurement decision centers for operator hardware consolidation.
China
MIIT network-access licenses create regulatory barriers for foreign OEMs while domestic vendors anchor IPTV rollout equipment. Provincial cable operators in Guangdong and Jiangsu upgrade legacy infrastructure to IP-based delivery. Shenzhen manufacturing clusters supply SoC components for regional set-top production.
Germany
Deutsche Telekom and regional cable operators consolidate procurement around energy-efficient Android TV stacks. EU Ecodesign directives tighten standby-power thresholds influencing chipset selection criteria. Bavaria and North Rhine-Westphalia host engineering centers for conditional-access integration and middleware customization.
Brazil
Satellite pay-TV operators extend coverage into remote Amazon and Northeast regions where terrestrial broadband remains uneconomical. ANVISA and national telecom regulator frameworks shape import certification for consumer electronics hardware. São Paulo industrial corridors concentrate assembly operations for Latin American market supply.
Set-Top Box Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying tuners, power management ICs, and conditional-access modules. Market structure concentrates around operators with balance-sheet depth capable of financing bulk multi-year deployments. Three archetypes dominate: integrated network-equipment bundlers, semiconductor vertical integrators, and hospitality-focused customization specialists. Competitive rivalry centers on Android TV reference design partnerships and energy-efficiency certification pre-emption.
Among Asia-Pacific technology conglomerates, Huawei Technologies and Samsung Electronics exemplify divergent positioning strategies. Huawei anchors large-scale IPTV rollouts through integrated network-equipment bundling relationships with state-affiliated operators. Samsung occupies a position leveraging captive semiconductor supply for premium Android-based units. North American infrastructure heritage resides with CommScope Holding, which represents the cable-focused systems integrator archetype sustaining operator relationships across legacy MSO footprints.
| Leading Market Players |
|---|
| CommScope Holding |
| Huawei Technologies |
| HUMAX Electronics |
| Samsung Electronics |
| Technicolor SA |
| Sagemcom SAS |
| Advanced Digital Broadcast |
| EchoStar Corporation |
| Roku |
| Others |
Supply Flow & Price Mechanics
Advanced SoC fabrication concentrates in Taiwan and South Korea, anchoring margin capture at the semiconductor tier while downstream hardware assemblers compete on operational efficiency and certification speed.
Pricing Analysis
Configured-to-order pricing for hospitality and government deployments commands substantial premiums over standard residential units, with customization depth and centralized management integration as primary value drivers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with California Energy Commission compliance tiers adding further stratification. Cost compression in the residential segment intensifies as smart TV native applications and HDMI streaming sticks erode standalone box viability. Operator procurement teams exhibit the highest price sensitivity, while hospitality chains prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Supplier-financing facilities and extended payment terms from foundry operators have become critical competitive weapons for vendors bidding on multi-million unit operator tenders. Component sourcing draws from Taiwan and South Korea for advanced SoCs, China for PCB assembly and power management ICs, and Vietnam for final box integration. Single-source vulnerability concentrates in 4K HDR decoder chip supply, exposing procurement to geopolitical export control disruption. Distribution runs through direct operator tenders for volume deployments, with regional distributors serving replacement demand and smaller MSO accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded Linux expertise for Android TV customization and security patch maintenance concentrates in specific technology clusters, creating acute talent scarcity that constrains vendor expansion velocity.
For Market Incumbents: Entrench operator relationships through backward integration into conditional-access module production and accelerated certification pre-emption under India's BIS and China's MIIT frameworks. Satellite infrastructure heritage and legacy cable MSO footprints provide defensive moats against streaming substitution, though Android TV middleware convergence demands sustained R&D commitment to reference design partnerships. For New Entrants and Emerging Players: Pursue hospitality vertical expansion and multi-dwelling unit channels where customized user-interface requirements and property management system integration sustain superior margins. Southeast Asian cable operators upgrading to IP-based delivery present the most penetrable geographic entry point, with white-label Android TV customization for tier-two operators as the preferred go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor vertical integrators with captive SoC supply and energy-efficiency certification leadership, positioned for sustained viability through regulatory tightening cycles. Monitor FCC AllVid implementation velocity and EU Ecodesign directive enforcement intensity as inflection indicators for hardware redesign demand and vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Android TV Reference Design Partnership | Reduces proprietary middleware engineering headcount while accelerating operator procurement consolidation. |
| Energy-Efficiency Certification Pre-emption | Secures market access under California Energy Commission and EU Ecodesign standby-power thresholds. |
| Hospitality Vertical Platform Integration | Captures superior margins through centralized management and customized user-interface deployments. |
| Conditional-Access Module Backward Integration | Reduces DRM integration complexity and extends contract values with pay-TV operators. |
| Multi-Million Unit Operator Tender Execution | Locks in volume commitments with Reliance Jio, Bharti Airtel, and regional FTTH expansion programs. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pay-TV operator procurement directors, hospitality technology integrators, semiconductor component suppliers, and conditional-access system vendors. Secondary validation drew from FCC AllVid proceeding documentation, EU Ecodesign directive regulatory filings, BIS compulsory registration scheme publications, and MIIT network-access license records. Bottom-up unit shipment estimates by product type and technology tier were triangulated against top-down operator capex disclosure analysis.
Calibration against historical replacement cycles and infrastructure deployment timelines anchored projections across the analysis window. Segmentation modeling spanned product architecture, middleware technology, end-user category, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating FTTH penetration rates, satellite pay-TV subscriber trends, and streaming substitution coefficients.
Macroeconomic conditions sit as an overlay; deviation in fiber deployment capital availability, semiconductor foundry capacity allocation, or trade policy enforcement would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation schedules and operator procurement consolidation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Low Power Wide Area Network (LPWAN) Market
Telecom Hardware
Global Time Sensitive Networking Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
DWDM Transceiver Market
Telecom Hardware
Global FPGA in Telecom Sector Market
Telecom Hardware
Synchronous Optical Network (SONET) Market
Telecom Hardware
Voice Communication Equipment Market
Telecom Hardware
Base Station Market
Telecom Hardware
Very Small Aperture Terminal (VSAT) Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Broadcast Antenna Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
5G BTS Antenna Market