
 NFC Tag Ics Market | 2026-2036
NFC Tag Ics Market Size, Share, and Industry Trends Forecast 2026-2036
NFC Tag Ics Market Foresight
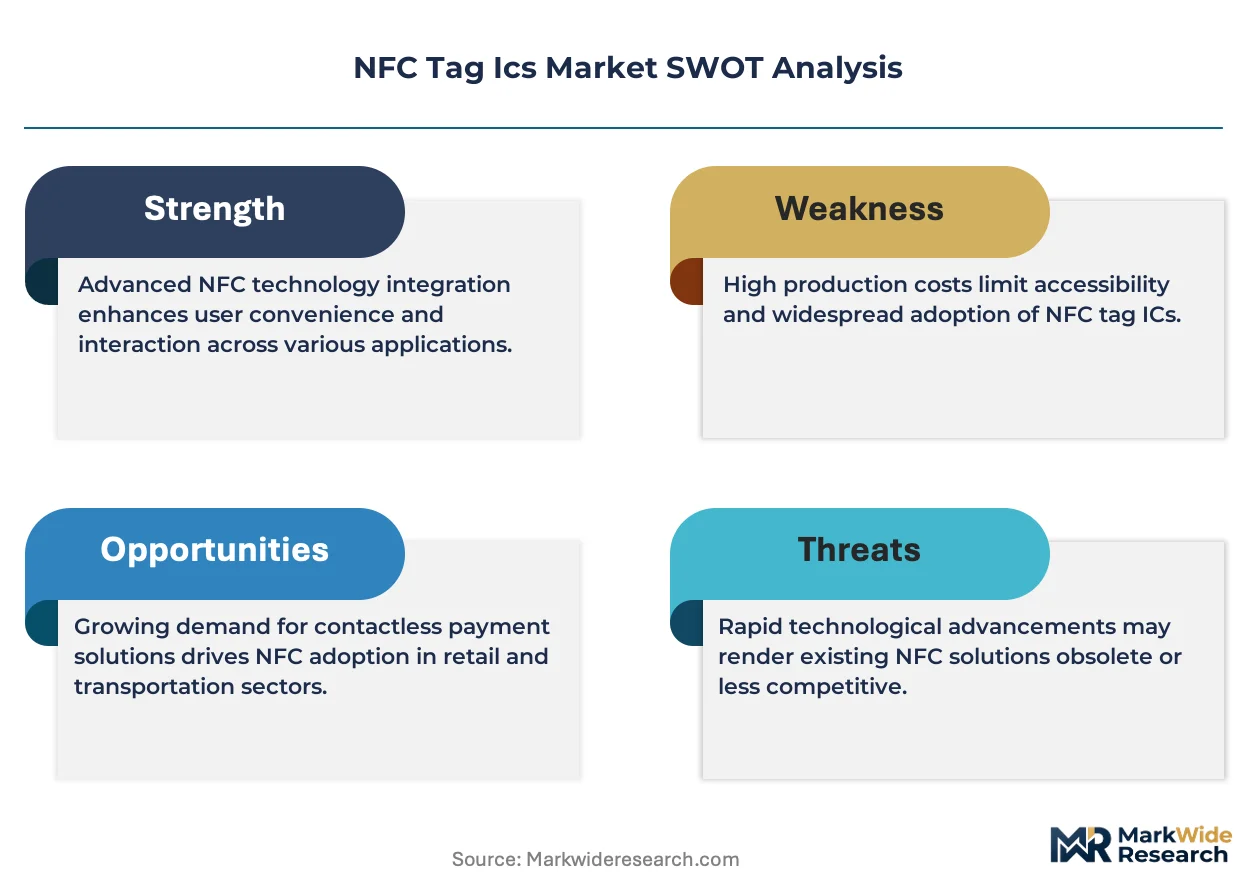
Retail payment infrastructure is expanding as the dominant demand vector for NFC tag ICs, displacing earlier reliance on standalone access control deployments. NXP Semiconductors leverages its secure element portfolio to anchor European banking and transit credential programs. STMicroelectronics sustains R&D intensity across dual-interface and contactless microcontroller lines. Broadcom competes through integrated NFC-Wi-Fi combo silicon for premium smartphone sockets.
NFC tag integrated circuits are semiconductor devices operating at 13.56 MHz, embedding non-volatile memory, radio frequency front-ends, and cryptographic controllers within single-die or multi-chip packages to enable short-range wireless data exchange between powered readers and unpowered tags. Passive NFC tags command the highest unit volumes due to minimal bill-of-materials and battery-free operation, though NFC controllers capture disproportionate margin pools through firmware complexity and security certification requirements. Payment Solutions applications lead value realization, while Logistics trails in penetration but offers replacement runway as pallet-level tracking mandates spread.
The European Commission's Radio Equipment Directive and ETSI EN 300 330 standards govern spectrum allocation and electromagnetic compatibility, forcing redesign cycles for products targeting EU member states. The Federal Communications Commission in the United States enforces Part 15 rules for unlicensed ISM band operation, creating divergent test regimes that fragment certification costs. China's Ministry of Industry and Information Technology administers network access licenses for cellular-NFC converged devices, adding procedural steps for foreign suppliers. Stakeholders must monitor evolving eIDAS qualification thresholds and decide whether to pursue Common Criteria certification ahead of anticipated digital identity wallet integration.
Market Dynamics
Contactless payment infrastructure is concentrating procurement decisions among retail banking consortia, compressing vendor qualification cycles and favoring suppliers with pre-certified secure element portfolios. This demand consolidation is restructuring competitive access to the highest-margin application segment.
Growth Catalysts
- Payment Solutions:Retail banking networks in France, Germany, and the Netherlands are mandating EMVCo-compliant contactless terminals, pulling passive tag volumes into merchant infrastructure refresh cycles.
- ETSI EN 300 330:The European harmonized standard for short-range devices is accelerating product homologation, reducing time-to-market for qualified NFC controller designs.
- Controller silicon:Multi-protocol NFC controllers integrating ISO 14443 Type A/B and FeliCa compatibility are displacing single-mode legacy designs in transit credential deployments.
Market Restraints
- Controller silicon concentration:Foundry capacity for advanced NFC controllers clusters in Taiwan and South Korea, exposing procurement to geopolitical logistics disruption.
- Secure element certification costs:Common Criteria EAL5+ evaluation cycles consume 18-24 months and seven-figure capital outlays, gating mid-tier vendor market entry.
- Ultra-wideband substitution:Apple's UWB-based spatial awareness protocols in premium handsets are fragmenting short-range wireless standards, diverting R&D investment from pure NFC development.
Strategic Opportunities
- India:The RBI's tokenization mandate for card-on-file transactions is forcing merchant acquirers to deploy NFC-enabled point-of-sale terminals at scale, creating fresh demand for certified controller silicon.
- Healthcare asset tracking:FDA Unique Device Identification requirements for Class II and III medical devices are opening NFC tag deployment for surgical instrument sterilization workflows.
- NFC-Bluetooth Low Energy convergence:Dual-radio tags enabling seamless handoff between tap-to-pair and continuous proximity monitoring are penetrating industrial condition-monitoring applications.
Industry Challenges
- RF engineering talent scarcity:Specialized antenna design and electromagnetic compatibility testing expertise concentrates among semiconductor veterans in Eindhoven, Grenoble, and Austin, constraining expansion capacity.
- Legacy system integration:Enterprise access control networks running MIFARE Classic infrastructure resist firmware migration to AES-128 secured protocols, elongating sales cycles for upgraded IC families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NFC Tag Ics Market |
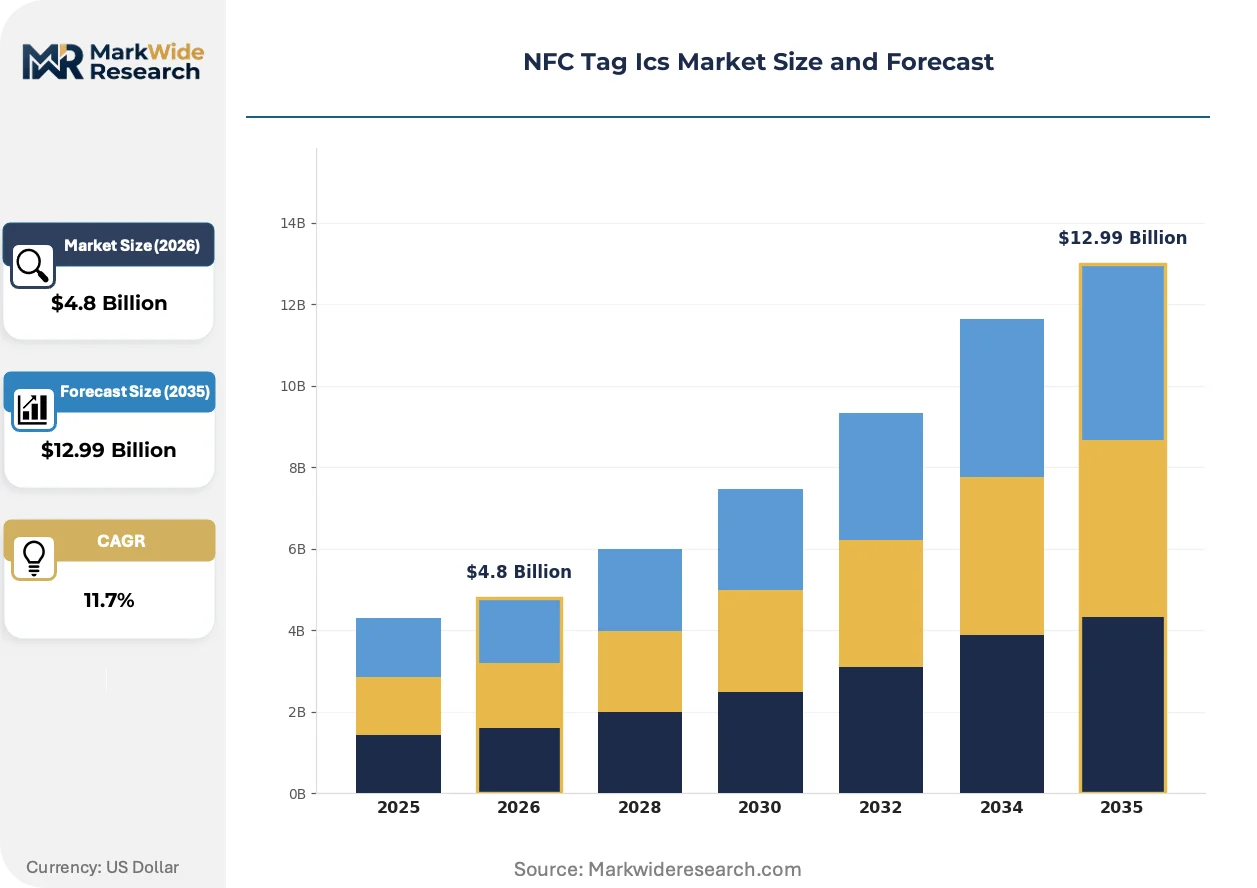
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active NFC Tags, Passive NFC Tags, NFC Readers, NFC Controllers Application: Payment Solutions, Access Control, Logistics, Marketing Campaigns End User: Retail Industry, Healthcare Sector, Transportation Sector, Entertainment Venues Technology: RFID Technology, Bluetooth Connectivity, Wi-Fi Integration, Others |
| Companies Covered | NXP Semiconductors, STMicroelectronics, Broadcom, Infineon Technologies, Texas Instruments, Qualcomm Technologies, Sony Corporation, Samsung Electronics, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NFC Tag Ics Market Shifts & Advancements
Silicon architecture is bifurcating between ultra-low-cost passive tags for disposable applications and secure microcontrollers for credential-heavy use cases. This technical divergence is forcing vendors to place separate bets on process node investment.
Energy-harvesting NFC tags with integrated temperature and humidity sensors are automating cold-chain compliance documentation for pharmaceutical shipments. Logistics operators in Germany and the Netherlands are piloting these devices for lane-level tracking. The technology is automating audit trail generation that previously required manual scanner intervention, compressing insurance claim resolution timelines.
The European Commission's eIDAS 2.0 framework mandates interoperable digital identity wallets by 2026, compelling NFC controller vendors to pre-integrate qualified electronic signature modules. Semiconductor designers are redesigning secure element architectures to accommodate government-issued credential storage. Banking and government service applications face the steepest compliance ramps, with pilot programs already live in Belgium and Estonia.
Merchant acquirers are consolidating terminal procurement through managed service contracts rather than hardware purchase, shifting payment device economics toward per-transaction revenue sharing. This model compresses upfront IC pricing tolerance while extending supplier relationships over 5-7 year service terms. The restructuring is most visible in the United Kingdom and Nordic markets, where banking-as-a-service platforms intermediate terminal deployment decisions.
NFC Tag Ics Market Segmentation
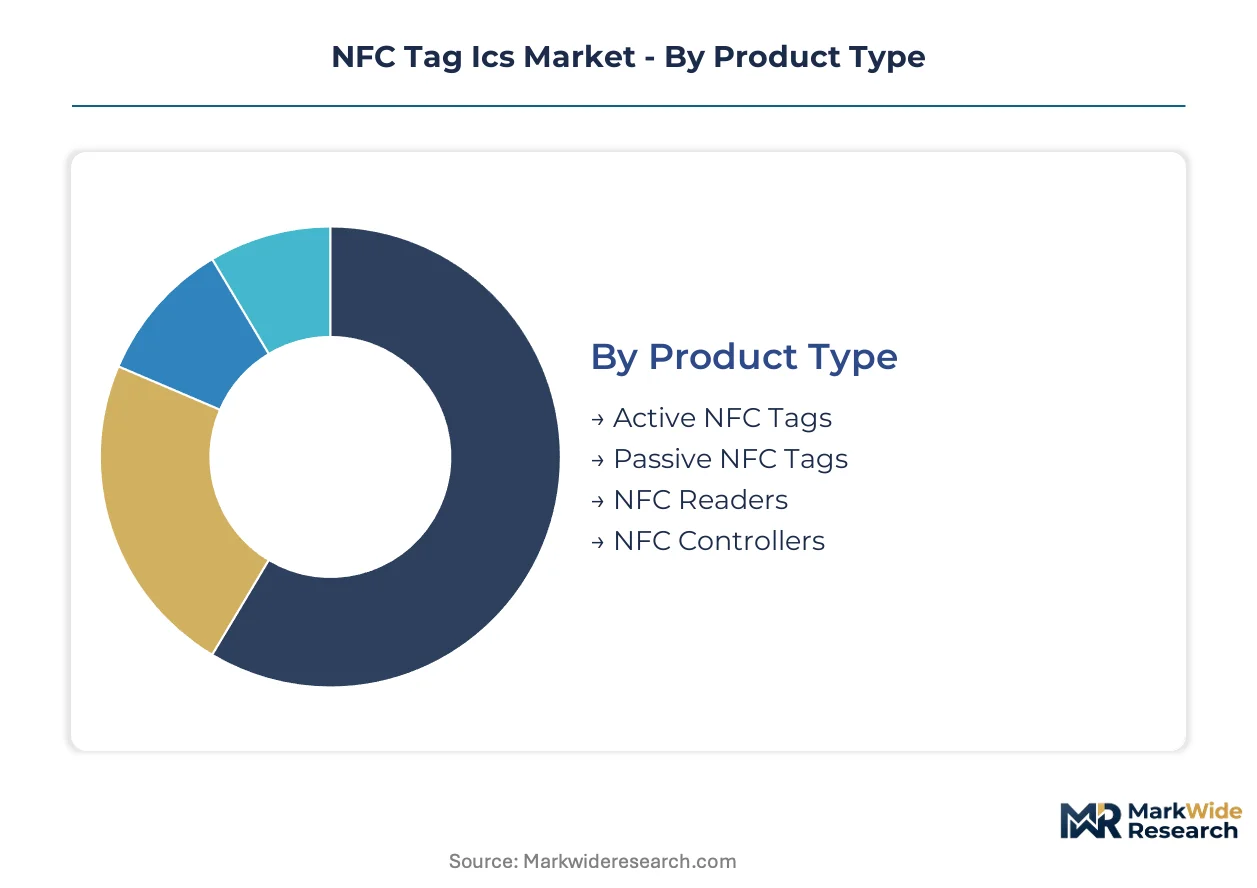
NFC tag ICs serve radically different integration depths—from disposable passive labels to secure microcontroller cores in smartphones. Segment boundaries reflect this architectural split between standalone tags and embedded controllers. Procurement patterns diverge accordingly, with payment infrastructure demanding certified secure elements while logistics favors minimal-cost passive designs.
Product Type:
Integration depth separates standalone tags from embedded controllers, with passive designs dominating unit economics and active variants serving specialized sensing applications.
- Active NFC Tags:Battery-assisted designs integrate sensors and logging capabilities for cold-chain monitoring. Pharmaceutical shipments from Germany and the Netherlands deploy these for autonomous temperature documentation during transit.
- Passive NFC Tags:The workhorse category operates without onboard power, harvesting energy from reader fields to exchange small data payloads. Retail payment terminals in France, Germany, and the Netherlands pull massive volumes into merchant infrastructure refresh cycles mandated by EMVCo compliance.
- NFC Readers:Powered devices initiate communication with unpowered tags, embedding in point-of-sale terminals and access control gates.
- NFC Controllers:Silicon cores managing protocol stacks and security operations, commanding premium pricing through firmware complexity and Common Criteria certification requirements.
Volume placements concentrate in Passive NFC Tags; the faster expansion belongs to NFC Controllers.
Application:
Commercial maturity varies sharply across use cases, with payment infrastructure commanding the steepest vendor qualification barriers.
- Payment Solutions:EMVCo-compliant contactless transactions anchor the highest-margin demand pool. Banking consortia in France, Germany, and the Netherlands compress vendor qualification cycles, favoring suppliers with pre-certified secure element portfolios.
- Access Control:Enterprise credential systems span legacy MIFARE Classic deployments and modern AES-128 secured protocols. Migration friction elongates sales cycles for upgraded IC families.
- Logistics:Pallet-level tracking mandates are spreading, though penetration trails payment solutions. Cold-chain operators pilot energy-harvesting tags with integrated sensors for pharmaceutical audit automation.
- Marketing Campaigns:Disposable tap-to-engage tags for promotional activation, prioritizing unit cost over durability or security certification.
Payment Solutions captures the dominant revenue share; Logistics is climbing the fastest as track-and-trace mandates broaden.
End User:
Customer sophistication determines pricing tolerance, with regulated sectors demanding certified silicon and consumer-facing venues prioritizing deployment speed.
- Retail Industry:Merchant acquirers consolidate terminal procurement through managed service contracts, shifting economics toward per-transaction revenue sharing over 5-7 year terms.
- Healthcare Sector:FDA Unique Device Identification requirements for Class II and III medical devices are opening NFC deployment for surgical instrument sterilization workflows.
- Transportation Sector:Transit credential programs in European metropolitan networks require multi-protocol controllers integrating ISO 14443 Type A/B and FeliCa compatibility.
- Entertainment Venues:Stadium and festival access systems favor rapid-deployment passive tags with minimal customization requirements.
Retail Industry dominates current procurement; Healthcare Sector shows the steepest expansion trajectory as regulatory compliance deadlines approach.
Technology:
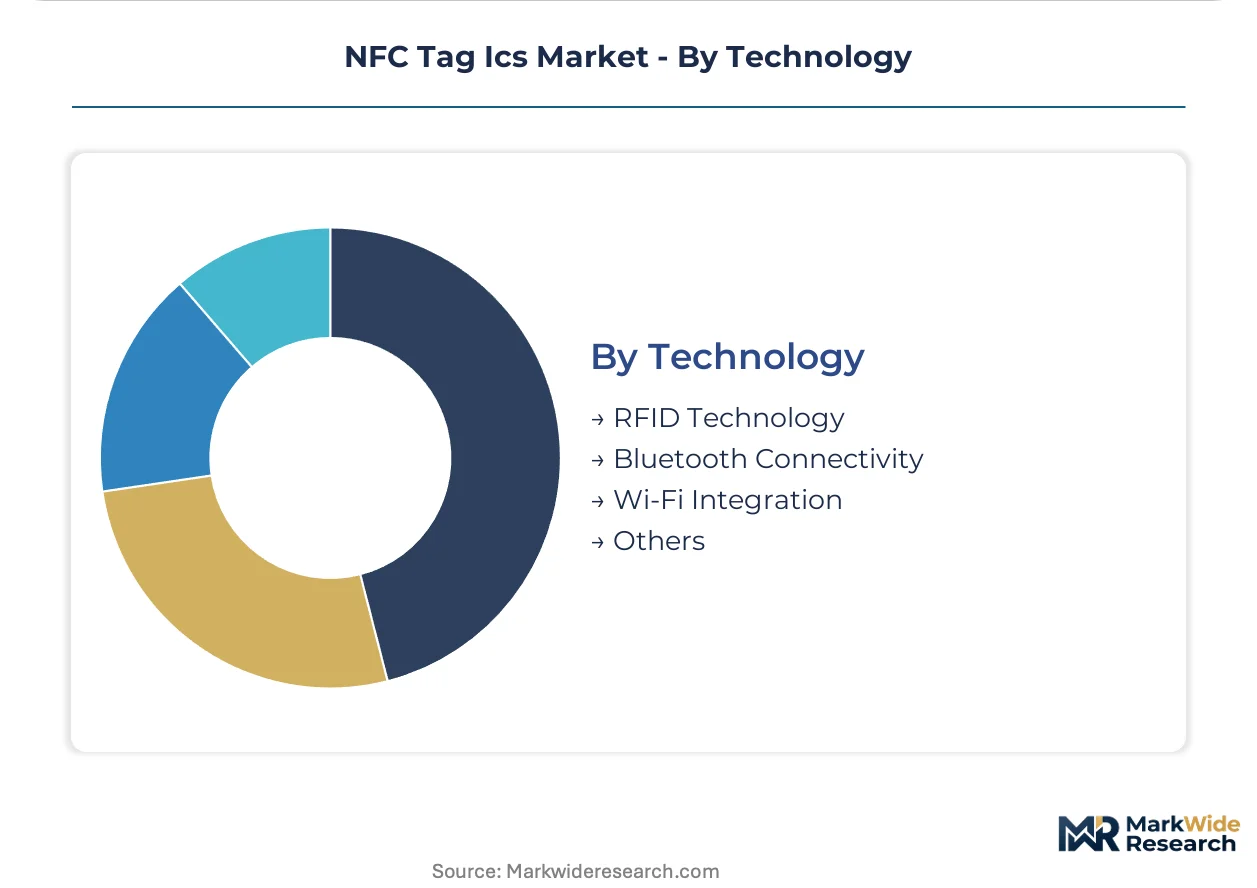
Radio layer choices determine interoperability scope and power consumption tradeoffs, with pure NFC competing against converged multi-protocol stacks.
- RFID Technology:The foundational 13.56 MHz air interface standardized under ISO/IEC 14443 and ISO/IEC 15693, embedding non-volatile memory and RF front-ends in single-die packages.
- Bluetooth Connectivity:Dual-radio tags enabling seamless handoff between tap-to-pair initiation and continuous proximity monitoring are penetrating industrial condition-monitoring applications.
- Wi-Fi Integration:Broadcom competes through integrated NFC-Wi-Fi combo silicon for premium smartphone sockets, consolidating radio subsystems to reduce board area.
- Others:Ultra-wideband and proprietary short-range protocols fragmenting standards in spatial awareness applications.
RFID Technology anchors volume shipments; Bluetooth Connectivity is gaining share fastest through industrial convergence demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate foundry capacity for advanced NFC controller silicon, concentrating supply chain leverage in East Asia while European banking consortia drive demand through EMVCo-mandated terminal refreshes.
China
MIIT network access licenses govern cellular-NFC converged devices, adding procedural steps for foreign suppliers accessing the domestic market. Shanghai and Shenzhen anchor wafer fabrication clusters where multi-protocol controller production scales for export markets. The Ministry of Industry and Information Technology's certification requirements shape product design cycles for entrants targeting Chinese smartphone OEMs.
United States
FCC Part 15 rules enforce unlicensed ISM band operation, creating divergent test regimes that fragment certification costs for suppliers. Austin and Silicon Valley host RF engineering talent pools specialized in antenna design and electromagnetic compatibility testing. The Federal Communications Commission's regulatory framework forces redesign cycles distinct from European harmonized standards.
Germany
Retail banking networks in France, Germany, and the Netherlands mandate EMVCo-compliant contactless terminals, pulling passive tag volumes into merchant infrastructure refresh cycles. Eindhoven and Grenoble anchor semiconductor design expertise for secure element architectures. The KBA and federal banking regulators enforce credential interoperability standards that compress vendor qualification timelines.
India
RBI tokenization mandates for card-on-file transactions force merchant acquirers to deploy NFC-enabled point-of-sale terminals at scale. Bangalore and Hyderabad concentrate fintech infrastructure deployment decisions for domestic payment networks. The Reserve Bank of India's regulatory push creates fresh demand for certified controller silicon across tier-1 and tier-2 urban centers.
Japan
METI industrial standards and FeliCa protocol heritage sustain multi-protocol controller demand for transit credential deployments. Tokyo and Osaka metropolitan networks require ISO 14443 Type A/B and FeliCa compatibility in unified ticketing systems. The Ministry of Economy, Trade and Industry shapes procurement specifications for railway and retail convergence applications.
NFC Tag Ics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with secure element portfolios commanding premium positioning in payment infrastructure while passive tag production scales through foundry partnerships. The vendor base concentrates around semiconductor conglomerates with pre-certified banking credentials and fabless designers serving logistics and marketing applications. Three archetypes dominate: integrated device manufacturers with captive secure element lines, fabless specialists licensing controller IP, and foundry-service hybrids bridging cost-sensitive passive tag volumes. Competitive moves center on Common Criteria certification pre-positioning ahead of eIDAS 2.0 wallet mandates and multi-protocol controller R&D to capture transit credential consolidation.
Within the integrated secure element tier, NXP Semiconductors and STMicroelectronics exemplify European banking and transit anchoring positions. Broadcom occupies a distinct vector through combo silicon integration for premium mobile device sockets. These three represent the archetype fragmentation between credential-heavy secure controllers, multi-protocol transit specialists, and radio subsystem consolidators competing for smartphone platform slots.
| Leading Market Players |
|---|
| NXP Semiconductors |
| STMicroelectronics |
| Broadcom |
| Infineon Technologies |
| Texas Instruments |
| Qualcomm Technologies |
| Sony Corporation |
| Samsung Electronics |
| Renesas Electronics |
| Others |
Supply & Pricing Matrix
EMVCo certification timelines gate both qualified supply and premium-tier pricing access, compressing vendor margins for uncertified entrants while rewarding pre-certified secure element portfolios with sustained pricing power in banking and transit procurement cycles.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with merchant acquirers paying 15-25% markups for certified controller silicon available under 12-week delivery windows versus spot-market inventory carrying discount penalties for extended stockholding. Three-tier pricing structure across Common Criteria EAL5+, EAL4+, and uncertified economy tiers separates payment infrastructure budgets from logistics tag procurement. Pricing pressure stems from managed service contract economics shifting terminal procurement toward per-transaction revenue sharing over 5-7 year terms. Retail banking consortia exhibit lowest price sensitivity due to compliance mandates, while marketing campaign buyers prioritize unit cost above certification grade.
Supply Chain Analysis
Dual-sourcing requirements from European banking consortia mandate multi-supplier qualification for secure element controllers, forcing vendors to maintain redundant foundry relationships despite concentration economics. Taiwan, South Korea, and China anchor wafer fabrication for advanced NFC controllers, with Shanghai and Shenzhen clusters scaling multi-protocol designs for export markets. Silicon feedstock, photoresist chemicals, and advanced packaging substrates constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan Strait logistics corridors. Distribution runs through semiconductor distributors serving OEM terminal manufacturers and merchant acquirer managed service platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive secure element foundry capacity is becoming the decisive competitive lever, with NXP Semiconductors and STMicroelectronics deepening backward integration while fabless competitors face margin compression from foundry pricing cycles.
For Market Incumbents: Anchor market position through pre-certification of controller architectures against anticipated eIDAS 2.0 wallet mandates, securing banking and government credential slots before compliance deadlines harden procurement specifications. Deepen backward integration into 40nm and 28nm foundry partnerships to reduce exposure to Taiwan capacity constraints. Ultra-wideband substitution in premium handsets threatens NFC controller socket erosion; multi-protocol R&D investment in NFC-Bluetooth Low Energy convergence defends against radio subsystem consolidation by Broadcom and Qualcomm. For New Entrants and Emerging Players: Launch via healthcare asset tracking specialization, exploiting FDA Unique Device Identification deadlines to penetrate surgical instrument sterilization workflows before incumbent secure element vendors redirect R&D bandwidth. Target India RBI tokenization infrastructure deployment in tier-2 urban centers, where merchant acquirer procurement cycles remain less consolidated than European banking consortia. White-label controller silicon for industrial condition-monitoring applications offers faster qualification paths than payment certification tracks. For Investors and Strategic Acquirers: India's central bank mandating tokenization-compliant terminal deployment is the leading indicator that certified controller demand will sustain expansion independent of smartphone socket saturation. Five-to-ten year viability hinges on digital identity wallet integration across European and Asian government credential programs. Acquisition targets should exhibit Common Criteria EAL4+ pre-certification and existing foundry allocation agreements. The signal to monitor is eIDAS 2.0 pilot program conversion to mandatory procurement specifications in Belgium and Estonia.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Pre-Certification | EMVCo and Common Criteria EAL5+ certification ahead of eIDAS 2.0 mandates locks banking credential slots. |
| Multi-Protocol Controller R&D | ISO 14443 Type A/B and FeliCa compatibility captures transit credential consolidation in Tokyo and Osaka networks. |
| Healthcare Specialization | FDA UDI compliance for Class II and III devices opens surgical instrument tracking applications with premium pricing. |
| Foundry Partnership Diversification | Dual-sourcing across Taiwan and South Korea reduces geopolitical logistics exposure for controller silicon supply. |
| Energy-Harvesting Tag Development | Integrated sensor tags automate pharmaceutical cold-chain documentation for German and Dutch logistics operators. |
Research Methodology
SEC filings from NXP Semiconductors, STMicroelectronics, and Broadcom, ETSI standardization documents, and EMVCo compliance registries formed the secondary backbone, cross-referenced against primary interviews with semiconductor procurement managers at European banking consortia, RF engineering directors in Eindhoven and Grenoble design clusters, and merchant acquirer terminal deployment leads. Bottom-up and top-down triangulation validated unit volume assumptions across passive tag and controller controller segments.
Bottom-up modeling anchored forecast outputs, with top-down macroeconomic cross-checks across the projection horizon. Segmentation dimensions included product type (passive tags, active tags, readers, controllers), application (payment solutions, access control, logistics, marketing), end user (retail, healthcare, transportation, entertainment), and technology (RFID, Bluetooth, Wi-Fi integration). CAGRs derived from fitted growth curves against historical banking terminal refresh cycles and regulatory mandate timelines. Industry-specific inputs encompassed EMVCo terminal deployment data and FDA UDI implementation schedules.
Geopolitical logistics disruption, eIDAS 2.0 implementation delays, and ultra-wideband substitution acceleration are the dominant revision risks to controller demand assumptions. Forecasts reflect documented assumptions regarding certification timeline elasticity and foundry capacity expansion plans. A model refresh is warranted upon material change in Taiwan Strait trade corridor stability or European digital identity wallet procurement specification finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
GNSS IC Market
IC (Integrated Circuits)
Audio Power Amplifier IC Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market