
 Battery Monitoring IC Market | 2026-2036
Battery Monitoring IC Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Monitoring IC Market Outlook
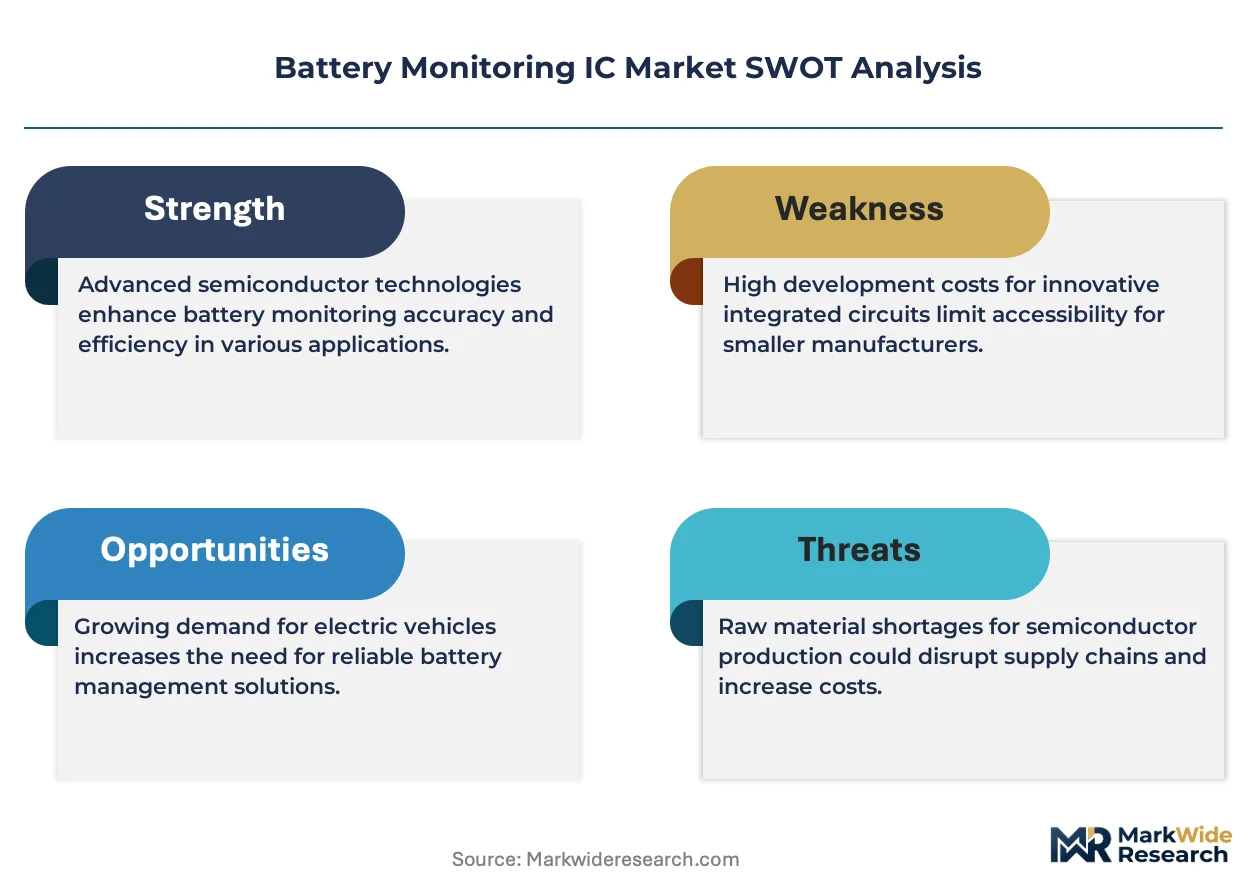
Power electronics engineering talent scarcity is bifurcating the competitive landscape between integrated semiconductor giants and specialized analog houses. Texas Instruments leverages its decades-long analog IP portfolio to sustain design-in relationships across automotive OEMs. Infineon Technologies anchors its position through in-house production of silicon carbide-compatible monitoring architectures. STMicroelectronics competes by extending its microcontroller ecosystem into battery management subsystems.
A battery monitoring integrated circuit measures cell voltage, current, and temperature with precision typically within one millivolt, enabling state-of-charge estimation and thermal runaway prevention in lithium-ion packs. Integrated Circuits combining multi-parameter sensing with embedded diagnostics command the strongest margin pools as OEMs reduce component count. Electric Vehicles represent the fastest-growing application segment, while Industrial Equipment maintains steadier procurement volumes with longer qualification cycles. Digital Technology is displacing legacy analog approaches in high-cell-count packs, though Linear Technology persists in cost-sensitive consumer electronics.
The EPA tailpipe emission rules and NHTSA battery safety standards in the United States, alongside ECHA REACH compliance requirements in Europe, compel manufacturers to certify monitoring accuracy across temperature extremes and aging profiles. China's MIIT enforces GB standards for new energy vehicle battery management systems, creating a fragmented certification landscape for exporters. Stakeholders must decide whether to pursue jurisdiction-specific qualification paths or modular platform designs that span multiple regulatory regimes.
Market Dynamics
The transition from passive analog monitoring to intelligent digital battery management systems is restructuring procurement priorities across automotive and industrial verticals. Cell-level traceability mandates from Brussels to Beijing are forcing IC suppliers to embed diagnostic capabilities directly into silicon.
Growth Catalysts
- EU Battery Regulation cell-passport requirements:Manufacturers must embed unique identifiers and lifecycle data into each cell, creating mandatory demand for integrated monitoring circuits with embedded memory and secure authentication.
- Silicon carbide powertrain adoption:Higher switching frequencies in EV inverters demand faster, more precise cell balancing and fault detection, pulling advanced monitoring architectures into mainstream vehicle platforms.
- China's new energy vehicle production concentration:Domestic battery supply chain scaling in Jiangsu and Fujian provinces generates concentrated procurement volumes for localized IC qualification and volume supply agreements.
Market Restraints
- 300mm analog wafer supply tightness:Specialty foundry capacity for precision analog processes remains constrained, with allocation prioritizing automotive MCUs and power discretes over battery monitoring ICs.
- Qualification timeline compression:AEC-Q100 Grade 0 certification cycles extend 18-24 months, locking design wins years before production and freezing out late entrants from high-volume EV platforms.
- Discrete passive integration limits:Precision resistors and temperature references cannot scale with digital logic, creating a packaging cost floor that prevents monolithic solutions below certain cell-count thresholds.
Strategic Opportunities
- Second-life battery stationary storage:Decommissioned EV packs require refurbished monitoring electronics for grid-scale deployment, opening a aftermarket IC segment with lower performance but high volume potential.
- India PLI scheme for ACC battery manufacturing:Local cell production incentives create a greenfield market for monitoring IC suppliers willing to establish domestic qualification and technical support presence.
- Wireless cell-monitoring convergence:Elimination of isolation transformers and harness weight through RF-based intra-pack communication enables architectural redesigns for aviation and racing applications.
Industry Challenges
- Mixed-signal design expertise scarcity:Universities produce digital IC graduates at multiples of analog specialists, forcing employers to poach from automotive Tier-1s or retrain RF engineers.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of NHTSA battery safety standards, ECHA REACH substance restrictions, and MIIT GB compliance creates documentation and testing cost multiplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Monitoring IC Market |
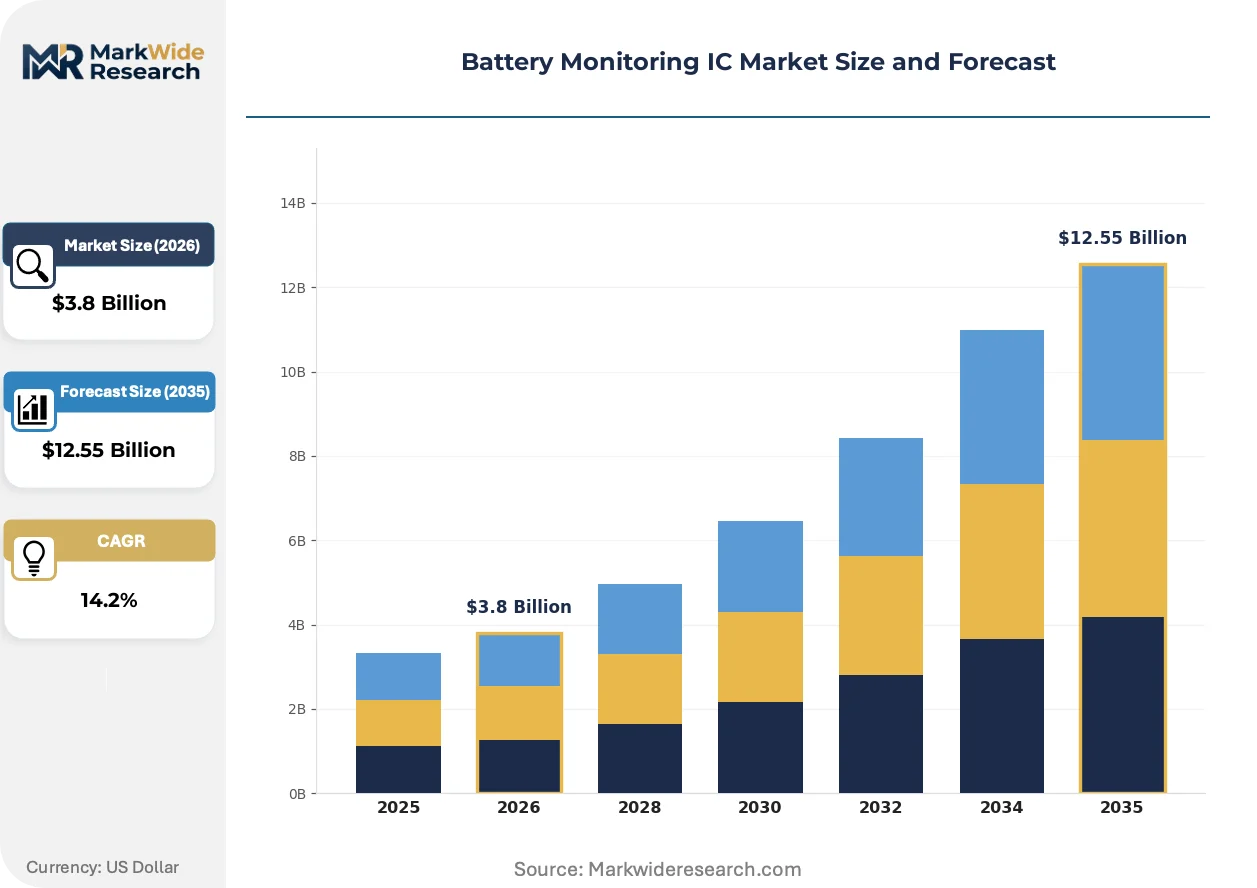
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voltage Monitors, Current Sensors, Temperature Monitors, Integrated Circuits Application: Electric Vehicles, Renewable Energy Systems, Consumer Electronics, Industrial Equipment Technology: Linear Technology, Digital Technology, Analog Technology, Wireless Technology End User: Aerospace, Automotive, Healthcare, Telecommunications |
| Companies Covered | NXP Semiconductors, Infineon Technologies, Texas Instruments, ON Semiconductor, Microchip Technology, Analog Devices, STMicroelectronics, ROHM, Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Monitoring IC Market Strategic Shifts
Architectural migration toward functional safety-rated monitoring subsystems is compressing supplier qualification cycles and elevating firmware integration requirements. Digital convergence is eroding the boundary between sensing front-ends and host microcontroller intelligence.
Isolated delta-sigma modulators with integrated DC-DC converters are displacing traditional isolated amplifier architectures in high-voltage EV battery packs. Automotive OEMs in Germany and the United States specify these devices for 800V platforms to achieve sub-microsecond fault detection latency. This displacement is collapsing the discrete magnetic component supply chain that previously dominated high-voltage sensing.
China's MIIT enforcement of GB/T 38661 and GB/T 39086 standards for new energy vehicle battery management systems is mandating specific fault-detection response times and diagnostic coverage metrics. Domestic IC suppliers gain preferential access to BYD and CATL supply chains through pre-qualified reference designs. Exporters must replicate this certification stack or cede volume to local competitors.
Cell-as-a-service leasing models in European commercial vehicle fleets are transferring monitoring IC procurement decisions from OEMs to battery asset operators. These operators prioritize field-replaceable monitoring modules and over-the-air calibration updates over upfront silicon cost. The Netherlands and Nordic markets exhibit the strongest adoption of this operational expenditure framework.
Battery Monitoring IC Market Segmentation
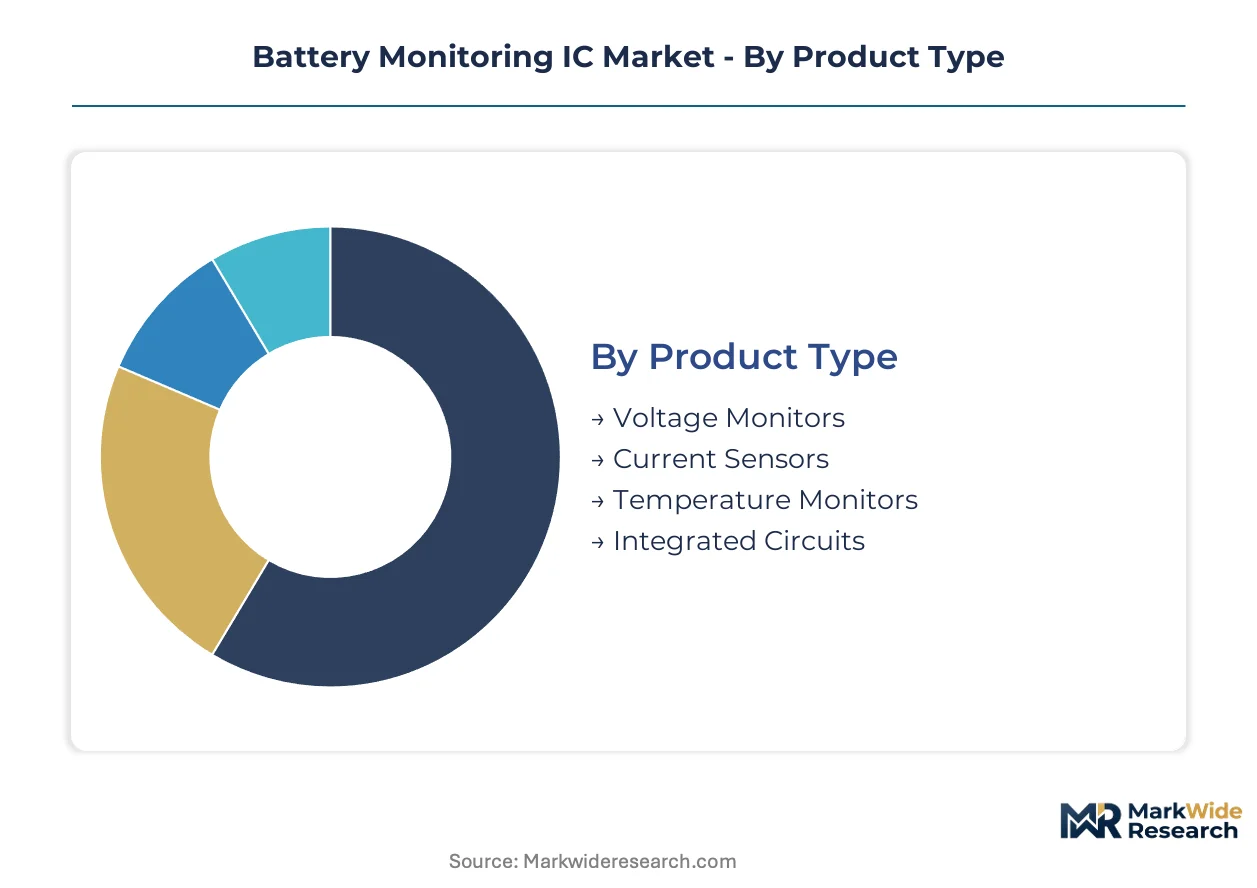
Battery monitoring IC procurement channels vary sharply by segment complexity. Automotive OEMs source through direct semiconductor partnerships while industrial buyers favor distribution networks for lower-volume configurations.
Product Type:
Voltage monitors and current sensors flow predominantly through direct OEM contracts, whereas temperature monitors and basic integrated circuits reach end-users via broadline distributors and specialized electronics retailers.
- Voltage Monitors:These circuits measure individual cell potentials with precision typically within one millivolt, employing successive approximation or delta-sigma architectures. Demand concentrates in German and Chinese electric vehicle platforms where 800V battery packs require sub-microsecond fault detection latency. The EU Battery Regulation's cell-passport mandates are accelerating design-ins with embedded authentication.
- Integrated Circuits:Multi-parameter sensing combines voltage, current, and thermal measurement with embedded diagnostics on single die. Procurement tilts toward BYD and CATL supply chains in Jiangsu and Fujian provinces where domestic IC suppliers hold pre-qualified reference design advantages.
- Current Sensors:Hall-effect and shunt-based architectures dominate high-current EV applications.
- Temperature Monitors:Precision thermistor interfaces and silicon bandgap sensors address thermal runaway prevention requirements.
Voltage monitors dominate installed base. Integrated circuits are where expansion concentrates.
Application:
Cost tier stratification separates premium automotive qualification from price-sensitive consumer electronics, with renewable energy systems occupying a mid-tier reliability band.
- Electric Vehicles:Battery management systems for lithium-ion packs require AEC-Q100 Grade 0 certification with 18-24 month qualification cycles. Procurement volumes cluster in China, Germany, and the United States as these countries scale domestic battery supply chains and enforce NHTSA, ECHA REACH, and MIIT GB compliance respectively.
- Industrial Equipment:Forklifts, uninterruptible power supplies, and material handling systems demand longer operational lifespans with steadier procurement volumes. German industrial OEMs specify extended temperature range performance from -40°C to 125°C, locking in analog-focused suppliers through decade-long supply agreements.
- Renewable Energy Systems:Grid-scale battery storage and residential solar-plus-storage installations require refurbished monitoring electronics for second-life EV pack deployment.
- Consumer Electronics:Smartphones, laptops, and power tools prioritize cost minimization over diagnostic sophistication.
Industrial equipment dominates installed base. Electric vehicles are gaining share fastest.
Technology:
Volume concentration favors digital architectures in high-cell-count automotive packs while analog persists in cost-constrained consumer segments.
- Digital Technology:Microcontroller-integrated battery management subsystems execute state-of-charge estimation through Kalman filtering and machine learning inference. China's MIIT enforcement of GB/T 38661 and GB/T 39086 standards mandates specific fault-detection response times that digital implementations satisfy more readily than legacy approaches.
- Linear Technology:Continuous-time analog front-ends maintain dominance in consumer electronics where power consumption and die area constraints outweigh diagnostic depth requirements. Texas Instruments and Analog Devices sustain margin pools through decades-long design-in relationships across portable device OEMs.
- Analog Technology:Discrete operational amplifier and comparator-based monitoring persists in legacy industrial installations.
- Wireless Technology:RF-based intra-pack communication eliminates isolation transformers and wiring harness weight for aviation and racing applications.
Linear technology dominates installed base. Digital technology is where expansion concentrates.
End User:
Customer type determines certification stacking intensity, with aerospace and automotive requiring the most extensive multi-jurisdiction documentation.
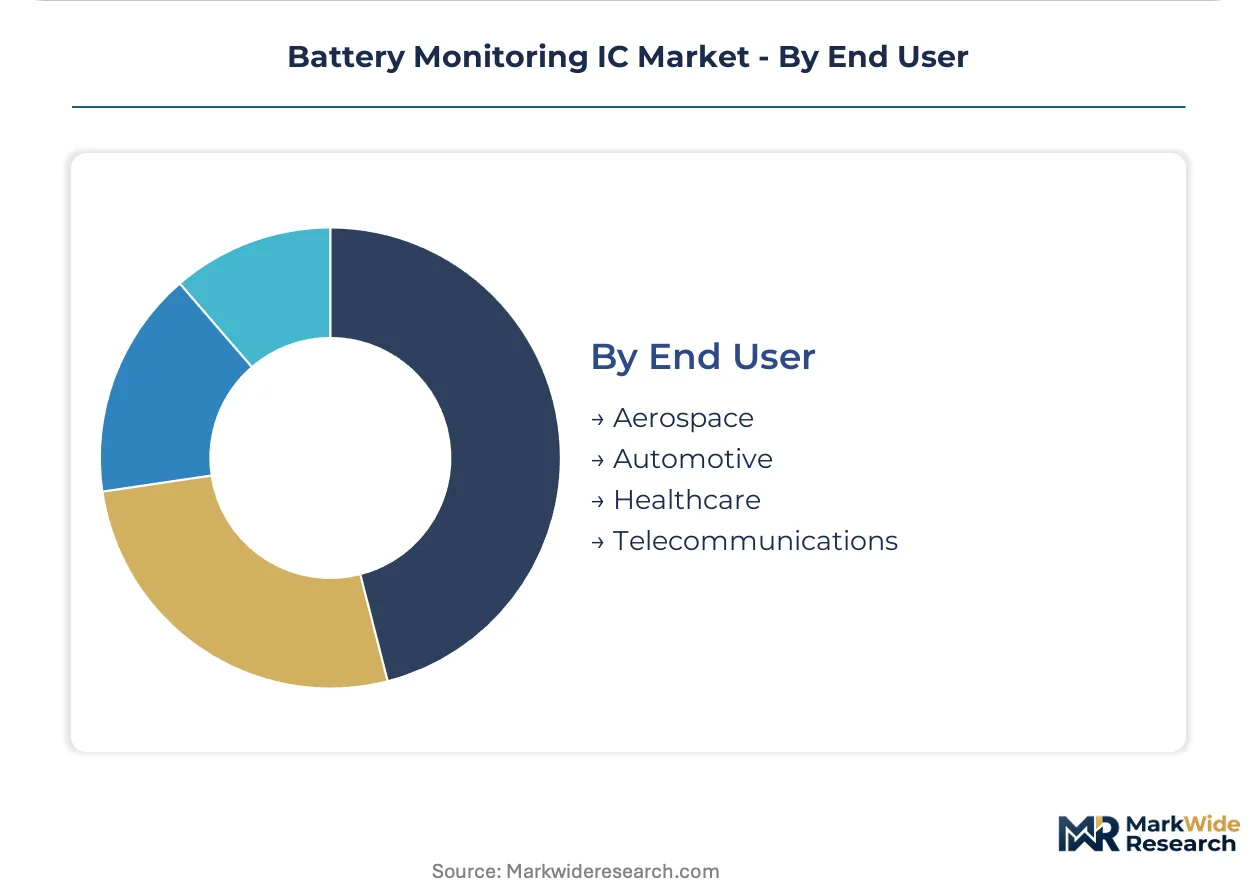
- Automotive:OEMs and Tier-1 suppliers specify functional safety-rated monitoring subsystems per ISO 26262 ASIL-D requirements. Cell-as-a-service leasing models in Dutch and Nordic commercial vehicle fleets are transferring procurement decisions from OEMs to battery asset operators who prioritize field-replaceable modules.
- Aerospace:Manned and unmanned electric aircraft demand wireless cell-monitoring convergence to reduce harness weight. FAA certification pathways for battery systems in advanced air mobility platforms are creating qualification bottlenecks that favor established suppliers with prior aerospace design wins.
- Healthcare:Portable medical devices and implantable systems require FDA-compliant monitoring accuracy across temperature extremes and aging profiles.
- Telecommunications:Base station backup power and data center uninterruptible power supplies prioritize mean time between failures over cell-level diagnostic granularity.
Automotive dominates installed base. Aerospace is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT enforcement of GB standards anchors the dominant geography, with procurement volumes clustering where domestic battery supply chains scale fastest. Regulatory fragmentation across Brussels, Washington, and Beijing creates distinct qualification pathways for IC suppliers.
China
Jiangsu and Fujian provinces generate concentrated demand as CATL and BYD expand cell production capacity. MIIT enforces GB/T 38661 and GB/T 39086 standards mandating specific fault-detection response times and diagnostic coverage metrics. Domestic IC suppliers secure preferential access through pre-qualified reference designs, forcing exporters to replicate certification stacks or cede volume.
Germany
Automotive OEMs specify functional safety-rated monitoring subsystems per ISO 26262 ASIL-D requirements for 800V battery platforms. ECHA REACH compliance restricts substance use in silicon packaging and thermal interface materials. Bavarian industrial clusters around Munich and Ingolstadt lock in analog-focused suppliers through decade-long supply agreements for extended temperature range performance.
United States
NHTSA battery safety standards and EPA tailpipe emission rules compel manufacturers to certify monitoring accuracy across temperature extremes and aging profiles. Silicon carbide powertrain adoption in Detroit and Austin design centers pulls advanced monitoring architectures into mainstream vehicle platforms. AEC-Q100 Grade 0 certification cycles extend 18-24 months, freezing design wins years before production.
India
The PLI scheme for ACC battery manufacturing creates a greenfield market for monitoring IC suppliers establishing domestic qualification presence. Tamil Nadu and Gujarat host emerging cell production facilities requiring localized technical support infrastructure. BIS standards for new energy vehicle components are converging with international automotive safety frameworks.
Netherlands
Cell-as-a-service leasing models in commercial vehicle fleets transfer procurement decisions from OEMs to battery asset operators. These operators prioritize field-replaceable monitoring modules and over-the-air calibration updates. Amsterdam and Rotterdam logistics corridors exhibit the strongest adoption of operational expenditure frameworks for battery management.
Battery Monitoring IC Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in a structure defined by analog IP depth and automotive qualification longevity. The upper tier commands design-in relationships through decades-long semiconductor ecosystem presence, while specialists defend position through silicon carbide compatibility and functional safety integration. Two archetypes dominate: diversified analog giants with automotive MCU adjacencies, and power semiconductor houses with captive SiC monitoring architectures. Competitive moves center on strategic partnerships for foundry capacity allocation and portfolio diversification into wireless cell-monitoring convergence.
Among diversified analog specialists, Texas Instruments and Analog Devices exemplify the design-in relationship archetype sustained through precision measurement heritage. Infineon Technologies anchors the power semiconductor vector with in-house production of silicon carbide-compatible monitoring architectures. These three occupy positions spanning the integrated-to-specialist spectrum, representing distinct competitive postures without overlapping strategic emphasis.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Infineon Technologies |
| Texas Instruments |
| ON Semiconductor |
| Microchip Technology |
| Analog Devices |
| STMicroelectronics |
| ROHM |
| Renesas Electronics Corporation |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide powertrain substitution for silicon IGBTs is redrawing procurement geography toward 800V-compatible monitoring architectures while compressing margin structures for legacy analog suppliers locked into 400V platform pricing.
Pricing Analysis
Price spreads between German automotive qualification tiers and Chinese domestic procurement run three-to-one for functionally equivalent die. Contract-based long-term offtake dominates high-volume EV platforms, with AEC-Q100 Grade 0 certification commanding substantial premiums over industrial-grade alternatives. Price differentiation hinges on ISO 26262 ASIL-D functional safety rating and volume scale commitments, with cost compression in consumer-grade segments intensifying as domestic Chinese suppliers expand reference design penetration. Battery asset operators in Dutch leasing fleets exhibit lowest price sensitivity, prioritizing field-replaceable modules and over-the-air calibration capabilities over upfront silicon cost.
Supply Chain Analysis
Container availability constraints on Shanghai-Rotterdam and Shenzhen-Los Angeles lanes have elevated inbound logistics costs for specialty analog wafers sourced from Taiwan, South Korea, and Japan. Precision analog process capacity draws from 200mm and 300mm foundries concentrated in Taiwan and South Korea, with raw material dependencies spanning high-purity silicon substrates, specialty photoresists, and noble metal sputtering targets. Single-source vulnerability around automotive-qualified packaging substrates in Japan creates structural risk for AEC-Q100 Grade 0 supply security. Distribution runs through direct OEM partnerships for high-volume automotive qualification, with broadline distributors serving industrial and aftermarket segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mixed-signal design expertise scarcity is constraining supplier expansion and amplifying acquisition premiums for analog-focused engineering teams with automotive functional safety credentials.
For Market Incumbents: Fortify analog IP moats through in-house production of silicon carbide-compatible architectures and captive qualification laboratory capacity in Jiangsu province. Lock in decade-long supply agreements with Bavarian industrial OEMs to defend against emerging domestic Chinese competitors with MIIT pre-certified reference designs. Prioritize firmware integration capabilities that collapse the boundary between sensing front-ends and host microcontrollers. For New Entrants and Emerging Players: AEC-Q100 Grade 0 fast-track certification partnerships with German TÜV laboratories offer the most viable entry path for fabless specialists targeting European commercial vehicle platforms. White-space concentration sits in refurbished monitoring electronics for second-life EV pack deployment into Indian grid-scale storage projects under the PLI scheme. Pursue wireless cell-monitoring convergence for aviation applications where harness weight reduction commands premium pricing and regulatory barriers remain lower than automotive. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified analog giants with automotive MCU adjacencies over pure-play power semiconductor houses. Long-term viability over the coming decade rests on functional safety integration depth and foundry capacity allocation priority rather than discrete product margin capture. Monitor MIIT enforcement intensity around GB/T 38661 fault-detection response mandates as the inflection signal for domestic Chinese supplier market share expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Monitoring Architecture Development | Enables sub-microsecond fault detection latency for 800V BYD and CATL platforms. |
| MIIT GB/T 38661 Pre-Certification Investment | Secures preferential access to Jiangsu and Fujian domestic battery supply chains. |
| Wireless Cell-Monitoring Convergence R&D | Eliminates isolation transformers for FAA advanced air mobility certification pathways. |
| Second-Life Battery Monitoring Module Production | Captures aftermarket volume from decommissioned EV packs in Indian grid storage. |
| Functional Safety Firmware Integration | Collapses sensing-microcontroller boundaries per ISO 26262 ASIL-D requirements. |
Study Parameters
Operator-level perspectives from battery management system architects at CATL and BYD, Tier 1 supplier procurement directors in Germany, analog IC design leads at Texas Instruments and Infineon, and Dutch battery asset operators anchored the qualitative base. Secondary validation drew from MIIT GB standard enforcement notices, ECHA REACH substance restriction updates, NHTSA battery safety guidance documents, and AEC-Q100 certification registry data. Bottom-up cell-count modeling across electric vehicle platforms triangulated against top-down semiconductor consumption estimates from specialty foundry utilization reports.
Sensitivity analysis tested forecast outputs against varying silicon carbide powertrain penetration trajectories and alternative qualification timeline scenarios across the projection horizon. Segmentation dimensions modeled include product type, application tier, technology architecture, and end-user vertical, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from installed base evolution and replacement cycle analysis, incorporating cell-passport mandate compliance deadlines and second-life battery redeployment rates as battery monitoring IC-specific forecast inputs.
Underlying assumptions cover sustained MIIT enforcement intensity, stable specialty analog foundry capacity allocation, and linear silicon carbide powertrain adoption curves, with deviation risk concentrated in multi-jurisdiction certification stacking delays and 300mm wafer supply tightness persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
United Arab Emirates Data Center Processor Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
Automotive Smart Chip Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
Global ASIC Miner Market
Chipset and Processors
Cloud AI Chipsets Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Europe Digital Signal Processor Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
Nano Chip Market