
 Mexico Data Center Processor Market | 2026-2036
Mexico Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Data Center Processor Market Insights
The widening performance gap between high-performance AI accelerators and general-purpose server processors is repositioning procurement strategies across Mexican data center operators. NVIDIA Corporation leverages its CUDA software ecosystem to dominate AI training workloads, while Intel Corporation sustains broad enterprise server commitments through x86 compatibility. Advanced Micro Devices competes aggressively on core density and thermal efficiency for cloud-native deployments.
Data center processors are integrated circuits engineered for continuous high-throughput computation, typically fabricated on sub-5nm process nodes with thermal design power ratings spanning from 75W edge chips to 500W+ AI accelerators requiring liquid cooling. These devices execute virtualization, database operations, and neural network inference across server racks. Server processors occupy the largest revenue share as legacy enterprise workloads persist, yet AI accelerators represent the fastest-expanding margin pool as Mexican banks and manufacturers deploy generative models. Edge processors are gaining traction in telco central offices where latency requirements preclude cloud backhaul.
COFETEL spectrum allocation rules and CRE electricity pricing frameworks shape facility location decisions, while NOM energy efficiency standards mandate power usage effectiveness thresholds for new constructions. The Secretariat of Economy's nearshoring incentives intersect with SEMARNAT environmental permits to channel investment toward renewable-powered campuses in Querétaro and Guanajuato. Stakeholders must weigh sovereign data residency requirements against cross-border latency constraints when selecting processor architectures for binational supply chain deployments.
Market Dynamics
The collision between sovereign data localization mandates and cross-border AI training requirements is forcing Mexican operators to architect heterogeneous compute environments that split inference and training workloads across domestic and US border facilities.
Growth Catalysts
- COFETEL spectrum reforms:Dense 5G rollouts in Mexico City and Querétaro are triggering edge processor deployments in telco central offices where sub-10ms latency is mandatory for industrial automation.
- Nearshoring manufacturing:Automotive and electronics assembly plants in Guanajuato and Nuevo León are demanding localized AI inference for quality control, pulling GPU clusters into regional data centers.
- Chihuahua-San Diego fiber corridors:Binational supply chain operators are deploying split-architecture systems that process sensitive Mexican data domestically while tapping US cloud for training.
Market Restraints
- CRE electricity pricing volatility:Industrial rate fluctuations in northern border states make 500W+ AI accelerator cooling costs unpredictable for multi-year facility planning.
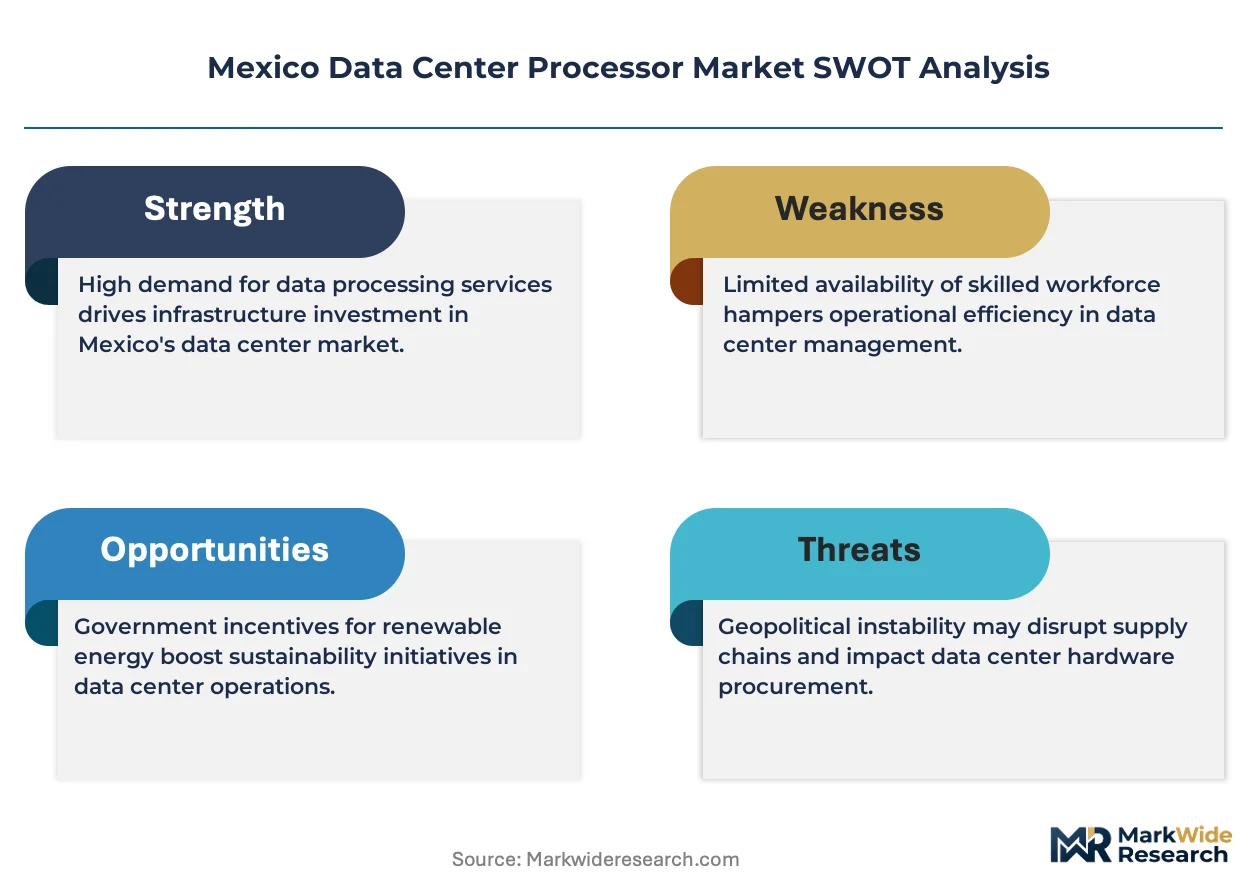
- Foundry concentration risk:Advanced node fabrication for sub-5nm processors concentrates in Taiwan and South Korea, exposing Mexican operators to single-source supply disruptions.
- NOM energy efficiency thresholds:Mandatory power usage effectiveness standards for new constructions add 12-18 months to facility commissioning timelines.
Strategic Opportunities
- Yucatán Peninsula subsea cable landings:Mérida and Cancún are emerging as latency arbitrage points for Caribbean and Central American financial services traffic.
- SEMARNAT renewable permitting fast-track:Wind and solar-powered campuses in Querétaro qualify for accelerated environmental clearance, reducing time-to-operation.
- FPGA-NPU convergence:Programmable logic paired with neural processing units is opening customization paths for Mexican fintech fraud detection workloads.
Industry Challenges
- Liquid cooling infrastructure skills gap:Installation and maintenance of direct-to-chip cooling systems for 400W+ processors requires specialized technician certification that outpaces local vocational training output.
- SEMARNAT-CRE permit sequencing complexity:Environmental and energy regulator coordination delays frequently misalign power connection timelines with processor delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Data Center Processor Market |
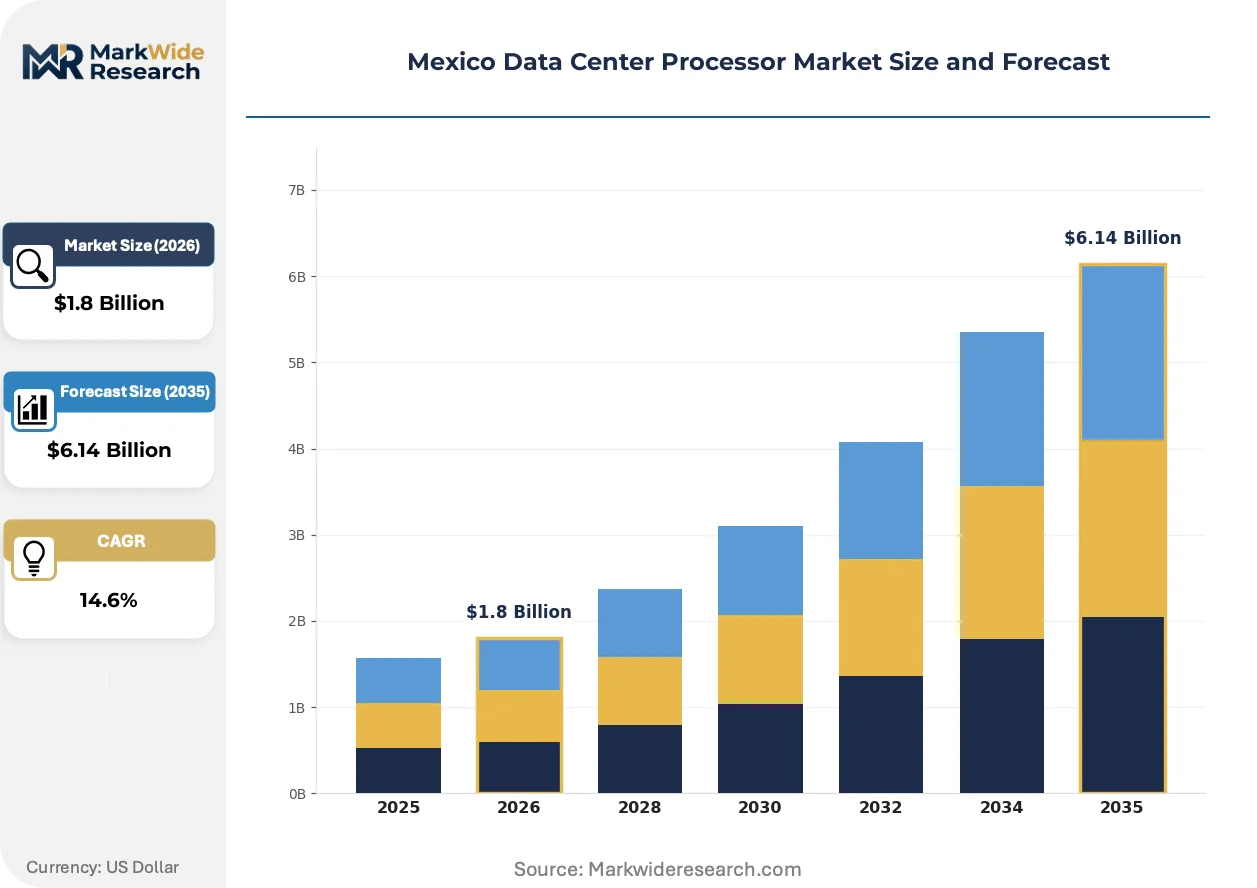
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Server Processors, Embedded Processors, AI Accelerators, Edge Processors End User: Cloud Service Providers, Telecom Operators, Enterprises, Colocation Providers Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud Power Rating: Low Power, Medium Power, High Power, Ultra-High Power |
| Companies Covered | Intel Corporation, NVIDIA Corporation, Advanced Micro Devices, Ampere Computing, Arm Holdings, IBM, Qualcomm Technologies, Samsung Electronics, NetApp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Data Center Processor Market Trends and Innovations
Compute architectures are fragmenting into workload-specific designs as Mexican operators abandon one-size-fits-all server procurement. This specialization is compressing refresh cycles and redrawing vendor relationships.
Chiplet-based processor designs are rewriting total cost of ownership calculations for Mexican cloud operators. AMD and Intel now ship modular dies that mix compute, memory, and I/O at different process nodes. Banco de México and retail payment processors are adopting these packages to right-size inference capacity without full socket replacements. The approach is compressing hardware refresh intervals from five years to thirty-six months.
NOM energy efficiency standards are mandating power usage effectiveness thresholds for all new data center constructions permitted after 2024. CRE industrial electricity rate structures now penalize facilities exceeding baseline consumption intensity. Hyperscale operators in Querétaro are responding with waste heat recovery systems that feed district heating networks, converting compliance cost into revenue streams.
Leasing arrangements are displacing capital purchases among mid-tier Mexican enterprises. Colocation providers in Monterrey and Tijuana now bundle processor access with managed AI inference services, unbundling hardware ownership from compute consumption. Manufacturing SMEs in Nuevo León are the fastest adopters, preferring opex-aligned contracts that match payment to production volume rather than fixed depreciation schedules.
Mexico Data Center Processor Market Segmentation
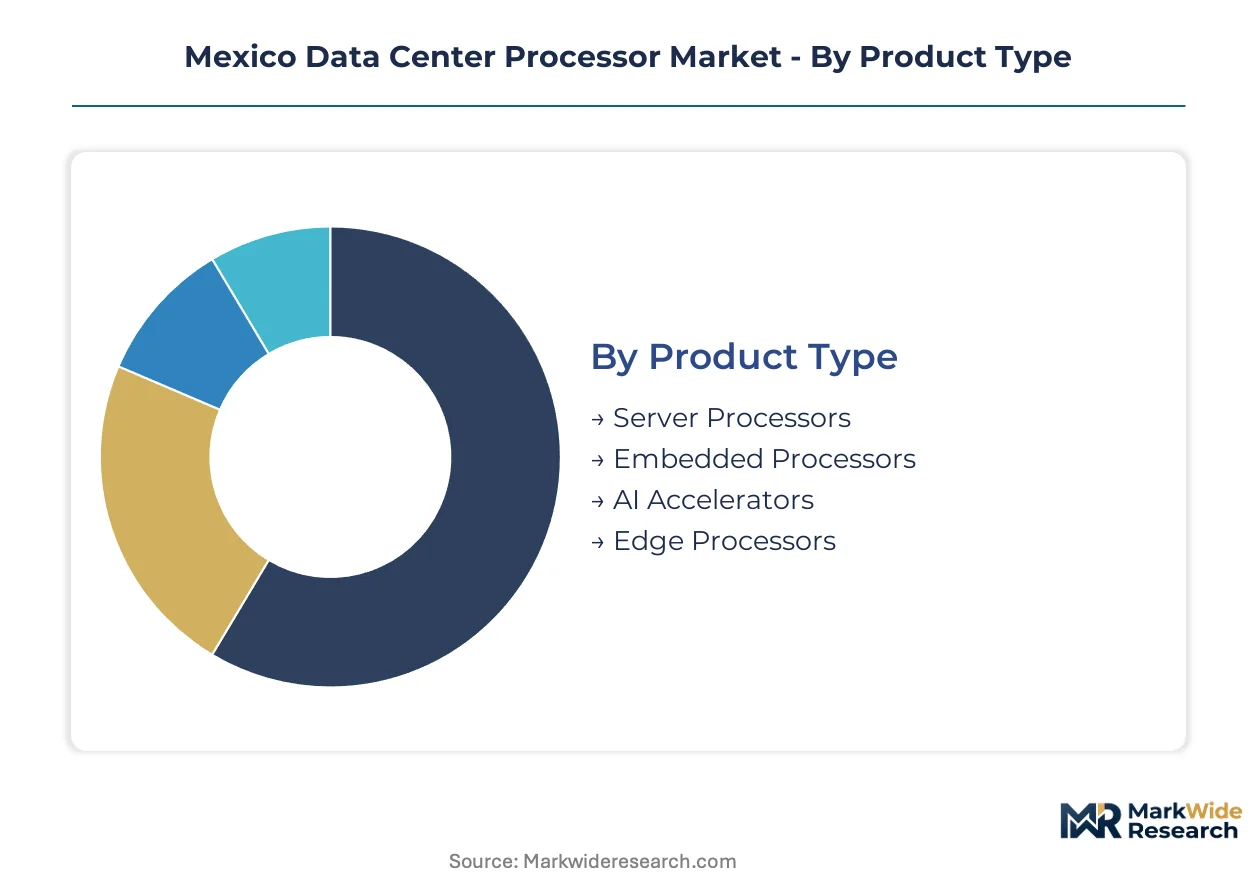
Processor procurement patterns in Mexico diverge sharply across facility types, with hyperscale cloud campuses in Querétaro demanding fundamentally different silicon than telco edge nodes in Mexico City. Segmentation reveals how workload specialization, power constraints, and data sovereignty requirements reshape vendor selection and deployment timelines across the country's emerging data center clusters.
Product Type:
Workload specialization drives divergent silicon requirements, with AI inference density and legacy virtualization compatibility pulling procurement in opposite directions.
- Server Processors:x86-based multi-core dies fabricated on 5nm and 3nm nodes execute database operations and enterprise virtualization across rack-mounted systems. Mexican banks and retail payment processors in Mexico City sustain demand for these devices as legacy ERP systems resist cloud migration.
- AI Accelerators:Tensor-optimized architectures with 500W+ thermal envelopes and HBM memory stacks train transformer models and execute inference at scale. Automotive quality-control deployments in Guanajuato and Nuevo León are pulling GPU clusters into regional facilities, accelerating procurement cycles.
- Embedded Processors:ARM-based system-on-chip designs integrate compute, networking, and security subsystems for appliance-grade servers. Industrial automation vendors in Monterrey specify these for ruggedized edge gateways.
- Edge Processors:Sub-75W devices with hardened thermal profiles operate in uncontrolled environments without mechanical cooling. COFETEL's 5G spectrum reforms are triggering deployments in telco central offices where sub-10ms latency is mandatory.
Volume sits with Server Processors; growth tilts toward AI Accelerators.
End User:
Facility ownership models determine procurement autonomy, with hyperscale operators controlling silicon selection while colocation tenants delegate hardware decisions.
- Cloud Service Providers:Hyperscale operators in Querétaro and Mexico City design custom server boards around specific processor SKUs, negotiating directly with foundries and bypassing distribution channels. Their procurement volumes justify qualification of bleeding-edge node transitions before general availability.
- Telecom Operators:Telmex and regional carriers deploy edge processors in central offices and radio access network facilities, prioritizing NEBS-compliant thermal profiles and timing synchronization for 5G fronthaul. COFETEL infrastructure mandates accelerate refresh cycles.
- Enterprises:Manufacturing conglomerates in Nuevo León and financial institutions in Mexico City maintain on-premises server rooms for compliance-sensitive workloads, favoring x86 compatibility over performance-per-watt optimization.
- Colocation Providers:KIO Networks and regional operators in Tijuana and Monterrey provision white-space power and cooling, leaving processor selection to tenant specifications. Their business model decouples facility investment from silicon procurement risk.
Cloud Service Providers command the largest procurement volumes; Telecom Operators are expanding most quickly.
Deployment Model:
Data residency requirements and latency constraints fragment compute placement, with binational supply chain operators splitting workloads across jurisdictions.
- On-Premises:Dedicated server rooms within manufacturing plants and bank headquarters house processors under direct enterprise control. Banco de México regulatory requirements and manufacturing IP protection sustain this model despite higher capital intensity.
- Hybrid Cloud:Split architectures process sensitive Mexican data domestically while tapping US cloud for training, enabled by Chihuahua-San Diego fiber corridors. This model is gaining traction among automotive suppliers with binational operations.
- Public Cloud:Shared multi-tenant facilities in Querétaro and Mexico City pool processor resources across unrelated customers. SMEs in Nuevo León prefer opex-aligned consumption without hardware ownership.
- Private Cloud:Single-tenant dedicated environments within colocation facilities isolate compute for compliance-sensitive sectors. Healthcare providers and government agencies specify these deployments.
Public Cloud captures the dominant share; Hybrid Cloud is climbing the fastest.
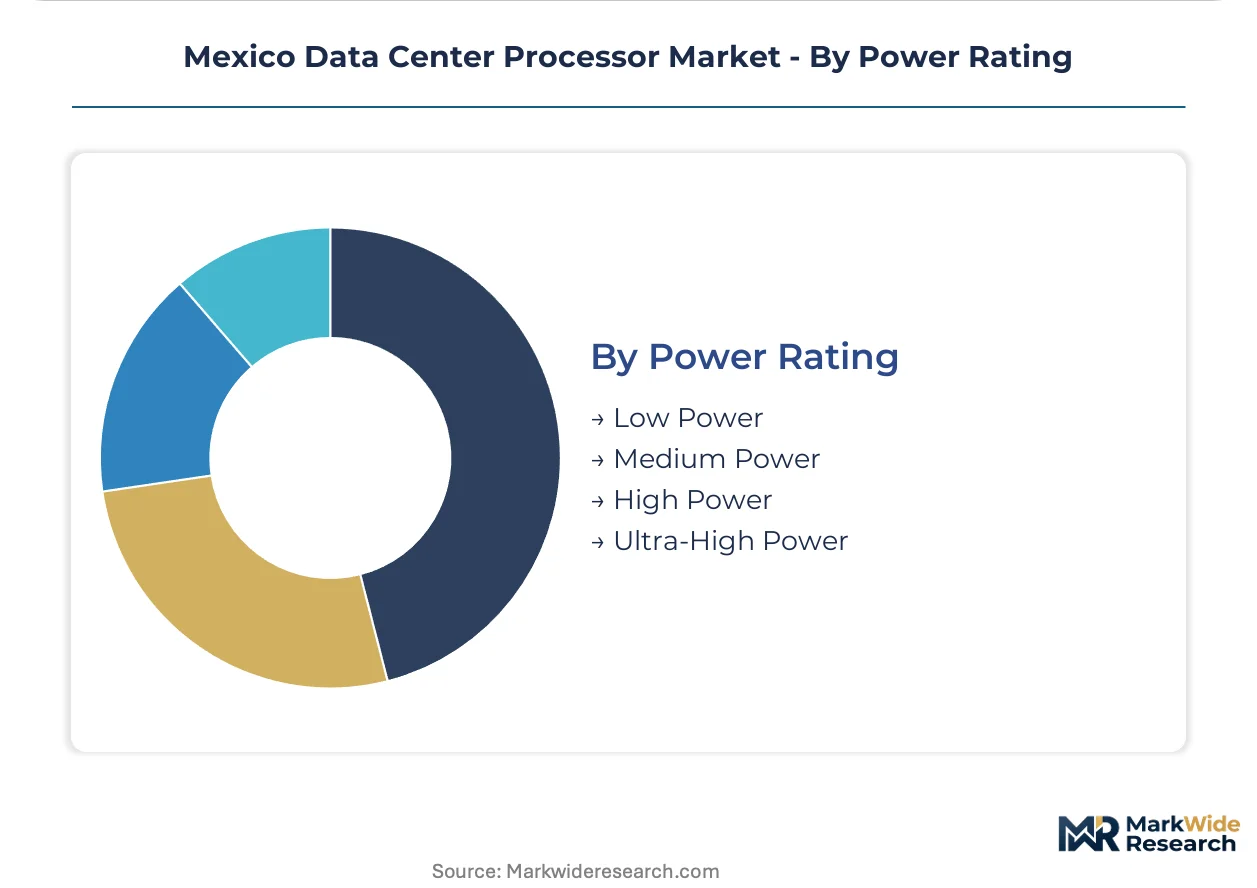
Power Rating:
Cooling infrastructure availability and electricity rate structures determine feasible thermal envelopes, with CRE pricing volatility constraining high-wattage deployments in northern border states.
- Low Power:Sub-75W processors operate in fan-cooled edge enclosures without mechanical refrigeration. Telco central offices in Mexico City and Guadalajara deploy these for 5G latency-sensitive applications.
- Medium Power:75W to 150W server processors populate standard rack configurations with aisle containment. Enterprise data rooms in Monterrey specify these for ERP and database consolidation.
- High Power:150W to 300W devices require precision air conditioning and hot-aisle containment. Cloud campuses in Querétaro deploy these for general-purpose virtualization workloads.
- Ultra-High Power:400W to 700W AI accelerators demand direct-to-chip liquid cooling and facility-level heat rejection engineering. Foundry concentration risk for sub-5nm fabrication exposes Mexican operators to supply disruptions for these SKUs.
Medium Power dominates current procurement; Ultra-High Power shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Querétaro anchors Mexico's data center processor deployment, with hyperscale campuses clustering around the Bajío region's renewable energy corridors and fiber interconnection nodes.
Bajío Region
Automotive quality-control AI and fintech fraud detection are pulling GPU clusters into Guanajuato and Querétaro facilities. SEMARNAT's renewable permitting fast-track accelerates wind and solar-powered campus commissioning. Hyperscale operators in Querétaro deploy custom server boards with direct-to-chip liquid cooling for 500W+ accelerators.
Northern Border States
Binational supply chain operators split inference and training workloads across Chihuahua-San Diego fiber corridors. CRE electricity pricing volatility constrains 400W+ AI accelerator deployments in Nuevo León and Tijuana. Manufacturing SMEs in Monterrey prefer opex-aligned colocation contracts over capital purchases.
Mexico City Metro
Legacy ERP systems at banks and retail payment processors sustain x86 server processor demand. COFETEL spectrum reforms trigger edge processor deployments in telco central offices for sub-10ms industrial automation latency. Federal data residency requirements reinforce on-premises server room commitments.
Jalisco
Guadalajara's software development ecosystem generates cloud-native workload demand for ARM-based embedded processors. State-level nearshoring incentives intersect with federal telecommunications infrastructure mandates. Industrial automation vendors specify ruggedized edge gateways for uncontrolled environment deployments.
Yucatán Peninsula
Mérida and Cancún emerge as latency arbitrage points for Caribbean and Central American financial services traffic. Subsea cable landings reduce round-trip times for cross-border payment processing. Edge processor deployments target telco central offices without mechanical cooling infrastructure.
Mexico Data Center Processor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal envelope specialization, with AI accelerator vendors commanding pricing power through CUDA ecosystem lock-in while x86-compatible suppliers compete on refresh cycle compression. The vendor base concentrates around three strategic archetypes: tensor-optimized AI specialists, modular chiplet integrators, and legacy virtualization compatibility providers. Dominant competitive moves include strategic partnerships with Mexican colocation operators and geographic expansion into Querétaro renewable energy zones.
Within the AI accelerator tier, NVIDIA Corporation and Intel Corporation anchor opposing strategic positions, with the former exemplifying software-ecosystem dominance and the latter representing x86 compatibility maintenance for enterprise workloads. Advanced Micro Devices occupies a chiplet-modularity position that right-sizes inference capacity without full socket replacements. These three fabricators collectively shape procurement timelines and qualification standards across Mexican hyperscale and enterprise deployments.
| Leading Market Players |
|---|
| Intel Corporation |
| NVIDIA Corporation |
| Advanced Micro Devices |
| Ampere Computing |
| Arm Holdings |
| IBM |
| Qualcomm Technologies |
| Samsung Electronics |
| NetApp |
| Others |
Pricing and Supply Chain Analysis
Liquid cooling technician certification gaps in Querétaro and Monterrey widen labor-cost differentials between premium AI accelerator deployments and standard server processor installations, compressing pricing-tier spreads for facilities lacking specialized maintenance capabilities.
Pricing Analysis
Value-based pricing anchored to inference throughput per watt dominates AI accelerator procurement, with Mexican cloud operators paying premiums for guaranteed uptime SLAs on 500W+ GPU clusters. Three-tier pricing structure across premium liquid-cooled, standard air-cooled, and economy refurbished tiers separates hyperscale operators from mid-tier enterprises and budget-constrained SMEs. Cost compression in the economy tier is intensifying because colocation providers bundle aging x86 servers with managed services to capture price-sensitive manufacturing clients in Nuevo León. Cloud service providers exhibit the lowest price sensitivity, while regional colocation tenants in Tijuana negotiate aggressively on per-rack power pricing.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea compound foundry concentration risk for sub-5nm EUV lithography nodes that fabricate leading-edge AI accelerators. Advanced packaging capacity in Malaysia and Vietnam supplements front-end wafer production, yet high-bandwidth memory stacks draw exclusively from SK Hynix and Samsung facilities in South Korea. Single-source vulnerability for CoWoS packaging exposes Mexican operators to allocation delays during demand surges. Distribution runs through direct foundry relationships for hyperscale operators and authorized distributors for enterprise procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NOM energy efficiency thresholds function as a cost-of-compliance barrier, with 12-18 month commissioning delays filtering out undercapitalized facility developers and preserving margin pools for operators with pre-permitted renewable power campuses.
For Market Incumbents: To counter foundry concentration risk for sub-5nm processors, secure multi-year allocation agreements with secondary packaging houses in Southeast Asia and deepen backward integration into liquid cooling infrastructure through captive technician training programs in Querétaro. For New Entrants and Emerging Players: The premium-to-economy price-point gap in edge processor deployments opens white-space opportunities in Yucatán Peninsula telco central offices, where sub-75W ARM-based designs address latency-sensitive Caribbean financial traffic without mechanical cooling infrastructure. Target Mérida and Cancún for initial beachhead contracts, leveraging SEMARNAT renewable permitting fast-tracks to compress time-to-revenue versus Bajío region competitors. For Investors and Strategic Acquirers: Re-rating potential sits with colocation operators holding pre-permitted Querétaro renewable power campuses given CRE industrial rate volatility in northern border states. Long-term viability hinges on facility-level heat rejection engineering capabilities that convert NOM compliance costs into district heating revenue streams. Monitor Chihuahua-San Diego fiber corridor utilization rates as the inflection signal for hybrid cloud architecture adoption among binational automotive suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Chip Liquid Cooling Deployment | Enables 500W+ AI accelerator hosting in Querétaro hyperscale facilities under NOM thermal thresholds. |
| Renewable Power Campus Pre-Permitting | SEMARNAT fast-track clearance compresses commissioning timelines versus standard environmental review. |
| Split-Architecture Hybrid Cloud Partnership | Chihuahua-San Diego fiber links let operators partition sovereign data residency from US training workloads. |
| Edge Processor Telco Integration | COFETEL 5G mandates drive sub-10ms latency deployments in Mexico City central offices. |
| Foundry Allocation Agreement Diversification | Secondary packaging capacity in Malaysia reduces single-source exposure for advanced node processors. |
Research Methodology
SEC 10-K filings, hyperscaler capex disclosures, and CRE electricity tariff schedules formed the secondary backbone, cross-referenced with primary interviews across data center operations directors, semiconductor procurement leads at Mexican cloud operators, COFETEL regulatory affairs specialists, and liquid cooling infrastructure contractors. Bottom-up and top-down triangulation reconciled facility-level processor deployment data with foundry shipment reports and colocation provider rack utilization metrics.
Bottom-up modeling aggregated individual facility processor procurement patterns across Querétaro, Monterrey, and Mexico City metro clusters, while top-down analysis tracked foundry wafer starts and advanced packaging capacity allocation. Segmentation dimensions spanned product type, end-user archetype, deployment model, and power rating tier across the analysis window. CAGRs derived from slope-log regression on annual facility commissioning data, with CRE rate volatility and foundry yield assumptions feeding sensitivity bands.
Underlying measurement precision varies by segment; hyperscale cloud provider procurement carries tighter precision than dispersed SME colocation contracts. Forecasts embed assumptions around NOM enforcement consistency and COFETEL spectrum allocation timelines. Material deviation in CRE industrial electricity rate structures or Taiwan Strait logistics conditions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Automotive MCU Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Global Heterogeneous Mobile Processing and Computing Market
Chipset and Processors
Quantum Processing Units (QPU) Market
Chipset and Processors
Europe Wi-Fi Chipset Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Global Automotive Self-Driving Chip Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
5G Chipset Market
Chipset and Processors
Global Merchant Embedded Computing Market
Chipset and Processors
United Kingdom Data Center Processor Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
ARM-Based Servers Market