
 Reset Integrated Circuit (IC) Market | 2026-2036
Reset Integrated Circuit (IC) Market Size, Share, and Industry Trends Forecast 2026-2036
Reset Integrated Circuit (IC) Market Analytics
Silicon carbide substrate adoption is decoupling traditional silicon-based reset IC cost structures from performance requirements in high-temperature automotive environments. Texas Instruments leverages its broad analog portfolio to sustain design-win momentum across automotive OEM toolchains. STMicroelectronics anchors European supply security through captive fab capacity in France and Italy. Infineon Technologies dominates automotive-grade supervisor segments with AEC-Q100-qualified product families.
A reset integrated circuit is a discrete semiconductor device that monitors supply voltage thresholds and generates a controlled reset signal to microprocessors or microcontrollers when voltage excursions exceed programmed tolerances, typically operating across temperature ranges from -40°C to +125°C with response times under 10 microseconds. Supervisory circuits constitute the largest product type segment due to their ubiquity in power-management subsystems, while mixed-signal technology commands premium positioning by integrating analog sensing with digital timing logic in single-die architectures. Voltage supervisors are gaining share fastest in automotive battery-management systems where functional safety requirements intensify.
REACH substance restrictions and RoHS hazardous substance directives in Europe constrain lead-frame plating chemistries and mold compound formulations, compelling suppliers to requalify materials. The EU AI Act and emerging MDR requirements for medical devices are extending traceability obligations to component-level documentation. China's GB standards and MIIT technical specifications mandate electromagnetic compatibility testing that shapes product development roadmaps. Stakeholders must monitor how evolving functional safety standards in automotive and medical verticals redefine qualification thresholds for reset IC architectures.
Market Dynamics
Silicon carbide substrate adoption is decoupling traditional silicon-based reset IC cost structures from performance requirements in high-temperature automotive environments. This material transition is reshaping supplier qualification timelines and fab capacity allocation across discrete semiconductor manufacturing.
Growth Catalysts
- AEC-Q100 Functional Safety Mandates:Automotive OEMs in Germany's Munich-Stuttgart corridor are expanding procurement of voltage supervisors for ECU reliability. Tier-1 suppliers must certify reset ICs to AEC-Q100 Grade 0 for battery-management systems.
- China's Dual Carbon Goals:GB standards and MIIT technical specifications are tightening power-efficiency benchmarks for discrete ICs. Domestic automotive electronics manufacturers face compliance deadlines that accelerate design-in cycles for low-quiescent-current supervisors.
- Medical Device Traceability:The EU AI Act and emerging MDR requirements extend documentation obligations to component-level reset architectures. Device manufacturers in Ireland and Switzerland are pre-qualifying supervisors with full material disclosure.
Market Restraints
- Silicon Carbide Wafer Cost Volatility:150mm SiC substrate pricing remains elevated versus silicon, compressing margins for automotive-grade reset ICs targeting 175°C operation. Foundry capacity for SiC epitaxy concentrates in Japan and the United States.
- REACH Substance Restrictions:ECHA regulations constrain lead-frame plating chemistries and mold compound formulations. European suppliers must requalify materials, extending NPI cycles by 8-14 months for RoHS-compliant product families.
- Integrated PMIC Substitution:System-on-chip power management units with embedded reset logic are displacing discrete supervisors in consumer electronics. Smartphone and tablet OEMs in South Korea and Taiwan are consolidating to single-chip solutions.
Strategic Opportunities
- India Automotive Electronics:PLI scheme incentives for semiconductor packaging are attracting reset IC test and assembly investments. Domestic EV manufacturers in Chennai and Pune require AEC-Q100-qualified supervisors for motor control modules.
- GaN-SiC Technology Convergence:Gallium nitride power stages operating above 1MHz require faster reset response times. Mixed-signal supervisors with sub-microsecond detection are penetrating server power-supply designs in the United States.
- EU Battery Passport Mandates:CSRD-aligned traceability requirements create pull for reset ICs with unique die identifiers. Industrial battery OEMs in the Netherlands and Sweden are specifying supervisory circuits with embedded serialization.
Industry Challenges
- Mixed-Signal Design Talent Scarcity:Analog-digital integration expertise for sub-10µs reset response is concentrated among senior designers in France, Germany, and the United States. Fabless startups face recruitment competition from integrated IDMs with captive analog teams.
- AEC-Q100 Rev-G Certification Timelines:Extended temperature cycling and ESD testing for Grade 0 qualification stretches development schedules. Automotive program managers in Stuttgart report 18-24 month validation cycles for new supervisor architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reset Integrated Circuit (IC) Market |
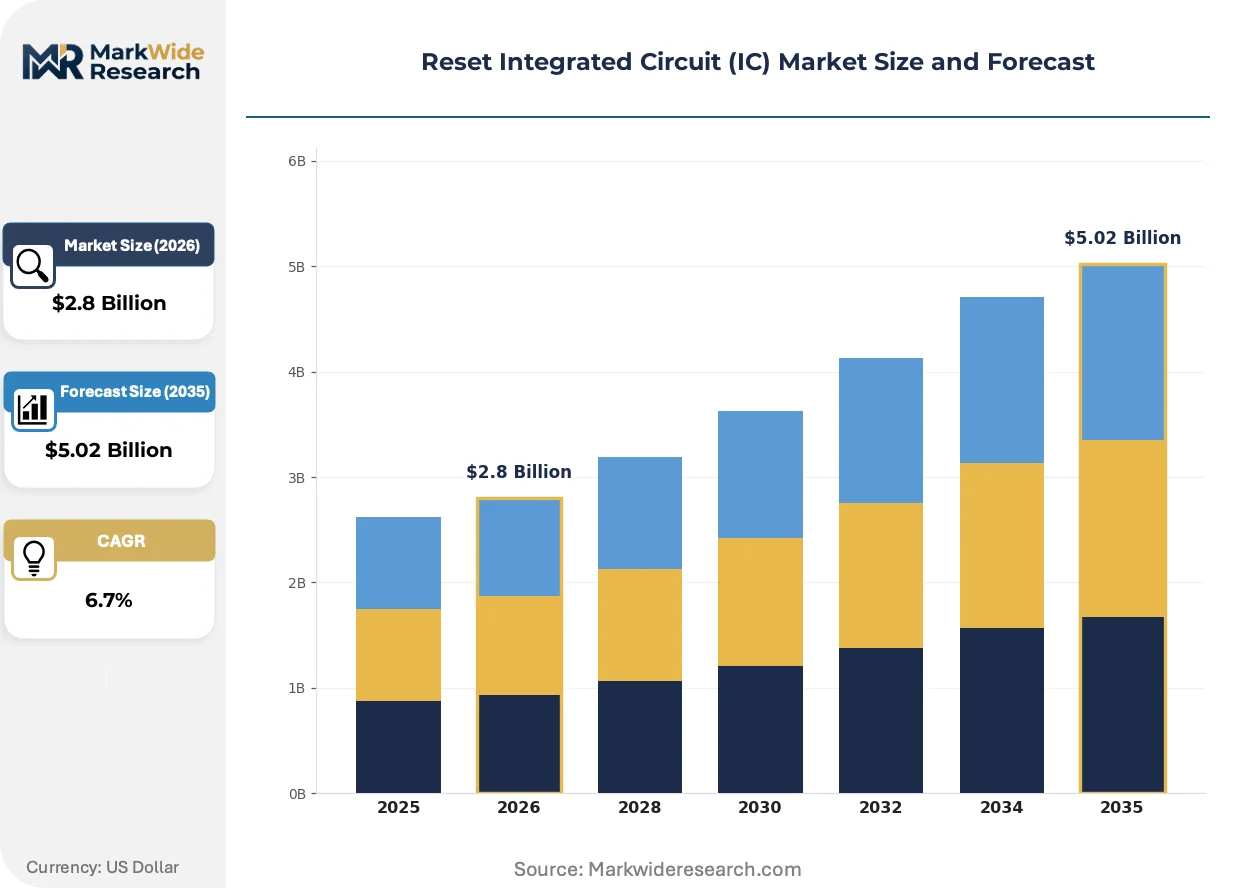
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supervisory Circuits, Voltage Supervisors, Microprocessor Supervisors, Reset Controllers Application: Consumer Electronics, Automotive Systems, Industrial Automation, Medical Devices Technology: Analog Technology, Digital Technology, Mixed-Signal Technology, CMOS Technology End User: OEMs, Contract Manufacturers, Distributors, Aftermarket Providers |
| Companies Covered | Texas Instruments, STMicroelectronics, Analog Devices, ON Semiconductor, ROHM, NXP Semiconductors, Infineon Technologies, Microchip Technology, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reset Integrated Circuit (IC) Market Evolving Landscape
Reset IC architectures are bifurcating between ultra-low-power medical designs and high-reliability automotive platforms. This divergence is forcing suppliers to maintain parallel qualification tracks while converging on common process technologies.
Silicon carbide-based voltage supervisors are converging with wide-bandgap power stages in electric vehicle traction inverters. Tier-1 automotive suppliers in Germany are adopting SiC reset ICs for 800V battery systems operating at junction temperatures exceeding 150°C. This convergence is compressing the traditional thermal derating margin that separated supervisor selection from power semiconductor ratings.
REACH substance restrictions and RoHS hazardous substance directives in Europe are constraining lead-frame plating chemistries and mold compound formulations. Suppliers must requalify materials under ECHA oversight, compelling reformulation of high-temperature mold compounds. Medical device manufacturers in Ireland and Switzerland are accelerating pre-qualification of reset ICs with full material disclosure to meet MDR traceability obligations.
Automotive system integrators are consolidating supplier relationships around analog portfolios with captive fab capacity. Procurement teams at German OEMs are reducing qualified vendor lists from twelve to four suppliers, favoring those with in-house 180nm BCD processes. This concentration is most visible in battery-management system designs, where functional safety requirements intensify scrutiny of second-source availability.
Reset Integrated Circuit (IC) Market Segmentation
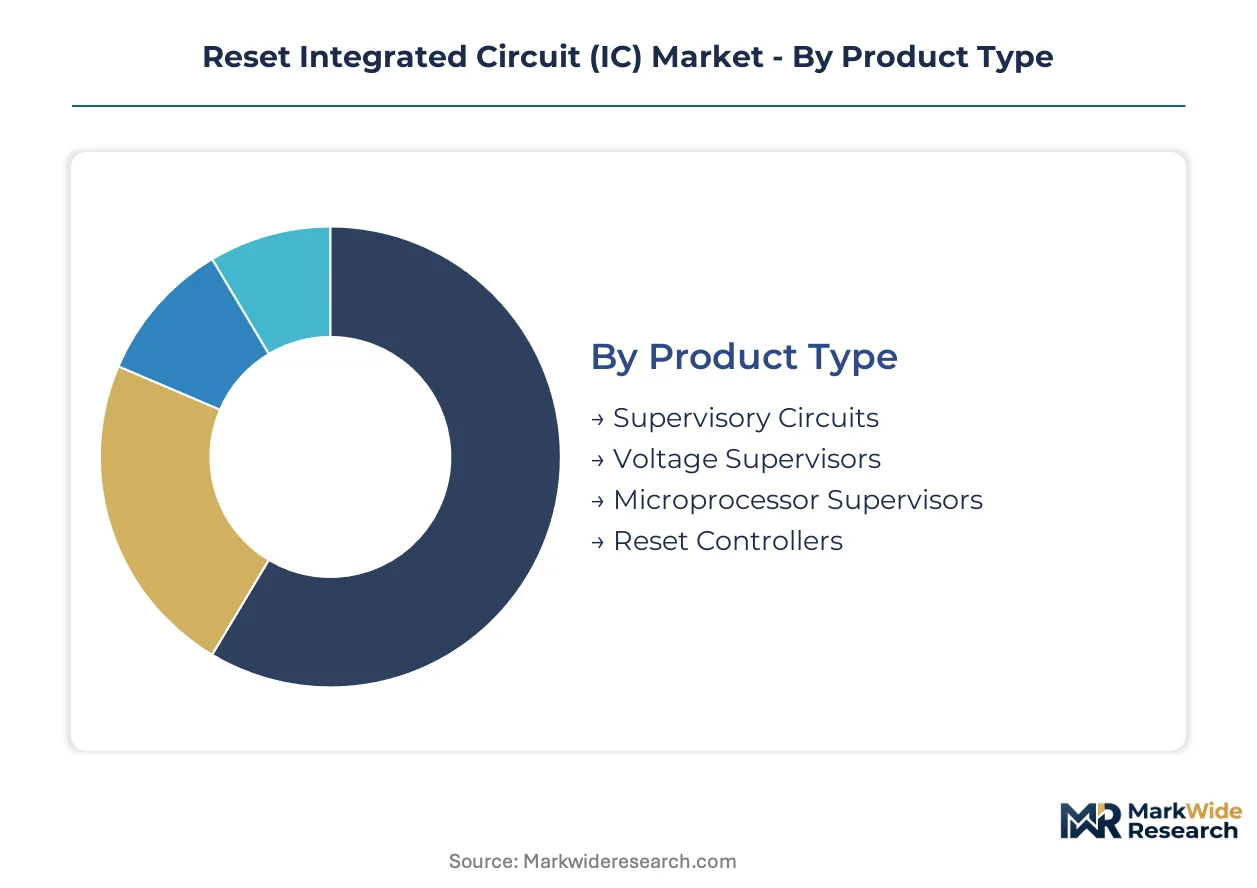
Reset IC architectures diverge sharply between cost-optimized consumer implementations and safety-critical automotive platforms. Procurement teams evaluate segments through distinct qualification lenses—functional safety certification versus bill-of-material compression.
Product Type:
Volume concentration favors standardized supervisory circuits, while premium positioning clusters around mixed-signal integration with sub-microsecond response specifications.
- Supervisory Circuits:These devices monitor multiple voltage rails through integrated comparators and reference generators, forming the backbone of power-management subsystems in consumer electronics. Demand concentrates in South Korean smartphone OEMs consolidating to single-chip power solutions with embedded reset logic.
- Voltage Supervisors:Dedicated threshold-detection circuits operating across -40°C to +175°C temperature ranges with programmable hysteresis. German automotive electronics clusters around Munich and Stuttgart are expanding procurement for battery-management systems requiring AEC-Q100 Grade 0 qualification.
- Microprocessor Supervisors:Compact watchdog-enabled devices with manual reset inputs for microcontroller-based designs.
- Reset Controllers:Configurable multi-rail sequencing circuits for complex SoC power-up requirements.
Mature deployment sits with Supervisory Circuits. Newer deployment is concentrated in Voltage Supervisors.
Application:
Automotive functional safety mandates are reshaping segment economics, while consumer electronics procurement shifts toward integrated PMIC substitution.
- Automotive Systems:Battery-management modules, ECU power sequencing, and motor control supervisors operating under ISO 26262 functional safety requirements. Tier-1 suppliers in Germany's Stuttgart corridor face 18-24 month AEC-Q100 Rev-G validation cycles for Grade 0 architectures.
- Industrial Automation:Programmable logic controller power supplies and factory automation controllers requiring extended temperature operation. European machinery OEMs in the Netherlands and Sweden are specifying reset ICs with embedded die serialization for EU Battery Passport traceability.
- Consumer Electronics:Smartphone, tablet, and wearable power-management integration.
- Medical Devices:Implantable and diagnostic equipment requiring MDR-aligned material disclosure.
Industrial Automation captures the steepest expansion trajectory as CSRD-aligned traceability mandates penetrate component specifications.
Technology:
Process node differentiation separates commodity analog implementations from digitally-enhanced architectures commanding design-win premiums.
- Mixed-Signal Technology:Single-die integration of analog sensing front-ends with digital timing and programmable logic, enabling sub-microsecond reset response. Server power-supply designers in the United States are adopting these architectures for GaN power stages operating above 1MHz switching frequencies.
- CMOS Technology:Scalable low-power implementations leveraging standard logic processes for consumer electronics integration.
- Analog Technology:Discrete comparator-based threshold detection with minimal quiescent current.
- Digital Technology:Firmware-configurable reset sequencing with I2C/SPI programmability.
Analog Technology dominates legacy installations. Mixed-Signal Technology is gaining share fastest in automotive and data center power architectures.
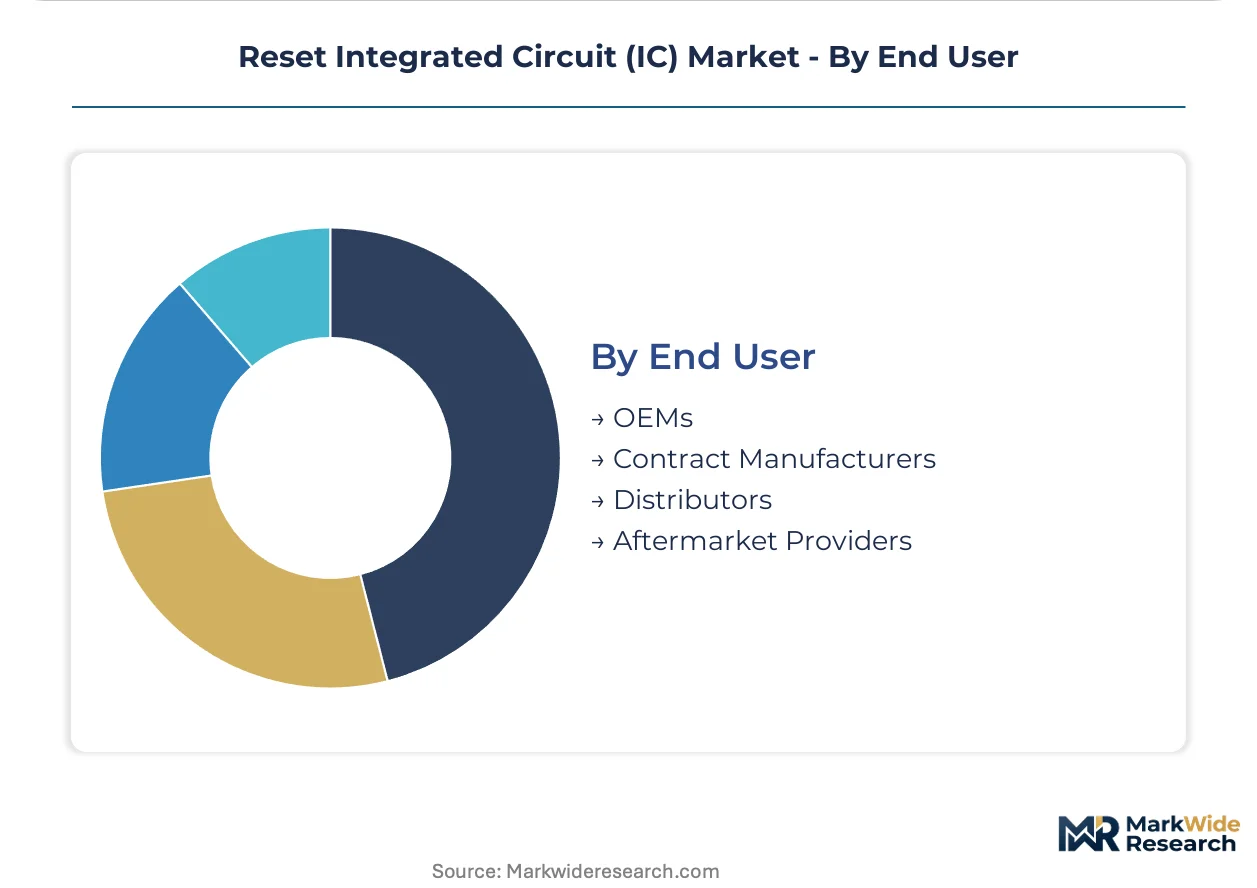
End User:
Supply chain configuration separates captive procurement by integrated OEMs from fragmented distributor channels serving mid-volume manufacturers.
- OEMs:Direct qualification relationships with automotive and medical device manufacturers requiring full material documentation. German OEM procurement teams are consolidating qualified vendor lists from twelve to four suppliers, favoring those with captive 180nm BCD fab capacity.
- Contract Manufacturers:Electronics manufacturing services providers managing component sourcing for mid-tier industrial and consumer brands.
- Distributors:Arrow, Avnet, and regional catalog houses stocking standard-grade supervisors with 8-14 week lead times.
- Aftermarket Providers:Repair and refurbishment channels for legacy industrial equipment.
Aftermarket Providers serve installed base maintenance. OEMs are concentrating design-in authority through reduced vendor lists and captive fab preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electronics clusters in Germany's Munich-Stuttgart corridor concentrate procurement of AEC-Q100-qualified voltage supervisors, while China's dual carbon compliance deadlines and India's PLI packaging incentives reshape discrete IC demand geography.
Germany
Tier-1 automotive suppliers source battery-management supervisors for 800V traction systems. KBA vehicle-type approval regulations enforce functional safety documentation for ECU power-sequencing components. Stuttgart-based procurement teams consolidate qualified vendor lists from twelve to four suppliers with captive BCD fab capacity.
China
Domestic EV manufacturers accelerate design-in cycles for low-quiescent-current supervisors in motor control modules. MIIT technical specifications and GB standards mandate electromagnetic compatibility testing with tightening power-efficiency benchmarks. Yangtze River Delta automotive electronics hubs face dual carbon goal compliance deadlines through 2025.
United States
Server power-supply designers adopt mixed-signal supervisors with sub-microsecond response for GaN stages above 1MHz switching. FCC Part 15 emissions standards shape electromagnetic compatibility product roadmaps. Silicon Valley fabless startups compete with integrated IDMs for analog-digital integration talent.
India
Chennai and Pune EV manufacturers require AEC-Q100-qualified supervisors for motor control modules. PLI scheme incentives for semiconductor packaging attract reset IC test and assembly investments. BIS certification timelines compress as domestic automotive electronics procurement expands.
Japan
Foundry capacity for SiC epitaxy concentrates among substrate suppliers serving 175°C automotive-grade reset ICs. METI technology roadmaps support wide-bandgap power stage integration. Kyushu-based manufacturing clusters anchor high-temperature supervisor qualification programs.
Reset Integrated Circuit (IC) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device manufacturers commanding automotive-grade qualification authority while fabless competitors serve consumer electronics substitution. Supplier consolidation concentrates design-win momentum around analog portfolios with captive fab capacity. Three archetypes dominate: vertically integrated semiconductor conglomerates with BCD processes, analog specialists with medical-grade material disclosure programs, and diversified electronics component houses with broad distribution reach. M&A activity targets mixed-signal design teams, while capacity expansion focuses on 180nm BCD fab utilization.
Among diversified analog semiconductor conglomerates, Texas Instruments, STMicroelectronics, and Infineon Technologies exemplify the integrated-model archetype. Texas Instruments leverages its broad analog portfolio across automotive OEM toolchains. STMicroelectronics anchors European supply security through captive fab capacity in France and Italy. Infineon Technologies occupies a dominant position in automotive-grade supervisor segments with AEC-Q100-qualified product families.
| Leading Market Players |
|---|
| Texas Instruments |
| STMicroelectronics |
| Analog Devices |
| ON Semiconductor |
| ROHM |
| NXP Semiconductors |
| Infineon Technologies |
| Microchip Technology |
| Renesas Electronics |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap analog specialists in France and Germany anchor supply security through captive 180nm BCD fab capacity, compressing pricing power for fabless competitors while sustaining premium positioning for AEC-Q100-qualified architectures.
Pricing Analysis
Volume-massive supervisory circuits for consumer electronics trade at compressed margins, while mixed-signal automotive supervisors with sub-microsecond response command substantial premiums. Pricing stratifies across AEC-Q100 Grade 0, Grade 1, and industrial-grade tiers, with certification level and captive fab ownership driving price differentiation. Cost compression in standard-grade CMOS implementations is intensifying because integrated PMIC substitution erodes discrete supervisor demand. Smartphone OEMs in South Korea exhibit highest price sensitivity, whereas German automotive procurement teams prioritize qualification reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with 150mm SiC epitaxy capacity concentrated in Japan and the United States, constraining high-temperature automotive-grade reset IC availability. Raw material dependencies include silicon carbide substrates, high-purity copper lead frames, and halogen-free mold compounds. Tariff exposure on semiconductor equipment imports threatens fab expansion timelines. Distribution runs through Arrow and Avnet for standard-grade products, while automotive OEMs engage direct qualification relationships with integrated IDMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reset IC market sits in a technology-transition phase as silicon carbide substrates displace legacy silicon implementations for 175°C automotive environments.
For Market Incumbents: Lock in automotive design-win momentum by expanding captive 180nm BCD fab utilization in France and Italy. Prioritize AEC-Q100 Rev-G Grade 0 certification investment to defend against GaN-SiC convergence threats in 800V traction systems. Consolidate qualified vendor list relationships with Stuttgart-based Tier-1 suppliers before fabless entrants secure mixed-signal talent. For New Entrants and Emerging Players: Enter via India's PLI-packaging incentives for semiconductor test and assembly, targeting Chennai and Pune EV manufacturers requiring AEC-Q100-qualified motor control supervisors. White-space exists in medical-grade material disclosure programs for Irish and Swiss device manufacturers facing MDR traceability mandates. Pursue foundry partnerships with BCD-capable fabs rather than greenfield capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor analog specialists with captive fab capacity in Europe and established medical-grade disclosure programs. Long-term viability hinges on functional safety certification depth rather than commodity consumer exposure. Watch SiC epitaxy utilization rates as inflection indicator for high-temperature automotive-grade supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Grade 0 Certification Investment | Qualification to Grade 0 unlocks 800V battery-management procurement at German OEMs. |
| SiC Epitaxy Capacity Expansion | Captive SiC substrate supply insulates margins from Japan-US foundry concentration. |
| Medical-Grade Material Disclosure Program | Full material documentation meets MDR traceability for Swiss implantable device manufacturers. |
| GaN-SiC Mixed-Signal Supervisor Development | Sub-microsecond response architectures penetrate server power designs with 1MHz GaN stages. |
| India PLI Packaging Investment | Test and assembly incentives attract reset IC investments serving domestic EV motor control. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving analog design directors, automotive Tier-1 procurement managers, semiconductor fab operations heads, and medical device regulatory affairs leads. SEC 10-K disclosures, ECHA substance restriction updates, MIIT technical specifications, and AEC component qualification databases provided demand-side validation. Bottom-up unit shipment modeling and top-down value triangulation converged on segment-level estimates.
Data-stream reconciliation across product type, application vertical, technology node, and end-user channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted adoption curves for SiC-based architectures and integrated PMIC substitution rates. Forecast inputs included AEC-Q100 qualification pipeline visibility, foundry capacity allocation announcements, and automotive platform electrification roadmaps.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SiC substrate supply disruption or accelerated integrated PMIC displacement in consumer electronics. Automotive functional safety standard revisions and REACH substance restriction expansions could revise qualification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Motor Driver IC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
CMOS Power Amplifier Market
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Taiwan Integrated Circuits Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Mixed Signal IC Market