
 RFID Reader IC Market | 2026-2036
RFID Reader IC Market Size, Share, and Industry Trends Forecast 2026-2036
RFID Reader IC Market Insights
Multi-protocol bundling into single-die configurations is consolidating buyer preference away from discrete component sourcing. NXP Semiconductors leverages its UHF portfolio to anchor European automotive RFID programs. Impinj competes through RAIN RFID endpoint scalability in retail environments. Texas Instruments sustains dominance in integrated reader front-ends for industrial automation.
An RFID Reader IC is a monolithic semiconductor device integrating a radio-frequency front-end, baseband processor, and digital interface to execute tag interrogation, signal demodulation, and protocol handshake at frequencies spanning LF to UHF bands; it enables automated identification without line-of-sight requirements. Passive RFID commands the largest volume share due to minimal tag cost and battery-free operation, while Battery-Assisted Passive RFID captures expanding margin pools in cold-chain pharmaceutical tracking. Supply Chain Management applications exhibit the steepest growth trajectory as enterprises embed item-level traceability from factory floor to last-mile delivery.
FCC Part 15 rules in the United States, ETSI EN 302 208 in Europe, and MIIT radio regulations in China define transmit power, spectrum allocation, and spurious emission limits that directly constrain reader IC architecture and antenna design. ISO 18000-63 and EPCglobal Gen2 standards further harmonize air-interface protocols, reducing regional SKU fragmentation for chip vendors. Stakeholders must monitor evolving national spectrum reallocations and interoperability mandates to align R&D roadmaps with certification timelines.
Market Dynamics
Protocol convergence toward RAIN RFID and EPCglobal Gen2 standards is compressing SKU diversity and forcing chip vendors to consolidate multi-frequency capability into single-die architectures.
Growth Catalysts
- Retail inventory automation:Merchants deploy item-level tagging to eliminate stockouts and shrinkage, with checkout-free stores requiring dense reader networks.
- MIIT spectrum harmonization:China's radio regulations now align UHF band plans with international norms, reducing certification overhead for module suppliers.
- Cold-chain pharmaceutical mandates:Temperature-sensitive biologics drive Battery-Assisted Passive RFID adoption for continuous environmental monitoring.
Market Restraints
- Silicon foundry concentration:Advanced mixed-signal fabrication for UHF front-ends depends on Taiwan-based capacity, exposing supply to geopolitical friction.
- ETSI power restrictions:European effective isotropic radiated power limits constrain read range, forcing antenna array complexity that elevates system cost.
- Barcode substitution:Two-dimensional symbologies retain cost advantage in low-value consumer goods, capping RFID penetration in price-sensitive segments.
Strategic Opportunities
- India logistics modernization:The country's PLI scheme for electronics manufacturing incentivizes domestic reader module assembly for warehousing networks.
- Automotive tire pressure integration:UHF RFID tags embedded during tire production enable lifecycle tracking from factory to retreading facilities.
- EU Digital Product Passport:The regulation mandates item-level traceability for textiles and batteries, creating mandated demand for embedded interrogation chips.
Industry Challenges
- RF engineering talent scarcity:Mixed-signal design expertise spanning microwave circuits and digital baseband processing concentrates in aging workforces.
- Multi-protocol certification backlog:Simultaneous FCC Part 15, ETSI EN 302 208, and regional variant testing extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFID Reader IC Market |
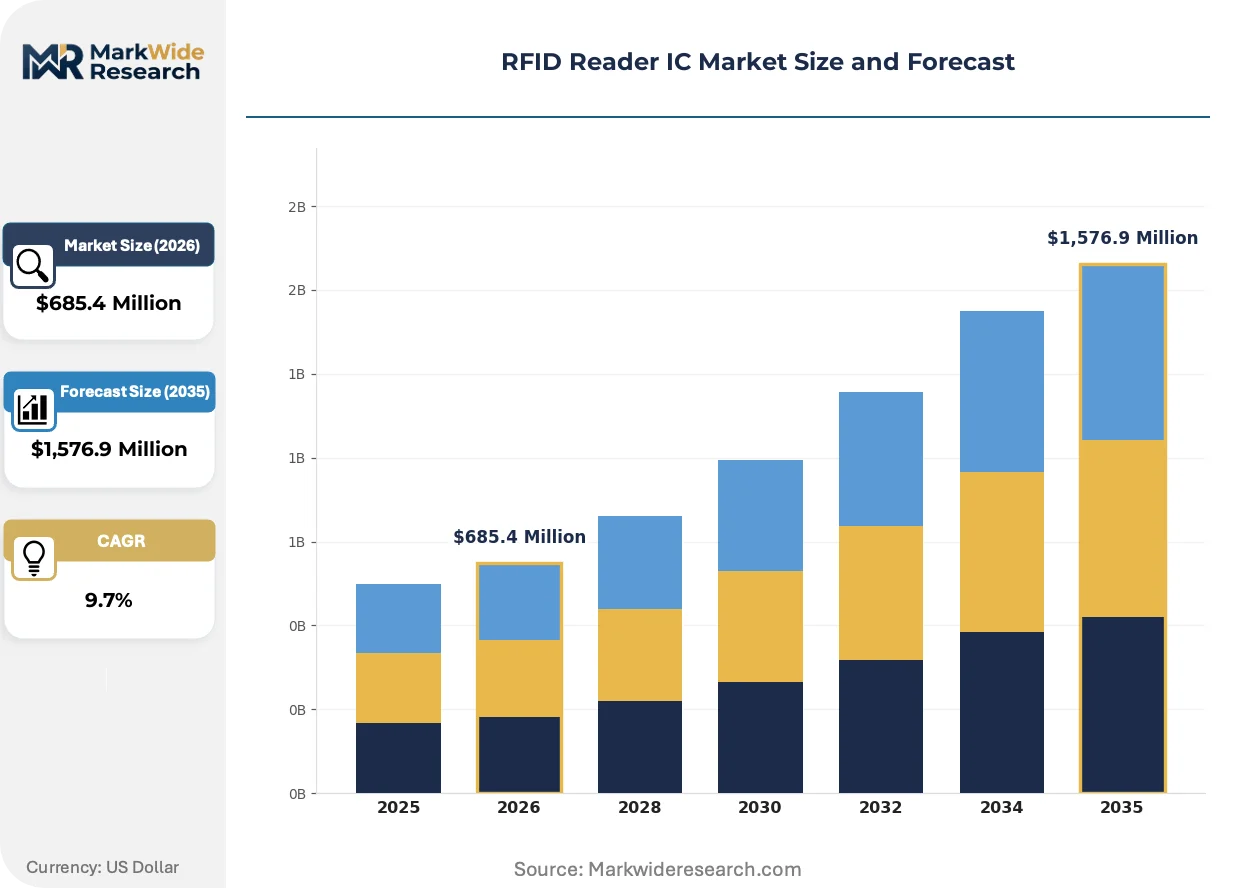
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active RFID, Passive RFID, Semi-Passive RFID, Battery-Assisted Passive RFID End User: Retail, Healthcare, Manufacturing, Transportation Technology: Frequency Modulation, Amplitude Modulation, Phase Modulation, Time Division Multiplexing Application: Inventory Management, Asset Tracking, Access Control, Supply Chain Management |
| Companies Covered | Alien Technology, Balluff, NXP Semiconductors, CAEN RFID, GAO RFID, Impinj, FEIG ELECTRONIC, Zebra Technologies, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFID Reader IC Market Trends and Innovations
Reader IC architectures are pivoting from discrete component stacks toward highly integrated system-in-package designs that embed antenna matching networks and power management.
Single-chip UHF readers with integrated power amplifiers are expanding into industrial automation gateways, where Siemens and Bosch deploy them for real-time production tracking. This integration eliminates external RF front-end modules, compressing bill-of-materials cost and board area for original equipment manufacturers.
REACH substance restrictions on halogenated flame retardants are forcing substrate material substitutions in reader module laminates. European automotive suppliers now specify halogen-free PCBs for under-hood RFID interrogators, with compliance documentation becoming a procurement gate.
Buyer consolidation among large-scale retail systems integrators is concentrating procurement leverage. Walmart's supplier mandates for source-tagging have compressed vendor qualification cycles, while tier-two logistics providers face extended payment terms and technical support obligations.
RFID Reader IC Market Segmentation
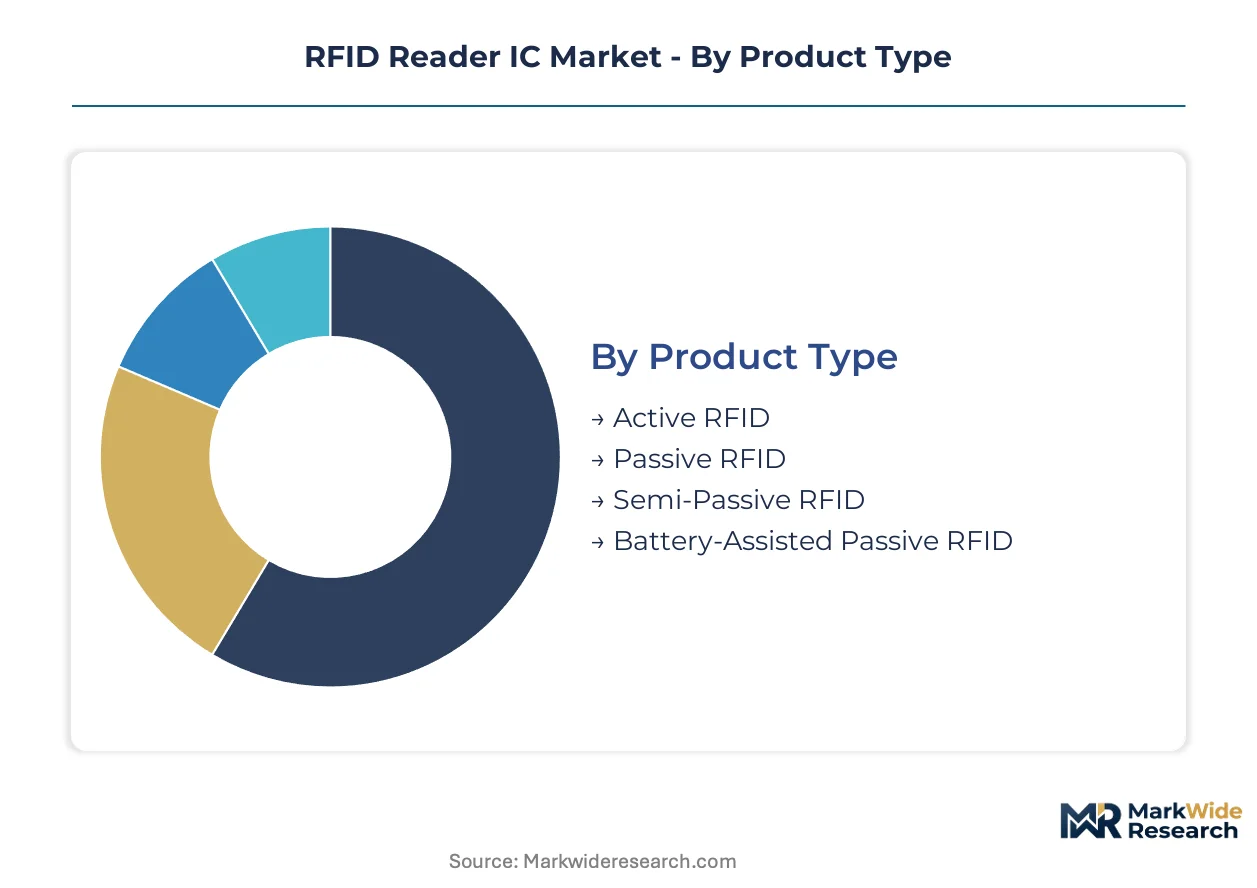
RFID Reader IC segmentation reveals divergent capital requirements across power architectures and signal processing methods. Procurement patterns cluster around passive UHF solutions for high-volume logistics, while battery-assisted variants command premium positioning in regulated cold-chain environments.
Product Type:
Passive RFID demands minimal silicon area and omits power management blocks, lowering mask costs and qualification overhead. Active RFID and Battery-Assisted Passive variants integrate energy storage interfaces and precision voltage references, ballooning NRE expenditure.
- Passive RFID:Monolithic designs harvest interrogation energy through rectenna structures, eliminating external power sources. Retail inventory systems in Shenzhen and Rotterdam deploy these chips at massive scale for item-level tagging, constrained only by read range in metal-dense environments.
- Battery-Assisted Passive RFID:Incorporates thin-film cells to sustain sensor logging during transit gaps. Pharmaceutical distributors in Germany and California specify these for temperature-sensitive biologics, where continuous monitoring overrides unit cost sensitivity.
- Active RFID:Carries onboard power for beacon-style transmission. Industrial yard management in Texas oilfields leverages this for real-time equipment positioning across sprawling facilities.
- Semi-Passive RFID:Hybrid architecture powering sensor circuits while relying on backscatter for communication. Cold-chain operators in Maharashtra pilot these for perishable agricultural exports.
Passive RFID absorbs the bulk of installed capacity; Battery-Assisted Passive RFID is expanding most quickly.
End User:
Manufacturing verticals prioritize reader density and sub-millisecond latency, while healthcare procurement scrutinizes FDA and EMA validation documentation. Retail buyers dominate unit volume but compress margins through consolidated tender processes.
- Manufacturing:Production lines demand multi-reader synchronization for work-in-progress tracking. Automotive plants in Stuttgart and Chennai embed interrogators at each assembly station, with chips hardened against welding electromagnetic interference.
- Retail:Checkout-free stores require dense reader meshing with collision-avoidance protocols. Merchant mandates from Bentonville, Arkansas have accelerated source-tagging adoption across apparel suppliers.
- Healthcare:Sterilization-resistant tags track surgical instrument lifecycles. Hospitals in Singapore and São Paulo deploy these to eliminate retained foreign object incidents.
- Transportation:Toll collection and fleet yard automation drive ruggedized reader specifications. Brazilian highway operators specify these for all-weather lane throughput.
Manufacturing commands the deepest reader penetration per facility; Retail is climbing the fastest on absolute unit shipments.
Technology:
Modulation schemes trade spectral efficiency against baseband complexity, with Phase Modulation demanding precision PLL architectures that consume additional die area. Frequency Modulation dominates where legacy infrastructure compatibility outweighs throughput optimization.
- Phase Modulation:Quadrature demodulation enables superior tag discrimination in dense reader zones. High-throughput distribution centers in the Netherlands deploy these for pallet-level bulk reading.
- Frequency Modulation:Simpler discriminator circuits reduce silicon cost. Legacy warehouse retrofits in Illinois and Ohio favor this for forklift-mounted readers.
- Amplitude Modulation:Envelope detection minimizes power draw. Battery-operated handheld units in Japanese retail audits specify this for extended field operation.
- Time Division Multiplexing:Synchronized slot allocation prevents reader-to-reader interference. Dense urban toll plazas in Seoul implement these for multi-lane concurrent processing.
Phase Modulation captures the highest-value design-ins; Frequency Modulation retains the broadest installed base.
Application:
Supply chain deployments span the longest physical footprints, mandating multi-protocol readers that bridge LF, HF, and UHF domains. Access control concentrates in shorter-range HF implementations with cryptographic authentication requirements.
- Supply Chain Management:End-to-end traceability from factory to last-mile delivery. Electronics assemblers in Dongguan and Guadalajara embed these for component provenance verification.
- Inventory Management:Real-time stock visibility with automated replenishment triggers. Apparel merchants in London and New York deploy ceiling-mounted reader arrays for continuous cycle counting.
- Asset Tracking:Lifecycle monitoring of high-value mobile equipment. Construction firms in Dubai tag heavy machinery for theft recovery and maintenance scheduling.
- Access Control:Secure perimeter management with mutual authentication. Corporate campuses in Bangalore and Munich specify these for contactless badge systems.
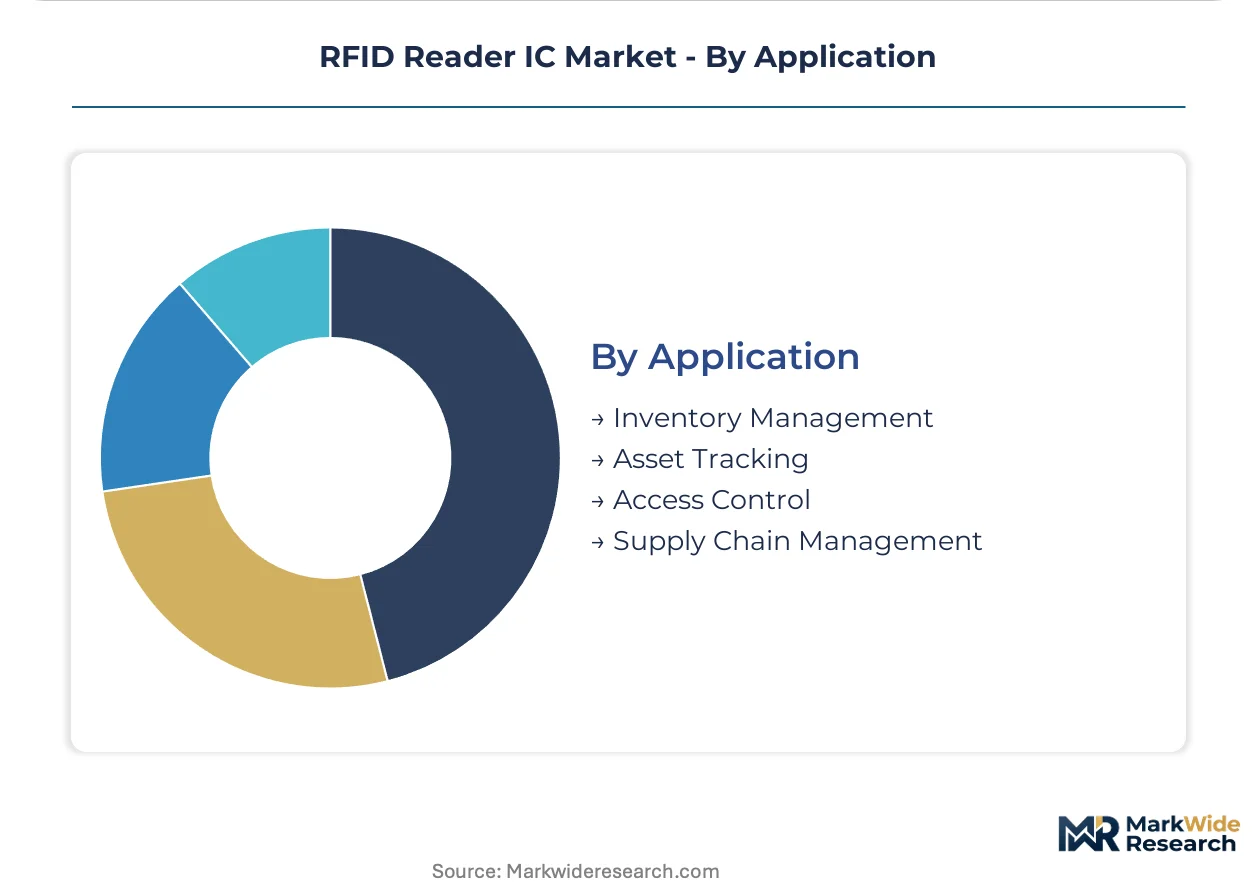
Supply Chain Management spans the widest geographic deployment; Inventory Management is gaining share fastest in reader IC procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates fabrication capacity for UHF reader front-ends, while the United States and Germany absorb the highest-value design-ins for automotive and industrial automation. Demand fragmentation across Shenzhen module houses, Texas oilfield operators, and Stuttgart assembly plants shapes divergent procurement specifications.
United States
Retail checkout automation and oilfield asset tracking drive reader IC procurement from Walmart supplier mandates and Permian Basin operators. FCC Part 15 rules govern transmit power and spurious emissions, compressing read-range specifications for dense urban deployments. Dallas-Fort Worth hosts Texas Instruments' integrated front-end operations for industrial automation gateways.
China
Shenzhen-based module houses feed domestic logistics networks and smart manufacturing lines with high-volume passive UHF chips. MIIT radio regulations now align UHF band plans with international norms, reducing certification overhead for export-oriented suppliers. Dongguan electronics assemblers embed multi-protocol readers for component provenance verification across export supply chains.
Germany
Automotive tire pressure integration and pharmaceutical cold-chain mandates propel Battery-Assisted Passive RFID adoption. ETSI EN 302 208 power restrictions constrain effective isotropic radiated power, forcing antenna array complexity at Stuttgart and Munich assembly plants. REACH substance restrictions on halogenated flame retardants now govern substrate materials for under-hood interrogators.
India
Warehousing modernization and agricultural export traceability pilot programs expand addressable demand for reader modules. The PLI scheme for electronics manufacturing incentivizes domestic module assembly for logistics networks in Maharashtra and Karnataka. Mumbai pharmaceutical distributors specify semi-passive variants for perishable cold-chain exports to European markets.
Netherlands
High-throughput distribution centers deploy phase-modulation readers for pallet-level bulk reading at Rotterdam port facilities. EMA validation requirements for pharmaceutical traceability elevate documentation burdens for reader IC procurement. Eindhoven-based systems integrators concentrate RAIN RFID deployment expertise for European retail automation projects.
RFID Reader IC Market Competitive Landscape
The competitive structure tilts toward integrated semiconductor vendors with captive mixed-signal fabrication capacity. Discrete module assemblers face margin compression as single-die architectures eliminate external RF front-end components. Two archetypes dominate: diversified analog/mixed-signal giants with broad industrial portfolios, and RFID specialists betting endpoint scalability. Competitive moves cluster around multi-protocol certification acceleration and foundry partnerships to secure Taiwan-based capacity.
Among diversified analog suppliers, NXP Semiconductors and Texas Instruments anchor the premium tier through integrated front-end dominance in automotive and industrial verticals. Impinj occupies a specialist position exemplifying RAIN RFID endpoint scalability archetypes. CAEN RFID and FEIG ELECTRONIC represent European mid-tier module integration specialists serving regional certification requirements.
| Leading Market Players |
|---|
| Alien Technology |
| Balluff |
| NXP Semiconductors |
| CAEN RFID |
| GAO RFID |
| Impinj |
| FEIG ELECTRONIC |
| Zebra Technologies |
| Texas Instruments |
| Others |
Pricing and Supply Chain Analysis
Mixed-signal RF engineering talent concentration in Taiwan and Germany widens pricing-tier spreads between commodity passive UHF chips and premium multi-protocol architectures. Labor-cost differentials between Dresden design houses and Shenzhen module assemblers compress margins at the economy tier while sustaining premium pricing for automotive-qualified die.
Pricing Analysis
Margin tightening in economy-tier passive UHF chips reflects foundry capacity competition from consumer wireless devices. Three-tier pricing structure across automotive-grade, industrial-certified, and commercial-off-the-shelf levels separates ETSI-validated designs from FCC-only variants. Price differentiation traces to certification breadth and antenna matching complexity. Logistics operators in price-sensitive emerging markets drive volume procurement of uncalibrated modules, while pharmaceutical cold-chain mandates sustain premium tier resilience.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific semiconductor hubs elevates landed costs for European and North American module integrators. Advanced mixed-signal fabrication draws from Taiwan, with back-end testing and packaging concentrated in Malaysia and Vietnam. Single-source vulnerability sits with TSMC's specialty RF process nodes. Distribution runs through Shenzhen module houses for Asia-bound volume and through Eindhoven systems integrators for European certification-heavy deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive foundry access and in-house antenna design capabilities determine margin capture. Players are pursuing backward integration into specialty RF process development to lock in die supply.
For Market Incumbents: Anticipate margin compression from Shenzhen-based module houses by securing multi-year foundry allocations at specialty RF nodes. Reinforce certification moats through simultaneous FCC, ETSI, and MIIT pre-validation investments. Barcode-to-RFID substitution threats in consumer goods demand cost-down roadmaps for sub-dollar tag-reader bundles. For New Entrants and Emerging Players: Battery-Assisted Passive RFID sensor integration offers a technology-first wedge into pharmaceutical cold-chain monitoring where unit economics tolerate premium positioning. Target India's PLI-subsidized electronics manufacturing clusters for domestic module assembly partnerships. Lead with cloud-native reader management platforms to differentiate from legacy hardware-centric incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with mixed-signal specialists possessing captive RF process development given spectrum harmonization catalysts. Long-term viability favors architectures spanning LF through UHF with integrated power amplifiers. Acquisition target archetype: European module integrators with ETSI certification pipelines and automotive OEM relationships. Watch MIIT spectrum reallocation announcements as inflection signal for China-facing revenue multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Certification Acceleration | Simultaneous FCC, ETSI, and MIIT pre-validation compresses product launch timelines for global module suppliers. |
| Foundry Partnership Securement | Multi-year capacity reservations at Taiwan-based specialty RF nodes insulate against geopolitical supply friction. |
| Antenna-in-Package Integration | System-in-package designs embedding matching networks eliminate external RF front-end components for OEM cost reduction. |
| Cloud-Native Reader Management Platform | Software-defined reader orchestration differentiates hardware-centric incumbents in retail automation tenders. |
| Battery-Assisted Passive RFID Sensor Development | Thin-film cell integration for cold-chain monitoring captures pharmaceutical mandate-driven premium positioning. |
Research Methodology
SEC filings, ETSI certification databases, and MIIT radio equipment type-approval records formed the secondary backbone for vendor positioning and regulatory timeline mapping. Primary interviews with mixed-signal design directors, RFID systems integrators, and automotive Tier 1 procurement managers validated demand assumptions. Bottom-up unit shipment estimates triangulated against top-down semiconductor revenue analysis across the projection horizon.
Historical trendline analysis of reader IC ASP trajectories informed price elasticity assumptions without year-specific anchoring. Segmentation modeling spanned power architecture, modulation technology, end-use vertical, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to validated base-year estimates, with cross-checks against foundry capacity expansion announcements and retail automation deployment timelines.
Several conditions sit outside the modeled scope, including unannounced spectrum reallocations, foundry process node yield disruptions, and trade policy shifts affecting Taiwan-based fabrication access. Forecasts reflect documented assumptions about RAIN RFID protocol adoption rates and EPCglobal Gen2 compliance timelines. Stakeholders should weight assumptions against their own operating context and qualification pipeline constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
Global Linear Regulator Power Management IC Market
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
South Korea Integrated Circuits Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
United States Integrated Circuits Market