
 Global Computer and Peripherals Special Purpose Logic Ic Market | 2026-2036
Global Computer and Peripherals Special Purpose Logic Ic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computer and Peripherals Special Purpose Logic Ic Market Foresight
Silicon design engineering talent is collapsing across mature economies, forcing foundries and fabless houses into aggressive recruitment in Southeast Asia and India. Intel Corporation leverages its IDM 2.0 strategy to reclaim captive wafer capacity for x86 and foundry services. NXP Semiconductors anchors automotive-grade special purpose logic with a process portfolio spanning 40nm to 16nm FinFET. Texas Instruments sustains analog-digital integration dominance through internal 300mm fabrication at its Sherman and Lehi facilities.
Computer and peripherals special purpose logic ICs are semiconductor devices engineered for dedicated computational tasks rather than general-purpose processing, typically fabricated on CMOS or silicon-on-insulator processes with gate lengths below 7nm for high-performance variants and operating at clock frequencies exceeding 3 GHz in data center accelerators. These devices execute protocol translation, signal conditioning, and algorithmic acceleration in systems where programmable flexibility must coexist with deterministic latency. Application-specific integrated circuits currently command the deepest margin pools in data center and telecommunications deployments where volume scale amortizes mask costs across million-unit runs. Field programmable gate arrays compete for mid-volume embedded systems and aerospace applications requiring in-field reconfiguration without silicon respins.
FDA oversight of diagnostic computing peripherals, EPA hazardous substance restrictions under TSCA, and FCC electromagnetic interference standards collectively shape product qualification timelines and material selection for logic ICs bound for US medical and communications equipment. REACH substance declarations and RoHS lead-free mandates in Europe extend compliance documentation burdens across the supply chain. Stakeholders must monitor how the EU AI Act's risk classification framework imposes traceability requirements on inference accelerators deployed in autonomous systems.
Market Dynamics
Data center operators are forcing a structural recalibration of special purpose logic IC supply chains through accelerated procurement of custom accelerators, compressing foundry reservation timelines from 18 months to 6 months for leading-edge nodes while sovereign capacity mandates redirect fabrication investments.
Growth Catalysts
- MIIT Domestic Substitution Mandates:China's Ministry of Industry and Information Technology directives compel state-affiliated equipment manufacturers to source logic ICs from domestic foundries, creating captive demand for locally fabricated protocol translation devices.
- Edge Computing Deployment:Manufacturing automation and autonomous vehicle sensor fusion requirements are pulling deterministic-latency ASICs into industrial control systems previously served by general-purpose processors.
- EU Chips Act Capital Access:European semiconductor fabrication subsidies are unlocking greenfield 300mm capacity for automotive-grade special purpose logic, with NXP and STMicroelectronics securing preferential allocation agreements.
Market Restraints
- Advanced Node Cost Escalation:Mask costs for 3nm logic designs now exceed $15 million per tape-out, freezing mid-volume entrants from data center accelerator segments.
- EUV Equipment Concentration:ASML's monopoly on extreme ultraviolet lithography systems creates single-source vulnerability for foundries scaling below 7nm gate lengths.
- Fluorinated Gas Supply Constraints:EU F-Gas Regulation phase-down schedules are restricting etching chemistry availability for high-aspect-ratio FinFET fabrication.
Strategic Opportunities
- India Semiconductor Mission Incentives:Modified Special Incentive Package Scheme disbursements are attracting fabless design houses to Bengaluru and Hyderabad for embedded logic development.
- Chiplets and 2.5D Integration:Heterogeneous integration of memory and logic dies through silicon interposers is enabling cost-effective performance scaling without monolithic shrink.
- Medical Device AI Acceleration:FDA breakthrough device designation pathways for diagnostic imaging peripherals are opening premium-margin sockets for inference-optimized ASICs.
Industry Challenges
- Physical Design Engineering Scarcity:Cadence and Synopsys tool expertise for 5nm and below node closure commands compensation premiums exceeding 40% above digital design market rates.
- Multi-Jurisdiction Qualification Overlap:Simultaneous FDA 510(k), EMA MDR, and NMPA registration requirements for diagnostic computing peripherals extend commercialization timelines by 14-22 months.
- Legacy PCIe Protocol Integration:Backward compatibility requirements for Gen3 and Gen4 interconnect standards are consuming 25-30% of modern accelerator die area.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computer and Peripherals Special Purpose Logic Ic Market |
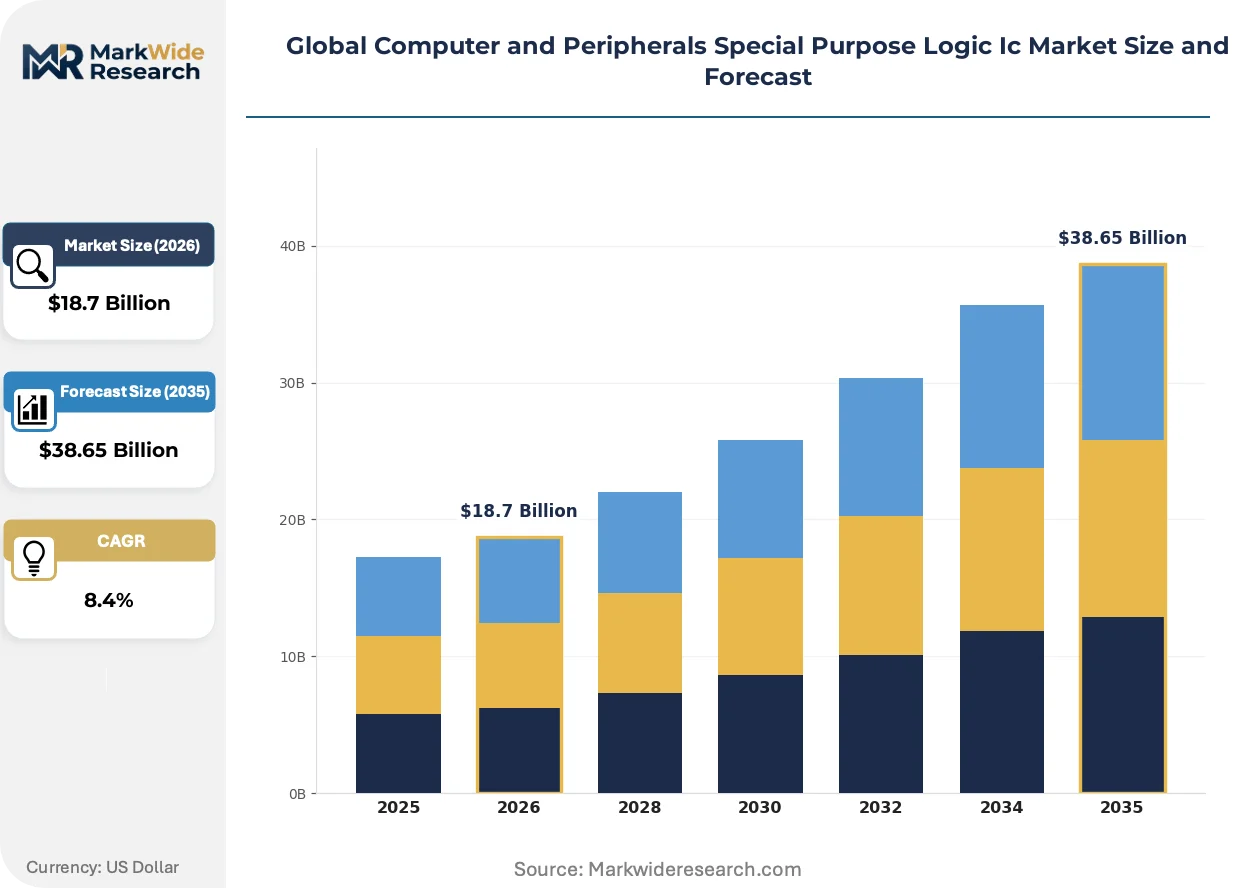
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Field Programmable Gate Arrays, Application-Specific Integrated Circuits, Programmable Logic Devices, Complex Programmable Logic Devices Technology: CMOS, Bipolar, BiCMOS, GaAs, Silicon-on-Insulator Application: Data Centers, Embedded Systems, Consumer Electronics, Telecommunications, Aerospace End User: OEMs, Tier-1 Vendors, System Integrators, Aftermarket Specialists, Contract Manufacturers |
| Companies Covered | Intel Corporation, NXP Semiconductors, Texas Instruments, Broadcom, Advanced Micro Devices, Microchip Technology, Analog Devices, Infineon Technologies, GOWIN Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computer and Peripherals Special Purpose Logic Ic Market Shifts & Advancements
Silicon architecture is bifurcating between monolithic scale-up and disaggregated scale-out approaches, with process technology choices increasingly tied to specific workload acceleration requirements rather than universal performance metrics.
Embedded non-volatile memory integration is fragmenting the standard-cell library landscape. Magnetoresistive RAM and ferroelectric FET technologies now enable power-gated state retention in edge inference accelerators without external DRAM. Automotive Tier-1 suppliers are qualifying these processes for 10-year retention specifications at 150°C junction temperatures. The technology is fragmenting foundry process roadmaps into workload-optimized variants rather than unified node migrations.
EU AI Act risk classification frameworks are imposing traceability mandates on inference accelerators deployed in autonomous systems. High-risk application categories must maintain audit logs of model weights and execution paths, forcing architectural modifications to on-chip memory hierarchies. Medical imaging and industrial robotics OEMs in Germany and France are demanding hardware-level attestation features that exceed baseline ISO 26262 functional safety requirements.
Hyperscaler procurement patterns are compressing traditional distribution channels. Amazon Web Services, Microsoft Azure, and Google Cloud are negotiating direct multi-year foundry capacity reservations for custom training accelerators, bypassing merchant silicon vendors entirely. Taiwan's Hsinchu corridor remains the geographic anchor for these arrangements, though Intel's Arizona and Ohio fabs are capturing x86-adjacent logic volumes through captive sourcing agreements.
Global Computer and Peripherals Special Purpose Logic Ic Market Segmentation
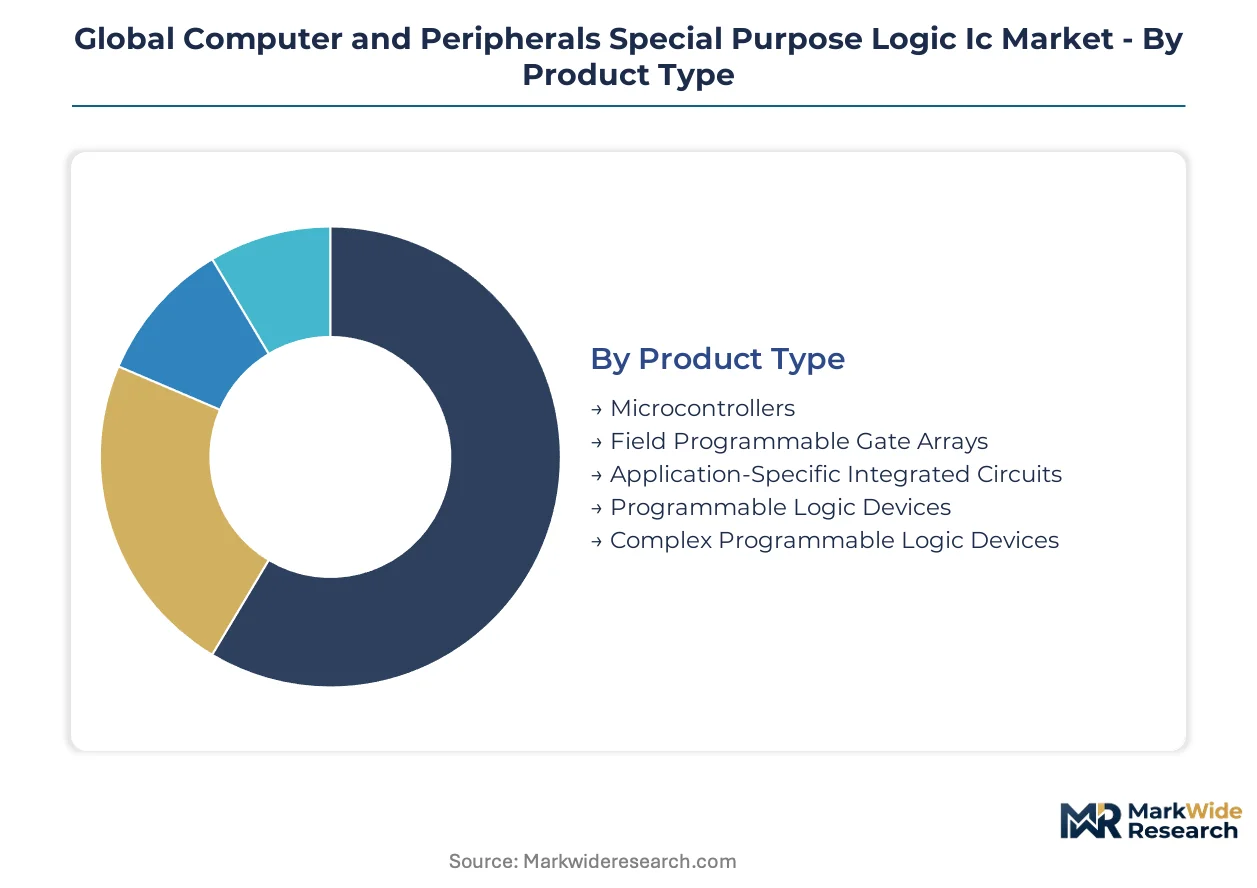
Segmentation in special purpose logic ICs reveals how substitution pressures and process constraints fragment procurement patterns across end-use categories. Technical specifications, sovereign sourcing mandates, and workload-specific acceleration requirements create divergent margin pools that resist commoditization.
Product Type:
Substitution pressure from software-defined alternatives and general-purpose processors threatens lower-complexity programmable devices most acutely, while custom silicon retains defensive positioning in latency-critical applications.
- Application-Specific Integrated Circuits:Full-custom silicon implementations achieve deterministic latency below 10 microseconds for protocol translation and cryptographic acceleration. Data center operators in Taiwan's Hsinchu corridor and Intel's Arizona fabs are reserving wafer starts 18 months ahead for training accelerators, compressing foundry access for mid-volume entrants. Mask cost escalation above $15 million per 3nm tape-out is freezing fabless competitors from leading-edge nodes.
- Field Programmable Gate Arrays:Reconfigurable gate arrays with in-field bitstream updates serve aerospace qualification cycles and industrial control systems requiring post-deployment algorithm modifications. NXP Semiconductors and Xilinx-derived AMD product lines dominate mid-volume sockets where million-unit ASIC amortization remains uneconomical. EU Chips Act subsidies are redirecting some automotive FPGA demand toward STMicroelectronics' Crolles facility.
- Microcontrollers:Embedded control cores with integrated non-volatile memory execute deterministic state machines in peripheral devices.
- Programmable Logic Devices:Lower-density programmable arrays face displacement from software-defined I/O in cost-sensitive consumer electronics.
- Complex Programmable Logic Devices:Mid-range programmable density serves legacy protocol bridging in industrial retrofit installations.
Application-Specific Integrated Circuits anchors the volume base while Field Programmable Gate Arrays gains share at the steepest rate.
Technology:
Process node economics stratify technology selection, with power-performance-area tradeoffs forcing divergent foundry commitments across performance tiers.
- CMOS:Complementary metal-oxide-semiconductor dominates cost-optimized production with mature node availability across 200mm and 300mm wafer formats. TSMC's Nanjing and SMIC's Shanghai fabs supply China's MIIT-mandated domestic substitution requirements for state-affiliated equipment manufacturers.
- Silicon-on-Insulator:Buried oxide isolation enables sub-threshold leakage reduction critical for edge inference accelerators in battery-constrained deployments. IBM's Albany NanoTech partnership and GlobalFoundries' Malta fab anchor US supply for defense-qualified radiation-hardened variants.
- Bipolar:High-current drive capability persists in linear power management and precision analog interfaces.
- BiCMOS:Combined bipolar-CMOS integration serves mixed-signal RF transceivers in telecommunications infrastructure.
- GaAs:Gallium arsenide retains niche positioning in millimeter-wave front-ends where silicon noise figures prove inadequate.
CMOS commands the installed base while Silicon-on-Insulator expands most quickly in power-constrained edge applications.
Application:
Workload-specific acceleration requirements are fragmenting architectural roadmaps, with each application imposing distinct memory hierarchy and interconnect constraints.
- Data Centers:Hyperscaler procurement of custom training accelerators through direct foundry reservations is bypassing traditional merchant silicon channels entirely. Amazon Web Services, Microsoft Azure, and Google Cloud have compressed reservation timelines from 18 months to 6 months for TSMC's leading-edge nodes, freezing fabless competitors from capacity access.
- Embedded Systems:Manufacturing automation and autonomous vehicle sensor fusion are pulling deterministic-latency ASICs into control systems previously served by general-purpose processors. Automotive Tier-1 suppliers in Germany and Japan are qualifying magnetoresistive RAM integration for 10-year retention at 150°C junction temperatures.
- Telecommunications:5G baseband processing and optical transport require protocol-specific acceleration with backward compatibility for legacy standards.
- Consumer Electronics:Cost-optimized protocol translation in peripherals faces margin compression from integrated SoC solutions.
- Aerospace:Radiation-hardened qualification cycles and ITAR restrictions create captive demand for domestic foundry supply.
Data Centers concentrates the revenue pool while Embedded Systems climbs the fastest as industrial automation accelerates.
End User:
Procurement authority concentration among hyperscalers and automotive OEMs is reshaping channel economics, with direct foundry relationships displacing distribution for high-volume categories.
- OEMs:Original equipment manufacturers with captive semiconductor design teams negotiate multi-year capacity reservations directly with foundries, compressing margin for merchant silicon vendors. Apple's in-house silicon organization and Tesla's Dojo program exemplify this vertical integration trajectory.
- Tier-1 Vendors:Automotive and telecommunications subsystem suppliers aggregate demand across multiple OEM programs to achieve ASIC volume thresholds. Bosch, Continental, and Denso maintain dedicated foundry allocation agreements through NXP and Renesas partnerships.
- System Integrators:Industrial and medical equipment assemblers source programmable logic for low-volume, high-mix configurations.
- Aftermarket Specialists:Legacy equipment retrofit demand sustains mature node programmable devices with extended qualification timelines.
- Contract Manufacturers:Foxconn, Jabil, and Flex manage component procurement for brand-holders without captive silicon design.
OEMs dominate direct foundry access while Tier-1 Vendors sustain the broadest product mix coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT directives in China are redirecting foundry capacity toward sovereign supply chains, while the EU Chips Act and US CHIPS and Science Act fragment fabrication investments across three continents. Taiwan's Hsinchu corridor retains process leadership for leading-edge nodes.
United States
Hyperscalers in Washington State and Northern Virginia compress foundry reservation timelines for training accelerators. The CHIPS and Science Act unlocks capital subsidies for Intel's Arizona and Ohio fabrication expansions. FDA oversight of diagnostic computing peripherals extends qualification timelines for medical-grade logic devices bound for Boston and San Francisco medical device clusters.
China
State-affiliated equipment manufacturers face MIIT mandates to source protocol translation devices from domestic foundries. SMIC's Shanghai and Beijing fabs supply captive demand for locally fabricated logic. Yangtze Memory Technologies and Hua Hong Semiconductor anchor sovereign capacity expansion in the Yangtze River Delta corridor.
Germany
Automotive OEMs in Stuttgart and Munich qualify magnetoresistive RAM integration for 10-year retention specifications. The EU Chips Act unlocks greenfield 300mm capacity through NXP and STMicroelectronics preferential allocation agreements. ECHA REACH substance declarations extend compliance documentation burdens across Bavarian industrial control supply chains.
Japan
Automotive Tier-1 suppliers in Nagoya and Tokyo demand hardware-level attestation features exceeding baseline functional safety requirements. METI semiconductor subsidies support embedded non-volatile memory process development. Renesas Electronics anchors automotive-grade special purpose logic fabrication in the Kyushu region.
South Korea
Samsung Electronics and SK Hynix dominate memory-logic heterogeneous integration through 2.5D silicon interposer technologies. The Seoul Capital Area concentrates fabless design houses for edge inference accelerators. MFDS medical device regulations shape diagnostic computing peripheral qualification timelines for export-bound production.
Global Computer and Peripherals Special Purpose Logic Ic Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in special purpose logic IC supply. IDM 2.0 strategists reclaim captive wafer capacity while fabless houses negotiate direct foundry reservations. Three archetypes dominate: vertically integrated fabricators with internal 300mm capacity, fabless design houses with custom accelerator programs, and automotive-grade specialists with extended temperature qualification portfolios. Competitive moves concentrate on multi-year foundry capacity reservations and heterogeneous integration partnerships.
Among US-based integrated fabricators, Intel Corporation exemplifies the captive capacity archetype through IDM 2.0 execution. NXP Semiconductors anchors the automotive-grade specialist tier with process portfolios spanning mature to advanced nodes. Texas Instruments represents analog-digital integration dominance through internal fabrication infrastructure.
| Leading Market Players |
|---|
| Intel Corporation |
| NXP Semiconductors |
| Texas Instruments |
| Broadcom |
| Advanced Micro Devices |
| Microchip Technology |
| Analog Devices |
| Infineon Technologies |
| GOWIN Semiconductor |
| Others |
Supply & Pricing Matrix
Domestic foundry substitution under China's MIIT mandates is rerouting protocol translation device procurement away from Taiwan's leading-edge nodes toward SMIC's mature capacity, simultaneously fragmenting supply geography and compressing margin pools for mid-volume ASIC entrants unable to amortize mask costs across reduced wafer allocations.
Pricing Analysis
Long-term offtake contracts dominate hyperscaler procurement, with Amazon Web Services, Microsoft Azure, and Google Cloud negotiating multi-year foundry reservations that lock in capacity at fixed wafer prices. Price differentiation rests on volume scale and EU AI Act attestation certification tiers, with high-risk autonomous system accelerators commanding premiums for hardware-level traceability. Cost compression in consumer-grade programmable logic is intensifying because integrated SoC solutions absorb peripheral translation functions. Tier-1 automotive suppliers exhibit lowest price sensitivity due to 10-year qualification cycles, while consumer electronics OEMs face acute margin pressure from software-defined I/O displacement.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for leading-edge special purpose logic, with TSMC's Hsinchu corridor supplying training accelerators and Samsung Electronics managing memory-logic heterogeneous integration. Raw material dependencies draw from ASML's EUV lithography systems, fluorinated etching chemistry subject to EU F-Gas phase-downs, and silicon interposer substrates for 2.5D packaging. Single-source vulnerability in extreme ultraviolet equipment creates structural concentration risk for nodes below 7nm. Distribution runs through direct foundry relationships for hyperscalers and automotive OEMs, bypassing traditional merchant silicon channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of physical design engineers capable of 5nm node closure is constraining supply expansion faster than demand growth, creating defensive moats for incumbents with captive talent pipelines while raising entry barriers for fabless competitors.
For Market Incumbents: Secure multi-year foundry allocation agreements at TSMC and Intel before reservation timelines compress further, and deepen backward integration into embedded non-volatile memory processes to differentiate from FPGA substitutes. Threat of hyperscaler custom silicon programs bypassing merchant vendors entirely makes captive design-service capabilities essential. Capacity addition in Arizona and Ohio fabs offers geographic diversification against Taiwan Strait concentration risk. For New Entrants and Emerging Players: FDA breakthrough device designation pathways offer the fastest certification fast-track for diagnostic imaging inference accelerators, opening premium-margin sockets insulated from hyperscaler procurement dominance. White-space targets concentrate in medical device AI acceleration and industrial edge control systems requiring deterministic latency below 10 microseconds. Go-to-market angle should emphasize hardware-level attestation features exceeding EU AI Act baseline requirements for German and French automotive Tier-1 suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fabless design houses holding Cadence and Synopsys tool expertise for advanced node closure. Long-term viability over the coming decade hinges on heterogeneous integration capabilities and sovereign foundry relationships rather than monolithic process leadership. Acquisition target archetype: automotive-grade specialists with 150°C qualification portfolios and NXP or Renesas partnership channels. Signal to watch: MIIT domestic substitution enforcement intensity redirecting Chinese state-affiliated demand toward SMIC and Hua Hong.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Foundry Capacity Reservation | Amazon Web Services and Microsoft Azure have compressed leading-edge node access timelines from 18 months to 6 months. |
| Heterogeneous Integration Partnership | Samsung Electronics and SK Hynix dominate 2.5D silicon interposer technologies for memory-logic stacking. |
| EU AI Act Attestation Certification | German automotive OEMs in Stuttgart demand hardware-level traceability exceeding ISO 26262 baselines. |
| Domestic Foundry Sourcing Transition | China's MIIT mandates redirect state-affiliated equipment procurement toward SMIC's Shanghai fabs. |
| Physical Design Engineering Acquisition | Cadence and Synopsys tool expertise commands compensation premiums exceeding 40% above market rates. |
Research Methodology
A standing panel of foundry operations executives, fabless design house CTOs, automotive Tier-1 procurement directors, and data center infrastructure planners provided ongoing calibration against secondary validation. Primary interviews combined with SEC 10-K filings, ECHA REACH substance declaration databases, FDA 510(k) submission records, and hyperscaler capital expenditure disclosures enabled bottom-up and top-down triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, technology node, application workload, and end-user procurement authority dimensions. CAGRs were derived from segmented demand modeling incorporating foundry capacity expansion schedules, sovereign substitution policy enforcement timelines, and edge computing deployment trajectories in manufacturing automation.
Underlying assumptions cover MIIT domestic substitution compliance rates, EU F-Gas Regulation phase-down adherence, and ASML EUV equipment delivery schedules, with deviation risk concentrated in Taiwan Strait logistics disruption and advanced node cost escalation beyond current tape-out thresholds. Recalibration cycles align with material shifts in sovereign capacity mandates and hyperscaler accelerator procurement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
South Korea Analog Integrated Circuits Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Automotive IC Market
IC (Integrated Circuits)
Programmable ASIC Market