
 Global Polyanionic Cellulose (PAC) Market | 2026-2036
Global Polyanionic Cellulose (PAC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyanionic Cellulose (PAC) Market Intelligence
Expertise in application-specific formulation, particularly for complex drilling environments, is rotating from broad-based chemical suppliers toward specialized service providers. The Dow Chemical Company leverages its vast manufacturing scale to serve high-volume industrial segments. In contrast, CP Kelco specializes in high-purity grades for food and pharmaceutical applications. Nouryon competes through its extensive distribution network and focus on sustainable chemical solutions, positioning itself across multiple end-user industries for greater market penetration.
Polyanionic cellulose is a high-purity, water-soluble polymer derived from chemically modified natural cellulose. It is characterized by its high degree of substitution and uniform distribution of substituent groups, which imparts excellent salt and thermal stability. Its primary function is to act as a fluid loss reducer and viscosifier in aqueous systems. The oilfield application continues to command the largest share due to PAC's critical role in drilling muds. Demand for food grade and pharmaceutical grade PAC shows accelerated growth from its use as a stabilizer.
Market access and product specifications are governed by a multi-layered regulatory environment. In Europe, chemical safety is managed under ECHA's REACH framework, while in the United States, the EPA regulates its use in applications like drilling fluids to ensure environmental compliance. For food applications, approvals from bodies like the FDA and EFSA are mandatory. Stakeholders must navigate the trade-off between investing in high-purity production capacity for regulated end-uses and competing on cost in the industrial grade segment.
Market Dynamics
The market's primary dynamic is the divergence between high-volume, cost-sensitive industrial applications and low-volume, high-purity regulated segments. This split is forcing a strategic choice between scale-driven production and specialized, certification-focused formulation for suppliers.
Growth Catalysts
- Unconventional Drilling:Expanded shale oil and gas exploration in the United States and Canada requires significant volumes of PAC for formulating high-performance drilling and completion fluids.
- Wastewater Regulation:Stricter effluent standards under policies like the EU's Water Framework Directive compel municipalities and industries to use PAC as a flocculant in water treatment processes.
- Asian Industrialization:China's continued investment in large-scale construction, textile manufacturing, and chemical production creates sustained demand for industrial-grade PAC as a thickener and stabilizer.
Market Restraints
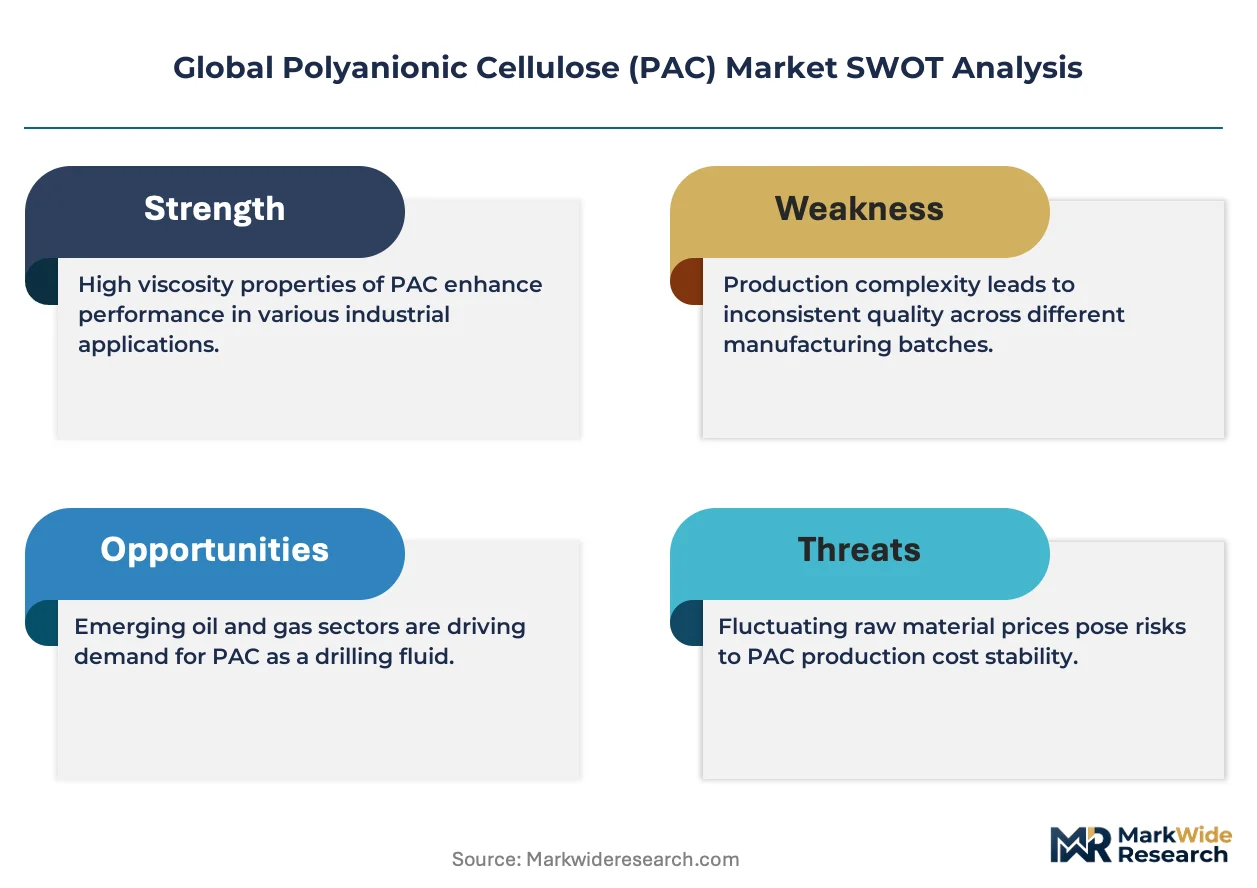
- Feedstock Volatility:Price and availability of high-purity wood pulp and cotton linter, the primary raw materials for PAC, are subject to fluctuations from competing industries like paper and textiles.
- Substitution Threat:In less demanding applications such as low-end detergents or construction mortars, lower-cost alternatives like carboxymethyl cellulose (CMC) or guar gum can substitute for PAC.
- Regulatory Barriers:The rigorous and costly approval processes mandated by bodies like the FDA in the United States and EFSA in Europe for food-contact grades limit market entry for new suppliers.
Strategic Opportunities
- Battery Technology:The emerging use of high-purity PAC as a binder and viscosity modifier in the anode slurries for lithium-ion battery manufacturing presents a high-value growth vector.
- Geographic Expansion:Investment in modernizing water and wastewater treatment infrastructure across India and Southeast Asian nations opens new markets for water-soluble polymers.
- Bio-based Formulations:Developing PAC grades derived from sustainable or recycled cellulose sources aligns with corporate ESG mandates and policies such as the EU Green Deal, creating a premium niche.
Industry Challenges
- Quality Consistency:Maintaining uniform purity and degree of substitution in PAC is challenging when sourcing raw cellulose from geographically diverse and seasonally variable agricultural feedstocks.
- Compliance Fragmentation:Manufacturers must navigate a complex and often overlapping web of regulations, including ECHA's REACH in Europe and EPA rules in the US, for the same product sold into different end-uses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyanionic Cellulose (PAC) Market |
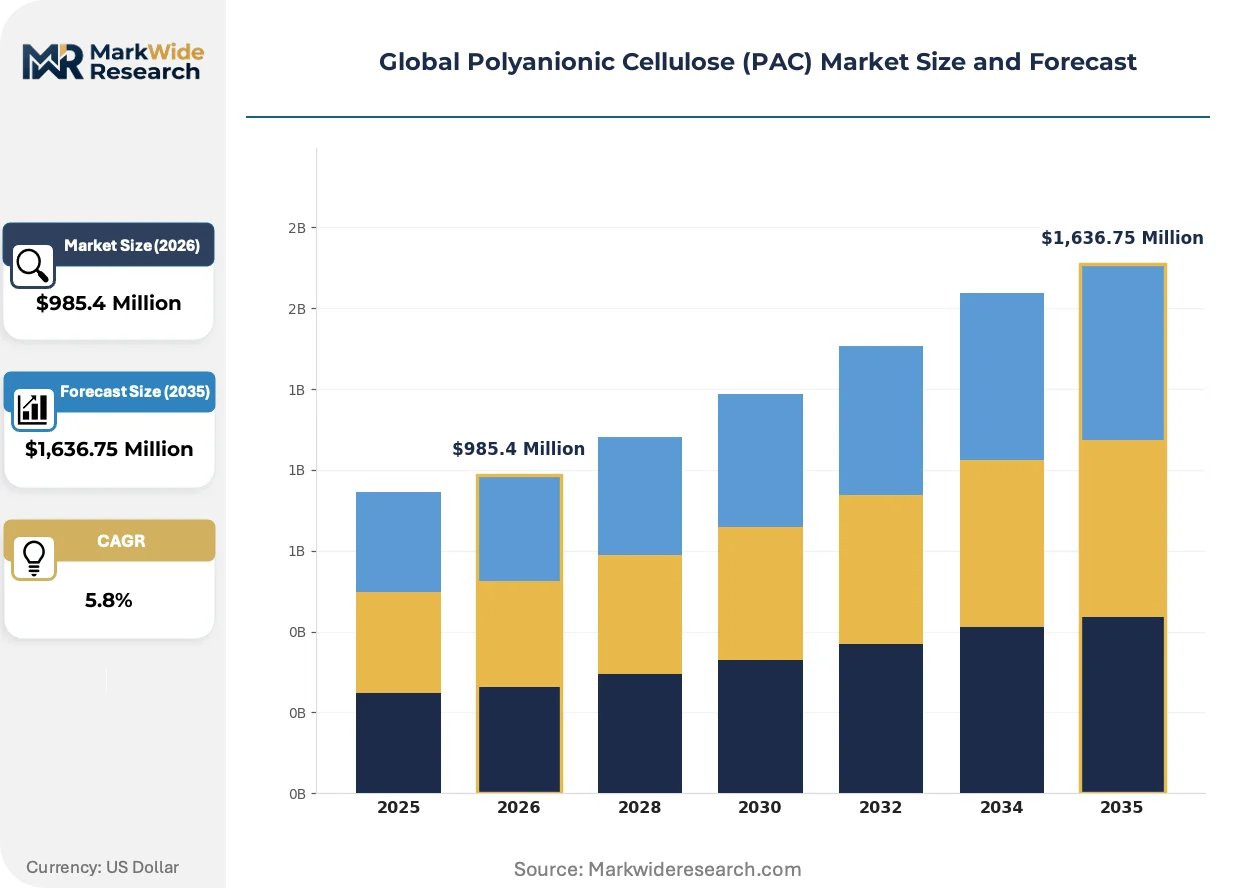
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,636.75 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Flakes, Paste Grade: Industrial, Pharmaceutical, Food Grade, Cosmetic Application: Water Treatment, Oilfield, Detergent & Cleaning, Paper & Textiles, Construction End User Industry: Chemical Manufacturers, Oil & Gas Operators, Consumer Goods Producers, Building Materials Suppliers |
| Companies Covered | The Dow Chemical Company, Ashland, Sidley Chemical Co., Ltd., IRO Group Inc., Global Drilling Fluids & Chemicals Ltd., Shanghai Bichain Industrial Chemical Co., Ltd., CP Kelco, Nouryon, Chevron Phillips Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyanionic Cellulose (PAC) Market Strategic Shifts & Innovations
A fundamental shift toward application-specific performance is underway. General-purpose grades are ceding ground to formulations engineered for precise regulatory and operational windows, from deepwater drilling to pharmaceutical excipients, demanding deeper technical expertise from suppliers.
Enzyme-cleavable PAC provides controlled viscosity reduction in drilling and completion fluids. The oil and gas sector is adopting this technology for enhanced hydraulic fracturing operations to improve proppant placement. This innovation is decomposing the reliance on uniform, persistent viscosifiers, enabling more targeted and efficient reservoir stimulation sequences that maximize hydrocarbon recovery.
Europe's REACH regulation mandates extensive chemical safety assessments and registration for substances manufactured or imported in high volumes. This creates a significant compliance barrier for non-EU producers of industrial-grade PAC. As a result, the European industrial segment is seeing a consolidation of supply towards larger, fully-registered chemical manufacturers.
Buyers in specialized sectors are moving from simple product procurement to acquiring PAC within integrated technical service contracts. This model disrupts traditional distributors who compete primarily on logistics and price. The shift is most pronounced in the offshore oil and gas industry, where fluid system performance guarantees are critical.
Global Polyanionic Cellulose (PAC) Market Segmentation
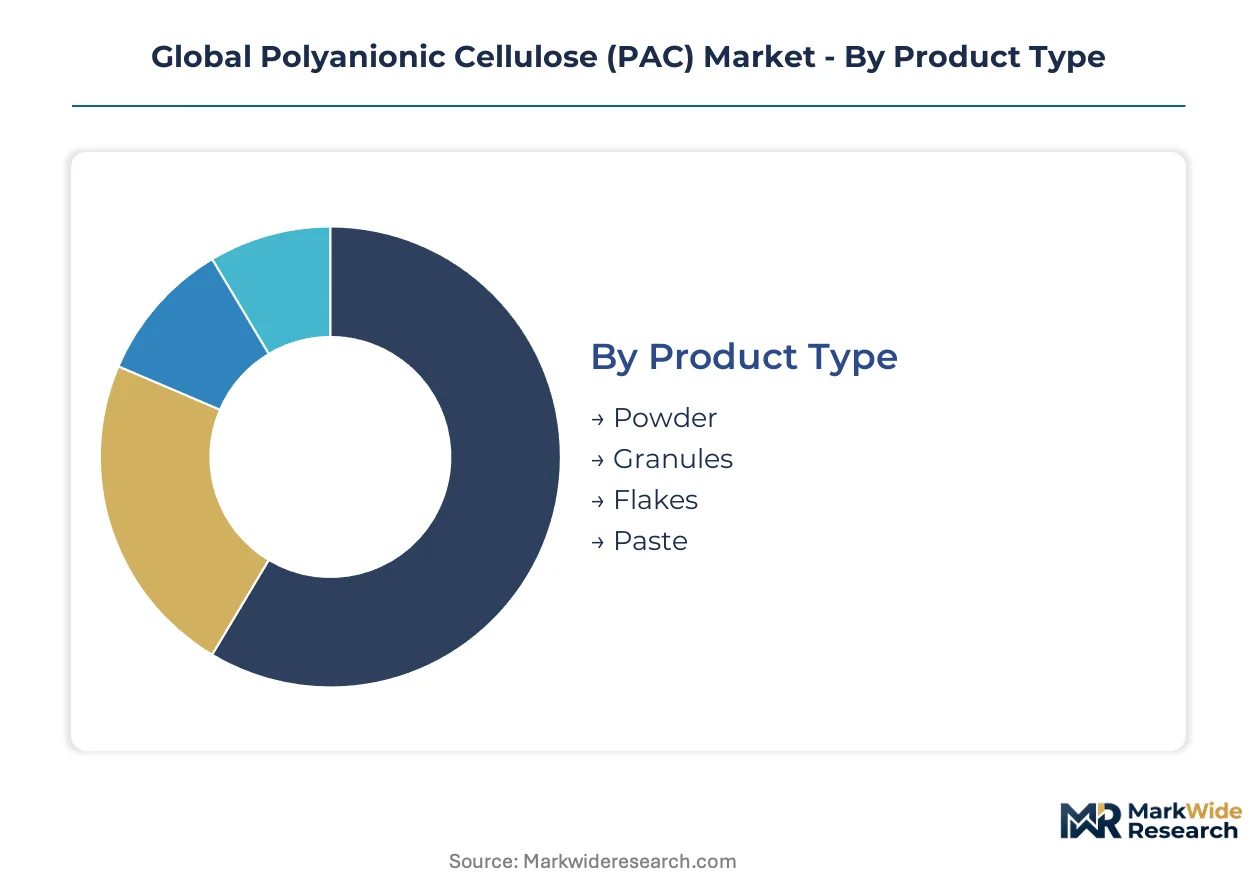
The polyanionic cellulose market exhibits distinct segments driven by diverse performance requirements and regulatory frameworks. Understanding these classifications illuminates the specialized demands across various industrial and consumer sectors. Each segment addresses unique functional needs, influencing production processes and market access strategies for suppliers.
Grade:
Regulatory bodies significantly differentiate PAC grades based on intended end-use, impacting production standards and market entry. Compliance requirements from agencies like the FDA in the United States and EFSA in Europe shape product specifications for certain high-purity grades.
- Pharmaceutical:This high-purity grade of PAC undergoes rigorous manufacturing processes to meet strict pharmacopeial standards, ensuring minimal impurities and consistent performance. Demand concentrates in the United States and European Union, driven by its function as an excipient in drug formulations and its use as a binder or disintegrant.
- Food Grade:Produced under stringent hygienic conditions, this PAC grade adheres to food safety regulations established by bodies like the FDA and EFSA, ensuring its suitability for human consumption. Its application as a thickener, stabilizer, and emulsifier in processed foods and beverages drives demand across Asia-Pacific and Europe.
- Industrial:This general-purpose grade of PAC serves high-volume applications where cost-effectiveness and functional performance are prioritized over ultra-high purity.
- Cosmetic:Used in personal care products, this grade of PAC acts as a thickener, binder, and film-former, meeting specific safety standards for topical applications.
Industrial grade handles the majority of throughput; Pharmaceutical grade is the fastest mover on share.
Application:
Applications for polyanionic cellulose vary widely, with certain sectors consuming significantly larger volumes due to their operational scale and critical performance requirements. The market's volume concentration sits primarily within industrial processes.
- Oilfield:PAC is critical in drilling fluids as a fluid loss reducer and viscosifier, essential for maintaining wellbore stability and efficient drilling operations in complex geological formations. Demand is concentrated in regions with extensive shale oil and gas exploration, such as the United States and Canada.
- Water Treatment:In this application, PAC functions as a flocculant and coagulant, aiding in the removal of suspended solids and impurities from industrial wastewater and municipal effluents. Stricter environmental regulations in Europe, like the EU's Water Framework Directive, compel its broader adoption.
- Detergent & Cleaning:PAC improves the cleaning efficacy of detergents by acting as an anti-redeposition agent and rheology modifier in various formulations.
- Paper & Textiles:This polymer enhances paper strength and surface properties, while in textiles it functions as a sizing agent and thickener for printing pastes.
- Construction:PAC improves the workability and water retention of cementitious materials and gypsum-based products, extending open time and enhancing adhesion.
Oilfield applications command the largest share of PAC consumption; Water Treatment applications are expanding most quickly.
End User Industry:
The end-user industry segmentation highlights the diverse customer base for PAC, each with distinct procurement patterns and technical service needs. These industries integrate PAC into their production processes for specific functional benefits.
- Oil & Gas Operators:These companies are major consumers of PAC, utilizing it directly in drilling and completion fluids to manage fluid loss and viscosity during exploration and production activities. Their procurement often involves specialized service providers offering integrated fluid management solutions.
- Chemical Manufacturers:These entities purchase PAC as a raw material or additive for further formulation into various products, including specialty chemicals, coatings, and adhesives. Their demand is driven by the need for consistent product quality and reliable supply chains for their downstream offerings.
- Consumer Goods Producers:This segment incorporates PAC into products such as personal care items, detergents, and processed foods, leveraging its thickening and stabilizing properties.
- Building Materials Suppliers:These suppliers use PAC in products like tile adhesives, plasters, and mortars to improve water retention, workability, and adhesion performance.
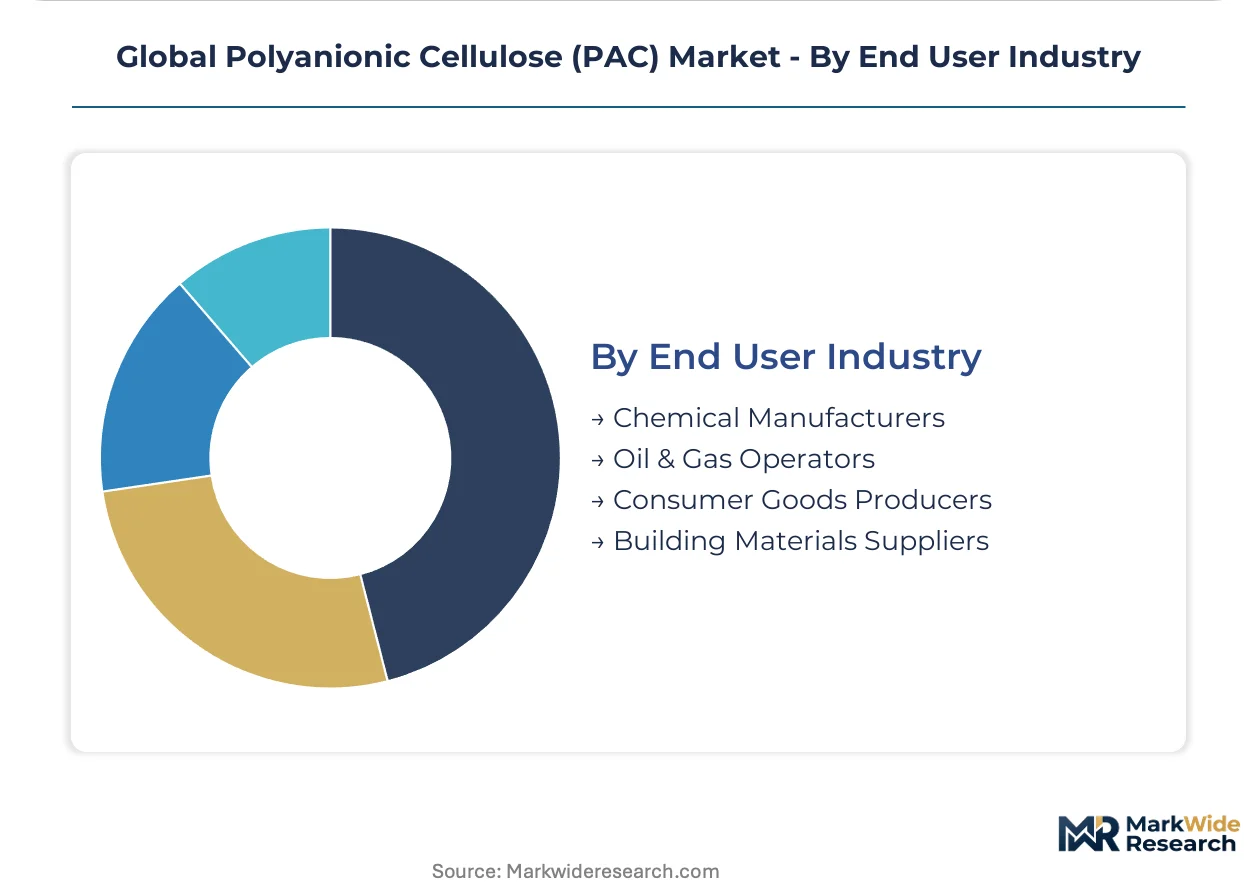
Oil & Gas Operators represent the largest direct purchasing segment; Consumer Goods Producers show a steep expansion trajectory.
Product Type:
Polyanionic cellulose is supplied in various physical forms, which often dictate handling, dissolution rates, and suitability for different manufacturing processes. The choice of product type depends on the end-user's equipment and formulation requirements.
- Powder:This is the most common form of PAC, offering high surface area for rapid dissolution and easy integration into dry-mix formulations and aqueous solutions. Its fine particle size requires careful handling to prevent dust formation during industrial processing.
- Granules:Granular PAC minimizes dust issues associated with powder forms, improving handling safety and dispersion properties in liquid systems, particularly in large-scale industrial mixing operations. This form is preferred in applications requiring controlled dissolution.
- Flakes:PAC flakes offer an alternative solid form, often used where specific dissolution profiles or visual characteristics are desired in specialized applications.
- Paste:This pre-dispersed form of PAC offers convenience and eliminates the need for on-site dissolution, making it suitable for applications requiring immediate viscosity modification.
Powdered PAC accounts for the majority of market volume; Granular forms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Environmental Protection Agency (EPA) in the United States sets standards for PAC use in drilling fluids. This regulatory oversight influences demand patterns across major consuming regions. Global polyanionic cellulose consumption reflects diverse industrial and environmental requirements.
United States
United States shale oil and gas exploration drives significant PAC demand for drilling fluids. The EPA regulates its use in these applications to ensure environmental compliance. Major oilfield service hubs like Houston see concentrated demand and technical service provision for PAC products.
China
China's expansive construction and chemical manufacturing sectors create sustained demand for industrial-grade PAC. The Ministry of Ecology and Environment (MEE) sets environmental standards impacting industrial wastewater treatment. The Yangtze River Delta region, a chemical production hub, utilizes PAC as a thickener and stabilizer.
Germany
Germany's pharmaceutical and food industries require high-purity PAC grades for excipients and stabilizers. ECHA's REACH framework governs chemical safety and market access for industrial PAC within Europe. The Rhine-Ruhr industrial region represents a key area for chemical manufacturing and specialized PAC applications.
India
India's modernizing water and wastewater treatment infrastructure expands demand for water-soluble polymers. The Food Safety and Standards Authority of India (FSSAI) approves PAC for food applications. Industrial clusters around Mumbai are increasing PAC adoption for effluent treatment and construction materials.
Canada
Canada's oil sands and shale gas operations utilize PAC in high-performance drilling and completion fluids. Health Canada regulates food and pharmaceutical grades, influencing market entry for specialized suppliers. Alberta's energy sector remains a primary consumer, particularly for enhanced oil recovery applications.
Global Polyanionic Cellulose (PAC) Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the polyanionic cellulose market. The industry exhibits a tiered structure, with large-scale chemical manufacturers competing on volume and price for industrial grades. Specialized formulators, conversely, focus on high-purity, regulated segments requiring precise technical expertise and certification. Strategic partnerships for distribution and geographic expansion into emerging markets are common competitive moves among these diverse players, alongside portfolio diversification.
Within this varied landscape, The Dow Chemical Company exemplifies the archetype of a large-scale industrial supplier, leveraging its vast manufacturing capabilities to serve high-volume segments of the polyanionic cellulose market. In contrast, CP Kelco represents a specialized formulator, focusing on high-purity grades essential for the demanding food and pharmaceutical applications that require stringent regulatory compliance. Nouryon positions itself across multiple end-user industries, leveraging an extensive distribution network and a focus on sustainable chemical solutions to achieve greater market penetration and differentiation.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| Ashland |
| Sidley Chemical Co., Ltd. |
| IRO Group Inc. |
| Global Drilling Fluids & Chemicals Ltd. |
| Shanghai Bichain Industrial Chemical Co., Ltd. |
| CP Kelco |
| Nouryon |
| Chevron Phillips Chemical |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for industrial PAC lock in volume commitments for oilfield operators, ensuring stable pricing and consistent material access. This contrasts with more volatile spot pricing for niche, high-purity segments.
Pricing Analysis
Geographic price spreads for PAC are evident, with higher premiums for pharmaceutical grades in the EU and US compared to industrial grades in China. Transactional, per-unit pricing dominates across most segments. Price differentiation stems from certification levels, particularly FDA and EFSA approvals, and the specific application's performance requirements. Pricing pressure stems from feedstock volatility and competition from lower-cost alternatives like CMC. Oil & Gas operators are less price-sensitive for critical drilling fluids, while detergent manufacturers exhibit higher price sensitivity.
Supply Chain Analysis
Inventory management and lead times are critical for high-purity PAC grades, often requiring longer planning cycles due to stringent quality control. Geographic supply concentration for PAC centers on China and the United States. Raw material dependencies include high-purity wood pulp and cotton linter. Supply chain risk arises from commodity price volatility of these natural feedstocks. Distribution runs through a hybrid model combining direct sales for large industrial buyers and specialized chemical distributors for smaller, high-purity segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyanionic cellulose market is experiencing high-growth disruption, driven by the technological inflection of enzyme-cleavable PAC for enhanced oil recovery. This innovation is reshaping application performance and supplier expertise.
For Market Incumbents: Shield core industrial market share by investing in large-scale, cost-efficient production capacity in regions like China, countering price competition from emerging players. Diversify product portfolios toward sustainable chemical solutions to mitigate feedstock volatility risks. Control distribution channels for high-volume industrial segments to fend off logistics-focused distributors.
For New Entrants and Emerging Players: Application-specific formulation expertise represents a service-layer gap where incumbents under-serve, especially for complex drilling environments or high-purity food grades. Target specialized, certification-focused segments like pharmaceutical excipients in Europe, leveraging bespoke technical support. A go-to-market angle focused on bio-based PAC formulations aligns with ESG mandates and offers a premium niche.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized formulators with strong intellectual property in high-purity PAC grades and integrated technical service capabilities. Long-term viability rests on securing access to sustainable cellulose feedstocks and navigating evolving regulatory landscapes like the EU Green Deal. An acquisition target archetype involves mid-sized companies with established customer relationships in regulated end-uses. The signal to watch is the accelerated adoption of PAC in lithium-ion battery manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enhances cost competitiveness for industrial-grade PAC in high-volume markets. |
| Green Manufacturing Transition | Aligns with corporate ESG mandates and attracts premium for sustainable PAC grades. |
| Long-term Supply Agreement | Secures consistent PAC supply and stabilizes input costs for critical drilling operations. |
| Regulatory Approval Pathway | Unlocks access to high-value pharmaceutical and food-grade PAC segments in Europe. |
| Product Diversification | Reduces reliance on single applications like oilfield, expanding into battery technology. |
Research Approach
A standing panel of R&D directors, procurement leads, and regulatory affairs specialists provided ongoing calibration through primary interviews. This was combined with secondary validation from customs data, ECHA REACH registrations, and company 10-K filings. Bottom-up and top-down triangulation ensured data integrity.
All quantitative outputs were consistency-checked against external benchmarks from industry associations and government reports across the analysis window. The analytical framework modeled PAC demand across grade, application, end-user industry, and product type. CAGRs were derived from historical growth trends and projected market influences. Forecast inputs included crude oil price trajectories and global construction spending.
Forecasts assume regulatory continuity in the EU's REACH framework and US EPA guidelines; material policy shifts would require re-modeling. These projections reflect assumptions regarding raw material availability and technological advancements in battery applications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Foamed Plastics Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Bio-Based Polymer Market
Polymers & Resins
Sugar Polymers Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Middle East Polymer Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market