
 Global Low Density Polyethylene (LDPE) Foams Market | 2026-2036
Global Low Density Polyethylene (LDPE) Foams Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Density Polyethylene (LDPE) Foams Market Foresight
Asset-light leasing models for extrusion equipment are reshaping competitive entry in LDPE foam production. Dow leverages captive polyethylene supply to sustain cost advantages across North American operations. Zotefoams plc anchors its position through nitrogen-autoclave technology leadership in high-performance cellular structures. INOAC Corporation dominates Asian supply chains through integrated resin-to-foam manufacturing networks.
Low density polyethylene foam comprises closed-cell thermoplastic structures manufactured via extrusion or cross-linking processes, typically achieving densities between 25-200 kg/m³ for cushioning and thermal barrier applications. Cross-linked LDPE foam commands premium positioning in automotive and sports equipment segments where dimensional stability under cyclic loading determines specification compliance. Non-cross-linked variants occupy high-volume packaging applications where cost minimization overrides extended service-life requirements. Electronics manufacturing procurement through direct sales channels concentrates margin pools with certified clean-room foam grades.
EPA regulations on hydrofluorocarbon blowing agents constrain formulation choices for US-based producers, while REACH Annex XVII restrictions in Europe limit residual chemical content in consumer-contact applications. China's GB standards for indoor air quality in construction materials create certification barriers for imported foam products. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and assess dual-sourcing strategies across extrusion and autoclave manufacturing routes.
Market Dynamics
Automotive lightweighting mandates in Germany and Japan are compressing substitution cycles for heavier structural materials, while REACH Annex XVII restrictions force simultaneous reformulation of blowing agent chemistries across European supply chains.
Growth Catalysts
- Extrusion equipment leasing:Asset-light models reduce entry capital for mid-scale producers in China's eastern manufacturing provinces.
- Clean-room certification premiums:Electronics assembly clusters in South Korea and Taiwan concentrate procurement through direct sales channels for certified foam grades.
- Nitrogen-autoclave process yields:High-performance cellular structures command specification compliance in automotive and sports equipment segments.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha pricing transmits cost pressure through non-integrated foam producers lacking captive polyethylene supply.
- Autoclave capacity concentration:High-performance nitrogen-cellular manufacturing clusters in Japan and the UK create geographic supply risk.
- Hydrofluorocarbon phase-down schedules:EPA regulations constrain blowing agent choices for US-based extrusion operations.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives attract assembly investment requiring clean-room foam grades currently met through imports.
- Construction thermal barriers:China's GB standards for indoor air quality create certification barriers that domestic producers can exploit against imports.
- Cross-linking technology licensing:Joint ventures between Japanese nitrogen-autoclave specialists and Southeast Asian extrusion operators transfer process capability.
Industry Challenges
- Polymer rheology expertise:Cross-linked foam production requires process engineers skilled in peroxide initiation kinetics and temperature-pressure profiling.
- Dual-certification timelines:REACH compliance for European consumer-contact applications runs parallel to EPA registration for US blowing agent alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Density Polyethylene (LDPE) Foams Market |
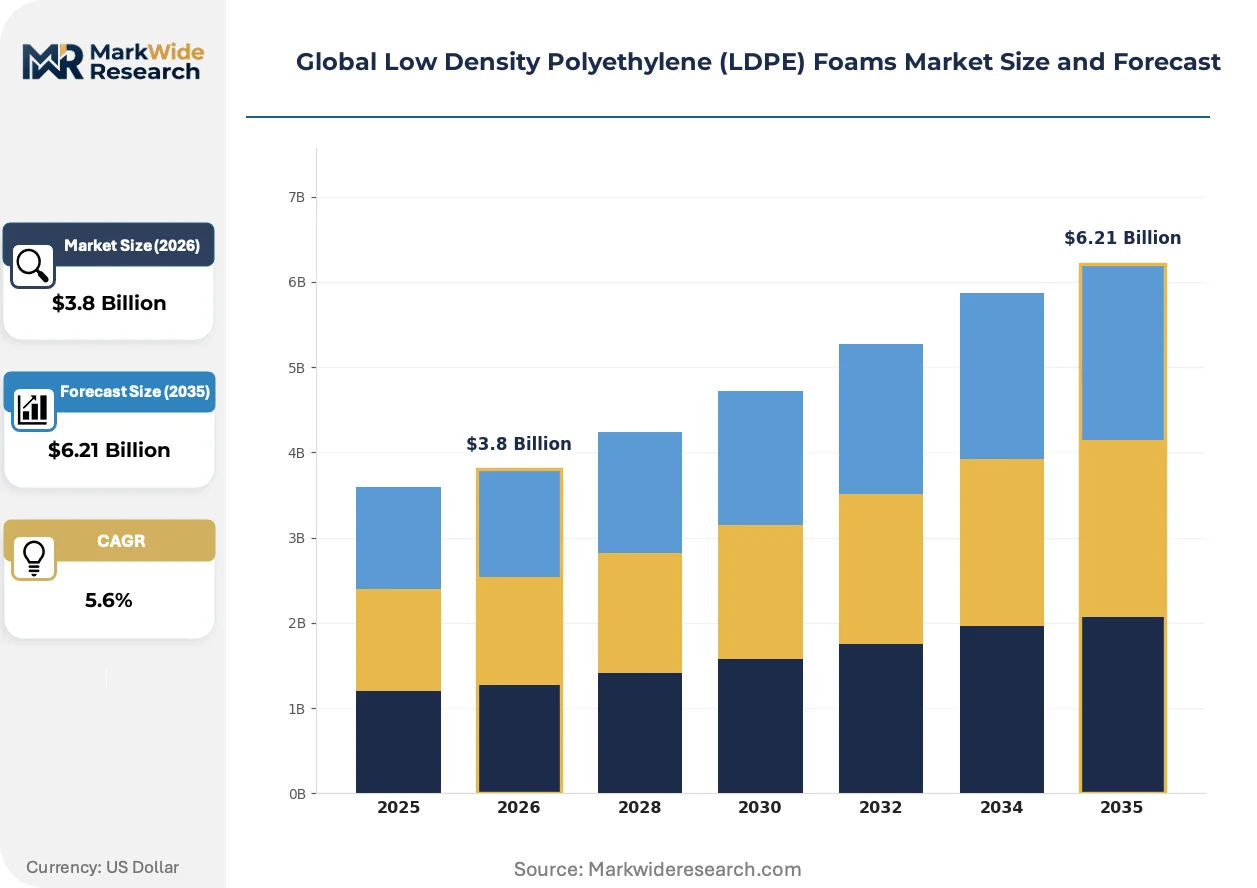
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross-linked LDPE Foam, Non-cross-linked LDPE Foam, Laminated Foam, Extruded Foam, Coated Foam Application: Packaging, Thermal Insulation, Cushioning Material, Automotive Components, Sports Equipment End User Industry: Electronics Manufacturing, Construction Firms, Consumer Goods Producers, Agricultural Sector, Furniture Manufacturers Sales Channel: Direct Sales, Distributors, Online Platforms, Industrial Suppliers, Wholesalers |
| Companies Covered | Armacell International S.A, Dow, Sealed Air Corporation, Zotefoams plc, INOAC Corporation, UFP Technologies, JSP, Recticel NV/SA, Sekisui Voltek LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Density Polyethylene (LDPE) Foams Market Shifts & Advancements
Digital process control systems and alternative blowing chemistries are compressing development cycles, while procurement concentration in electronics clusters reconfigures distribution economics.
Supercritical nitrogen infusion is virtualizing conventional chemical blowing agent dependencies. Automotive seating suppliers in Germany adopt the technology to eliminate residual volatile organic compound concerns. The process is virtualizing specification hierarchies by enabling density gradients impossible with azodicarbonamide decomposition.
REACH F-Gas Regulation amendments tighten hydrofluorocarbon quotas for foam blowing applications. European producers accelerate hydrocarbon and carbon dioxide system investments. Cross-linked LDPE foam for medical packaging faces the steepest compliance timeline compression.
Direct mill relationships are displacing distributor intermediation in electronics procurement. Clean-room certified foam buyers in China's Jiangsu and Guangdong provinces negotiate volume commitments with extrusion operators. The shift concentrates margin pools with producers maintaining ISO 14644-1 compliant manufacturing environments.
Global Low Density Polyethylene (LDPE) Foams Market Segmentation
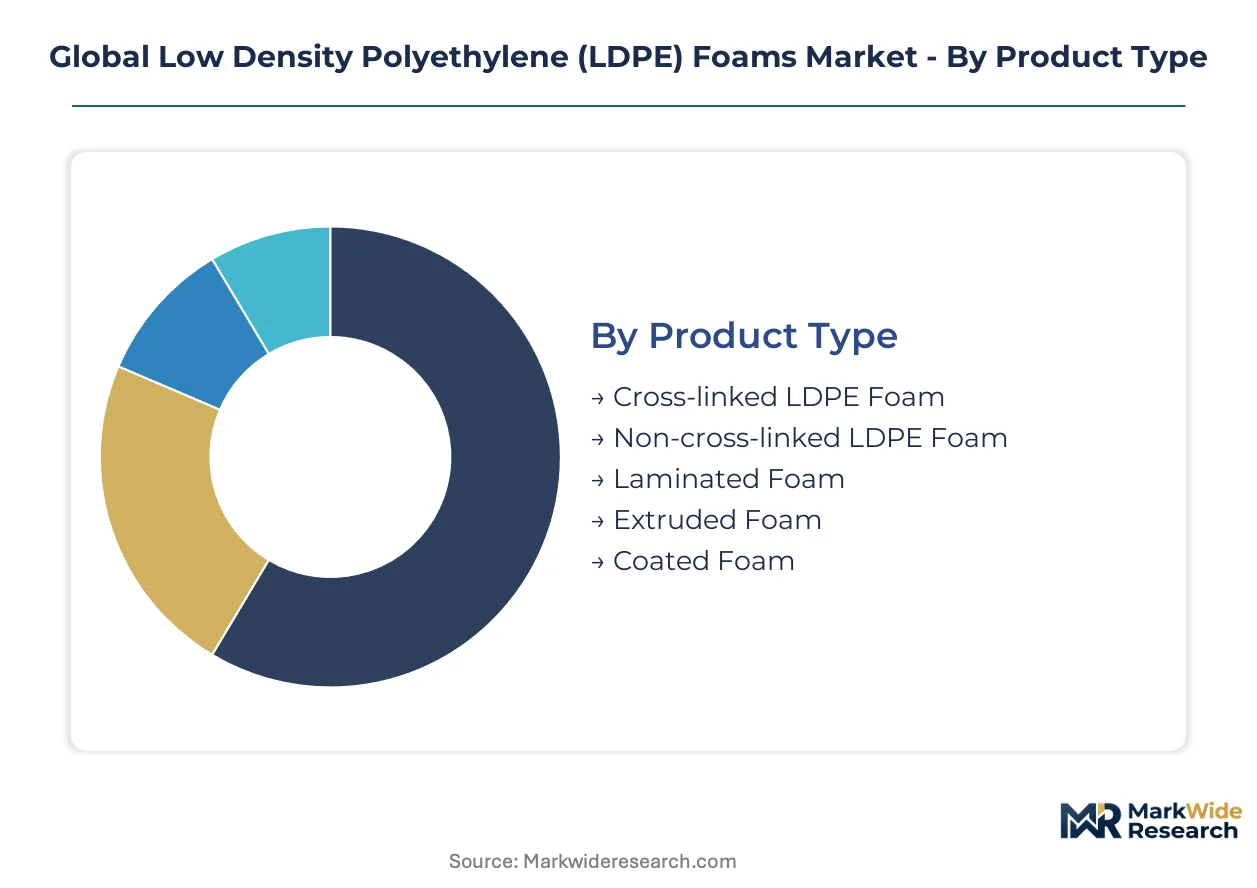
LDPE foam market segmentation reveals how manufacturing process differences, application requirements, and procurement channel economics create distinct competitive arenas. Each dimension carries implications for margin structure, certification burden, and customer relationship intensity.
Product Type:
Cost tier differentiation separates premium-processed cellular structures from commodity extrusion outputs, with nitrogen-autoclave methods commanding specification premiums.
- Cross-linked LDPE Foam:Peroxide-initiated molecular bonding creates thermoset stability under cyclic loading. Automotive seating suppliers in Germany specify these grades for dimensional retention across temperature swings. REACH F-Gas Regulation amendments compress reformulation timelines for European medical packaging applications.
- Non-cross-linked LDPE Foam:Extruded thermoplastic structures without covalent cross-linking permit thermoforming and recycling. Electronics packaging in China's Jiangsu province consumes high volumes where cost minimization dominates procurement criteria.
- Laminated Foam:Multi-layer constructions bond LDPE cellular cores to films or fabrics for surface performance.
- Extruded Foam:Continuous sheet production via tandem extrusion lines serves high-volume packaging applications.
- Coated Foam:Surface-treated variants add chemical resistance or aesthetic finishes for consumer goods.
Cross-linked LDPE Foam holds installed capacity. Non-cross-linked LDPE Foam is rotating up the share rankings.
Application:
Application segmentation tracks how functional requirements—mechanical protection, thermal resistance, or structural compliance—dictate foam specification hierarchies.
- Packaging:Protective cushioning for fragile goods exploits closed-cell energy absorption. Direct mill relationships in South Korea's electronics clusters displace distributor intermediation for clean-room certified grades.
- Thermal Insulation:Low thermal conductivity barriers serve construction and HVAC applications. China's GB standards for indoor air quality create certification barriers that domestic producers exploit against imports.
- Cushioning Material:Impact absorption for furniture and logistics applications.
- Automotive Components:Lightweight structural and interior parts subject to OEM material qualification protocols.
- Sports Equipment:Protective gear and matting requiring rebound resilience and moisture resistance.
Packaging maintains volume leadership. Thermal Insulation is climbing the fastest on building efficiency mandates.
End User Industry:
Customer type segmentation exposes how procurement sophistication, certification requirements, and volume scale vary across downstream sectors.
- Electronics Manufacturing:Clean-room assembly operations demand ISO 14644-1 compliant foam grades with low outgassing. Taiwan and South Korea procurement concentrates through direct sales channels, compressing distributor margins.
- Construction Firms:Thermal barrier and sealant applications face China's GB standards compliance requirements. Domestic extrusion operators leverage certification proximity against import competition.
- Consumer Goods Producers:Packaging and presentation applications with moderate performance thresholds.
- Agricultural Sector:Greenhouse insulation and protective cushioning for produce handling.
- Furniture Manufacturers:Upholstery support and protective wrapping for finished goods distribution.
Electronics Manufacturing concentrates margin pools. Construction Firms are gaining share fastest on thermal efficiency regulations.
Sales Channel:
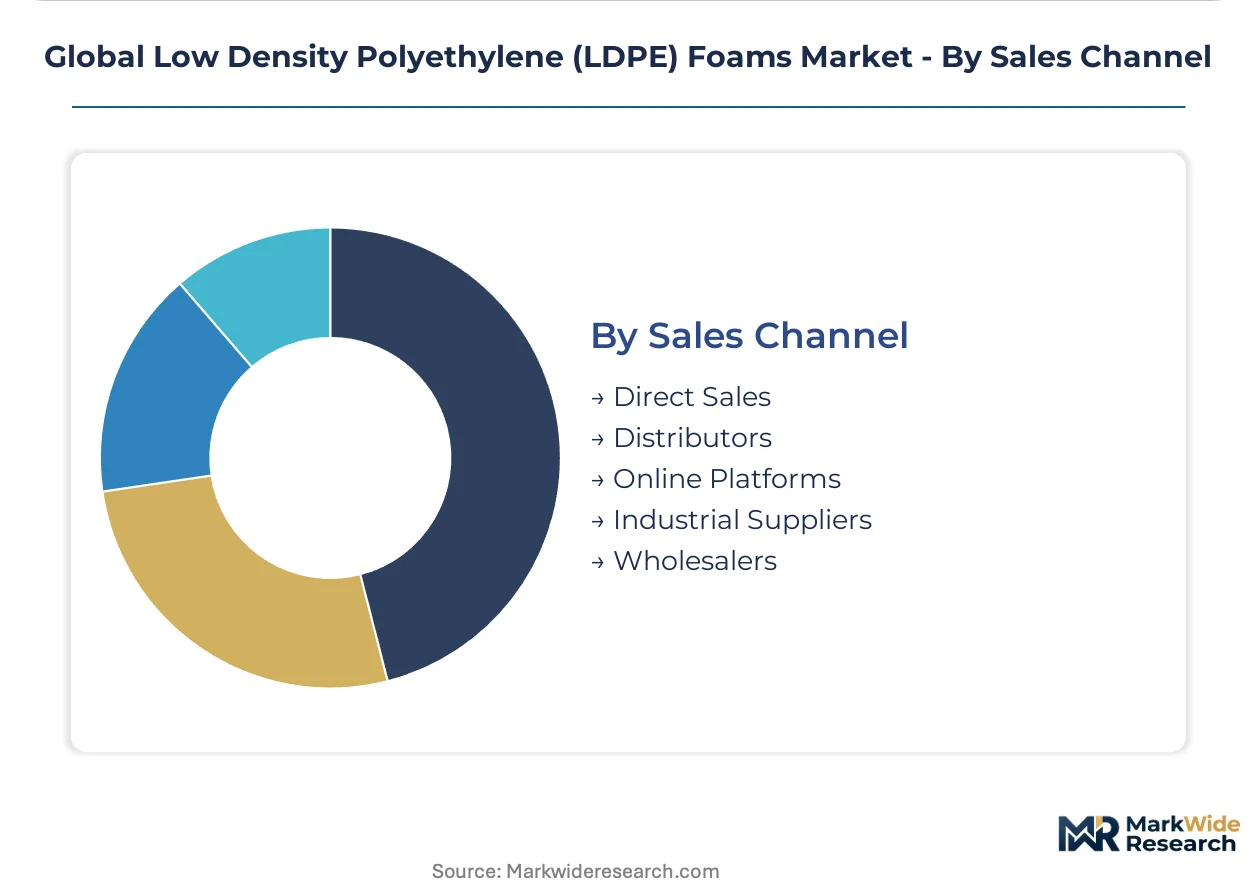
Channel segmentation captures the shift from distributor intermediation toward direct procurement relationships in specification-intensive segments.
- Direct Sales:Mill-direct relationships dominate electronics and automotive procurement where clean-room certification and lot traceability are mandatory. China's eastern manufacturing provinces negotiate volume commitments with extrusion operators.
- Distributors:Inventory-carrying intermediaries serve fragmented packaging and consumer goods accounts.
- Online Platforms:Digital procurement channels for standardized grades and small-lot orders.
- Industrial Suppliers:Integrated MRO distributors serving maintenance and repair applications.
- Wholesalers:Bulk resellers for commodity packaging grades with minimal technical support.
Direct Sales commands specification-premium capture. Online Platforms are rotating up the share rankings on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics assemblers in South Korea and Taiwan concentrate procurement through direct sales channels, while automotive seating engineers in Germany and Japan specify foam grades for lightweighting programs. Construction thermal barrier demand clusters in China's eastern provinces where domestic producers exploit certification proximity.
Germany
Automotive OEMs specify cross-linked LDPE foam for seating and interior structural components under lightweighting mandates. REACH F-Gas Regulation amendments compress reformulation timelines for blowing agent alternatives. Bavarian automotive clusters around Munich and Ingolstadt negotiate volume commitments with nitrogen-autoclave operators.
China
Electronics packaging procurement concentrates in Jiangsu and Guangdong provinces where clean-room certified grades face GB standards compliance requirements. MIIT industrial policy prioritizes domestic foam production for thermal insulation applications. Yangtze River Delta extrusion operators leverage certification proximity against import competition.
United States
EPA hydrofluorocarbon phase-down schedules constrain formulation choices for extrusion-based packaging producers. Automotive suppliers in Michigan and Ohio qualify foam grades under NHTSA material protocols. Southeast manufacturing corridors attract electronics assembly investment requiring ISO 14644-1 compliant cushioning.
Japan
METI energy efficiency standards accelerate foam substitution for heavier automotive structural materials. Nitrogen-autoclave manufacturing clusters in Nagoya and Osaka supply high-performance cellular structures for sports equipment. Kanto region electronics assemblers concentrate procurement through direct mill relationships.
South Korea
Electronics manufacturing procurement dominates clean-room foam consumption through direct sales channels. MFDS medical packaging regulations compress compliance timelines for cross-linked grades. Seoul Capital Area and Busan-Ulsan clusters negotiate volume commitments with certified extrusion operators.
Global Low Density Polyethylene (LDPE) Foams Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into integrated resin-to-foam manufacturers, nitrogen-autoclave technology specialists, and regional extrusion operators serving packaging accounts. Three strategic archetypes dominate: captive polyethylene suppliers leveraging feedstock control, high-performance cellular structure specialists commanding specification premiums, and asset-light leasing operators reducing entry capital for mid-scale producers. Competitive moves concentrate on technology licensing partnerships and dual-certification capacity investments spanning REACH and EPA compliance requirements.
Among integrated multinational suppliers, Dow and INOAC Corporation represent archetypes of backward integration into captive polyethylene supply. Zotefoams plc exemplifies the nitrogen-autoclave technology specialist tier where process leadership commands premium positioning. These three anchors illustrate how feedstock control, manufacturing technology, and geographic supply chain integration create distinct competitive positions without overlapping customer segments.
| Leading Market Players |
|---|
| Armacell International S.A |
| Dow |
| Sealed Air Corporation |
| Zotefoams plc |
| INOAC Corporation |
| UFP Technologies |
| JSP |
| Recticel NV/SA |
| Sekisui Voltek LLC |
| Others |
Supply & Pricing Matrix
Ethylene feedstock concentration in US Gulf Coast and Middle Eastern petrochemical complexes anchors margin distribution toward integrated producers with captive polyethylene supply. Non-integrated extrusion operators in China's eastern provinces absorb naphtha-linked cost volatility while competing for electronics packaging contracts.
Pricing Analysis
Certification level creates the primary spread between ISO 14644-1 clean-room grades and commodity packaging tiers. Three-tier pricing structure across premium nitrogen-autoclave, standard cross-linked extrusion, and economy non-cross-linked variants reflects performance differentiation. Cost compression in economy packaging tiers is intensifying because asset-light leasing models expand extrusion capacity. Electronics manufacturers in South Korea and Taiwan exhibit lowest price sensitivity due to specification compliance requirements, while furniture and logistics buyers drive hardest volume negotiations.
Supply Chain Analysis
Extended payment terms from electronics assemblers in China's Jiangsu province compress working capital for mid-scale extrusion operators. Raw material sourcing draws from Saudi Arabian and US ethylene derivatives, Japanese nitrogen-autoclave equipment, and German peroxide initiator chemicals. Single-source vulnerability concentrates in Japanese nitrogen-autoclave manufacturing clusters serving automotive seating specifications. Distribution runs through direct mill relationships for certified grades and distributor networks for commodity packaging volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital procurement platforms and supercritical nitrogen process licensing are reconfiguring this market toward ecosystem economics where interoperability between equipment suppliers and foam producers determines competitive access.
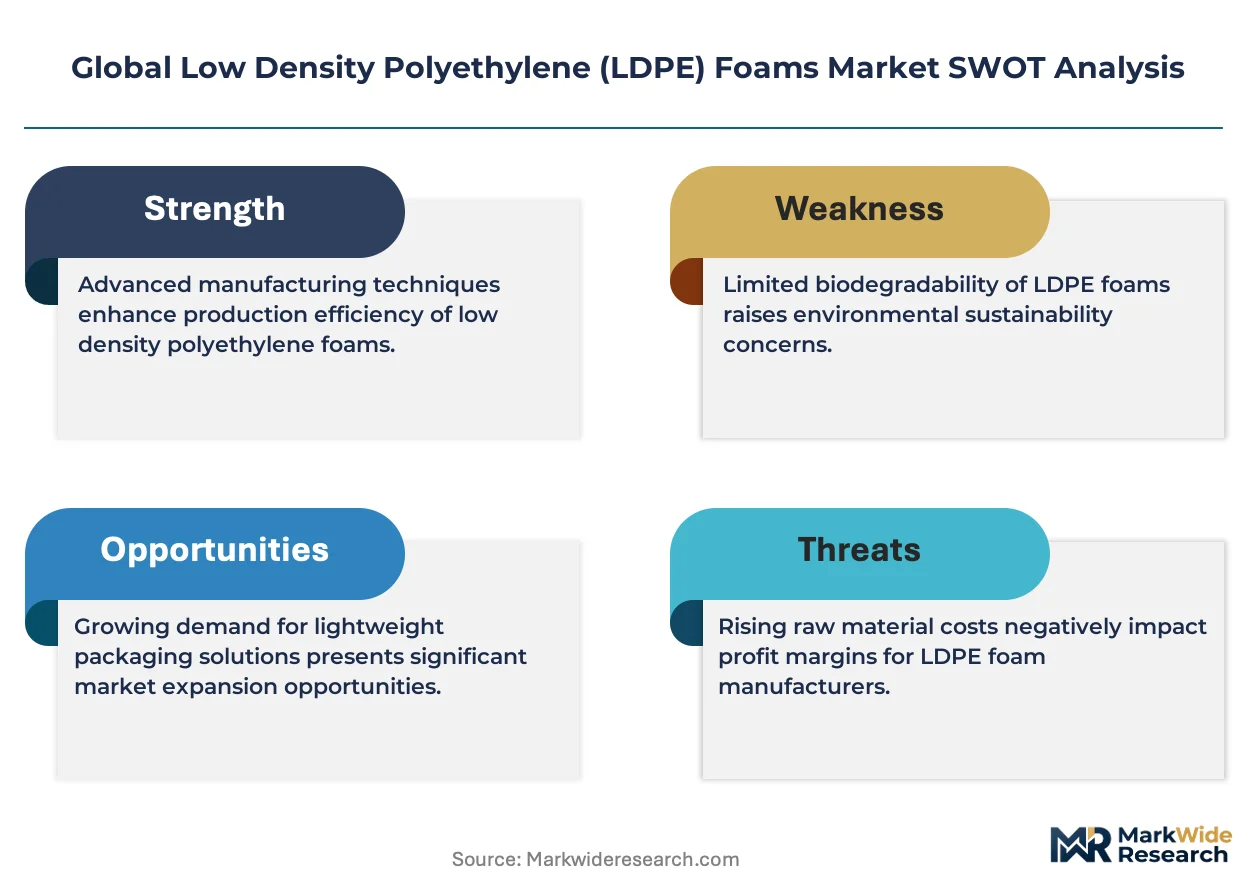
For Market Incumbents: Build certification moats around dual REACH-EPA compliance capacity before reformulation deadlines compress. Invest in captive polyethylene supply integration to neutralize feedstock volatility threatening non-integrated competitors. Supercritical nitrogen technology licensing from Japanese specialists represents the critical capability gap to close against emerging process alternatives. For New Entrants and Emerging Players: Establish a beachhead in India's electronics manufacturing corridor where PLI scheme incentives attract assembly investment currently served through imports. Target clean-room foam grades for medical packaging applications facing steepest REACH F-Gas compliance timeline compression. Partner with Southeast Asian extrusion operators for technology transfer joint ventures bridging nitrogen-autoclave capability gaps. For Investors and Strategic Acquirers: Capital is best deployed toward nitrogen-autoclave technology specialists commanding specification premiums in automotive and medical packaging segments. Long-term viability favors producers with backward integration into ethylene supply and dual-certification capacity spanning European and North American regulatory frameworks. Monitor supercritical nitrogen process adoption rates in German automotive seating supply chains as inflection indicator for conventional blowing agent displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical Nitrogen Process Licensing | Eliminates residual VOC concerns for German automotive seating suppliers under REACH compliance. |
| Dual-Certification Capacity Investment | Captures margin pools in electronics packaging requiring simultaneous REACH and EPA compliance. |
| Backward Integration into Ethylene Supply | Neutralizes naphtha-linked cost volatility compressing non-integrated extrusion operator margins. |
| Clean-Room Certification Expansion | Secures direct procurement relationships with South Korean and Taiwanese electronics assemblers. |
| Asset-Light Equipment Leasing Programs | Reduces entry capital barriers for mid-scale producers in China's eastern manufacturing provinces. |
Research Methodology
Desk research of customs trade databases, chemical industry association filings, and regulatory submission records preceded structured interviews with foam plant managers, electronics procurement leads, automotive Tier 1 supplier engineers, and nitrogen-autoclave equipment specialists. Primary fieldwork across Germany, China, Japan, South Korea, and the United States validated secondary data on capacity utilization and specification hierarchies. Bottom-up segmentation modeling triangulated against top-down macroeconomic demand drivers.
Assumptions held fixed include prevailing REACH F-Gas and EPA hydrofluorocarbon phase-down schedules, while crude-linked naphtha pricing and electronics assembly relocation patterns were varied across sensitivity scenarios. Segmentation dimensions modeled encompass manufacturing process type, cross-linking chemistry, certification grade, end-use industry, and regional production hub. CAGRs were derived from installed capacity expansion timelines and substitution elasticity estimates for automotive lightweighting applications.
Sensitivities concentrate around regulatory acceleration of blowing agent restrictions and feedstock price volatility transmission. Forecasts reflect documented assumptions on technology adoption curves and regional demand migration. Macroeconomic contraction, regulatory timeline compression, or breakthrough alternative material substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Expanded Polypropylene Market
Polymers & Resins
PVDF Resin Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
Nylon Resins Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market