
 Europe Cyclic Olefin Copolymer Market | 2026-2036
Europe Cyclic Olefin Copolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cyclic Olefin Copolymer Market Analytics
The gap between pharmaceutical-grade COC and general packaging resin is realigning contract terms across Europe. TOPAS Advanced Polymers GmbH leverages its Zeon-backed technology base to dominate high-clarity medical grades in Central Europe. Mitsui Chemicals anchors its position through backward integration into norbornene feedstock, insulating margins from olefin volatility. Borealis AG competes by extending its polyolefin compounding infrastructure into customized COC blends for automotive lighting.
Cyclic olefin copolymer is an amorphous thermoplastic produced through metallocene-catalyzed copolymerization of ethylene and norbornene, yielding glass transition temperatures from 75°C to 180°C depending on norbornene content. Its exceptional moisture barrier, low extractables, and UV transparency make it indispensable for pharmaceutical packaging and diagnostic consumables. High-clarity grades lead value generation due to stringent optical requirements in medical device applications, while film production represents the fastest-expanding application channel as European converters replace PVC in blister packs. Injection molding remains the mature volume anchor, though 3D printing filament trials are opening niche prototyping demand.
EMA medical device regulations and REACH chemical restrictions jointly shape material qualification timelines, forcing resin suppliers to maintain comprehensive extractables documentation. The EU Green Deal's plastics circularity targets are pressing COC producers to develop mechanically recycled and bio-based norbornene pathways. Stakeholders must monitor Germany's national packaging law amendments and France's extended producer responsibility schemes, as these will determine whether premium COC grades retain cost advantages against recycled PET and PP alternatives in pharmaceutical applications.
Market Dynamics
EU MDR and REACH compliance timelines are compressing qualification windows for pharmaceutical-grade COC, forcing converters to pre-certify resin batches before contract awards and reshaping supplier-buyer power dynamics across the Rhine-Main corridor.
Growth Catalysts
- Blister pack PVC replacement:Germany's pharmaceutical packaging cluster is accelerating COC film trials to meet EU Green Deal circularity targets ahead of national packaging law amendments.
- EMA MDR extractables documentation:Tighter medical device material traceability requirements are locking in premium COC grades for syringe and diagnostic cassette manufacturers seeking pre-market approval.
- Norbornene supply backward integration:Captive feedstock production by Japanese and German resin suppliers is stabilizing input costs and securing volume commitments from Central European converters.
Market Restraints
- Norbornene price volatility:Ethylene-norbornene copolymer input costs fluctuate with cracker operating rates, squeezing compounder margins during European energy price spikes.
- Specialized metallocene catalyst scarcity:Limited qualified catalyst suppliers concentrate technical risk in high-clarity medical grade production.
- Mechanical recycling incompatibility:COC's amorphous structure resists conventional polyolefin reprocessing streams, complicating EU circularity compliance.
Strategic Opportunities
- France extended producer responsibility schemes:Premium COC pharmaceutical packaging can capture eco-modulation fee advantages over conventional plastics in upcoming national implementation.
- 3D printing filament prototyping:Medical device developers in Switzerland and the Netherlands are trialing COC filament for surgical guide and diagnostic housing rapid iteration.
- Bio-based norbornene pathways:EU Green Deal R&D funding is accelerating pilot production of renewable feedstock-derived cyclic olefin copolymers for sustainability-certified applications.
Industry Challenges
- Metallocene polymerization expertise gap:European compounders face acute shortages of process engineers capable of tuning glass transition temperatures for customized medical grades.
- Extractables testing backlog:EMA-registered laboratories are extending qualification timelines to 18-24 months, delaying new COC grade commercialization.
- Multi-material laminate separation:Pharmaceutical blister packs combining COC with aluminum and PVC layers complicate post-consumer sorting infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cyclic Olefin Copolymer Market |
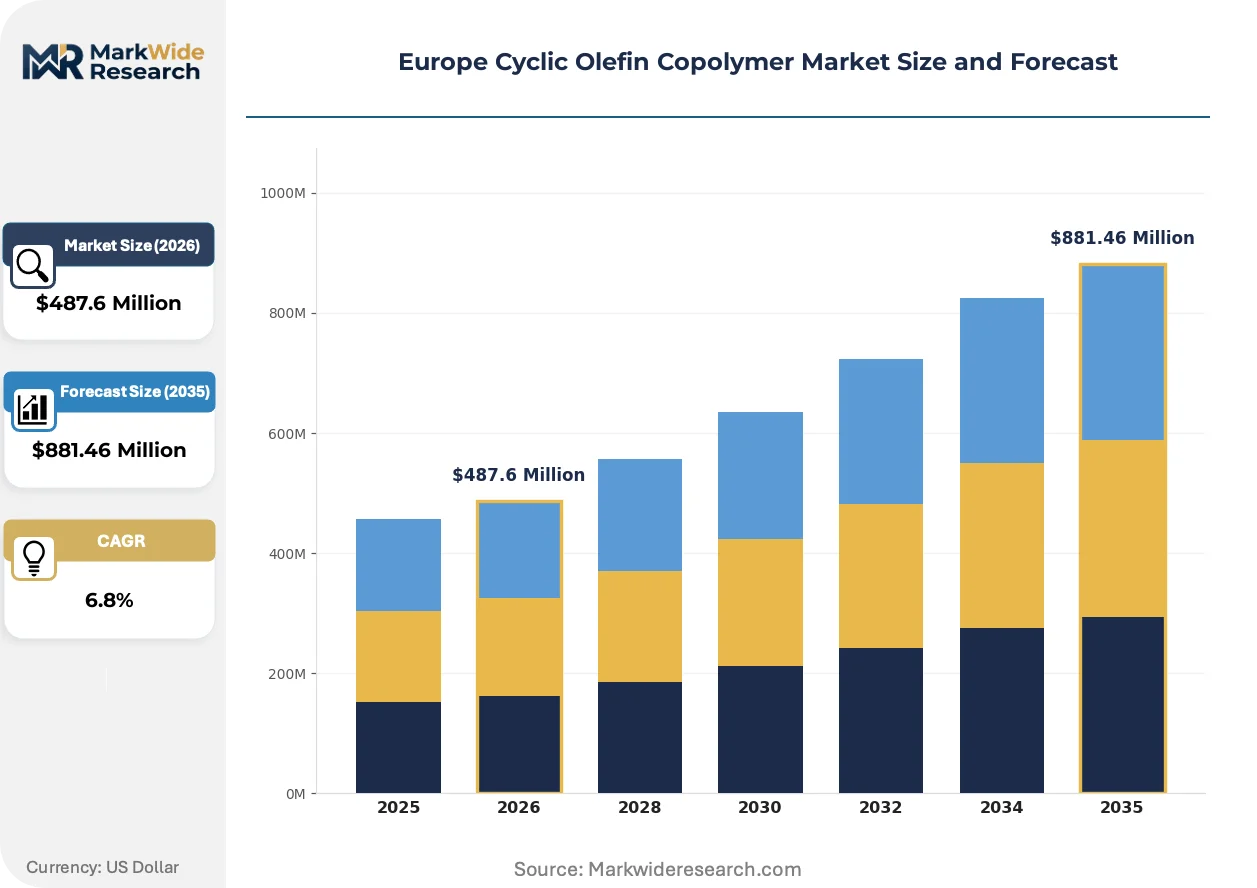
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
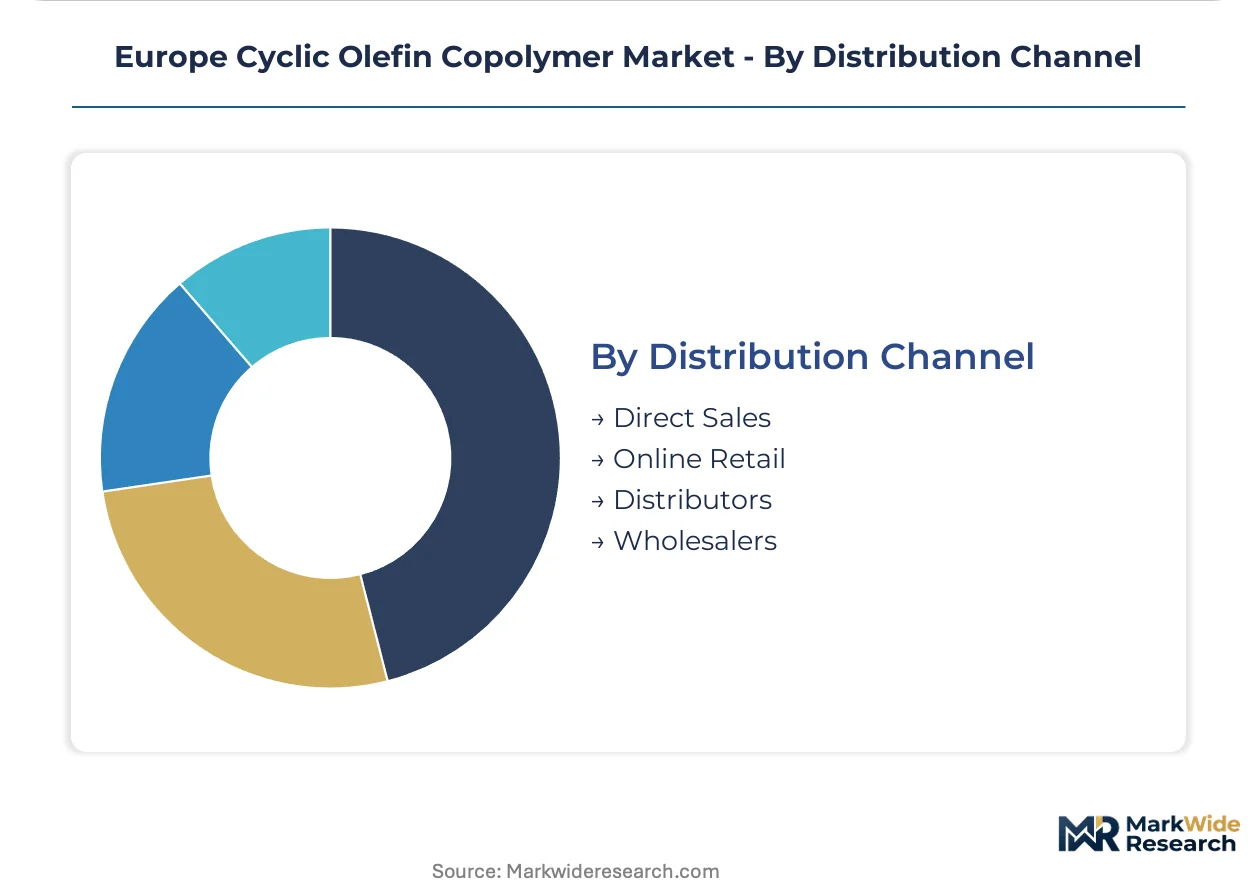
| Segmentation | Product Type: Polymer Grades, High Clarity, Low Viscosity, High Heat Resistance End User: Packaging, Medical Devices, Electronics, Automotive Application: Injection Molding, Blow Molding, 3D Printing, Film Production Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Polyplastics Co., Ltd., Mitsui Chemicals, Inc., Borealis AG, BASF SE, INEOS Group, SABIC, Zeon Corporation, JSR Corporation, TOPAS Advanced Polymers GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cyclic Olefin Copolymer Market Evolving Landscape
Digitalization of supply chain documentation and accelerated materials qualification protocols are compressing development cycles for medical-grade cyclic olefin copolymers across European pharmaceutical manufacturing.
Metallocene catalysis is consolidating as the dominant production technology for high-clarity COC grades with tunable glass transition temperatures. German syringe manufacturers are adopting these resins at expanded volume scales for EU MDR-compliant devices. The technology is consolidating process control advantages that marginalize older Ziegler-Natta systems in pharmaceutical applications.
REACH chemical restriction amendments are tightening extractables thresholds for polymers in patient-contact devices. ECHA's updated guidance forces resin suppliers to expand toxicological dossiers beyond standard migration testing. Medical packaging converters in France and Benelux are responding by locking in multi-year supply contracts with pre-qualified COC producers.
Specification-driven procurement is replacing commodity resin purchasing for pharmaceutical applications. European medical device OEMs now require batch-level extractables certificates before contract execution, displacing spot-market buying. This shift is most visible in Germany's diagnostic consumables sector, where COC cassette manufacturers demand full supply chain documentation from norbornene feedstock onward.
Europe Cyclic Olefin Copolymer Market Segmentation
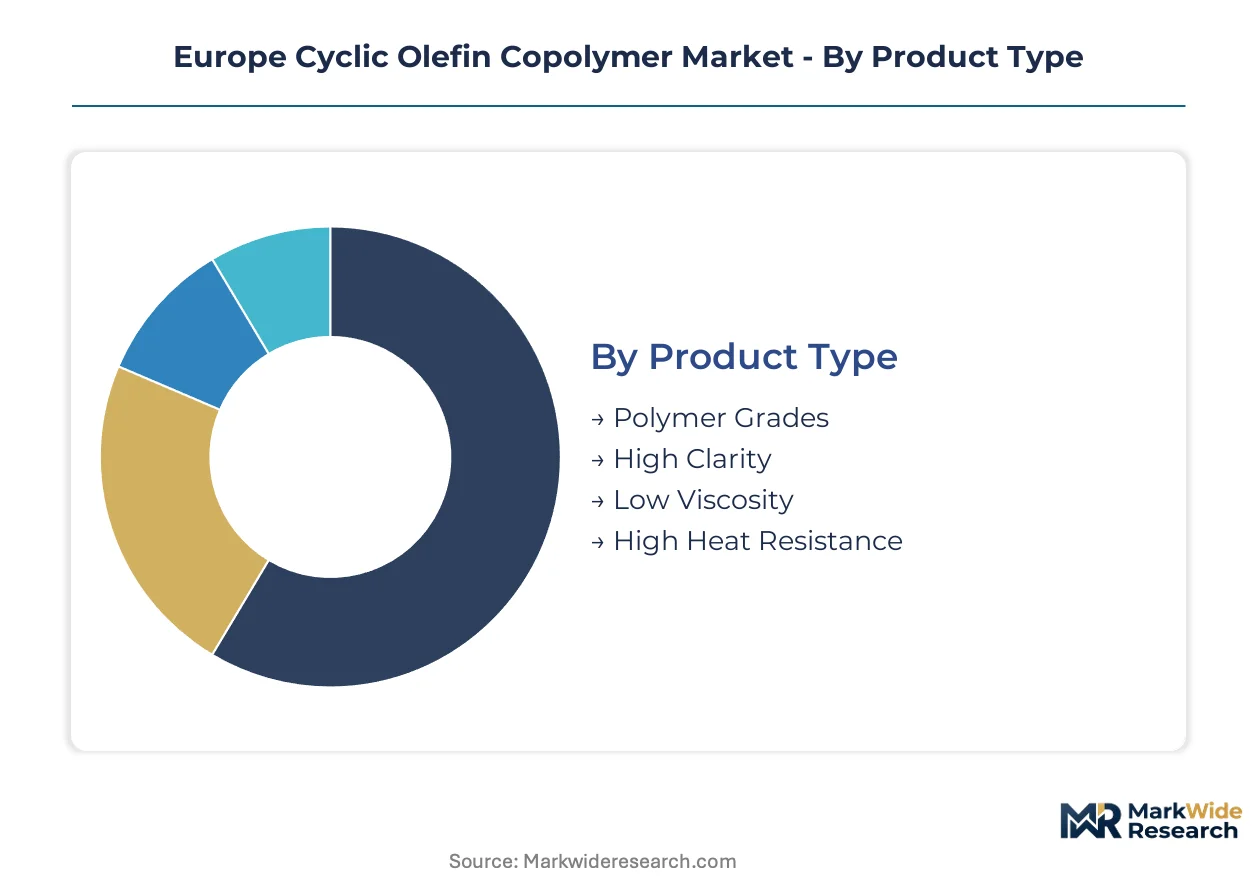
COC market segmentation in Europe tracks the divergence between commodity polyolefin replacement and premium medical-grade specifications. Each axis reveals distinct margin structures and qualification barriers that reshape supplier strategies across the Rhine-Main corridor.
Product Type:
Technical specification tiers separate pharmaceutical-certified grades from industrial applications, with glass transition temperature and extractables profiles determining contract value.
- Polymer Grades:Standardized viscosity classifications serve bulk packaging converters in Germany's industrial regions. ECHA REACH documentation requirements now mandate batch-level certification for all grades entering medical channels, compressing spot-market availability.
- High Clarity:Optical-grade resins with haze values below 1% command premium positioning for diagnostic cassettes and syringe barrels. German device manufacturers pre-qualify these grades 18-24 months ahead of EU MDR submission deadlines.
- Low Viscosity:Flow-optimized formulations enable thin-wall molding for microfluidic components. Swiss and Dutch prototyping labs specify these grades for rapid iteration cycles in point-of-care diagnostic development.
- High Heat Resistance:Elevated glass transition variants above 150°C target automotive lighting bezels and sterilizable medical trays. Borealis AG compounds these through customized norbornene ratios at its Austrian facilities.
Mature deployment sits with Polymer Grades. Newer deployment is concentrated in High Clarity.
End User:
Application-specific regulatory burdens fragment demand patterns, with EMA MDR and EU Green Deal targets pulling procurement in divergent directions.
- Packaging:Blister film converters across Germany's pharmaceutical cluster accelerate PVC replacement trials. France's extended producer responsibility eco-modulation fees favor COC over conventional plastics in upcoming national implementation.
- Medical Devices:Syringe and diagnostic cassette manufacturers anchor volume commitments. EMA extractables documentation requirements lock in multi-year supply contracts with pre-qualified resin producers.
- Electronics:Moisture-barrier films for display components utilize COC's amorphous stability. Dutch semiconductor packaging specialists trial these grades for wafer-level protection.
- Automotive:LED lighting lens housings exploit UV transparency and thermal stability. German OEMs specify these for headlamp assemblies requiring long-term optical clarity.
Volume concentrates in Medical Devices. Margin expansion is climbing the fastest in Packaging.
Application:
Processing technology selection determines norbornene content optimization and catalyst system requirements for each output specification.
- Injection Molding:High-throughput syringe barrel and diagnostic housing production dominates European volume. Mitsui Chemicals supplies captive-feedstock grades optimized for multi-cavity tooling in Central European converter networks.
- Blow Molding:Hollow-container applications for laboratory reagent bottles utilize mid-range clarity formulations. German packaging specialists qualify these through ECHA-registered toxicological dossiers.
- 3D Printing:Filament prototyping for surgical guides and custom diagnostic fixtures gains traction in Swiss medical device development labs. Material qualification timelines lag behind conventional processing by 12-18 months.
- Film Production:Blister pack and lidding film extrusion represents the steepest expansion trajectory as converters respond to EU circularity targets. TOPAS Advanced Polymers GmbH dedicates Zeon-backed production lines to pharmaceutical film grades.
Established volume anchors Injection Molding. Technology transition is accelerating in Film Production.
Distribution Channel:
Procurement channel selection reflects batch traceability requirements and volume scale economics across customer segments.
- Direct Sales:Pharmaceutical-grade volume commitments flow through producer-direct relationships. TOPAS and Mitsui Chemicals maintain dedicated account teams for German medical device OEMs requiring norbornene-to-resin chain of custody documentation.
- Online Retail:Small-lot prototyping grades and 3D printing filaments reach research laboratories and startup device developers. Swiss and Netherlands-based distributors specialize in rapid-turnaround technical grade shipments.
- Distributors:Regional compounders and converters access standardized grades through Benelux and Rhine-Main logistics hubs. These intermediaries manage ECHA-compliant safety data sheet translation and local stockholding.
- Wholesalers:Bulk industrial grades for non-medical packaging flow through polyolefin trading networks. German packaging law amendments are pressuring these channels toward certified circularity documentation.
Contract security concentrates in Direct Sales. Channel experimentation is expanding most quickly in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Main corridor anchors European COC demand through pharmaceutical packaging clusters in Frankfurt and Darmstadt. Medical device manufacturers and blister film converters across this region drive specification-grade resin procurement.
Germany
Syringe barrel and diagnostic cassette manufacturers in Hesse and Baden-Württemberg anchor medical-grade COC consumption. EU MDR extractables documentation requirements compress qualification timelines to 18-24 months. The Rhine-Main packaging cluster around Frankfurt accelerates PVC replacement trials in pharmaceutical blister films.
France
Extended producer responsibility eco-modulation fees favor premium COC pharmaceutical packaging over conventional plastics. ANSM medical device regulations align with EMA traceability mandates for patient-contact polymers. Diagnostic consumables producers in the Île-de-France region lock in multi-year supply contracts with pre-qualified resin suppliers.
Switzerland
Swissmedic certification requirements drive batch-level extractables documentation for COC grades entering surgical device channels. Medical device prototyping labs in Basel and Zurich trial 3D printing filament for rapid diagnostic housing iteration. Swiss converters specialize in small-lot technical grades for point-of-care development.
Netherlands
Benelux distribution hubs manage ECHA-compliant safety data sheet translation and regional stockholding for standardized grades. Semiconductor packaging specialists trial moisture-barrier COC films for wafer-level protection. Rotterdam-area logistics networks channel German-produced resin to French and Belgian converters.
Austria
Automotive lighting manufacturers in Upper Austria specify high-heat COC grades for LED lens housings requiring long-term UV stability. Borealis AG compounds elevated glass transition variants through customized norbornene ratios at its domestic facilities. Polyolefin compounding infrastructure extends into specialized automotive blends.
Europe Cyclic Olefin Copolymer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and industrial-grade resin tiers. Japanese and German resin suppliers dominate pharmaceutical-certified channels through captive norbornene feedstock control, while regional compounders compete on customized blends for automotive and packaging applications. Three archetypes define the competitive set: backward-integrated polymer producers with metallocene technology bases, polyolefin compounders extending infrastructure into specialty grades, and distribution-focused intermediaries managing ECHA compliance documentation. Capacity expansion and strategic technology licensing represent the dominant competitive moves reshaping supply relationships.
Among Japan-based polymer producers, Mitsui Chemicals, Inc. and Zeon Corporation exemplify backward-integrated archetypes with captive control over norbornene feedstock pathways. TOPAS Advanced Polymers GmbH occupies a position bridging German production assets with Zeon-backed technology licensing. Borealis AG represents the European compounder archetype extending polyolefin infrastructure into customized high-heat formulations for automotive lighting applications.
| Leading Market Players |
|---|
| Polyplastics Co., Ltd. |
| Mitsui Chemicals, Inc. |
| Borealis AG |
| BASF SE |
| INEOS Group |
| SABIC |
| Zeon Corporation |
| JSR Corporation |
| TOPAS Advanced Polymers GmbH |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade certification divergence from industrial packaging resin creates parallel pricing architectures across European COC procurement. EMA MDR extractables documentation requirements and REACH batch-level traceability mandates force medical device manufacturers into long-term offtake contracts at substantial premiums, while blister film converters access spot-market industrial grades through Rhine-Main distribution hubs at compressed margins.
Pricing Analysis
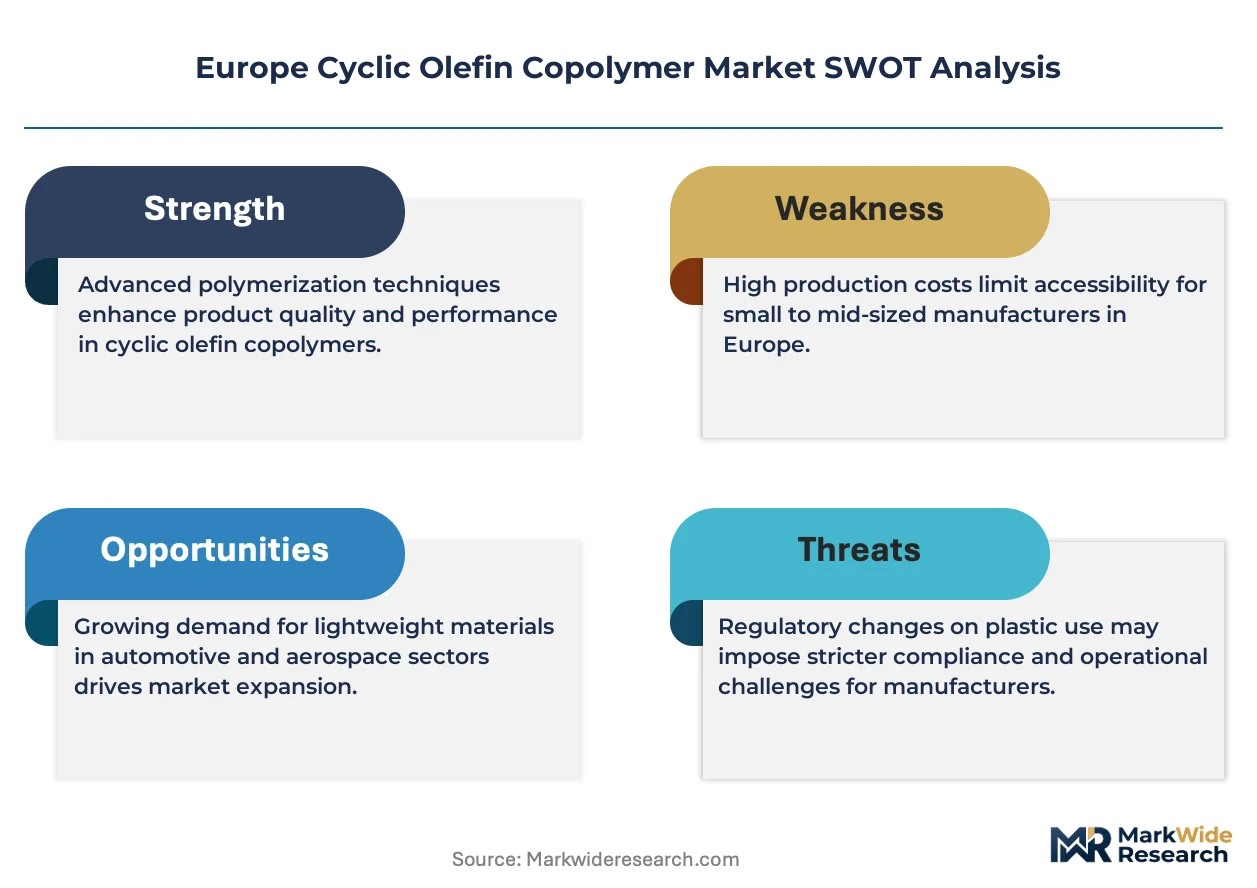
Yield-locked pricing tied to diagnostic cassette throughput and syringe barrel optical clarity anchors pharmaceutical-grade contract values. Three-tier pricing structure across premium, standard, and economy levels separates EMA-pre-certified medical grades from REACH-compliant industrial formulations and commodity polyolefin alternatives. Cost compression in industrial film grades is intensifying because PVC replacement trials are expanding qualified supplier pools across Germany's packaging cluster. Diagnostic OEMs exhibit lowest price sensitivity due to locked-in regulatory qualification timelines, while automotive lighting compounders negotiate aggressively on norbornene content customization.
Supply Chain Analysis
Dual-sourcing requirements from German syringe manufacturers and French diagnostic cassette producers mandate multi-supplier qualification across Japanese and German resin producers. Geographic supply concentration centers on Germany, Japan, and Austria for metallocene-catalyzed polymer production. Raw material dependencies rest on ethylene cracker output, specialized metallocene catalyst systems, and norbornene monomer from petrochemical derivatives. Single-source vulnerability concentrates in qualified catalyst suppliers for high-clarity medical grades. Distribution runs through producer-direct relationships for pharmaceutical volumes and Benelux hub intermediaries for standardized industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized metallocene polymerization capacity scarcity props pricing across pharmaceutical-grade COC tiers, constraining volume expansion regardless of demand pull from EU MDR compliance deadlines.
For Market Incumbents: Acquire captive norbornene production assets to insulate margin structures from olefin feedstock volatility. Secure EMA-registered laboratory partnerships to compress 18-24 month extractables testing timelines. Expand metallocene catalyst qualification programs to offset technical risk concentration in limited supplier pools. For New Entrants and Emerging Players: The premium-to-economy price-point gap in automotive lighting grades offers accessible entry without pharmaceutical certification barriers. Target Austrian and Upper German LED lens housing manufacturers seeking high-heat COC alternatives to polycarbonate. Pursue co-development partnerships with Borealis AG compounding infrastructure to bypass standalone metallocene investment requirements. For Investors and Strategic Acquirers: Re-rating potential sits with backward-integrated Japanese polymer producers given EU Green Deal bio-based norbornene pathway funding acceleration. Long-term viability over a multi-year horizon favors archetypes with captive feedstock control and established EMA extractables dossiers. Monitor France's extended producer responsibility eco-modulation implementation as demand inflection signal for premium pharmaceutical packaging grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Norbornene Feedstock | Mitsui Chemicals and Zeon Corporation insulate margins from ethylene cracker rate volatility through captive supply. |
| EMA-Registered Extractables Laboratory Partnership | TOPAS Advanced Polymers GmbH compresses qualification timelines for German syringe manufacturers facing MDR deadlines. |
| Bio-Based Norbornene Pilot Production | EU Green Deal R&D funding accelerates renewable pathway development for sustainability-certified COC grades. |
| High-Clarity Film Production Line Dedication | Pharmaceutical blister pack converters replace PVC ahead of national packaging law amendments across Germany. |
| 3D Printing Filament Grade Development | Swiss and Dutch medical device prototyping labs trial surgical guide applications for rapid iteration cycles. |
Research Methodology
Document review covered ECHA REACH registration databases, EU MDR guidance documents, and trade flow records from German and Benelux customs authorities, complemented by interviews with polymer plant managers, pharmaceutical packaging procurement leads, medical device regulatory affairs directors, and distribution channel partners across the Rhine-Main corridor. Secondary validation drew from SEC filings of listed chemical producers, Cefic industry statistics, and metallocene catalyst patent landscapes. Bottom-up resin consumption estimates triangulated against top-down pharmaceutical packaging production indices.
Historical volume trajectories cross-referenced against expert panel assessments of EU MDR implementation pace and PVC replacement timelines across the projection horizon. Segmentation modeling spanned grade tier, end-use industry, processing technology, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating norbornene price volatility assumptions and pharmaceutical qualification backlog estimates.
Underlying measurement precision varies by segment; pharmaceutical-grade consumption carries tighter precision than emerging 3D printing filament demand. Forecasts reflect documented assumptions regarding EMA laboratory capacity expansion and EU Green Deal bio-based pathway commercialization. Deviation in France's extended producer responsibility fee structure or REACH extractables threshold amendments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Oman PVC Products Market
Polymers & Resins
Polymer Resin Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Global Nylon Market
Polymers & Resins
Bio-Based PU Market