
 Polyalkylene Glycols (Pags) Market | 2026-2036
Polyalkylene Glycols (Pags) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyalkylene Glycols (Pags) Market Analytics
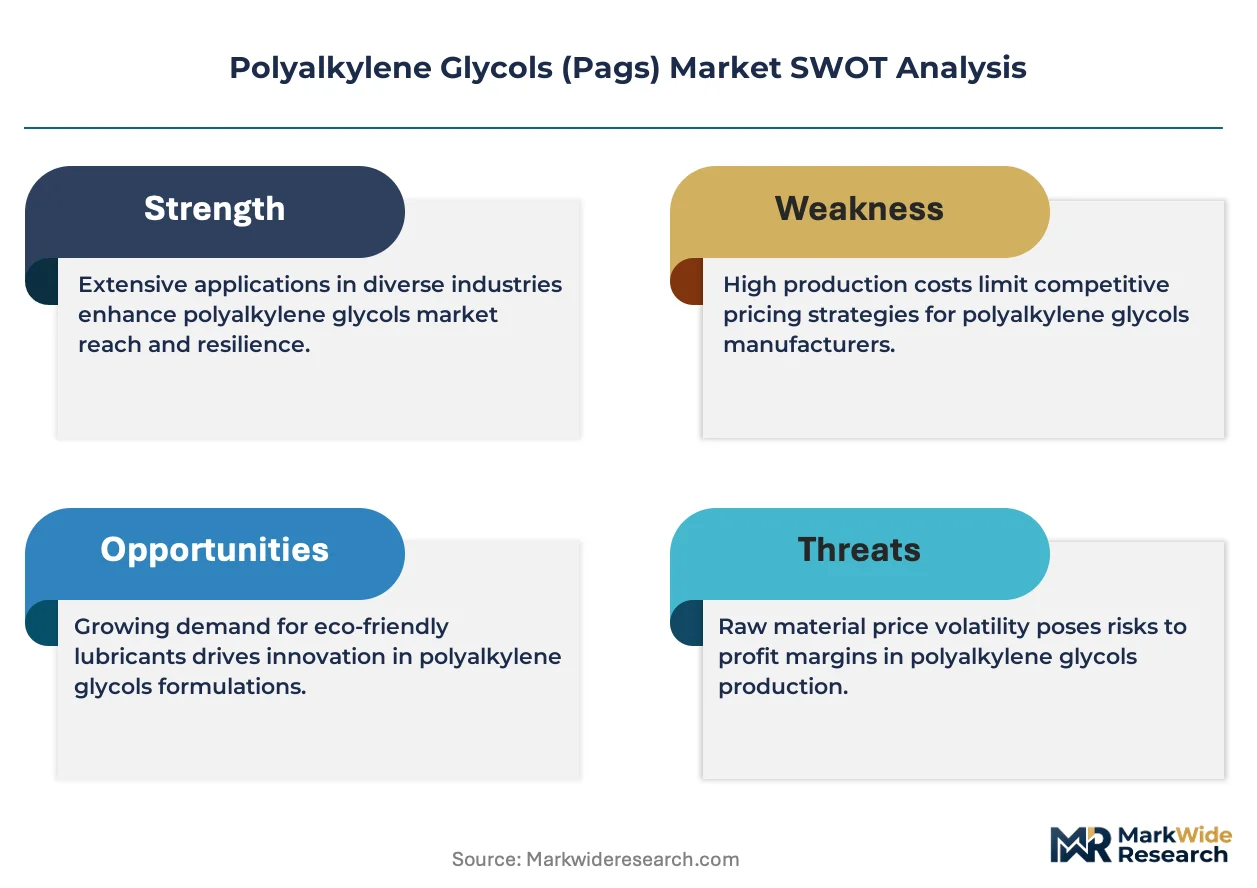
REACH registration requirements for chemical importers is hardening the cost-of-entry calculus for PAG suppliers without pre-registered substance dossiers. BASF SE leverages its integrated Ludwigshafen Verbund complex to sustain captive ethylene oxide feedstock for polyethylene glycol production. Dow Inc. anchors North American supply through its Freeport, Texas manufacturing base, while Shell plc competes via specialized polypropylene glycol blends for compressor lubricants.
Polyalkylene glycols constitute a family of synthetic polyether compounds produced through alkoxide polymerization of ethylene oxide, propylene oxide, or their mixtures, yielding products with molecular weights from 200 to over 35,000 g/mol and tunable water solubility profiles. These materials function primarily as high-performance lubricant basestocks, surfactant intermediates, and rheology modifiers across industrial and consumer applications. Polyethylene glycol maintains volume leadership in pharmaceutical and personal care formulations where biocompatibility and FDA compliance matter most. Block copolymers represent the fastest-expanding structural category, driven by demand for thermoreversible gels in advanced lubricant and antifoaming applications where amphiphilic behavior enables multifunctional performance.
The EPA governs PAG discharge limits under Clean Water Act provisions for industrial lubricant runoff, while FDA 21 CFR regulations dictate polyethylene glycol purity thresholds for pharmaceutical and food-contact applications. ECHA's SVHC candidate list screenings now target residual epoxide impurities in high-molecular-weight glycols, forcing reformulation investments across European supply chains. Stakeholders must monitor evolving electric vehicle thermal fluid specifications from NHTSA and OEM engineering groups, as these will determine which PAG chemistries capture next-generation coolant and grease contracts.
Market Dynamics
Electric vehicle thermal fluid specifications are compressing formulation windows for PAG suppliers, forcing simultaneous compliance with dielectric strength, low conductivity, and biodegradability requirements that legacy mineral oil chemistries cannot satisfy.
Growth Catalysts
- REACH substance registration:ECHA's tightened purity documentation for imported glycol ethers is advantaging pre-registered European producers with existing dossiers.
- Compressor lubricant demand:Industrial refrigeration systems are converting from mineral oils to polypropylene glycol blends for improved miscibility with ammonia refrigerants.
- Block copolymer thermoreversibility:Amphiphilic PAG architectures enable multifunctional grease formulations that phase-separate for controlled release in wind turbine drivetrains.
Market Restraints
- Ethylene oxide feedstock volatility:Captive EO supply at integrated Ludwigshafen and Freeport complexes insulates majors from spot market swings that fragment smaller compounders.
- High-molecular-weight glycol impurity scrutiny:ECHA's SVHC candidate screening for residual epoxides forces reformulation investments without immediate volume recovery.
- Polyether polyol substitution:Polyurethane flexible foam manufacturers are partially reverting to conventional polyols where PAG performance premiums do not justify cost deltas.
Strategic Opportunities
- India automotive thermal management:PLI scheme incentives for domestic EV manufacturing are creating first-mover openings for localized PAG coolant formulation.
- Pharmaceutical excipient grade expansion:FDA 21 CFR polyethylene glycol purity thresholds for parenteral applications command 3-4x standard industrial pricing.
- Marine biodegradable lubricants:EPA Vessel General Permit discharge limits are mandating PAG-based stern tube oils for Great Lakes and coastal operations.
Industry Challenges
- Alkoxide polymerization specialist scarcity:Batch reactor control for narrow molecular weight distribution requires expertise concentrated among retiring German and Japanese process engineers.
- Multi-jurisdictional certification timelines:Simultaneous FDA, EMA, and PMDA pharmaceutical-grade approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyalkylene Glycols (Pags) Market |
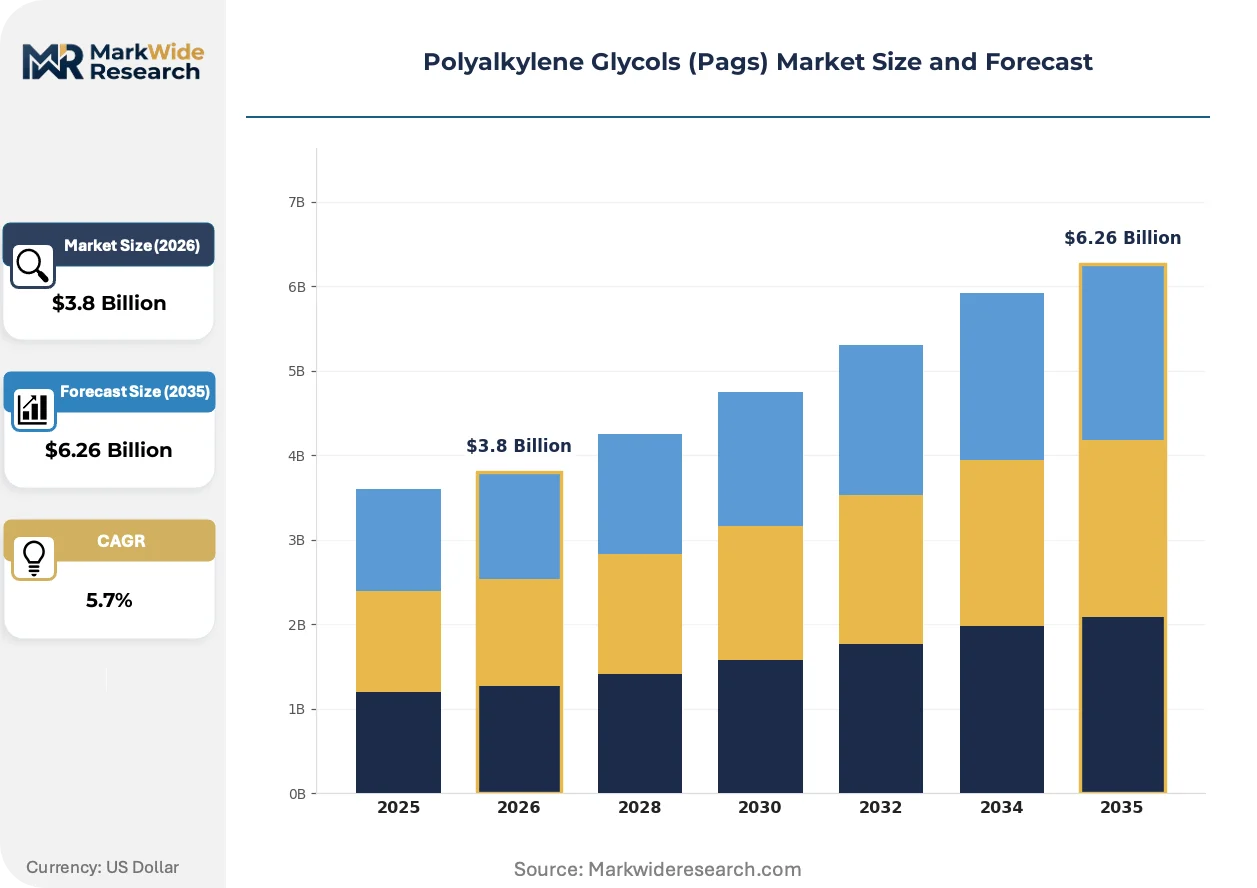
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Glycol, Polypropylene Glycol, Block Copolymers, Others End Use Industry: Pharmaceutical, Cosmetics, Food Processing, Textile Application: Lubricants, Surfactants, Antifoaming Agents, Personal Care Form: Liquid, Solid, Powder, Emulsion |
| Companies Covered | BASF SE, Dow Inc., LyondellBasell Industries, Clariant, Idemitsu Kosan Co., Ltd., INEOS Group, Shell plc, Huntsman Corporation, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyalkylene Glycols (Pags) Market Evolving Landscape
Formulation science is pivoting from single-property optimization to multifunctional architectures that satisfy conflicting performance mandates across thermal, electrical, and environmental domains.
Water-soluble PAG lubricants for metalworking fluids are consolidating market share against emulsion-based coolants in precision machining operations. Automotive Tier 1 suppliers are specifying these chemistries for aluminum electric motor housing production. The technology is consolidating supplier bases by disqualifying regional compounders lacking molecular weight customization capabilities.
REACH Annex XVII restrictions on microplastics in consumer products are redirecting cosmetic formulators toward biodegradable polyethylene glycol thickeners. ECHA's 2027 enforcement timeline is compressing reformulation windows for personal care multinationals. High-purity pharmaceutical grades now face allocation constraints as manufacturers prioritize compliant cosmetic volumes.
Direct procurement contracts between automotive OEM thermal engineering groups and PAG formulators are displacing traditional lubricant distributor networks. EV battery pack manufacturers in Germany and Texas are negotiating multi-year coolant supply agreements with volume commitments tied to cell production ramp schedules. This channel compression is most visible where gigafactory concentration enables dedicated logistics infrastructure.
Polyalkylene Glycols (Pags) Market Segmentation
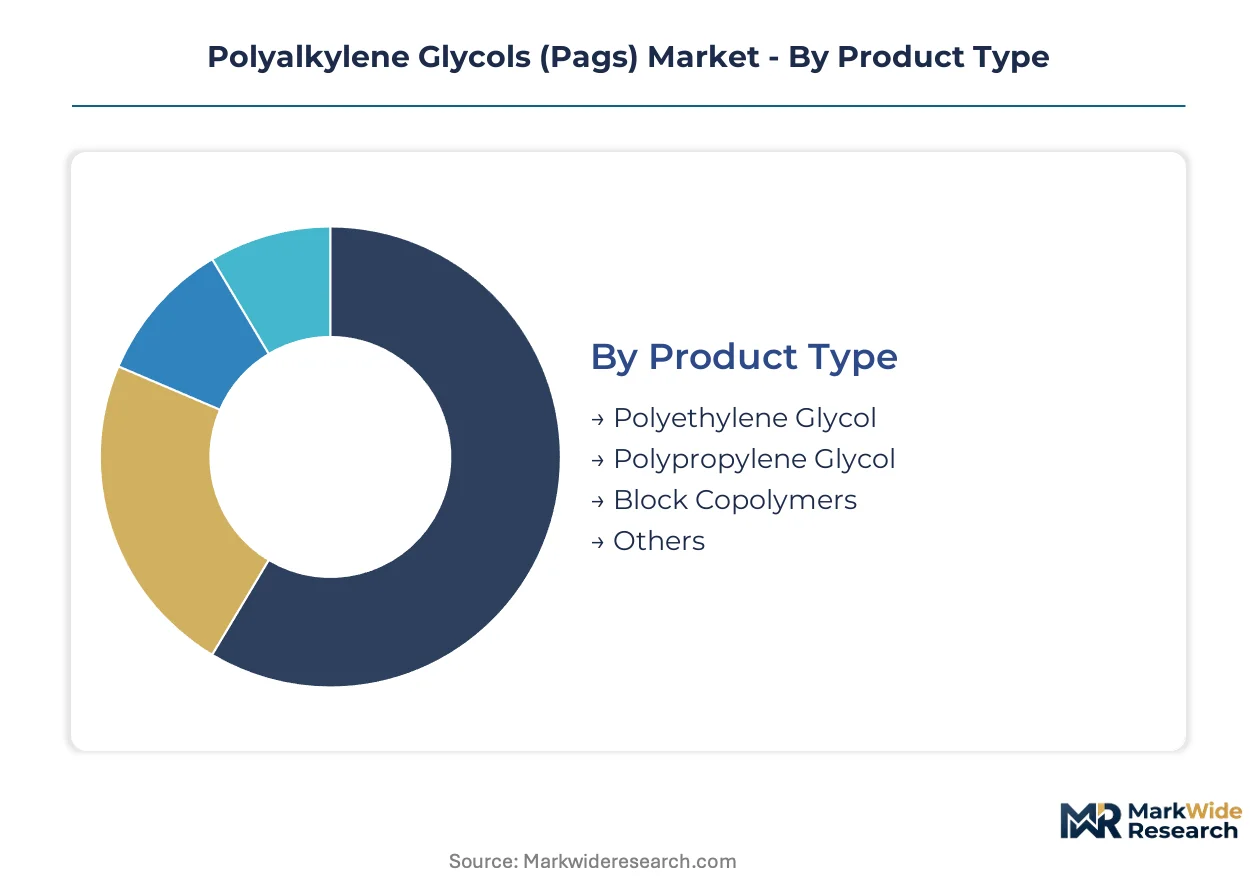
Polyalkylene glycol suppliers configure product portfolios around molecular architecture and purity grades that dictate end-use eligibility. Segmentation discipline separates commodity industrial volumes from pharmaceutical-grade premiums where regulatory dossiers command pricing power.
Product Type:
Upgrade cycles in thermal fluid specifications are pushing formulators toward copolymer architectures that legacy single-oxide chemistries cannot satisfy.
- Polyethylene Glycol:Linear polyether produced via ethylene oxide polymerization, available in molecular weights from 200 to 35,000 g/mol. Pharmaceutical and personal care formulators in Germany's Ludwigshafen corridor concentrate demand for FDA 21 CFR-compliant grades where residual epoxide thresholds determine supplier qualification.
- Block Copolymers:Amphiphilic structures combining ethylene oxide and propylene oxide blocks in controlled sequences. EV thermal management engineering groups specify these for dielectric coolants requiring simultaneous low conductivity and biodegradability that homogeneous PAGs fail to deliver.
- Polypropylene Glycol:Hydrophobic polyether basestock with inverse temperature solubility characteristics. Compressor lubricant formulators specify PPG for ammonia refrigeration systems.
- Others:Random copolymers and specialty alkoxide modifications for niche rheology applications.
Polyethylene Glycol sits at the top of the volume ranking, with Block Copolymers climbing the fastest.
End Use Industry:
Cost tier stratification separates excipient-grade pharmaceutical volumes from standard industrial applications.
- Pharmaceutical:Parenteral and oral dosage form applications governed by FDA, EMA, and PMDA purity protocols. Multi-jurisdictional approval timelines extend launch cycles.
- Cosmetics:REACH Annex XVII microplastic restrictions redirect formulators toward biodegradable PEG thickeners ahead of ECHA's enforcement timeline.
- Food Processing:Food-contact lubricants and packaging additives subject to FDA food additive regulations.
- Textile:Fiber lubricants and dye carriers where water solubility enables clean processing.
Pharmaceutical commands the premium pricing tier, with Cosmetics expanding most quickly under regulatory pressure.
Application:
Application selection tracks customer technical sophistication and specification authority.
- Lubricants:Industrial and automotive basestocks where PAGs displace mineral oils for thermal stability and biodegradability. Metalworking fluid formulators specify water-soluble PAGs for aluminum EV motor housing machining.
- Surfactants:Intermediates for emulsification and wetting agent production across institutional cleaning.
- Antifoaming Agents:Process control additives leveraging PAG surface tension modification.
- Personal Care:Moisturizers and delivery vehicles where biocompatibility and sensory profile determine selection.
Lubricants anchor volume demand, with Surfactants gaining share fastest in institutional cleaning conversion.
Form:
Physical form selection constrains logistics infrastructure and handling equipment requirements.
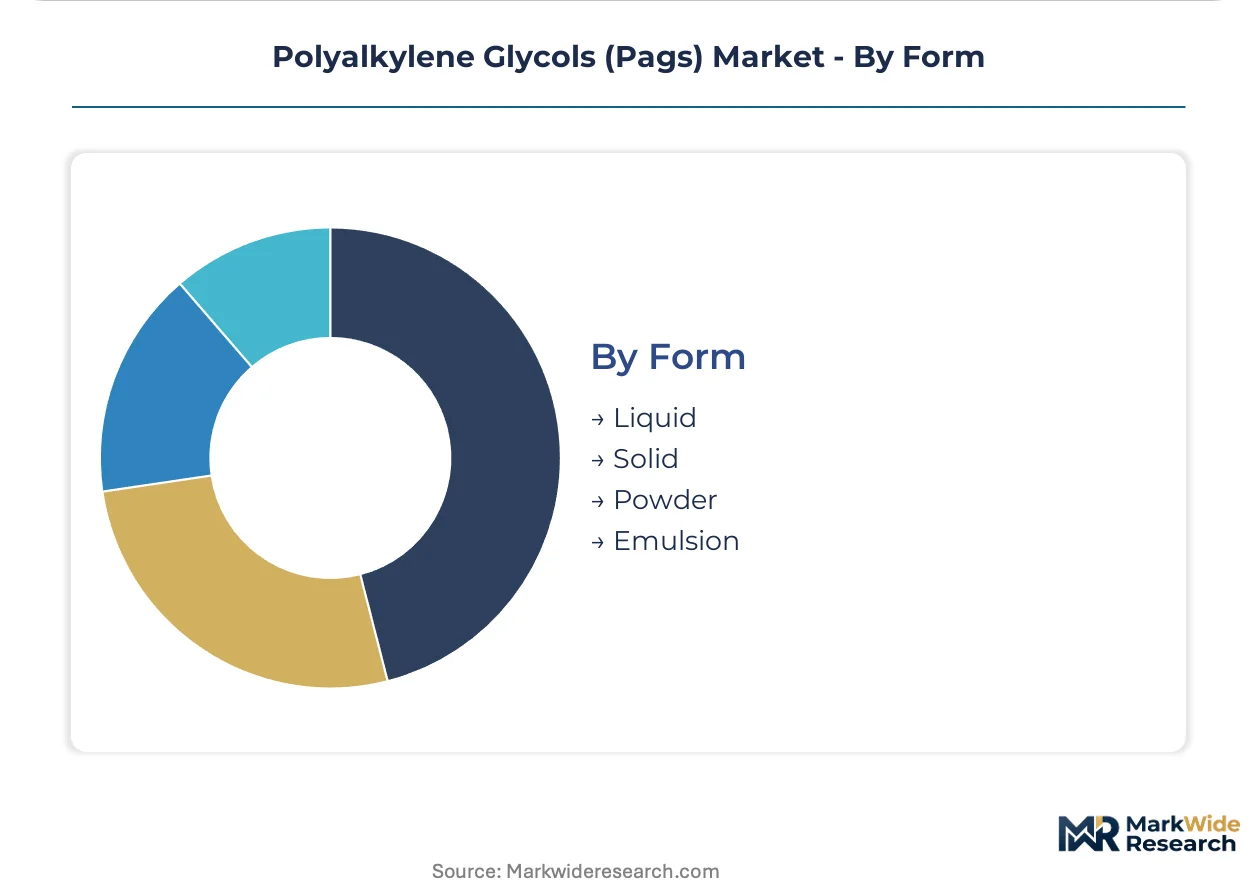
- Liquid:Standard delivery form for lubricant basestocks and surfactant feedstocks. Bulk tanker and drum distribution dominates.
- Solid:High-molecular-weight polyethylene glycol flakes for controlled-release pharmaceutical matrices.
- Powder:Micronized grades for dry blend compatibility in powder detergent and cosmetic formulations.
- Emulsion:Pre-dispersed aqueous systems for metalworking coolant direct use.
Liquid holds the volume lead, with Powder expanding fastest in solid dosage form manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German process engineers and Japanese alkoxide polymerization specialists anchor the technical workforce concentration for advanced PAG manufacturing. Ludwigshafen and Leverkusen host the deepest talent pools for batch reactor control. This expertise concentration shapes regional supply capabilities.
United States
EV battery gigafactories in Texas and the Southeast are contracting directly with PAG formulators for thermal coolant supply. EPA Clean Water Act provisions govern industrial lubricant discharge limits. The Freeport petrochemical complex sustains captive ethylene oxide feedstock for polyethylene glycol production.
Germany
Automotive OEM thermal engineering groups in Stuttgart and Munich are specifying block copolymer dielectric coolants for next-generation EV platforms. ECHA REACH registration requirements harden purity documentation standards for imported glycol ethers. The Ludwigshafen Verbund complex integrates ethylene oxide through downstream PAG derivatives.
China
Domestic EV manufacturers are localizing PAG coolant formulation under MIIT industrial policy guidance. NMPA pharmaceutical-grade polyethylene glycol protocols command premium pricing for parenteral applications. The Yangtze River Delta concentrates surfactant intermediate production for institutional cleaning markets.
India
PLI scheme incentives for domestic EV manufacturing are opening first-mover positions for localized thermal fluid formulation. BIS standards for industrial lubricants are converging with automotive OEM specifications. Gujarat's chemical corridor is attracting PAG compounding investments for textile and pharmaceutical applications.
Japan
Precision metalworking fluid formulators are specifying water-soluble PAGs for aluminum EV motor housing machining. METI energy efficiency standards are accelerating compressor lubricant conversion from mineral oils to polypropylene glycol blends. The Nagoya industrial zone maintains specialized alkoxide polymerization expertise.
Polyalkylene Glycols (Pags) Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical majors with captive ethylene oxide supply. Three archetypes dominate: integrated Verbund operators with backward control into alkoxide feedstocks, regional compounders serving specification-tolerant industrial accounts, and pharmaceutical-grade specialists commanding certification premiums. Capacity expansion and direct OEM procurement contracting represent the dominant competitive moves as distributor networks compress.
Among German-integrated operators, BASF SE occupies the archetype position of captive-feedstock manufacturer. Dow Inc. anchors North American supply capabilities. Shell plc exemplifies the specialized-blend competitor focused on compressor lubricant applications.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| LyondellBasell Industries |
| Clariant |
| Idemitsu Kosan Co., Ltd. |
| INEOS Group |
| Shell plc |
| Huntsman Corporation |
| SABIC |
| Others |
Value Network & Pricing Analysis
Automotive OEM thermal engineering groups in Germany and Texas concentrate procurement authority for dielectric coolant volumes, compressing supplier margins through multi-year offtake contracts that bundle formulation development with dedicated logistics infrastructure.
Pricing Analysis
Technical service bundling separates pricing models across the PAG market. Three-tier pricing structure across pharmaceutical-grade, industrial-performance, and commodity-standard levels reflects FDA 21 CFR certification costs and molecular weight customization capabilities. Pricing pressure stems from REACH registration dossier investments that smaller compounders cannot amortize across thin volumes. Automotive thermal fluid buyers exhibit lowest price sensitivity due to dielectric performance mandates, while textile fiber lubricant purchasers prioritize cost minimization over specification breadth.
Supply Chain Analysis
Retiring German and Japanese alkoxide polymerization specialists constrain batch reactor commissioning timelines at new facilities. Manufacturing gravity centers on Germany's Ludwigshafen corridor, Texas Gulf Coast petrochemical complexes, and China's Yangtze River Delta surfactant hubs. Ethylene oxide and propylene oxide feedstock sourcing draws from integrated Verbund sites and merchant spot markets. Single-source vulnerability runs through captive EO supply at BASF's Ludwigshafen and Dow's Freeport complexes. Distribution runs through direct OEM procurement channels that displace traditional lubricant distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European REACH compliance costs and Indian PLI scheme incentives create a manufacturing cost arbitrage window favoring localized compounding investments in Gujarat's chemical corridor over continued import dependence.
For Market Incumbents: Lock in captive ethylene oxide supply through long-term pipeline commitments or backward integration into alkoxide production. BASF's Ludwigshafen Verbund model demonstrates how integrated feedstock control insulates margin position against spot market volatility. Prioritize pharmaceutical-grade certification investments to defend pricing power as REACH Annex XVII microplastic restrictions redirect cosmetic formulators toward compliant PEG thickeners. For New Entrants and Emerging Players: The 3-4x price spread between pharmaceutical excipient grades and standard industrial PEGs defines the most penetrable white-space opportunity. Target India's domestic EV thermal fluid formulation under PLI scheme localization mandates. Pursue toll manufacturing partnerships with established alkoxide polymerization specialists to bypass workforce scarcity constraints in Germany and Japan. For Investors and Strategic Acquirers: Petrochemical majors with downstream lubricant divisions are the most active acquirer in this space, seeking molecular weight customization capabilities for EV coolant specifications. Five-to-ten year viability hinges on block copolymer architecture expertise for dielectric thermal management applications. Monitor NHTSA and OEM engineering group coolant specification releases as the critical inflection signal for chemistry selection winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply at Ludwigshafen and Freeport insulates margin position against spot volatility. |
| Pharmaceutical-Grade Certification Investment | FDA 21 CFR compliance unlocks 3-4x pricing premiums in parenteral excipient applications. |
| Direct OEM Procurement Contracting | Multi-year thermal fluid supply agreements with EV battery manufacturers displace distributor networks. |
| Block Copolymer R&D Expansion | Amphiphilic architectures satisfy conflicting dielectric and biodegradability mandates in EV coolants. |
| India Localization Partnership | PLI scheme incentives for domestic EV manufacturing create first-mover compounding positions in Gujarat. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from alkoxide polymerization process engineers, automotive OEM thermal management directors, pharmaceutical formulation scientists, and industrial lubricant procurement leads. Secondary validation drew from ECHA REACH registration databases, FDA 21 CFR filings, SEC 10-K petrochemical segment disclosures, and Cefic chemical production statistics. Bottom-up volume modeling triangulated against top-down market sizing across molecular architecture segments.
Historical reference periods anchored growth trajectory assumptions across the projection horizon. The analytical framework modeled segmentation dimensions including product type, end-use industry, application function, and physical form. CAGRs derived from regression analysis against ethylene oxide feedstock pricing, EV production ramp schedules, and pharmaceutical approval timelines. Industry-specific inputs incorporated REACH SVHC screening impacts on reformulation cycles and EPA Vessel General Permit enforcement patterns for marine lubricant displacement.
Caveats apply where ECHA regulatory enforcement intensity, EV thermal fluid specification finalization, or ethylene oxide supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions about alkoxide polymerization capacity expansion and pharmaceutical-grade allocation constraints. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Global VAE Emulsion Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market